
 Metal Jet 3D Printing Technology Market | 2026-2036
Metal Jet 3D Printing Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Metal Jet 3D Printing Technology Market Insights
Subscription-based software licensing for build preparation and real-time process monitoring is hardening into a core revenue stream alongside hardware sales. HP Inc. leverages its print-head intellectual property to control binder jetting nozzle architecture. XJet sustains competitive differentiation through nanoparticle jetting expertise in ceramics and metals. Desktop Metal anchors its position with bound-metal feedstock systems targeting low-volume automotive tooling.
Metal jet 3D printing deposits liquid binding agents onto successive layers of metal powder, followed by sintering to achieve near-full density parts with feature resolutions below 50 microns, serving applications where conventional machining cannot produce internal conformal cooling channels or lattice structures. Aerospace applications command premium positioning due to FAA airworthiness certification requirements and long qualification cycles that lock in supplier relationships. Medical implants represent the fastest-expanding application segment as FDA 510(k) pathways for patient-specific devices streamline market access. Among technology categories, binder jetting leads in unit shipments while selective laser melting retains margin concentration in titanium aerospace work.
FAA certification standards for flight-critical components and FDA quality system regulation under 21 CFR Part 820 shape product development timelines and capital allocation for metal jet equipment investments. EPA powder handling mandates and OSHA respiratory protection standards drive sealed-system design requirements that elevate equipment cost floors. Stakeholders must weigh qualification pathway duration against production volume economics when selecting between binder jetting and laser-based alternatives for new manufacturing cells.
Market Dynamics
Metal jet 3D printing is consolidating around binder jetting architectures as aerospace and medical OEMs demand production-scale throughput over prototyping flexibility, compressing equipment supplier margins while elevating software and materials lock-in as profit centers.
Growth Catalysts
- EU Green Deal compliance:REACH mandates on powder handling and waste reduction push automotive and tooling manufacturers toward closed-loop metal jet systems with integrated recycling.
- Titanium aerospace work:FAA airworthiness certification pathways for flight-critical turbine components create multi-year supplier relationships that stabilize equipment demand.
- Germany:Stuttgart and Munich precision tooling clusters integrate metal jet cells into serial production lines, establishing reference architectures for European adoption.
Market Restraints
- Feedstock cost volatility:Specialized metal powders and proprietary binders concentrate pricing power with limited qualified suppliers, squeezing job shop margins.
- Sintering furnace bottleneck:Batch thermal processing limits effective throughput regardless of print speed, constraining true serial production economics.
- Selective laser melting substitution:Laser-based systems retain titanium aerospace dominance where full-density requirements exceed binder-jetted green part capabilities.
Strategic Opportunities
- Patient-specific medical devices:FDA 510(k) pathway streamlines market access for cranial implants and orthopedic guides, opening high-margin low-volume segments.
- Conformal cooling tooling:Automotive injection mold makers adopt metal jet for lattice-structured cooling channels that cut cycle times 20-40 percent versus drilled straight channels.
- Software subscription models:Real-time process monitoring and predictive maintenance modules shift revenue from one-time hardware sales to recurring annual licenses.
Industry Challenges
- Multi-physics simulation expertise:Sintering distortion prediction requires rare combined skills in thermal modeling, materials science, and machine operation.
- Post-processing integration:Green part depowdering, sintering, and finishing equipment from disparate vendors creates workflow fragmentation and quality variance.
- ISO/ASTM standardization gaps:Absence of unified test methods for as-sintered properties prolongs customer qualification cycles and limits cross-platform part interchangeability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metal Jet 3D Printing Technology Market |
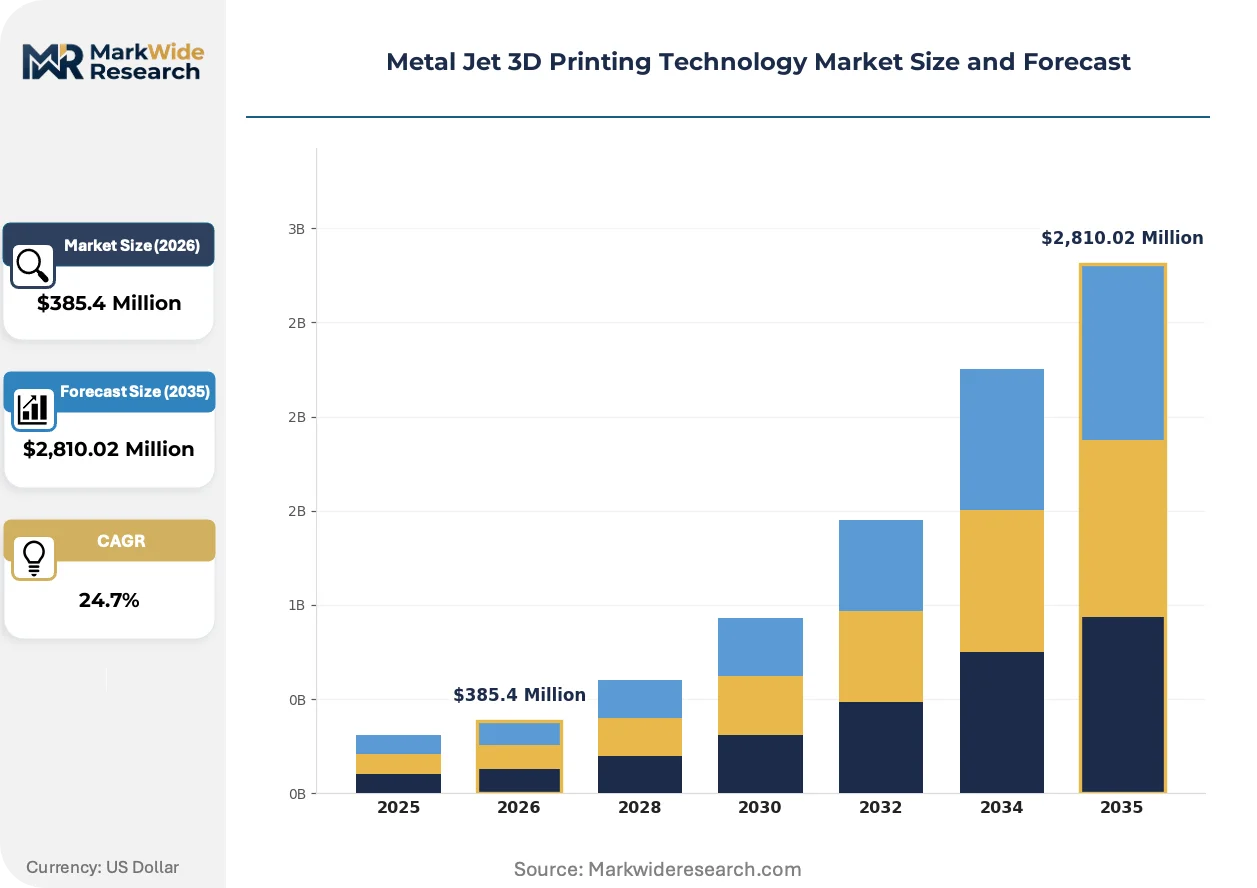
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $2,810.02 Million |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metal Powder, Bound Metal, Composite Material, Ceramic Material Application: Aerospace, Automotive Components, Medical Implants, Industrial Prototyping Technology: Binder Jetting, Selective Laser Melting, Direct Energy Deposition, Metal Extrusion End User: Aerospace Manufacturers, Medical Device Firms, Automotive OEMs, Tooling Companies |
| Companies Covered | Desktop Metal, XJet, Tritone Technologies, Markforged, HP Inc., Velo3D, 3D Systems, Stratasys, GE Additive, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metal Jet 3D Printing Technology Market Trends and Innovations
Process control software and machine learning are reshaping competitive positioning in metal jet, transforming what was hardware-centric equipment sales into data-driven manufacturing platforms.
Single-pass binder jetting is consolidating as the dominant throughput architecture. This technology deposits binding agent across full powder layers in one continuous motion, eliminating reciprocating print carriage delays. Aerospace Tier 1 suppliers in the US and Germany are piloting these systems for turbine blade tooling. The structural consequence is compressing unit economics for aluminum and stainless steel parts below selective laser melting thresholds in non-flight-critical applications.
REACH compliance deadlines in Europe are forcing reformulation of legacy binder chemistries. ECHA restrictions on formaldehyde-releasing compounds and volatile organic compounds push suppliers toward aqueous and bio-based alternatives. German automotive OEMs now specify reduced-waste binder systems as procurement prerequisites, locking in compliant suppliers for multi-year tooling contracts.
Buyer concentration among aerospace primes and medical device contract manufacturers is shifting negotiation leverage toward performance guarantees and uptime commitments. Equipment vendors face pressure to embed predictive maintenance and remote diagnostics as standard offerings rather than premium add-ons. This behavioral shift is most visible in Germany and the US, where automotive and aerospace clusters negotiate enterprise-wide fleet purchases with service-level agreements spanning five to seven years.
Metal Jet 3D Printing Technology Market Segmentation
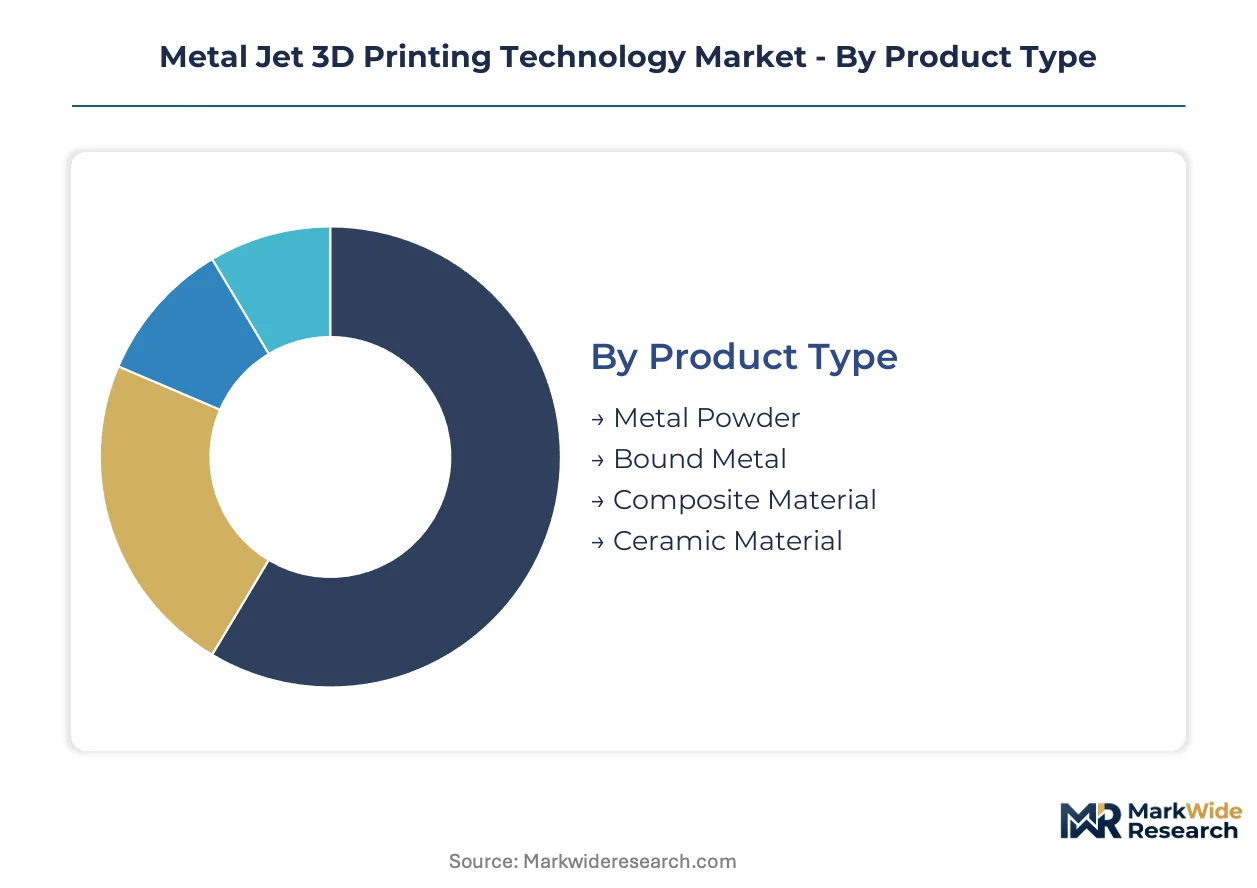
Metal jet 3D printing technology fragments across four distinct segmentation dimensions that shape procurement patterns and supplier positioning. Product type determines feedstock economics and post-processing requirements. Application segments separate qualification-heavy aerospace work from volume-driven automotive tooling. Technology choice locks buyers into specific capital equipment ecosystems with divergent throughput profiles. End-user concentration among primes and contract manufacturers concentrates negotiating leverage.
Product Type:
Cost tier separates commodity powders from proprietary bound-metal systems with embedded IP value.
- Metal Powder:Atomized stainless steel, aluminum, and titanium powders constitute the foundational feedstock for binder jetting systems. Aerospace manufacturers in Germany and the US dominate procurement, driven by FAA certification requirements that lock in qualified supplier relationships and stabilize long-term contracts.
- Bound Metal:Polymer-bound metal filament and rods enable extrusion-based printing before thermal debinding and sintering. Tooling companies in Stuttgart and Munich precision clusters favor this format for low-volume injection mold inserts where geometric complexity outweighs throughput requirements.
- Composite Material:Metal-matrix composites with ceramic reinforcement target wear-resistant industrial applications.
- Ceramic Material:Technical ceramics processed through nanoparticle jetting serve high-temperature tooling and biomedical applications.
Metal powder leads volumes today; bound metal is gaining share fastest in automotive prototyping cells.
Application:
Margin concentration and qualification duration separate flight-critical work from production tooling.
- Aerospace:Turbine blades, structural brackets, and fuel system components demand near-full density with FAA airworthiness certification. US and German Tier 1 suppliers anchor demand, constrained by multi-year qualification cycles that freeze supplier relationships and equipment choices.
- Automotive Components:Conformal cooling channels in injection molds and powertrain fixtures cut cycle times versus conventional drilling. Stuttgart automotive OEMs specify metal jet tooling for serial production, establishing reference architectures across European supply chains.
- Medical Implants:Patient-specific cranial plates and orthopedic guides exploit FDA 510(k) pathway streamlining.
- Industrial Prototyping:Functional metal prototypes bridge design validation and low-volume production.
Automotive components lead volumes today; medical implants are expanding most quickly on regulatory pathway efficiency.
Technology:
Throughput architecture and capital intensity separate production-scale binder jetting from precision laser systems.
- Binder Jetting:Single-pass deposition of liquid binding agent across full powder layers eliminates reciprocating delays. Aerospace and automotive OEMs in Germany and the US pilot these systems for aluminum and stainless steel production parts where speed outweighs titanium density requirements.
- Selective Laser Melting:Laser fusion of powder beds achieves full density in titanium and nickel superalloys. US aerospace primes retain this technology for flight-critical turbine components where binder-jetted green parts cannot meet structural specifications.
- Direct Energy Deposition:Wire or powder-fed laser/welding systems repair existing components and build large structures.
- Metal Extrusion:Fused filament fabrication with bound-metal feedstock targets low-cost prototyping and tooling.
Binder jetting leads volumes today; selective laser melting retains margin concentration in certified aerospace work.
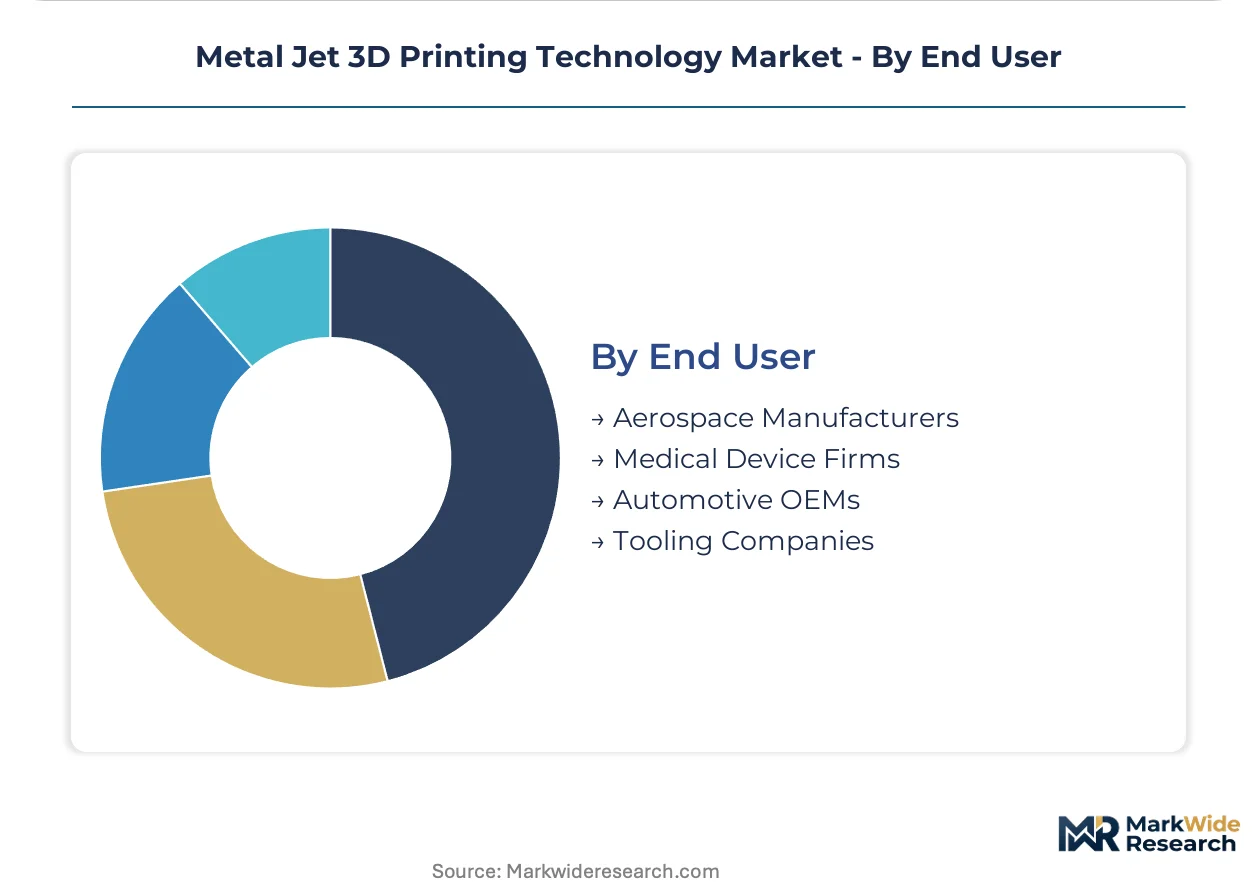
End User:
Volume scale and in-house capability determine whether buyers purchase equipment or outsource to service bureaus.
- Aerospace Manufacturers:Boeing, Airbus, and their Tier 1 suppliers operate captive metal jet cells for qualified component production. FAA certification requirements and long supplier qualification cycles concentrate demand among established primes with capital for multi-year equipment amortization.
- Medical Device Firms:Stryker, Zimmer Biomet, and contract manufacturers exploit FDA 510(k) streamlining for patient-specific implants. These firms prioritize software-integrated systems with traceability documentation for quality system regulation compliance.
- Automotive OEMs:BMW, Volkswagen, and Mercedes-Benz integrate metal jet into Stuttgart and Munich tooling clusters.
- Tooling Companies:Injection mold makers and die casters adopt conformal cooling applications to differentiate service offerings.
Aerospace manufacturers lead volumes today; medical device firms are climbing the fastest on regulatory pathway advantages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands the highest equipment density per capita, while the United States leads in absolute installed base and certification-driven contract values. China accelerates domestic binder jetting adoption through state-backed advanced manufacturing initiatives. Japan and the United Kingdom anchor specialized medical and aerospace qualification pathways respectively.
United States
FAA airworthiness certification for turbine components and defense procurement sustain multi-year equipment contracts. EPA powder handling mandates under 40 CFR Part 68 drive sealed-system design investments. Aerospace Tier 1 suppliers in Connecticut and California operate captive metal jet cells for qualified flight-critical production.
Germany
REACH compliance deadlines and EU Green Deal carbon targets push automotive OEMs toward closed-loop powder recycling. ECHA restrictions on formaldehyde-releasing binders force reformulation of legacy chemistries. Stuttgart and Munich precision tooling clusters integrate single-pass binder jetting into serial injection mold production lines.
China
MIIT advanced manufacturing directives and dual carbon goals accelerate domestic equipment substitution for imported laser systems. GB standards development for additive manufacturing quality assurance proceeds through SAMR technical committees. Yangtze River Delta aerospace suppliers pilot metal jet systems for non-flight-critical bracket production.
Japan
METI industrial competitiveness programs and PMDA streamlined pathways for patient-specific implants concentrate demand among orthopedic device manufacturers. JIS standardization efforts for metal powder specifications reduce supplier qualification friction. Nagoya aerospace subcontractors evaluate binder jetting for tooling applications below titanium density thresholds.
United Kingdom
Civil Aviation Authority alignment with EASA certification frameworks preserves aerospace supplier access to continental markets. UK Research and Innovation funding for advanced manufacturing supports metal jet pilot programs at Midlands aerospace clusters. Birmingham and Bristol tooling firms adopt conformal cooling applications for automotive export contracts.
Metal Jet 3D Printing Technology Market Competitive Landscape
Top-tier vendors anchor equipment supply, while mid-tier specialists and regional fabricators fill application-specific niches. The market exhibits moderate consolidation around print-head intellectual property and powder-binder formulation expertise. Three archetypes dominate: diversified technology conglomerates with print-head control, nanoparticle jetting specialists, and bound-metal feedstock innovators. Competitive moves center on strategic partnerships with aerospace primes and vertical integration into captive powder production.
Within the diversified technology tier, HP Inc. and GE Additive occupy positions reflecting deep industrial system integration. XJet exemplifies the nanoparticle specialization archetype with its ceramic and metals capability. Desktop Metal anchors the bound-metal feedstock approach targeting low-volume tooling segments. These three represent distinct strategic vectors rather than direct substitution competitors.
| Leading Market Players |
|---|
| Desktop Metal |
| XJet |
| Tritone Technologies |
| Markforged |
| HP Inc. |
| Velo3D |
| 3D Systems |
| Stratasys |
| GE Additive |
| Others |
Pricing and Supply Chain Analysis
Single-pass binder jetting adoption across German automotive clusters and US aerospace Tier 1 suppliers simultaneously compresses per-part cost economics and concentrates powder supply relationships among qualified vendors meeting FAA and REACH specifications. This technology transition locks buyers into multi-year feedstock contracts while elevating software licensing as the primary margin capture mechanism for equipment vendors.
Pricing Analysis
Capacity additions in Germany and the United States are reshaping price floors for metal jet systems as domestic equipment assembly reduces import tariff exposure and logistics overhead. Three-tier pricing structure across premium flight-certified, standard production-grade, and economy prototyping levels separates aerospace qualification-heavy contracts from automotive tooling volumes. Cost compression in the economy tier intensifies because bound-metal feedstock alternatives displace proprietary powder systems in low-volume applications. Job shops and contract manufacturers exhibit highest price sensitivity, while aerospace primes with captive qualification cycles demonstrate lowest sensitivity due to switching cost barriers.
Supply Chain Analysis
Domestic-content mandates under China's MIIT advanced manufacturing directives and dual carbon goals are reshaping sourcing patterns for critical print-head components and atomized powder feedstock. Supply concentrates in Germany, the United States, and China for specialized metal powders, precision binder formulations, and high-temperature sintering furnaces. Raw material dependencies draw from titanium sponge, stainless steel atomization feedstock, and ceramic nanoparticle precursors. Single-source vulnerability persists in print-head nozzle architectures controlled by HP Inc.'s intellectual property estate. Distribution runs through direct OEM sales for large fleet purchases and authorized service bureaus for mid-volume job shop access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Metal jet 3D printing functions as a stable compounder anchored by multi-year FAA certification cycles that freeze supplier relationships and equipment choices across aerospace supply chains.
For Market Incumbents: Anticipate selective laser melting substitution pressure in titanium flight-critical applications by deepening captive powder production capabilities and embedding predictive maintenance software as standard rather than premium offerings. Lock in Stuttgart and Munich automotive tooling clusters through conformal cooling application engineering partnerships that create switching cost barriers. Certification investment in FDA 510(k) pathway documentation for medical device contract manufacturers represents the priority defensive lever. For New Entrants and Emerging Players: EU Green Deal compliance deadlines in Germany open a window for aqueous binder formulation specialists to displace legacy formaldehyde-releasing chemistries among automotive OEM procurement specifications. Target patient-specific medical implants as the most penetrable segment given streamlined FDA regulatory pathways and lower capital requirements versus aerospace qualification. Pursue software-integrated system sales with traceability documentation as the primary go-to-market angle for medical device contract manufacturers. For Investors and Strategic Acquirers: Valuations sit cheapest among bound-metal feedstock innovators serving low-volume tooling segments where geometric complexity requirements outweigh throughput economics. The five-to-ten-year viability window favors equipment vendors with print-head intellectual property control and vertical integration into powder production. Acquisition target archetype: mid-tier specialists with nanoparticle jetting expertise in ceramics and metals. Watch for sintering furnace bottleneck resolution as the inflection signal indicating true serial production economics have arrived.| Strategic Initiative | Industry Significance |
|---|---|
| Print-Head Intellectual Property Acquisition | HP Inc.'s nozzle architecture control creates defensive moats against Asian equipment entrants. |
| REACH-Compliant Binder Reformulation | ECHA restrictions on formaldehyde-releasing compounds force chemistry transitions among German automotive OEMs. |
| Patient-Specific Medical Device FDA Submission | 510(k) pathway streamlining enables Stryker and Zimmer Biomet contract manufacturers to capture high-margin low-volume segments. |
| Conformal Cooling Tooling Partnership | Stuttgart injection mold makers achieve 20-40 percent cycle time reductions versus drilled straight channels. |
| Predictive Maintenance Software Integration | Real-time process monitoring modules shift revenue from one-time hardware sales to recurring annual licenses. |
Research Methodology
Coverage spans Germany, the United States, China, Japan, and the United Kingdom, with primary inputs from each market gathered through structured interviews with equipment vendor sales directors, aerospace Tier 1 supplier manufacturing engineers, medical device contract manufacturer quality affairs leads, and automotive OEM tooling procurement managers. Secondary validation draws from FAA airworthiness certification filings, FDA 510(k) submission databases, ECHA REACH restriction updates, MIIT advanced manufacturing directives, and SEC equipment supplier 10-K disclosures. Bottom-up installed base counts triangulate against top-down addressable market estimates segmented by technology category and end-use application.
Rate-of-change decomposition separates volume expansion from price trajectory and mix shift effects across the projection horizon. Segmentation dimensions modeled include product type, application, technology architecture, and end-user concentration, with additional granularity on certification status and geographic regulatory cluster. CAGRs derive from logistic diffusion curves fitted to historical adoption patterns in adjacent additive manufacturing technologies, adjusted for metal jet-specific qualification cycle durations and powder-binder supply constraints. Industry-specific forecast inputs incorporate sintering furnace capacity utilization rates and REACH compliance deadline schedules.
Revisions become necessary when FAA certification timeline accelerations, ECHA binder chemistry restrictions, or MIIT domestic-content mandate expansions materialize outside baseline assumptions. Forecasts reflect documented assumptions regarding equipment substitution elasticities and powder supply concentration. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Materials
Aerospace 3D Printing Materials Market
3D Printing Materials
Non-Metal 3D Printing Market
3D Printing Materials
3D Printing Resin Market
3D Printing Materials
Medical 3D Printing Plastics Market
3D Printing Materials
3D Printing Coating Market
3D Printing Materials
Vat Photopolymerization 3D Printing Technology Market
3D Printing Materials
LAMEA 3D Graphene Market
3D Printing Materials
Graphene in 3D Printing Market
3D Printing Materials
Middle East 3D Printing Materials Market
3D Printing Materials
Additive Manufacturing and Materials Market
3D Printing Materials
Advanced Materials for 3D Printing Market
3D Printing Materials
Stainless Steel 3D Printing Market
3D Printing Materials
3D Printing Consumables Market
3D Printing Materials
Global Biocompatible 3D Printing Materials Market
3D Printing Materials
3D Printing Elastomers Market
3D Printing Materials
3D Printing Polymers Market