
 Middle East 3D Printing Materials Market | 2026-2036
Middle East 3D Printing Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East 3D Printing Materials Market Foresight
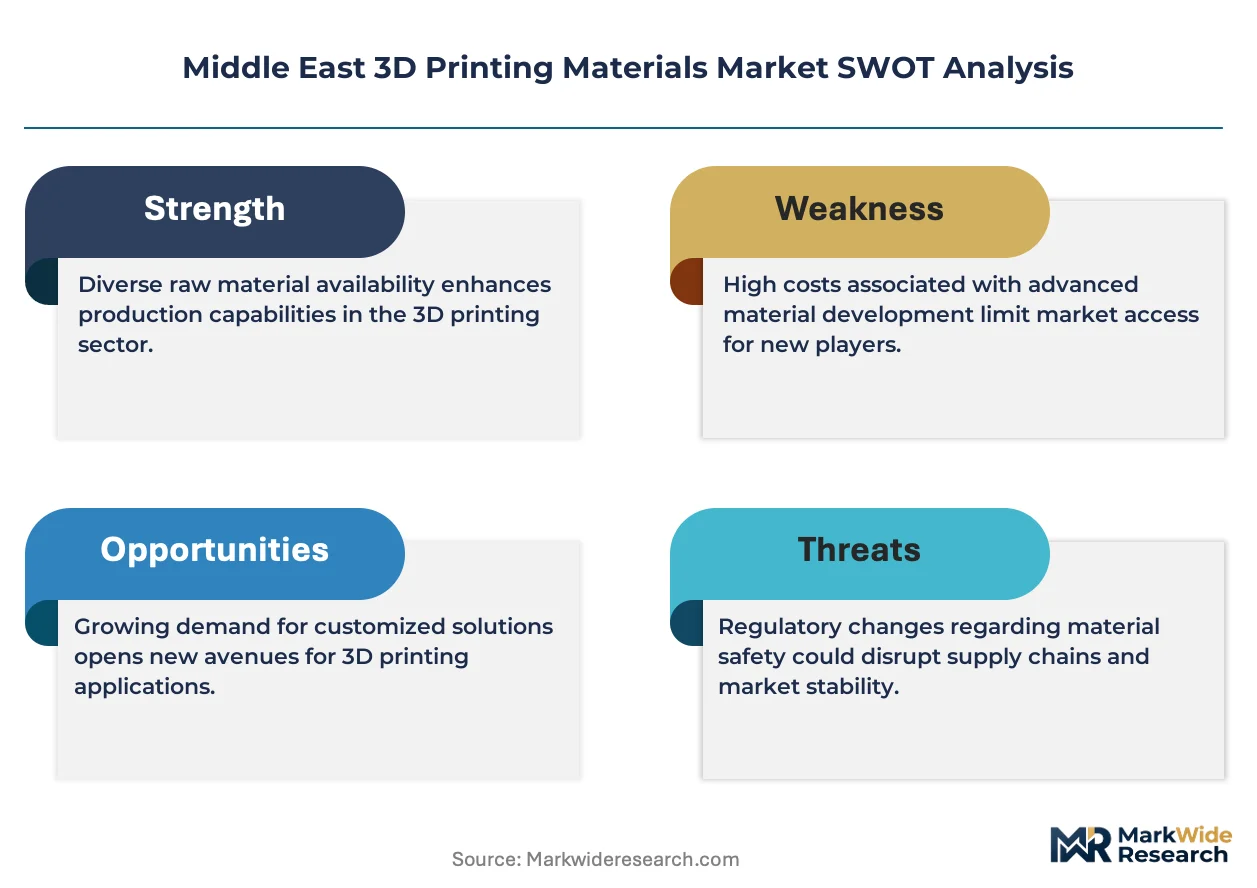
Multi-source procurement of polymer and metal powders is repositioning supply chain resilience as a strategic priority across Gulf additive manufacturing operations. BASF SE leverages its Ludwigshafen material science infrastructure to sustain filament and powder supply commitments into Dubai and Jeddah industrial zones. Stratasys Ltd. anchors its regional presence through certified distributor networks serving aerospace maintenance facilities in the UAE and Saudi Arabia. Evonik Industries AG specializes in high-performance polyamide 12 formulations, differentiating its powder portfolio for selective laser sintering applications in medical and dental device production.
Middle East 3D printing materials comprise thermoplastics, photopolymers, metals, and ceramics formulated as filaments, powders, or resins, with melt flow indices typically ranging from 2–15 g/10min and particle size distributions of 15–45 microns for laser-based processes, serving industrial prototyping, end-use part fabrication, and tooling replacement. FDM technology dominates volume consumption among hobbyists and design studios due to lower equipment barriers, while SLS powder systems capture premium positioning in aerospace and medical segments where dimensional tolerance requirements fall below 0.1 millimeters. PLA and ABS thermoplastics represent the mature baseline for educational and consumer prototyping, whereas nylon formulations and metal powders concentrate margin pools in defense and orthopedic implant applications requiring certified traceability.
SFDA in Saudi Arabia and MOHAP in the UAE govern biocompatibility certification for patient-contact devices, compelling material suppliers to maintain ISO 13485 quality management systems and lot-specific testing documentation. The EU AI Act and CE marking conventions indirectly shape Gulf procurement standards as European OEMs extend their supply chain compliance requirements into regional joint ventures and technology transfer agreements. Stakeholders must monitor how Saudi Arabia's dual carbon goals and the UAE's national advanced manufacturing strategies redirect public R&D funding toward localized powder metallurgy and recycled feedstock development.
Market Dynamics
Gulf aerospace manufacturers are consolidating polymer and metal powder procurement around localized supply hubs, with Saudi Arabia's industrial cities and Dubai's free zones emerging as dual anchors for additive manufacturing feedstock distribution.
Growth Catalysts
- Saudi SFDA Medical Device Pathways:Streamlined biocompatibility certification for patient-contact implants accelerates polyamide 12 and titanium powder qualification timelines for orthopedic device producers in Jeddah and Riyadh.
- UAE Advanced Manufacturing Incentives:Government-backed localization programs in Dubai South and Masdar City provide capital subsidies for selective laser sintering powder production facilities serving aerospace maintenance operations.
- Lightweighting Mandates in Aviation:Gulf carriers' fleet modernization programs drive demand for topology-optimized aluminum and Inconel components requiring certified metal powder traceability from ingot to finished part.
Market Restraints
- Feedstock Import Dependency:High-performance polyamide 12 and cobalt-chrome powders remain concentrated in European and East Asian supply bases, exposing Gulf fabricators to shipping disruptions and currency fluctuation risks.
- Capital Equipment Thresholds:Electron beam melting systems for reactive metal processing require facility investments exceeding mid-tier Gulf machine shop capacity, constraining titanium alloy adoption outside sovereign-funded operations.
- Technical Workforce Scarcity:Qualified process engineers for parameter optimization in laser powder bed fusion remain concentrated in Western aerospace clusters, delaying technology transfer to Saudi and Emirati production floors.
Strategic Opportunities
- Qatar and Kuwait Industrial Zones:Underdeveloped additive manufacturing infrastructure in Doha's Ras Laffan and Kuwait's Al-Zour presents first-mover positioning for material suppliers establishing regional powder blending and quality testing facilities.
- Construction Sector Adoption:Large-format concrete and polymer composite printing for modular housing aligns with Saudi Vision 2030 giga-project timelines, creating demand for specialized extrusion-grade cementitious formulations.
- Recycled Feedstock Development:UAE circular economy mandates and Saudi dual carbon goals redirect public R&D funding toward localized metal powder atomization from machining scrap and polymer filament reprocessing from industrial waste streams.
Industry Challenges
- ISO 13485 Quality System Implementation:Medical device material suppliers face 12-18 month certification timelines to meet SFDA and MOHAP documentation requirements for lot-specific mechanical testing and biocompatibility validation.
- Multi-Material Process Integration:Aerospace tier-1 suppliers struggle to qualify hybrid workflows combining polymer sacrificial tooling with direct metal printing, requiring extensive parameter development and destructive testing protocols.
- Intellectual Property Licensing Complexity:Powder bed fusion machine OEMs enforce restrictive material compatibility clauses, limiting Gulf fabricators' ability to source third-party metal powders at competitive pricing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East 3D Printing Materials Market |
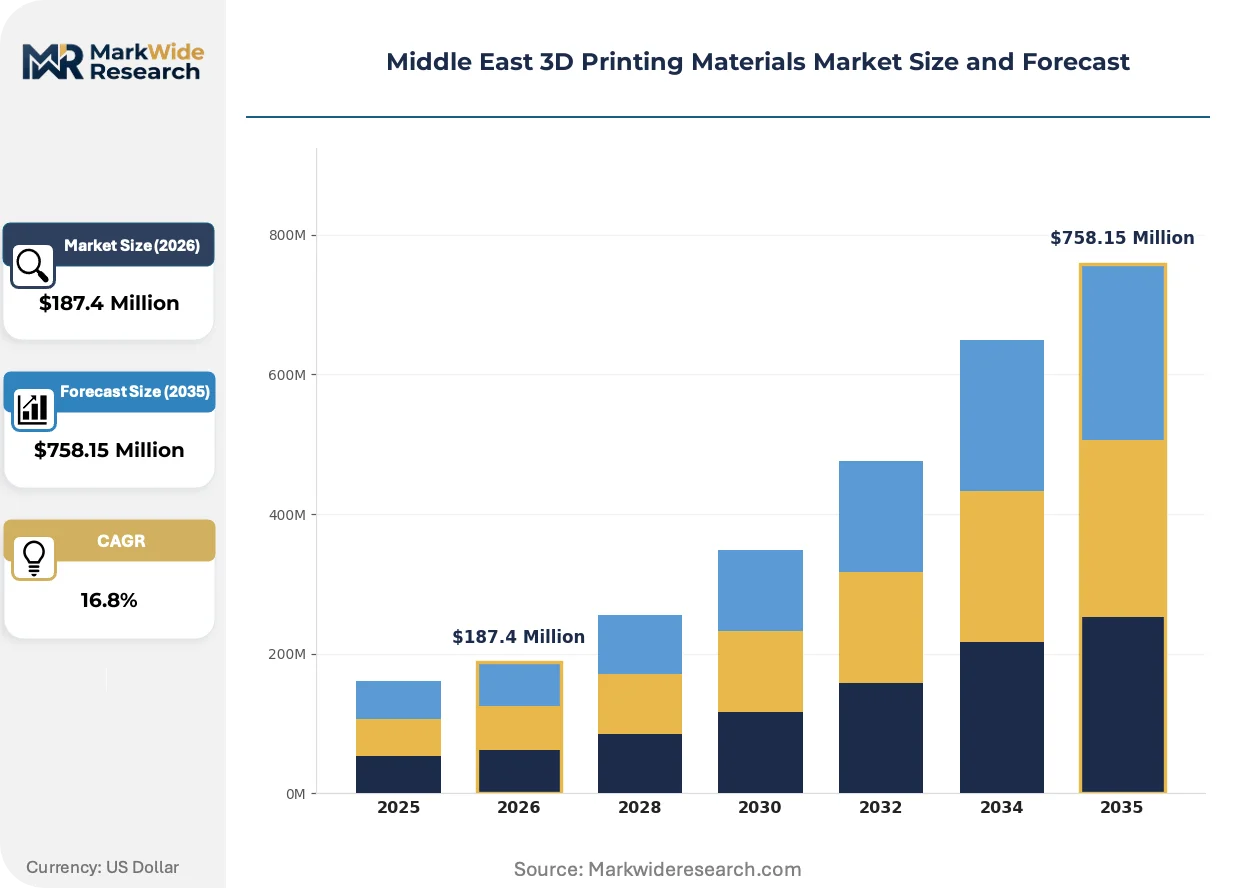
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $758.15 Million |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: PLA, ABS, Nylon, PETG Application: Aerospace, Automotive, Medical, Consumer Goods Technology: FDM, SLS, SLA, DLP End User: Manufacturers, Designers, Researchers, Hobbyists |
| Companies Covered | EOS GmbH, BASF SE, Stratasys Ltd., HP Inc., Evonik Industries AG, 3D Systems, Inc., Arkema S.A., General Electric (GE) Additive, Materialise NV, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East 3D Printing Materials Market Shifts & Advancements
Material formulation science and regulatory alignment are compressing qualification cycles for production-grade additive manufacturing across Gulf industrial zones.
High-flow polyamide 12 powders optimized for multi-laser selective laser sintering systems are consolidating process throughput advantages in dental aligner and surgical guide production. Saudi dental laboratories in Riyadh's healthcare clusters are adopting these formulations at accelerated pace to meet same-day appliance delivery commitments. The technology is consolidating equipment vendor market positions around integrated powder-to-part workflow packages rather than standalone material sales.
SFDA's alignment with EU MDR technical documentation requirements is compressing biocompatibility certification timelines for imported photopolymers and titanium alloys. Gulf medical device distributors now demand ISO 13485-certified supply chains with lot-specific USP Class VI testing data prior to contract execution. Orthopedic implant manufacturers in Jeddah's industrial city are responding by qualifying dual-source powder suppliers with pre-submitted master file documentation.
Aerospace maintenance, repair, and overhaul facilities are compressing spare part procurement cycles through distributed powder inventory agreements with Jebel Ali free zone distributors. Legacy broker-based sourcing for obsolete casting patterns is yielding to direct digital warehousing where STL files and certified powder lots ship concurrently to Gulf MRO stations. The shift is most visible in Emirates and Saudia engineering facilities where flight-critical bracketry now prints on-demand from localized titanium powder stocks.
Middle East 3D Printing Materials Market Segmentation
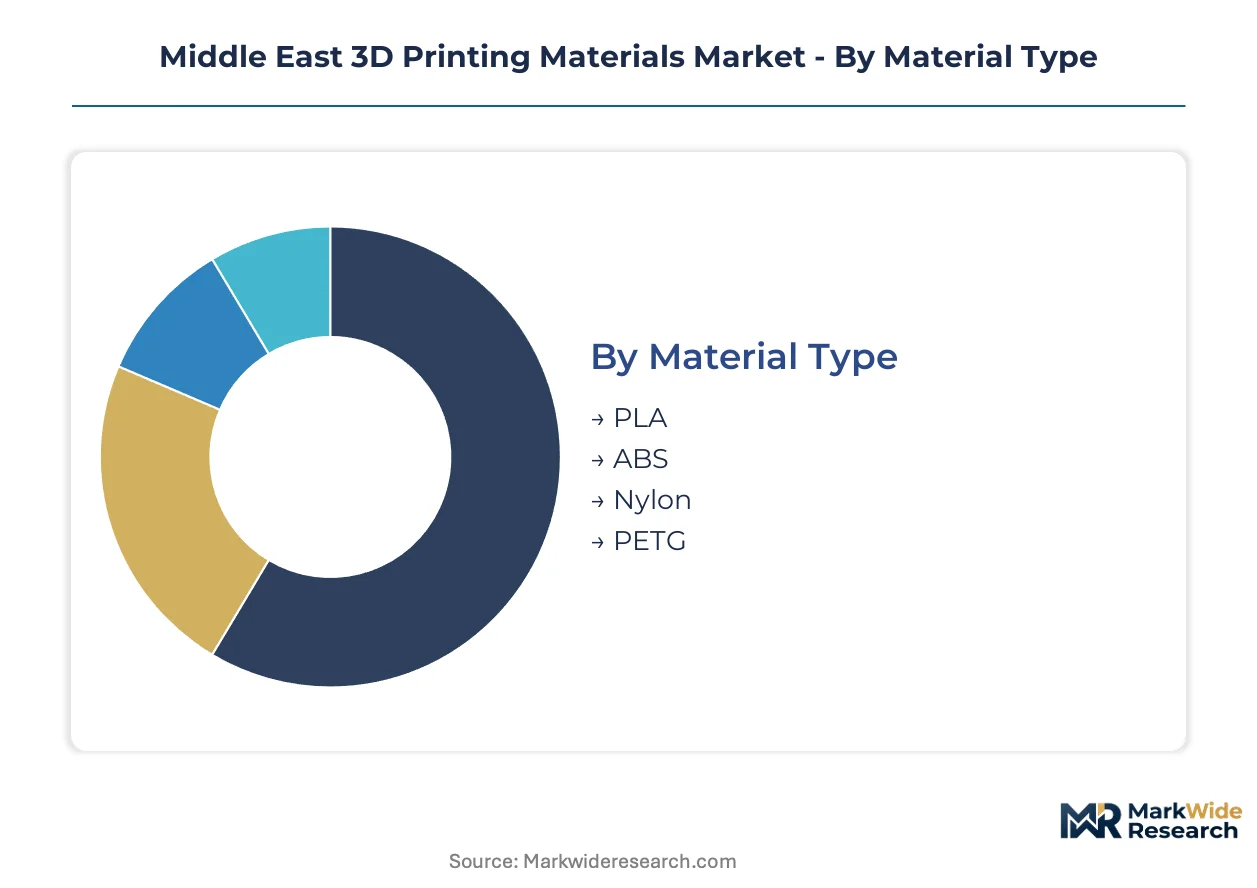
Material selection in Gulf additive manufacturing operations hinges on thermal performance requirements and regulatory compliance pathways. Segmentation reveals how aerospace-grade metal powders command premium positioning while commodity thermoplastics sustain volume throughput across educational and prototyping installations.
Material Type:
Volume concentrates in entry-level thermoplastics, while margin pools accrue to engineering polymers with certified traceability.
- PLA:Polylactic acid filaments derived from corn starch or sugarcane offer biodegradability and low-temperature processing at 180-220°C extrusion ranges. Saudi technical institutes and Dubai design studios purchase PLA in bulk for foundational prototyping, though heat deflection limitations below 55°C restrict functional end-use deployment.
- ABS:Acrylonitrile butadiene styrene delivers impact resistance and acetone vapor smoothing compatibility for presentation-grade models. Automotive styling centers in Jeddah industrial zones specify ABS for interior trim prototypes requiring dimensional stability across 40°C ambient temperature swings.
- Nylon:Polyamide formulations, particularly PA12 and PA11 variants, dominate selective laser sintering workflows for medical device manufacturers seeking USP Class VI biocompatibility certification.
- PETG:Polyethylene terephthalate glycol combines chemical resistance with FDA-compliant food contact properties, finding traction in packaging prototype development across UAE free zone manufacturing clusters.
Today's leader: Nylon. Tomorrow's challenger: PETG.
Application:
Defense and medical procurement standards are compressing qualification timelines for production-grade materials.
- Aerospace:Topology-optimized aluminum and Inconel components for Gulf carrier fleet modernization require certified powder traceability from atomization through finished part. Emirates Engineering and Saudia Technical Services maintain localized titanium powder inventories for flight-critical bracketry.
- Automotive:Jeddah-based styling studios and Dubai South mobility clusters drive ABS and nylon consumption for interior trim validation and wind tunnel modeling.
- Medical:SFDA-aligned biocompatibility pathways for orthopedic implants concentrate demand on titanium alloys and high-purity photopolymers with ISO 13485 documentation.
- Consumer Goods:Personalized product fabrication and jewelry casting patterns sustain photopolymer resin throughput in Sharjah and Riyadh retail-adjacent production facilities.
Aerospace captures the steepest expansion trajectory as distributed manufacturing displaces legacy casting supply chains.
Technology:
Equipment capital thresholds stratify adoption between hobbyist studios and certified production floors.
- FDM:Fused deposition modeling dominates volume consumption through sub-$5,000 desktop systems deployed across Saudi technical colleges and Dubai maker spaces. Material extrusion of PLA and ABS filaments sustains educational pipeline development for advanced manufacturing workforce training.
- SLS:Selective laser sintering of nylon powders captures premium positioning in medical and dental laboratories where 0.1mm dimensional tolerances govern appliance fit. Riyadh healthcare clusters are adopting multi-laser systems for same-day surgical guide production.
- SLA:Stereolithography vat photopolymerization serves jewelry and dental mold applications requiring surface finishes below 25 microns Ra.
- DLP:Digital light processing accelerates ceramic and high-temperature resin throughput for investment casting patterns in Kuwaiti and Qatari industrial zones.
FDM sustains installed base leadership. SLS is gaining share fastest through healthcare certification alignment.
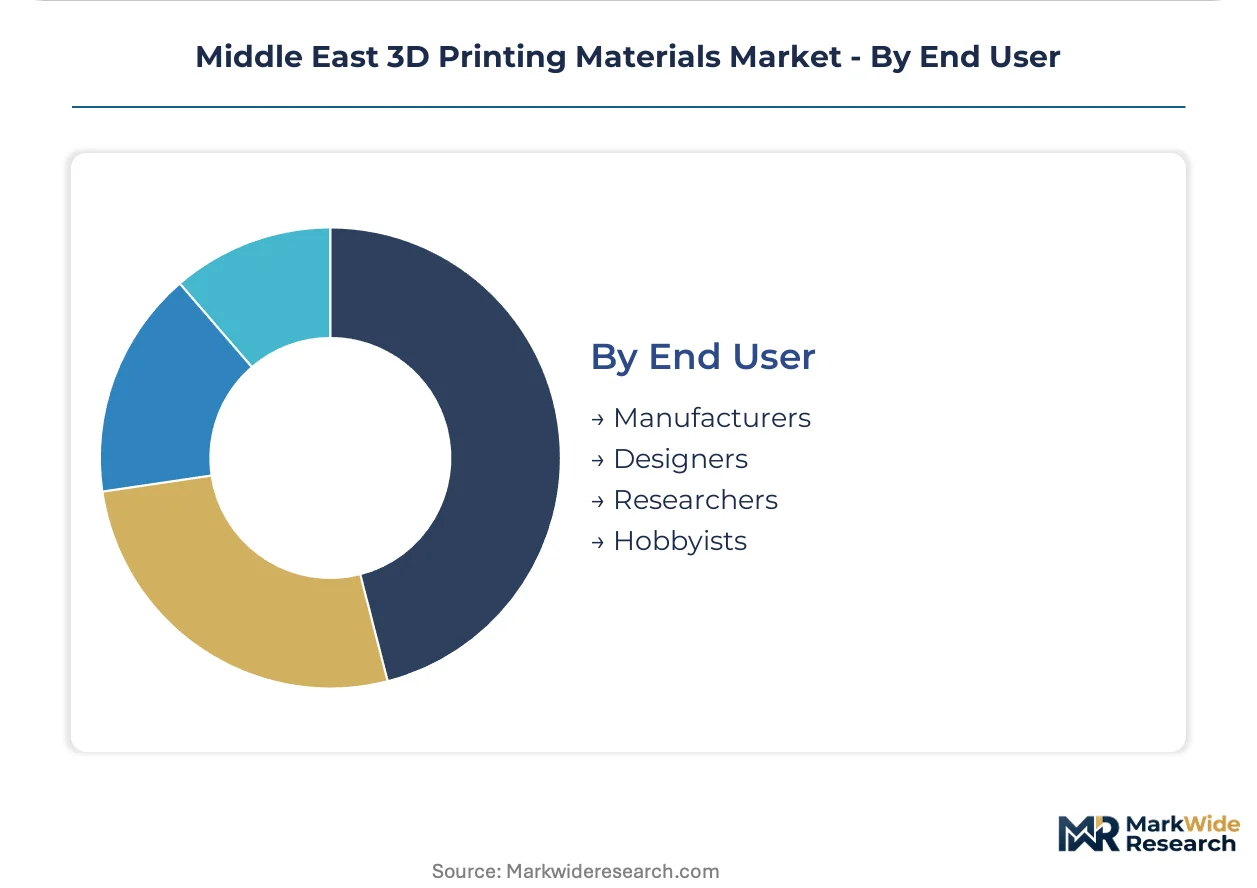
End User:
Procurement sophistication separates production-scale buyers from price-sensitive entry-level adopters.
- Manufacturers:Aerospace tier-1 suppliers and medical device producers in Saudi industrial cities specify lot-controlled metal powders with mechanical testing documentation. SFDA master file submissions require suppliers to maintain ISO 13485 quality systems.
- Designers:Architectural and product design studios in Dubai Design District prioritize full-color material jetting and multi-material capabilities for client presentation models.
- Researchers:University laboratories at KAUST and Khalifa University drive experimental formulation development for construction-scale concrete printing and recycled feedstock characterization.
- Hobbyists:Consumer filament purchases through e-commerce channels sustain PLA volume, though price compression limits supplier margin extraction.
Manufacturers command pricing power through certification requirements. Researchers are expanding most quickly via sovereign R&D funding redirection.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's industrial cities anchor regional additive manufacturing feedstock demand, with Jeddah and Riyadh clusters driving polymer and metal powder procurement for aerospace and medical device fabrication.
Saudi Arabia
King Abdullah Economic City and Jeddah Industrial City concentrate selective laser sintering powder demand for dental aligner production. SFDA medical device registration pathways compress biocompatibility certification timelines for orthopedic implant materials. Riyadh healthcare clusters are adopting multi-laser nylon systems for same-day surgical guide manufacturing.
United Arab Emirates
Dubai South and Masdar City free zones attract selective laser sintering powder production facilities through advanced manufacturing incentives. MOHAP biocompatibility standards govern patient-contact device material qualification for dental and orthopedic applications. Jebel Ali free zone distributors maintain localized titanium powder inventories for Emirates Engineering flight-critical bracketry.
Qatar
Ras Laffan Industrial City presents first-mover positioning for material suppliers establishing regional powder blending capabilities. The country's national industrial development strategy prioritizes advanced manufacturing localization. Doha's underdeveloped additive manufacturing infrastructure creates openings for certified distributor networks serving energy sector maintenance operations.
Kuwait
Al-Zour industrial zone lacks established additive manufacturing feedstock distribution, exposing fabrication shops to import lead time volatility. The central government's industrial diversification programs target manufacturing sector expansion. Kuwait City technical institutes drive PLA and ABS filament consumption for workforce training pipelines.
Israel
Tel Aviv metropolitan medical device startups demand high-purity photopolymers with ISO 13485 documentation for surgical guide production. The national innovation authority directs R&D funding toward aerospace-grade metal powder characterization. Haifa's defense-industrial complex qualifies hybrid polymer-metal workflows for rapid tooling applications.
Middle East 3D Printing Materials Market Competitive Landscape
Global majors compete with regional champions across material formulation certification and localized distribution reach. Market structure stratifies into three tiers: integrated chemical conglomerates with powder atomization capabilities, specialized polymer formulators serving healthcare segments, and equipment-anchored material vendors bundling feedstock with hardware service contracts. Dominant competitive moves include distributor network expansion into Gulf free zones and strategic partnerships with sovereign industrial development funds.
Among German-headquartered specialists, EOS GmbH and Evonik Industries AG exemplify the premium powder formulation archetype, occupying positions anchored in high-performance polyamide and metal alloy development for laser-based systems. BASF SE represents the integrated chemical conglomerate tier, leveraging Ludwigshafen infrastructure to sustain filament and powder supply commitments into Dubai and Jeddah industrial zones.
| Leading Market Players |
|---|
| EOS GmbH |
| BASF SE |
| Stratasys Ltd. |
| HP Inc. |
| Evonik Industries AG |
| 3D Systems, Inc. |
| Arkema S.A. |
| General Electric (GE) Additive |
| Materialise NV |
| Others |
Supply & Pricing Matrix
Sovereign-backed localization programs in Saudi Arabia and the UAE have concentrated powder production capacity within Gulf industrial zones, compressing pricing power for imported feedstocks while elevating margin capture for domestic blenders serving SFDA-certified medical device manufacturers.
Pricing Analysis
Input-cost pass-through from polyamide 12 and titanium powder atomization governs contract pricing for Gulf aerospace and medical device fabricators. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13485-certified medical lots from industrial-grade powder batches and commodity filament spools. Pricing pressure stems from European and East Asian suppliers absorbing currency fluctuation risks to defend market share in Dubai free zones. Hobbyist PLA buyers exhibit acute price sensitivity, whereas orthopedic implant manufacturers prioritize lot-traceability premiums over per-kilogram differentials.
Supply Chain Analysis
Logistics and freight cost volatility from European and East Asian powder atomization centers exposes Gulf fabricators to 8-12 week import lead times for high-performance polyamide 12 and cobalt-chrome formulations. Supply concentrates in Germany, China, and Japan for specialized metal powders and engineering polymers. Raw material dependencies span caprolactam monomers, titanium sponge, and photopolymer resin precursors. Single-source vulnerability persists for electron beam melting-grade titanium alloys. Distribution runs through Jebel Ali and Jeddah free zone distributors maintaining localized inventory buffers for Emirates Engineering and Saudia Technical Services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Gulf additive manufacturing materials hinges on localized powder atomization investments that compress import dependency while capturing premium-tier certification markups from SFDA-aligned orthopedic implant producers.
For Market Incumbents: To counter feedstock import dependency and currency exposure, BASF SE and Evonik Industries AG should anchor backward integration into Saudi industrial city powder blending facilities. Stratasys Ltd. must deepen distributor exclusivity clauses in Dubai South free zones to preempt European competitor encroachment.
For New Entrants and Emerging Players: Launch via certified distributor partnerships targeting Qatar's Ras Laffan and Kuwait's Al-Zour industrial zones where additive manufacturing infrastructure remains underdeveloped. Construction-grade cementitious formulations for Saudi giga-projects offer the most penetrable white-space, with direct sales to sovereign-backed EPC contractors as the optimal go-to-market angle.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional powder blending specialists with pre-qualified ISO 13485 documentation and existing SFDA master file submissions. Long-term viability centers on capturing localization incentives under Saudi Vision 2030 and UAE advanced manufacturing strategies. The signal to watch is sovereign R&D funding redirection toward recycled feedstock development and circular economy mandates.
| Strategic Initiative | Industry Significance |
|---|---|
| Localized Powder Atomization Facility | Captures Saudi SFDA certification premiums while reducing European import lead times for Jeddah medical device clusters. |
| ISO 13485 Quality System Investment | Unlocks orthopedic implant material contracts requiring lot-specific biocompatibility documentation under SFDA pathways. |
| Recycled Feedstock Development Program | Aligns with UAE circular economy mandates and Saudi dual carbon goals redirecting sovereign R&D funding. |
| Multi-Laser SLS Powder Formulation | Consolidates equipment vendor positions in Riyadh dental laboratories demanding same-day surgical guide throughput. |
| Construction-Scale Extrusion Material Launch | Addresses modular housing demand from Saudi giga-projects through specialized cementitious and polymer composite formulations. |
Research Methodology
Bottom-up aerospace and medical device demand modeling reconciled against top-down powder production capacity tracking forms the analytical core of this study. Primary interviews with plant managers at Saudi industrial city facilities, procurement leads at Emirates Engineering, biomedical engineers in Riyadh healthcare clusters, and distribution channel partners in Jebel Ali free zone were validated against secondary sources including SFDA medical device registration databases, UAE Ministry of Industry and Advanced Technology policy filings, SEC 10-K disclosures from listed material suppliers, and customs trade data for polymer and metal powder imports.
Input-output matrices mapping filament extrusion throughput, selective laser sintering powder consumption, and metal powder bed fusion adoption across the analysis window were segmented by material type, application, technology, and end-user procurement sophistication. CAGRs were derived from elasticity-adjusted demand projections and supply-side capacity buildout schedules, incorporating SFDA regulatory timeline compression and UAE localization incentive uptake as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including unannounced sovereign industrial policy shifts, abrupt feedstock trade restriction implementations, and technology transfer agreement renegotiations. Forecasts reflect documented assumptions about regulatory alignment continuity and capital equipment deployment schedules. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Materials
3D Printing Elastomers Market
3D Printing Materials
Stainless Steel 3D Printing Market
3D Printing Materials
Vat Photopolymerization 3D Printing Technology Market
3D Printing Materials
Non-Metal 3D Printing Market
3D Printing Materials
Polypropylene in 3D Printing Market
3D Printing Materials
LAMEA 3D Graphene Market
3D Printing Materials
Global Metal Additive Manufacturing Market
3D Printing Materials
3D Printing Powder Market
3D Printing Materials
3D Printing Coating Market
3D Printing Materials
Global 3D Printing Construction Material Market
3D Printing Materials
Global Arf Dry and Immersion Resist Materials Market
3D Printing Materials
Advanced Materials for 3D Printing Market
3D Printing Materials
3D Printing Photopolymers Market
3D Printing Materials
Global 3D Printing Ceramics Market
3D Printing Materials
3D Printing Iron Powder Market
3D Printing Materials
Industrial 3D Printing Plastic Market