
 Industrial 3D Printing Plastic Market | 2026-2036
Industrial 3D Printing Plastic Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial 3D Printing Plastic Market Insights
Aftermarket service revenue is reshaping margin capture across the industrial 3D printing plastic value chain. Stratasys Ltd. leverages its installed base of fused deposition systems to sustain recurring material and service income. BASF SE anchors polymer formulation leadership through backward integration into specialized nylon and photopolymer feedstocks. EOS GmbH dominates powder-bed polymer printing in European aerospace and medical tooling applications.
Industrial 3D printing plastic encompasses thermoplastic and photopolymer materials formulated for layer-by-layer additive manufacturing, typically processed at build temperatures between 180°C and 380°C depending on polymer class, to produce functional prototypes and end-use components with tolerances reaching ±0.1 mm. These materials serve industries requiring geometric complexity, weight reduction, or low-volume production without hard tooling investment. Powder materials command premium positioning in aerospace and healthcare segments where selective laser sintering of polyamide 12 delivers isotropic mechanical properties. Resin formulations for stereolithography and digital light processing are accelerating fastest in dental and hearing-aid production, where voxel-level precision reduces post-processing labor. Filament extrusion retains volume leadership in prototyping and jigs across automotive supply chains.
FDA material qualification protocols and EU REACH substance restrictions jointly determine which polymer chemistries gain commercial traction in medical and consumer-facing applications. ISO 10993 biocompatibility standards and ASTM F3301 process specification frameworks further segment market access between certified and uncertified material suppliers. Stakeholders must monitor evolving EPA emissions guidance for powder handling facilities and the EU Green Deal's emerging plastics circularity mandates, as these frameworks will reshape feedstock sourcing and recycling infrastructure requirements.
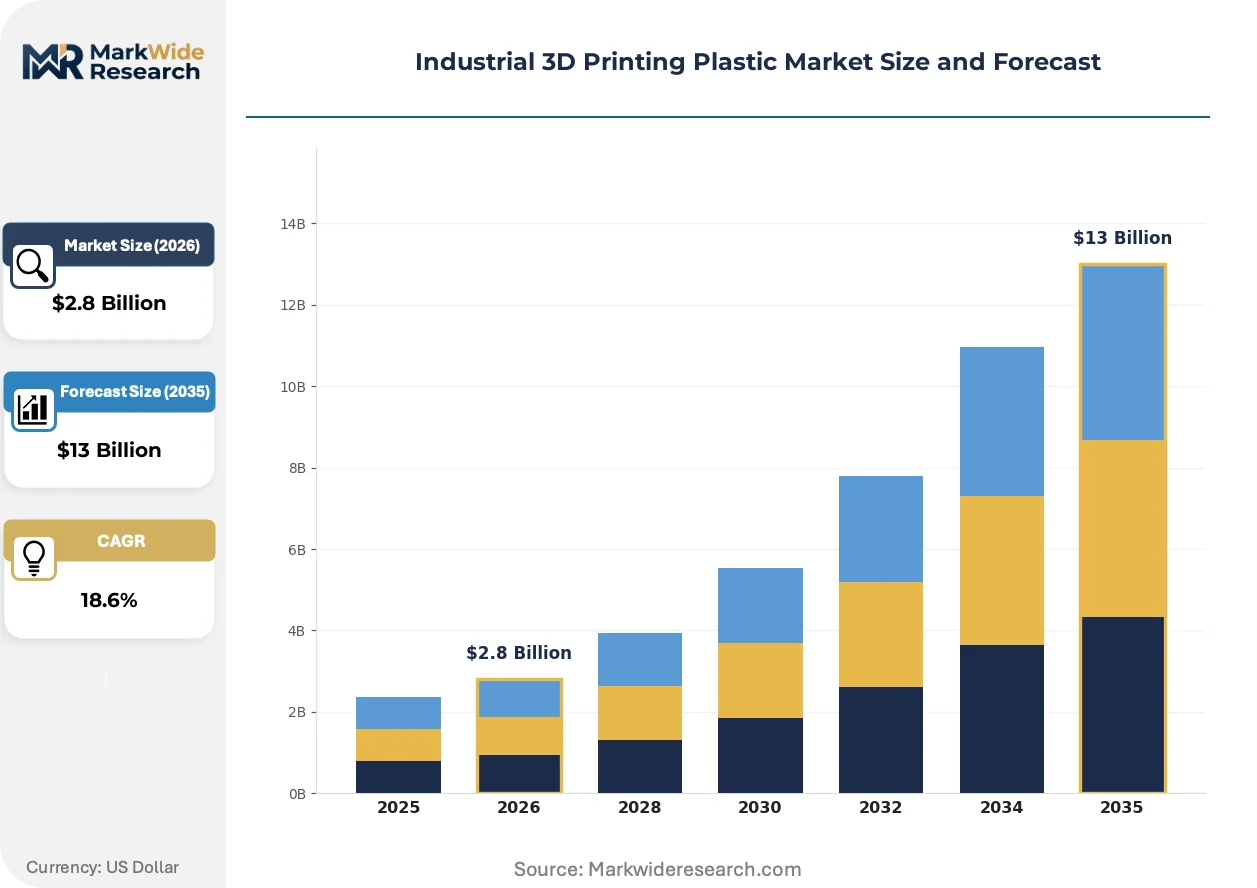
Market Dynamics
Flight-critical aerospace adoption of additively manufactured polymer components is compressing qualification timelines and forcing material suppliers to integrate process-parameter datasets with raw feedstock specifications.
Growth Catalysts
- REACH substance restrictions:ECHA's tightening polymer registration requirements are filtering out uncertified suppliers and concentrating demand on qualified European feedstock producers.
- Selective laser sintering of polyamide 12:Aerospace tooling and medical device manufacturers prioritize isotropic mechanical properties achievable only through powder-bed fusion processes.
- Germany:EOS GmbH and regional chemical suppliers anchor industrial polymer powder ecosystems that accelerate regional qualification pathways.
Market Restraints
- Specialized nylon feedstock concentration:Backward-integrated chemical majors control photopolymer resin supply chains, limiting second-source options for mid-tier printer OEMs.
- ISO 10993 biocompatibility certification timelines:Medical device polymer approvals stretch 18-24 months, freezing formulation innovation cycles for healthcare applications.
- Injection molding cost floor:Conventional plastic processing retains 40-60% cost advantage above 10,000-unit production runs, capping addressable volume for additive alternatives.
Strategic Opportunities
- Dental and hearing-aid production:Voxel-level precision in stereolithography and digital light processing resin formulations reduces post-processing labor by eliminating manual finishing steps.
- EU Green Deal circularity mandates:Emerging feedstock recycling infrastructure requirements create first-mover advantage for powder reclaim and photopolymer resin recovery systems.
- Automotive supply chain jigs:Filament extrusion prototyping retains untapped penetration in tier-two supplier tooling where geometric complexity justifies additive economics.
Industry Challenges
- Process-parameter engineering talent scarcity:Qualified technicians who bridge polymer science and machine operation command premium wages, constraining OEM service network expansion.
- ASTM F3301 process specification fragmentation:Competing national standards bodies delay unified qualification frameworks, forcing redundant testing across export markets.
- Legacy ERP integration:Additive manufacturing work order management requires custom middleware development to synchronize with conventional MRP systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial 3D Printing Plastic Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Filament, Resin, Powder, Liquid Technology: Fused Deposition Modeling, Stereolithography, Selective Laser Sintering, Digital Light Processing End User: Aerospace, Automotive, Healthcare, Consumer Goods Application: Prototyping, Tooling, Production Parts, Accessories |
| Companies Covered | Stratasys Ltd., 3D Systems Corporation, Arkema S.A., BASF SE, Evonik Industries AG, SABIC, Covestro AG, HP Inc., EOS GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial 3D Printing Plastic Market Trends and Innovations
Material-process digital twins and closed-loop quality systems are compressing the gap between prototype validation and production qualification in flight-critical applications.
Multi-material jetting systems with voxel-level control are digitizing gradient property distribution within single components. Medical implant manufacturers adopt these platforms to match bone modulus without assembly. The technology is digitizing orthopedic device supply chains by collapsing multi-step fabrication into single-build workflows.
EU MDR medical device regulations now mandate Unique Device Identification traceability for polymer implants. This forces additive manufacturers to embed lot-level process data into component metadata. German and French notified bodies are prioritizing audit capacity for laser-sintered polyamide 12 spinal cages.
Automotive tier-one suppliers now specify material-origin certificates for jigs and fixtures. Purchasing departments reject uncertified filament batches regardless of unit cost. This behavioral shift is most visible in Stuttgart and Wolfsburg supply clusters where OEM sustainability scorecards penalize unverified feedstock sources.
Industrial 3D Printing Plastic Market Segmentation
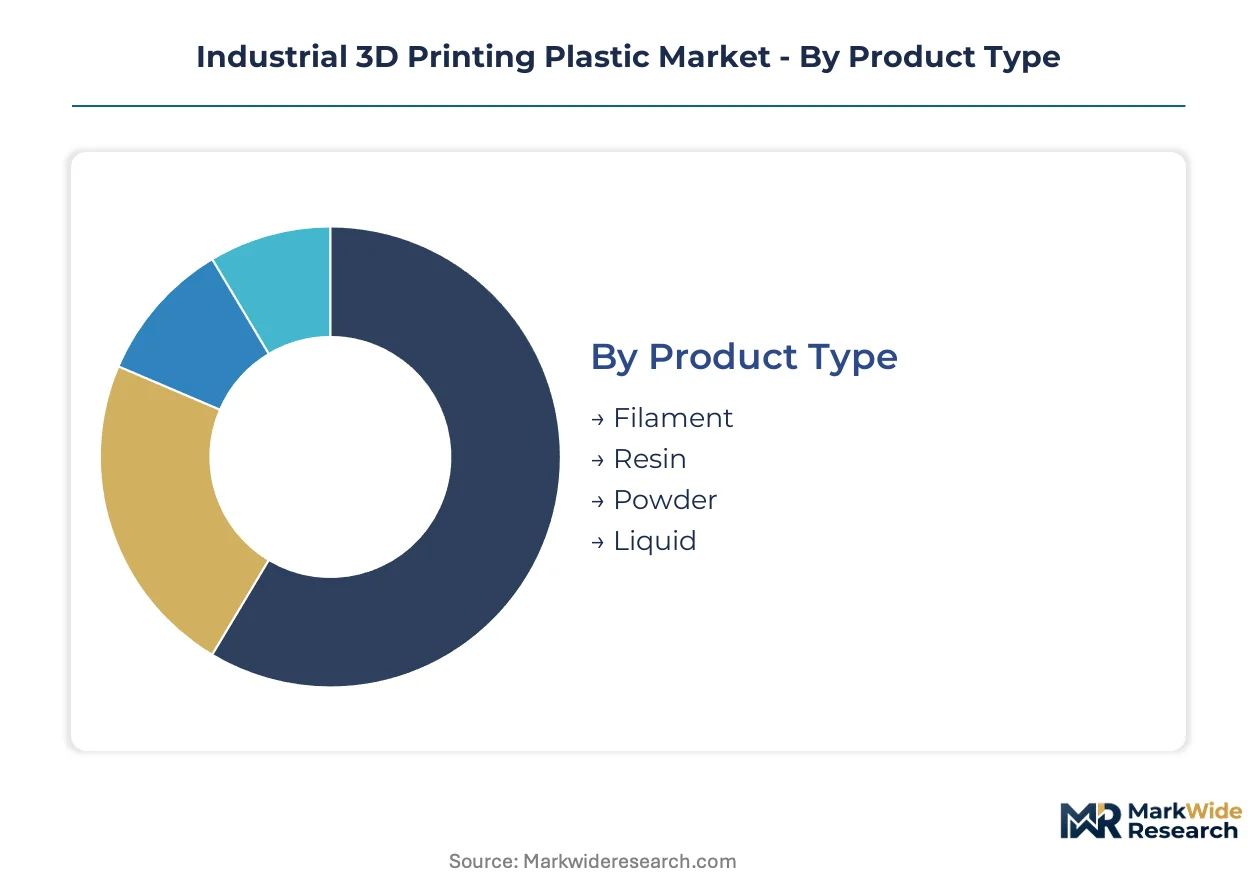
Material-process compatibility and end-use certification requirements fragment the industrial 3D printing plastic market into distinct supply ecosystems. Each segmentation dimension carries unique margin structures and qualification barriers that determine supplier positioning.
Product Type:
Use-case spectrum spans from low-cost prototyping consumables to flight-critical powder formulations requiring full traceability.
- Filament:Thermoplastic feedstocks extruded as continuous wire for fused deposition systems, typically ABS, PLA, or nylon grades. Automotive prototyping and jigs in Germany and Michigan absorb volume where geometric complexity justifies additive economics over machined tooling.
- Resin:Photopolymer formulations cured by UV light in vat-polymerization systems, delivering voxel-level precision. Dental aligner production in Switzerland and hearing-aid manufacturing in Denmark concentrate demand where surface finish eliminates manual finishing labor.
- Powder:Polyamide 12 and specialty nylon grades optimized for selective laser sintering, delivering isotropic mechanical properties. Aerospace tooling and medical spinal cages in Toulouse and Hamburg require REACH-compliant feedstock with integrated process-parameter datasets.
- Liquid:Uncured photopolymer precursors and specialized thermoset resins for jetting systems. Multi-material orthopedic implants with gradient modulus matching drive emerging adoption in Swiss and French medical device clusters.
Established volume favors filament; emerging adoption favors powder.
Technology:
Cost tier separates entry-level extrusion from capital-intensive powder-bed systems requiring climate-controlled facilities.
- Fused Deposition Modeling:Layer-by-layer extrusion of thermoplastic filament at 180-250°C build temperatures. Tier-two automotive suppliers in Stuttgart and Wolfsburg deploy these systems for jig fabrication where sustainability scorecards now mandate material-origin certificates.
- Stereolithography:Laser-cured resin vat polymerization achieving ±0.05 mm tolerances. Dental laboratories across Switzerland and the Netherlands prioritize this technology for crown and bridge production under EU MDR traceability mandates.
- Selective Laser Sintering:CO2 laser fusion of polymer powder beds at 160-180°C ambient temperatures. Flight-critical aerospace components in Toulouse and Hamburg compress qualification timelines through material-process digital twins.
- Digital Light Processing:Projector-based resin curing with faster layer times than laser systems. Hearing-aid shell production in Copenhagen and Stockholm leverages this speed for same-day patient customization workflows.
Capital deployment favors fused deposition modeling; precision requirements favor selective laser sintering.
End User:
Application maturity varies sharply across sectors, with medical and aerospace carrying the steepest certification burdens.
- Aerospace:Flight-critical polymer brackets, ducting, and interior components. Boeing and Airbus tier-one suppliers in Everett and Toulouse now embed additively manufactured parts into primary assemblies, forcing material suppliers to integrate FAA process specifications with feedstock data.
- Automotive:Prototyping, tooling, and low-volume production parts. BMW and Volkswagen purchasing departments in Munich and Wolfsburg reject uncertified filament batches regardless of unit cost, embedding sustainability verification into supplier scorecards.
- Healthcare:Surgical guides, implants, and personalized medical devices. FDA material qualification protocols and ISO 10993 biocompatibility standards stretch approval timelines 18-24 months, freezing formulation innovation cycles for uncertified entrants.
- Consumer Goods:Custom accessories, eyewear, and electronics housings. Eyewear designers in Milan and Paris leverage resin jetting for frame personalization where voxel-level control enables mass customization without tooling investment.
Regulatory intensity favors healthcare; volume scale favors automotive.
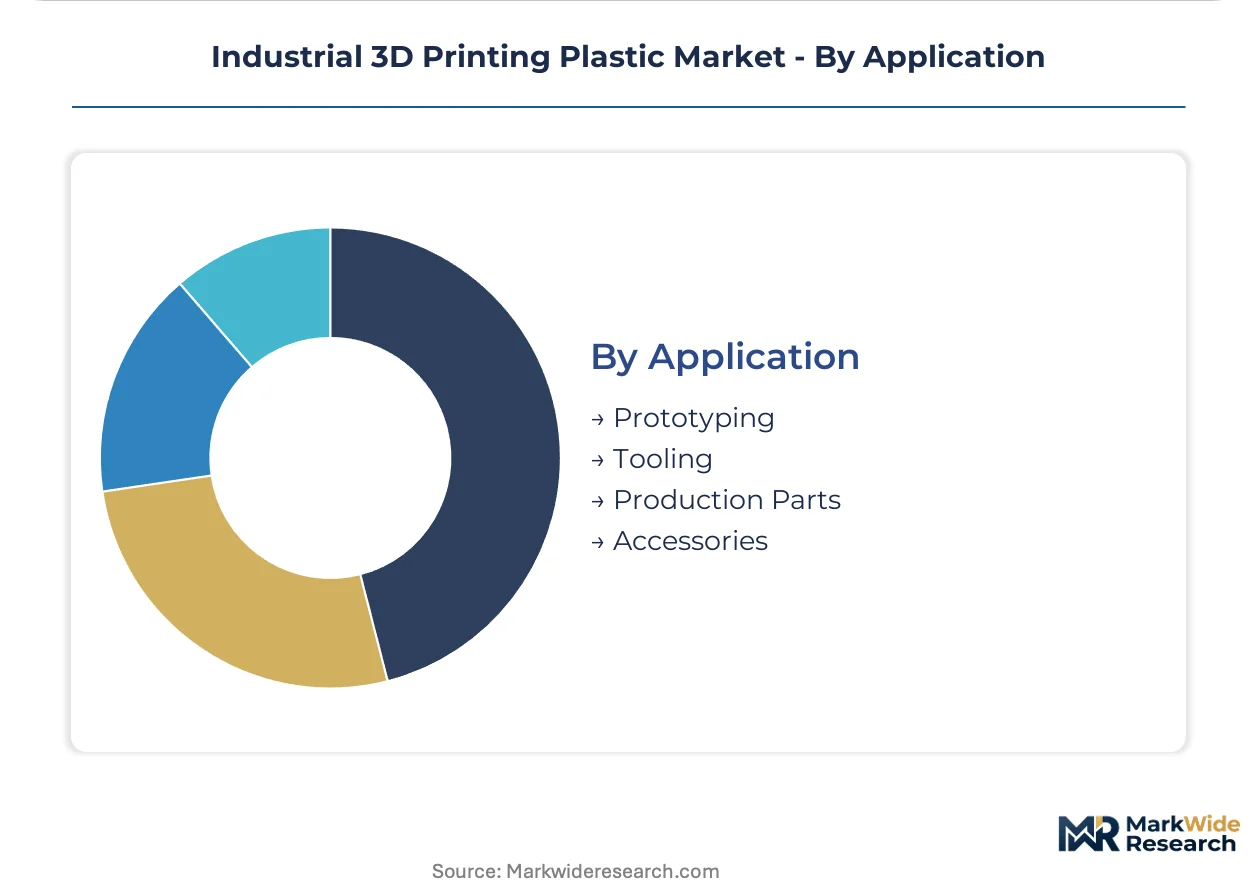
Application:
Customer type stratification separates R&D prototyping from production-line integration with distinct service and support requirements.
- Prototyping:Form and fit validation parts produced in quantities of 1-100 units. Design studios in London and Amsterdam prioritize speed over mechanical properties, driving filament and resin consumption in creative services clusters.
- Tooling:Jigs, fixtures, and manufacturing aids replacing machined metal equivalents. German automotive suppliers in Ingolstadt and Zuffenhausen specify polymer tooling for assembly lines where weight reduction improves operator ergonomics.
- Production Parts:End-use components qualified for functional performance. Aerospace ducting and medical spinal cages in Hamburg and Toulouse represent the steepest expansion trajectory as flight-critical and implant-grade qualifications mature.
- Accessories:Non-structural components including enclosures, housings, and cosmetic elements. Consumer electronics brands in Shenzhen and Seoul deploy resin jetting for limited-edition product runs where design refresh cycles compress tooling payback periods.
Margin capture favors production parts; volume throughput favors prototyping.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in prototyping and jig fabrication remain highly price-sensitive, while aerospace and medical device purchasers absorb substantial premiums for qualified powder formulations. This elasticity divergence fragments procurement patterns across geographies.
United States
FAA flight-critical qualification timelines compress as Boeing and Airbus tier-one suppliers in Everett embed additively manufactured polymer brackets into primary assemblies. EPA emissions guidance for powder handling facilities tightens operational compliance burdens. The Pacific Northwest aerospace cluster anchors demand for REACH-equivalent feedstock traceability systems.
Germany
Automotive purchasing departments in Munich and Wolfsburg reject uncertified filament batches regardless of unit cost, embedding sustainability verification into supplier scorecards. EU Green Deal circularity mandates reshape feedstock recycling infrastructure requirements. EOS GmbH and regional chemical suppliers in Bavaria anchor industrial polymer powder ecosystems that accelerate regional qualification pathways.
France
Medical device manufacturers in Toulouse prioritize laser-sintered polyamide 12 spinal cages under EU MDR traceability mandates. ANSM and notified bodies prioritize audit capacity for implant-grade polymer qualifications. The aerospace-medical manufacturing corridor concentrates demand for isotropic mechanical properties in flight-critical and implant applications.
Switzerland
Dental laboratories across Zurich and Geneva leverage stereolithography for crown and bridge production where surface finish eliminates manual finishing labor. Swissmedic biocompatibility protocols exceed baseline EU requirements, extending formulation approval cycles. The precision medical device cluster commands premium positioning for voxel-level resin formulations.
China
Consumer electronics brands in Shenzhen deploy resin jetting for limited-edition product runs where design refresh cycles compress tooling payback periods. MIIT industrial additive manufacturing standards formalize domestic qualification frameworks. The Pearl River Delta manufacturing base absorbs volume in prototyping and jig fabrication despite certification lag in flight-critical segments.
Industrial 3D Printing Plastic Market Competitive Landscape
Capability concentration sits with specialized powder formulators and precision resin developers; scale advantage sits with diversified chemical majors with backward integration into feedstock supply. The market structures around three tiers: integrated chemical conglomerates controlling polymer supply chains, precision equipment OEMs with installed-base service revenue, and specialized material formulators targeting medical and aerospace certifications. Dominant competitive moves include strategic partnerships between printer OEMs and chemical suppliers to secure qualified feedstock pipelines, and capacity expansion in powder reclaim systems to preempt EU circularity mandates.
Within the integrated chemical tier, BASF SE and Evonik Industries AG exemplify formulators with captive nylon and photopolymer resin supply chains. EOS GmbH, a German GmbH-structured equipment specialist, anchors the precision-systems tier through powder-bed polymer printing dominance in European aerospace and medical tooling applications. Stratasys Ltd., an Israel-originated corporation, represents the installed-base service model through recurring material and support revenue from fused deposition system deployments.
| Leading Market Players |
|---|
| Stratasys Ltd. |
| 3D Systems Corporation |
| Arkema S.A. |
| BASF SE |
| Evonik Industries AG |
| SABIC |
| Covestro AG |
| HP Inc. |
| EOS GmbH |
| Others |
Pricing and Supply Chain Analysis
Bavaria's polymer powder ecosystem anchors European supply capacity, translating EOS GmbH's regional dominance into pricing power for REACH-compliant polyamide 12 formulations. Buyers in aerospace and medical segments absorb substantial premiums for qualified feedstock with integrated process-parameter datasets, while automotive prototyping purchasers in Stuttgart and Wolfsburg drive cost compression in filament grades.
Pricing Analysis
Long-term offtake contracts dominate aerospace and medical powder procurement, locking in 18-24 month pricing for polyamide 12 with full traceability documentation. Spot purchasing prevails in filament and resin segments where automotive and dental buyers prioritize flexibility over volume commitments. Price differentiation hinges on certification tier (ISO 10993 biocompatibility, REACH registration status) and after-sales technical support bundling. Cost compression in standard-grade filament is intensifying because tier-two automotive suppliers now mandate material-origin certificates regardless of unit economics. Healthcare purchasers show lowest price sensitivity, absorbing premiums for implant-grade formulations with embedded lot-level process metadata.
Supply Chain Analysis
Export-control restrictions on selective laser sintering equipment and powder-bed fusion process-parameter datasets limit technology transfer to certain jurisdictions, constraining qualified manufacturing capacity expansion. Raw material supply concentrates in Germany, the United States, and China, with specialized nylon feedstock drawing from captive production by BASF SE and Evonik Industries AG. Photopolymer resin precursors rest on petrochemical derivatives and photoinitiator chemicals sourced through specialized chemical distributors. Single-source vulnerability runs through qualified polyamide 12 powder supply for flight-critical applications, where second-source qualification timelines stretch multiple years. Distribution feeds from direct OEM relationships in aerospace and medical segments, while automotive and dental supply runs through authorized distributor networks with regional technical service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flight-critical aerospace adoption of additively manufactured polymer components represents a high-growth disruption, with FAA and EASA qualification pathway compression accelerating material-process digital twin integration.
For Market Incumbents: Harden qualification data moats by embedding lot-level process metadata into component certificates required under EU MDR traceability mandates. Deepen backward integration into photopolymer resin precursors to offset feedstock concentration risk from chemical majors. Prioritize capacity expansion in powder reclaim systems to capture first-mover advantage from emerging EU Green Deal circularity requirements. For New Entrants and Emerging Players: Establish a beachhead in dental aligner and hearing-aid resin formulations where voxel-level precision reduces post-processing labor and Swissmedic biocompatibility protocols create qualification barriers for incumbents. Target tier-two automotive jig fabrication in Ingolstadt and Zuffenhausen supply clusters where sustainability scorecards now mandate verified feedstock sources. Deploy direct technical service teams to differentiate from distributor-dependent competitors. For Investors and Strategic Acquirers: Long-term, this sits as a materials-science consolidation play because qualified polymer formulation expertise is concentrating among fewer suppliers capable of bridging ISO 10993 certification with process-parameter engineering. Acquisition targets should display captive feedstock relationships or installed-base service revenue models. Watch for FDA guidance updates on medical device polymers as the signal indicating qualification timeline compression or extension.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialized Nylon Feedstocks | Captive polyamide 12 supply secures margin control against chemical major pricing power. |
| Powder Reclaim System Capacity Expansion | EU Green Deal mandates position reclaim infrastructure as regulatory compliance differentiator. |
| Material-Process Digital Twin Development | FAA qualification compression rewards suppliers integrating feedstock data with machine parameters. |
| ISO 10993 Biocompatibility Certification Investment | Medical device polymer approvals stretch 18-24 months, freezing out uncertified competitors. |
| Direct Technical Service Network Buildout | Process-parameter engineering talent scarcity commands premium wages, constraining OEM expansion. |
Research Methodology
Initial hypotheses were tested against primary input from additive manufacturing equipment OEMs, polymer formulation chemists, aerospace tier-one supplier procurement directors, and medical device regulatory affairs specialists, and refined through secondary validation against ECHA REACH registration databases, FDA 510(k) submission records, ASTM F3301 process specifications, and customs trade data for polymer powder and photopolymer resin categories. Bottom-up demand modeling triangulated with top-down chemical industry capacity assessments.
Demand-supply balance dynamics across material grade tiers, technology platforms, end-use industries, and regional regulatory clusters shaped the analytical framework throughout the projection horizon. CAGRs derived from segment-level volume buildups incorporating build temperature requirements, certification timeline assumptions, and substitution elasticity against injection molding cost floors. Industry-specific inputs included selective laser sintering machine installation data and dental laboratory digital adoption rates.
Stress conditions across REACH substance restriction scope expansion, FAA qualification timeline variability, and powder handling facility emissions compliance costs were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding automotive sustainability scorecard enforcement intensity and EU MDR audit capacity expansion. Material shifts in FDA guidance for medical device polymers or ECHA polymer registration requirement scope would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Materials
Global 3D Printing Ceramics Market
3D Printing Materials
3D Printing Applications Polymers Market
3D Printing Materials
Additive Manufacturing and Materials Market
3D Printing Materials
3D Printing Polymers Market
3D Printing Materials
Global 3D Printing Metals Market
3D Printing Materials
3D Printing High Performance Plastic Market
3D Printing Materials
Rapid Prototyping Materials Market
3D Printing Materials
Graphene in 3D Printing Market
3D Printing Materials
Polyamide 12 Powder for High-Performance 3D Printing Market
3D Printing Materials
Global Biocompatible 3D Printing Materials Market
3D Printing Materials
3D Printing Materials Market
3D Printing Materials
Europe Polypropylene in 3D Printing Market
3D Printing Materials
Metal Jet 3D Printing Technology Market
3D Printing Materials
Middle East 3D Printing Materials Market
3D Printing Materials
LAMEA 3D Graphene Market
3D Printing Materials
3D Printed Nanocellulose Market