
 3D Printing Consumables Market | 2026-2036
3D Printing Consumables Market Size, Share, and Industry Trends Forecast 2026-2036
3D Printing Consumables Market Insights
REACH compliance is recalibrating the cost-of-entry calculus for European polymer suppliers, forcing reformulation of photopolymer resin chemistries ahead of restricted substance deadlines. Stratasys leverages its captive filament production network to sustain margin control across North American distribution channels. Evonik Industries AG anchors high-performance powder supply for medical and aerospace certifications through its Essen-based polymer compounding operations.
3D printing consumables encompass feedstock materials—thermoplastics, photopolymers, metal powders, composite filaments, and wax—engineered to specific melt flow indices, particle size distributions, or curing wavelengths for layer-by-layer additive fabrication. These materials convert digital geometries into physical objects through fused deposition modeling, stereolithography, or powder bed fusion processes, serving prototyping through serial production workflows. Metal powders command the deepest margin pools due to atomization complexity and aerospace qualification overhead, while composite filaments represent the fastest-expanding category as continuous fiber reinforcement penetrates structural tooling applications. Photopolymers retain dominance in dental and jewelry micro-resolution segments where layer thickness below 25 micrometers determines surface finish quality.
The EPA regulates volatile organic compound emissions from photopolymer resin handling facilities, pushing demand toward low-odor and bio-based formulations in US manufacturing zones. EMA medical device frameworks and FDA 510(k) pathways jointly determine which implant-grade titanium or PEEK powder lots achieve clinical deployment, creating dual-jurisdiction compliance burdens for suppliers. ISO/ASTM 52900 standards unify terminology and test methods across national markets, reducing friction in cross-border material certification. Stakeholders must now decide whether to vertically integrate powder atomization or outsource to specialized metallurgical suppliers as qualification timelines lengthen.
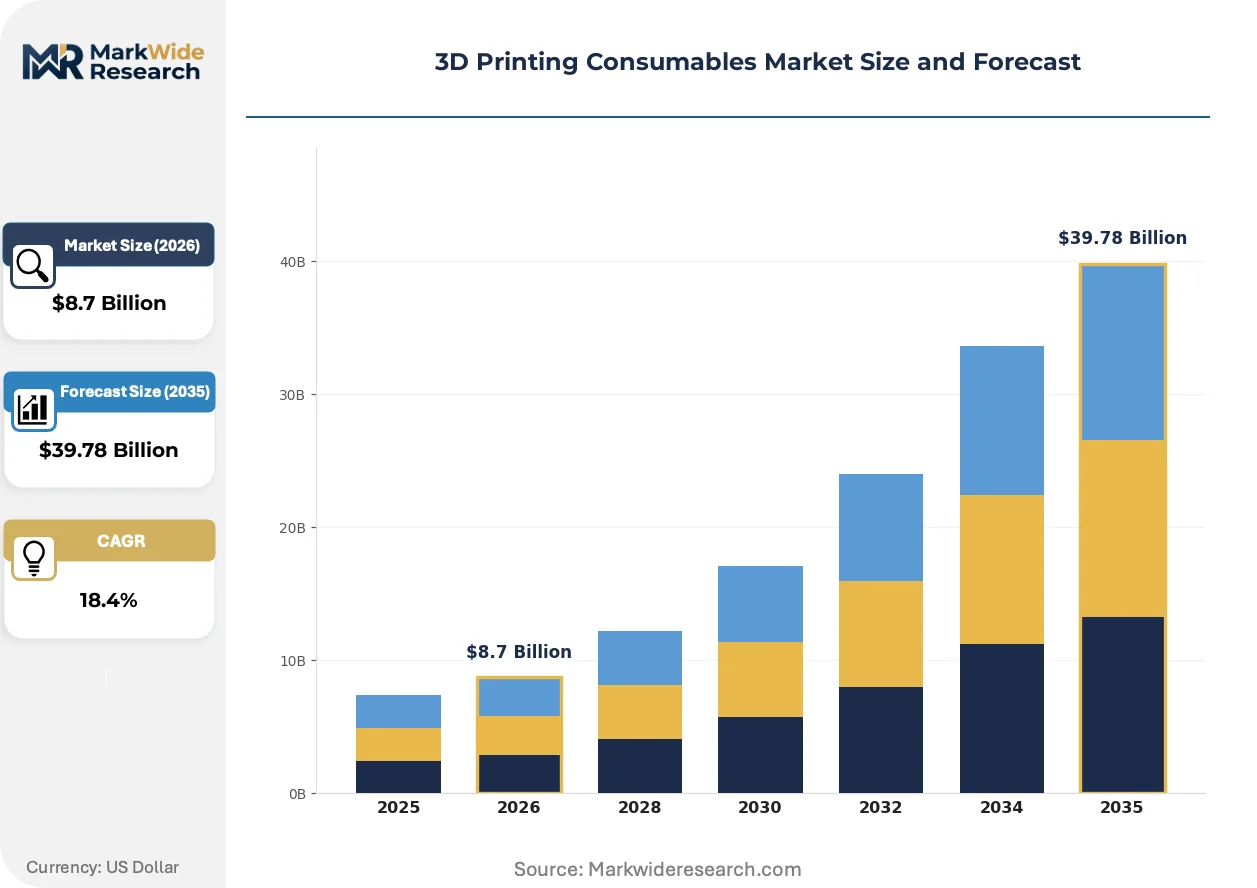
Market Dynamics
Flight-critical aerospace qualification timelines are compressing supply chains around certified powder atomizers, forcing consumable suppliers to choose between captive metallurgy investments and specialized tolling partnerships.
Growth Catalysts
- REACH substance restrictions:ECHA deadlines for restricted photoinitiators are accelerating reformulation R&D among European resin formulators ahead of compliance windows.
- Continuous fiber thermoplastics:Automated fiber placement integration with extrusion-based systems is opening structural tooling applications in automotive and marine manufacturing.
- Pearl River Delta bundling:Chinese contract manufacturers now package consumable supply with printer fleet management, locking in multi-year feedstock commitments.
Market Restraints
- Gas atomization feedstock volatility:Nickel and titanium sponge price swings transmit directly to powder cost structures with limited hedging mechanisms.
- Plasma atomizer concentration:Premium spherical powder supply clusters among three specialized metallurgical suppliers in Germany and Sweden.
- Layer thickness limitations:Directed energy deposition cannot achieve the surface finish tolerances required for dental prosthetics without secondary machining.
Strategic Opportunities
- India PLI scheme:Domestic medical device manufacturing incentives are creating localized demand for implant-grade PEEK filament compounding.
- Bio-based photopolymer formulations:EPA VOC enforcement is opening market share for low-odor soybean-derived resin chemistries in US dental labs.
- Multi-material deposition convergence:Combining fused filament fabrication with inkjet binder jetting enables gradient property parts for orthopedic implants.
Industry Challenges
- Dual-jurisdiction certification timelines:EMA medical device frameworks and FDA 510(k) pathways require parallel documentation for titanium powder lots, extending qualification cycles.
- Atomization technician scarcity:Plasma torch operation and particle size distribution control demand specialized metallurgical training unavailable in standard polymer processing curricula.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Printing Consumables Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Thermoplastics, Photopolymers, Metal Powders, Composite Filaments, Wax Form: Filament, Resin, Powder, Sheet, Pellet Application: Prototyping, Tooling, End-use Parts, Jewelry Design, Educational Models End User Industry: Aerospace, Consumer Electronics, Architecture, Footwear Manufacturing, Education |
| Companies Covered | 3D Systems, Inc., Stratasys, Arkema, Evonik Industries AG, GE Aerospace, Syensqo, Sandvik AB, Höganäs AB, Nano Dimension, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Printing Consumables Market Trends and Innovations
Open-source filament extrusion hardware is fragmenting polymer feedstock supply chains, enabling regional compounders to challenge branded distribution networks with customized material formulations.
Desktop pellet-to-filament extrusion systems are decentralizing thermoplastic supply for small-batch manufacturers. Machine shops and design studios in North America and Western Europe now compound ABS and PETG on-site from virgin pellets, compressing lead times from weeks to hours while bypassing spooled filament markups.
EU Green Deal material traceability mandates are forcing polymer suppliers to implement blockchain-enabled lot tracking. ECHA registration requirements now extend to recycled feedstock streams, compelling compounders in Germany and the Netherlands to document regrind percentages and contamination testing protocols for every production batch.
Consolidated procurement through printer OEM subscription programs is displacing spot-market resin purchases. Dental service organizations in the United States now source photopolymer through locked agreements with equipment manufacturers, trading formulation flexibility for predictable per-part costing and automated replenishment logistics.
3D Printing Consumables Market Segmentation
Material specifications determine printer compatibility and part performance, forcing buyers to match feedstock properties to deposition technology. Segmentation reveals where formulation investments concentrate and which supply chains command premium positioning.
Material Type:
Buyers differentiate by thermal stability, tensile strength, and regulatory qualification burden rather than price alone.
- Thermoplastics:ABS and PLA formulations dominate fused deposition modeling workflows with melt flow indices calibrated to extruder temperature ranges. Automotive prototyping in Germany and consumer goods manufacturing in China's Pearl River Delta absorb the highest filament volumes, though REACH-compliant reformulations are compressing margins for European compounders.
- Metal Powders:Gas-atomized titanium and nickel superalloys command the deepest margin pools due to plasma torch complexity and aerospace certification overhead. Flight-critical bracket qualification through laser powder bed fusion in Germany concentrates demand among three specialized atomizers, extending lead times for qualified lots.
- Photopolymers:Acrylate and epoxy resin systems cure under specific UV wavelengths for stereolithography and digital light processing printers. Dental labs in the United States drive micro-resolution demand where layer thickness below 25 micrometers determines surface finish quality.
- Composite Filaments:Continuous carbon fiber reinforcement within nylon or ABS matrices enables structural tooling applications. Automated fiber placement integration with extrusion systems is opening automotive and marine manufacturing segments.
- Wax:Investment casting feedstocks with controlled thermal expansion properties serve jewelry design and dental crown production. Low-ash burnout formulations remain essential for precision metal casting workflows.
Thermoplastics lead volumes today; composite filaments are gaining share fastest.
Form:
Physical configuration dictates handling infrastructure, storage requirements, and deposition system compatibility.
- Filament:Spooled thermoplastic wire with diameter tolerances of ±0.05 millimeters feeds fused deposition modeling systems. Desktop pellet-to-filament extrusion systems in North America are decentralizing supply for small-batch manufacturers.
- Resin:Liquid photopolymer formulations require UV-opaque packaging and temperature-controlled storage to prevent premature curing. Dental service organizations now source through printer OEM subscription programs, trading flexibility for predictable per-part costing.
- Powder:Spherical particle morphology with tight size distributions enables uniform powder bed fusion layers. Plasma atomizer concentration in Germany and Sweden limits premium spherical supply.
- Sheet:Laminated paper or polymer composites feed laminated object manufacturing systems for architectural modeling and concept visualization.
- Pellet:Virgin polymer granules enable on-site filament extrusion, compressing lead times from weeks to hours for machine shops with desktop compounding systems.
Filament maintains the widest installed base; pellet adoption is climbing the fastest as regional compounders challenge branded distribution.
Application:
Use case maturity determines material specification tolerance and volume predictability.
- Prototyping:Form-and-fit validation parts tolerate broader dimensional variance than production components. Consumer electronics design studios in Shenzhen cycle through rapid iterations with standard PLA and ABS formulations.
- Tooling:Jigs, fixtures, and mold inserts demand higher thermal resistance and compressive strength. Continuous fiber thermoplastics are penetrating automotive assembly line tooling as deposition speeds improve.
- End-use Parts:Flight-critical aerospace brackets and implant-grade medical devices require certified powder lots with full traceability. Dual-jurisdiction EMA and FDA documentation extends qualification timelines.
- Jewelry Design:Micro-resolution wax patterns and castable photopolymers enable intricate geometries impossible through traditional carving.
- Educational Models:Low-cost PLA and basic resin formulations serve university engineering programs and secondary school STEM curricula.
Prototyping retains the largest addressable base; end-use parts show the steepest expansion trajectory.
End User Industry:
Regulatory exposure and performance requirements fragment procurement patterns across verticals.
- Aerospace:Flight-critical qualification mandates drive titanium and nickel superalloy powder demand. German manufacturers now qualify more brackets through laser powder bed fusion, compressing supply chains around certified atomizers.
- Consumer Electronics:Rapid design iteration cycles favor standard thermoplastics with minimal qualification overhead. Pearl River Delta contract manufacturers bundle consumable supply with printer fleet management.
- Architecture:Concept models and facade prototypes utilize full-color gypsum composites and large-format filament systems.
- Footwear Manufacturing:Midsole lattices and custom insoles exploit TPU elasticity and variable density printing.
- Education:Budget-constrained institutions prioritize low-cost PLA and open-source filament extrusion hardware.
Consumer electronics absorbs the highest filament tonnage; aerospace commands the premium powder tier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized metallurgical technicians cluster around plasma atomization facilities in Germany and Sweden, while polymer compounding expertise concentrates in the Netherlands and China's coastal manufacturing zones.
United States
Dental service organizations and aerospace primes drive photopolymer and titanium powder consumption respectively. EPA VOC enforcement from resin handling facilities accelerates demand for bio-based formulations. Machine shops across the Midwest now deploy desktop pellet-to-filament systems to bypass spooled filament distribution.
Germany
Flight-critical bracket qualification through laser powder bed fusion concentrates demand for certified powder lots. ECHA REACH deadlines force reformulation of photoinitiator chemistries ahead of restricted substance windows. Essen-based polymer compounding anchors high-performance PEEK supply for medical implant certifications.
China
Contract manufacturers in the Pearl River Delta bundle consumable supply with printer fleet management, locking multi-year feedstock commitments. The country's dual carbon goals tighten material traceability requirements for recycled polymer streams. Shenzhen's consumer electronics design studios cycle through rapid prototyping iterations with standard thermoplastic formulations.
India
Domestic medical device manufacturing incentives under the PLI scheme create localized demand for implant-grade PEEK filament compounding. CDSCO regulatory frameworks determine which powder lots achieve clinical deployment. Gujarat and Maharashtra host emerging compounding operations serving orthopedic implant fabricators.
Sweden
Premium spherical powder supply clusters among specialized metallurgical suppliers serving aerospace qualification timelines. Gas atomization feedstock volatility transmits directly to regional powder cost structures. Plasma torch operation expertise concentrates in Scandinavian metallurgical institutes, constraining technician supply expansion.
3D Printing Consumables Market Competitive Landscape
The competitive structure tilts toward diversified materials conglomerates with captive polymer compounding and metallurgical capabilities. Three archetypes dominate: printer OEMs with integrated consumable supply, independent specialty chemical suppliers with aerospace certification depth, and tolling-focused atomization specialists with plasma torch expertise. Capacity expansion around qualified powder lots and backward integration into resin formulation represent the dominant competitive moves as qualification timelines lengthen.
Among diversified chemical conglomerates, Evonik Industries AG and Arkema exemplify the certification-heavy archetype anchoring high-performance polymer supply. Sandvik AB occupies a position within the metallurgical specialist tier, representing plasma atomization concentration for premium spherical powders. Stratasys sits within the integrated equipment-consumables segment, leveraging captive filament production networks to sustain margin control across North American distribution channels.
| Leading Market Players |
|---|
| 3D Systems, Inc. |
| Stratasys |
| Arkema |
| Evonik Industries AG |
| GE Aerospace |
| Syensqo |
| Sandvik AB |
| Höganäs AB |
| Nano Dimension |
| Others |
Pricing and Supply Chain Analysis
Plasma torch operators concentrated in Essen and Sandviken command wage premiums that widen spreads between certified aerospace powder tiers and commodity filament grades. Labor-cost differentials between Scandinavian metallurgical institutes and Chinese coastal compounding zones drive a three-tier pricing structure across premium, standard, and economy levels, with REACH compliance adding fixed-cost burdens that compress margins at the lower tiers.
Pricing Analysis
Bundled printer-fleet-management contracts in the Pearl River Delta diverge sharply from spot-market resin purchases in North American dental labs. Pricing stratifies across premium, standard, and economy tiers based on certification grade and volume scale, with flight-critical aerospace lots commanding substantial premiums over prototyping-grade thermoplastics. Cost compression in standard filament tiers is intensifying because desktop pellet-to-filament systems enable on-site compounding. Consumer electronics contract manufacturers show highest price sensitivity, while aerospace primes prioritize qualification reliability over unit cost.
Supply Chain Analysis
India's PLI scheme and domestic-content mandates for medical devices are reshaping sourcing patterns for implant-grade PEEK compounding. Premium spherical powder supply clusters in Germany, Sweden, and China, while polymer compounding expertise concentrates in the Netherlands and China's coastal zones. Raw material dependencies draw from nickel and titanium sponge feedstocks, photoinitiator chemistries, and continuous carbon fiber tows. Single-source vulnerability around plasma atomization facilities in Scandinavia creates structural risk. Distribution runs through printer OEM subscription programs, specialized metallurgical suppliers, and regional compounder networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where ECHA REACH deadlines for restricted photoinitiators are accelerating demand for reformulated resin systems ahead of compliance windows.
For Market Incumbents: Hedge gas atomization feedstock volatility through long-term titanium sponge offtake agreements with Australian and Chinese suppliers. Secure captive plasma torch capacity in Sweden or Germany before technician scarcity worsens. Backward integration into photopolymer resin formulation protects margin control as European substance restrictions tighten. For New Entrants and Emerging Players: Capture localized medical device compounding opportunities in Gujarat and Maharashtra under India's PLI scheme before CDSCO frameworks mature. Target bio-based photopolymer formulations for US dental labs facing EPA VOC enforcement. Partner with printer OEMs for bundled fleet-management contracts rather than competing on spot-market pricing. For Investors and Strategic Acquirers: Printer OEMs with integrated consumable supply are the most active acquirers in this space, seeking to lock in feedstock security for subscription programs. Long-term viability rests on certification depth rather than volume scale. Watch for EMA-FDA dual-jurisdiction qualification timelines as the signal indicating which powder lots achieve clinical deployment premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Powder Atomization | Captive metallurgy secures qualified lot supply for aerospace bracket certifications in Germany. |
| Reformulation R&D for REACH Compliance | European resin formulators invest ahead of ECHA photoinitiator restriction deadlines. |
| Regional Compounding Facility Expansion | Gujarat-based PEEK filament operations serve India's PLI-driven orthopedic implant demand. |
| Printer OEM Subscription Programs | Locked agreements displace spot-market resin purchases in US dental service organizations. |
| Blockchain-Enabled Lot Tracking Implementation | EU Green Deal mandates force German compounders to document regrind percentages. |
Research Methodology
Coverage spans Germany, China, India, Sweden, and the United States, with primary inputs from each market. The study combines structured interviews with plasma atomization technicians, polymer compounding plant managers, dental lab procurement leads, aerospace quality engineers, and printer OEM supply chain directors with secondary validation. Sources include ECHA registration databases, FDA 510(k) filings, EU Green Deal implementation protocols, and customs trade data for titanium sponge and nickel powder flows. Bottom-up material consumption estimates triangulate against top-down printer installation forecasts.
Granularity extends to material type, physical form, application maturity, and end-user industry across the analysis window. The analytical framework models thermoplastic filament volumes by melt flow index tier, metal powder demand by atomization method, and photopolymer consumption by curing wavelength compatibility. CAGRs derive from regression analysis against printer fleet expansion rates and qualification timeline compression. Industry-specific inputs include EMA-FDA dual-jurisdiction certification cycle lengths and REACH substance restriction implementation schedules.
Feedstock price volatility, regulatory deadline delays, and plasma torch technician availability are the dominant revision risks to projection assumptions. Forecasts reflect documented qualification timelines and substitution elasticity between deposition technologies. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Materials
Metal Jet 3D Printing Technology Market
3D Printing Materials
Patterning Materials Market
3D Printing Materials
Additive Manufacturing and Materials Market
3D Printing Materials
Global 3D Printing Metals Market
3D Printing Materials
Aerospace 3D Printing Materials Market
3D Printing Materials
Global Arf Dry and Immersion Resist Materials Market
3D Printing Materials
3D Printing Polymers Market
3D Printing Materials
3D Printing Elastomers Market
3D Printing Materials
Global 3D Printing Ceramics Market
3D Printing Materials
Medical 3D Printing Plastics Market
3D Printing Materials
LAMEA 3D Graphene Market
3D Printing Materials
3D Printing Materials and Services Market
3D Printing Materials
Non-Metal 3D Printing Market
3D Printing Materials
3D Printing Photopolymers Market
3D Printing Materials
Global 3D Printing Construction Material Market
3D Printing Materials
Industrial 3D Printing Plastic Market