
 Additive Manufacturing and Materials Market | 2026-2036
Additive Manufacturing and Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Additive Manufacturing and Materials Market Outlook
The direct sales channel for industrial metal printers is narrowing as OEMs consolidate authorized service networks. EOS GmbH leverages its installed base in laser sintering to sustain premium pricing on powder-bed systems. BASF competes through backward integration into specialty polymer feedstocks, anchoring material consistency for automotive qualification programs.
Additive manufacturing and materials encompass layer-by-layer fabrication processes that fuse polymers, metals, or ceramics using directed energy or binding agents, typically achieving tolerances of 50-500 microns depending on the technology. These systems produce geometrically complex components for tooling, implants, and lightweight structural parts where subtractive methods face constraints. FDM and SLS technologies dominate unit shipments, though DMLS systems capture the highest margin pools in aerospace and medical implant production. Materials represent the fastest-expanding revenue category as qualified metal powders and high-performance photopolymers command recurring consumable spend.
FDA's 510(k) clearance framework and the EU MDR shape medical device market access, while FAA certification standards govern flight-critical part production in the United States. ISO/ASTM 52900 standards provide the baseline terminology and process classifications that regulators reference for quality system audits. Stakeholders must monitor evolving powder recycling protocols and emissions thresholds as environmental compliance becomes a gatekeeper for facility permits.
Market Dynamics
Flight-certification pathways for polymer and metal components are compressing development cycles in aerospace, while EU machinery safety mandates force retrofits of legacy production lines. Powder recyclability standards and emissions thresholds now gate facility permits in industrial clusters.
Growth Catalysts
- EU CE marking under MDR:Tighter qualification protocols for production-grade implants and surgical instruments are elevating barrier-to-entry for qualified suppliers, concentrating contract awards among certified producers in Germany and France.
- Aerospace part consolidation:Topology-optimized brackets and ducting produced via laser powder-bed fusion replace multi-piece assemblies, reducing airframe weight and fastener counts for next-generation narrowbody programs.
- Photopolymer formulation advances:Ceramic-filled resins with heat-deflection temperatures exceeding 300°C are opening mold tooling applications previously locked to machined aluminum.
Market Restraints
- Argon and nitrogen feedstock volatility:Inert gas costs for powder-bed fusion represent 8-12% of operating expenditure, with European industrial gas supply concentrating among three producers.
- Qualified metal powder scarcity:Plasma atomization capacity for Ti-6Al-4V and Inconel 718 concentrates in Germany and the United States, creating single-source risk for aerospace Tier-1 suppliers.
- FAA certification timeline friction:Part-level qualification for flight-critical applications requires 18-36 months of mechanical testing and process validation, freezing design iterations.
Strategic Opportunities
- India PLI scheme for advanced manufacturing:Domestic production-linked incentives for precision engineering components are attracting powder-bed system deployments for aerospace and defense subcontracts.
- Multi-material deposition convergence:Hybrid systems combining directed energy deposition with CNC machining enable repair of turbine blades and landing gear, capturing aftermarket value previously lost to scrap.
- Dental aligner production automation:Continuous resin printers with automated support removal are displacing labor-intensive thermoforming in orthodontic appliance fabrication.
Industry Challenges
- Process-parameter technician scarcity:Laser power modulation, scan strategy optimization, and thermal management require 2,000+ hours of apprenticeship, with training pipelines lagging installed base expansion.
- ISO/ASTM 52900 audit preparation:Quality system documentation for process classification and feedstock traceability demands 6-12 months of consultant engagement before regulator submission.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Additive Manufacturing and Materials Market |
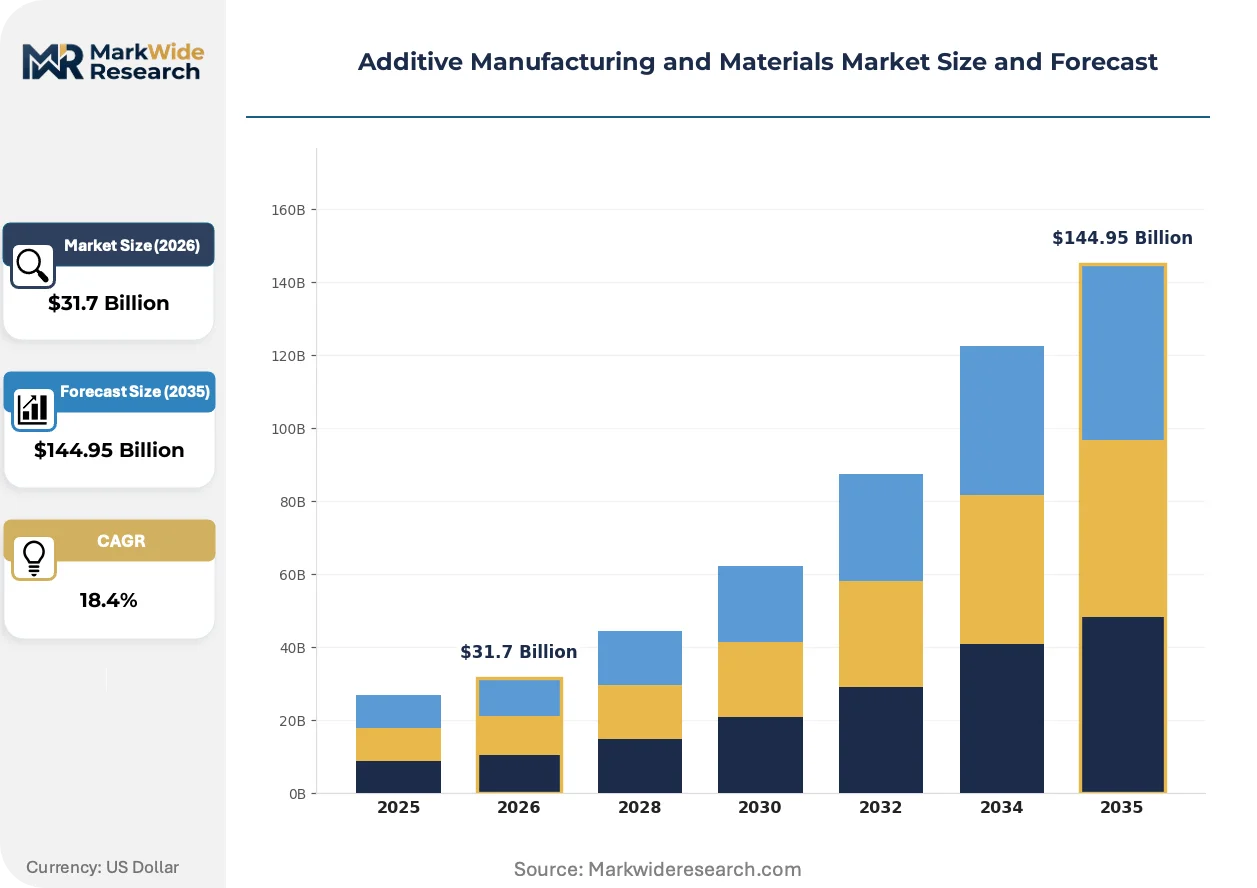
| Market Size in 2026 | $31.7 Billion |
| Market Size in 2035 | $144.95 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 3D Printers, Materials, Software, Services Technology: FDM, SLA, SLS, DMLS End User: Aerospace, Automotive, Healthcare, Consumer Goods Application: Prototyping, Tooling, Production Parts, Customization |
| Companies Covered | Stratasys Ltd., 3D Systems Corporation, HP Inc., General Electric Company (GE Additive), EOS GmbH, BASF, Materialise NV, Renishaw plc, Evonik Industries AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Additive Manufacturing and Materials Market Strategic Shifts
Computational design tools and closed-loop process monitoring are fusing to compress the iteration cycle between part qualification and production release. Regulatory data packages now embed in-situ sensor streams rather than post-build inspection.
Continuous liquid interface printing is collapsing throughput constraints for dental and audiology applications. Aligner manufacturers in the United States and Germany are adopting roll-to-roll photopolymer systems that achieve 24-hour turnaround on 500-unit batches. This velocity is collapsing the traditional mold-fabrication interval that previously gated same-day appliance delivery.
EU MDR post-market surveillance requirements are mandating unique device identifiers and batch-level traceability for implantable components. Manufacturers must now integrate powder lot records, build parameters, and sterilization logs into centralized quality databases. German and French notified bodies are auditing these systems quarterly, with non-conformity penalties blocking market access for 90-day remediation periods.
Spare parts procurement for legacy industrial equipment is migrating to digital inventory models. Energy and mining operators in Australia and Canada are qualifying on-demand printed wear components—pump impellers, valve seats, conveyor rollers—against OEM spare part catalogs. This bypasses the 12-24 week lead times that previously forced excessive safety stock holdings at remote extraction sites.
Additive Manufacturing and Materials Market Segmentation
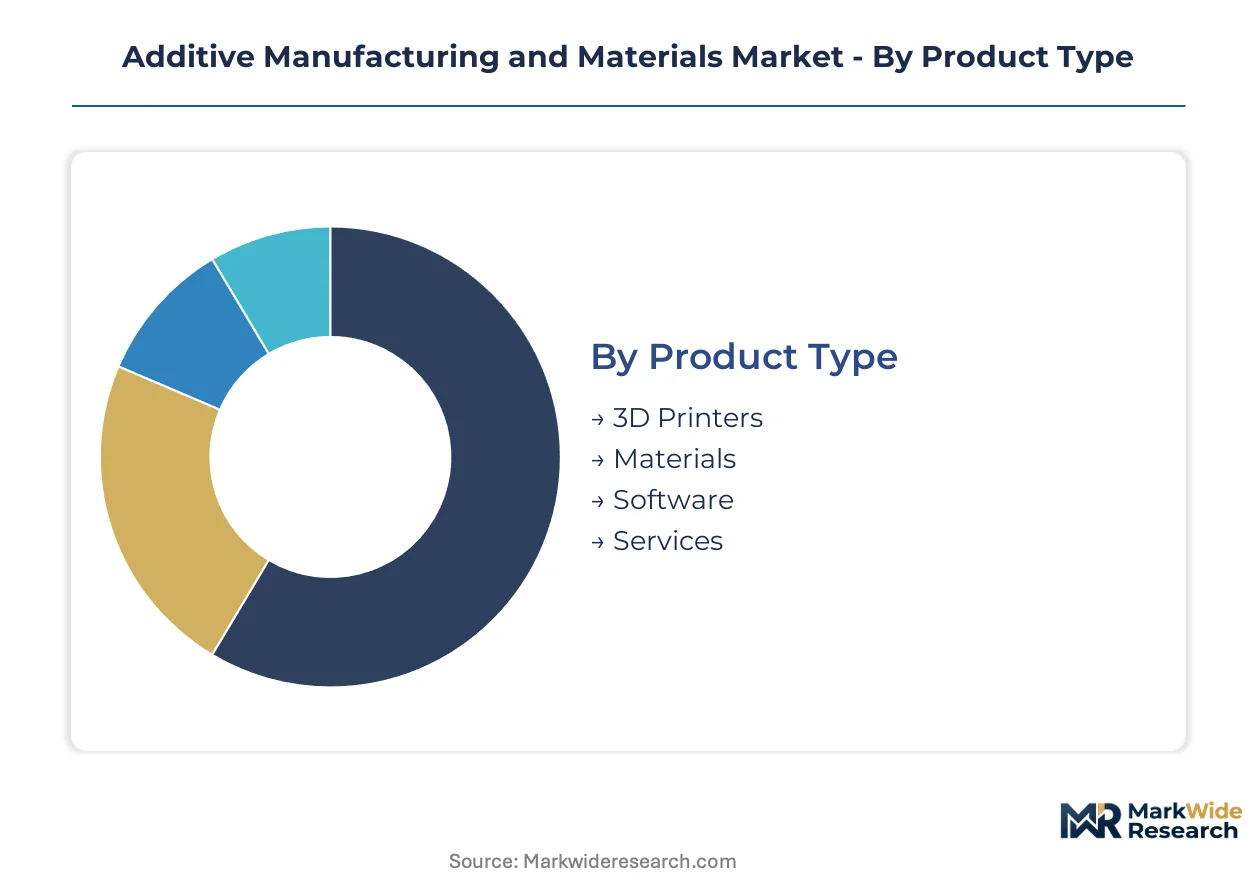
Segmentation in additive manufacturing reveals how value pools concentrate across hardware, consumables, and digital workflows. Technology choice dictates margin structure, while end-use verticals impose divergent qualification regimes that reshape competitive positioning.
Product Type:
Cost tier separates capital equipment from recurring revenue streams in the installed base economics.
- 3D Printers:Laser powder-bed systems for titanium and Inconel command the highest hardware margins, with aerospace Tier-1 suppliers in Germany and the United States driving qualification-driven procurement. Metal systems require 18-36 month payback validation against CNC machining centers.
- Materials:Qualified metal powders and ceramic-filled photopolymers generate recurring consumable spend with 60-70% gross margins. Plasma atomization capacity for Ti-6Al-4V concentrates in Germany and the United States, creating supply bottlenecks for flight-certified feedstock.
- Software:Topology optimization and build preparation tools license per-seat or per-machine, embedding process-parameter libraries that lock users into vendor ecosystems.
- Services:Part production bureaus and equipment maintenance contracts capture value from users avoiding capital deployment, particularly in dental aligner and hearing aid verticals.
Materials holds installed capacity. Services is rotating up the share rankings.
Technology:
Application requirements dictate technology selection, with tolerance demands and throughput needs driving divergent adoption curves.
- FDM:Fused deposition modeling dominates unit shipments through low-cost polymer extrusion, with Stratasys and Bambu Lab systems penetrating education and consumer goods prototyping. Layer thicknesses of 100-300 microns limit flight-critical or medical implant applications.
- SLA:Stereolithography achieves 25-50 micron resolution through photopolymer vat polymerization, anchoring dental crown and audiology mold production in Germany and the United States. Ceramic-filled resin formulations now exceed 300°C heat-deflection temperatures, displacing aluminum tooling in injection mold inserts.
- SLS:Selective laser sintering of nylon and TPU powders enables functional prototyping and end-use brackets without support structures, with EOS GmbH systems concentrating in German automotive supply chains.
- DMLS:Direct metal laser sintering captures the highest margin pools through powder-bed fusion of titanium, aluminum, and nickel superalloys. FAA and EASA certification pathways for flight-critical brackets and fuel nozzles concentrate demand among qualified suppliers in Germany, France, and the United States.
DMLS holds installed capacity. SLA is rotating up the share rankings.
End User:
Customer type determines qualification burden and contract structure, with regulated verticals imposing multi-year validation cycles.
- Aerospace:Flight-critical part production requires FAA or EASA certification, with topology-optimized brackets and ducting replacing multi-piece assemblies in next-generation narrowbody programs. Laser powder-bed fusion of Ti-6Al-4V and Inconel 718 dominates this vertical.
- Automotive:Tooling and prototyping applications leverage polymer and metal systems for jigs, fixtures, and low-volume end-use components. BMW and Volkswagen qualify printed parts for production vehicles in German manufacturing clusters.
- Healthcare:FDA 510(k) and EU MDR frameworks govern implantable devices and surgical instruments, with patient-specific cranial plates and spinal cages produced via EBM and DMLS. Unique device identifier mandates now require batch-level traceability from powder lot to sterilization log.
- Consumer Goods:Eyewear, footwear, and electronics housings exploit design freedom for mass customization, with Adidas and Luxottica deploying continuous resin printing for midsole lattices and frame geometries.
Aerospace holds installed capacity. Healthcare is rotating up the share rankings.
Application:
Volume and margin characteristics diverge across the product lifecycle, from design iteration through full-scale manufacturing.
- Prototyping:Form and fit validation drives polymer system utilization, with FDM and SLA technologies dominating early-stage product development cycles in consumer electronics and automotive design studios.
- Tooling:Conformal cooling channels in injection mold inserts and die-cast dies reduce cycle times 20-40%, with copper-alloy DMLS and ceramic-filled SLA resins expanding addressable geometries.
- Production Parts:Flight-certified brackets, medical implants, and energy sector wear components represent the highest-value application tier, with part-level qualification locking designs for multi-year production runs.
- Customization:Patient-specific implants, dental aligners, and hearing aid shells exploit lot-size-one economics, with automated support removal and post-processing enabling 24-hour turnaround at 500-unit batch scales.
Prototyping holds installed capacity. Production Parts is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German powder-bed system suppliers command 15-20% price premiums over North American equivalents, while Chinese resin printer manufacturers undercut European tooling costs by 40-60% in consumer-facing verticals.
United States
FAA certification timelines for flight-critical Ti-6Al-4V brackets drive 18-36 month procurement cycles among aerospace Tier-1 suppliers. The Inflation Reduction Act's advanced manufacturing tax credits accelerate powder-bed system deployments in defense subcontracting. Greater Boston hosts concentrated medical implant production, with FDA 510(k) pathways governing patient-specific cranial plate qualification.
Germany
Automotive tooling demand from BMW and Volkswagen sustains laser sintering capacity expansion in Baden-Württemberg and Bavaria. EU MDR post-market surveillance mandates quarterly notified body audits for implantable device traceability. EOS GmbH anchors a dense supplier ecosystem around industrial polymer and metal powder systems in Krailling.
China
Domestic narrowbody programs and naval shipbuilding drive qualified metal powder demand beyond plasma atomization capacity. MIIT dual carbon goals tighten emissions thresholds for facility permits in Yangtze River Delta industrial clusters. Shanghai and Shenzhen concentrate continuous resin printer manufacturing for dental aligner export markets.
India
Defense aerospace subcontracts and precision engineering component demand attract powder-bed system deployments under PLI scheme incentives. BIS standards for industrial machinery safety force retrofits of legacy production lines. Karnataka and Telangana host emerging contract manufacturing clusters for medical device exports to EU markets.
Japan
Automotive lightweighting programs and turbine blade repair applications sustain directed energy deposition demand. METI technology roadmaps prioritize multi-material hybrid system development for next-generation manufacturing. Nagoya and Osaka industrial corridors concentrate metal powder qualification expertise for aerospace supply chains.
Additive Manufacturing and Materials Market Competitive Environment
Integrated hardware-materials platforms and specialized powder metallurgy suppliers split the market into divergent margin structures. Laser powder-bed system OEMs capture premium pricing through flight-certification track records, while resin formulation specialists defend position via photopolymer recipe IP. Three archetypes dominate: capital equipment manufacturers with captive materials portfolios, independent feedstock suppliers with plasma atomization scale, and software-anchored workflow platforms. Consolidation pressure concentrates among European powder producers seeking backward integration into atomization capacity.
Within the integrated-system tier, EOS GmbH and Stratasys Ltd. exemplify divergent specialization paths—German powder-bed heritage against polymer extrusion scale. BASF occupies a distinct position as a chemicals conglomerate with captive specialty polymer feedstock production. HP Inc. represents the capital-equipment archetype leveraging existing printhead technology into production-grade metal systems.
| Leading Market Players |
|---|
| Stratasys Ltd. |
| 3D Systems Corporation |
| HP Inc. |
| General Electric Company (GE Additive) |
| EOS GmbH |
| BASF |
| Materialise NV |
| Renishaw plc |
| Evonik Industries AG |
| Others |
Value Chain & Pricing Dynamics
Rotterdam-Antwerp corridor freight costs for argon and nitrogen feedstock shipments compress margins on European powder-bed fusion systems while amplifying price spreads between flight-certified and standard-grade metal powders. This logistics chokepoint concentrates bargaining power among German plasma atomization suppliers who anchor premium pricing for Ti-6Al-4V and Inconel 718 qualified to FAA and EASA specifications.
Pricing Analysis
The customization-premium spread separates configured-to-order laser powder-bed systems from standard polymer extrusion hardware, with aerospace qualification tiers commanding substantial markups over prototyping-grade equipment. Three-tier pricing structure across premium, standard, and economy levels reflects certification burden, with FDA 510(k) cleared medical systems and FAA flight-certified metal platforms occupying the premium tier. Cost compression in the economy tier intensifies as Chinese resin printer manufacturers undercut European tooling costs for consumer-facing verticals. Dental aligner production bureaus exhibit highest price sensitivity due to batch-scale economics, while aerospace Tier-1 suppliers demonstrate lowest sensitivity given 18-36 month procurement cycles and part-level qualification lock-in.
Supply Chain Analysis
Upstream feedstock for qualified metal powders draws from plasma atomization capacity concentrated in Germany and the United States, with secondary atomization emerging in Japan for turbine blade repair applications. Specialty polymer resin formulations source from BASF's Ludwigshafen complex and Evonik's Marl operations, while ceramic-filled photopolymers depend on proprietary additive packages from German and Japanese chemical suppliers. Single-source vulnerability concentrates in Ti-6Al-4V powder for aerospace, where three producers control flight-certified output. Distribution runs through authorized service networks for industrial metal systems, with direct OEM sales dominating powder-bed platforms and channel partners handling resin printer volume in dental and audiology verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The additive manufacturing and materials market reads as a service-attach opportunity where materials recurring revenue and equipment maintenance contracts expand faster than hardware unit sales, particularly as qualified metal powder consumption scales with installed base utilization.
For Market Incumbents: Pre-empt margin erosion in polymer extrusion by backward integration into specialty photopolymer formulations, mirroring BASF's captive feedstock model. Lock aerospace Tier-1 suppliers into multi-year powder supply agreements before Chinese plasma atomization capacity achieves EASA qualification, preserving pricing power on Ti-6Al-4V and Inconel 718.
For New Entrants and Emerging Players: India's defense aerospace subcontracting base offers white-space penetration under PLI scheme incentives, with Karnataka and Telangana contract manufacturing clusters seeking powder-bed system deployments for medical device export qualification. Target dental aligner automation as the most penetrable application, where continuous resin printing with automated support removal displaces thermoforming labor. Pursue software-anchored workflow platforms as the go-to-market angle, embedding process-parameter libraries that create switching costs.
For Investors and Strategic Acquirers: Independent plasma atomization specialists with EASA and FAA certification track records represent the priority acquisition archetype, given supply concentration and recurring consumable economics. Monitor India PLI scheme disbursement velocity as the inflection signal, with accelerated powder-bed system deployments indicating downstream contract manufacturing maturity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plasma Atomization | Captures margin on Ti-6Al-4V powder while securing EASA qualification for aerospace Tier-1 supply. |
| Multi-Material Hybrid System Development | Combines directed energy deposition with CNC machining to capture turbine blade repair aftermarket value. |
| Continuous Resin Printer Manufacturing Scale-Up | Addresses 24-hour aligner turnaround demand in Germany and United States orthodontic markets. |
| EU MDR Traceability Database Integration | Enables quarterly notified body audits for implantable device batch-level powder lot tracking. |
| India PLI Scheme Facility Deployment | Positions for defense aerospace subcontracts and medical device export qualification to EU markets. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of SEC filings, EU MDR notified body audit records, FAA certification databases, and plasma atomization capacity registries. The research combines structured interviews with powder metallurgy procurement managers at aerospace Tier-1 suppliers, regulatory affairs leads at medical device OEMs, plant engineers at automotive tooling operations, and aftermarket service heads at printer OEMs. Bottom-up triangulation of equipment installed base and materials consumption patterns validates against top-down market sizing from trade flow analysis.
Forecast inputs include technology adoption curves across FDM, SLA, SLS, and DMLS platforms; end-use vertical penetration in aerospace, automotive, healthcare, and consumer goods; and geographic deployment patterns across the analysis window. Segmentation dimensions cover product type, technology, end user, and application with cross-cutting analysis of qualification burden and margin structure. CAGRs derive from installed base expansion rates multiplied by utilization-driven materials consumption intensity, with sensitivity testing against argon feedstock cost volatility and FAA certification timeline friction.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese plasma atomization entrants or accelerated India PLI scheme disbursements would shift outcomes materially. Cross-checking against EASA and FAA certification pipeline data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Materials
Aerospace 3D Printing Materials Market
3D Printing Materials
Europe Polypropylene in 3D Printing Market
3D Printing Materials
3D Printed Nanocellulose Market
3D Printing Materials
3D Printing Iron Powder Market
3D Printing Materials
Low-Temperature Flow Improver Additives for 3D Printing Resins Market
3D Printing Materials
Thermoformed Plastics for Printing Market
3D Printing Materials
3D Printing Materials Market
3D Printing Materials
Patterning Materials Market
3D Printing Materials
Polyamide 12 Powder for High-Performance 3D Printing Market
3D Printing Materials
Polypropylene in 3D Printing Market
3D Printing Materials
Stainless Steel 3D Printing Market
3D Printing Materials
Middle East 3D Printing Materials Market
3D Printing Materials
Vat Photopolymerization 3D Printing Technology Market
3D Printing Materials
Global 3D Printing Metals Market
3D Printing Materials
3D Printing Materials and Services Market
3D Printing Materials
3D Printing PLA Market