
 Global Metal Additive Manufacturing Market | 2026-2036
Global Metal Additive Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Metal Additive Manufacturing Market Outlook
Buyer concentration among aerospace primes is repositioning supply chain power toward tier-one OEMs with captive additive capacity. EOS GmbH leverages its laser-based powder bed fusion portfolio to dominate European aerospace qualification programs. Nikon SLM Solutions sustains R&D intensity across multi-laser architectures for production-scale metal printing. GE Additive anchors its position through vertical control from powder atomization to finished aero-engine components.
Metal additive manufacturing fuses metallic powders or wire feedstock using directed energy sources to build near-net-shape components with complex internal geometries and typical layer thicknesses of 20–100 microns. Its primary purpose is eliminating tooling costs and material waste for low-volume, high-complexity parts in critical-load applications. Powder bed fusion occupies the largest installed base and margin pool among product types, while binder jetting represents the fastest-expanding segment as sintering furnace networks mature. Laser-based systems lead technology adoption, though electron beam melting commands premium positioning in titanium aerospace structures where vacuum environments reduce oxidation.
FDA, EASA, and China's NMPA each maintain distinct qualification pathways for printed medical implants and flight-critical components, creating fragmented certification costs that favor multi-regional players. REACH powder handling rules and EU F-Gas Regulation constrain solvent and shielding gas supply chains, pushing producers toward closed-loop recycling systems. Stakeholders must monitor evolving powder traceability mandates as qualification standards tighten across aviation and orthopedic end uses.
Market Dynamics
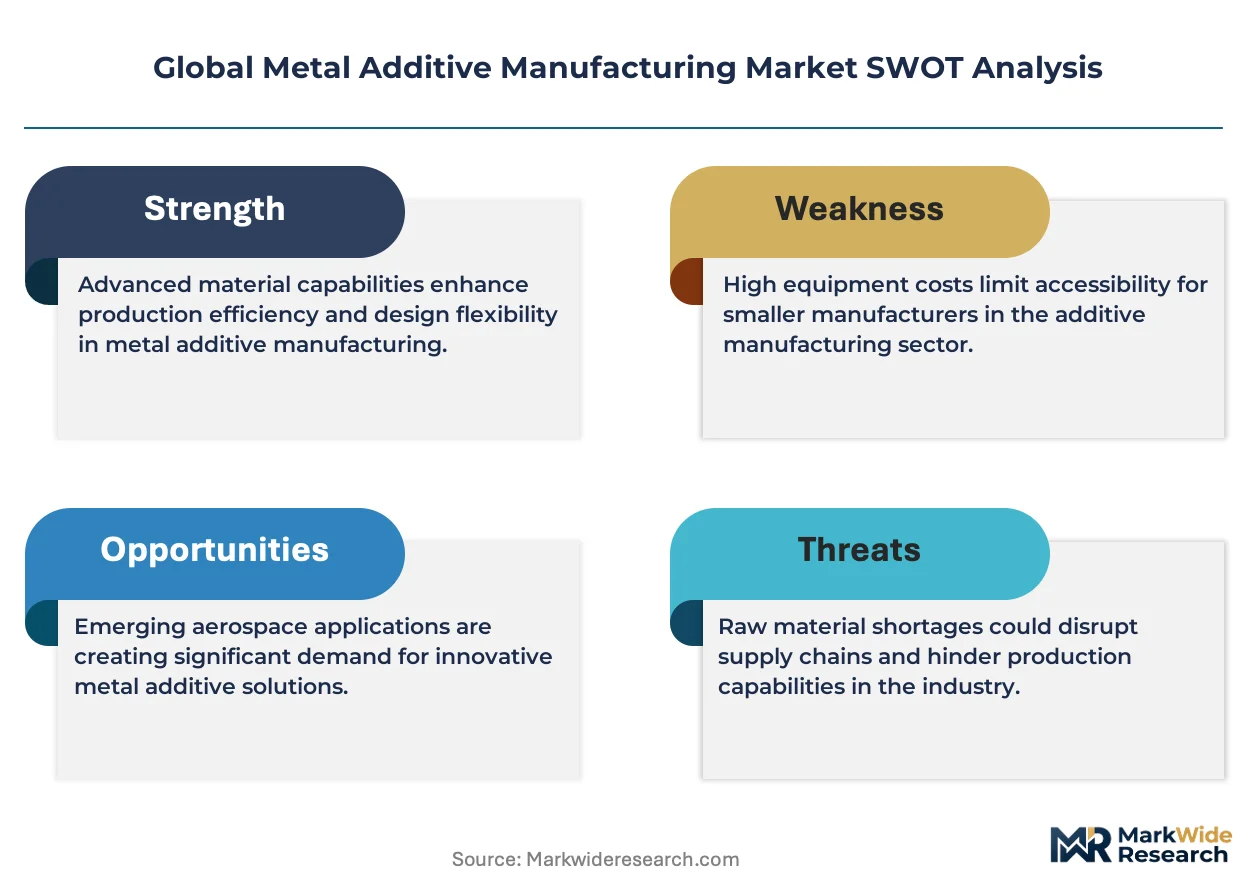
Aerospace OEMs are consolidating in-house metal printing capacity, reversing decades of outsourced component sourcing and forcing tier-two suppliers to reposition around qualification services rather than finished parts.
Growth Catalysts
- EU Green Deal emissions mandates:Powder producers in Germany and France are retrofitting atomization lines to meet carbon intensity benchmarks, creating first-mover advantage for low-carbon titanium and nickel superalloy grades.
- Multi-laser architectures:Laser-based powder bed fusion systems with four or more simultaneous beams are collapsing build times for aerospace brackets and heat exchangers, pulling demand from conventional five-axis machining.
- China's NMPA orthopedic track:Streamed certification pathways for patient-specific cranial and spinal implants are accelerating hospital adoption of printed titanium constructs in Shanghai and Shenzhen surgical centers.
Market Restraints
- Argon and helium supply concentration:Shielding gas dependency on Russian and Qatari sources exposes European powder bed fusion operators to price volatility and allocation risk during energy market shocks.
- Post-processing bottleneck:Hot isostatic pressing and precision CNC finishing capacity lags printer installation rates by roughly three years, constraining effective throughput regardless of build speed improvements.
- REACH powder handling compliance:ECHA classification of fine metallic powders as respiratory hazards mandates costly containment infrastructure, elevating operational expenditure for job shops below fifty-employee thresholds.
Strategic Opportunities
- Binder jetting sintering networks:Mature furnace infrastructure in Michigan and Ohio is enabling stainless steel and tool steel production at costs approaching conventional MIM, opening automotive fluid handling components.
- India's PLI scheme for aerospace:Domestic content requirements for defense platforms are pulling EOS and SLM Solutions to establish qualification partnerships with Bangalore and Hyderabad precision engineering clusters.
- Wire-arc directed energy deposition:Convergence with robotic welding platforms is expanding into maritime propeller repair and oil tool remanufacturing, segments previously uneconomical for powder-based systems.
Industry Challenges
- Non-destructive testing technician scarcity:Industrial CT scanning and ultrasonic validation for internal porosity require certification levels that outpace vocational training output in the US and Germany.
- EASA/FAA dual qualification burden:Divergent fatigue test protocols for flight-critical titanium brackets force redundant test campaigns, compressing margin on low-volume aero-engine contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Metal Additive Manufacturing Market |
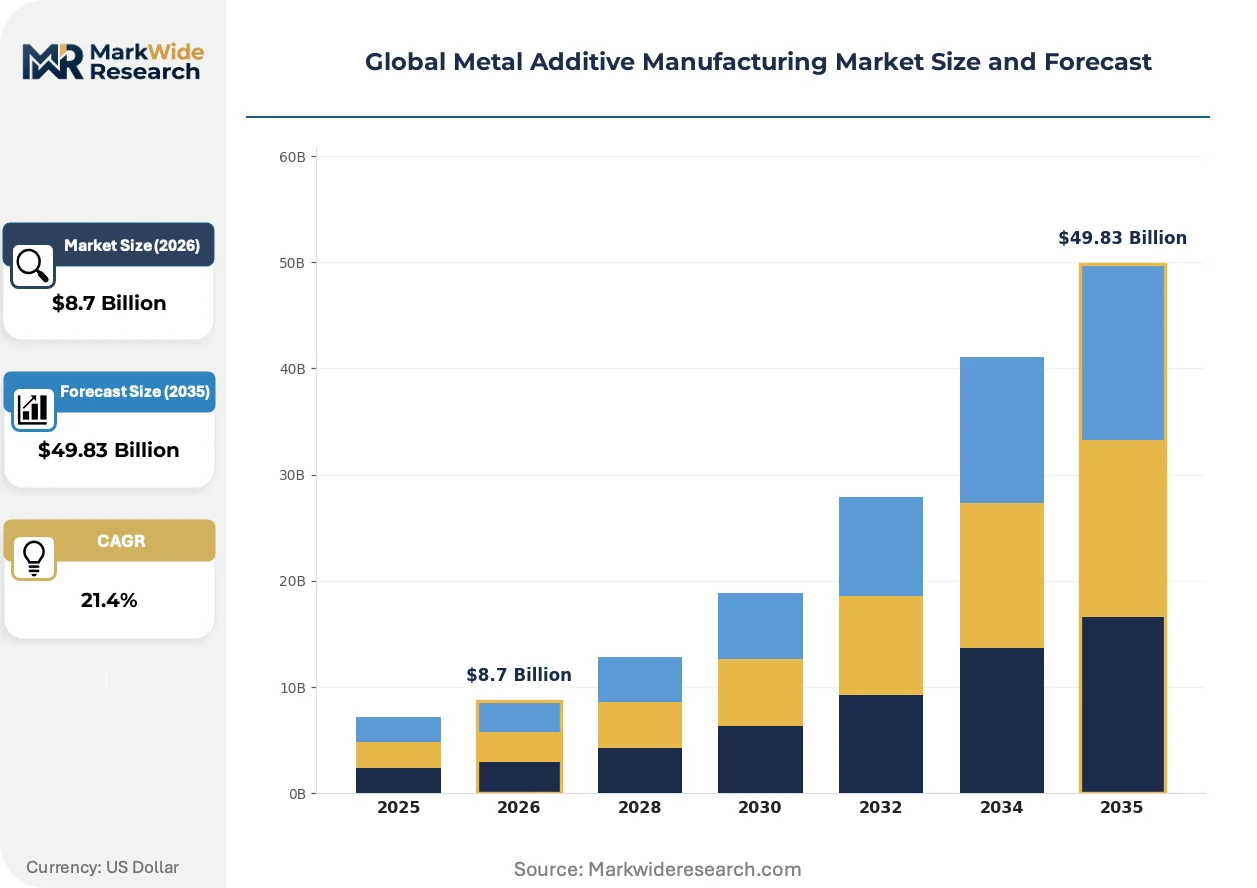
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $49.83 Billion |
| CAGR (2026 – 2036) | 21.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder Bed Fusion, Directed Energy Deposition, Binder Jetting, Material Extrusion Application: Aerospace Components, Medical Devices, Automotive Parts, Tooling End User: OEMs, Research Institutions, Service Bureaus, Startups Technology: Laser-Based Systems, Electron Beam Melting, Hybrid Manufacturing, Sintering Techniques |
| Companies Covered | EOS GmbH, BLT, Nikon SLM Solutions, GE Additive, Renishaw, 3D Systems, DMG Mori, Farsoon, BeAM Machines, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Metal Additive Manufacturing Market Strategic Shifts
Process monitoring and machine learning are converging to enable real-time defect prediction, shifting quality assurance from post-build inspection toward in-situ intervention.
Multi-laser powder bed fusion is expanding into production-scale aerospace bracket manufacturing. Tier-one suppliers in Toulouse and Hamburg are qualifying four-laser configurations for A350 and A320neo structural components. Build-rate economics are compressing the crossover point where additive matches forged-and-machined cost structures for lot sizes below two hundred units.
REACH and EU F-Gas Regulation are tightening solvent and shielding gas supply chains. Powder recyclers in Belgium and the Netherlands are deploying closed-loop argon recovery to maintain operating permits. Binder jetting operators face reformulation pressure as traditional solvents lose authorization, pushing water-based binder development.
Buyer concentration among aerospace primes is consolidating procurement around qualified tier-one additive suppliers. Long-term powder supply agreements with fixed qualification scopes are displacing spot-market purchasing in Toulouse, Munich, and Seattle supply bases. Defense contracts in the UK and Italy now mandate captive additive capacity as a bid prerequisite.
Global Metal Additive Manufacturing Market Segmentation
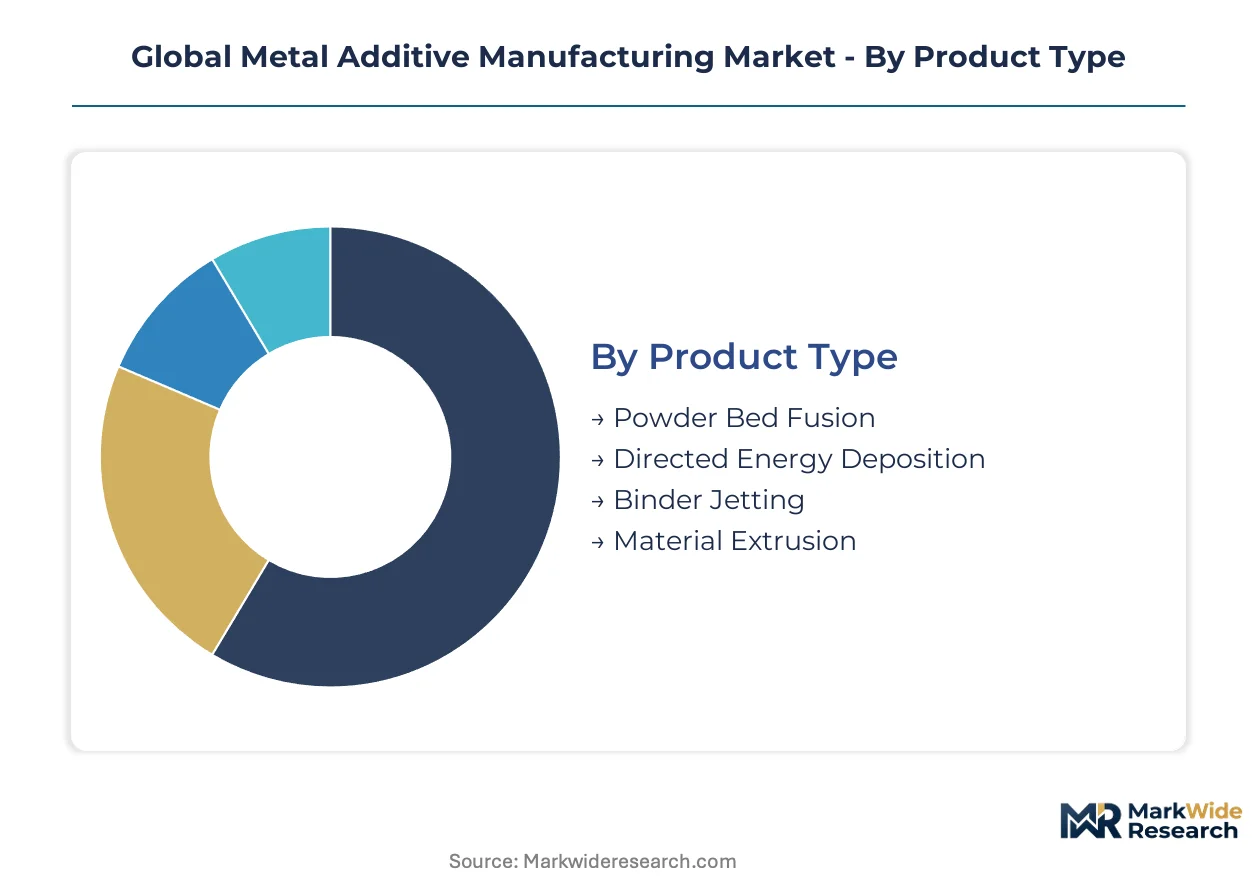
Segmentation in metal additive manufacturing reveals how technology choices lock in downstream economics. Product type determines capital intensity and material scope. Application segments expose diverging qualification timelines and margin structures across aerospace, medical, and industrial end uses.
Product Type:
Customization intensity spans from fully programmable beam paths to constrained sintering workflows, reshaping how buyers match equipment to production economics.
- Powder Bed Fusion:Layer-by-layer selective melting of metallic powders using laser or electron beam energy sources achieves dimensional tolerances of ±50 microns. Demand clusters in Germany around Munich and Aachen industrial corridors, where aerospace OEMs qualify titanium and nickel superalloy flight hardware under EASA protocols. The EU Green Deal's carbon intensity benchmarks are pressuring atomization suppliers to decarbonize feedstock production for these systems.
- Directed Energy Deposition:Wire or powder-fed molten pools built by robotic manipulation enable near-net-shape repair and feature addition on existing components. Maritime propeller remanufacturing in Rotterdam and Singapore shipyards drives adoption, with classification societies developing repair procedure approvals that bypass full forging replacement.
- Binder Jetting:Deposition of liquid binder onto metal powder beds followed by furnace sintering offers tooling-grade stainless steel production without thermal gradients. Mature furnace infrastructure in Michigan and Ohio enables cost convergence with metal injection molding for automotive fluid handling components.
- Material Extrusion:Fused filament fabrication using metal-polymer feedstocks requires secondary sintering and achieves lower densities than fully melted alternatives. Research institutions in Switzerland and Japan pilot structural electronics enclosures where geometric complexity outweighs mechanical loading requirements.
Most installed capacity flows through Powder Bed Fusion. Expansion is steepest in Binder Jetting.
Application:
Cost tier separation divides flight-critical qualification pathways from production-scale industrial tooling with relaxed certification burdens.
- Aerospace Components:Turbine brackets, heat exchangers, and structural nodes demand fatigue life validation under FAA and EASA dual protocols. Toulouse and Hamburg supply bases concentrate procurement around tier-one suppliers with captive additive capacity, displacing spot-market purchasing.
- Medical Devices:Patient-specific cranial plates and spinal cages require biocompatibility certification through FDA 510(k) or China's NMPA orthopedic track. Hospital adoption accelerates in Shanghai and Shenzhen surgical centers where streamlined regulatory pathways reduce time-to-implantation.
- Automotive Parts:Conformal cooling mold inserts and lightweight bracketry target lot sizes below two hundred units where tooling amortization fails. Porsche and BMW motorsport divisions in Stuttgart and Munich lead qualification for aluminum and titanium powertrain hardware.
- Tooling:Injection mold cores with conformal cooling channels reduce cycle times in high-volume polymer processing. H13 tool steel deposition via directed energy deposition serves oil tool remanufacturing in Houston and Aberdeen where component replacement costs exceed repair economics.
Aerospace commands qualification premiums. Medical is climbing fastest on regulatory streamlining.
End User:
Customer type determines access to capital, in-house metallurgical expertise, and tolerance for process development risk.
- OEMs:Airbus, GE Aviation, and Safran consolidate in-house printing capacity, reversing decades of outsourced component sourcing. Captive powder atomization and heat treatment infrastructure insulates against argon supply volatility from Russian and Qatari sources.
- Research Institutions:ETH Zurich, Fraunhofer ILT, and Oak Ridge National Laboratory advance multi-laser process monitoring and machine learning defect prediction. Public funding flows through EU Horizon programs and US Department of Defense manufacturing innovation institutes.
- Service Bureaus:Job shops below fifty-employee thresholds face REACH powder handling compliance costs and ECHA respiratory hazard containment mandates. Consolidation favors regional players with qualified aerospace supplier status.
- Startups:Venture-backed firms in Bangalore and Hyderabad exploit India's PLI scheme for aerospace domestic content requirements. Partnerships with EOS and SLM Solutions accelerate qualification timelines for defense platform bids.
OEMs anchor volume commitments. Startups show steepest headcount expansion.
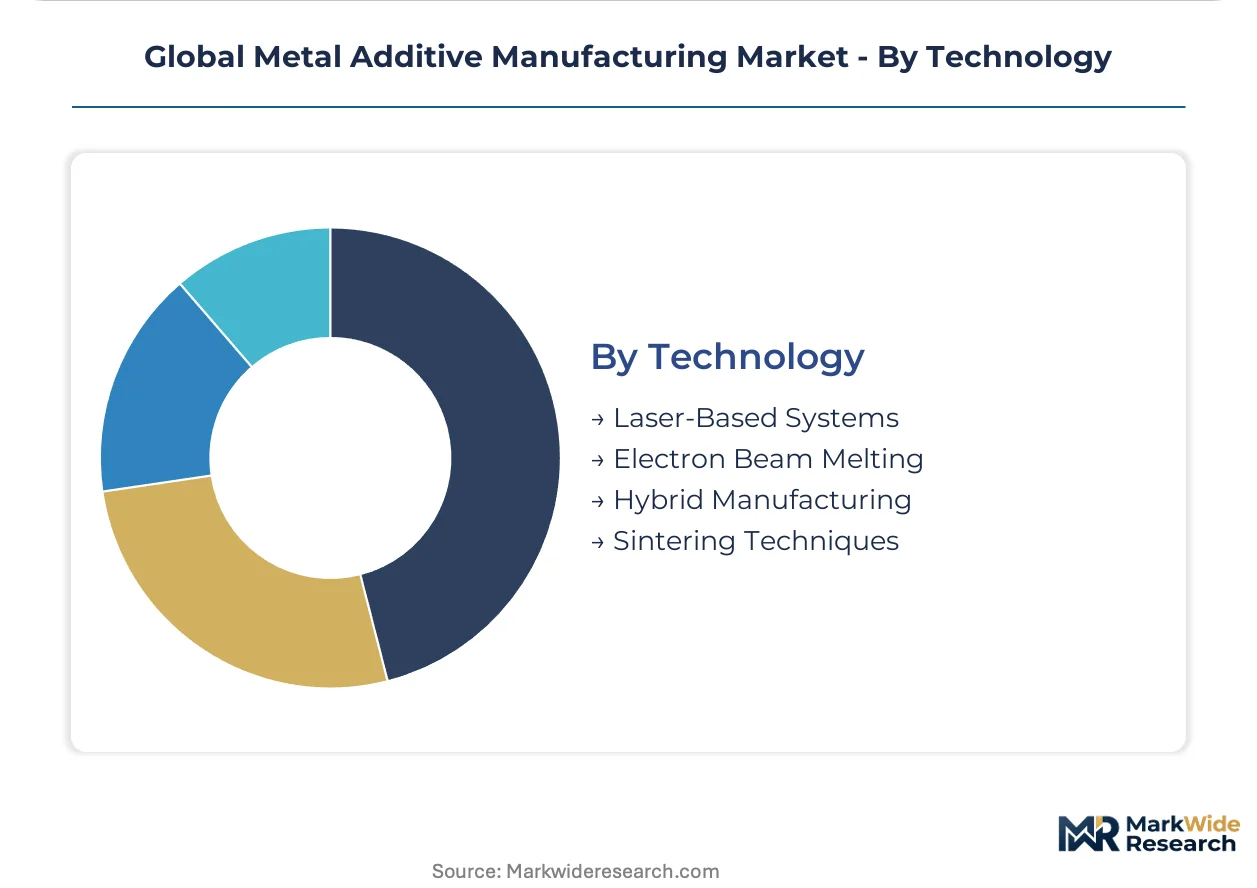
Technology:
Maturity gradient separates production-proven laser architectures from emerging hybrid workflows with unproven scale economics.
- Laser-Based Systems:Fiber and diode laser configurations with four or more simultaneous beams collapse build times for aerospace brackets. Nikon SLM Solutions and EOS GmbH dominate European aerospace qualification programs with multi-laser powder bed fusion portfolios.
- Electron Beam Melting:Vacuum chamber processing eliminates oxidation in titanium aerospace structures, commanding premium positioning for fatigue-critical applications. GE Additive anchors vertical control from powder atomization through finished aero-engine components.
- Hybrid Manufacturing:Integration of additive deposition with five-axis CNC finishing addresses post-processing bottlenecks where hot isostatic pressing capacity lags printer installation rates. DMG MORI and Mazak target mold and die applications in Japan and Germany.
- Sintering Techniques:Binder jetting and metal injection molding convergence depends on furnace network density for stainless steel and tool steel densification. Desktop Metal and ExOne compete on binder formulation as EU F-Gas Regulation constrains traditional solvent authorization.
Laser-Based Systems carry the installed base. Hybrid Manufacturing is gaining share fastest on throughput economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German metallurgical engineers and French aerospace technicians anchor Europe's additive workforce density, while Chinese manufacturing specialists and Indian precision machinists drive Asia-Pacific capacity expansion.
Germany
Munich and Aachen industrial corridors concentrate EASA qualification programs for titanium aerospace brackets. The EU Green Deal's carbon intensity benchmarks pressure atomization suppliers in Bavaria and North Rhine-Westphalia to retrofit production lines for low-carbon nickel superalloy grades.
United States
Michigan and Ohio furnace networks mature binder jetting sintering infrastructure for automotive fluid handling components. FAA dual qualification protocols with EASA force redundant fatigue test campaigns on titanium brackets, compressing margins for Seattle and Los Angeles aerospace suppliers.
China
Shanghai and Shenzhen surgical centers accelerate hospital adoption of printed titanium cranial implants under NMPA's streamlined orthopedic certification track. The country's dual carbon goals pressure powder producers to decarbonize atomization processes for domestic aerospace qualification programs.
India
Bangalore and Hyderabad precision engineering clusters attract qualification partnerships from European equipment manufacturers. The PLI scheme for aerospace domestic content requirements pulls defense platform bids toward captive additive capacity mandates.
United Kingdom
Sheffield and Bristol aerospace suppliers face REACH powder handling compliance costs and ECHA respiratory hazard containment mandates. Defense contracts now require captive additive infrastructure as a bid prerequisite, consolidating procurement around qualified tier-one vendors.
Global Metal Additive Manufacturing Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across technology tiers. Market structure consolidates around three archetypes: European laser-system incumbents with aerospace qualification dominance, Asian equipment manufacturers scaling cost-competitive platforms, and diversified industrial conglomerates integrating additive into broader machining portfolios. Competitive moves center on multi-laser architecture R&D intensity and strategic partnerships for regional qualification acceleration.
Within the European pure-play tier, EOS GmbH exemplifies laser-based powder bed fusion specialization anchored in German industrial clusters. Nikon SLM Solutions occupies a position representing multi-laser system development for production-scale aerospace manufacturing. GE Additive sits within the diversified conglomerate archetype, exemplifying vertical control from feedstock through finished component supply chains.
| Leading Market Players |
|---|
| EOS GmbH |
| BLT |
| Nikon SLM Solutions |
| GE Additive |
| Renishaw |
| 3D Systems |
| DMG Mori |
| Farsoon |
| BeAM Machines |
| Others |
Value Chain & Pricing Dynamics
Argon shielding gas costs cascade from Qatari liquefaction terminals through European powder bed fusion operators, stratifying equipment pricing across captive-atomization OEMs and gas-dependent job shops. REACH compliance investments at the powder handling stage compress margins for sub-fifty-employee service bureaus while tier-one suppliers with closed-loop recovery systems capture pricing premiums on qualified aerospace feedstock.
Pricing Analysis
Equipment-plus-consumables bundling dominates laser-based powder bed fusion transactions, separating turnkey qualification packages from bare-metal hardware sales. Price differentiation rests on EASA/FAA dual-certification status and captive powder atomization capability. Cost compression in mid-tier stainless steel job shop services intensifies as binder jetting furnace networks mature in Michigan and Ohio. Defense OEMs with mandated captive additive capacity show lowest price sensitivity; automotive fluid handling component buyers exhibit highest.
Supply Chain Analysis
Single-source vulnerability sits with Russian and Qatari argon and helium supply for European shielding gas dependency. Germany, China, and the United States anchor powder atomization capacity for titanium and nickel superalloy grades. Feedstock draws from sponge titanium producers in Japan and Ukraine alongside gas atomization equipment sourced from Italy and the United Kingdom. Tariff exposure on Chinese-sourced tungsten filaments for electron beam guns constrains equipment cost structures. Distribution runs through qualified tier-one aerospace supplier networks with long-term offtake agreements displacing spot purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU Green Deal carbon intensity benchmarks on powder production are accelerating capital redeployment toward low-carbon atomization infrastructure.
For Market Incumbents: Extend multi-laser architecture R&D intensity to collapse build-time economics for aerospace bracket production. Deepen backward integration into powder atomization to insulate margin from argon supply volatility. Lock in long-term qualification partnerships with Toulouse and Hamburg supply bases before EASA protocol harmonization widens the competitive aperture. For New Entrants and Emerging Players: Begin with wire-arc directed energy deposition for maritime propeller repair and oil tool remanufacturing segments where powder-based systems remain uneconomical. Target India's Bangalore and Hyderabad precision engineering clusters under PLI scheme domestic content requirements. Lead with robotic welding platform convergence rather than competing head-to-head on laser system installed base. For Investors and Strategic Acquirers: Consolidation pressure builds where REACH compliance costs and ECHA respiratory hazard mandates exceed sub-fifty-employee job shop cash flow generation. Five-to-ten-year viability favors regional service bureaus with qualified aerospace supplier status and closed-loop powder recycling infrastructure. Watch NMPA orthopedic track expansion in Shanghai and Shenzhen surgical centers as signal for patient-specific implant production scale inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Laser System Deployment | Four-beam architectures collapse build times for A350 structural brackets at Toulouse suppliers. |
| Closed-Loop Argon Recovery | Belgian and Dutch powder recyclers maintain operating permits under EU F-Gas Regulation constraints. |
| Hybrid Manufacturing Integration | DMG MORI and Mazak address post-processing bottlenecks where HIP capacity lags printer installations. |
| Regional Qualification Partnership | EOS and SLM Solutions accelerate defense platform bids under India's PLI scheme mandates. |
| Water-Based Binder Reformulation | Desktop Metal and ExOne respond to solvent authorization loss under tightening EU chemical regulations. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with equipment OEM procurement directors, aerospace tier-one supplier manufacturing engineers, powder atomization plant managers, EASA qualification specialists, and hospital biomedical procurement committees with secondary validation against SEC equipment manufacturer filings, EU Horizon program disbursement records, FAA and EASA airworthiness directives, and customs trade data for titanium sponge and gas atomization equipment. Bottom-up printer installation counts and top-down aerospace procurement spend estimates were triangulated for segment sizing.
Comparable historical reference periods anchored the projection horizon across product type, application, end user, and technology segmentation dimensions with regional regulatory cluster overlays. CAGRs were derived from equipment shipment trajectories, powder consumption intensity ratios, and qualification pipeline velocity. Forecast inputs incorporated multi-laser beam count adoption curves, REACH compliance cost pass-through assumptions, and NMPA orthopedic certification throughput rates.
Caveats apply where argon supply allocation shocks, EASA/FAA protocol divergence expansion, or binder jetting furnace network buildout delays could materially shift the outlook. Forecasts reflect documented assumptions on powder recyclability rates and aerospace qualification cycle durations. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Materials
Global 3D Printing Metals Market
3D Printing Materials
Global 3D Printing Construction Material Market
3D Printing Materials
3D Printing Consumables Market
3D Printing Materials
Patterning Materials Market
3D Printing Materials
Europe Polypropylene in 3D Printing Market
3D Printing Materials
Vat Photopolymerization 3D Printing Technology Market
3D Printing Materials
3D Printed Nanocellulose Market
3D Printing Materials
Global Arf Dry and Immersion Resist Materials Market
3D Printing Materials
Industrial 3D Printing Plastic Market
3D Printing Materials
Aerospace 3D Printing Materials Market
3D Printing Materials
LAMEA 3D Graphene Market
3D Printing Materials
Medical 3D Printing Plastics Market
3D Printing Materials
3D Printing Plastics Market
3D Printing Materials
Rapid Prototyping Materials Market
3D Printing Materials
Non-Metal 3D Printing Market
3D Printing Materials
3D Printing High Performance Plastic Market