
 Global Biocompatible 3D Printing Materials Market | 2026-2036
Global Biocompatible 3D Printing Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Global Biocompatible 3D Printing Materials Market Analysis
Medical-grade ISO 10993 certification is bifurcating the competitive landscape into qualified suppliers and commodity resin vendors. Evonik Industries AG leverages its polymer chemistry heritage to anchor European supply chains for implantable PCL grades. 3D Systems Inc sustains North American leadership through vertical control over SLA biocompatible resin formulation. Stratasys Ltd competes by dominating FDM filament certification for hospital-sited surgical planning models.
Biocompatible 3D printing materials encompass photopolymer resins, thermoplastic filaments, and metal powders engineered to meet cytotoxicity, sensitization, and systemic toxicity thresholds under ISO 10993 protocols, serving patient-contact devices from craniomaxillofacial implants to drug-eluting scaffolds. PLA and PCL thermoplastics lead volume consumption due to established degradation profiles in tissue engineering, while SLA photopolymers command premium positioning in dental and hearing aid applications where surface finish precision governs clinical outcomes. SLS-processed TPU and nylon powders occupy growing share in prosthetic sockets and orthotic braces where ductility and fatigue resistance outweigh raw material cost.
FDA 510(k) clearance pathways and EMA MDR compliance frameworks compel material suppliers to maintain Design History Files and biocompatibility testing portfolios that smaller resin compounders cannot fund. The EU Green Deal chemical sustainability criteria and REACH substance restrictions further filter market access for non-European feedstock producers. ISO 13485 quality management certification now functions as a baseline procurement filter for hospital systems and contract manufacturers selecting material partners. Stakeholders must monitor how FDA draft guidance on patient-matched devices reshapes material qualification burdens versus standardized implant portfolios.
Market Dynamics
ISO 10993 certification requirements are splitting qualified medical-grade suppliers from commodity resin vendors, forcing material compounders to absorb multi-year biocompatibility testing costs before accessing implantable device supply chains.
Growth Catalysts
- FDA 510(k) pathway expansion:Streamlined clearance for patient-matched devices accelerates hospital adoption of surgical planning models printed from certified photopolymers.
- Germany's orthopedic cluster:Concentrated implant manufacturing around Tuttlingen and Berlin sustains captive demand for PCL and PLA filament grades.
- SLA surface precision:Sub-25-micron layer resolution enables dental crown and hearing aid shell production that exceeds milled acrylic outcomes.
Market Restraints
- Caprolactone monomer supply:European petrochemical feedstock concentration exposes PCL resin pricing to naphtha volatility and ETS carbon cost pass-through.
- ISO 13485 audit burden:Small compounders lack capital to maintain Design History Files and batch traceability systems required by contract manufacturers.
- Titanium powder substitution:Electron beam melting of Ti-6Al-4V competes for load-bearing orthopedic applications where polymers face fatigue limitations.
Strategic Opportunities
- China NMPA pathway harmonization:Mutual recognition initiatives with FDA and EMA reduce redundant biocompatibility testing for imported resin grades.
- Drug-eluting scaffold convergence:Combination of FDM-printed PCL meshes with API-loaded hydrogels opens controlled-release cardiovascular applications.
- Hospital-sited print farms:Point-of-care manufacturing models bypass distributor markups for craniomaxillofacial surgical guides.
Industry Challenges
- Polymer chemist scarcity:Formulation expertise for photocurable resins with cytocompatibility profiles concentrates in legacy dental material firms.
- Cleanroom capex intensity:ISO Class 7 production environments for implantable-grade filament extrusion require seven-figure facility investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Biocompatible 3D Printing Materials Market |
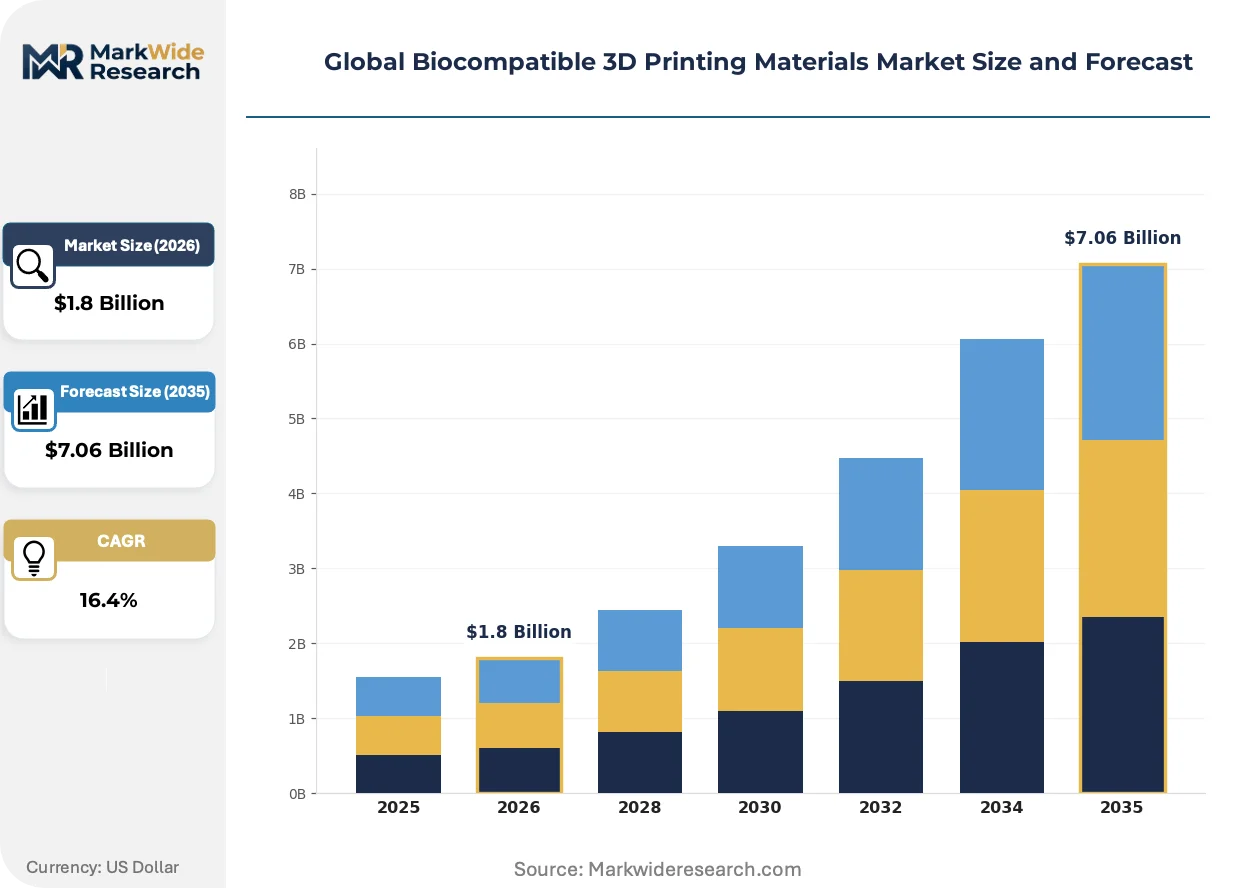
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.06 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: PLA, PCL, TPU, Nylon Application: Medical Devices, Prosthetics, Tissue Engineering, Drug Delivery Technology: FDM, SLA, SLS, DMLS End User: Hospitals, Research Institutions, Pharmaceutical Companies, Universities |
| Companies Covered | Formlabs Inc, 3D Systems Inc, Evonik Industries AG, Stratasys Ltd, Concept Laser GmbH, Renishaw plc, Envisiontec Inc, Cellink, Hoganas AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Biocompatible 3D Printing Materials Market Emerging Trajectories
Material qualification protocols and print technology maturation are converging to expand biocompatible polymers from prototyping into permanent implant applications.
Multi-material extrusion systems with active mixing nozzles are fragmenting the historical separation between structural scaffolds and soft-tissue mimicking regions in tissue engineering constructs. Research hospitals in Boston and Rotterdam deploy these systems for patient-specific tumor models and vascular graft prototypes. The capability compresses lead times for complex geometries that previously required assembly of separately printed components.
EU MDR Article 10 technical documentation requirements now mandate clinical evaluation reports for all implantable device materials, extending qualification timelines for new resin grades. German and Swiss compounders respond by pre-submission engagement with notified bodies. The burden falls heaviest on mid-volume suppliers lacking regulatory affairs departments.
Surgeon-led design workflows are displacing centralized engineering departments for craniomaxillofacial reconstruction guides. Maxillofacial units in London and Melbourne now license direct-to-printer software that bypasses traditional CAD service bureaus. This pattern concentrates in academic medical centers with embedded biomedical engineering programs.
Global Biocompatible 3D Printing Materials Market Segmentation
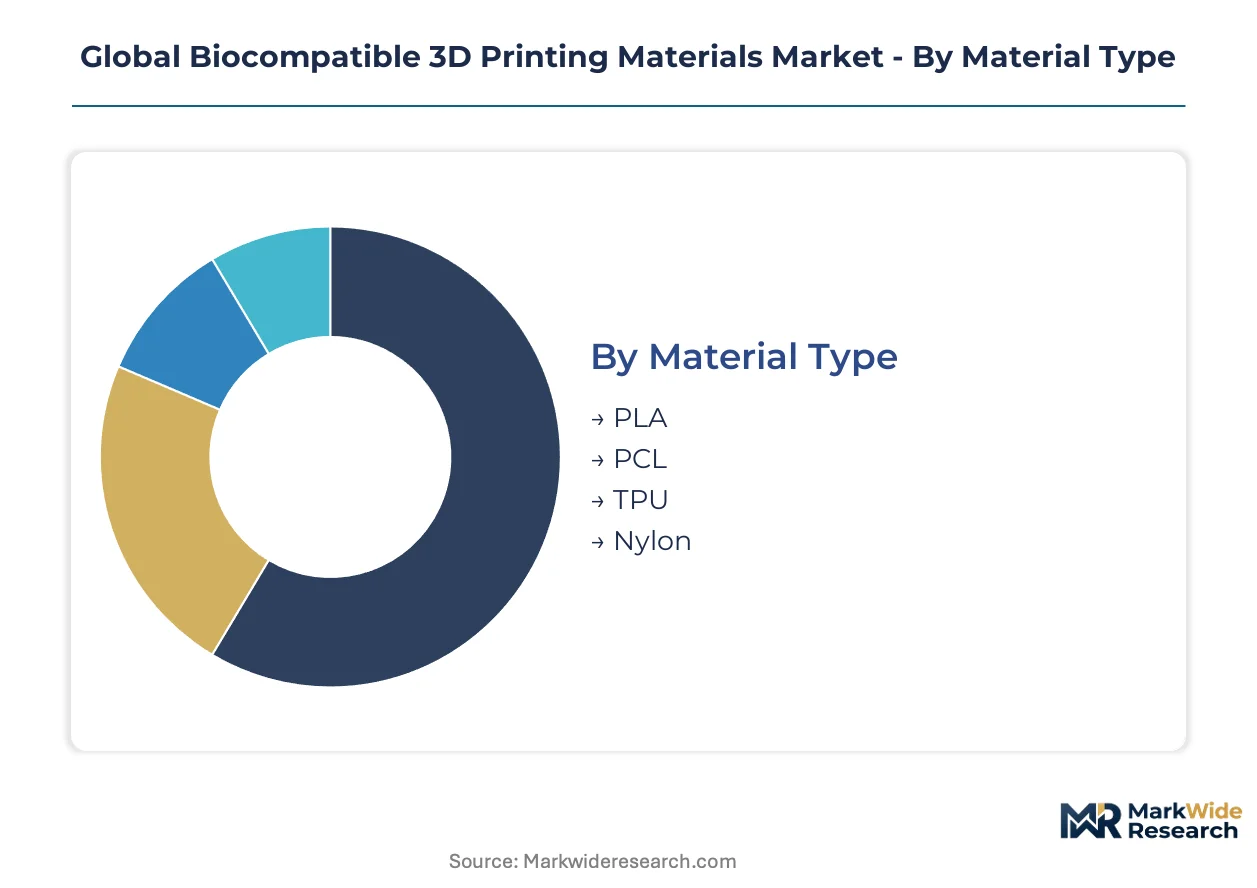
Material qualification pathways and print technology compatibility create divergent margin structures across the biocompatible 3D printing materials market. Segmentation reveals where ISO 10993 certification investments concentrate returns and which application clusters absorb premium pricing.
Material Type:
Margin pools concentrate in implantable-grade thermoplastics where degradation profile validation commands sustained pricing power against commodity resin alternatives.
- PCL:Polycaprolactone offers tunable hydrolytic degradation timelines from 6 to 24 months, enabling scaffold-to-tissue load transfer in orthopedic applications. German implant manufacturers around Tuttlingen anchor European demand for medical-grade filament extrusions. FDA 510(k) submissions for PCL-based cranial plates have expanded hospital procurement specifications.
- PLA:Poly(lactic acid) delivers the most established regulatory clearance portfolio among biodegradable thermoplastics, with documented clinical histories in maxillofacial plating systems. Chinese research institutions drive volume consumption for tissue engineering scaffolds where faster resorption kinetics match shorter healing windows.
- TPU:Thermoplastic polyurethane bridges the gap between rigid structural polymers and soft-tissue mimicking requirements in prosthetic liners.
- Nylon:SLS-processed polyamide powders serve load-bearing orthotic braces where fatigue resistance exceeds PLA limitations.
PCL holds installed capacity. TPU is rotating up the share rankings.
Application:
End-use segmentation tracks how regulatory burden and reimbursement pathways fragment addressable markets across temporary contact versus permanent implant indications.
- Medical Devices:Surgical planning models and patient-specific instrumentation represent the largest addressable volume, with craniomaxillofacial guides leading hospital adoption. The FDA's streamlined 510(k) pathway for patient-matched devices has compressed qualification timelines for photopolymer resins in dental crown and hearing aid shell production.
- Tissue Engineering:Scaffold applications command the steepest expansion trajectory among all segments, driven by convergence of FDM-printed meshes with drug-eluting hydrogels for cardiovascular regeneration. Rotterdam and Boston research hospitals deploy multi-material extrusion systems for vascular graft prototypes.
- Prosthetics:Custom socket manufacturing absorbs SLS-processed TPU and nylon powders where ductility requirements exclude rigid thermoplastics.
- Drug Delivery:Combination product regulations impose the heaviest qualification burden, with EMA MDR Article 10 clinical evaluation requirements extending timelines for API-loaded scaffold submissions.
Medical Devices holds installed capacity. Tissue Engineering is rotating up the share rankings.
Technology:
Print modality selection determines surface finish precision, sterilization compatibility, and throughput economics for each material-resin pairing.
- SLA:Stereolithography dominates dental and hearing aid applications where sub-25-micron layer resolution governs clinical acceptance of printed versus milled acrylic outcomes. 3D Systems maintains North American leadership through captive resin formulation capabilities.
- FDM:Fused deposition modeling anchors hospital-sited print farms for surgical guide production, with PLA and PCL filament grades qualifying for point-of-care craniomaxillofacial reconstruction workflows.
- SLS:Selective laser sintering processes TPU and nylon powders for prosthetic sockets where isotropic mechanical properties outweigh photopolymer brittleness.
- DMLS:Direct metal laser sintering competes for load-bearing orthopedic applications with Ti-6Al-4V powders, constraining polymer penetration in high-stress implant zones.
SLA holds installed capacity. FDM is rotating up the share rankings.
End User:
Customer type segmentation maps procurement authority and quality system requirements across institutional purchasing workflows.
- Hospitals:Academic medical centers with embedded biomedical engineering programs license direct-to-printer software for surgeon-led design workflows, bypassing traditional CAD service bureaus. Maxillofacial units in London and Melbourne concentrate early adoption of point-of-care manufacturing models.
- Pharmaceutical Companies:Drug-eluting scaffold development programs absorb the highest-margin material grades, with combination product regulations mandating ISO 13485-certified supply chains for API-polymer integration.
- Research Institutions:Universities and hospital-affiliated labs drive experimental material qualification, with German and Swiss compounders engaging notified bodies early under EU MDR pre-submission pathways.
- Universities:Educational deployments favor uncertified resin grades for training applications, creating a price-tiered demand floor distinct from clinical-grade procurement.
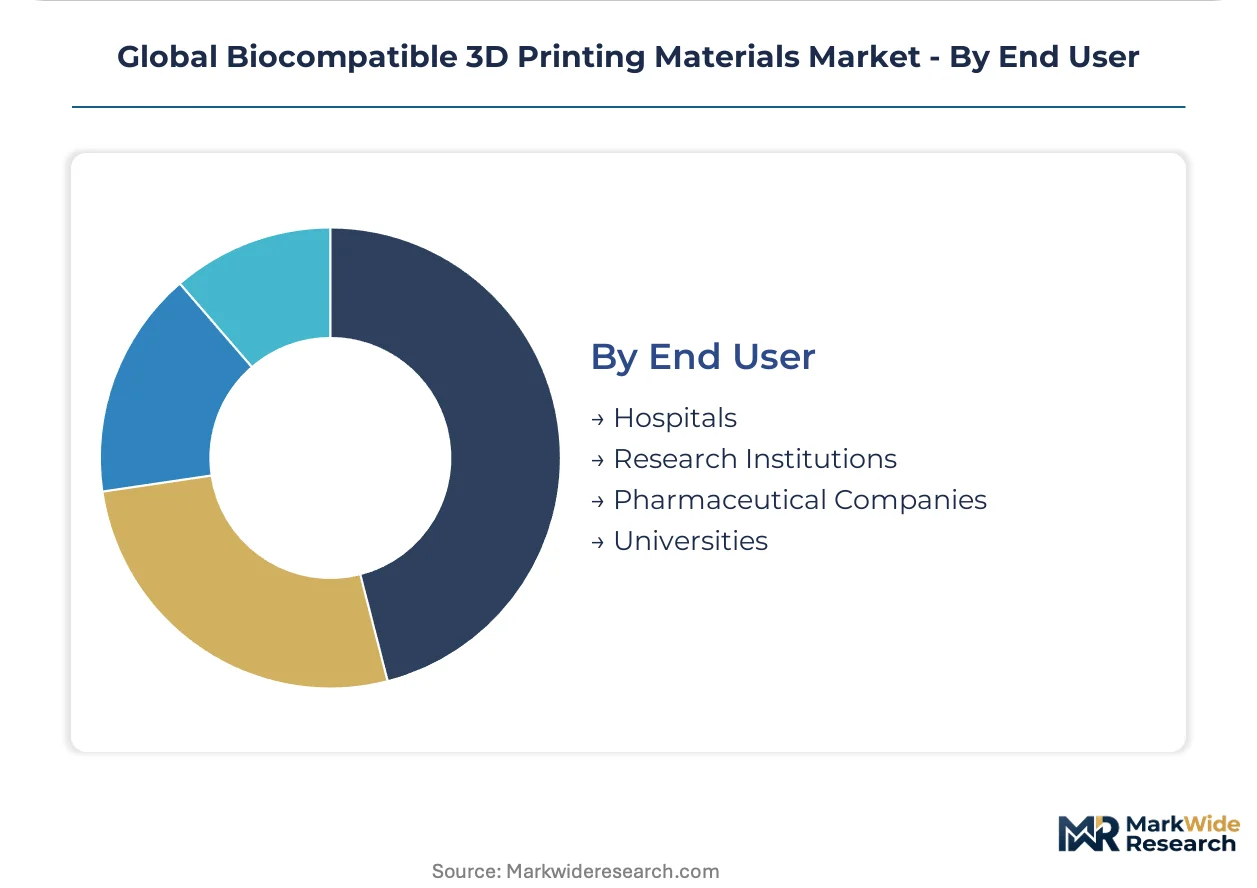
Hospitals hold installed capacity. Pharmaceutical Companies is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European petrochemical feedstock concentration around caprolactone monomer production exposes PCL resin pricing to naphtha volatility. German implant manufacturing clusters and US hospital print farms anchor demand, while Chinese research institutions drive tissue engineering scaffold consumption.
Germany
Tuttlingen and Berlin concentrate orthopedic implant manufacturing, sustaining captive demand for medical-grade PCL and PLA filament grades. EMA MDR compliance frameworks compel material suppliers to maintain Design History Files and biocompatibility testing portfolios. Evonik Industries AG leverages its polymer chemistry heritage to anchor European supply chains for implantable PCL grades.
United States
FDA 510(k) pathway expansion for patient-matched devices accelerates hospital adoption of surgical planning models printed from certified photopolymers. Academic medical centers in Boston and New York license direct-to-printer software for surgeon-led craniomaxillofacial reconstruction workflows. 3D Systems Inc sustains North American leadership through vertical control over SLA biocompatible resin formulation.
China
Research institutions in Shanghai and Beijing drive volume consumption of PLA thermoplastics for tissue engineering scaffolds where faster resorption kinetics match shorter healing windows. NMPA pathway harmonization initiatives with FDA and EMA reduce redundant biocompatibility testing for imported resin grades. The country's national pharmaceutical regulator tightens material qualification pathways for implantable device applications.
United Kingdom
Maxillofacial units in London concentrate early adoption of point-of-care manufacturing models for craniomaxillofacial surgical guides. MHRA alignment with EU MDR Article 10 technical documentation requirements extends qualification timelines for new resin grades. Surgeon-led design workflows are displacing centralized engineering departments for patient-specific reconstruction planning.
Switzerland
German and Swiss compounders engage notified bodies early under EU MDR pre-submission pathways to navigate extended qualification timelines. Swissmedic oversight of combination product regulations imposes the heaviest qualification burden for API-loaded scaffold submissions. Basel and Zurich host research hospitals deploying multi-material extrusion systems for vascular graft prototypes.
Global Biocompatible 3D Printing Materials Market Vendor Landscape
Concentration sits with diversified polymer compounders and specialized 3D printing equipment manufacturers that control resin formulation capabilities. The competitive landscape bifurcates between qualified medical-grade suppliers with ISO 10993 certification and commodity resin vendors excluded from implantable device supply chains. Strategic archetypes include petrochemical-derived polymer specialists, photopolymer resin formulators, and hospital-sited print farm operators. Dominant competitive moves encompass multi-year biocompatibility testing investments and captive supply chain integration for medical-grade filament extrusion.
Within the polymer chemistry tier, Evonik Industries AG and Stratasys Ltd exemplify divergent positioning strategies. Evonik represents the petrochemical heritage archetype with European supply chain anchoring for implantable grades, while Stratasys occupies the equipment-integrated filament certification position for hospital-sited surgical planning models. 3D Systems Inc sits within the photopolymer formulation specialist category, sustaining North American market presence through resin chemistry control.
| Leading Market Players |
|---|
| Formlabs Inc |
| 3D Systems Inc |
| Evonik Industries AG |
| Stratasys Ltd |
| Concept Laser GmbH |
| Renishaw plc |
| Envisiontec Inc |
| Cellink |
| Hoganas AB |
| Others |
Supply Flow & Price Mechanics
Titanium powder substitution for load-bearing orthopedic implants simultaneously shifts production geography toward Chinese and German metal powder hubs and compresses polymer pricing power in high-stress applications. This substitution dynamic feeds back into resin compounder decisions on whether to absorb ISO 10993 certification costs for implantable grades or retreat to surgical planning model markets.
Pricing Analysis
FDA 510(k) and EMA MDR compliance dictates the pricing tier structure across medical-grade biocompatible materials. Three-tier pricing structure across implantable-certified, hospital-grade, and research-use levels separates qualified suppliers from commodity resin vendors. Price differentiation rests on ISO 10993 certification depth and batch traceability systems. Cost compression in hospital-grade photopolymers is intensifying because surgeon-led design workflows bypass traditional CAD service bureaus. Academic medical centers exhibit lowest price sensitivity due to embedded biomedical engineering programs, while training universities drive economy-tier demand.
Supply Chain Analysis
Container availability fluctuations on Asia-Europe trade lanes expose German and Chinese compounders to naphtha feedstock volatility. Geographic supply concentrates in Germany, China, and the United States. Raw material dependencies center on caprolactone monomer, photoinitiator chemicals, and titanium powder alternatives. Single-source vulnerability sits with European petrochemical feedstock concentration for PCL resin. Distribution runs through hospital GPO contracts and implant manufacturer direct procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating among hospital systems with embedded biomedical engineering programs, fragmenting procurement authority away from centralized distributor networks. This shift demands repositioning across incumbent, entrant, and investor strategies.
For Market Incumbents: Fortify ISO 13485-certified filament extrusion capacity in Germany and the United States against emerging Chinese resin compounders. Deepen backward integration into caprolactone monomer supply to offset ETS carbon cost pass-through. Prioritize captive resin formulation capabilities for SLA dental applications where 3D Systems holds defensive positioning. For New Entrants and Emerging Players: Lead with drug-eluting scaffold convergence applications in Rotterdam and Boston research hospitals where multi-material extrusion expertise concentrates. Target tissue engineering segments before orthopedic implant qualification barriers harden further. Pursue notified body pre-submission pathways under EU MDR Article 10 to compress regulatory timelines versus incumbent Design History File portfolios. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed photopolymer resin formulators lacking ISO 10993 implantable-grade certification. Five-to-ten year viability favors compounders with dual FDA-EMA clearance portfolios and hospital-sited print farm partnerships. Monitor NMPA-FDA harmonization progress as inflection indicator for Chinese market access premiums.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 10993 Certification Investment | Biocompatibility testing portfolios differentiate qualified suppliers from commodity resin vendors in implantable device supply chains. |
| Hospital System Partnership | Academic medical centers in Boston and Melbourne license direct-to-printer software for surgeon-led craniomaxillofacial workflows. |
| Backward Integration into Monomer Supply | European compounders reduce naphtha volatility exposure through captive caprolactone production capacity. |
| Multi-Material Extrusion Development | Active mixing nozzle systems compress lead times for vascular graft prototypes at Rotterdam research hospitals. |
| Regulatory Pre-Submission Engagement | German and Swiss compounders navigate EU MDR Article 10 clinical evaluation requirements through early notified body consultation. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EMA MDR submissions, ISO 13485 audit records, and hospital procurement databases. Primary interviews engaged polymer chemists at resin compounders, biomedical engineers at academic medical centers, GPO contracts managers, and regulatory affairs leads at notified bodies. Bottom-up filament shipment data triangulates against top-down implant manufacturer material spend analysis.
Segmentation dimensions modeled include material type, application indication, print technology modality, and end-user procurement authority across the projection horizon. CAGRs derive from installed capacity analysis, qualification timeline assumptions, and substitution elasticity between polymer and metal powder alternatives. Forecast inputs incorporate surgeon adoption curves for point-of-care manufacturing and REACH substance restriction trajectories.
Forecasts assume regulatory continuity in FDA 510(k) pathways and EMA MDR enforcement; material policy shifts would require re-modeling. NMPA harmonization progress, caprolactone supply disruptions, and titanium powder cost movements constitute primary revision triggers. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Materials
3D Printing High Performance Plastic Market
3D Printing Materials
Global 3D Printing Construction Material Market
3D Printing Materials
3D Printing Elastomers Market
3D Printing Materials
3D Printing Materials and Services Market
3D Printing Materials
3D Printing Resin Market
3D Printing Materials
3D Printing Photopolymers Market
3D Printing Materials
Global Metal Additive Manufacturing Market
3D Printing Materials
3D Printing Materials Market
3D Printing Materials
Global 3D Printing Filament Market
3D Printing Materials
Polyamide 12 Powder for High-Performance 3D Printing Market
3D Printing Materials
Industrial 3D Printing Plastic Market
3D Printing Materials
Non-Metal 3D Printing Market
3D Printing Materials
Middle East 3D Printing Materials Market
3D Printing Materials
3D Printing Applications Polymers Market
3D Printing Materials
Stainless Steel 3D Printing Market
3D Printing Materials
Metal Jet 3D Printing Technology Market