
 3D Printing Elastomers Market | 2026-2036
3D Printing Elastomers Market Size, Share, and Industry Trends Forecast 2026-2036
3D Printing Elastomers Market Analysis
Project finance for industrial additive manufacturing installations is rewriting competitive entry barriers in 3D printing elastomers. BASF SE leverages its integrated polymer science portfolio to supply certified TPU feedstocks for automotive qualification programs. Carbon Inc anchors its position through proprietary Digital Light Processing platforms that deliver isotropic elastomeric properties. Stratasys Ltd. competes across healthcare and aerospace verticals with validated workflow ecosystems.
3D printing elastomers are stretchable, rubber-like materials formulated from thermoplastic polyurethanes, photopolymer resins, or silicone compositions, processed through layer-by-layer additive techniques to achieve Shore hardness values between 30A and 95A for functional sealing, cushioning, and ergonomic applications. Flexible filaments currently dominate production volumes due to compatibility with widely deployed Fused Deposition Modeling hardware. Liquid silicone rubber represents the fastest-growing formulation category as medical device manufacturers pursue biocompatible, sterilizable geometries impossible through conventional molding. Thermoplastic elastomers concentrate margin pools in automotive underhood applications where heat resistance and fatigue life determine specification.
FDA 510(k) material master files and EU MDR technical documentation requirements shape product development timelines and commercialization pathways for healthcare-focused elastomer suppliers. EPA industrial chemical notifications and REACH SVHC candidate list screenings constrain formulation freedom for photoinitiators and plasticizers in cross-border supply chains. ISO 10993 biocompatibility testing protocols add cost layers but create defensible positions for qualified vendors. Stakeholders must monitor evolving chemical hazard classifications and build regulatory intelligence capabilities before committing capital to new elastomer platforms.
Market Dynamics
Automotive manufacturers are consolidating supplier relationships around certified TPU feedstocks capable of withstanding underhood thermal cycling, forcing material vendors to pre-qualify formulations against OEM specification databases before design release.
Growth Catalysts
- REACH SVHC Screening:ECHA's expanding candidate list for Substances of Very High Concern is accelerating R&D investment in bio-based photoinitiators and non-phthalate plasticizers for cross-border elastomer formulations.
- Medical Device Prototyping:ISO 10993 biocompatibility testing protocols are creating captive demand for liquid silicone rubber capable of sterilization cycles impossible through conventional molding.
- German Industrial Automation:Precision engineering clusters around Stuttgart and Munich are driving specification pull for Shore 40A-70A elastomers with fatigue life exceeding ten million cycles.
Market Restraints
- Photopolymer Resin Volatility:Acrylate and methacrylate monomer prices fluctuate with propylene oxide feedstock costs, compressing margin predictability for photopolymer elastomer suppliers.
- Hardware Vendor Lock-in:Proprietary resin formulations tied to Carbon Inc's Digital Light Processing and Stratasys Ltd's PolyJet platforms fragment material procurement across incompatible equipment ecosystems.
- FDA 510(k) Timeline Friction:Material master file review cycles extending eighteen to thirty-six months delay commercialization of novel elastomer platforms for healthcare applications.
Strategic Opportunities
- Indian Medical Device Manufacturing:CDSCO's streamlined medical device rules and production-linked incentive schemes are attracting contract manufacturers seeking sterilizable elastomer components for export markets.
- Soft Robotics Convergence:Integration of pneumatic actuation with variable-stiffness 3D-printed elastomers is opening specification channels in warehouse automation and prosthetic devices.
- Direct Digital Distribution:Cloud-based material libraries and print-parameter marketplaces are disintermediating traditional resin distributors for low-volume, high-mix elastomer procurement.
Industry Challenges
- Process Engineering Talent Scarcity:Compound expertise spanning rheology, photochemistry, and additive process control concentrates among a narrow cohort of specialists, inflating recruitment costs.
- Multi-Material Integration Complexity:Bonding dissimilar elastomers to rigid substrates in single-build workflows requires proprietary interlayer chemistry that few vendors have validated at production scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Printing Elastomers Market |
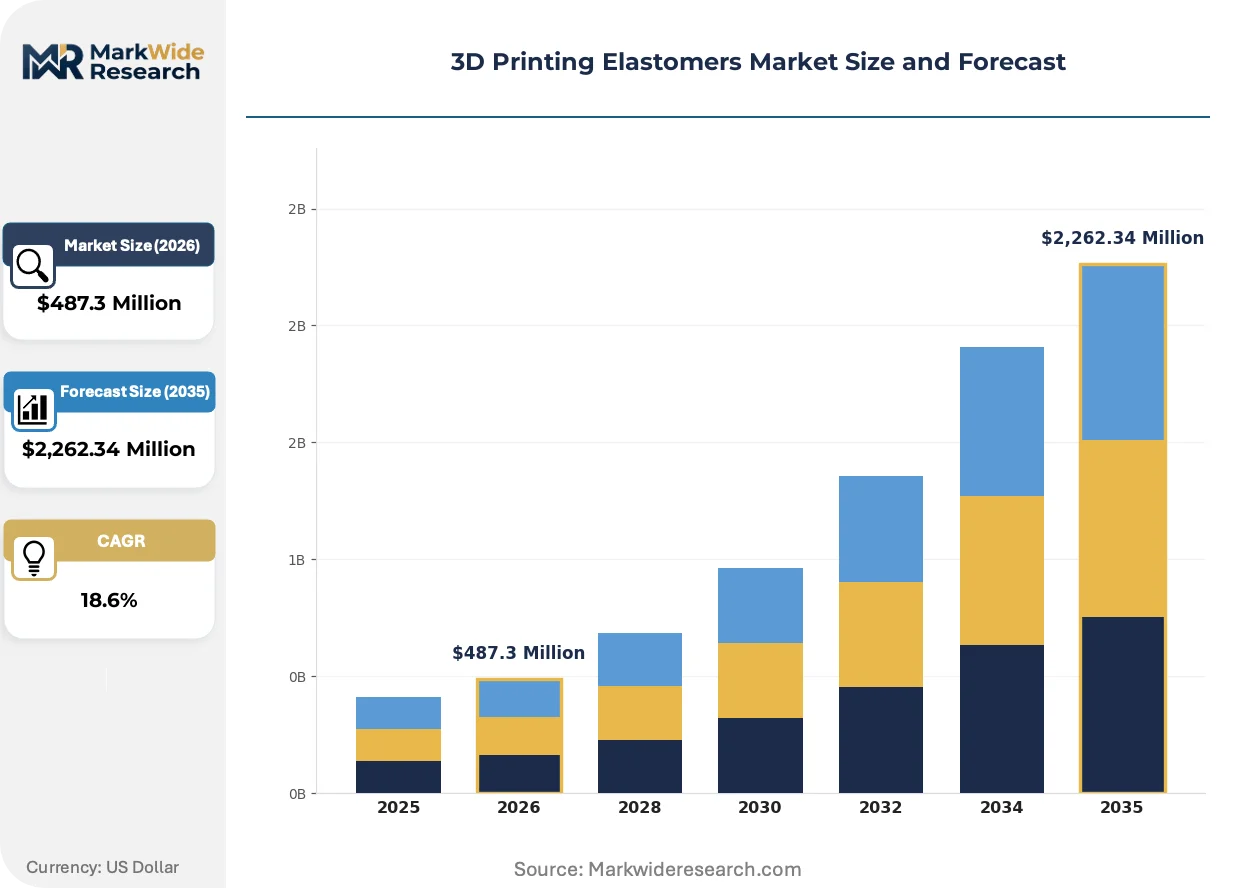
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $2,262.34 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Filaments, Thermoplastic Elastomers, Liquid Silicone Rubber, UV-Curable Resins Application: Medical Devices, Automotive Components, Consumer Products, Industrial Parts Technology: Stereolithography, Fused Deposition Modeling, Selective Laser Sintering, Digital Light Processing End User: Healthcare Sector, Automotive Manufacturers, Aerospace Industry, Consumer Goods Companies |
| Companies Covered | Stratasys Ltd., 3D Systems Corporation, BASF SE, Arkema S.A., Evonik Industries AG, Henkel AG & Co. KGaA, EOS GmbH, Lubrizol Corporation, Carbon Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Printing Elastomers Market Emerging Trajectories
Material science breakthroughs and regulatory harmonization pressures are converging to compress development cycles while fragmenting competitive positions across hardware-locked ecosystems.
Liquid silicone rubber formulations with tunable durometer gradients are digitizing the production of patient-specific medical devices. Surgical instrument manufacturers in Minnesota and Massachusetts are qualifying these materials for sterilizable handles and seals. The technology is digitizing supply chains previously dependent on steel-tooling lead times exceeding twelve weeks.
EU MDR technical documentation requirements and FDA 510(k) material master file pathways are diverging in data package specifications. European notified bodies are demanding extended cytotoxicity testing protocols that US submissions do not require. Medical elastomer suppliers are responding by maintaining parallel regulatory intelligence teams in Brussels and Washington.
Automotive procurement teams are unbundling after-sales service contracts from initial component supply, creating spot-market dynamics for replacement seals and gaskets. Tier-one suppliers are responding with distributed print-cell networks positioned near regional assembly plants. This pattern is most visible in Bavaria and Baden-Württemberg, where just-in-sequence delivery mandates compress inventory buffers to forty-eight hours.
3D Printing Elastomers Market Segmentation
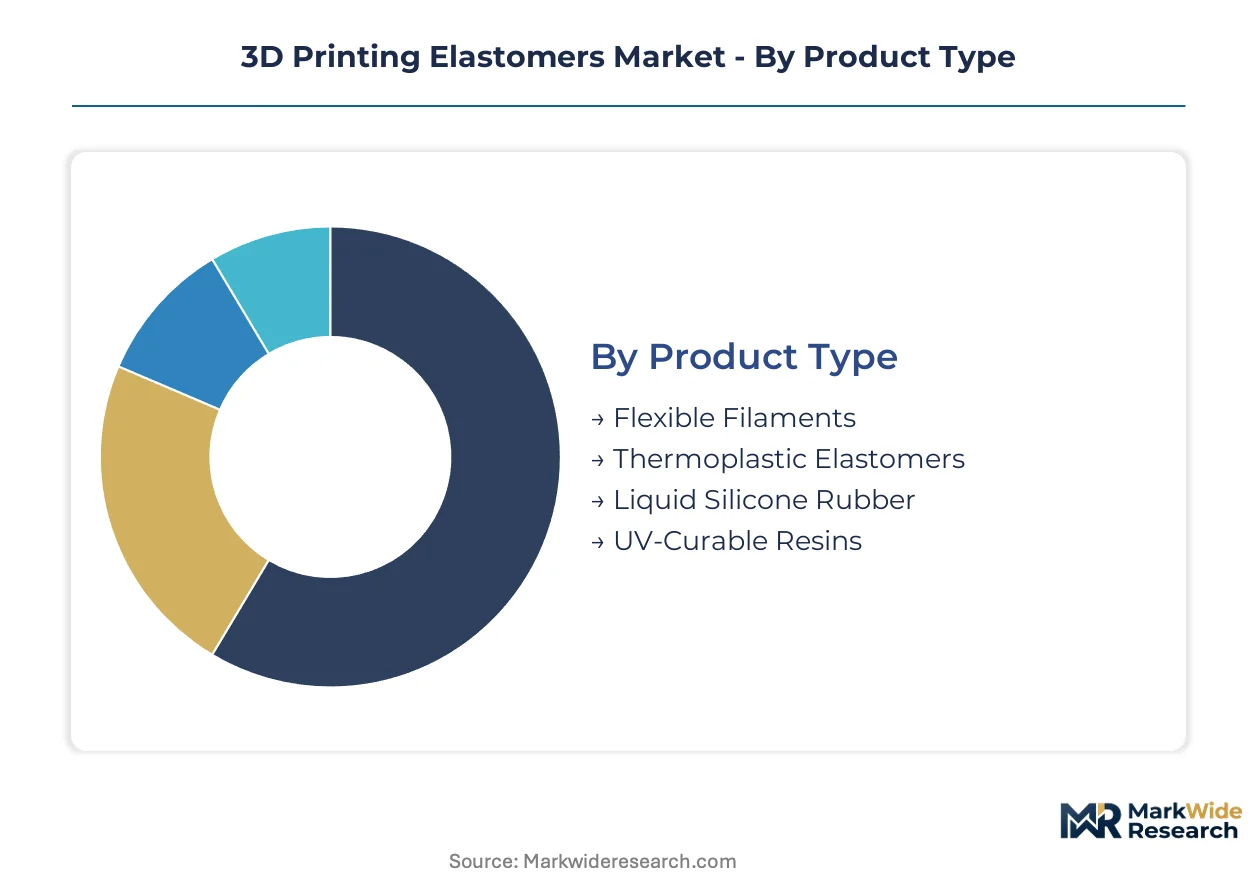
Segmentation in 3D printing elastomers reveals how material properties, process constraints, and regulatory requirements partition commercial opportunity. Suppliers must align formulation portfolios with specific hardware ecosystems and end-use qualification pathways to capture margin.
Product Type:
Mature formulations dominate installed base volumes while emerging chemistries reshape specification pipelines.
- Flexible Filaments:Thermoplastic polyurethane filaments extrude through standard Fused Deposition Modeling hardware at Shore 85A-95A hardness. Automotive prototyping teams in Germany specify these materials for seal validation cycles due to equipment ubiquity and feedstock cost predictability.
- Liquid Silicone Rubber:Two-part platinum-cure silicone systems achieve Shore 30A-60A with biocompatibility profiles meeting ISO 10993 protocols. Minnesota surgical instrument manufacturers are qualifying these for sterilizable handles that conventional molding cannot produce in low volumes.
- Thermoplastic Elastomers:Injection-grade TPE pellets adapted for pellet-fed additive systems bridge conventional processing with geometric freedom.
- UV-Curable Resins:Acrylate-urethane hybrid photopolymers deliver isotropic elasticity through vat polymerization platforms.
Flexible filaments handle the majority of throughput; liquid silicone rubber is the fastest mover on share.
Application:
Application segmentation tracks how regulatory intensity and performance requirements stratify procurement behavior across verticals.
- Medical Devices:Patient-specific prosthetics, surgical guides, and sterilizable seals require ISO 10993 biocompatibility and FDA 510(k) material master files. Massachusetts device startups are digitizing supply chains for instruments previously dependent on twelve-week steel tooling lead times.
- Automotive Components:Underhood seals, gaskets, and vibration dampers demand heat resistance beyond 150°C and fatigue life exceeding ten million cycles. Bavarian OEMs are consolidating supplier relationships around certified TPU feedstocks pre-qualified against specification databases.
- Consumer Products:Ergonomic grips, wearables, and sporting goods prioritize haptics and color stability over thermal performance.
- Industrial Parts:Custom gaskets, bellows, and damping elements for machinery maintenance exploit geometric complexity without mold investment.
Automotive components command the largest addressable spend; medical devices show the steepest expansion trajectory as regulatory pathways mature.
Technology:
Technology segmentation reflects hardware vendor lock-in and the process-property trade-offs that constrain material selection.
- Fused Deposition Modeling:Filament extrusion systems dominate installed base and operator familiarity. Stuttgart automation clusters specify FDM for rapid seal prototyping where surface finish requirements remain secondary to speed.
- Digital Light Processing:Mask-based vat polymerization delivers isotropic mechanical properties and smooth surface finishes. Proprietary resin formulations tie material procurement to specific hardware ecosystems, fragmenting supply chains.
- Stereolithography:Laser-scanned vat systems achieve fine feature resolution for microfluidic and hearing aid applications.
- Selective Laser Sintering:Powder bed fusion of TPU powders enables complex lattices and multi-material gradients without support structures.
Fused Deposition Modeling anchors current throughput; Digital Light Processing is gaining share fastest as production-grade platforms penetrate automotive validation workflows.
End User:
End user segmentation exposes how qualification burden and volume scale fragment procurement patterns across buyer archetypes.
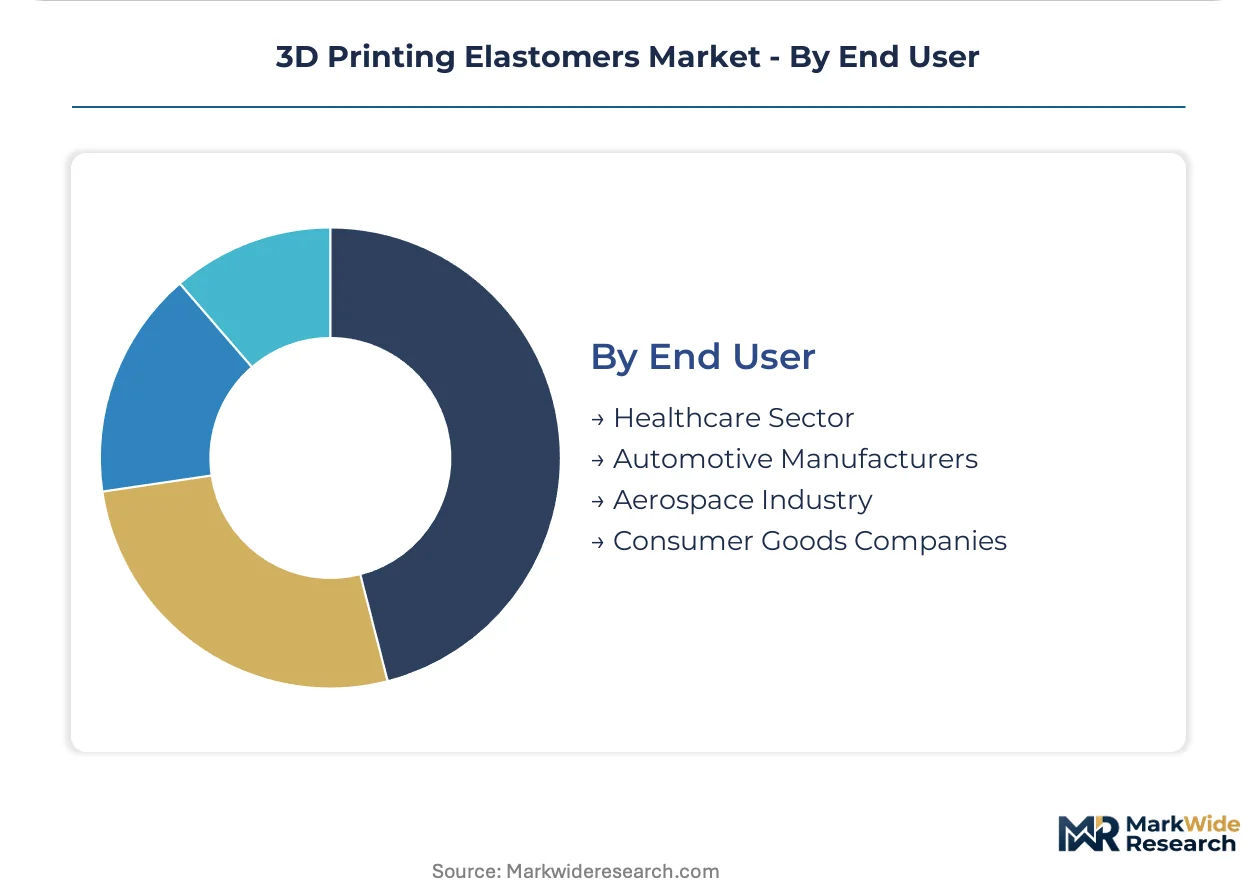
- Healthcare Sector:Hospitals, contract manufacturers, and device startups pursue patient-specific geometries and sterilizable materials. CDSCO's streamlined rules in India are attracting production-linked incentive beneficiaries seeking export-qualified elastomer components.
- Automotive Manufacturers:OEMs and tier-one suppliers consolidate around certified feedstocks for underhood thermal cycling. Just-in-sequence delivery mandates in Baden-Württemberg compress inventory buffers to forty-eight hours, favoring distributed print-cell networks.
- Aerospace Industry:Cabin interior components and duct seals require FAR 25.853 flammability compliance and traceable material lots.
- Consumer Goods Companies:Footwear, electronics, and sporting goods brands prioritize design iteration speed and regional production flexibility.
Automotive manufacturers represent the deepest specification expertise; healthcare sector buyers are expanding most quickly as regulatory harmonization accelerates platform qualification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German material suppliers extract pricing premiums for REACH-certified TPU feedstocks while Indian contract manufacturers compete on sterilizable component volume. This asymmetry reflects divergent regulatory burden and automation intensity across regional production bases.
United States
Massachusetts surgical instrument startups and Minnesota medical device clusters drive demand for liquid silicone rubber with ISO 10993 clearance. FDA 510(k) material master file pathways extend eighteen to thirty-six months, compressing commercialization velocity for novel formulations. Boston-area contract manufacturers operate distributed print-cell networks for patient-specific prosthetics.
Germany
Baden-Württemberg and Bavarian automotive OEMs consolidate procurement around certified TPU feedstocks for underhood thermal cycling. ECHA REACH SVHC screenings constrain photoinitiator selection, accelerating R&D investment in bio-based alternatives. Stuttgart precision engineering clusters specify Shore 40A-70A elastomers with fatigue life exceeding ten million cycles.
India
CDSCO's streamlined medical device rules and production-linked incentive schemes attract contract manufacturers targeting export markets. CDSCO alignment with EU MDR technical documentation requirements reduces dual-qualification burden for sterilizable components. Maharashtra and Gujarat industrial corridors host emerging print-cell networks for regional automotive supply.
China
SAMR industrial chemical notifications and GB standards compliance shape formulation freedom for photopolymer resin suppliers. MIIT additive manufacturing industrialization programs accelerate domestic hardware deployment. Yangtze River Delta medical device manufacturers qualify liquid silicone rubber for biocompatible geometries.
Japan
METI technology roadmaps prioritize high-performance elastomer development for robotics and prosthetic applications. PMDA biocompatibility protocols align with ISO 10993 while maintaining country-specific documentation requirements. Kansai industrial automation clusters integrate 3D-printed elastomeric actuators into warehouse logistics systems.
3D Printing Elastomers Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in feedstock and formulation layers. The vendor base stratifies across three tiers: integrated chemical conglomerates with polymer science portfolios, hardware-locked platform operators with proprietary resin ecosystems, and independent material suppliers serving cross-platform demand. Dominant competitive moves include strategic partnerships between chemical suppliers and hardware vendors, plus geographic expansion of distributed print-cell networks near regional automotive assembly plants.
Among diversified chemical conglomerates, BASF SE and Evonik Industries AG occupy positions anchored by integrated polymer science capabilities and certified feedstock portfolios. Carbon Inc exemplifies the hardware-locked platform archetype through proprietary Digital Light Processing ecosystems that fragment material procurement. Stratasys Ltd. sits within the validated workflow tier, competing across healthcare and aerospace verticals with equipment-agnostic material partnerships.
| Leading Market Players |
|---|
| Stratasys Ltd. |
| 3D Systems Corporation |
| BASF SE |
| Arkema S.A. |
| Evonik Industries AG |
| Henkel AG & Co. KGaA |
| EOS GmbH |
| Lubrizol Corporation |
| Carbon Inc |
| Others |
Supply Flow & Price Mechanics
REACH SVHC regulatory chokepoints on photoinitiator feedstocks determine both three-tier pricing stratification across certified, standard, and uncertified material grades and the geographic reshaping of formulation supply chains toward German and US chemical clusters.
Pricing Analysis
Industrial OEM buyers anchor pricing stratification across premium, standard, and economy tiers. Price differentiation hinges on REACH certification grade and ISO 10993 biocompatibility clearance. Cost compression in economy-grade TPU filaments is intensifying because Asian feedstock suppliers are expanding pellet capacity. Tier-one automotive manufacturers show least price sensitivity due to qualification lock-in, while contract manufacturers in India exhibit highest sensitivity.
Supply Chain Analysis
Extended payment terms from BASF SE and Evonik Industries AG finance downstream inventory positions for distributors serving mid-volume buyers. Feedstock production concentrates in Germany, the United States, and China. Formulation draws from propylene oxide derivatives, platinum-cure silicone precursors, and bio-based photoinitiators. Single-source vulnerability runs through Carbon Inc's proprietary resin ecosystem for Digital Light Processing hardware. Distribution runs through authorized material distributors and direct digital platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflects as hardware-locked resin ecosystems fragment procurement and cloud-based parameter marketplaces disintermediate traditional distributors.
For Market Incumbents: Build certification moats around FDA 510(k) material master files and EU MDR technical documentation to defend against emerging bio-based formulation entrants. Deepen backward integration into photoinitiator supply to offset REACH SVHC restriction risk. Anchor capacity expansion in Baden-Württemberg to serve just-in-sequence automotive mandates. For New Entrants and Emerging Players: Build out liquid silicone rubber formulation capabilities targeting Minnesota and Massachusetts surgical instrument clusters where sterilizable geometries command specification premiums. Penetrate CDSCO-registered contract manufacturers in Maharashtra seeking export-qualified elastomer components. Lead with direct digital distribution to bypass incumbent distributor relationships. For Investors and Strategic Acquirers: EU MDR-MDR technical documentation divergence reshapes the acquisition landscape toward vendors maintaining parallel regulatory intelligence capabilities. Five-to-ten year viability favors platform-agnostic material suppliers with validated cross-hardware workflows. Target independent formulation houses with ISO 10993 testing infrastructure. Watch FDA 510(k) review cycle compression as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Certified Feedstock Expansion | BASF SE and Evonik Industries AG secure premium pricing tiers in German automotive supply chains. |
| Platform-Agnostic Material Partnership | Stratasys Ltd. reduces hardware lock-in risk by validating workflows across multiple resin ecosystems. |
| Distributed Print-Cell Network Buildout | Tier-one suppliers position regional capacity near Bavarian assembly plants for forty-eight-hour delivery mandates. |
| CDSCO Registration Pathway Investment | Contract manufacturers in Maharashtra access production-linked incentives for sterilizable component exports. |
| Cloud-Based Parameter Marketplace Launch | Direct digital distribution disintermediates traditional resin distributors for low-volume, high-mix procurement. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA 510(k) material master file databases, ECHA REACH SVHC candidate list updates, and SEC 10-K disclosures from chemical conglomerates. Primary interviews engaged formulation chemists at TPU feedstock suppliers, procurement leads at Bavarian automotive OEMs, regulatory affairs directors at medical device manufacturers, and biomedical engineers at Massachusetts surgical instrument startups. Bottom-up segment sizing triangulates against top-down chemical industry production data.
Forecast inputs include hardware installation base trajectories, regulatory pathway clearance rates, and OEM qualification cycle durations across the projection horizon. Segmentation models incorporate material type, application vertical, technology platform, and end-user archetype dimensions. CAGRs derive from elasticity of substitution between additive and conventional molding processes, weighted by regional automation intensity.
The forecast holds incumbent behavior within observed patterns; aggressive ecosystem exclusivity moves by hardware-locked platform operators would shift outcomes. Macroeconomic contraction in automotive capital expenditure, accelerated REACH SVHC list expansion, or breakthroughs in continuous liquid interface printing would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Materials
Global Metal Additive Manufacturing Market
3D Printing Materials
Global 3D Printing Metals Market
3D Printing Materials
3D Printing Materials and Services Market
3D Printing Materials
Polyamide 12 Powder for High-Performance 3D Printing Market
3D Printing Materials
Low-Temperature Flow Improver Additives for 3D Printing Resins Market
3D Printing Materials
3D Printing Materials Market
3D Printing Materials
3D Printing PLA Market
3D Printing Materials
Metal Jet 3D Printing Technology Market
3D Printing Materials
3D Printed Nanocellulose Market
3D Printing Materials
Global 3D Printing Construction Material Market
3D Printing Materials
Patterning Materials Market
3D Printing Materials
3D Printing Powder Market
3D Printing Materials
Advanced Materials for 3D Printing Market
3D Printing Materials
LAMEA 3D Graphene Market
3D Printing Materials
Global Biocompatible 3D Printing Materials Market
3D Printing Materials
Europe Polypropylene in 3D Printing Market