
 Non-Metal 3D Printing Market | 2026-2036
Non-Metal 3D Printing Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Metal 3D Printing Market Insights
A capital-intensity divergence between desktop polymer printers and industrial multi-laser systems is reorganizing competitive tiers in non-metal additive manufacturing. Stratasys leverages its materials ecosystem and healthcare certifications to sustain premium positioning in medical-grade thermoplastics. Formlabs specializes in desktop stereolithography and competes on accessibility for engineering prototyping in North American and European design studios.
Non-metal 3D printing encompasses additive fabrication of polymers, resins, composites, and ceramics through layer-by-layer deposition or photopolymerization, typically achieving tolerances of 25–100 microns depending on technology and material. Its primary industrial purpose is to produce geometrically complex components without hard tooling, reducing lead times for prototypes, jigs, and end-use parts across aerospace and medical supply chains. Plastic formulations processed through fused deposition modeling occupy the largest volume share, though resin-based stereolithography captures higher margins in dental and audiology applications where surface finish determines clinical acceptance. Selective laser sintering of polyamide powders leads in functional testing and production tooling segments, where part durability under mechanical load justifies per-unit cost premiums over extrusion alternatives.
FDA 510(k) clearance pathways and the EU Medical Device Regulation shape product development cycles for healthcare-facing printers and biocompatible resins, extending time-to-market for new material certifications. ISO 10993 biocompatibility testing and REACH chemical compliance add cost layers that favor established suppliers with dedicated regulatory affairs teams over emerging entrants. Stakeholders must monitor convergence between printer hardware and validated material workflows, as procurement criteria shift from equipment specifications toward guaranteed output consistency under audited quality systems.
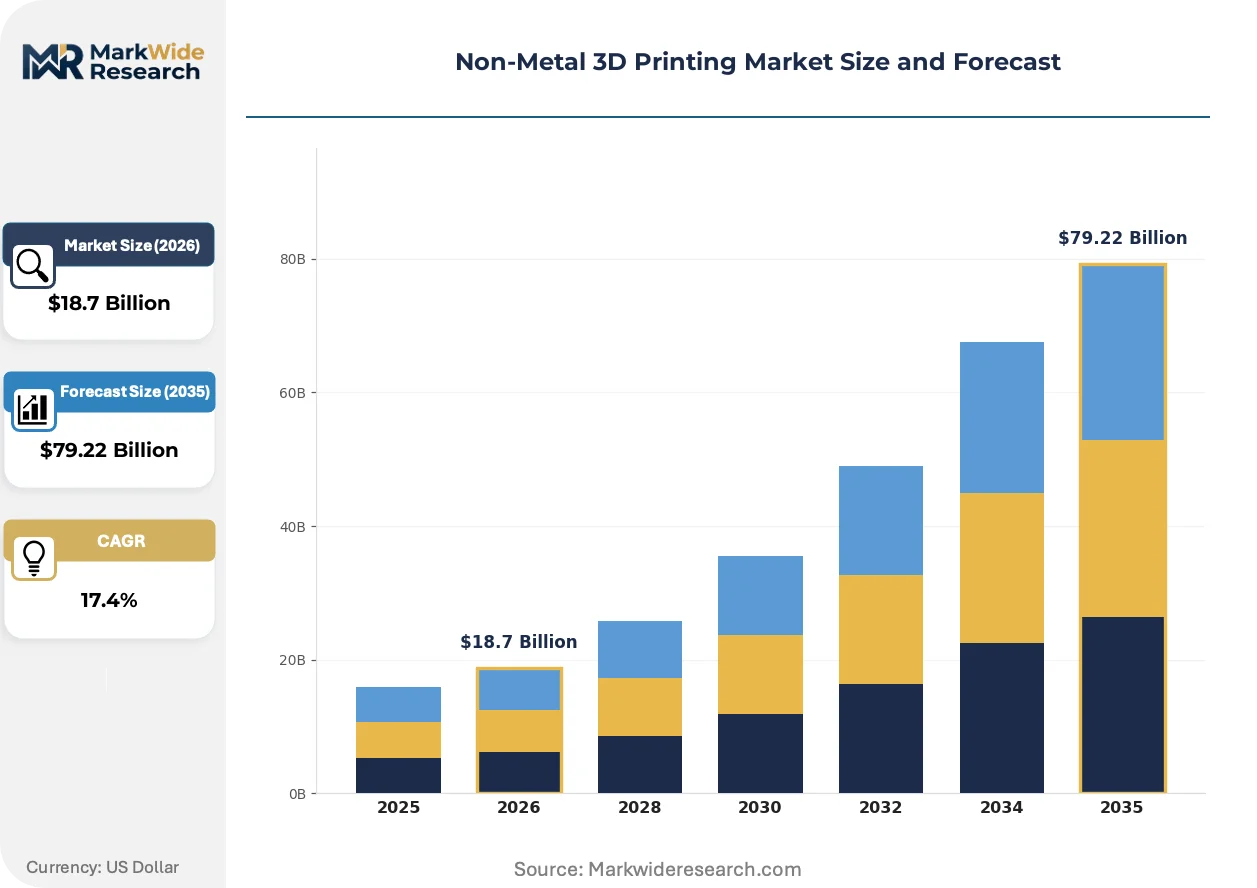
Market Dynamics
The convergence of biocompatible resin chemistry with ISO 10993 certification workflows is restructuring competitive entry barriers, forcing hardware manufacturers to absorb multi-year validation cycles before accessing medical procurement channels.
Growth Catalysts
- EU Medical Device Regulation:Mandatory biocompatibility documentation for polymer implants is consolidating supplier relationships around certified resin portfolios, locking out uncertified competitors from German and French hospital supply chains.
- Patient-specific surgical guides:Orthopedic departments in major hospital systems are converting CT scan data into sterilizable nylon fixtures within 48-hour turnaround windows, eliminating CNC machining bottlenecks for complex reconstructions.
- Polyamide powder bed fusion:Functional testing labs in aerospace supply chains are adopting laser-sintered jigs for composite layup tooling, displacing aluminum fixtures in low-volume production runs.
Market Restraints
- Photopolymer resin cost volatility:Acrylate and epoxy monomer prices fluctuate with petrochemical feedstock indices, compressing margins for dental aligner manufacturers locked into fixed-price contracts with orthodontists.
- Industrial printer supply concentration:Multi-laser powder bed systems rely on precision galvanometer assemblies sourced from a narrow German and Swiss supplier base, creating 12-16 month lead time exposure.
- Post-processing labor intensity:Resin-based parts require solvent washing and UV curing stations that add 30-40% to total production time, limiting throughput scaling for high-volume dental laboratories.
Strategic Opportunities
- India medical device manufacturing:CDSCO's streamlined Class A/B device registration pathway is attracting polymer printer deployments for domestic production of surgical planning models, reducing import dependency.
- Continuous liquid interface production:Oxygen-permeable membrane printing is decomposing layer-resolution tradeoffs, enabling audiology labs to produce transparent ear molds with sub-50 micron clarity in single-digit minute cycles.
- Japan METI carbon-neutral manufacturing incentives:Subsidies for low-waste additive processes are accelerating polyamide recycling system adoption in automotive prototyping centers near Nagoya.
Industry Challenges
- Biocompatibility certification timeline:ISO 10993-5 cytotoxicity through ISO 10993-10 sensitization testing sequences extend material validation to 18-24 months, freezing formulation R&D roadmaps.
- Multi-material workflow integration:Design engineers lack training in topology optimization software that matches anisotropic mechanical properties to load-bearing requirements in printed composite structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Metal 3D Printing Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $79.22 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Resin, Composite, Ceramics Technology: Fused Deposition Modeling, Stereolithography, Selective Laser Sintering, Digital Light Processing End User: Aerospace, Automotive OEMs, Healthcare Providers, Consumer Electronics Application: Prototyping, Functional Testing, Tooling, Production Parts |
| Companies Covered | Stratasys, 3D Systems, HP Development Company, EOS GmbH, Materialise, Formlabs, Carbon, Ultimaker, Prusa Research, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Metal 3D Printing Market Trends and Innovations
Material science advances and regulatory harmonization efforts are compressing the gap between prototyping utility and production-grade reliability in polymer additive manufacturing.
Vat photopolymerization with ceramic-loaded resins is decomposing the traditional mold-and-fire workflow for dental crown production. Japanese dental laboratories are adopting these composite formulations to bypass wax pattern labor, achieving zirconia-like durability with same-day chairside delivery. The structural consequence is a compression of dental lab outsourcing relationships as clinics internalize production.
REACH Annex XVII restrictions on microplastic release are forcing reformulation of water-soluble support materials used in multi-material extrusion. European filament suppliers are pivoting to plant-derived alternatives, with ECHA compliance documentation becoming a mandatory tender requirement for public sector procurement in France and the Netherlands. Medical device manufacturers face the steepest adaptation curve due to revalidation obligations.
Hospital supply managers are consolidating vendor relationships around validated printer-and-resin combinations rather than equipment-only purchases. German university hospitals are leading this transition, bundling hardware leases with guaranteed material throughput commitments and on-site biocompatibility auditing. The shift is most pronounced in craniomaxillofacial surgical planning, where liability exposure demands documented process control.
Non-Metal 3D Printing Market Segmentation
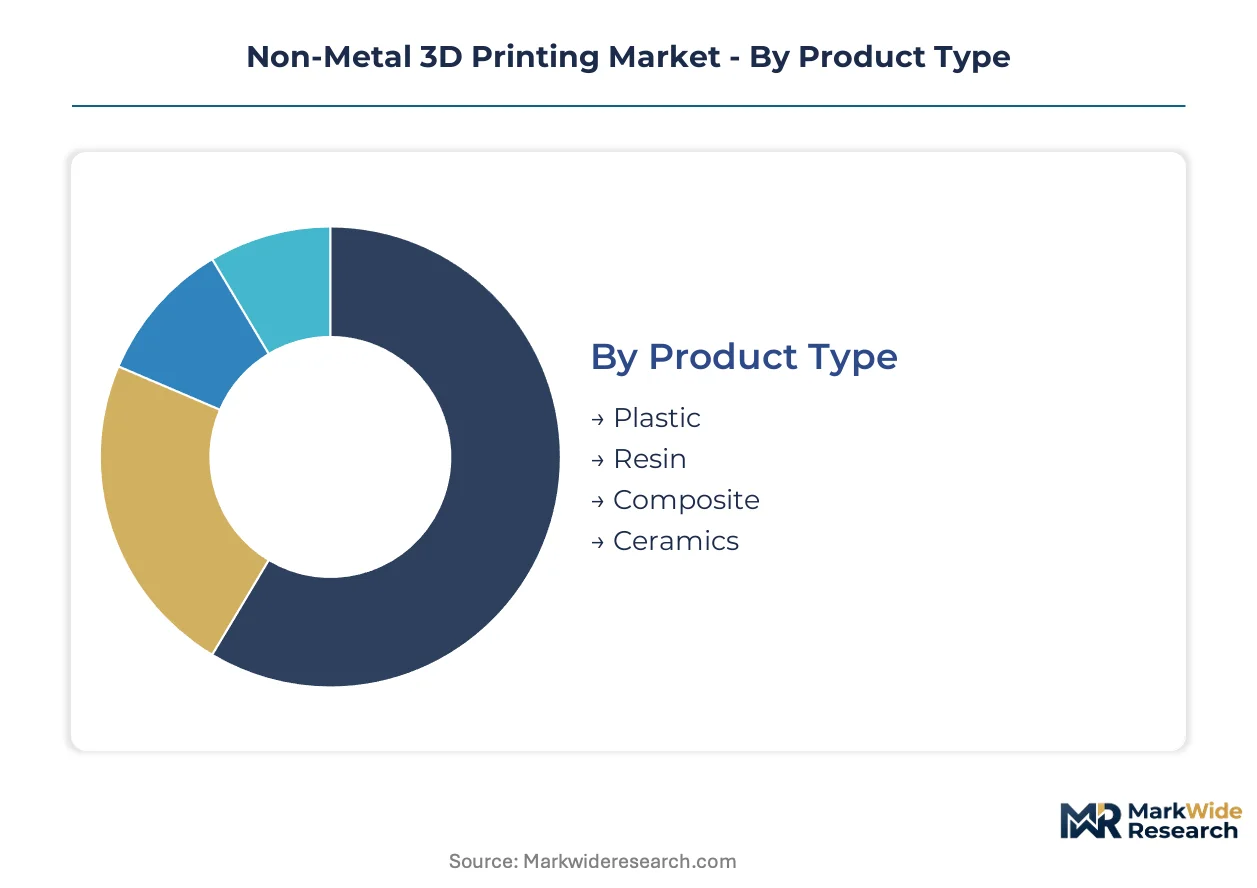
Segmentation in non-metal additive manufacturing reveals divergent margin profiles across material chemistries and deposition technologies. Procurement patterns increasingly favor validated workflow bundles over discrete equipment purchases, compressing standalone hardware margins while elevating recurring material revenue streams.
Product Type:
Substitution pressure from CNC machining and injection molding varies sharply across material categories, with commodity thermoplastics facing the steepest price-based displacement while ceramic-loaded resins defend niche clinical positions.
- Plastic:Fused deposition modeling of ABS and PLA filaments dominates desktop prototyping volumes, though aerospace functional testing labs in Germany and the US are converting to carbon-fiber-reinforced nylon for jigs that withstand autoclave cycles. Medical device manufacturers face FDA 510(k) revalidation costs when switching suppliers, locking in incumbent relationships.
- Resin:Acrylate and epoxy photopolymers command premium pricing in dental aligner production, where surface finish below 25 microns determines clinical acceptance. Orthodontic laboratories in France and Spain are consolidating purchases around ISO 10993-certified resin portfolios to satisfy EU Medical Device Regulation documentation requirements.
- Composite:Continuous fiber-reinforced thermoplastics enable structural automotive brackets that match aluminum stiffness-to-weight ratios. BMW and Porsche prototyping centers near Munich have adopted these materials for crash-test validation parts, bypassing metal tooling lead times.
- Ceramics:Alumina and zirconia-loaded resins bypass traditional mold-and-fire workflows for dental crown production. Japanese dental laboratories leverage these formulations for same-day chairside delivery, compressing outsourcing relationships with centralized production facilities.
Plastic formulations anchor the volume base while ceramics gain share at the steepest rate, driven by chairside dental production adoption in East Asian markets.
Technology:
Cost tier stratification separates desktop systems accessible to design studios from industrial multi-laser platforms requiring dedicated facility infrastructure and climate-controlled powder handling environments.
- Fused Deposition Modeling:Extrusion-based deposition of thermoplastic filament occupies the largest installed base by unit volume. Engineering departments at North American universities deploy these systems for undergraduate prototyping curricula, though tolerance limitations above 100 microns exclude precision medical applications.
- Stereolithography:Laser-scanned vat photopolymerization delivers sub-50 micron resolution for audiology ear molds and dental surgical guides. Formlabs and 3D Systems compete on resin ecosystem breadth, with biocompatible clear formulations capturing premium positioning in transparent orthodontic aligner production.
- Selective Laser Sintering:CO2 laser fusion of polyamide powders leads in functional testing and production tooling segments. EOS GmbH systems in German automotive supply chains produce composite layup jigs that withstand repeated thermal cycling without dimensional drift.
- Digital Light Processing:Projector-based photopolymerization enables batch production of identical parts in single-digit minute cycles. Hearing aid manufacturers in Denmark and the Netherlands deploy DLP cells for high-throughput ear shell manufacturing, amortizing equipment cost across thousands of units monthly.
Fused deposition modeling retains the broadest installed base while digital light processing expands most quickly in high-volume dental and audiology production environments.
End User:
Application maturity diverges across customer types, with healthcare providers advancing fastest toward production-grade adoption while consumer electronics remains constrained by surface finish requirements for visible enclosure components.
- Aerospace:Tier-1 suppliers leverage laser-sintered polyamide for non-flight-critical ducting and bracketry. Airbus procurement specifications now permit additive thermoplastics in cabin interior applications, subject to flame-retardant certification under FAA fireworthiness standards.
- Automotive OEMs:BMW, Ford, and Toyota operate dedicated additive manufacturing centers for prototyping powertrain components. Tooling applications dominate current spend, though end-use production of customized interior trim pieces is emerging in limited-series vehicle programs.
- Healthcare Providers:German university hospitals bundle printer leases with guaranteed resin throughput and on-site biocompatibility auditing. Craniomaxillofacial surgical planning departments convert CT data into sterilizable nylon fixtures within 48-hour windows, eliminating CNC machining bottlenecks.
- Consumer Electronics:Apple and Samsung suppliers prototype enclosure geometries through stereolithography, though visible surface quality requirements prevent transition to production volumes. Internal antenna brackets and heat dissipation components represent nearer-term production opportunities.
Healthcare providers command the steepest technology upgrade trajectory while aerospace maintains the most stringent qualification protocols.
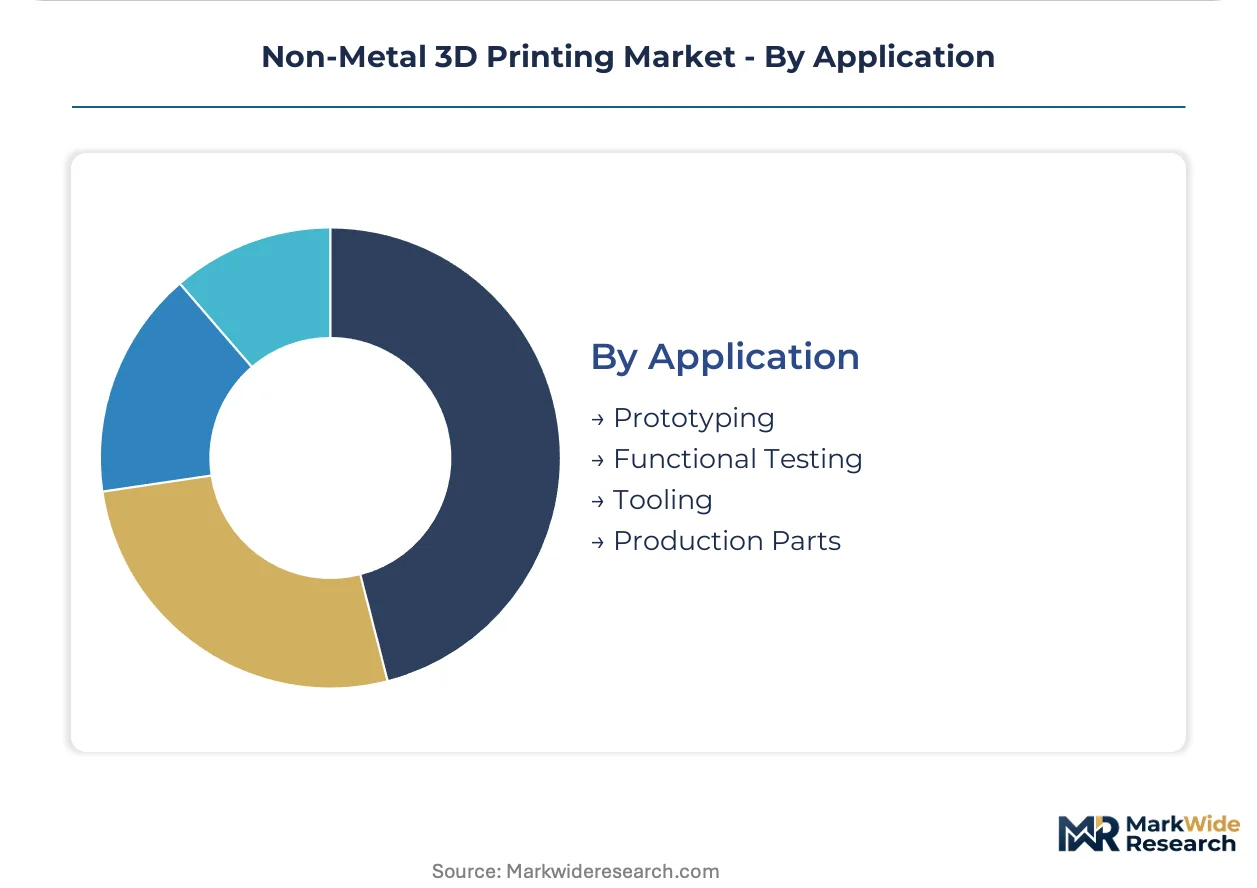
Application:
Volume scale and margin structure invert across the application spectrum, with prototyping delivering equipment sales margins and production parts generating recurring material revenue at substantially higher lifetime value per installed system.
- Prototyping:Design validation remains the entry-point application for polymer additive adoption. Engineering consultancies in London and Milan operate service bureaus offering 24-hour turnaround on stereolithography parts, competing on geometric complexity rather than unit cost.
- Functional Testing:Laser-sintered polyamide jigs substitute for aluminum fixtures in composite layup and assembly verification. Boeing and Airbus suppliers validate these parts under mechanical load and thermal cycling before committing to hard tooling investments.
- Tooling:Conformal cooling channels in printed injection mold inserts reduce cycle times for automotive bumper production. Mold makers in Stuttgart and Wolfsburg have adopted copper-alloy-loaded polymer composites for their thermal conductivity advantages.
- Production Parts:FDA-cleared resins enable patient-specific dental aligners and hearing aid shells at million-unit annual scales. Align Technology and Sonova manufacture exclusively through additive processes, having vertically integrated printer fleets and resin formulation capabilities.
Prototyping sustains the largest addressable equipment base while production parts deliver the steepest margin expansion trajectory as healthcare applications scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity for polymer printers diverges sharply across end-use segments. Dental laboratories absorb premium resin costs without volume contraction, while consumer prototyping buyers compress hardware margins through price comparison platforms. German hospital systems bundle equipment with multi-year resin commitments, insulating suppliers from spot-market volatility.
United States
Orthodontic aligner manufacturers drive resin consumption at million-unit scales. FDA 510(k) clearance pathways extend material validation timelines, favoring incumbent suppliers with dedicated regulatory affairs teams. Boston-area audiology labs deploy stereolithography cells for high-throughput ear shell production.
Germany
Automotive prototyping centers near Munich adopt laser-sintered polyamide jigs for composite layup tooling. EU Medical Device Regulation mandates biocompatibility documentation for polymer implants, consolidating supplier relationships around certified resin portfolios. EOS GmbH anchors an industrial polymer printing cluster in Krailling.
Japan
Dental laboratories leverage ceramic-loaded resins for same-day chairside crown delivery. METI carbon-neutral manufacturing subsidies accelerate polyamide recycling system adoption in automotive prototyping centers near Nagoya. Tokyo-based hearing aid manufacturers vertically integrate printer fleets for transparent ear mold production.
India
Domestic surgical planning model production expands as CDSCO streamlines Class A/B device registration. Hospital systems in Maharashtra and Karnataka reduce import dependency through localized polymer printer deployments. Mumbai medical device manufacturers target ASEAN export markets with sterilizable nylon fixtures.
France
Orthodontic laboratories consolidate purchases around ISO 10993-certified resin portfolios to satisfy EU Medical Device Regulation documentation requirements. ECHA compliance documentation for plant-derived support materials becomes mandatory for public sector procurement. Lyon-area craniomaxillofacial departments convert CT data into sterilizable fixtures within 48-hour windows.
Non-Metal 3D Printing Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes in non-metal additive manufacturing. The market structure stratifies into three tiers: industrial multi-laser system suppliers commanding premium positioning, desktop specialists competing on accessibility, and materials-integrated platforms capturing recurring revenue through validated workflows. Dominant competitive moves include strategic partnerships bundling hardware with certified resin portfolios, and geographic expansion targeting hospital procurement consolidation in German and French supply chains.
Among Germany-based fabricators, EOS GmbH and Materialise occupy positions within the industrial system tier, anchoring polymer powder bed fusion clusters that serve automotive and medical supply chains. Formlabs exemplifies the desktop accessibility archetype, competing on resin ecosystem breadth for engineering prototyping in North American and European design studios. Stratasys represents the materials-integrated platform model, sustaining premium positioning through healthcare certifications and biocompatible thermoplastic portfolios.
| Leading Market Players |
|---|
| Stratasys |
| 3D Systems |
| HP Development Company |
| EOS GmbH |
| Materialise |
| Formlabs |
| Carbon |
| Ultimaker |
| Prusa Research |
| Others |
Pricing and Supply Chain Analysis
Long-term resin throughput commitments lock in supply access and price visibility for German hospital systems bundling hardware leases with multi-year material contracts. This contract structure insulates EOS GmbH and Stratasys from acrylate monomer spot volatility while freezing out competitors lacking validated ISO 10993-certified portfolios.
Pricing Analysis
After-sales material revenue drives lifetime value in non-metal additive manufacturing, with recurring resin and powder sales delivering margins that hardware transactions cannot match. Three-tier pricing structure across medical-grade certified, engineering-grade, and desktop economy levels separates Stratasys healthcare premiums from Formlabs accessibility positioning. Cost compression in dental aligner production intensifies as orthodontists demand fixed-price contracts despite petrochemical feedstock volatility. Consumer prototyping buyers exhibit highest price sensitivity through comparison platforms, while hospital supply managers absorb premiums for documented biocompatibility.
Supply Chain Analysis
Just-in-time powder handling dominates industrial selective laser sintering operations, though strategic stockpiling of photopolymer resins persists among high-volume dental laboratories managing FDA 510(k) revalidation risks. Precision galvanometer assemblies concentrate in German and Swiss supplier bases, while acrylate monomer production draws from Belgian and Dutch petrochemical complexes. Single-source vulnerability in multi-laser system optics creates exposure for automotive prototyping centers. Distribution runs through authorized reseller networks bundling hardware with certified material workflows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Non-metal 3D printing sits at a regulatory inflection where EU Medical Device Regulation biocompatibility mandates are consolidating procurement around validated supplier ecosystems. This technological-regulatory convergence favors incumbents with dedicated compliance infrastructure over hardware-only competitors.
For Market Incumbents: Consolidate certified resin portfolios through exclusive distribution agreements with hospital systems in Germany and France. Lock in multi-year throughput commitments that embed on-site biocompatibility auditing. Defend against desktop specialists by restricting material ecosystem access to leased hardware fleets.
For New Entrants and Emerging Players: CDSCO's streamlined Class A/B device registration pathway offers fastest certification fast-track for surgical planning model production in Maharashtra and Karnataka. Target domestic Indian hospital systems reducing import dependency. Pursue white-label resin formulation partnerships with established hardware OEMs lacking biocompatification capabilities.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors materials-integrated platforms over hardware-only vendors. Long-term viability hinges on captive resin formulation capabilities and regulatory affairs scale. Watch for ISO 10993-5 cytotoxicity testing backlog duration as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Biocompatibility Certification Fast-Track | CDSCO's streamlined pathway accelerates hospital procurement access in domestic Indian markets. |
| Resin Ecosystem Exclusive Partnership | Stratasys leverages healthcare certifications to lock out competitors from German university hospital supply chains. |
| Multi-Laser Capacity Expansion | EOS GmbH anchors industrial polymer printing clusters serving automotive composite layup tooling demand. |
| Continuous Liquid Interface Production Deployment | Carbon's oxygen-permeable membrane technology enables sub-50 micron audiology mold clarity. |
| Polyamide Recycling System Integration | Japan METI subsidies accelerate closed-loop powder handling in Nagoya automotive prototyping centers. |
Research Methodology
Cross-validation between primary interviews with hospital procurement managers, biomedical engineers, and dental laboratory directors anchors the qualitative findings against secondary validation. Regulatory affairs leads at resin formulation suppliers and GPO contracts managers at German university hospital systems provided operational perspective. Secondary sources include FDA 510(k) filings, ECHA REACH Annex XVII documentation, CDSCO device registration databases, and customs records of polymer printer imports. Bottom-up installed base estimates triangulate against top-down healthcare procurement spend allocations.
Sensitivity analysis around resin price volatility and certification timeline assumptions shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include material chemistry, deposition technology, end-use industry, application maturity, and regional regulatory cluster. CAGRs derive from elasticity-adjusted adoption curves incorporating ISO 10993 validation lag effects. Industry-specific inputs capture orthodontic aligner production scaling and automotive prototyping center deployment rates.
Underlying assumptions cover EU Medical Device Regulation enforcement continuity and petrochemical feedstock price bands, with deviation risk concentrated in CDSCO regulatory pathway delays and REACH microplastic restriction scope expansion. Revision becomes warranted when ISO 10993-5 testing backlog duration crosses 24-month thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Materials
3D Printing Iron Powder Market
3D Printing Materials
Global 3D Printing Metals Market
3D Printing Materials
3D Printed Nanocellulose Market
3D Printing Materials
Global Biocompatible 3D Printing Materials Market
3D Printing Materials
Industrial 3D Printing Plastic Market
3D Printing Materials
3D Printing Plastics Market
3D Printing Materials
Global Metal Additive Manufacturing Market
3D Printing Materials
3D Printing PLA Market
3D Printing Materials
3D Printing Photopolymers Market
3D Printing Materials
Low-Temperature Flow Improver Additives for 3D Printing Resins Market
3D Printing Materials
3D Printing High Performance Plastic Market
3D Printing Materials
Global 3D Printing Construction Material Market
3D Printing Materials
3D Printing Powder Market
3D Printing Materials
3D Printing Resin Market
3D Printing Materials
Global 3D Printing Filament Market
3D Printing Materials
3D Printing Polymers Market