
 Global Cold Plate Market | 2026-2036
Global Cold Plate Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cold Plate Market Analysis
Hyperscale data center operators are bifurcating from enterprise IT buyers as the dominant demand archetype for high-performance cold plates. Boyd Corporation leverages its captive supply of aluminum micro-channel extrusions to serve direct-to-chip liquid cooling programs. Wakefield-Vette anchors North American production with vertically integrated stamping and brazing capabilities for defense and aerospace thermal management. Wieland Thermal Solutions competes through specialized copper cold plate geometries optimized for laser diode arrays and power electronics.
A cold plate is a heat exchanger that mounts directly to a heat-generating component, circulating a coolant through internal channels—typically machined, drilled, or vacuum-brazed with channel widths below 2 mm—to maintain junction temperatures within specified limits. Liquid cold plates dominate commercial volumes due to superior heat flux handling above 500 W/cm², while vapor cold plates gain traction in spacecraft and satellite thermal control where fluid management constraints apply. Aluminum material configurations lead on cost efficiency for mass-market electronics, though copper and composite material variants command premium positioning in medical devices and semiconductor test equipment where thermal uniformity dictates performance.
The EPA SNAP program in the United States restricts high-GWP refrigerants in cooling systems, pushing OEMs toward water-glycol and dielectric fluid cold plate designs that bypass F-gas compliance burdens. Ecodesign requirements under the EU Green Deal mandate minimum energy efficiency thresholds for data center cooling infrastructure, directly elevating specifications for active cooling and thermoelectric cooling subsystems integrated with cold plate distribution networks. Stakeholders must monitor how China's GB standards for data center power usage effectiveness evolve alongside MIIT dual carbon enforcement timelines, as these will determine qualification thresholds for cold plate suppliers serving domestic hyperscale projects.
Market Dynamics
Hyperscale data center operators are forcing a supply-side recalibration as rack densities breach 100 kW per cabinet, rendering legacy air-cooled architectures thermally obsolete and mandating liquid cold plate retrofit at scale.
Growth Catalysts
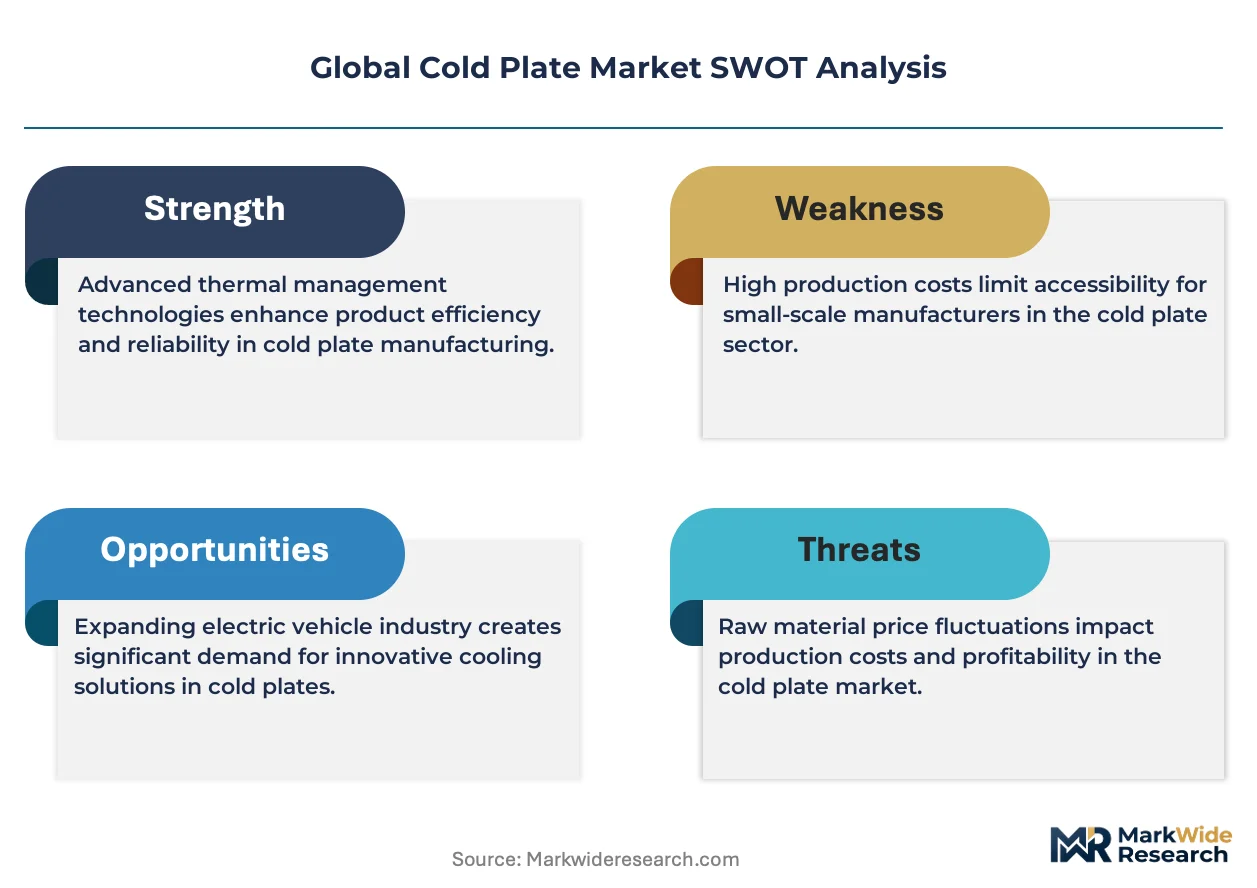
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon refrigerants is accelerating migration toward water-glycol and dielectric fluid cold plate systems that eliminate compliance exposure for European OEMs.
- Semiconductor fabrication:Advanced lithography and etching equipment generate localized heat flux exceeding 300 W/cm², requiring precision cold plate integration for process control.
- China's hyperscale buildouts:Domestic cloud infrastructure expansion and MIIT dual carbon enforcement timelines are concentrating procurement volumes for high-performance liquid cooling solutions.
Market Restraints
- Copper price volatility:Raw material cost swings for thermal-grade copper directly compress margin structures for precision-machined cold plate manufacturers serving medical device and laser diode markets.
- Aluminum extrusion concentration:Micro-channel supply chains cluster in specific East Asian manufacturing corridors, creating single-source vulnerability for high-volume electronics cooling programs.
- Dielectric fluid compatibility:Material degradation risks with certain fluorinated working fluids limit cold plate alloy selection and channel surface treatment options.
Strategic Opportunities
- India data center PUE mandates:CEA efficiency regulations and rising ambient temperatures are opening deployment windows for liquid cooling in Mumbai and Bangalore hyperscale facilities.
- Edge computing nodes:Distributed AI inference infrastructure requires compact thermal management solutions where traditional chiller-based systems prove economically unviable.
- Japan METI carbon neutrality roadmap:Public-private partnerships for green data center certification are incentivizing domestic adoption of advanced liquid cooling technologies.
Industry Challenges
- Micro-channel machining expertise:Tight tolerance drilling and vacuum brazing of sub-2 mm geometries require specialized workforce capabilities concentrated among legacy aerospace suppliers.
- Legacy air-cooled retrofit integration:Facility infrastructure incompatibility with liquid cooling manifolds creates deployment friction and extended commissioning timelines for brownfield data centers.
- Multi-jurisdictional certification:Divergent pressure vessel standards across EPA SNAP, EU PED, and China GB frameworks extend product qualification cycles for global cold plate vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cold Plate Market |
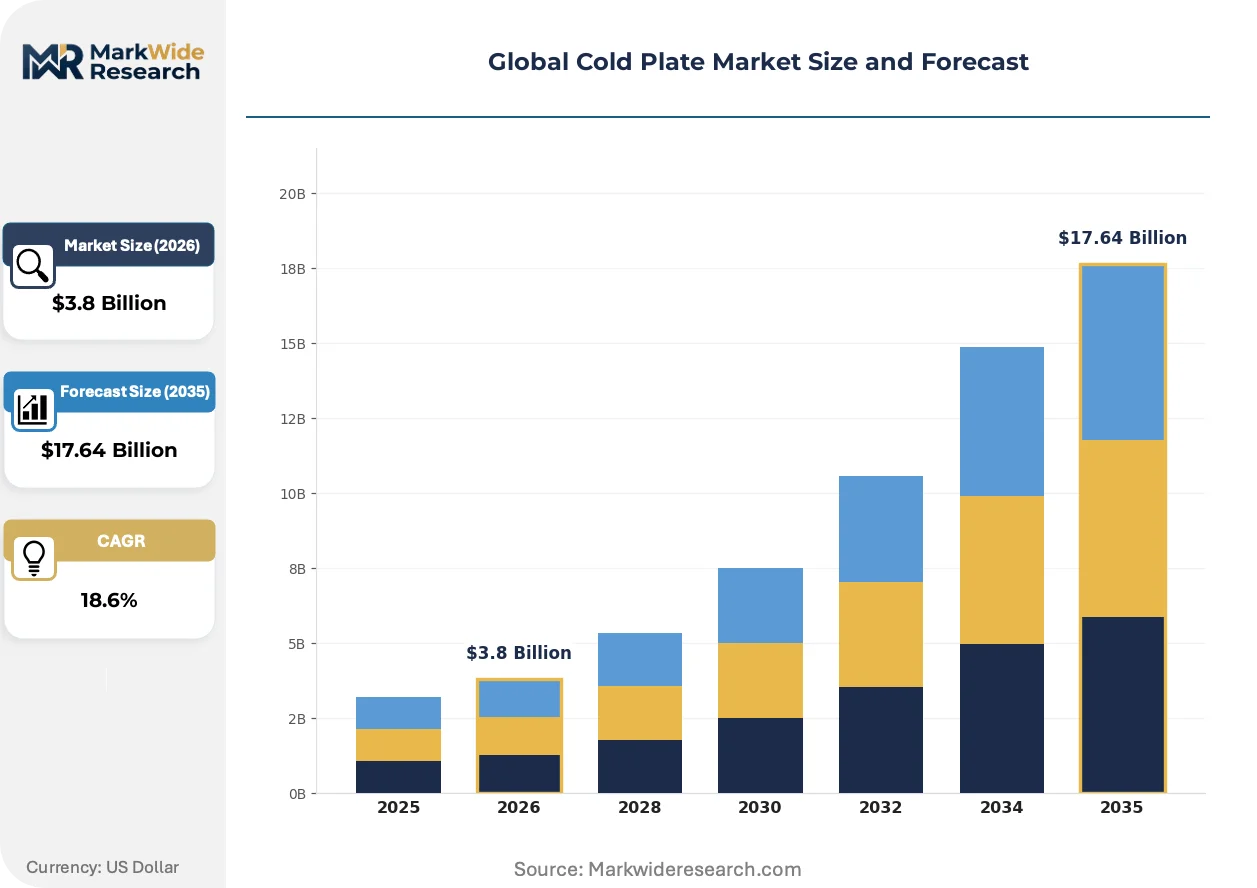
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Cold Plates, Vapor Cold Plates, Air Cold Plates, Phase Change Cold Plates Application: Computer Cooling, LED Heat Management, Laser Equipment, Medical Devices Material: Aluminum, Copper, Brass, Composite Materials Cooling Technology: Passive Cooling, Active Cooling, Thermoelectric Cooling, Heat Pipe Technology |
| Companies Covered | Wakefield-Vette, Advanced Cooling Technologies, Boyd Corporation, Wieland Thermal Solutions, Delta T Corporation, Lytron, Laird Thermal Systems, Parker Hannifin Corp., Aavid Thermalloy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cold Plate Market Emerging Trajectories
Additive manufacturing of conformal cooling channels is collapsing lead times for complex geometries while enabling topology-optimized heat transfer surfaces previously unreachable through conventional machining.
Micro-channel cold plate fabrication is miniaturizing. Internal channel widths now routinely descend below 1 mm in production deployments, enabling direct-to-chip liquid cooling for GPU clusters. Hyperscale operators in Singapore and the Netherlands are specifying these geometries for next-generation AI training infrastructure. The technology is compressing thermal resistance targets and forcing capital equipment upgrades across the supplier base.
EPA SNAP restrictions on high-GWP refrigerants are reshaping cold plate working fluid selection. The regulatory framework disqualifies common synthetic refrigerants from new cooling system deployments, pushing OEMs toward water-based and engineered dielectric alternatives. Data center operators in California and Virginia are front-running compliance by specifying F-gas-exempt architectures in current procurement cycles.
Specification authority is migrating from facilities engineering to chip procurement teams. Thermal design power thresholds for accelerators now dictate cooling architecture selection before data center construction begins. This pattern is most pronounced in Taiwan and South Korea, where semiconductor foundries and cloud operators maintain integrated supply relationships.
Global Cold Plate Market Segmentation
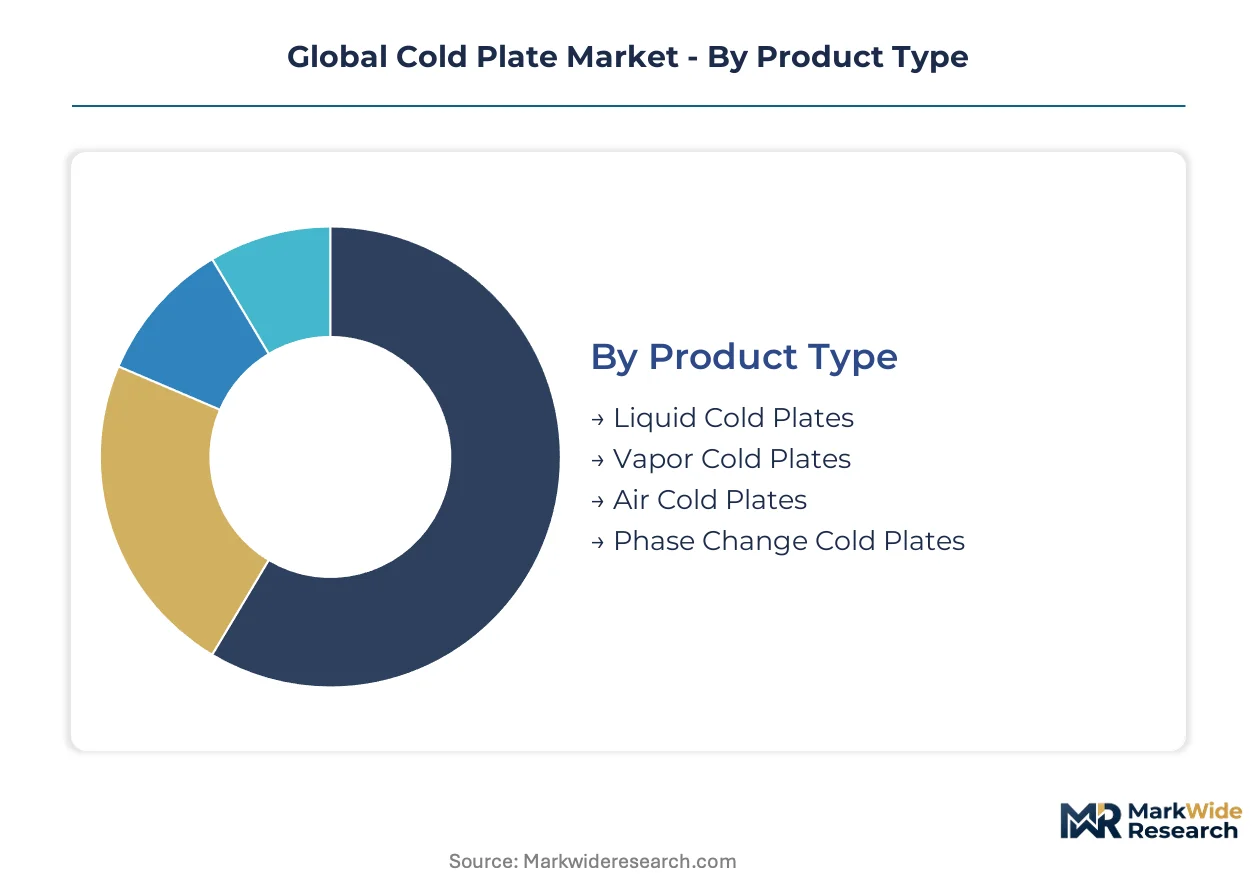
Cold plate procurement decisions cascade through multiple technical dimensions. Product architecture determines thermal performance ceilings. Material selection governs cost structures and regulatory compliance pathways. Application context dictates channel geometry and coolant compatibility requirements.
Product Type:
Liquid cold plates command the widest margin pools due to their dominance in hyperscale data center deployments and premium positioning in semiconductor fabrication equipment.
- Liquid Cold Plates:Internal channel networks circulate water-glycol or dielectric fluids through machined or vacuum-brazed geometries, handling heat flux above 500 W/cm². Procurement concentrates in China for domestic cloud infrastructure buildouts and MIIT dual carbon compliance timelines.
- Vapor Cold Plates:Two-phase working fluid circulation enables isothermal heat spreading across extended surface areas. Demand clusters in spacecraft thermal control and satellite payloads where fluid management constraints eliminate pumped liquid architectures.
- Air Cold Plates:Extended fin arrays conduct heat to forced convection airstreams, retaining viability in legacy enterprise IT refresh cycles and cost-constrained edge computing nodes.
- Phase Change Cold Plates:Solid-liquid phase transition materials absorb transient thermal loads in pulsed power electronics and medical imaging equipment.
Liquid cold plates hold installed capacity. Vapor cold plates are rotating up the share rankings.
Application:
Application segmentation tracks how thermal design power thresholds migrate specification authority from facilities engineering to component procurement teams.
- Computer Cooling:Direct-to-chip liquid cooling for GPU clusters and AI training infrastructure now dictates data center construction sequencing. Hyperscale operators in Singapore and the Netherlands specify micro-channel geometries below 1 mm for next-generation deployments.
- LED Heat Management:Street lighting and horticultural arrays require aluminum cold plates with anodized surfaces for corrosion resistance in outdoor environments. Municipal procurement in India and Brazil drives volume.
- Laser Equipment:Copper cold plates with precision-machined micro-channels maintain diode bar junction temperatures within tight tolerances for industrial cutting and medical systems.
- Medical Devices:MRI gradient coils and surgical laser systems demand copper or composite cold plates with thermal uniformity specifications exceeding commercial electronics standards.
Computer cooling captures the steepest expansion trajectory. Medical devices maintain the highest average selling prices.
Material:
Material selection bifurcates between cost-optimized aluminum extrusions and performance-critical copper alloys.
- Aluminum:Micro-channel extrusions dominate mass-market electronics cooling through Boyd Corporation's captive supply and East Asian manufacturing corridors. EPA SNAP refrigerant restrictions accelerate water-glycol system adoption compatible with aluminum metallurgy.
- Copper:Thermal-grade copper commands premium positioning in laser diode arrays and semiconductor test equipment where thermal uniformity dictates performance. Price volatility compresses margin structures for precision-machined manufacturers.
- Brass:Naval brass variants serve marine and coastal installations requiring corrosion resistance without copper's cost position.
- Composite Materials:Aluminum-graphite and copper-molybdenum composites address coefficient of thermal expansion matching in power electronics and aerospace applications.
Aluminum retains volume leadership. Copper is climbing the fastest in revenue contribution.
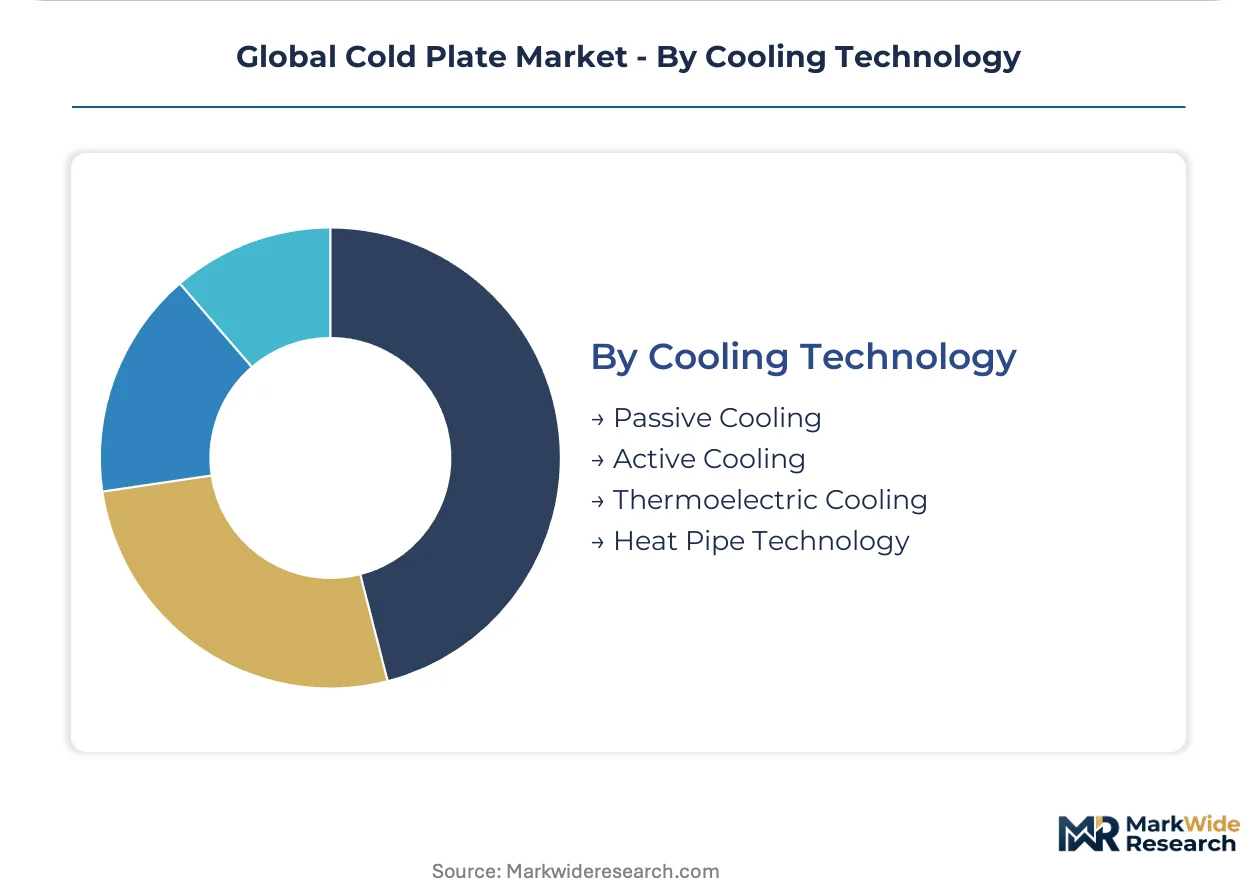
Cooling Technology:
Technology segmentation reflects the shift from passive conduction to active, precision-controlled thermal management.
- Passive Cooling:Conduction-dominated heat spreading without powered components serves cost-sensitive consumer electronics and legacy industrial equipment.
- Active Cooling:Pumped liquid loops with variable flow control enable dynamic thermal response for data center workloads with fluctuating power draw.
- Thermoelectric Cooling:Peltier modules integrated with cold plate distribution networks provide sub-ambient cooling for medical diagnostics and scientific instrumentation.
- Heat Pipe Technology:Two-phase heat transport extends thermal management reach in space-constrained electronics enclosures and remote heat sink configurations.
Active cooling holds installed capacity. Thermoelectric cooling is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta's dense fiber optic and power grid infrastructure underwrites China's dominance in hyperscale data center construction and cold plate procurement volumes.
China
Domestic cloud infrastructure buildouts and semiconductor fabrication investments drive acute demand concentration. MIIT dual carbon enforcement timelines and evolving GB standards for data center power usage effectiveness determine supplier qualification thresholds. Procurement clusters in Shanghai and surrounding Jiangsu province where hyperscale operators specify micro-channel geometries below 1 mm.
United States
Hyperscale facilities in Virginia and California front-run EPA SNAP compliance by specifying F-gas-exempt liquid cooling architectures. Data center construction in Ashburn and Santa Clara prioritizes direct-to-chip cold plate integration for AI training clusters. State-level efficiency mandates in California accelerate retrofit programs for legacy air-cooled infrastructure.
Germany
Industrial laser equipment and automotive power electronics sustain precision cold plate demand. EU F-Gas Regulation and Ecodesign requirements under the EU Green Deal elevate specifications for water-glycol systems. Manufacturing concentrates in Baden-Württemberg where suppliers serve medical device and laser diode array producers with thermal uniformity requirements.
Japan
METI carbon neutrality roadmaps and public-private partnerships for green data center certification incentivize domestic liquid cooling adoption. Semiconductor foundries and precision equipment manufacturers in the Tokyo-Osaka corridor specify copper cold plate geometries for process control applications. Spacecraft thermal control programs drive vapor cold plate procurement for satellite payloads.
Singapore
Tropical ambient temperatures and limited land availability force aggressive cooling efficiency mandates for data center operators. Government sustainability requirements and rising rack densities above 100 kW per cabinet specify micro-channel liquid cold plates for new hyperscale deployments. Procurement concentrates in the Tuas data center cluster where operators integrate direct-to-chip cooling for GPU infrastructure.
Global Cold Plate Market Vendor Landscape
Listed leaders compete with private specialists across capital intensity and technical capability dimensions. The vendor base organizes around three tiers: multinational conglomerates with captive thermal divisions, mid-cap fabricators with captive aluminum extrusion supply, and specialized precision-machining houses serving aerospace and medical niches. Dominant competitive moves include backward integration into micro-channel extrusion capacity and strategic partnerships with semiconductor foundries for co-developed thermal solutions.
Among North American fabricators, Wakefield-Vette anchors defense and aerospace thermal management with vertically integrated stamping and brazing capabilities. Boyd Corporation exemplifies the captive supply model through in-house production of aluminum micro-channel extrusions for direct-to-chip programs. Wieland Thermal Solutions occupies a position in specialized copper geometries for laser diode arrays and power electronics where thermal uniformity commands premium positioning.
| Leading Market Players |
|---|
| Wakefield-Vette |
| Advanced Cooling Technologies |
| Boyd Corporation |
| Wieland Thermal Solutions |
| Delta T Corporation |
| Lytron |
| Laird Thermal Systems |
| Parker Hannifin Corp. |
| Aavid Thermalloy |
| Others |
Supply Flow & Price Mechanics
EU F-Gas Regulation phaseout timelines gate supplier qualification and simultaneously stratify price tiers between compliant water-glycol architectures and legacy refrigerant-dependent systems. Hyperscale data center operators in Virginia and Singapore now mandate F-gas-exempt cold plate specifications, compressing margins for non-compliant fabricators while rewarding certified suppliers with premium positioning.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement contracts. Premium tiers attach to copper micro-channel geometries for semiconductor test equipment and medical imaging systems where thermal uniformity specifications exceed commercial standards. Standard tiers capture aluminum extrusion volumes for mass-market electronics cooling. Economy tiers serve legacy air-cooled retrofit programs with extended lead times and reduced after-sales support. Price differentiation hinges on certification grade—UL-listed and CE-marked products command 15-25% premiums over uncertified alternatives—and volume scale, with hyperscale operators extracting steep discounts for multi-year offtake agreements. Cost compression in aluminum micro-channel tiers is intensifying because East Asian manufacturing corridors face energy cost inflation and carbon border adjustment exposure. Medical device OEMs exhibit lowest price sensitivity due to thermal performance requirements, while edge computing node deployers prioritize unit economics above specification compliance.
Supply Chain Analysis
Strait of Malacca transit underwrites raw material flows for thermal-grade copper and aluminum billet shipments serving East Asian extrusion corridors. Manufacturing gravity centers on China, South Korea, and Taiwan for micro-channel fabrication, with Germany and the United States retaining specialized capacity for aerospace and medical precision machining. Raw material dependencies draw from Chilean copper concentrate, Australian bauxite, and Taiwanese semiconductor-grade aluminum alloys. Single-source vulnerability concentrates in vacuum brazing equipment supply, where German and Japanese OEMs control 80% of installed capacity for sub-2 mm channel geometries. Distribution runs through direct OEM relationships for hyperscale data center programs, with distributor networks serving fragmented industrial and medical equipment markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Direct-to-chip liquid cooling substitution threatens incumbent air-cooled suppliers as rack densities breach thermal limits. Incumbents must navigate this technology transition while defending installed base relationships.
For Market Incumbents: Secure captive aluminum micro-channel extrusion capacity before East Asian supply corridors face carbon border adjustment constraints. Lock multi-year offtake agreements with hyperscale operators in Singapore and the Netherlands to defend share against emerging competitors. Accelerate EPA SNAP and EU F-Gas certification portfolios to disqualify non-compliant rivals from procurement shortlists.
For New Entrants and Emerging Players: UL certification fast-track for water-glycol cold plate architectures opens procurement access to North American hyperscale facilities. Target India's data center PUE mandate compliance window, where CEA regulations and tropical ambient temperatures create deployment urgency without entrenched incumbent relationships. Lead with compact edge computing thermal solutions where traditional chiller-based systems prove economically unviable.
For Investors and Strategic Acquirers: METI carbon neutrality roadmap milestones reshape the acquisition landscape by concentrating Japanese demand around certified green data center suppliers. Prioritize mid-cap fabricators with backward integration into aluminum extrusion and established semiconductor foundry relationships. Watch China's evolving GB standards for data center power usage effectiveness as the signal for qualification threshold tightening that will consolidate supplier tiers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Micro-Channel Extrusion | Boyd Corporation's captive supply model demonstrates margin defense against aluminum price volatility. |
| EPA SNAP Compliance Certification | F-gas-exempt architecture qualification unlocks procurement access to California and Virginia hyperscale clusters. |
| Semiconductor Foundry Partnership | Co-developed thermal solutions with TSMC or Samsung Foundry embed cold plates in next-generation packaging roadmaps. |
| India Market Entry | CEA efficiency regulations and Mumbai hyperscale buildouts create first-mover advantages for liquid cooling specialists. |
| Additive Manufacturing Capability | Topology-optimized conformal channels collapse lead times for complex geometries in aerospace and medical niches. |
Methodological Framework
A standing panel of data center facilities engineers, thermal management procurement leads at hyperscale operators, semiconductor fabrication equipment specialists, and cold plate manufacturing operations directors provided ongoing calibration throughout the study period. Primary interviews combined with secondary validation from EPA SNAP regulatory filings, EU Ecodesign directive documentation, China MIIT policy releases, and hyperscaler capital expenditure disclosures. Trade data from customs authorities in Germany, Japan, and the United States anchored supply chain mapping. Bottom-up and top-down triangulation cross-validated segment-level estimates against aggregate market outputs.
Consistency checks against external benchmarks verified projection outputs across the modeling period. The analytical framework modeled cold plate demand through product type, application context, material configuration, cooling technology, and regional regulatory cluster dimensions. CAGRs derived from segment-level growth trajectory analysis incorporating technology substitution curves and policy enforcement timelines. Forecast inputs included rack density evolution at hyperscale facilities, F-gas phaseout compliance deadlines, and semiconductor fabrication equipment capital expenditure patterns.
The analysis sits within stated boundaries; outcomes outside sustained hyperscale data center construction momentum or accelerated F-gas regulatory enforcement would require recalibration. Forecasts reflect documented assumptions regarding technology adoption curves and policy implementation schedules. Practitioners should keep alternative scenarios live as China's GB standards for data center power usage effectiveness and EU carbon border adjustment mechanisms evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
COG Bonder Market
Industrial Equipment
Laser Marking Machine Market
Industrial Equipment
Global High Speed Dispenser Market
Industrial Equipment
Dust Extraction System Market
Industrial Equipment
Photography Panoramic Tripod Heads Market
Industrial Equipment
TIG Torch Market
Industrial Equipment
Global Abrasive Waterjet Cutting Machine Market
Industrial Equipment
Global Linear Bearings Market
Industrial Equipment
Europe Industrial Centrifuge Market
Industrial Equipment
Spot Curing System Market
Industrial Equipment
Global Electro Hydraulic Servo Valve Market
Industrial Equipment
Laser Drilling Market
Industrial Equipment
Global Fans and Blowers Market
Industrial Equipment
North America Rental Chillers Market
Industrial Equipment
Chemical Storage Tank and Bottle for Semiconductor Market
Industrial Equipment
Global Special Purpose Machines Market