
 Asia-Pacific Dermal Fillers Market | 2026-2036
Asia-Pacific Dermal Fillers Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Dermal Fillers Market Analysis
Multi-syringe treatment kits is consolidating as the dominant packaging configuration across premium dermatology channels. Allergan (AbbVie) leverages its Juvederm portfolio breadth to anchor bundled protocol sales in Australian and Japanese clinics. Galderma sustains R&D intensity in hyaluronic acid cross-linking technology, competing directly with Teoxane Laboratories for facial contouring market share in Singapore and Hong Kong.
Dermal fillers comprise injectable biocompatible substances, primarily hyaluronic acid gels with particle sizes ranging from 200 to 1000 microns, manufactured through bacterial fermentation or chemical cross-linking processes to restore facial volume and correct wrinkles. Hyaluronic acid formulations occupy the largest revenue share due to reversibility with hyaluronidase and established safety profiles, while poly-L-lactic acid biostimulators represent the fastest-growing category as clinics shift toward collagen-inducing protocols for longer patient return intervals. Volume Restoration applications command premium pricing in dermatology clinics, whereas Wrinkle Reduction segments face margin compression from commoditized entry-level products distributed through medical wholesalers.
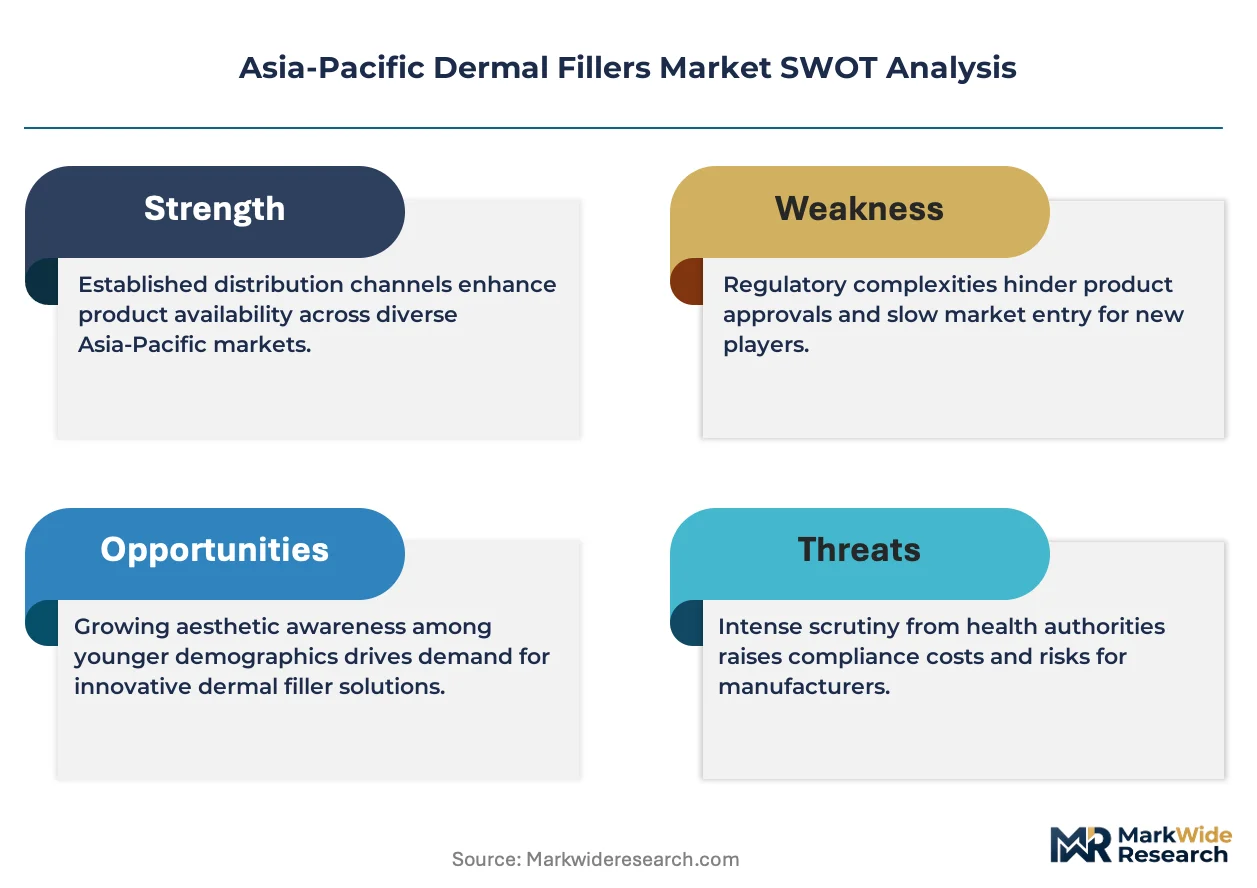
Australia's TGA and South Korea's MFDS enforce divergent biocompatibility testing standards, creating compliance fragmentation that favors manufacturers with localized regulatory affairs teams. China's NMPA requires domestic clinical trials for novel filler approvals, extending market access timelines for European and US headquartered firms. India's CDSCO has begun aligning with ISO 13485 quality management benchmarks, signaling tighter oversight for imported aesthetic devices. Stakeholders must prioritize regulatory pathway mapping before committing manufacturing partnerships or distribution agreements across jurisdictions with non-harmonized approval frameworks.
Market Dynamics
China's NMPA domestic clinical trial mandate is fragmenting market entry timelines, forcing European and US manufacturers to establish localized regulatory infrastructure while Korean and Thai clinics accelerate premium protocol adoption through medical tourism flows.
Growth Catalysts
- Biostimulator protocol expansion:Poly-L-lactic acid formulations are extending patient return intervals, driving clinic economics toward collagen-inducing treatments over traditional volume replacement.
- MFDS streamlined approval pathways:South Korea's regulator has reduced review timelines for hyaluronic acid derivatives with established safety profiles, accelerating product cycles for cross-linked gel manufacturers.
- Gangnam district cluster density:Seoul's aesthetic corridor concentrates purchasing power and clinical expertise, creating demonstration effects that diffuse premium filler protocols across Asia-Pacific metropolitan markets.
Market Restraints
- Non-harmonized biocompatibility standards:Australia's TGA and South Korea's MFDS enforce divergent testing protocols, multiplying compliance costs for manufacturers without localized regulatory affairs teams.
- Hyaluronic acid raw material concentration:Bacterial fermentation supply chains cluster in specific production geographies, exposing fillermakers to input cost volatility and single-source dependency risks.
- Reversibility as commoditization vector:Hyaluronidase reversibility of HA gels eliminates switching costs for patients, compressing brand loyalty and margin protection for established formulations.
Strategic Opportunities
- India's CDSCO alignment trajectory:The regulator's movement toward ISO 13485 benchmarks creates first-mover advantage for quality-certified manufacturers ahead of formal mandate implementation.
- Multi-syringe kit bundling:Protocol-based packaging configurations enable premium pricing through treatment continuity commitments rather than per-unit commodity competition.
- Thailand medical tourism infrastructure:Bangkok and Phuket clinic networks are expanding capacity for international patients, creating demand pull for mid-premium filler tiers with multilingual training support.
Industry Challenges
- Cross-linking chemistry talent scarcity:Specialized polymer science expertise for HA gel rheology optimization concentrates in European and Korean research clusters, constraining R&D expansion timelines.
- Domestic trial data generation costs:China's NMPA requirement for in-country clinical endpoints demands capital-intensive site activation and patient recruitment in tier-one hospital networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Dermal Fillers Market |
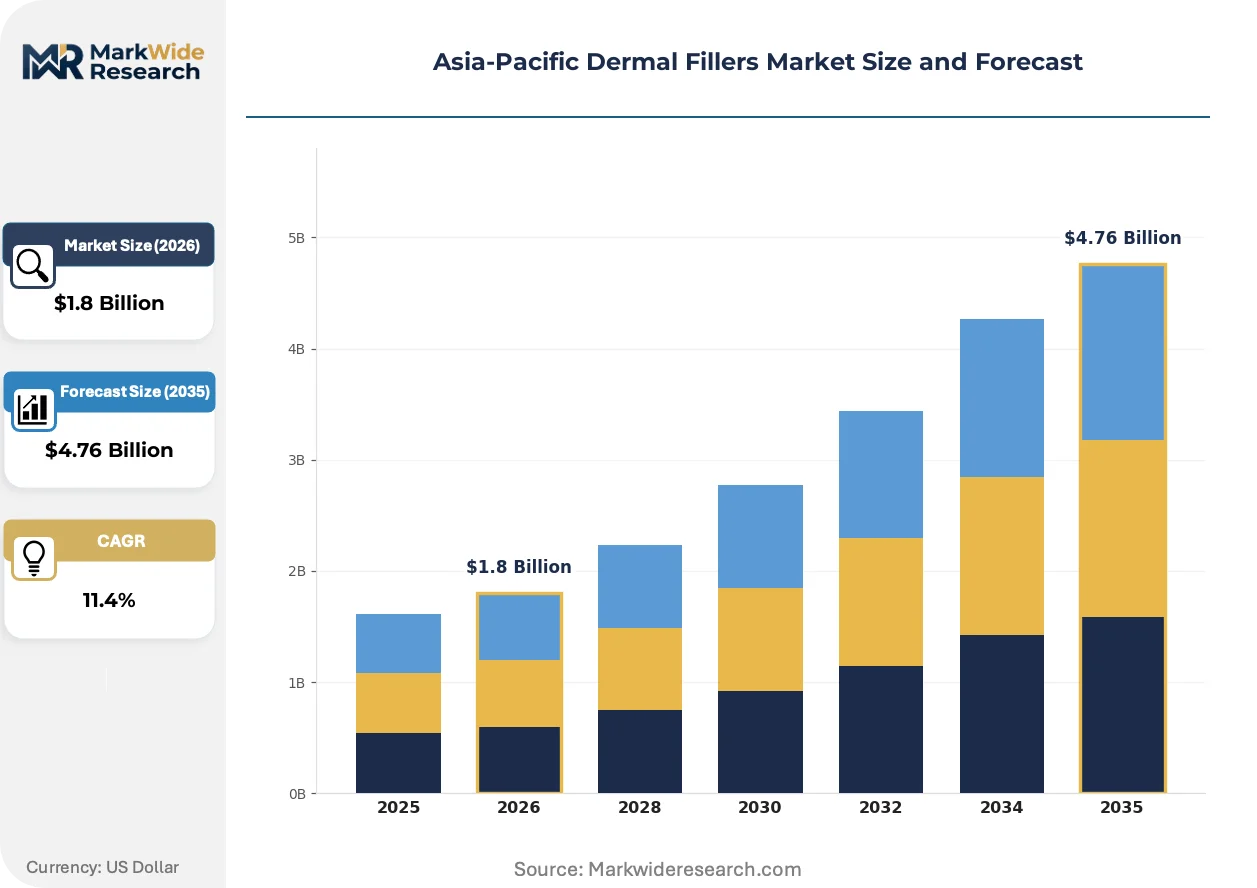
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hyaluronic Acid, Calcium Hydroxylapatite, Poly-L-Lactic Acid, Polymethyl Methacrylate Application: Facial Contouring, Wrinkle Reduction, Lip Enhancement, Volume Restoration End User: Dermatology Clinics, Cosmetic Surgeons, Spas, Hospitals Distribution Channel: Online, Offline, Direct Sales, Medical Distributors |
| Companies Covered | Revance Therapeutics, Suneva Medical, Allergan (AbbVie), Sinclair Pharma, Teoxane Laboratories, Galderma, Medytox, Ipsen, Merz Pharma, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Dermal Fillers Market Emerging Trajectories
Injectable aesthetic protocols are pivoting from wrinkle correction toward facial contouring and structural volumization, reshaping product development priorities and clinician training curricula across Asia-Pacific metropolitan markets.
Non-animal stabilized hyaluronic acid with advanced cross-linking density is rewriting treatment durability expectations. Dermatology clinics in Seoul and Shanghai are adopting these formulations for mid-face volumization protocols. The technology is compressing competitive differentiation around longevity claims rather than immediate aesthetic outcomes.
China's NMPA tightened biocompatibility review timelines are extending market access windows for novel filler submissions. Manufacturers must now generate domestic clinical trial data before registration approval. European-headquartered firms with existing Chinese site infrastructure are responding by accelerating partnership negotiations with local contract research organizations.
Clinic procurement is consolidating around bundled protocol sales rather than single-syringe transactions. Australian and Japanese dermatology practices are negotiating annual volume commitments with manufacturers in exchange for training certification and priority supply allocation. This behavior shift is most visible in Sydney and Tokyo aesthetic clusters where patient consultation-to-treatment conversion rates drive inventory planning cycles.
Asia-Pacific Dermal Fillers Market Segmentation
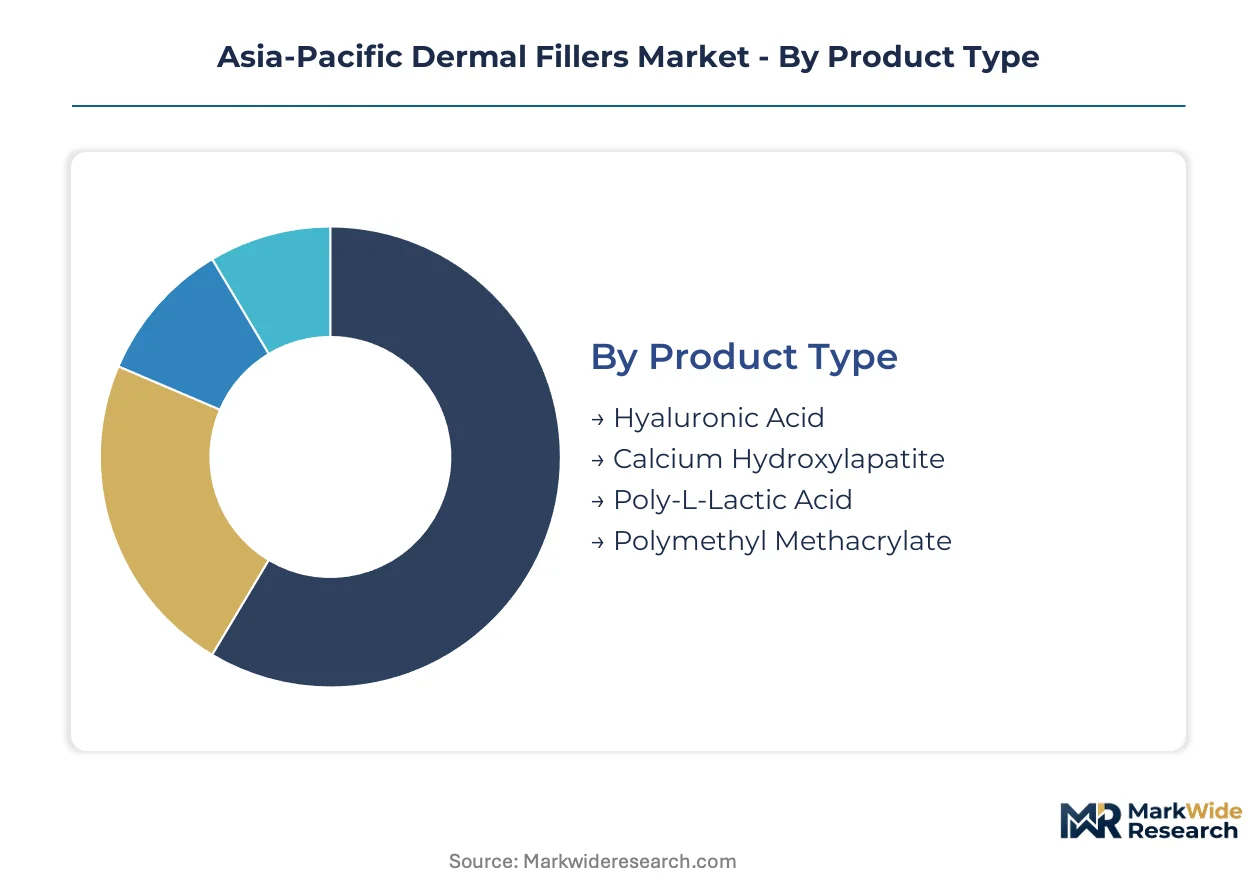
Product heterogeneity across the Asia-Pacific dermal fillers market demands granular segmentation to align formulation properties with clinical use cases and regulatory pathways. Understanding how hyaluronic acid gels, biostimulators, and permanent fillers map to specific applications and procurement channels enables targeted commercial strategy.
Product Type:
Hyaluronic acid formulations function as standalone reversible treatments, while biostimulators and permanent fillers embed into longer protocol sequences requiring sequential patient commitment.
- Hyaluronic Acid:Cross-linked bacterial fermentation gels with particle sizes from 200 to 1000 microns dominate procurement volumes across Seoul's Gangnam district and Shanghai's tier-one clinic clusters. Reversibility with hyaluronidase anchors patient trust but eliminates switching costs, compressing brand loyalty for established manufacturers.
- Poly-L-Lactic Acid:Collagen-inducing biostimulator microspheres suspend in aqueous solution for gradual volumization over multiple treatment sessions. Clinics in Bangkok's medical tourism corridor favor these protocols for extended patient return intervals and improved per-patient lifetime value economics.
- Calcium Hydroxylapatite:Biosynthetically produced microspheres in carboxymethylcellulose gel carrier provide immediate volume plus neocollagenesis stimulation.
- Polymethyl Methacrylate:Permanent microsphere implants suspended in bovine collagen or synthetic carrier require informed consent protocols and specialized injection training.
Hyaluronic acid leads volumes today; poly-L-lactic acid is gaining share fastest.
Application:
Clinical demand concentrates where aesthetic outcomes justify premium pricing and repeat treatment scheduling.
- Volume Restoration:Mid-face volumization protocols using high G-prime hyaluronic acid formulations command premium per-syringe pricing in Tokyo and Sydney dermatology practices. China's NMPA registration pathways for structural volumization indications require dedicated clinical trial endpoints, extending commercialization timelines.
- Facial Contouring:Jawline definition and cheekbone projection treatments using cohesive polydensified matrix gels concentrate purchasing power in Seoul's demonstration clinics. Korean MFDS streamlined approvals for established cross-linking technologies accelerate product cycles for contouring-specific formulations.
- Wrinkle Reduction:Nasolabial fold and perioral line corrections face margin compression from commoditized entry-level products distributed through medical wholesalers.
- Lip Enhancement:Vermilion border definition and philtrum column treatments require low-viscosity gels with precise extrusion force characteristics.
Volume restoration commands the highest per-treatment revenue; facial contouring shows the steepest expansion trajectory.
End User:
Procurement authority and protocol complexity determine which channels manufacturers prioritize for training investment and supply allocation.
- Dermatology Clinics:Specialist-led practices in Australia's TGA-regulated environment negotiate annual volume commitments for bundled multi-syringe kits with manufacturer-certified training programs. These clinics drive adoption of advanced cross-linking density formulations for structural volumization.
- Cosmetic Surgeons:Hospital-affiliated and independent surgical practices in South Korea's MFDS jurisdiction perform combination procedures integrating fillers with surgical interventions, requiring higher-viscosity products with prolonged residence time.
- Spas:Non-medical aesthetic centers in Thailand's medical tourism infrastructure source mid-premium filler tiers with multilingual training support for international patient protocols.
- Hospitals:Academic medical centers in China generate the domestic clinical trial data required for NMPA novel filler approvals, creating partnership opportunities with contract research organizations.
Dermatology clinics dominate current purchasing volumes; cosmetic surgeons are expanding their share of high-complexity procedures.
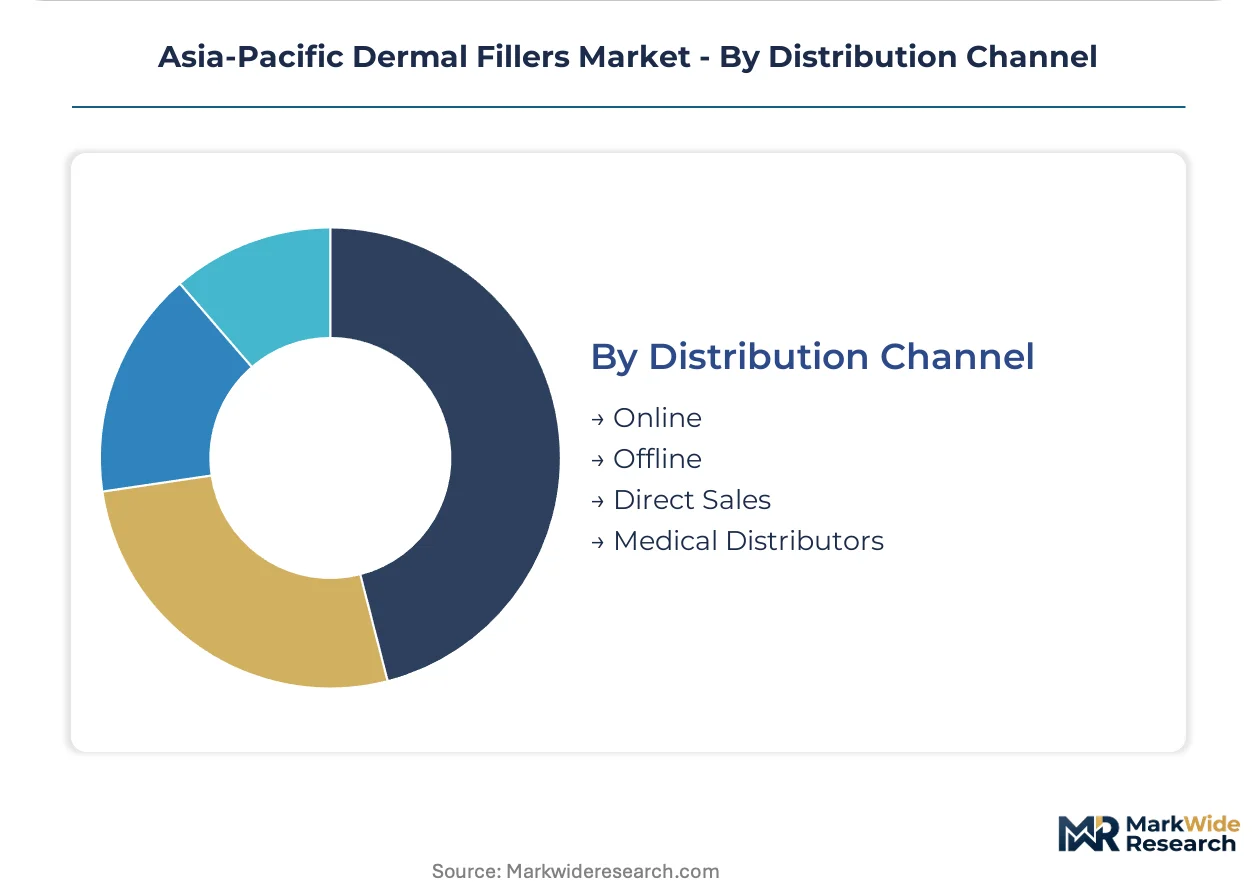
Distribution Channel:
Channel selection reflects product classification, cold chain requirements, and regulatory traceability mandates across Asia-Pacific jurisdictions.
- Direct Sales:Manufacturer field forces engage tier-one clinic clusters in Seoul, Tokyo, and Shanghai with protocol-based bundling, training certification, and priority supply allocation. This channel captures premium pricing through treatment continuity commitments.
- Medical Distributors:Specialized aesthetic device distributors with cold chain logistics serve secondary cities and regional markets where direct sales infrastructure remains uneconomical.
- Online:E-procurement platforms facilitate reordering of established products with existing NMPA, MFDS, or TGA registrations for clinics with predictable consumption patterns.
- Offline:Traditional pharmaceutical and medical supply wholesalers handle commoditized entry-level hyaluronic acid fillers for price-sensitive segments.
Direct sales generates the highest margin per unit; medical distributors reach the broadest geographic footprint.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea pioneered the modern aesthetic medicine infrastructure that now defines Asia-Pacific dermal filler protocols. The country's clinic clustering model diffused across metropolitan markets from Seoul to Shanghai. This historical foundation shapes current regulatory pathways and procurement patterns throughout the region.
China
Tier-one cities Shanghai and Beijing concentrate purchasing power for premium hyaluronic acid formulations. NMPA domestic clinical trial mandates extend market access timelines for novel filler submissions. The Yangtze River Delta aesthetic corridor generates demonstration effects that diffuse treatment protocols into secondary urban markets.
South Korea
Seoul's Gangnam district anchors the highest clinic density per capita for facial contouring procedures globally. MFDS streamlined approval pathways for established cross-linking technologies accelerate product cycles for hyaluronic acid gel manufacturers. Busan-Ulsan medical tourism infrastructure pulls international patients seeking bundled aesthetic protocols.
Japan
Tokyo and Osaka dermatology practices negotiate annual volume commitments for bundled multi-syringe kits. PMDA maintains rigorous biocompatibility standards that favor manufacturers with localized regulatory affairs teams. The Kanto region's aesthetic clusters drive adoption of advanced cross-linking density formulations for structural volumization.
Australia
Sydney and Melbourne dermatology clinics anchor premium procurement for volume restoration applications. TGA enforces divergent biocompatibility testing standards that multiply compliance costs for manufacturers without localized infrastructure. The country's specialist-led practices drive bundled protocol sales rather than single-syringe transactions.
Thailand
Bangkok and Phuket clinic networks expand capacity for international medical tourism patients. The country's aesthetic infrastructure sources mid-premium filler tiers with multilingual training support. Thai clinics favor poly-L-lactic acid biostimulators for extended patient return intervals and improved per-patient lifetime value economics.
Asia-Pacific Dermal Fillers Market Vendor Landscape
Premium-margin players sit above commodity-margin players across cross-linking technology sophistication and regulatory pathway maturity. The market structures around three tiers: multinational pharmaceutical conglomerates with full regulatory infrastructure, specialized aesthetic device manufacturers with regional concentration, and emerging biotech firms pursuing novel biostimulator formulations. Consolidation pressures intensify as China's NMPA domestic trial requirements favor players with existing Chinese site infrastructure. Strategic moves center on partnership negotiations with local contract research organizations and bundled protocol packaging configurations.
Within the multinational tier, Allergan (AbbVie), Galderma, and Teoxane Laboratories occupy positions defined by portfolio breadth and geographic reach. Allergan (AbbVie) exemplifies the conglomerate archetype leveraging established regulatory pathways across multiple Asia-Pacific jurisdictions. Galderma represents the specialized pharmaceutical model with sustained R&D intensity in hyaluronic acid cross-linking technology. Teoxane Laboratories anchors the Swiss-based precision manufacturing segment competing for facial contouring market share in Singapore and Hong Kong. These three entities illustrate how regulatory infrastructure scale separates premium-tier positioning from mid-market competition.
| Leading Market Players |
|---|
| Revance Therapeutics |
| Suneva Medical |
| Allergan (AbbVie) |
| Sinclair Pharma |
| Teoxane Laboratories |
| Galderma |
| Medytox |
| Ipsen |
| Merz Pharma |
| Others |
Supply Flow & Price Mechanics
Dermatology clinic clusters in Seoul's Gangnam district and Shanghai's tier-one aesthetic corridors anchor purchasing power for bundled multi-syringe protocol kits, compressing per-unit commodity competition into premium treatment-continuity pricing models. This buyer concentration reshapes manufacturer incentives toward annual volume commitments with certified training allocations rather than transactional spot purchasing.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates high G-prime structural volumization formulations from mid-tier facial contouring gels and entry-level wrinkle correction products. Price differentiation hinges on cross-linking density certification grades and bundled after-sales training depth. Cost compression in economy-tier hyaluronic acid segments intensifies as medical wholesalers consolidate procurement volumes. Price sensitivity concentrates among Thailand's medical tourism clinics sourcing mid-premium tiers, while Seoul's demonstration clinics exhibit minimal elasticity for novel biostimulator protocols.
Supply Chain Analysis
Regional distribution centers in Singapore and Hong Kong anchor hub-and-spoke cold chain logistics for temperature-sensitive hyaluronic acid gel inventories across Southeast Asian markets. Bacterial fermentation capacity clusters in South Korea, Japan, and select European production geographies. Raw material dependencies center on pharmaceutical-grade sodium hyaluronate, cross-linking agent BDDE, and sterile packaging components. Single-source vulnerability in fermentation-derived hyaluronic acid concentrates exposes fillermakers to input cost volatility. Distribution runs through manufacturer field forces for tier-one clinic clusters and specialized medical distributors for secondary city penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where patient demand shifts toward collagen-inducing biostimulator protocols with extended durability specifications. Premium formulation manufacturers capture margin expansion as clinic economics favor longer patient return intervals over commoditized volume replacement.
For Market Incumbents: Deepen cross-linking chemistry R&D partnerships with Korean and European polymer science clusters to defend formulation differentiation against emerging biostimulator entrants. Anchor bundled protocol sales through annual volume commitments with priority supply allocation. Counter regulatory fragmentation by expanding localized regulatory affairs teams in China and Australia ahead of NMPA and TGA biocompatibility mandate evolution. For New Entrants and Emerging Players: Advanced polydensified matrix technology for facial contouring applications offers the most penetrable wedge into premium-tier procurement dominated by established cross-linking patent portfolios. Target Thailand's Bangkok-Phuket medical tourism corridor with multilingual training support and mid-premium pricing positioning. Pursue CDSCO pre-certification alignment ahead of formal ISO 13485 mandate implementation to capture first-mover positioning in India's emerging aesthetic clinic infrastructure. For Investors and Strategic Acquirers: Specialized pharmaceutical conglomerates with existing Chinese clinical trial infrastructure are the most active acquirers in this space, consolidating regional players to satisfy NMPA domestic data generation requirements. Long-term viability favors manufacturers with vertically integrated fermentation capacity and multi-jurisdictional regulatory pathway maturity. Monitor MFDS streamlined approval pathway expansion as the inflection signal for accelerated product cycle economics.| Strategic Initiative | Industry Significance |
|---|---|
| Cross-Linking Technology Patent Expansion | Galderma and Teoxane Laboratories compete for facial contouring share through proprietary HA gel rheology optimization. |
| Localized Clinical Trial Infrastructure | European-headquartered firms accelerate CRO partnerships in China to satisfy NMPA domestic endpoint mandates. |
| Multi-Syringe Protocol Bundling | Allergan anchors annual volume commitments in Australian and Japanese clinics through Juvederm portfolio breadth. |
| Biostimulator Formulation Development | Poly-L-lactic acid microsphere protocols extend patient return intervals for Bangkok medical tourism clinics. |
| Regulatory Affairs Team Localization | Manufacturers deploy dedicated TGA and MFDS compliance infrastructure to navigate divergent biocompatibility standards. |
Methodological Framework
Multiple input streams — primary interviews with dermatology clinic directors, regulatory affairs specialists at NMPA and MFDS, and medical device procurement managers; secondary validation through FDA 510(k) filings, PMDA submission databases, and Asia-Pacific customs trade records; plus hospital procurement database analysis — were reconciled through bottom-up and top-down triangulation. Conversations with cosmetic surgeons in Seoul's Gangnam district and biomedical engineers at Shanghai tier-one hospitals informed formulation preference dynamics. Cross-referencing manufacturer field force deployment patterns against clinic density mapping yielded channel structure validation.
Data-stream reconciliation across product type segmentation by cross-linking technology, application segmentation by volumization versus contouring versus wrinkle correction protocols, and end-user segmentation by dermatology clinic versus cosmetic surgeon procurement authority anchored the analytical framework throughout the projection horizon. CAGRs were derived from patient treatment volume modeling and per-protocol revenue assumptions. Forecast inputs incorporated MFDS approval pathway acceleration effects and NMPA domestic trial timeline extensions specific to novel filler submissions.
The model holds under stable regulatory pathway timelines and continued medical tourism flow expansion; deviation in NMPA biocompatibility mandate severity or hyaluronic acid raw material supply disruption would shift volume and value trajectories. Forecasts reflect documented assumptions around clinic adoption curves for biostimulator protocols. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aesthetic Medicine
Aesthetic Lasers and Energy Devices Market
Aesthetic Medicine
North America Medical Aesthetic Devices Market
Aesthetic Medicine
Customized China Aesthetics Equipment Market
Aesthetic Medicine
Facial Rejuvenation Market
Aesthetic Medicine
Non-Invasive Fat Reduction Market
Aesthetic Medicine
Global Aesthetic Threads Market
Aesthetic Medicine
Global Dermal Filler Market
Aesthetic Medicine
Europe Dermal Fillers Market
Aesthetic Medicine
Japan Facial Aesthetics Market
Aesthetic Medicine
Energy-Based Aesthetic Devices Market
Aesthetic Medicine
UAE Laser Hair Removal Market
Aesthetic Medicine
North America Non-Invasive Aesthetic Treatment Market
Aesthetic Medicine
Aesthetic Laser Market
Aesthetic Medicine
Spain Facial Aesthetics Market
Aesthetic Medicine
Professional Beauty Services Market
Aesthetic Medicine
Global Aesthetic Dermatology Market