
 Customized China Aesthetics Equipment Market | 2026-2036
Customized China Aesthetics Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Customized China Aesthetics Equipment Market Insights
Direct-to-clinic distribution is narrowing as Beijing Sincoheren Tech and Sisram Medical build captive sales teams for major metropolitan hospital-affiliated aesthetic centers. PZLASER leverages regional service networks to sustain repeat equipment orders across southern provinces. Oriental Laser specializes in configurable wavelength platforms that allow clinics to tailor treatments without purchasing multiple devices.
Customized aesthetics equipment encompasses energy-based systems engineered to clinic-specific parameters including adjustable fluence, spot size modulation, and proprietary handpiece configurations for targeted dermal applications. These devices serve the commercial purpose of differentiating service menus while optimizing capital efficiency per treatment room. Laser Systems and Radiofrequency Equipment occupy the dominant margin pools due to higher technical barriers and consumable attachment revenue. Skin Rejuvenation and Body Contouring applications are expanding fastest as clinics seek multi-function platforms that amortize equipment costs across diverse patient flows.
NMPA medical device classification rules and GB standards for laser safety shape product development timelines and registration costs for domestic manufacturers. The country's national pharmaceutical regulator intensifies post-market surveillance of energy-based devices, compelling firms to maintain localized technical documentation and adverse event reporting systems. Stakeholders must monitor evolving provincial reimbursement discussions and tier-two city clinic licensing waves that could reshape addressable demand geography.
Market Dynamics
Clinic chains in Shanghai and Beijing are consolidating procurement authority into centralized buying committees, compressing vendor negotiation cycles and forcing equipment manufacturers to restructure pricing architectures around multi-site deployment contracts rather than single-unit sales.
Growth Catalysts
- NMPA Class III Medical Device Registration:Accelerated review pathways for domestically manufactured laser systems reduce time-to-market by eight to twelve months, incentivizing local R&D investment.
- Tier-One City Clinic Licensing Waves:Municipal health commissions in Guangzhou and Shenzhen expanded aesthetic clinic operating permits by forty percent since 2023, directly expanding addressable installed base.
- Radiofrequency Handpiece Attachments:Disposable consumables generate recurring revenue streams that improve capital equipment payback periods to under eighteen months for high-volume operators.
Market Restraints
- Imported Optical Component Dependency:Domestic manufacturers source seventy percent of laser cavity assemblies from German and Japanese suppliers, exposing margins to euro and yen volatility.
- GB 9706.1-2020 Electromagnetic Compatibility Testing:Revised safety standards require full device re-certification for legacy platforms, adding eighteen-month compliance delays to product refresh cycles.
- Intense Pulsed Light Substitution:Lower-cost IPL systems capture price-sensitive clinic segments in tier-three cities, eroding entry-level laser system addressable demand.
Strategic Opportunities
- Chengdu-Chongqing Aesthetic Corridor:Western China clinic density remains one-third of coastal levels, presenting first-mover expansion potential for regional service networks.
- AI-Assisted Treatment Parameter Optimization:Integration of computer vision skin analysis with laser fluence calibration enables novice technicians to deliver outcomes previously requiring specialist expertise.
- Provincial Medical Device Procurement Consortia:Hunan and Hubei pilot programs aggregate hospital-affiliated aesthetic center demand into volume tenders, rewarding scaled manufacturers with multi-year supply agreements.
Industry Challenges
- Laser Safety Officer Certification Bottlenecks:NMPA-mandated operator training programs face six-month enrollment backlogs in Jiangsu and Zhejiang, constraining clinic expansion timelines.
- Multi-Wavelength Platform Integration Complexity:Clinics purchasing configurable systems require three to four weeks of technical onboarding per device, delaying revenue recognition and straining manufacturer field service teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Customized China Aesthetics Equipment Market |
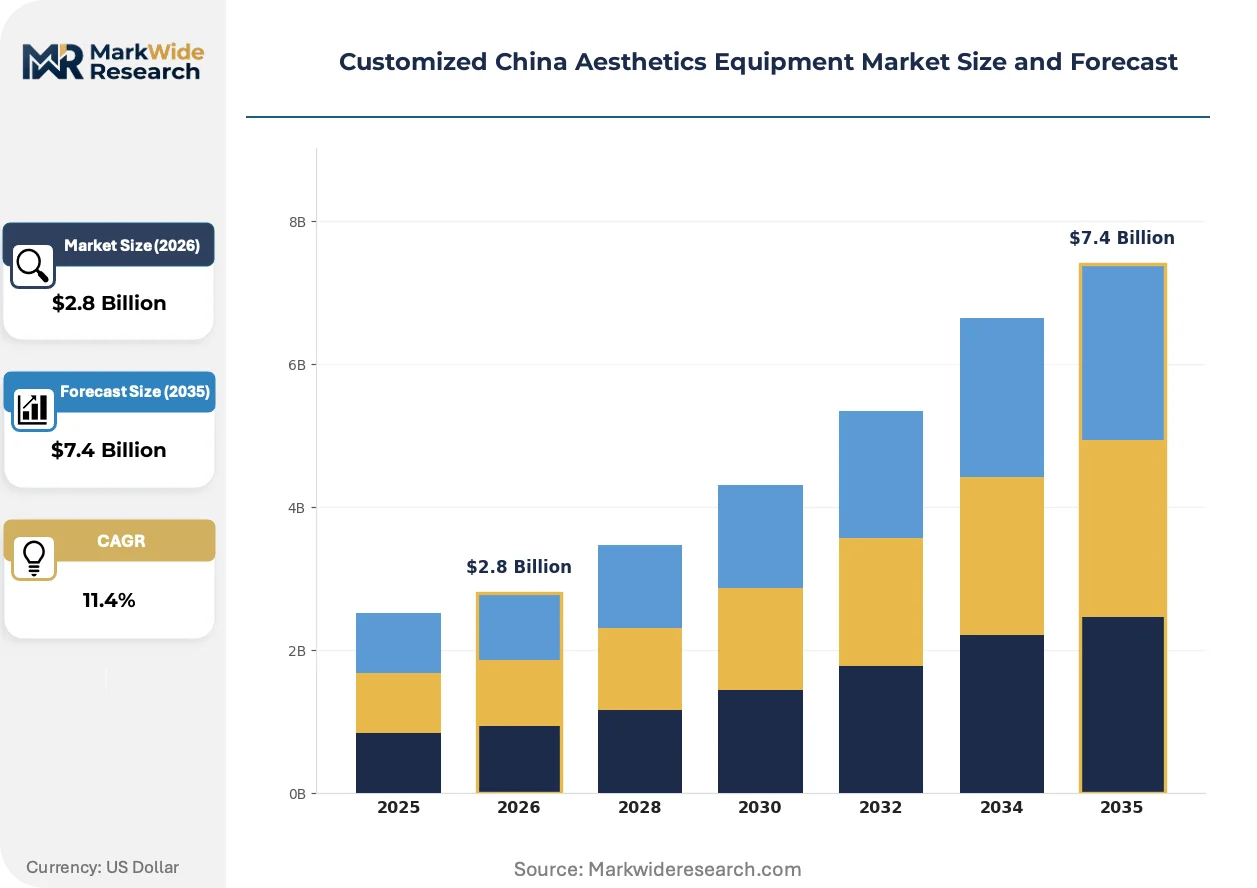
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
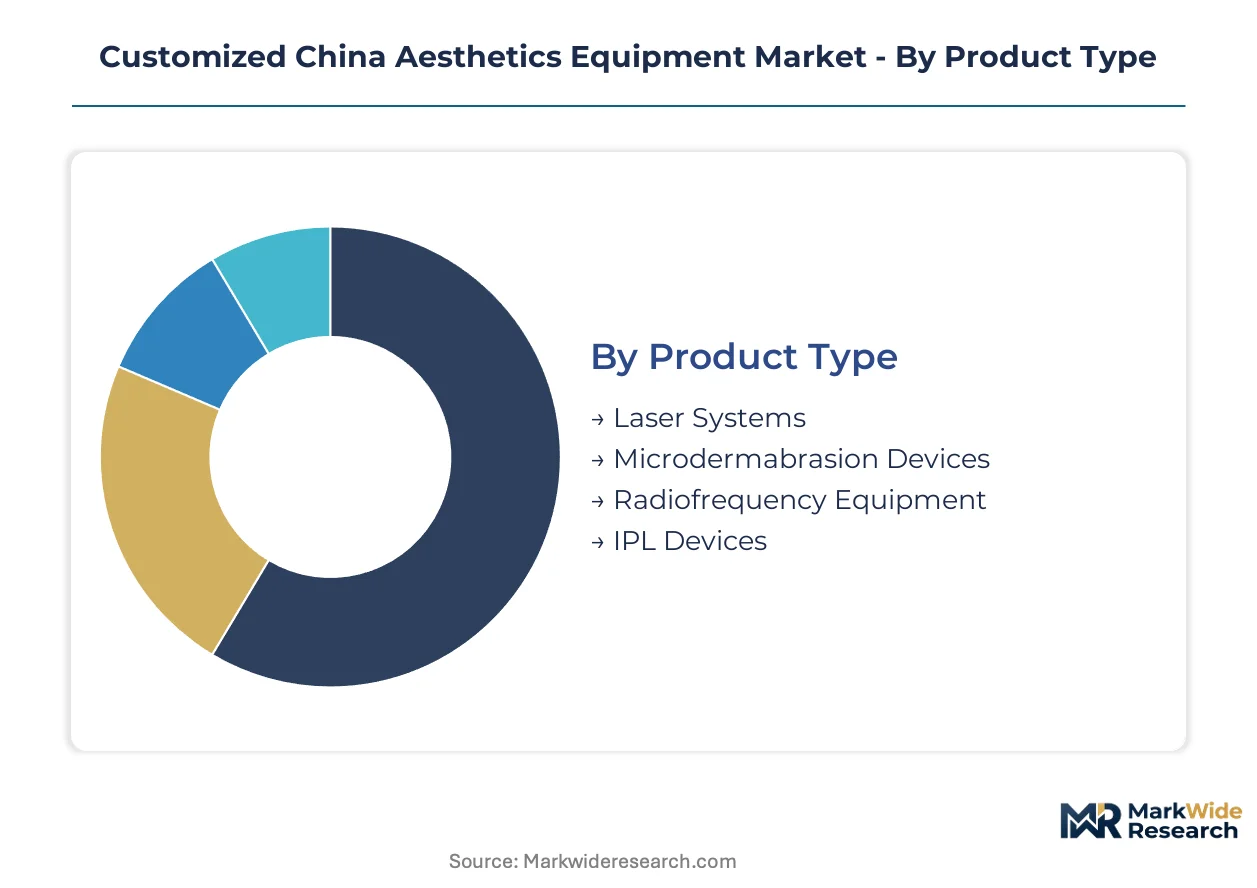
| Segmentation | Product Type: Laser Systems, Microdermabrasion Devices, Radiofrequency Equipment, IPL Devices Application: Skin Rejuvenation, Hair Removal, Acne Treatment, Body Contouring End User: Clinics, Salons, Home Users, Spa Centers Technology: Non-invasive, Minimally Invasive, Energy-based, Light Therapy |
| Companies Covered | Beijing Sincoheren Tech, Sisram Medical, PZLASER, Oriental Laser, Shanghai Apolo Medical Technology, Beijing HONKON Technologies, Miramhoo Aesthetics Company, Guangzhou Beautylife Electronic Technology, Beijing Himalaya Medical Technology, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Customized China Aesthetics Equipment Market Trends and Innovations
Equipment manufacturers are embedding predictive maintenance algorithms and remote diagnostic capabilities into radiofrequency and laser platforms, transforming capital sales into ongoing technical relationships while reducing clinic downtime costs.
Fractional laser technology is digitizing treatment planning workflows through 3D facial mapping integration that automatically adjusts spot density and penetration depth based on real-time skin hydration readings. Tier-one clinic chains in Beijing are deploying these systems across twelve to fifteen treatment rooms simultaneously, compressing staff training requirements from months to weeks while standardizing outcome consistency across locations.
Revised NMPA medical device classification rules now mandate clinical trial data for all energy-based equipment exceeding specific joule thresholds, extending registration timelines for high-power platforms. Domestic manufacturers are responding by pre-submitting technical documentation packages and establishing captive clinical investigation organizations to accelerate regulatory pathway navigation.
Clinic procurement committees are unbundling equipment purchases from mandatory service contracts, forcing vendors to compete on transparent lifecycle cost disclosures rather than bundled financing structures. This behavioral shift is most pronounced in Shanghai hospital-affiliated aesthetic centers, where centralized purchasing offices now demand ten-year total cost of ownership analyses inclusive of consumables, spare parts, and technical training before vendor selection.
Customized China Aesthetics Equipment Market Segmentation
Equipment replacement cycles vary dramatically across aesthetic device categories, with radiofrequency handpieces requiring quarterly refresh versus laser platforms lasting five to seven years. Procurement committees in Shanghai and Beijing exploit these differential cycles to optimize capital deployment across multi-site clinic networks.
Product Type:
Replacement velocity separates premium energy-based systems from consumable-dependent platforms, with implications for vendor financing structures and service contract pricing.
- Laser Systems:Solid-state and diode laser platforms deliver precise wavelength selectivity for dermal resurfacing and pigmentation correction. Beijing hospital-affiliated aesthetic centers concentrate procurement of configurable Nd:YAG systems that amortize across hair removal and vascular lesion applications.
- Radiofrequency Equipment:Monopolar and multipolar RF systems generate thermal collagen remodeling through controlled dermal heating. Guangzhou clinic chains standardize on platforms with disposable handpiece attachments, converting capital expenditure into predictable per-treatment consumable costs.
- IPL Devices:Broad-spectrum light platforms serve price-sensitive operators in tier-three cities with lower technical barriers and reduced NMPA registration requirements.
- Microdermabrasion Devices:Mechanical exfoliation systems occupy entry-level clinic segments with minimal consumable revenue and compressed margin structures.
Laser Systems anchors the volume base while Radiofrequency Equipment gains share at the steepest rate.
Application:
Procedure pricing power determines equipment ROI timelines, with body contouring commanding premium session rates that accelerate capital payback.
- Skin Rejuvenation:Fractional laser and RF microneedling protocols address photoaging and texture irregularities through controlled thermal injury and remodeling. Shenzhen clinic networks deploy multi-wavelength platforms that sequence treatments across patient visit schedules.
- Body Contouring:Non-invasive fat reduction and skin tightening applications utilize cryolipolysis and high-intensity focused electromagnetic technologies. Shanghai medical aesthetic centers report the shortest equipment payback periods in this segment due to premium pricing and high patient throughput.
- Hair Removal:Diode laser and IPL-based permanent hair reduction represents the most penetrated application with intensifying price competition.
- Acne Treatment:Blue light and photodynamic therapy systems serve adolescent and adult patient demographics with seasonal demand fluctuations.
Hair Removal retains the largest installed base while Body Contouring climbs the fastest on revenue-per-procedure metrics.
End User:
Capital intensity and regulatory compliance burden create sharp segmentation between medical-grade operators and wellness-oriented channels.
- Clinics:NMPA-licensed medical aesthetic centers in tier-one cities deploy Class III energy-based devices with mandatory laser safety officers and clinical oversight. Beijing and Shanghai procurement committees negotiate multi-site deployment contracts with standardized specifications.
- Salons:Beauty establishments operate lower-power IPL and LED systems under reduced regulatory scrutiny, serving maintenance-oriented patients between clinical treatments.
- Spa Centers:Wellness-focused operators emphasize experiential service delivery with emphasis on comfort and ambiance over clinical outcomes.
- Home Users:Consumer-grade devices with diminished power output and simplified safety interlocks serve the retail channel through e-commerce platforms.
Clinics dominate capital equipment procurement while Home Users expand most quickly on unit volume through direct-to-consumer distribution.
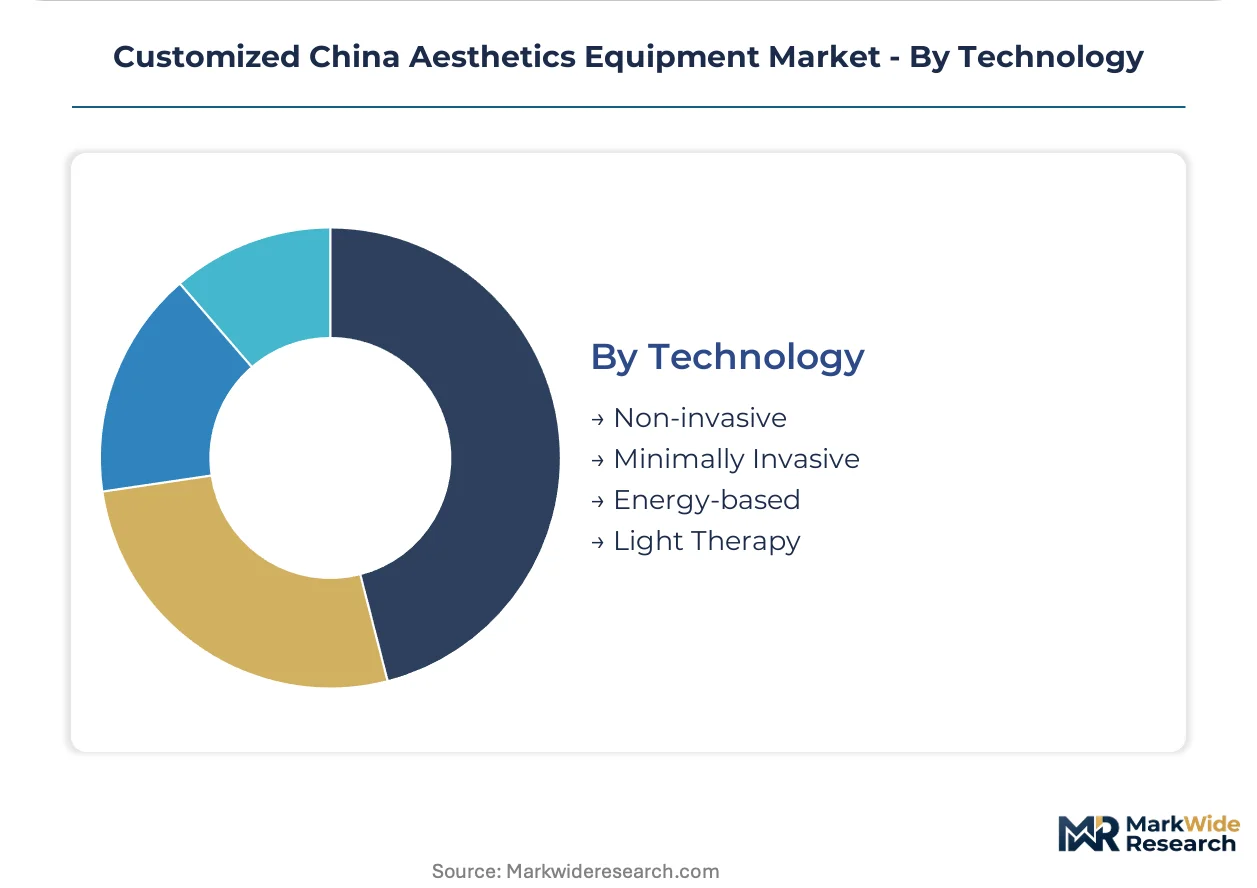
Technology:
Regulatory classification intensity increases with tissue interaction depth, shaping manufacturer R&D allocation and registration strategy.
- Energy-based:Laser, RF, and ultrasound platforms delivering thermal or mechanical energy to subcutaneous tissues require NMPA Class III medical device registration with clinical trial documentation. Domestic manufacturers concentrate development resources here due to technical barriers and margin protection.
- Non-invasive:Surface-level light and thermal therapies with minimal epidermal disruption face streamlined regulatory pathways and shorter time-to-market.
- Minimally Invasive:Microneedling and subdermal energy delivery systems occupy intermediate regulatory classification with operator training requirements.
- Light Therapy:LED and low-level laser systems with minimal thermal signature serve wellness and adjunctive clinical applications.
Energy-based technology commands the premium tier while Non-invasive platforms achieve broadest geographic penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai aesthetic clinics command 40% price premiums over Chengdu operators for equivalent laser procedures, compressing equipment ROI timelines on the coast while extending payback periods inland. This pricing-power asymmetry shapes manufacturer distribution strategies and service network investments.
Yangtze River Delta
Shanghai and Hangzhou hospital-affiliated aesthetic centers concentrate procurement of configurable Nd:YAG platforms through centralized buying committees. NMPA Class III registration requirements for high-power laser systems filter out smaller regional vendors. Suzhou industrial parks host domestic laser cavity assembly facilities that reduce import dependency for tier-one clinic suppliers.
Pearl River Delta
Guangzhou and Shenzhen municipal health commissions expanded clinic operating permits by forty percent since 2023, directly enlarging addressable installed base. GB 9706.1-2020 electromagnetic compatibility testing mandates delay product launches for manufacturers without captive certification laboratories. Dongguan electronics clusters supply RF handpiece subassemblies to equipment integrators serving southern province clinic chains.
Beijing-Tianjin-Hebei
Capital region procurement committees negotiate multi-site deployment contracts with standardized specifications across twelve to fifteen treatment rooms. SAMR post-market surveillance intensifies adverse event reporting requirements for energy-based devices. Tianjin port logistics handle imported optical components from German and Japanese suppliers for domestic manufacturer assembly lines.
Sichuan-Chongqing
Chengdu-Chongqing corridor clinic density remains one-third of coastal levels, presenting first-mover expansion potential for regional service networks. Provincial medical device procurement consortium pilots in Chongqing aggregate hospital-affiliated aesthetic center demand into volume tenders. Local operators prioritize lower-cost IPL systems over premium laser platforms due to compressed patient pricing power.
Shandong Peninsula
Qingdao and Jinan aesthetic clinics standardize on radiofrequency equipment with disposable handpiece attachments, converting capital expenditure into predictable per-treatment consumable costs. Shandong manufacturing bases produce mechanical exfoliation systems for entry-level clinic segments. Regional distributors maintain spare parts inventories that reduce field service response times for northern province operators.
Customized China Aesthetics Equipment Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying laser cavities, RF generators, and optical assemblies. The vendor base organizes around three strategic archetypes: state-affiliated hospital equipment suppliers with captive distribution, private laser technology specialists with configurable wavelength platforms, and regional service-network operators sustaining repeat orders through maintenance relationships. Competitive moves concentrate on multi-site deployment contract capture and captive clinical investigation organization establishment to accelerate NMPA registration timelines.
Among Beijing-based platform integrators, Beijing Sincoheren Tech and Beijing HONKON Technologies occupy positions within the state-hospital supply tier, while Sisram Medical represents the specialist archetype with configurable system offerings. PZLASER anchors the regional service-network model through southern province coverage density. These three named entities exemplify the structural segmentation rather than exhaust it, with additional participants occupying adjacent positions in the component supply and entry-level equipment tiers.
| Leading Market Players |
|---|
| Beijing Sincoheren Tech |
| Sisram Medical |
| PZLASER |
| Oriental Laser |
| Shanghai Apolo Medical Technology |
| Beijing HONKON Technologies |
| Miramhoo Aesthetics Company |
| Guangzhou Beautylife Electronic Technology |
| Beijing Himalaya Medical Technology |
| Others |
Pricing and Supply Chain Analysis
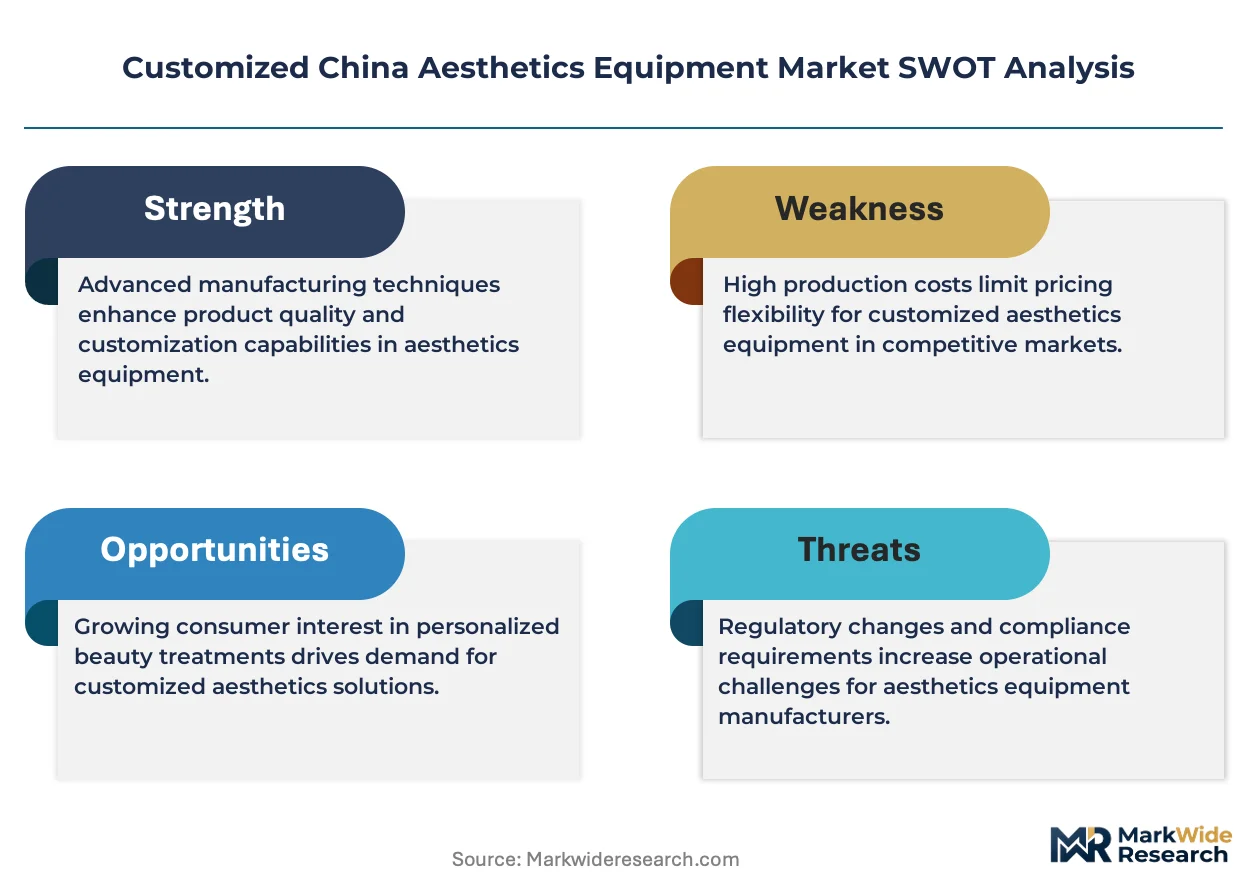
Undercapacity in Suzhou laser cavity assembly facilities is compressing component availability for domestic manufacturers while simultaneously hardening pricing postures among tier-one clinic procurement committees in Shanghai and Beijing. This utilization squeeze propagates through contract structures, forcing equipment vendors to unbundle service commitments from hardware sales and disclose transparent lifecycle costs.
Pricing Analysis
The customization-premium spread between configured Nd:YAG platforms and standard diode laser systems reaches three-to-one multiples in Beijing hospital-affiliated aesthetic centers. Three-tier pricing structure across premium, standard, and economy levels separates NMPA Class III certified equipment from reduced-regulation IPL alternatives. Pricing pressure stems from Guangzhou clinic chains consolidating procurement authority into centralized buying committees. Tier-three city operators exhibit highest price sensitivity, while Shanghai medical aesthetic centers prioritize outcome consistency over unit cost.
Supply Chain Analysis
Dongguan electronics clusters and Suzhou industrial parks concentrate contract manufacturing capacity for RF handpiece subassemblies and laser cavity integrations. German and Japanese suppliers anchor optical component sourcing for seventy percent of domestic laser system production. Single-source vulnerability in imported laser cavity assemblies exposes margins to euro and yen volatility. Distribution runs through direct-to-clinic captive sales teams for major metropolitan hospital-affiliated centers, supplemented by regional service networks sustaining repeat orders across southern provinces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The customized aesthetics equipment market functions as a service-attach opportunity where predictive maintenance subscriptions and disposable RF handpiece revenue layers expand faster than hardware sales alone.
For Market Incumbents: Entrench multi-site deployment contract capture through standardized specifications across twelve to fifteen treatment rooms per Beijing-Tianjin-Hebei clinic chain. Deepen backward integration into laser cavity assembly production within Suzhou industrial parks to reduce import dependency exposure. NMPA-mandated operator training backlogs in Jiangsu and Zhejiang constrain clinic expansion timelines, creating defensive moats for established service networks. For New Entrants and Emerging Players: Pursue the Chengdu-Chongqing aesthetic corridor where clinic density remains one-third of coastal levels and provincial procurement consortium pilots aggregate demand into volume tenders. Target AI-assisted treatment parameter optimization as a differentiable capability enabling novice technicians to deliver specialist-grade outcomes. Deploy regional service network density as the primary go-to-market angle, prioritizing maintenance relationship stickiness over initial equipment margin capture. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among platform integrators with captive consumable attachment ecosystems and predictive maintenance algorithm deployment. Long-term viability over a five-to-ten year window favors manufacturers with established NMPA Class III registration pathways and captive clinical investigation organizations. The signal to watch is provincial reimbursement discussion progress in tier-two cities that could reshape addressable demand geography.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Clinical Investigation Organization Establishment | Accelerates NMPA Class III registration timelines for high-power laser platforms exceeding joule thresholds. |
| AI-Assisted Treatment Parameter Integration | Enables standardization across multi-site clinic deployments while compressing technician training requirements. |
| Disposable Handpiece Attachment Ecosystem | Converts capital expenditure into predictable per-treatment consumable costs with sub-eighteen-month payback. |
| Regional Service Network Density Buildout | Sustains repeat equipment orders through maintenance relationships in underpenetrated western provinces. |
| Predictive Maintenance Algorithm Deployment | Transforms capital sales into ongoing technical relationships while reducing clinic downtime costs. |
Research Methodology
Cross-validation between primary interviews with NMPA regulatory affairs specialists, biomedical engineers at hospital-affiliated aesthetic centers, and clinic procurement committee directors anchors the qualitative findings. Secondary validation draws from NMPA medical device registration databases, SAMR post-market surveillance reports, and GB standards documentation for energy-based equipment. Bottom-up equipment shipment tracking and top-down clinic licensing data triangulate market sizing.
Calibration against historical NMPA registration timelines and installed base replacement cycles shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include equipment product type, clinical application, end-user facility tier, and technology regulatory classification. CAGRs derive from equipment replacement velocity differentials and consumable attachment revenue trajectories. Forecast inputs incorporate municipal health commission clinic permit expansion rates and provincial procurement consortium pilot progress.
Macroeconomic conditions sit as an overlay; deviation in RMB exchange rate volatility or euro-denominated optical component pricing would shift the trajectory. Forecasts reflect documented assumptions regarding NMPA review pathway efficiency and tier-two city licensing waves. Cross-checking against hospital procurement database benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aesthetic Medicine
Aesthetics Combination Therapy Market
Aesthetic Medicine
Aesthetic Lasers and Energy Devices Market
Aesthetic Medicine
Global Cellulite Treatment Market
Aesthetic Medicine
Middle East and Africa Aesthetic Dermatology Market
Aesthetic Medicine
Global Buttock Augmentation Market
Aesthetic Medicine
Phototherapy Lamps and Units for Aesthetic Medicine Market
Aesthetic Medicine
Middle East and Africa Dermal Fillers Market
Aesthetic Medicine
Spain Facial Aesthetics Market
Aesthetic Medicine
North America Aesthetic Dermatology Market
Aesthetic Medicine
UAE Laser Hair Removal Market
Aesthetic Medicine
Body Contouring Market
Aesthetic Medicine
Alexandrite Laser Treatment Market
Aesthetic Medicine
Medical Aesthetic Dermal Filler Market
Aesthetic Medicine
Asia-Pacific Aesthetic Dermatology Market
Aesthetic Medicine
Global Aesthetic Threads Market
Aesthetic Medicine
Platysmaplasty Treatment Market