
 Sneaker Identification Service Market | 2026-2036
Sneaker Identification Service Market Size, Share, and Industry Trends Forecast 2026-2036
Sneaker Identification Service Market Insights
Artificial intelligence image recognition is decoupling sneaker identification from manual labor, collapsing per-unit verification costs and enabling platform scale. StockX leverages proprietary computer vision pipelines to authenticate high-volume resale transactions. Goat sustains premium positioning through hybrid human-AI verification protocols. CheckCheck competes via mobile-first architecture that democratizes access for individual collectors.
A sneaker identification service applies forensic analysis, spectral imaging, and database cross-referencing to determine authenticity, condition grade, and market value of footwear. These systems process stitching patterns, material composition, and factory codes against manufacturer reference sets to issue tamper-evident certification. Verification services dominate transaction volume across resale platforms, while blockchain-based provenance tracking captures the fastest expansion as collectors demand immutable ownership records. AI-Based technology leads R&D investment intensity, though mobile app distribution anchors consumer accessibility.
The US Federal Trade Commission polices counterfeit commerce and deceptive authentication claims, while China's SAMR enforces anti-counterfeiting standards on domestic resale platforms. The EU's proposed Digital Product Passport framework will mandate traceability data for imported footwear, directly shaping compliance architecture for identification services. Stakeholders must monitor regulatory fragmentation between jurisdictions and decide whether to build modular compliance stacks or pursue geographic specialization.
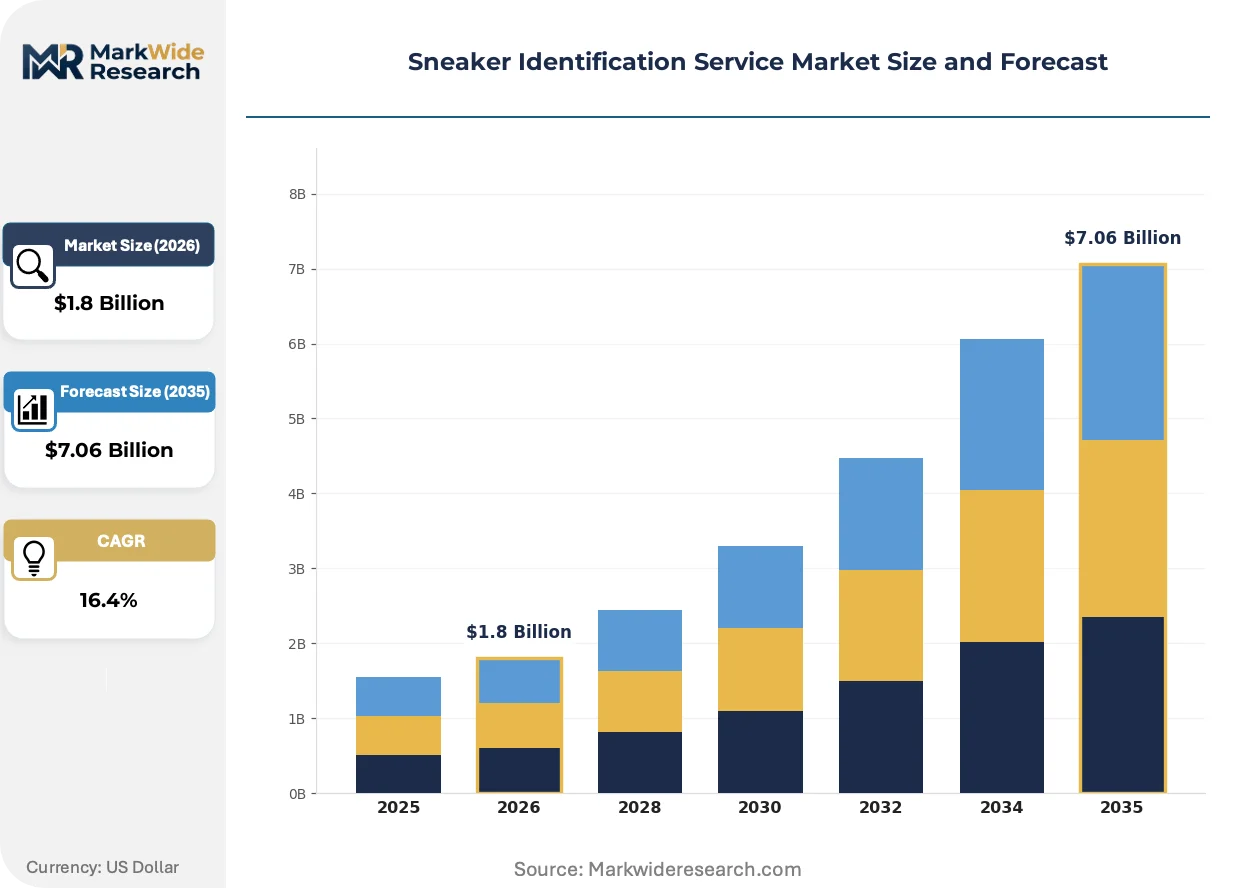
Market Dynamics
AI image recognition is collapsing authentication costs while blockchain provenance creates new compliance architectures, forcing identification services to rebuild around automated verification pipelines and immutable ownership records rather than manual expertise.
Growth Catalysts
- EU Digital Product Passport:The proposed framework mandates traceability data for imported footwear, compelling identification services to develop modular compliance stacks for European market access.
- Resale platform volume:Secondary market transaction density generates authentication demand that scales beyond human verifier capacity, necessitating automated pipeline deployment.
- Spectral imaging:Non-destructive material analysis enables factory-grade verification without physical destruction, expanding serviceable sneaker categories and collector willingness to submit items.
Market Restraints
- Reference database concentration:Authentic sneaker datasets remain concentrated among manufacturer archives and a handful of private collectors, creating bottleneck risk for AI training pipelines.
- Hardware cost volatility:GPU clusters and edge computing devices required for real-time image recognition face semiconductor supply constraints and tariff exposure.
- Regulatory fragmentation:Divergent anti-counterfeiting enforcement between the US FTC, China's SAMR, and EU frameworks forces multi-jurisdictional compliance investment without harmonized standards.
Strategic Opportunities
- India resale emergence:Urban sneaker collecting in Mumbai and Delhi remains underserved by professional authentication, creating first-mover advantage for mobile-first verification deployment.
- Cross-technology convergence:Near-field communication chips embedded by manufacturers is converging with blockchain provenance to enable tap-to-verify consumer experiences that bypass photographic submission entirely.
- Insurance underwriting:High-value sneaker policies require certified appraisal, opening B2B channels with specialty insurers seeking standardized condition grading.
Industry Challenges
- Forensic talent scarcity:Stitching-pattern analysis and factory-code interpretation require skills that AI augmentation has disincentivized new entrants from developing, creating human-AI handoff friction.
- Legacy platform integration:Established resale marketplaces operate on authentication workflows that resist modular API insertion, forcing custom engineering for each deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sneaker Identification Service Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.06 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Verification, Authentication, Valuation, Tracking Customer Type: Collectibles, Retailers, Enthusiasts, Investors Technology: AI-Based, Blockchain, Mobile App, Web Platform Distribution Channel: Online, In-Store, Events, Direct Sales |
| Companies Covered | Sneaker-Index, Dewu, Goat, StockX, Nice, Knowin, Legit Check, Farfetch, CheckCheck, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sneaker Identification Service Market Trends and Innovations
Authentication technology is bifurcating between high-volume automated pipelines and premium hybrid verification, while regulatory pressure on product traceability accelerates investment in permanent digital identity infrastructure.
Computer vision architectures trained on manufacturer defect databases is converging with mobile edge deployment to enable instant authentication without cloud latency. Individual collectors and small resellers adopt these tools fastest, compressing the addressable market for manual verification services and forcing platform differentiation toward hybrid human-AI protocols for high-value items.
China's SAMR enforcement of anti-counterfeiting standards on domestic resale platforms mandates documented authentication chains for cross-border transactions. This regulatory pressure is pushing identification services to build compliant data architectures that satisfy both Chinese export requirements and destination market import rules, with footwear facing stricter scrutiny than apparel categories.
Collector procurement patterns increasingly prioritize pre-authenticated inventory over raw secondary market sourcing, compressing the verification timeline from post-purchase to pre-listing. This shift is visible most acutely in the United States and United Kingdom, where platform-embedded authentication has become a default expectation rather than a premium add-on, forcing independent services to integrate directly into listing workflows or face channel exclusion.
Sneaker Identification Service Market Segmentation
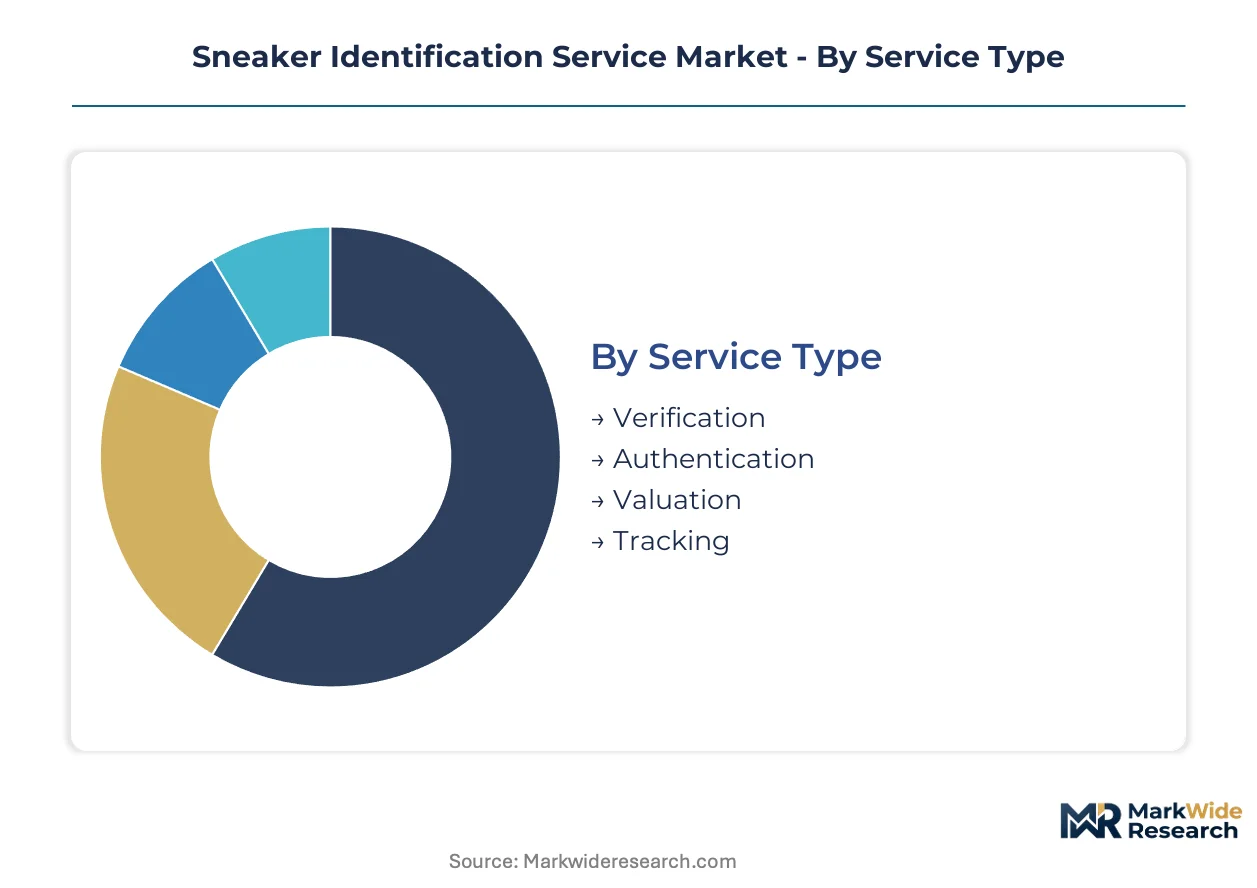
Segmentation in sneaker identification services reveals how certification burdens, technology costs, and customer risk profiles fragment pricing and compliance architectures across the value chain. Each dimension carries distinct regulatory exposure and margin structures that shape platform strategy.
Service Type:
Certification burden concentrates heaviest in segments requiring tamper-evident documentation and legal defensibility against counterfeit claims.
- Verification:Basic authenticity confirmation through visual inspection and database cross-reference. Demand clusters on high-volume resale platforms in the United States where FTC enforcement of deceptive commerce claims elevates liability exposure for undocumented sales.
- Authentication:Forensic-grade analysis incorporating spectral imaging, stitching-pattern recognition, and factory-code verification against manufacturer reference sets. This tier commands premium pricing from collectors in the United Kingdom seeking insurance-grade documentation for high-value inventory.
- Valuation:Market price assessment combining condition grading with transaction history analysis. Investors in China utilize these services to establish collateral value for secured lending against sneaker portfolios.
- Tracking:Ownership chain documentation and provenance logging, increasingly blockchain-anchored. Collectibles specialists in the United States drive adoption as immutable records become default expectation for trophy acquisitions.
Leading the category by volume: Verification. Growing fastest: Tracking.
Customer Type:
Cost tolerance and repeat purchase frequency separate segments, with institutional buyers absorbing fixed platform fees that individual enthusiasts reject.
- Collectibles:High-net-worth individuals acquiring rare or limited-edition footwear as alternative assets. These customers in the United Kingdom and United States demand white-glove service tiers with dedicated account management and expedited turnaround.
- Retailers:Brick-and-mortar and online sellers requiring batch verification for inventory acquisition. Retailers in China face SAMR-mandated authentication chains for cross-border transactions, forcing platform integration investments.
- Enthusiasts:Individual collectors with moderate transaction volumes and price sensitivity. Mobile-first solutions capture this segment through per-use micropricing rather than subscription models.
- Investors:Financial actors treating sneakers as securitized assets. These customers in the United States require standardized condition grading compatible with specialty insurance underwriting and custodial storage protocols.
Dominating revenue contribution: Collectibles. Expanding most quickly: Investors.
Technology:
Development intensity and infrastructure requirements stratify competitive entry barriers, with capital-heavy segments consolidating around well-funded platforms.
- AI-Based:Computer vision pipelines trained on manufacturer defect databases enabling automated authentication at scale. Deployment concentrates in the United States where GPU cluster availability and technical talent pools support real-time image recognition.
- Blockchain:Distributed ledger systems anchoring provenance records and enabling smart-contract-based ownership transfer. Adoption accelerates among collectors in the United Kingdom seeking permanent, platform-agnostic documentation.
- Mobile App:Edge-computing verification tools enabling instant authentication without cloud dependency. Enthusiasts in China and the United States drive volume through download-driven user acquisition models.
- Web Platform:Browser-based submission workflows with human verifier review queues. Legacy architecture serves retailers requiring batch upload capabilities and API integration with inventory management systems.
Highest R&D concentration: AI-Based. Gaining share fastest: Blockchain.
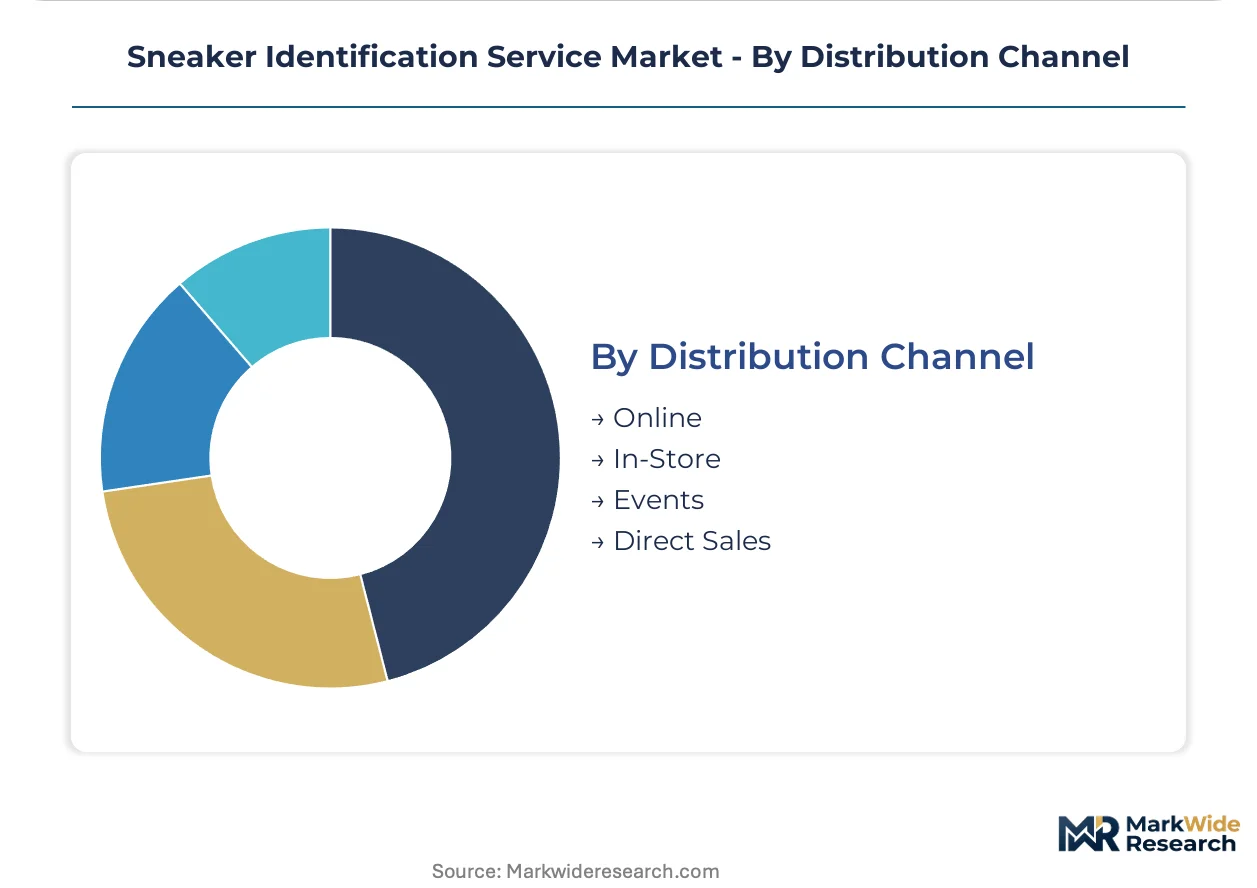
Distribution Channel:
Physical presence requirements and customer acquisition economics determine channel viability, with hybrid models emerging to capture trust-sensitive transactions.
- Online:Digital-first submission and return logistics dominating transaction volume. Platforms in the United States optimize this channel through prepaid shipping and photographic pre-screening to reduce rejection rates.
- In-Store:Physical verification stations offering immediate authentication and same-day pickup. Retailers in China deploy these locations to satisfy SAMR documentation requirements while building customer trust.
- Events:Pop-up authentication at sneaker conventions and trade shows. Collectors in the United Kingdom utilize these touchpoints for high-value acquisitions requiring on-site verification before cash settlement.
- Direct Sales:White-label authentication services embedded in private transactions between individual buyers and sellers. This channel grows through API partnerships with peer-to-peer marketplaces seeking to reduce dispute resolution costs.
Capturing majority volume: Online. Steepest expansion trajectory: Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Collector density and resale platform maturity concentrate demand in the United States, China, and the United Kingdom, with authentication infrastructure investments scaling fastest where regulatory enforcement elevates liability for undocumented transactions.
United States
FTC enforcement of deceptive commerce claims drives platform-embedded authentication adoption, with StockX and Goat operating high-volume verification pipelines in Detroit and Los Angeles. The country's national consumer protection regulator polices counterfeit claims aggressively. Collector procurement in New York and Miami now defaults to pre-authenticated inventory, compressing verification timelines from post-purchase to pre-listing.
China
SAMR-mandated authentication chains for cross-border transactions force platform integration investments, with Dewu deploying compliant data architectures in Shanghai and Beijing. The country's market regulator enforces anti-counterfeiting standards that exceed apparel category scrutiny. Spectral imaging adoption concentrates in Shenzhen manufacturing corridors where factory-grade verification enables non-destructive analysis.
United Kingdom
EU Digital Product Passport preparation compels modular compliance stack development, with London collectors driving blockchain provenance adoption for trophy acquisitions. The proposed framework mandates traceability data for imported footwear. Authentication services in Manchester and Birmingham integrate directly into listing workflows as platform-embedded verification becomes default expectation.
Japan
High-net-worth collector demand for white-glove service tiers sustains premium hybrid verification, with METI-indicated standards shaping quality expectations in Tokyo and Osaka. The country's ministry of economy, trade and industry influences certification benchmarks. Forensic-grade analysis commands insurance-grade documentation premiums in Kansai region trophy markets.
Germany
Industrial machinery expertise feeds spectral imaging equipment supply chains, with Bavaria-based precision optics manufacturers exporting to global authentication platforms. CE marking requirements for electronic verification devices shape hardware compliance. Collector enthusiasm in Berlin and Hamburg drives demand for permanent digital identity infrastructure as regulatory pressure accelerates.
Sneaker Identification Service Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with platform-embedded services capturing volume while independent verification tools compete on accessibility. The vendor base stratifies around three strategic archetypes: high-volume automated pipelines, premium hybrid human-AI protocols, and mobile-first democratization tools. Dominant competitive moves include API integration partnerships with resale marketplaces and edge-computing deployment for instant authentication without cloud dependency.
Among platform-embedded specialists, StockX and Goat exemplify the automated-to-hybrid spectrum, with the former representing high-volume pipeline efficiency and the latter occupying premium positioning through human-AI verification protocols. CheckCheck anchors the mobile-first democratization tier, enabling individual collector access through per-use micropricing rather than subscription models. These three entities collectively illustrate how technology deployment choices—cloud versus edge, automated versus hybrid, platform-embedded versus standalone—determine competitive segmentation and customer acquisition economics.
| Leading Market Players |
|---|
| Sneaker-Index |
| Dewu |
| Goat |
| StockX |
| Nice |
| Knowin |
| Legit Check |
| Farfetch |
| CheckCheck |
| Others |
Pricing and Supply Chain Analysis
Forensic talent concentration in Shenzhen and Los Angeles creates labor-cost differentials that stretch pricing-tier spreads between automated verification and hybrid human-AI protocols. Authentication services source stitching-pattern analysts and spectral imaging technicians from these pools, with wage arbitrage enabling platform-embedded services to undercut premium white-glove offerings.
Pricing Analysis
Volume-driven verification commands thin margins through per-unit micropricing on resale platforms, while forensic-grade authentication sustains premium spreads through insurance-grade documentation and dedicated account management. Price differentiation hinges on certification burden—tamper-evident legal defensibility against FTC deceptive commerce claims—and turnaround urgency, with same-day service capturing 3-4x standard rates. Pricing pressure stems from mobile-first edge computing tools collapsing per-authentication costs for individual collectors. Enthusiasts exhibit highest price sensitivity, rejecting subscription models for per-use pricing; collectibles investors absorb fixed platform fees without volume negotiation.
Supply Chain Analysis
Workforce availability for computer vision engineers and forensic analysts concentrates in the United States, China, and Germany, with GPU cluster deployment scaling fastest where technical talent pools support real-time image recognition pipelines. Hardware inputs draw from Taiwan semiconductor fabs, Bavaria precision optics manufacturers, and Shenzhen edge computing device assemblers. Supply chain risk centers on single-source vulnerability for manufacturer defect databases held by Nike, Adidas, and private archive collectors. Distribution runs through platform-embedded APIs, direct mobile app downloads, and white-label partnerships with peer-to-peer marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a supply-constrained story where reference database concentration props pricing power for incumbent platforms. Scarce manufacturer defect archives and forensic-trained human verifiers create capacity bottlenecks that sustain margin structures despite automation pressure.
For Market Incumbents: Cement platform-embedded authentication through exclusive API partnerships with high-volume resale marketplaces, locking out modular insertion by competitors. Acquire spectral imaging equipment suppliers in Germany to secure hardware cost advantages and CE marking compliance. Counter the threat of mobile-first democratization tools by embedding edge-computing verification into listing workflows before CheckCheck captures enthusiast migration. For New Entrants and Emerging Players: The price-point gap between premium hybrid verification and economy mobile apps creates entry space for mid-tier offerings combining AI automation with limited human oversight. Target India's underserved Mumbai and Delhi collector bases through localized mobile-first deployment before Dewu extends cross-border infrastructure. Pursue white-label B2B channels with specialty insurers seeking standardized condition grading for sneaker portfolio collateralization. For Investors and Strategic Acquirers: The window for entry favors vertically integrated authentication platforms with captive reference database access and compliant data architectures for SAMR and EU Digital Product Passport requirements. Long-term viability rests on convergence between NFC chip embedding by manufacturers and blockchain provenance systems, enabling tap-to-verify bypass of photographic submission entirely. Watch for regulatory harmonization signals between US FTC, China's SAMR, and EU frameworks as inflection indicator for compliance stack consolidation plays.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Provenance Integration | Immutable ownership records satisfy EU Digital Product Passport traceability mandates for imported footwear. |
| Edge Computing Deployment | Instant mobile authentication without cloud latency captures price-sensitive enthusiast segments from platform incumbents. |
| Manufacturer Database Licensing | Exclusive access to Nike or Adidas defect archives creates insurmountable training data moats for AI pipelines. |
| Insurance Partnership Channel | B2B authentication integration with specialty underwriters opens collateralized lending against sneaker portfolios. |
| NFC Chip Convergence | Tap-to-verify consumer experiences bypass photographic submission entirely, collapsing per-authentication labor costs. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combined with primary interviews across platform authentication executives, forensic verification specialists, resale marketplace operations directors, and collector community organizers. SEC filings from StockX and Goat, SAMR enforcement bulletins, and EU Digital Product Passport consultation documents supplied secondary validation. Bottom-up triangulation against top-down market sizing checked for consistency across service type, customer segment, and technology deployment dimensions.
Granularity-level modeling operated at the intersection of certification tier, customer risk profile, and regional regulatory cluster, with value and volume outputs derived through multiplicative frameworks across the projection horizon. CAGRs emerged from segment-level growth rate synthesis rather than single-point extrapolation. AI training pipeline costs, blockchain infrastructure deployment curves, and mobile app download velocity served as industry-specific forecast inputs alongside resale platform transaction density metrics.
Inputs from FTC enforcement actions, SAMR compliance directives, and EU regulatory consultations were available through the study window; gaps in manufacturer defect database access terms and proprietary computer vision training methodologies introduce uncertainty bands around AI-based segment projections. Forecasts reflect documented assumptions regarding regulatory harmonization timelines and hardware cost trajectories. Material deviation in SAMR cross-border enforcement intensity, GPU cluster supply availability, or EU Digital Product Passport implementation scope warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Footwear
Sneakers Market
Footwear
Breathable Mesh Running Shoes Market
Footwear
Water Shoes Market
Footwear
US Slip Resistant Shoes Market
Footwear
Duck Boots Market
Footwear
Waterproof Sneakers Market
Footwear
Formal Shoes Market
Footwear
Football Shoes Market
Footwear
Running Shoes Market
Footwear
Protective Footwear Market
Footwear
Orthopedic Footwear Market
Footwear
Kids Barefoot Shoes Market
Footwear
Trail Running Shoes Market
Footwear
Western Boots Market
Footwear
Asia-Pacific Athletic Footwear Market
Footwear
North America Footwear Market