
 Golf Footwear Market | 2026-2036
Golf Footwear Market Size, Share, and Industry Trends Forecast 2026-2036
Golf Footwear Market Analysis
The capital-intensity gap between heritage manufacturers and digital-native entrants is rotating competitive advantage toward vertically integrated supply chains. FootJoy leverages its domestic manufacturing footprint to sustain rapid replenishment cycles for pro-shop channels. Nike competes through materials science partnerships that anchor its position in the spikeless performance category. Adidas differentiates via athlete endorsement density that extends brand visibility across professional tournament broadcasts.
Golf footwear encompasses specialized athletic shoes engineered with cleated or spikeless outsoles, waterproof uppers, and torsional stability plates to maintain traction and biomechanical control across varied turf conditions. Leather uppers treated with hydrophobic coatings remain the dominant construction standard for premium products, though knit textiles and synthetic microfibers are gaining share in lightweight warm-weather designs. The men's segment still occupies the largest revenue pool, yet the women's category registers the fastest structural expansion as brands resize lasts and broaden color offerings beyond traditional palettes. Mid-range price tiers capture the highest unit volumes, though premium leather constructions concentrate margin pools through replacement-cycle compression among serious amateurs.
The Consumer Product Safety Commission governs chemical content in footwear adhesives and synthetic materials, while ISO 20344 standards for slip resistance influence outsole design specifications across export-bound production. California's Proposition 65 disclosure requirements affect labeling practices for products containing chromium-tanned leathers, adding compliance costs for brands serving that state. Stakeholders must monitor how state-level chemical restrictions proliferate beyond California, as fragmented regulatory landscapes could force SKU proliferation or material reformulation investments that reshape cost structures.
Market Dynamics
Waterproof membrane technologies from Gore-Tex and competing suppliers are compressing replacement cycles while elevating performance baselines across all price tiers, forcing manufacturers to recalibrate material sourcing and margin structures.
Growth Catalysts
- Recreational golfer expansion:Participation broadening beyond traditional country club demographics is creating new volume pools in mid-range price tiers.
- California Proposition 65:Disclosure requirements for chromium-tanned leathers are accelerating industry-wide migration toward alternative tanning processes.
- Spikeless outsole innovation:Traction plate engineering advances are displacing traditional cleated designs in casual-course environments.
Market Restraints
- Raw material concentration:Premium full-grain leather supply concentrates in Italian and Argentinian tanneries, exposing brands to hide price volatility.
- SKU proliferation costs:State-level chemical restriction fragmentation forces material reformulation investments that compress operating margins.
- Athleisure substitution:Cross-training footwear with adequate traction is capturing casual-round occasions from dedicated golf purchases.
Strategic Opportunities
- Women's category white space:Resized lasts and expanded color palettes can capture the fastest-structural expansion segment in North American retail.
- Direct-to-consumer channel buildout:Bypassing wholesale margin extraction enables premium positioning without price tier escalation.
- Warm-weather textile penetration:Knit uppers and synthetic microfibers offer lightweight alternatives for humid-climate courses in Southeast Asia.
Industry Challenges
- Biomechanical engineering talent scarcity:Specialized footwear designers with turf-traction expertise command premium compensation in competitive labor markets.
- Pro-shop inventory velocity:Rapid replenishment cycles for course-retail channels strain working capital and forecasting accuracy.
- ISO 20344 certification timelines:Slip resistance testing protocols delay product launches for export-bound production runs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Golf Footwear Market |
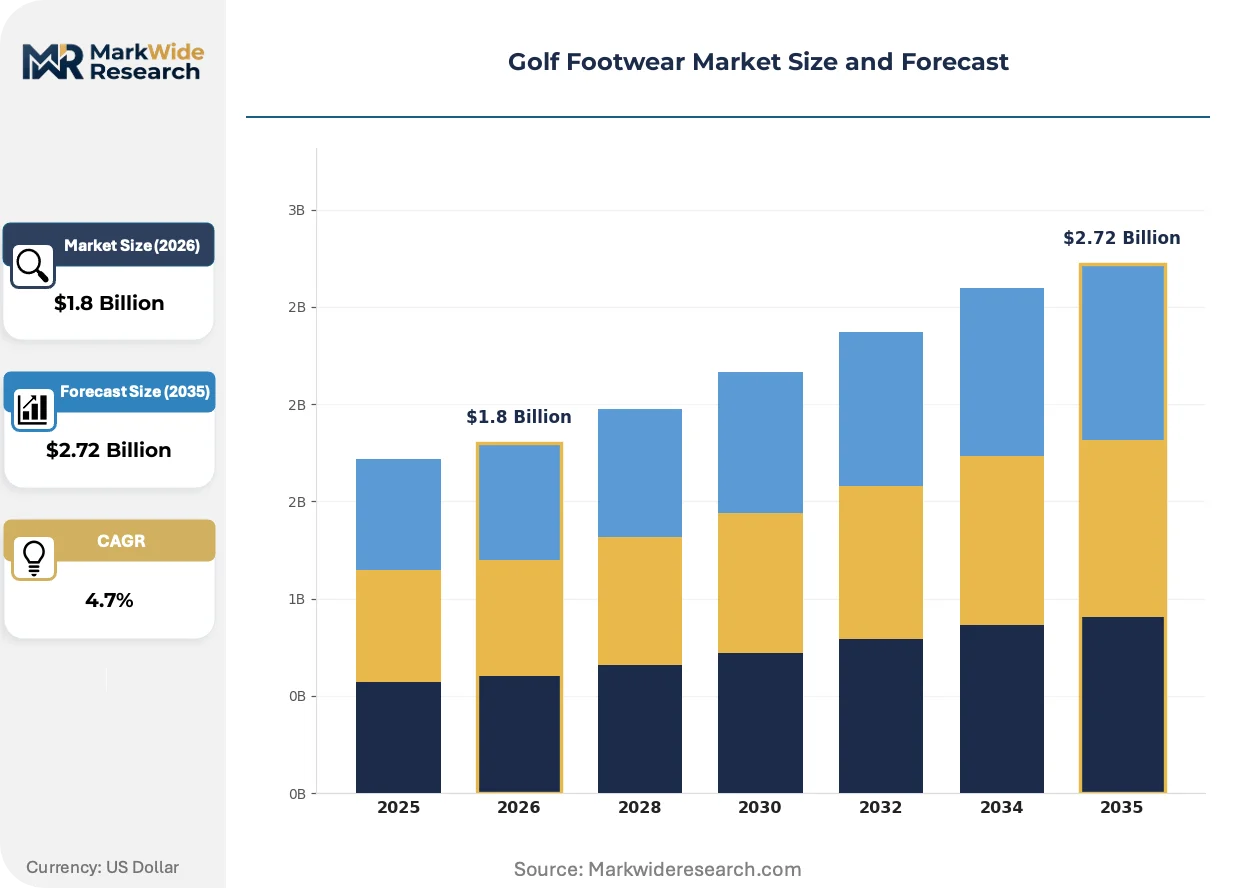
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shoes, Sandals, Cleats, Boots Material: Leather, Synthetic, Textile, Rubber End User: Men, Women, Youth, Professionals Price Tier: Premium, Mid-range, Budget, Discounted |
| Companies Covered | Puma, Under Armour, FootJoy, G/FORE, Skechers, Nike, Ecco, TRUE Linkswear, Adidas, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Golf Footwear Market Emerging Trajectories
Material science partnerships and membrane integration are redrawing competitive boundaries between heritage manufacturers and technology-forward entrants. Three forces are actively restructuring how performance attributes translate to purchase decisions.
Spikeless traction systems employing thermoplastic polyurethane plates is decomposing the traditional cleat-replacement revenue model. Recreational golfers in North America and Western Europe are adopting these designs for dual-use walking comfort. The technology is compressing aftermarket accessory sales while elevating upfront product price tolerance.
REACH restrictions on per- and polyfluoroalkyl substances are forcing reformulation of water-repellent treatments across European export production. The industrial consequence extends to supply chain requalification costs for adhesive and coating suppliers. Premium leather constructions face the steepest compliance burden, accelerating synthetic material adoption in mid-tier products.
Course-proximity retail is losing share to specialty athletic footwear chains and brand-owned digital storefronts. Pro-shop buyers now concentrate on immediate-play emergency purchases while planned replacements migrate to comparison-shopping environments. This channel rotation is most visible in United States metropolitan markets with dense off-course retail infrastructure.
Golf Footwear Market Segmentation
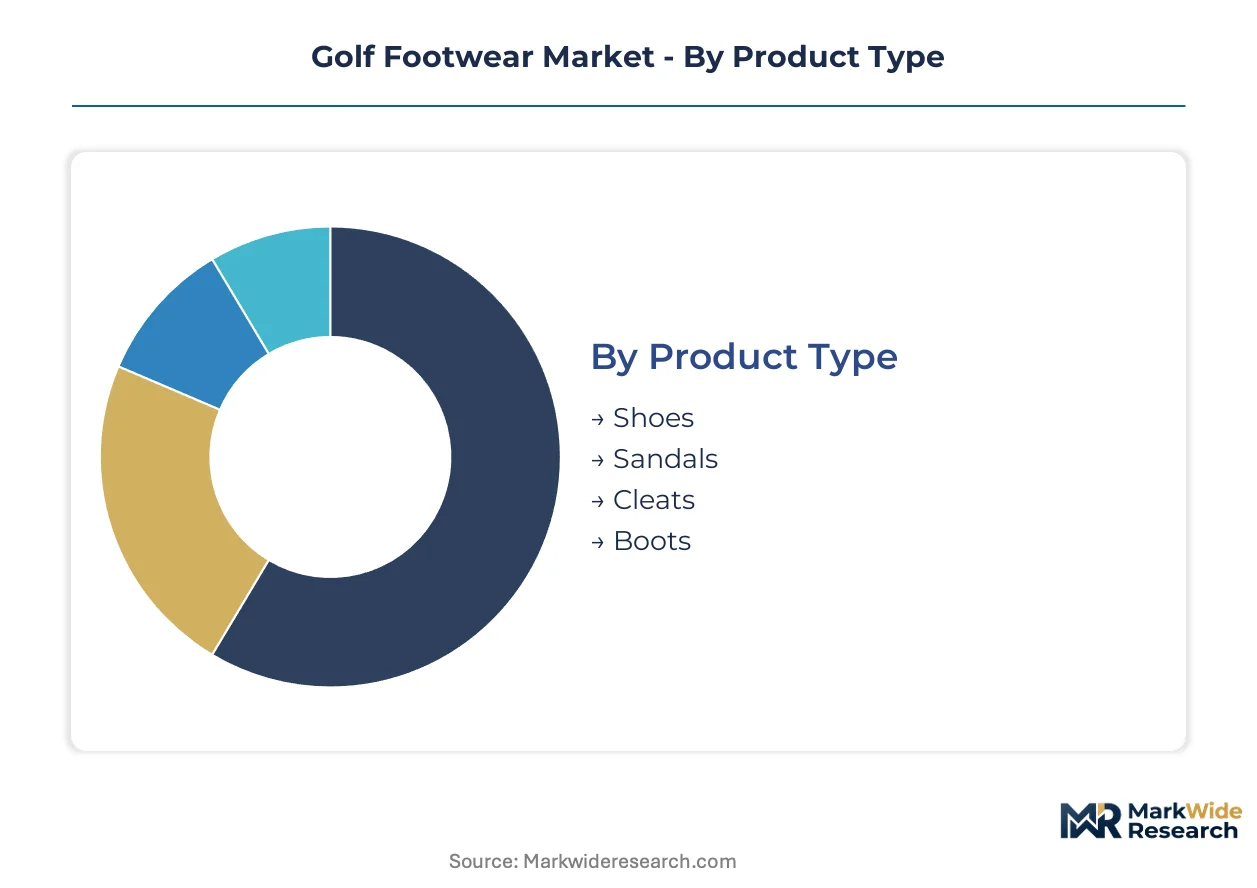
Segmentation in golf footwear determines channel strategy and margin architecture. Product construction dictates whether units flow through pro-shop impulse purchases or planned replacement cycles at specialty retail. Material choices and price positioning further stratify inventory velocity across course-proximity versus off-course channels.
Product Type:
Channel mix varies sharply by construction—closed-toe athletic designs dominate planned purchases at off-course retailers, while open-toe and weather-adaptive formats concentrate in course-proximity emergency buying.
- Shoes:Encompasses both traditional cleated and spikeless constructions with waterproof membrane integration. Demand concentrates in the United States among recreational golfers seeking dual-use walking comfort, with spikeless variants displacing cleated designs in metropolitan markets with dense off-course retail infrastructure.
- Cleats:Traditional removable-stud systems employing thermoplastic polyurethane or metal interfaces for maximum turf penetration. Tournament professionals and competitive amateurs in Florida and Arizona sustain demand despite compression from spikeless alternatives in casual-round environments.
- Sandals:Open-toe designs with molded traction surfaces for warm-climate practice sessions. Spikeless traction plates from TPU suppliers enable limited on-course use.
- Boots:Ankle-height waterproof constructions for winter play and links-style courses with heavy dew conditions. Gore-Tex membrane integration elevates price positioning.
Shoes dominate installed base. Cleats is where expansion concentrates for competitive segments, while sandals and boots occupy niche volume pools.
Material:
Cost tier alignment drives procurement patterns—premium constructions source from concentrated tanneries, while synthetic and textile alternatives enable margin flexibility in mid-range positioning.
- Leather:Full-grain and corrected-grain uppers treated with hydrophobic coatings remain the construction standard for premium products. Italian and Argentinian tanneries supply hides, exposing brands to price volatility that compresses operating margins during supply shocks.
- Synthetic:Microfiber and polyurethane constructions offering waterproof performance without chromium-tanning compliance burdens. REACH restrictions on per- and polyfluoroalkyl substances are accelerating synthetic adoption in European export production.
- Textile:Knit uppers and engineered mesh for lightweight warm-weather designs. Southeast Asian humidity drives demand concentration in Singapore and Malaysian markets.
- Rubber:Molded outsole compounds and waterproof bootie constructions for budget-tier waterproofing. Commodity price exposure is lower than leather inputs.
Leather commands premium positioning. Synthetic is climbing the fastest as regulatory compliance costs reshape material selection.
End User:
Customer type determines sizing infrastructure and color palette breadth, with women's category expansion requiring resized lasts beyond simple colorway extension.
- Men:Occupies the largest revenue pool with standardized lasts and conservative color offerings. Replacement cycles compress among serious amateurs with multiple pairs for varying conditions.
- Women:Fastest-structural expansion segment as brands resize lasts and broaden color offerings beyond traditional palettes. North American retail white space exists in metropolitan markets with growing female participation rates.
- Youth:Sized-down constructions with simplified closure systems and accelerated replacement due to foot growth. Price sensitivity concentrates demand in mid-range and budget tiers.
- Professionals:Custom-fitted tour-issue products with athlete endorsement visibility driving brand preference among aspirational purchasers. Tournament broadcast exposure extends reach beyond direct sales volume.
Men dominate installed base. Women is where expansion concentrates for structural growth.
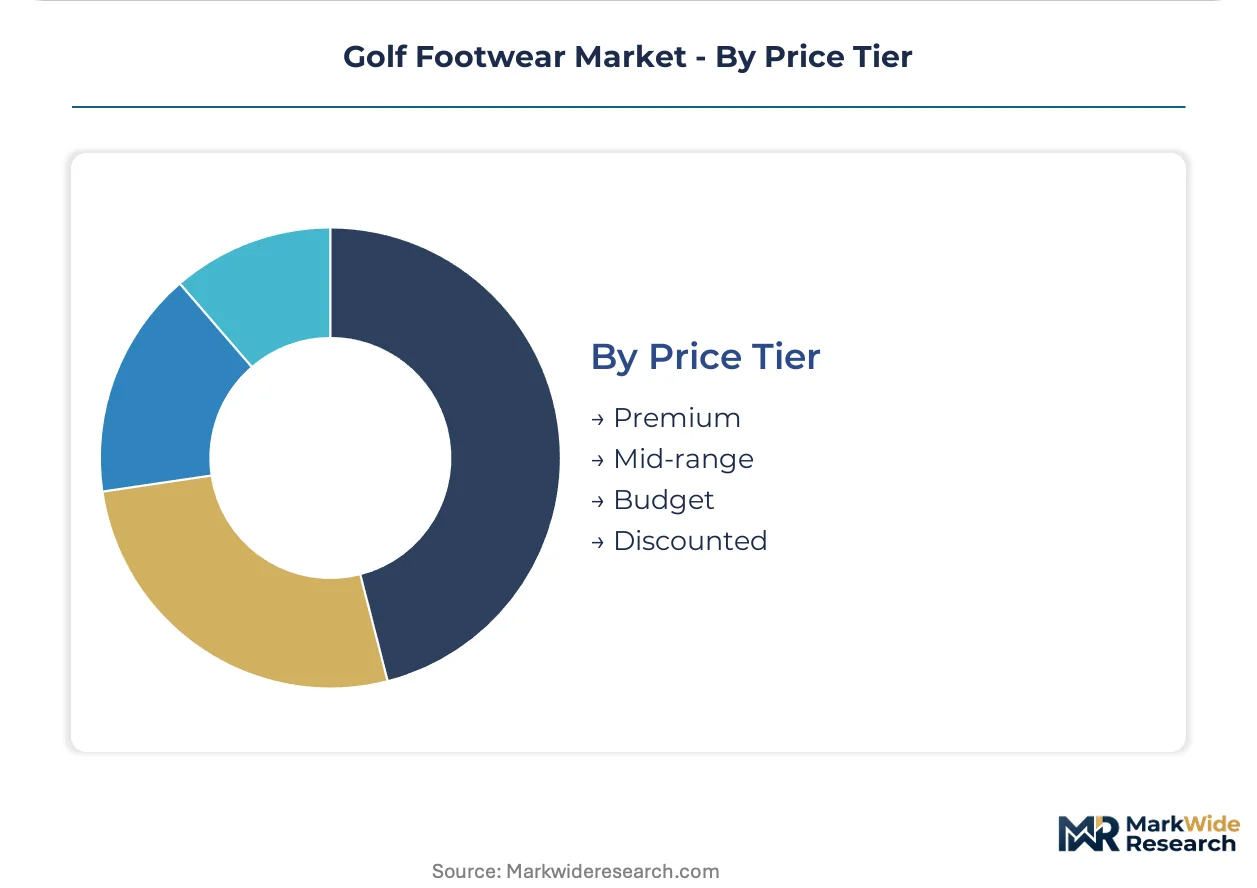
Price Tier:
Margin architecture stratifies across construction quality and membrane technology, with three-tier pricing separating waterproof-breathable systems from basic coated constructions.
- Premium:Full-grain leather uppers with Gore-Tex or equivalent membrane integration, torsional stability plates, and pro-shop service levels. Concentrates margin pools through replacement-cycle compression among serious amateurs.
- Mid-range:Synthetic leather or coated textile constructions with basic waterproofing for recreational golfers entering the category. Captures highest unit volumes as participation broadens beyond traditional country club demographics.
- Budget:PVC or basic rubber constructions without membrane technology for occasional players and practice facility use. Price elasticity sustains volume in economic downturns.
- Discounted:Closeout inventory and prior-season colorways through outlet channels and digital flash sales. Inventory clearance function rather than strategic positioning.
Mid-range captures volume leadership. Premium is where margin expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Southeast Asia and Latin America exhibit the highest price elasticity, while United States and Japanese consumers absorb premium waterproof membrane technologies with minimal volume sensitivity. This demand-elasticity contrast shapes regional channel strategies and product mix decisions.
United States
Recreational golfer expansion beyond country club demographics drives mid-range volume growth, with metropolitan markets like Phoenix and Orlando supporting spikeless adoption for dual-use walking comfort. The Consumer Product Safety Commission governs chemical content in adhesives, while California's Proposition 65 disclosure requirements for chromium-tanned leathers accelerate alternative tanning migration. Carlsbad, California anchors a cluster of performance footwear R&D facilities where membrane integration testing occurs.
Japan
Serious amateur replacement-cycle compression sustains premium leather demand despite demographic headwinds, with tournament broadcast visibility reinforcing brand preference among aspirational purchasers. METI oversees industrial standards alignment with ISO 20344 slip resistance protocols that influence outsole design specifications. The Kansai region around Osaka concentrates domestic distribution infrastructure for specialty athletic retail channels.
Germany
REACH restrictions on per- and polyfluoroalkyl substances force water-repellent treatment reformulation across European export production, elevating compliance costs for premium leather constructions. ECHA chemical registration requirements drive supply chain requalification investments among adhesive and coating suppliers. Bavaria hosts precision outsole engineering facilities serving continental tournament professional demand.
United Kingdom
Links-style course conditions sustain demand for ankle-height waterproof boots with Gore-Tex membrane integration, particularly in Scotland and coastal England where heavy dew prevails. CE marking requirements for personal protective equipment influence product safety documentation practices. St. Andrews and surrounding Fife region concentrate heritage manufacturing knowledge for traditional cleated constructions.
South Korea
Humid summer conditions drive lightweight textile upper adoption among recreational segments, with Seoul Capital Area retail infrastructure supporting rapid style rotation. MFDS chemical safety assessments apply to imported footwear materials, adding documentation layers for foreign brands. Busan-Ulsan industrial corridor houses synthetic microfiber production capacity serving regional warm-weather demand.
Golf Footwear Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure where heritage manufacturers compete on materials science partnerships and digital-native entrants optimize direct-to-consumer channel economics. The market consolidates around three strategic groupings: vertically integrated domestic producers with rapid replenishment capabilities, global athletic brands leveraging athlete endorsement density, and specialized golf-native labels emphasizing course-culture authenticity. Dominant competitive moves include membrane technology licensing agreements and portfolio diversification into spikeless traction systems that compress traditional cleat-replacement revenue models.
Within the heritage manufacturer tier, FootJoy and Ecco occupy positions defined by manufacturing footprint control and European leather supply relationships respectively. Among global athletic brands, Nike and Adidas exemplify divergent strategies—materials science anchoring versus broadcast visibility extension. Puma sits within the specialty athletic tier, representing the archetype of cross-category sportswear houses adapting golf-specific traction engineering.
| Leading Market Players |
|---|
| Puma |
| Under Armour |
| FootJoy |
| G/FORE |
| Skechers |
| Nike |
| Ecco |
| TRUE Linkswear |
| Adidas |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements with Italian and Argentinian tanneries lock in premium full-grain leather access while anchoring price visibility for heritage manufacturers serving serious amateur segments. These contractual structures insulate FootJoy and Ecco from hide price volatility that compresses margins for spot-market dependent competitors, yet simultaneously constrain flexibility to pivot toward synthetic alternatives as REACH compliance costs escalate.
Pricing Analysis
After-market cleat replacement revenue traditionally drove lifetime value, yet spikeless traction systems are decomposing this model and elevating upfront price tolerance. Three-tier pricing structure across premium leather-membrane integration, standard synthetic constructions, and economy PVC tiers separates waterproof-breathable performance from basic coated alternatives. Pricing pressure stems from athleisure substitution capturing casual-round occasions, forcing compression in mid-range tiers. Recreational golfers entering the category exhibit highest price sensitivity, while tournament professionals absorb premium positioning with minimal volume elasticity.
Supply Chain Analysis
Inventory velocity in pro-shop channels demands rapid replenishment cycles that strain working capital for manufacturers without domestic manufacturing footprints. Production concentrates in Italy and Argentina for premium leather, China for synthetic microfiber and molded components, and Vietnam for textile upper assembly. Raw material dependencies span full-grain hides, thermoplastic polyurethane traction plates, and Gore-Tex membrane licensing. Single-source vulnerability in Italian tanning capacity exposes brands to supply shocks. Distribution runs through specialty athletic footwear chains, brand-owned digital storefronts, and course-proximity retail with divergent margin extraction profiles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion characterizes this market as recreational participation broadens beyond traditional country club demographics, creating volume pools that did not exist a decade prior. Waterproof membrane technology diffusion across all price tiers sustains replacement-cycle compression that benefits premium positioning.
For Market Incumbents: Consolidate manufacturing footprint control through captive tannery relationships or backward integration into membrane assembly, defending against digital-native entrants optimizing direct-to-consumer channel economics. Reinforce pro-shop inventory velocity capabilities as course-proximity retail loses share to off-course comparison shopping. Prioritize biomechanical engineering talent retention as specialized designers command premium compensation in competitive labor markets.
For New Entrants and Emerging Players: Lead with women's category white space in North American metropolitan markets, where resized lasts and expanded color palettes address fastest-structural expansion with minimal incumbent saturation. Target Southeast Asian warm-weather textile penetration where humidity drives lightweight knit upper demand. Deploy direct-to-consumer channel buildout to bypass wholesale margin extraction and enable premium positioning without price tier escalation.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated domestic producers with rapid replenishment capabilities and established membrane technology licensing relationships, as these archetypes capture early-cycle expansion with defensive moats. Monitor athlete endorsement density as inflection indicator—brands with tournament broadcast visibility extension command aspirational purchaser preference that translates to pricing power.
| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Technology Licensing | Gore-Tex partnerships anchor waterproof-breathable performance differentiation across premium tiers. |
| Direct-to-Consumer Channel Buildout | Digital storefronts bypass wholesale margin extraction while capturing planned replacement cycles. |
| Women's Category Expansion | Resized lasts and broadened color palettes capture fastest-structural growth segment in North America. |
| Spikeless Traction System Development | TPU plate engineering displaces traditional cleat-replacement revenue models with dual-use walking comfort. |
| Alternative Tanning Process Migration | California Proposition 65 compliance accelerates chromium-free leather adoption reducing regulatory risk. |
Methodological Framework
Operator-level perspectives from brand product managers, specialty retail buyers, pro-shop operators, and tannery procurement leads anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation through customs records, retail audit data from Nielsen/Circana, SEC footwear segment filings, and ISO certification registries. Bottom-up unit economics triangulated against top-down market sizing across waterproof membrane integration tiers, construction materials, end-user segments, and regional demand clusters.
Sensitivity analysis tested forecast robustness across recreational participation growth scenarios, hide price volatility bands, and regulatory compliance cost escalations throughout the projection horizon. Segmentation modeling captured product type, material construction, end-user category, and price tier dimensions alongside geographic adoption pattern variations. CAGRs derived from replacement-cycle compression rates, participation expansion trajectories, and channel mix evolution assumptions specific to golf footwear purchase behavior.
Forecasts assume regulatory continuity in California Proposition 65 enforcement and REACH restriction implementation; material policy shifts would require re-modeling of material sourcing economics and compliance cost structures. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Footwear
Global Footwear Market
Footwear
US Slip Resistant Shoes Market
Footwear
UK Lifestyle Sneakers Market
Footwear
Leather Sneakers Market
Footwear
South America Athletic Footwear Market
Footwear
Tennis Shoes Market
Footwear
Footwear Testing Services Market
Footwear
North America Athletic Footwear Market
Footwear
Tactical Footwear Market
Footwear
Sports Footwear Market
Footwear
Second Hand Designer Shoes Market
Footwear
Asia-Pacific Athletic Footwear Market
Footwear
Footwear Manufacturing Machinery Market
Footwear
Sports Shoes Market
Footwear
Snow Boots for Women Market
Footwear
Europe Footwear Market