
 Sports Footwear Market | 2026-2036
Sports Footwear Market Size, Share, and Industry Trends Forecast 2026-2036
Sports Footwear Market Intelligence
The buyer base for performance footwear is broadening beyond traditional professional athletes to encompass collegiate programs, amateur running clubs, and corporate wellness initiatives. Nike leverages its direct-to-consumer platform to control pricing and inventory flow across digital channels. Adidas sustains innovation momentum through its Boost foam chemistry and recycled polyester integration. Puma competes aggressively in soccer cleats through partnerships with European football clubs.
Sports footwear comprises engineered athletic shoes designed with cushioning systems, traction outsoles, and breathable uppers to enhance biomechanical performance and reduce injury risk during physical activity. The category serves competitive sports, fitness training, and lifestyle applications where motion control and energy return determine functional value. Running shoes anchor the product type mix due to marathon participation and everyday jogging penetration. Mesh and synthetic materials lead the material split because manufacturers prioritize weight reduction and moisture management over leather durability. The professional end-user segment commands premium pricing, while casual users drive volume through athleisure crossover demand.
Regulatory scrutiny from the EPA on per- and polyfluoroalkyl substances affects waterproofing treatments across US-manufactured lines. REACH restrictions in Europe constrain certain synthetic dyes and rubber accelerators, forcing reformulation of midsole compounds. California's Proposition 65 labeling requirements add compliance costs for brands distributing in that state. Stakeholders must monitor evolving chemical restrictions and traceability mandates to protect market access and avoid supply chain disruptions.
Market Dynamics
Material traceability mandates and chemical disclosure requirements are forcing wholesale restructuring of sourcing networks, with brands now mapping tier-three suppliers for compliance verification rather than cost optimization alone.
Growth Catalysts
- Amateur League Expansion:Collegiate athletic programs and recreational running clubs are professionalizing their equipment standards, creating pull for performance-grade cushioning systems previously reserved for elite competition.
- REACH Chemical Reformulation:European restrictions on synthetic rubber accelerators and azo dyes are accelerating adoption of bio-based midsole alternatives that reduce liability exposure while opening green-premium pricing tiers.
- Corporate Wellness Mandates:Employer-funded fitness stipends in North America and Western Europe are converting sedentary office workers into regular training participants, expanding the addressable base beyond traditional athletic demographics.
Market Restraints
- Petrochemical Feedstock Volatility:Ethylene-vinyl acetate and thermoplastic polyurethane prices swing with crude oil indices, compressing margin predictability for foam-intensive product lines.
- China Manufacturing Concentration:Over 70 percent of midsole molding capacity sits in Fujian and Guangdong provinces, exposing brands to single-point geopolitical and logistics disruption risks.
- Waterproofing Chemistry Constraints:EPA scrutiny of per- and polyfluoroalkyl substances eliminates durable water-repellent treatments that long defined trail-running competitive advantage, forcing performance trade-offs.
Strategic Opportunities
- India Distribution Infrastructure:Organized retail penetration remains below 15 percent in tier-two and tier-three cities, creating first-mover advantage for brands building exclusive store networks ahead of income growth curves.
- Recycled Polyester Integration:Mechanical recycling of post-consumer PET into engineered mesh uppers satisfies emerging ESG procurement criteria in European corporate uniform programs.
- SAMR Biodegradability Standards:China's evolving national standards for footwear end-of-life disposal position domestic brands with pilot composting programs to capture preferential shelf placement.
Industry Challenges
- Biomechanical Engineering Talent Scarcity:The intersection of sports medicine, materials science, and computational modeling commands premium compensation, constraining mid-tier brand R&D staffing.
- Multi-Tier Supplier Auditing Costs:California SB 657 and analogous disclosure laws require documented verification of labor practices across subcontracted component manufacturers, inflating compliance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sports Footwear Market |
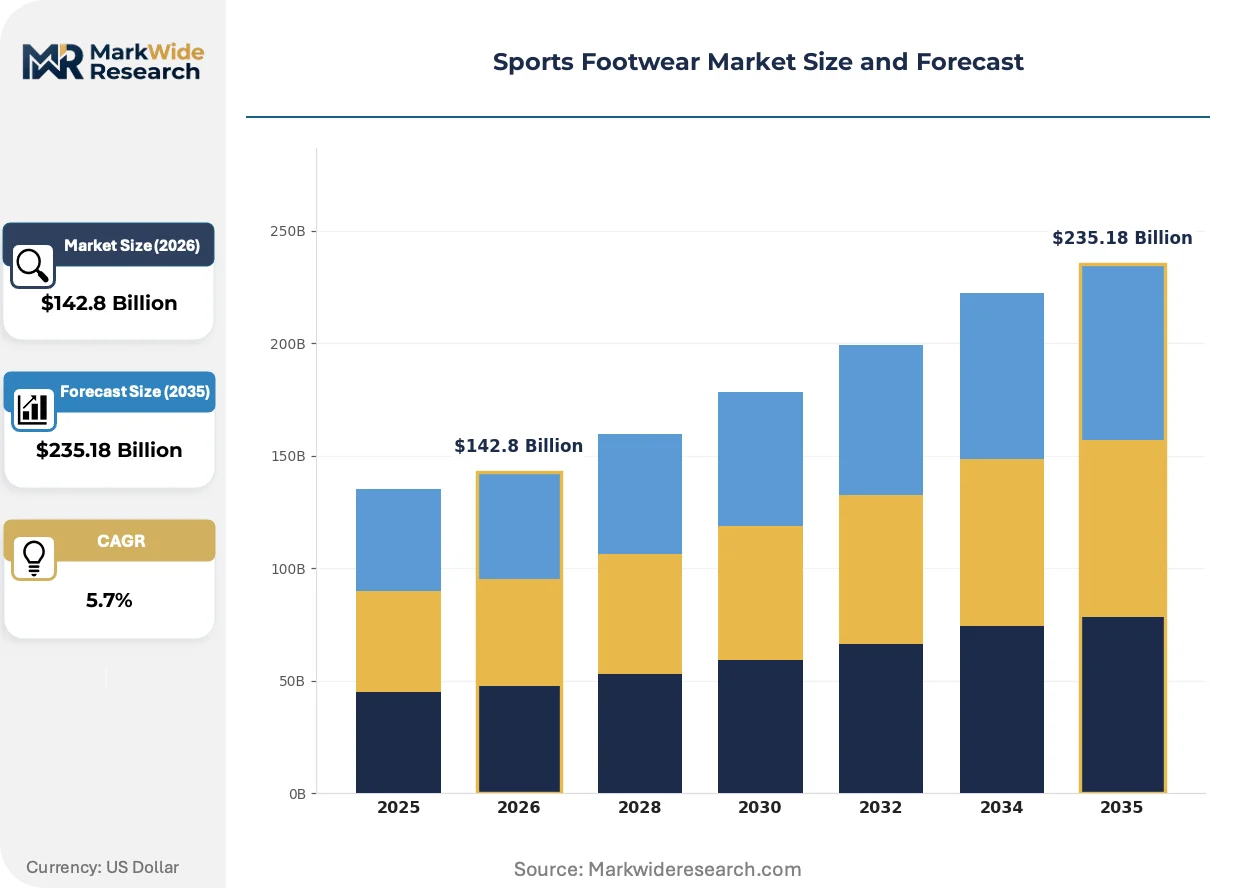
| Market Size in 2026 | $142.8 Billion |
| Market Size in 2035 | $235.18 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Running Shoes, Training Shoes, Basketball Shoes, Soccer Cleats End User: Adults, Kids, Professionals, Casual Users Material: Synthetic, Leather, Mesh, Rubber Usage Occasion: Fitness, Competition, Casual Wear, Outdoor Activities |
| Companies Covered | Skechers, Under Armour, Nike, Brooks, Reebok, Adidas, Puma, ON Running, New Balance, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sports Footwear Market Strategic Shifts & Innovations
Digital manufacturing and biomaterial science are converging to compress development cycles and enable mass customization, while regulatory chemistry constraints accelerate substitution timelines for legacy formulations.
Generative design software is automating lattice-structure midsole geometries that optimize energy return for individual gait patterns. Elite marathon programs and specialty running retailers are piloting these patient-specific configurations. The technology is automating what previously required months of physical prototyping into days of computational iteration.
California's Proposition 65 enforcement against unlabeled phthalate exposure has expanded to footwear adhesives and synthetic leather finishes. Brands distributing in the state now face relabeling costs or reformulation investments. Trail-running and children's segments bear disproportionate compliance burden due to extended skin-contact duration and heightened liability sensitivity.
Direct-to-consumer subscription models for performance shoe replacement are displacing traditional retail repurchase cycles. Marathon training programs and CrossFit affiliates are aggregating member orders for quarterly delivery. Germany and the United Kingdom show highest conversion rates where consumers already accept apparel rental and circular economy propositions.
Sports Footwear Market Segmentation
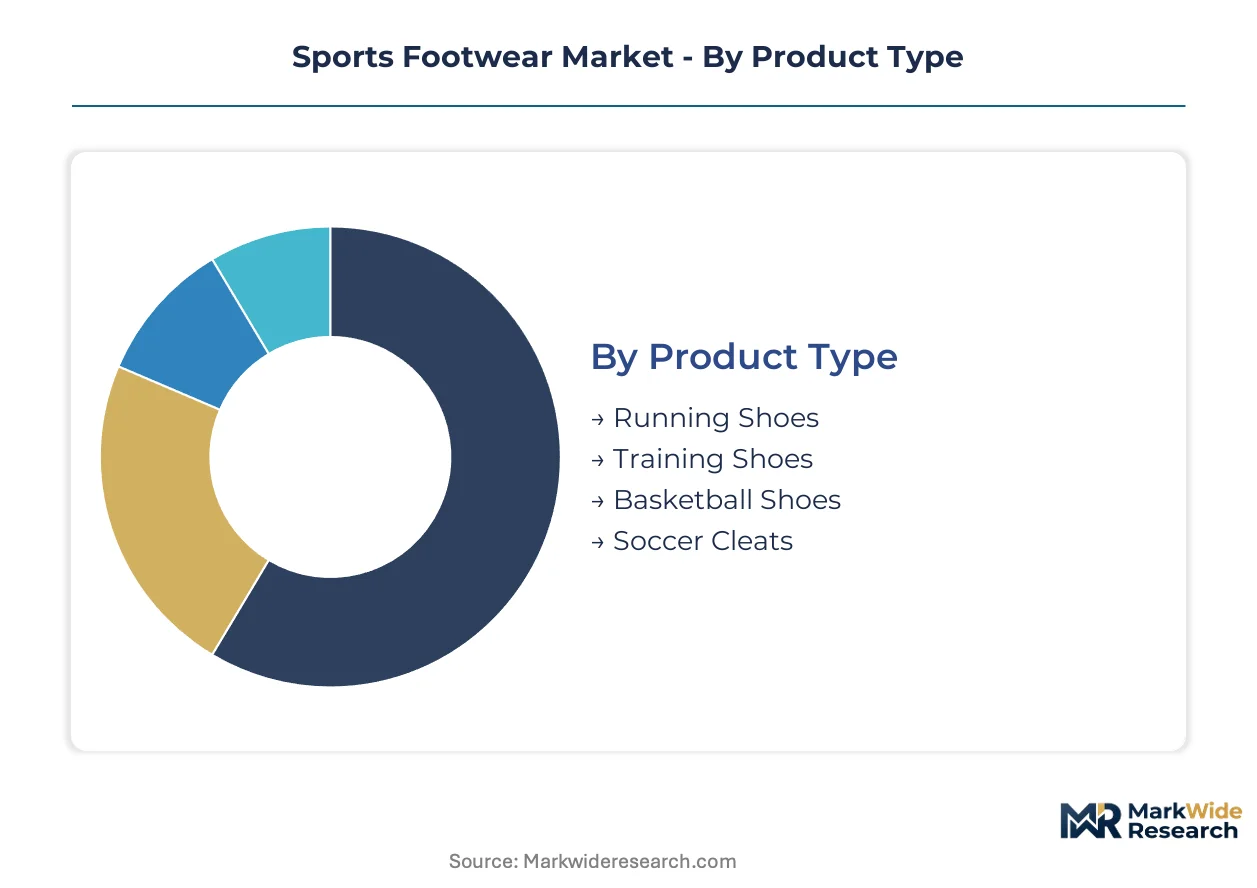
Sports footwear segmentation reveals how biomechanical requirements, material preferences, and usage intensity fragment demand across distinct price-performance tiers. Manufacturers configure supply chains differently for each slice, from marathon-grade carbon-plate engineering to injection-molded casual silhouettes.
Product Type:
Performance differentiation separates buyers by impact forces, court surfaces, and propulsion mechanics rather than brand loyalty alone.
- Running Shoes:Engineered with ethylene-vinyl acetate or thermoplastic polyurethane midsole stacks and carbon-fiber propulsion plates for energy return. Marathon participation in Boston, Berlin, and Tokyo drives premium cushioning adoption among amateur athletes seeking injury prevention.
- Soccer Cleats:Feature molded thermoplastic polyurethane or metal studs configured for natural grass versus artificial turf traction. European football academies in Spain and Germany sustain demand for position-specific boot geometries that optimize ball control or sprint mechanics.
- Basketball Shoes:High-top collars and herringbone rubber outsoles address ankle stabilization and hardwood grip.
- Training Shoes:Cross-functional platforms balance lateral support with heel-to-toe drop versatility for gym-floor versatility.
Volume sits with Running Shoes; growth tilts toward Soccer Cleats.
End User:
Purchasing authority and replacement frequency vary sharply between parent-driven children's segments and self-directed adult procurement.
- Adults:Self-directed buyers with established brand preferences and higher per-unit spending on technical specifications. Corporate wellness stipends in the United States and United Kingdom convert sedentary workers into regular training participants, expanding the addressable base beyond traditional athletic demographics.
- Kids:Growth-accommodating sizing and abrasion-resistant overlays dominate design priorities. Parental procurement in suburban United States markets concentrates on back-to-school seasonal windows with durability-to-price ratio sensitivity.
- Professionals:Sponsored athletes and collegiate programs receiving equipment allocations.
- Casual Users:Athleisure-driven purchasers prioritizing aesthetic versatility over performance metrics.
Adults generate the highest absolute revenue; Kids expand most quickly as organized youth sports participation broadens.
Material:
Weight-to-durability tradeoffs and regulatory chemistry constraints determine sourcing strategies across upper, midsole, and outsole components.
- Mesh:Engineered polyester or nylon knit constructions maximize breathability and moisture evacuation during sustained aerobic output. REACH restrictions on synthetic dyes in Europe accelerate adoption of solution-dyed variants that reduce water consumption and chemical discharge liability.
- Synthetic:Polyurethane and thermoplastic polyurethane films enable seamless construction and localized structural reinforcement. Fujian province manufacturing clusters dominate capacity for hot-melt lamination processes that bond synthetic layers to foam substrates.
- Leather:Traditional kangaroo and calfskin uppers retain premium positioning in heritage soccer and lifestyle categories.
- Rubber:Natural and synthetic compounds formulated for abrasion resistance and wet-surface traction.
Mesh commands production volume; synthetic materials climb fastest as waterproofing chemistry reformulation demands thermoplastic versatility.
Usage Occasion:
Intensity of mechanical stress and exposure conditions separate intermittent recreational use from daily competitive training regimens.
- Fitness:Gym-based training, group exercise classes, and home workout protocols requiring multi-directional stability. CrossFit affiliate networks in Texas and Florida aggregate member orders for quarterly shoe replacement, sustaining predictable demand cycles.
- Competition:Sanctioned events with equipment regulations and performance verification standards. Elite marathon programs in Kenya and Ethiopia pilot patient-specific midsole geometries through generative design partnerships.
- Casual Wear:Street and workplace environments where aesthetic integration supersedes athletic function.
- Outdoor Activities:Trail running, hiking, and adventure racing exposed to variable terrain and weather conditions.
Fitness anchors current volume; Competition shows the steepest expansion trajectory as amateur racing professionalizes equipment standards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ethylene-vinyl acetate feedstock concentration in the US Gulf Coast and Fujian province manufacturing clusters anchor regional supply configurations for performance foam production.
United States
Corporate wellness stipends convert sedentary office workers into training participants across Texas and Florida. EPA scrutiny of per- and polyfluoroalkyl substances forces reformulation of waterproofing treatments for trail-running lines. Boston anchors marathon-driven demand for carbon-plate running shoes through specialty retail networks.
China
Domestic brands command significant volume in tier-two and tier-three cities where organized retail penetration remains below 15 percent. SAMR biodegradability standards for footwear end-of-life disposal pilot composting programs in manufacturing clusters. Fujian and Guangdong provinces concentrate over 70 percent of midsole molding capacity for global brands.
Germany
European football academies sustain demand for position-specific soccer cleat geometries. REACH restrictions on synthetic rubber accelerators and azo dyes accelerate adoption of bio-based midsole alternatives. Bavaria hosts generative design partnerships between elite marathon programs and footwear engineers.
United Kingdom
CrossFit affiliates aggregate member orders for quarterly shoe replacement with highest subscription model conversion rates in Europe. Proposition 65 labeling requirements affect brands distributing through California-linked supply chains. London specialty running retailers pilot patient-specific midsole configurations.
India
Organized retail penetration in tier-two and tier-three cities creates first-mover advantage for exclusive store network construction. BIS standards govern product safety and quality certification for imported athletic footwear. Maharashtra and Karnataka concentrate domestic distribution infrastructure ahead of income growth curves.
Sports Footwear Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue direct-to-consumer subscription models and biomechanical customization services. The vendor base stratifies across three tiers: global scale operators with captive retail networks, regional specialists in single sports categories, and technology-driven challengers leveraging generative design. Competitive moves concentrate on M&A for digital manufacturing capabilities and strategic partnerships with elite athletic programs for product validation.
Within the scale-driven tier, Nike Inc. and Adidas AG exemplify integrated supply chain control spanning design through direct-to-consumer distribution. ON Running represents the technology-forward challenger archetype, leveraging computational midsole engineering to capture marathon-trained amateur athletes. Skechers anchors the accessible-performance segment, converting casual fitness participants through value-engineered cushioning platforms without elite sponsorship overhead.
| Leading Market Players |
|---|
| Skechers |
| Under Armour |
| Nike |
| Brooks |
| Reebok |
| Adidas |
| Puma |
| ON Running |
| New Balance |
| Others |
Cost & Logistics Intelligence
Collegiate athletic programs and amateur running clubs concentrate procurement volume in the mid-tier performance segment, anchoring a pricing model that rewards scale commitments with preferential unit economics. This buyer archetype's professionalizing equipment standards create tiered negotiation leverage that separates marathon-grade carbon-plate configurations from value-engineered cushioning platforms.
Pricing Analysis
Volume concentrates in mesh-upper running shoes priced for quarterly replacement cycles, while margins accrue to patient-specific midsole geometries configured through generative design partnerships. Pricing stratifies across premium, standard, and economy tiers based on biomechanical customization depth and REACH-compliant material certification. Cost compression in the standard tier intensifies as ethylene-vinyl acetate feedstock volatility compresses foam-intensive product lines. Casual users exhibit highest price sensitivity due to athleisure crossover demand, whereas sponsored collegiate programs accept premium positioning for injury-prevention specifications.
Supply Chain Analysis
Ethylene-vinyl acetate and thermoplastic polyurethane supply rests on US Gulf Coast petrochemical complexes and Fujian province specialty chemical producers, with midsole molding capacity clustering in Guangdong manufacturing zones. Raw material dependencies span crude oil derivatives for foam chemistry, carbon fiber sheet for propulsion plates, and solution-dyed polyester for breathable uppers. Single-source vulnerability concentrates in China's Fujian and Guangdong provinces, where over seventy percent of global midsole molding capacity faces geopolitical disruption exposure. Distribution runs through direct-to-consumer platforms for inventory control, supplemented by specialty running retail networks for gait-analysis consultation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH chemical reformulation and California SB 657 disclosure mandates have erected substantial compliance moats, positioning incumbent brands with verified tier-three supplier mapping to capture market share from under-resourced challengers facing relabeling cost burdens.
For Market Incumbents: Deploy generative design capabilities to automate patient-specific midsole configurations, converting months of physical prototyping into computational iteration cycles that emerging entrants cannot replicate. Deepen backward integration into bio-based midsole alternatives to reduce REACH liability exposure while capturing green-premium pricing tiers. Consolidate position against technology-driven challengers by exclusive partnerships with elite marathon programs in Kenya and Ethiopia for product validation. For New Entrants and Emerging Players: Tier-two and tier-three Indian cities represent the most penetrable geography, where organized retail penetration below fifteen percent enables first-mover exclusive store network construction ahead of income growth curves. Corporate wellness stipend aggregators in Texas and Florida offer a direct-to-employer go-to-market angle, bypassing saturated specialty retail channels through quarterly subscription models for training program members. For Investors and Strategic Acquirers: The window for entry favors technology-forward challengers with computational midsole engineering capabilities and established direct-to-consumer infrastructure. Long-term viability hinges on five-to-ten year positioning around biomechanical customization and circular economy compliance ahead of SAMR biodegradability standard enforcement. Monitor EPA enforcement patterns on per- and polyfluoroalkyl substances as the critical inflection signal for waterproofing chemistry substitution timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Platform Expansion | Nike's proprietary app infrastructure controls pricing and inventory flow across digital channels. |
| Recycled Polyester Integration | Mechanical recycling of post-consumer PET satisfies ESG procurement criteria in European corporate uniform programs. |
| Generative Design Partnership | Elite marathon programs in Bavaria pilot patient-specific midsole geometries through computational engineering collaboration. |
| Bio-Based Midsole Reformulation | REACH restrictions on synthetic rubber accelerators accelerate adoption of green-premium pricing tiers. |
| India Distribution Infrastructure Buildout | Maharashtra and Karnataka concentrate domestic distribution infrastructure ahead of income growth curves. |
Research Approach
Independent corroboration across primary interviews with footwear brand supply chain directors, specialty running retail buyers, collegiate athletic equipment managers, and materials science R&D leads underwrites the qualitative findings. Secondary validation draws from customs and trade data, SEC 10-K filings of publicly traded manufacturers, European Chemicals Agency REACH registration databases, and retail audit data from Nielsen and Circana. Bottom-up segmentation modeling triangulates against top-down market sizing derived from production capacity assessments in Fujian and Guangdong provinces.
Historical reference periods spanning the pre-pandemic baseline through the supply chain disruption window anchor the forecast framework across the analysis window. Segmentation dimensions model product type, material composition, end-user archetype, and usage occasion intensity, with regional regulatory clusters capturing REACH, EPA, and SAMR compliance trajectories. CAGRs derive from elasticity-adjusted demand projections incorporating marathon participation trends, corporate wellness stipend penetration, and amateur league professionalization rates.
Revisions become necessary when petrochemical feedstock volatility exceeds historical bands, when EPA enforcement actions expand beyond per- and polyfluoroalkyl substances to additional waterproofing chemistries, or when geopolitical disruption affects Fujian province manufacturing clusters. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Footwear
Loafers Market
Footwear
UGG Boots Market
Footwear
Mountain Bike Footwear and Socks Market
Footwear
Women's Luxury Footwear Market
Footwear
Flip Flops Market
Footwear
Refurbished Sneaker Market
Footwear
Shoe Insoles Market
Footwear
Asia-Pacific Athletic Footwear Market
Footwear
Women's Non-Athletic Footwear Market
Footwear
Trail Running Shoes Market
Footwear
Outdoor Trail Running Shoes Market
Footwear
Kids Barefoot Shoes Market
Footwear
Western Boots Market
Footwear
PVC Footwear Market
Footwear
Luxury Footwear Market
Footwear
Premium Shoes Market