
 Kids Barefoot Shoes Market | 2026-2036
Kids Barefoot Shoes Market Size, Share, and Industry Trends Forecast 2026-2036
Kids Barefoot Shoes Market Analysis
Podiatric biomechanics expertise is bifurcating the competitive landscape, as brands with in-house foot-health credentials pull ahead of generalist athletic entrants. Vivobarefoot sustains its lead through clinical partnerships with European gait laboratories. Xero Shoes leverages direct-to-consumer engineering feedback loops to refine last shapes for developing feet. Softstar Shoes anchors its position through made-to-order craftsmanship from its Oregon workshop.
Kids barefoot shoes are minimal-sole footwear engineered with zero heel-to-toe drop, flexible thin outsoles typically measuring 3-8 millimeters, and anatomically wide toe boxes to preserve natural foot splay during developmental years. Their primary purpose is to replicate unshod biomechanics while providing puncture protection and thermal insulation across varied terrains. Sneakers and sandals together dominate unit volume, with sandals capturing disproportionate margin pools in warm-climate markets due to simpler construction and seasonal replenishment cycles. Leather uppers command premium positioning among preschool-age segments, where durability concerns override the lower price points of canvas alternatives.
REACH compliance in the European Union governs phthalate content in synthetic materials, while the US Consumer Product Safety Commission monitors small-part detachment risks in toddler sizes. The EU Green Deal's textile sustainability targets are forcing material traceability disclosures that favor natural rubber and vegetable-tanned leather suppliers. Stakeholders must monitor how pediatric orthopedic associations in Germany and South Korea formalize barefoot footwear recommendations into clinical guidelines.
Market Dynamics
REACH chemical safety standards in the European Union are forcing manufacturers to abandon phthalate-laden synthetic soles and reformulate around certified natural rubber compounds, restructuring material sourcing across the value chain.
Growth Catalysts
- Pediatric biomechanics research:Gait laboratories in Germany and the United Kingdom now generate clinical evidence supporting proprioception development in toddlers wearing minimal-soled footwear, creating prescriptive demand channels.
- Alternative education networks:Montessori and Waldorf parent communities in South Korea drive premium adoption through peer recommendation systems concentrated in Seoul and Busan urban clusters.
- EU Green Deal textile targets:Material traceability disclosures mandated under sustainability frameworks favor vegetable-tanned leather and natural rubber suppliers with certified supply chains.
Market Restraints
- Natural rubber price volatility:Sole compound costs fluctuate with Southeast Asian latex harvest cycles and climate disruptions, compressing margin predictability for small-batch producers.
- Specialized manufacturing concentration:Anatomical last production for developing feet clusters in traditional footwear manufacturing regions of Portugal and northern Italy, creating geographic supply risk.
- Canvas durability substitution:Lower-price canvas uppers in toddler sizes face replacement pressure from synthetic mesh alternatives despite leather's premium positioning among durability-focused preschool segments.
Strategic Opportunities
- Clinical guideline formalization:Pediatric orthopedic associations in Germany and South Korea are drafting barefoot footwear recommendations that would institutionalize prescriptive demand through physiotherapy channels.
- Warm-climate sandal expansion:Simplified construction and seasonal replenishment cycles in Mediterranean and Australian markets capture disproportionate margin pools versus year-round sneaker production.
- Direct-to-consumer fit technology:3D foot scanning integration with made-to-order craftsmanship enables precise last matching for developing feet without retail inventory carry.
Industry Challenges
- Podiatric biomechanics talent scarcity:In-house foot-health credentials require specialized training that generalist athletic footwear designers rarely possess, constraining brand differentiation.
- Small-part compliance timelines:US Consumer Product Safety Commission detachment risk assessments for toddler sizes extend product development cycles before market entry.
- Multi-material integration complexity:Combining flexible thin outsoles with anatomically wide toe boxes demands precise bonding techniques that workshop-scale producers struggle to scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kids Barefoot Shoes Market |
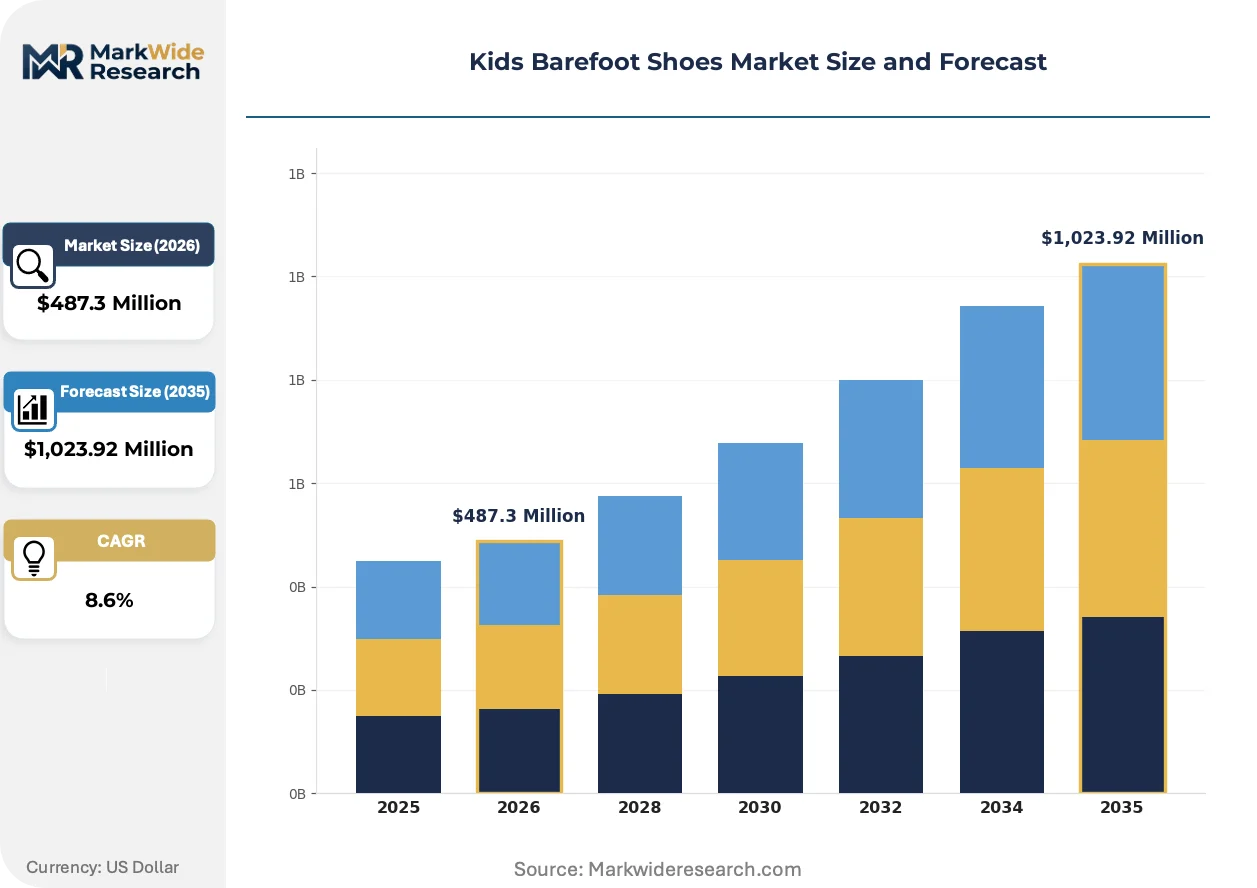
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,023.92 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sandals, Sneakers, Slippers, Boots Material: Natural Rubber, Canvas, Leather, Synthetic Age Group: Toddlers, Preschoolers, School-Age, Preteens Use Case: Everyday Wear, Sports, Outdoor Activities, Water Play |
| Companies Covered | Xero Shoes, Softstar Shoes, Vivobarefoot, Vaistoa, Lang.S by Tikki Shoes, Wildling Shoes, Saguaro, Snugi, Merrell, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kids Barefoot Shoes Market Emerging Trajectories
Material science and digital fit technologies are restructuring how minimal footwear for children is engineered, tested, and distributed. Three converging developments are compressing traditional manufacturing timelines while elevating clinical credibility requirements.
Biomechanical sensor integration is bifurcating the product development landscape. Pressure-mapping insoles embedded in prototype footwear capture real-time gait data during toddler locomotion trials. European gait laboratories now require such datasets for partnership validation. This capability compression separates brands with clinical research budgets from design-only competitors.
REACH compliance enforcement is intensifying material substitution pressures. ECHA monitoring of phthalate content in synthetic sole compounds has triggered reformulation mandates across EU-bound production lines. German manufacturers are responding fastest, with several establishing captive natural rubber processing relationships in Sri Lanka and Malaysia to secure certified supply.
Parent purchasing behavior is fragmenting across channel preferences. Urban professional segments in South Korea and Germany bypass traditional retail for subscription-based sizing programs that accommodate rapid foot growth. Direct-to-consumer brands capture this shift through mobile-first fit algorithms, while legacy distributors struggle to replicate the replenishment convenience these networks demand.
Kids Barefoot Shoes Market Segmentation
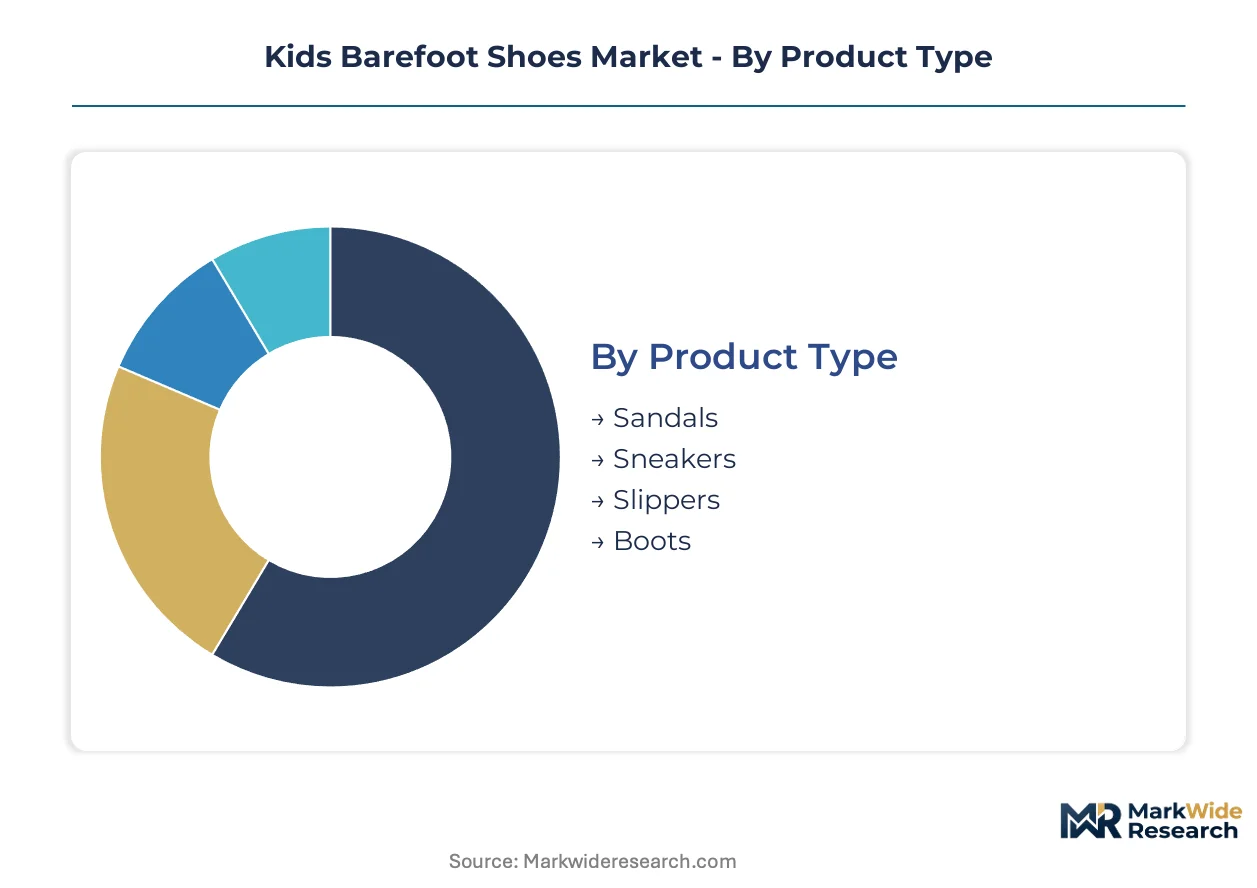
Segmentation in kids barefoot shoes reveals distinct channel preferences that shape inventory and margin strategies. Product type and material choices diverge sharply between clinical prescription channels and direct-to-consumer platforms, while age-based sizing drives replenishment frequency.
Product Type:
Channel distribution varies dramatically by construction complexity and seasonal replenishment cycles. Sandals flow disproportionately through warm-climate specialty retailers and Montessori school networks, while sneakers dominate year-round e-commerce subscriptions.
- Sneakers:Year-round silhouettes with 3-8 millimeter flexible soles and anatomical toe boxes command the largest unit volumes. Demand concentrates in urban parent networks across Germany and South Korea, where physiotherapy referrals and alternative education communities drive premium positioning through direct-to-consumer channels.
- Sandals:Simplified open-toe constructions with natural rubber outsoles capture disproportionate margin pools in Mediterranean and Australian markets. Seasonal replenishment cycles and lower material costs enable faster inventory turns for workshop-scale producers targeting warm-climate Montessori clusters.
- Slippers:Indoor-focused minimal soles with thermal insulation layers serve northern European and North American winter demand through specialty children's retailers.
- Boots:Weather-protected uppers with puncture-resistant thin outsoles address outdoor parent segments in temperate climates with shorter purchase cycles.
By volume, sneakers lead. By growth pace, sandals are expanding most quickly.
Material:
Cost tier stratification separates certified supply chains from commodity alternatives, with REACH compliance costs reshaping procurement priorities across European production.
- Leather:Vegetable-tanned uppers with natural rubber sole bonding command premium positioning among preschool-age segments. Durability concerns override canvas price advantages in German and UK physiotherapy prescription channels where replacement frequency matters.
- Natural Rubber:Certified latex compounds for flexible thin outsoles face sourcing concentration risks in Sri Lankan and Malaysian processing facilities. ECHA monitoring of phthalate alternatives drives fastest reformulation investment among EU-bound manufacturers.
- Canvas:Lower-price woven cotton uppers in toddler sizes face substitution pressure from synthetic mesh despite cost advantages.
- Synthetic:Phthalate-restricted polymer compounds struggle with REACH compliance timelines while offering moisture-wicking performance for sports use cases.
By revenue concentration, leather dominates premium tiers. By reformulation investment velocity, natural rubber is climbing the fastest.
Age Group:
Customer type determines fit precision requirements and replenishment frequency, with rapid foot growth driving subscription model adoption.
- Toddlers:Proprioception-critical first walkers with 3-5 millimeter sole profiles generate prescriptive demand through German and UK pediatric gait laboratories. Small-part detachment compliance extends US Consumer Product Safety Commission development timelines for this segment.
- Preschoolers:Durability-focused active use with wider toe box requirements concentrates parent spending on leather-upper constructions.
- School-Age:Institutional wear requirements and peer influence shift purchasing toward sneaker silhouettes with brand visibility.
- Preteens:Aesthetic preferences begin overriding biomechanical specifications, compressing margin premiums for functional design.
By clinical referral volume, toddlers lead. By absolute unit scale, school-age is gaining share fastest.
Use Case:
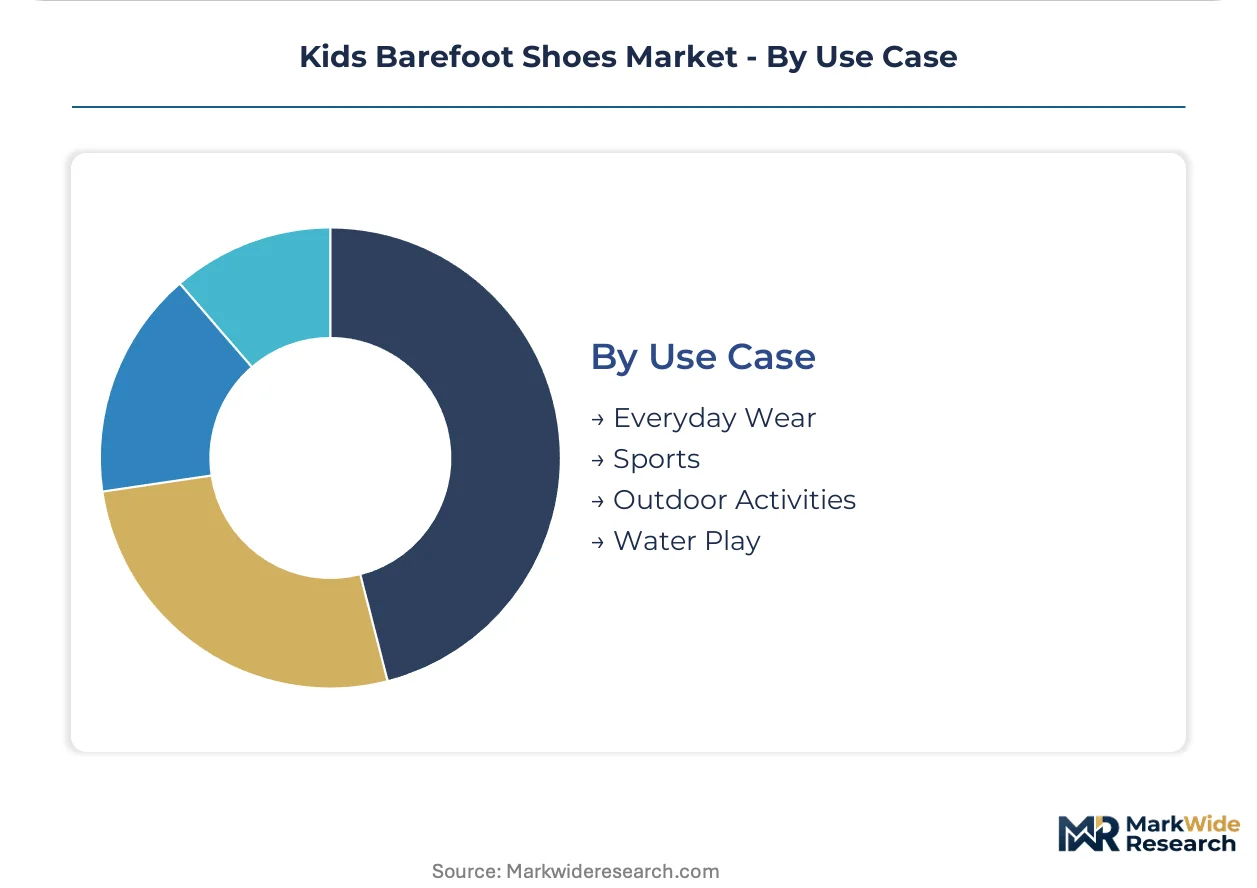
Application context determines performance specifications and seasonal demand patterns across distribution channels.
- Everyday Wear:All-terrain versatility with puncture protection and thermal balance serves the core addressable market through generalist children's retailers.
- Sports:Enhanced ground feel for running and gymnastics concentrates in specialty athletic channels with biomechanical validation requirements.
- Outdoor Activities:Weather-resistant constructions with aggressive tread patterns address hiking and nature play segments in temperate climate markets.
- Water Play:Quick-drain designs with synthetic uppers and natural rubber grip patterns serve summer camp and beach recreation demand.
By baseline volume, everyday wear leads. By seasonal spike amplitude, water play shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH compliance enforcement by ECHA anchors European demand generation for certified natural rubber compounds, while pediatric gait laboratories in Germany and the United Kingdom convert clinical evidence into prescriptive channels.
Germany
Pediatric physiotherapy clinics in Munich and Berlin prescribe barefoot-style footwear for proprioception development, driving institutional adoption. The country's national product safety regulator enforces REACH phthalate restrictions on synthetic sole compositions. Manufacturing clusters in Bavaria and Baden-Württemberg host anatomical last production facilities serving EU-bound brands.
United Kingdom
London and Manchester parent networks concentrate demand through Montessori school referral systems. The Health and Safety Executive monitors chemical content in children's footwear imports under retained EU regulations. Gait laboratories in Oxford and Cambridge generate biomechanical validation datasets for brand partnerships.
South Korea
Seoul and Busan urban clusters drive premium adoption through Waldorf education parent communities. The Ministry of Food and Drug Safety oversees product safety standards for children's goods. Subscription-based sizing programs capture rapid foot growth replenishment cycles in the capital region.
United States
Pacific Northwest and Northeast Corridor parent segments favor direct-to-consumer fit technology for developing feet. The Consumer Product Safety Commission extends small-part detachment assessment timelines for toddler sizes. Oregon-based workshop producers supply made-to-order craftsmanship to durability-focused preschool segments.
Australia
Sydney and Melbourne warm-climate markets capture disproportionate sandal margins through seasonal replenishment cycles. The Therapeutic Goods Administration monitors product safety claims in pediatric health positioning. Queensland and New South Wales outdoor parent segments drive hiking-boot demand for nature play applications.
Kids Barefoot Shoes Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the competitive structure. Three archetypes dominate: clinical-research brands with gait laboratory partnerships, workshop-scale craft producers with made-to-order capabilities, and direct-to-consumer operators with mobile-first fit algorithms. Competitive moves concentrate on strategic partnerships with pediatric orthopedic associations and geographic expansion into warm-climate sandal markets.
Within the clinical-research tier, Vivobarefoot and Xero Shoes exemplify divergent positioning strategies. Vivobarefoot occupies a position anchored through European gait laboratory relationships. Xero Shoes represents the direct-to-consumer engineering feedback model. Softstar Shoes sits within the workshop-craft archetype, anchoring made-to-order production from its Oregon base.
| Leading Market Players |
|---|
| Xero Shoes |
| Softstar Shoes |
| Vivobarefoot |
| Vaistoa |
| Lang.S by Tikki Shoes |
| Wildling Shoes |
| Saguaro |
| Snugi |
| Merrell |
| Others |
Supply Flow & Price Mechanics
Batch-size economics in anatomical last production determine price floors across the value chain, with Portuguese and northern Italian workshop clusters commanding premium positioning while Southeast Asian natural rubber processing creates raw material cost volatility that compresses margin predictability for small-batch producers.
Pricing Analysis
Geographic price spreads between German physiotherapy prescription channels and South Korean direct-to-consumer platforms reflect certification-grade differentiation. Three-tier pricing structure across clinical-partnership premium, standard e-commerce, and economy canvas tiers anchors the market. Price differentiation rests on REACH compliance certification and in-house biomechanics expertise. Cost compression in economy canvas segments is intensifying because synthetic mesh substitution erodes cotton's cost advantage. Montessori parent networks in Seoul show lowest price sensitivity; budget-focused toddler retailers in North America exhibit highest.
Supply Chain Analysis
Sri Lankan latex processing concentration creates single-source vulnerability for certified natural rubber compounds. Manufacturing gravity centers on Portugal, northern Italy, and Bavaria for anatomical last production. Raw material dependencies include Malaysian latex harvests, vegetable-tanned leather from Italian tanneries, and German-engineered biomechanical sensors. Distribution runs through direct-to-consumer subscription platforms in urban parent networks and specialty children's retailers in clinical referral channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat structure where regulatory entrenchment through REACH compliance and clinical guideline formalization creates sustainable barriers against generalist athletic footwear entrants.
For Market Incumbents: Shield prescriptive demand channels by deepening captive natural rubber relationships in Sri Lanka and Malaysia before ECHA reformulation mandates accelerate. Secure gait laboratory exclusivity agreements in Germany and the United Kingdom to lock out design-only competitors. Prioritize certification investment ahead of pediatric orthopedic association guideline formalization.
For New Entrants and Emerging Players: Differentiate on 3D foot-scanning fit technology for rapid-growth toddler segments where replenishment frequency creates subscription stickiness. Target warm-climate sandal markets in Australia and Mediterranean regions with simplified construction and seasonal inventory turns. Pursue direct-to-consumer mobile-first algorithms as the primary go-to-market angle.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among direct-to-consumer operators with subscription-based sizing programs accommodating rapid foot growth. Long-term viability favors brands with integrated clinical research capabilities and certified supply chain control. Acquisition target archetype: workshop-scale producers with made-to-order craftsmanship and existing gait laboratory relationships. Watch for pediatric orthopedic association guideline publication as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Partnership Expansion | Gait laboratory validation in Germany and the United Kingdom creates prescriptive demand channels inaccessible to design-only competitors. |
| Captive Natural Rubber Sourcing | Direct processing relationships in Sri Lanka and Malaysia secure REACH-compliant supply ahead of ECHA reformulation mandates. |
| Direct-to-Consumer Platform Launch | Mobile-first fit algorithms capture urban parent network replenishment cycles in Seoul and Busan clusters. |
| Warm-Climate Sandal Line Extension | Simplified construction enables faster inventory turns in Australian and Mediterranean seasonal markets. |
| 3D Foot Scanning Integration | Precise last matching for developing feet reduces return rates and builds subscription stickiness in toddler segments. |
Methodological Framework
Initial hypotheses were tested against primary input from pediatric physiotherapy clinic directors, Montessori school procurement coordinators, natural rubber supply chain managers, and direct-to-consumer brand operators, then refined against secondary validation from ECHA compliance databases, EU customs trade records, and South Korean Ministry of Food and Drug Safety filings. Bottom-up unit economics from workshop-scale producers were triangulated with top-down market sizing across product type, material, age group, and use case dimensions.
Variance decomposition across the projection horizon isolates volume drivers from price-mix effects. Segmentation modeling incorporated product type, material certification tier, age-based replenishment frequency, and geographic regulatory cluster. CAGRs were derived from cohort-based growth trajectory analysis. Industry-specific forecast inputs include Southeast Asian latex harvest cycle data and pediatric orthopedic association guideline development timelines.
Decision-makers should treat outputs as directional under sustained REACH enforcement and clinical adoption assumptions; material deviation would warrant model refresh. Forecasts incorporate base-case assumptions regarding ECHA monitoring intensity and physiotherapy referral channel expansion. Revision becomes warranted when natural rubber price volatility crosses threshold levels or pediatric guideline formalization accelerates beyond modeled timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Footwear
Duck Boots Market
Footwear
High Heels Footwear Market
Footwear
Sports Shoes Market
Footwear
Global Espadrille Flats Market
Footwear
Leather Sneakers Market
Footwear
Women's Sneakers Market
Footwear
Tennis Shoes Market
Footwear
Sports Footwear Market
Footwear
United States Footwear Market
Footwear
Golf Footwear Market
Footwear
Refurbished Sneaker Market
Footwear
Premium Shoes Market
Footwear
Slip Resistant Shoes Market
Footwear
Trail Running Shoes Market
Footwear
Hiking Footwear Market
Footwear
North America Footwear Market