
 Middle East and Africa Athletic Footwear Market | 2026-2036
Middle East and Africa Athletic Footwear Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Athletic Footwear Market Foresight
Recycled polyester is rebalancing cost structures across the Middle East and Africa Athletic Footwear supply chain as brands substitute virgin petroleum-based textiles. Nike Inc. leverages its Flyknit manufacturing scale to reduce material waste in regional production hubs. Adidas AG anchors its competitive stance through Parley Ocean Plastic partnerships that resonate with environmentally conscious consumers in Gulf markets. Puma SE differentiates via localized design collaborations that address heat-performance requirements specific to Middle Eastern climates.
Athletic footwear comprises engineered upper materials, midsole cushioning systems, and outsole traction compounds designed for biomechanical performance during sport or training activities. Midsole formulations typically incorporate ethylene-vinyl acetate foams or thermoplastic polyurethane energy-return plates to attenuate ground reaction forces and enhance propulsion efficiency. Running shoes command the dominant revenue position within product type segmentation, sustained by marathon participation growth in Dubai and Cape Town. The athletes end user segment represents the fastest-expanding category, driven by government-funded sports academies in Saudi Arabia and Qatar. Online retail channels are capturing disproportionate growth velocity relative to brick-and-mortar alternatives, reflecting mobile-commerce penetration rates among younger demographics.
South Africa's National Regulator for Compulsory Specifications enforces labeling and performance standards that filter substandard imports from Asian manufacturing centers. The UAE's Product Conformity Scheme mandates pre-shipment testing for athletic footwear, creating compliance cost barriers for smaller exporters. Saudi Standards, Metrology and Quality Organization specifications for slip resistance and durability are tightening as domestic manufacturing ambitions expand under Vision 2030 diversification targets. Stakeholders must monitor regulatory divergence between Gulf harmonization initiatives and sub-Saharan African national standards regimes to optimize regional supply chain configuration.
Market Dynamics
Saudi Vision 2030 and Qatar National Vision 2030 are redirecting public expenditure toward sports infrastructure, creating structural demand pull for performance-grade athletic footwear across government-funded academies and municipal fitness programs.
Growth Catalysts
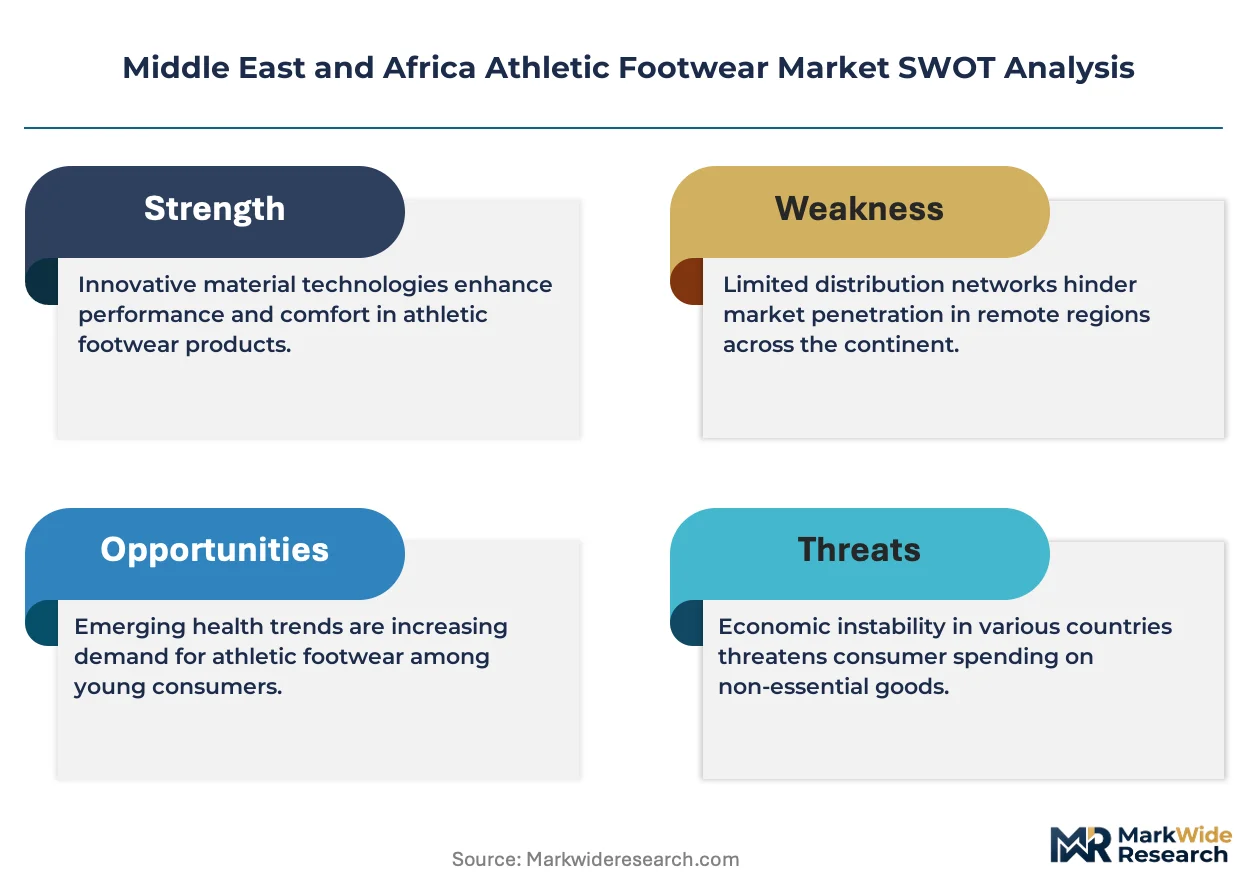
- Recycled polyester substitution:Virgin petroleum-based textile costs are destabilizing as brands pivot to ocean-plastic feedstocks, compressing raw material expenditure volatility for regional manufacturers.
- Marathon participation clusters:Dubai and Cape Town road-race calendars are expanding athlete headcounts, concentrating replacement-cycle demand for carbon-plated racing flats and daily training shoes.
- MOHAP pre-shipment mandates:The UAE's Product Conformity Scheme is filtering low-grade Asian imports, elevating quality-floor expectations and opening margin space for compliant suppliers.
Market Restraints
- Ethylene-vinyl acetate price volatility:Midsole foam feedstock costs fluctuate with crude oil benchmarks, squeezing margin predictability for value-tier product lines.
- Single-source supply concentration:Thermoplastic polyurethane energy-return plate fabrication concentrates in East Asian specialty chemical hubs, exposing regional brands to shipping disruption risk.
- SAWMA durability testing delays:South Africa's National Regulator for Compulsory Specifications extends certification timelines for imported athletic goods, compressing seasonal inventory windows.
Strategic Opportunities
- Riyadh urban fitness corridor:The Saudi capital's mall-based retail and e-commerce platform convergence is creating omnichannel white space for direct-to-consumer performance brands.
- Heat-adapted upper engineering:Breathable knit constructions with region-specific ventilation mapping address ambient temperature performance degradation unmet by temperate-climate designs.
- SASO domestic manufacturing incentives:Saudi Standards, Metrology and Quality Organization localization requirements under industrial diversification targets are subsidizing captive production capacity.
Industry Challenges
- Biomechanical engineering talent scarcity:Footwear-specific sports science and computational gait analysis expertise concentrates in Western European and North American research clusters, complicating regional R&D staffing.
- Multi-jurisdiction labeling compliance:Divergent Gulf Cooperation Council harmonization timelines versus sub-Saharan African national standards regimes multiply SKU-specific documentation overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Athletic Footwear Market |
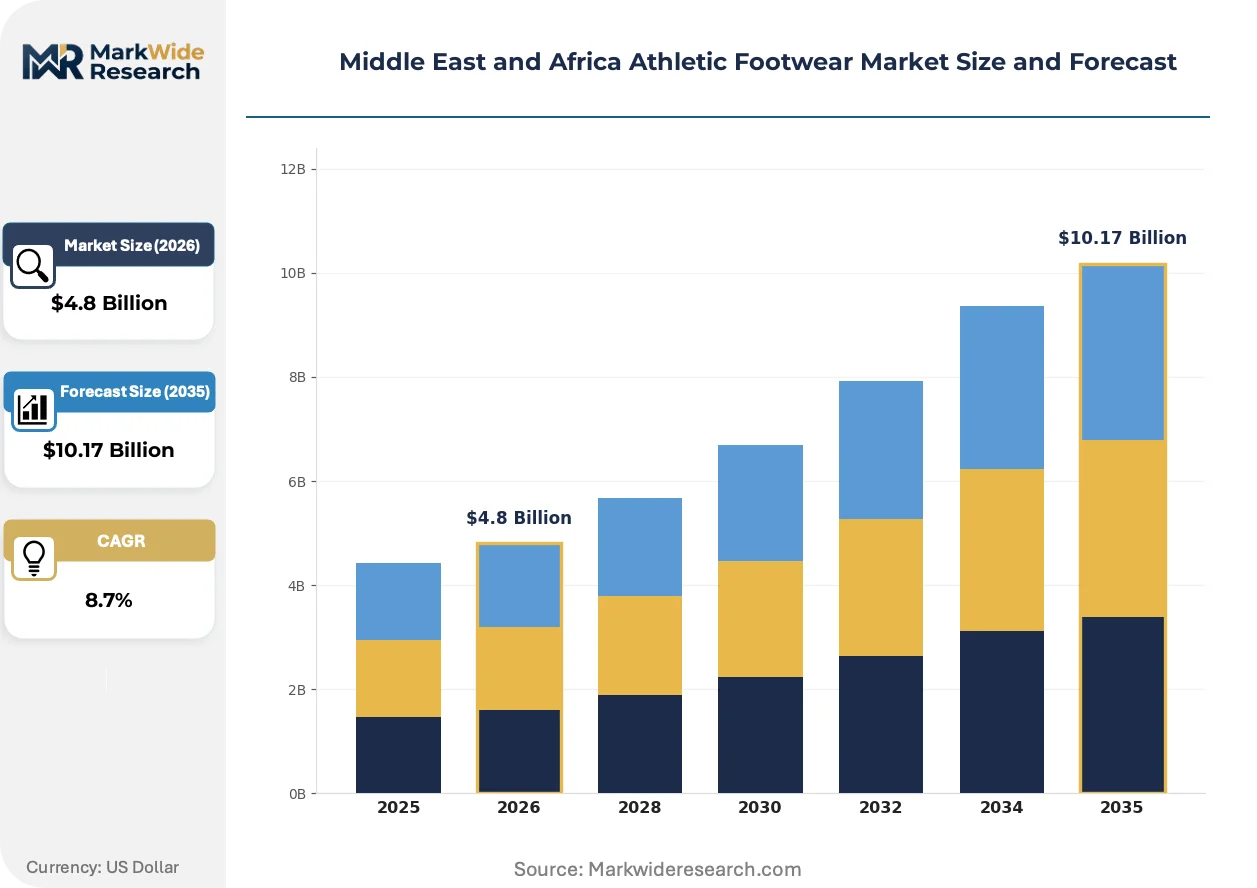
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Running Shoes, Training Shoes, Sports Sandals, Casual Sneakers End User: Men, Women, Children, Athletes Distribution Channel: Online Retail, Specialty Stores, Department Stores, Supermarkets Price Tier: Premium, Mid-Range, Budget, Luxury |
| Companies Covered | Nike Inc., Adidas AG, Under Armour Inc., Puma SE, New Balance Athletics Inc., Skechers U.S.A. Inc., ASICS Corp, Fila Inc., The North Face, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Athletic Footwear Market Shifts & Advancements
Material science convergence with climate-specific performance engineering is redefining product development priorities across Middle Eastern and African athletic footwear markets, compressing traditional design-to-shelf cycles.
Flyknit-style engineered mesh uppers are electrifying regional manufacturing economics by eliminating material waste through computerized knitting. Saudi-funded sports academies are adopting these constructions for academy-issued training footwear at accelerated procurement cadences. The technology is electrifying cost structures by collapsing cutting-and-stitching labor requirements while enabling heat-optimized ventilation patterns.
SASO slip-resistance and durability specifications are tightening enforcement scopes for imported athletic footwear, extending laboratory testing obligations before customs release. Domestic manufacturing ambitions under Vision 2030 are accelerating compliance infrastructure investment among regional distributors. Running shoe categories face the steepest certification burden given ground-contact performance claims.
Athlete-end-user procurement preferences are fragmenting across mobile-commerce platforms, compressing traditional wholesale-retail margin stacking. Government-funded sports academies in Qatar and Saudi Arabia are consolidating volume purchasing through centralized digital tenders, disintermediating multi-brand retailers. This behavioral pivot concentrates most visibly in Gulf Cooperation Council urban centers where smartphone penetration supports app-based specification comparison.
Middle East and Africa Athletic Footwear Market Segmentation
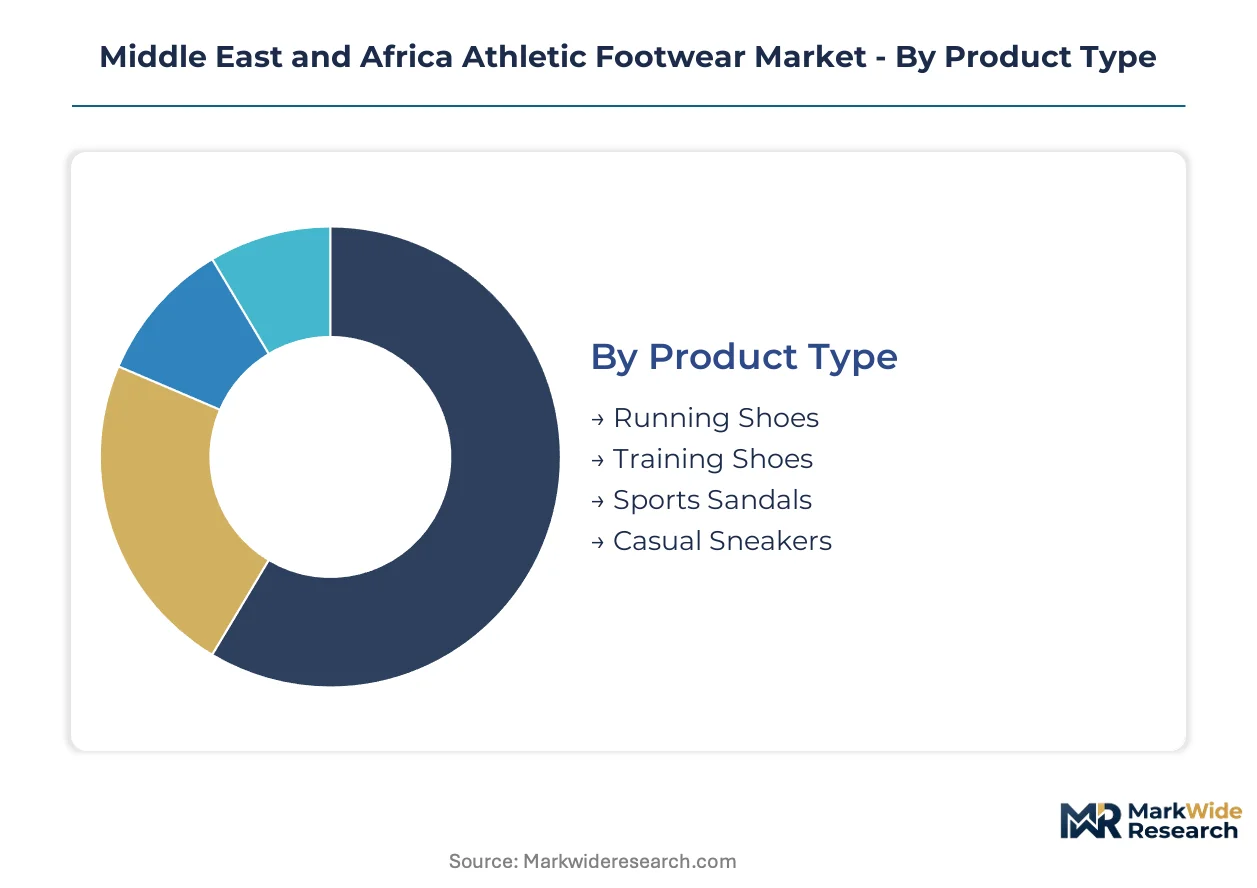
Capital allocation across the Middle East and Africa Athletic Footwear Market diverges sharply by segment, with carbon-plated racing platforms demanding polymer science investment while mass-market categories compete on logistics efficiency. Segmentation reveals where Gulf state procurement budgets concentrate versus where volume manufacturing achieves scale.
Product Type:
Running shoes absorb the heaviest R&D capitalization due to energy-return plate engineering and computational gait modeling requirements.
- Running Shoes:Ethylene-vinyl acetate midsoles paired with thermoplastic polyurethane plates attenuate ground reaction forces during propulsion. Demand clusters in Dubai and Cape Town marathon circuits where replacement cycles accelerate with race-calendar expansion.
- Training Shoes:Multi-directional traction outsoles and reinforced upper stitching withstand repetitive lateral loading. Saudi-funded sports academies issue these at volume through centralized tenders, bypassing traditional retail markup structures.
- Sports Sandals:Open-heel constructions with molded arch support address heat dissipation requirements specific to Gulf climates.
- Casual Sneakers:Lifestyle-oriented silhouettes prioritize aesthetic versatility over biomechanical performance in urban mall-based retail environments.
Most installed capacity flows through Running Shoes. Expansion is steepest in Training Shoes.
End User:
Procurement concentration varies by institutional buyer power versus individual replacement behavior.
- Athletes:Government-funded academies in Qatar and Saudi Arabia issue specification-grade footwear through digital tender platforms. MOHAP pre-shipment testing mandates filter substandard imports, elevating quality-floor requirements for academy suppliers.
- Men:Marathon participation demographics skew male in Dubai and Cape Town road-race calendars, concentrating carbon-plated racing flat demand.
- Women:Heat-adapted upper engineering with region-specific ventilation mapping addresses performance degradation in ambient Gulf temperatures.
- Children:Youth fitness program expansion under Saudi Vision 2030 widens the addressable base for academy-issued training footwear.
Procurement volume concentrates in Men. The Athletes segment is climbing the fastest.
Distribution Channel:
Margin stacking compression accelerates where smartphone penetration enables direct specification comparison.
- Online Retail:Mobile-commerce platforms capture disproportionate growth velocity among younger demographics across Gulf Cooperation Council urban centers. App-based tender participation disintermediates multi-brand retailers for institutional buyers.
- Specialty Stores:Gait analysis services and fitting expertise justify premium positioning in Dubai and Riyadh mall corridors.
- Department Stores:Aggregated footwear departments serve convenience-driven purchasers in secondary Saudi and UAE urban centers.
- Supermarkets:Value-tier placement targets impulse replacement purchases with limited technical specification requirements.
Transaction volume flows through Specialty Stores. Share gain is steepest in Online Retail.
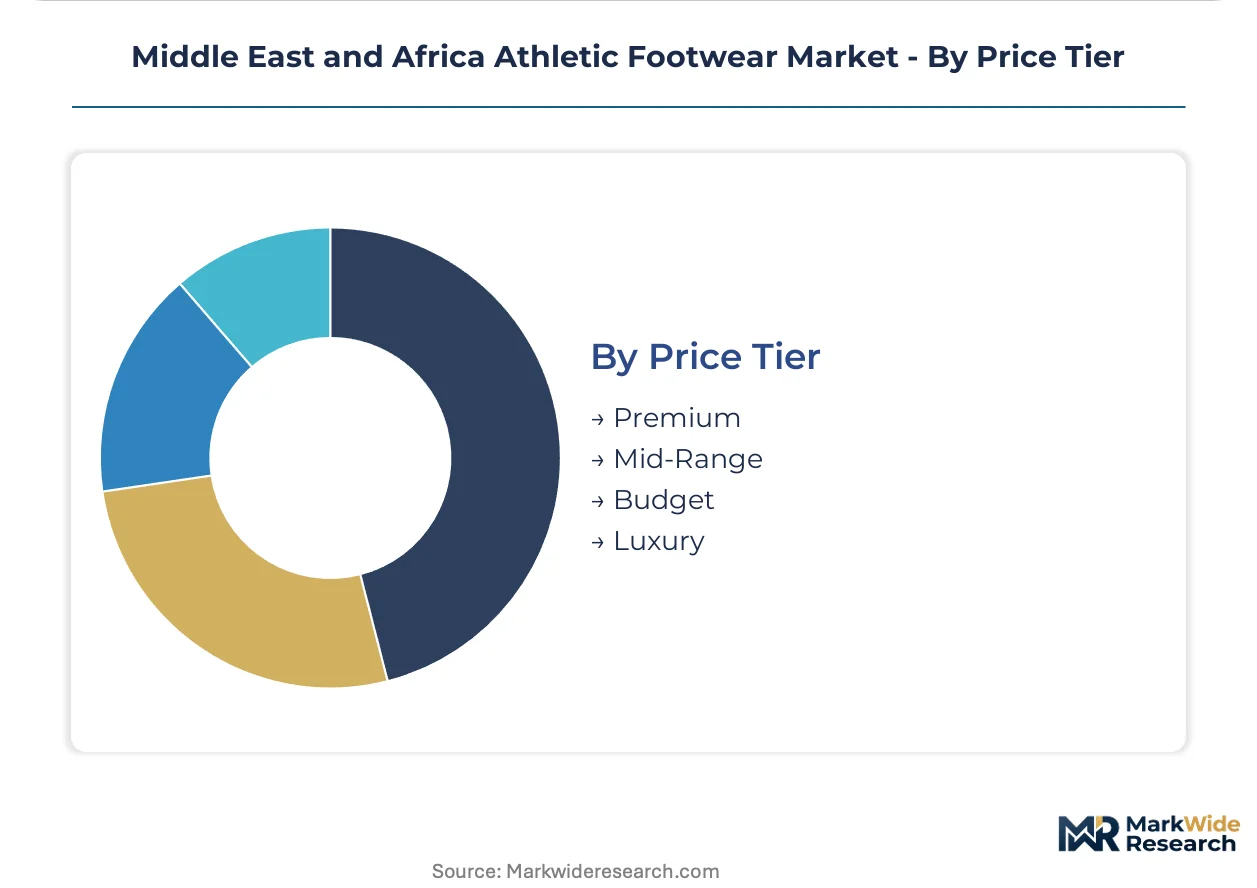
Price Tier:
Certification burden and raw material feedstock costs stratify margin structures across quality floors.
- Premium:Flyknit-style engineered mesh uppers eliminate cutting waste while enabling heat-optimized ventilation. SASO durability specifications extend laboratory testing obligations, compressing seasonal inventory windows for compliant suppliers.
- Mid-Range:Balanced construction quality meets recreational runner requirements without carbon-plate cost premiums.
- Budget:Ethylene-vinyl acetate price volatility squeezes margin predictability for value-tier product lines dependent on crude oil benchmarks.
- Luxury:Limited-edition collaborations and material storytelling command scarcity premiums in Gulf mall-based retail environments.
Revenue concentration sits in Premium. Volume manufacturing scales fastest in Mid-Range.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai's mall-based retail corridor anchors athletic footwear distribution across the Middle East and Africa, converging with Riyadh's e-commerce platform expansion to reshape procurement geography. Government-funded sports infrastructure in Gulf Cooperation Council states and marathon circuit growth in South Africa concentrate demand in distinct urban clusters. Regulatory divergence between Gulf harmonization initiatives and sub-Saharan national standards regimes complicates supply chain configuration.
United Arab Emirates
Dubai's marathon calendar and mall-based specialty retail drive carbon-plated racing flat demand among recreational runners. MOHAP pre-shipment testing mandates under the Product Conformity Scheme filter substandard Asian imports, elevating compliance costs for smaller exporters. Abu Dhabi's government-funded sports academies consolidate volume purchasing through centralized digital tenders, bypassing traditional wholesale channels.
Saudi Arabia
Vision 2030 youth fitness programs and municipal sports infrastructure expand the addressable base for academy-issued training footwear. SASO slip-resistance and durability specifications tighten enforcement scopes for imported goods, extending laboratory testing obligations before customs release. Riyadh's urban fitness corridor converges mall-based retail with mobile-commerce platforms, creating omnichannel white space for direct-to-consumer brands.
South Africa
Cape Town's road-race calendar accelerates replacement-cycle demand for daily training shoes among marathon participants. The National Regulator for Compulsory Specifications enforces labeling and performance standards that extend certification timelines for imported athletic goods. Johannesburg's specialty retail clusters concentrate gait analysis services and fitting expertise for premium-tier positioning.
Qatar
Qatar National Vision 2030 redirects public expenditure toward sports academies and municipal fitness programs, creating structural demand pull for performance-grade footwear. Government-funded sports academies issue specification-grade training shoes through digital tender platforms, disintermediating multi-brand retailers. Doha's retail infrastructure supports heat-adapted upper engineering with region-specific ventilation mapping for ambient temperature performance.
Turkey
Istanbul's geographic position bridges European supply chains with Middle Eastern distribution networks for athletic footwear logistics. The country's national standards regulator enforces import compliance requirements that filter substandard goods from Asian manufacturing centers. Ankara's domestic manufacturing base captures regional contract production for mid-range training shoe categories.
Middle East and Africa Athletic Footwear Market Competitive Landscape
Strategic partnerships dominate the current landscape as brands anchor competitive positioning through material science collaborations and localized design alliances. The vendor base concentrates around three tiers: global sportswear conglomerates with integrated R&D infrastructure, regional distributors with compliance expertise, and specialized fabricators serving institutional procurement channels. Two strategic archetypes define the field: technology licensors leveraging patented midsole formulations, and sustainability-focused operators deploying ocean-plastic feedstocks. Portfolio diversification and geographic expansion represent the dominant competitive moves, with brands extending heat-adapted product lines into Gulf markets while consolidating academy supply contracts.
Within the global conglomerate tier, Nike Inc. and Adidas AG exemplify divergent material science strategies, with the former leveraging engineered mesh manufacturing scale and the latter anchoring positioning through marine-plastic partnerships. Puma SE occupies a position emphasizing localized design collaborations that address climate-specific performance requirements. These three entities represent the primary competitive anchors, each sitting within distinct sustainability-technology positioning vectors that shape procurement preferences among Gulf-based institutional buyers and individual athletes alike.
| Leading Market Players |
|---|
| Nike Inc. |
| Adidas AG |
| Under Armour Inc. |
| Puma SE |
| New Balance Athletics Inc. |
| Skechers U.S.A. Inc. |
| ASICS Corp |
| Fila Inc. |
| The North Face |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between SASO-compliant imports and uncertified alternatives splits procurement economics across Saudi Arabia and the UAE, compressing margin structures for non-compliant suppliers while elevating pricing power for accredited distributors with in-house testing infrastructure. This bifurcation feeds directly into supply chain configuration decisions, as warehousing and logistics investments concentrate around Dubai and Jeddah customs zones where pre-shipment validation accelerates clearance velocity.
Pricing Analysis
Ethylene-vinyl acetate feedstock pass-through from crude oil benchmarks compresses margin predictability for value-tier product lines, while thermoplastic polyurethane energy-return plate costs anchor premium-tier pricing. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification burden and material specification, with academy procurement tenders favoring mid-range positioning. Pricing pressure stems from recycled polyester substitution disrupting virgin petroleum-based textile cost baselines. Institutional buyers in Qatar and Saudi Arabia exhibit lowest price sensitivity due to consolidated volume purchasing, whereas individual consumers in South Africa's secondary urban centers drive hardest bargain hunting.
Supply Chain Analysis
Single-source vulnerability sits with East Asian thermoplastic polyurethane specialty chemical hubs for energy-return plate fabrication, exposing regional brands to shipping disruption risk. Manufacturing concentration in China, Vietnam, and Indonesia feeds raw material dependencies spanning ethylene-vinyl acetate foams, engineered polyester textiles, and rubber outsole compounds. Tariff exposure compounds risk through divergent Gulf Cooperation Council harmonization timelines versus sub-Saharan African national standards regimes. Distribution runs through Dubai's mall-based retail corridor converging with Riyadh's e-commerce platform expansion, creating omnichannel fulfillment complexity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunity concentrates in heat-adapted upper engineering where recycled polyester substitution compresses input costs while SASO certification requirements filter price-competitive imports. Premium-tier positioning around climate-specific performance claims captures academy procurement budgets with reduced price elasticity.
For Market Incumbents: Anchor competitive positioning through backward integration into Flyknit-style engineered mesh manufacturing to eliminate cutting waste and accelerate heat-optimized ventilation prototyping. Defend against emerging direct-to-consumer entrants by securing exclusive academy supply contracts through digital tender platforms, leveraging existing MOHAP compliance infrastructure as a barrier to smaller exporters lacking laboratory testing capabilities. For New Entrants and Emerging Players: Government-funded sports academies in Qatar and Saudi Arabia represent the most penetrable buyer archetype, with centralized digital procurement disintermediating established multi-brand retailers. White-space opportunity concentrates in heat-adapted training shoes for youth fitness programs under Vision 2030, where specification-grade requirements remain undersupplied by temperate-climate designs. Go-to-market execution should prioritize app-based tender participation with SASO pre-certification investment to bypass traditional wholesale margin stacking. For Investors and Strategic Acquirers: Consolidation pressure builds where compliance cost barriers eliminate subscale distributors lacking in-house testing infrastructure across multiple jurisdiction regimes. Long-term viability favors vertically integrated operators with captive recycled polyester feedstock arrangements and regional manufacturing footprints under Saudi industrial diversification incentives. Acquisition target archetype: mid-range specialists with existing academy supply relationships and heat-engineering R&D capabilities. Signal to watch: SASO domestic manufacturing subsidy expansion accelerating localization timelines beyond import-dependent competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Heat-Adapted Product Line Extension | Engineered mesh ventilation mapping captures Gulf climate performance premiums in Dubai and Riyadh. |
| Recycled Polyester Feedstock Integration | Ocean-plastic sourcing partnerships compress material volatility while resonating with environmentally conscious institutional buyers. |
| Academy Supply Contract Consolidation | Centralized digital tender participation disintermediates multi-brand retailers in Qatar and Saudi procurement. |
| SASO Certification Infrastructure Investment | In-house laboratory testing accelerates customs clearance velocity and filters price-competitive uncertified imports. |
| Omnichannel Distribution Convergence | Mall-based retail and mobile-commerce platform integration captures smartphone-enabled specification comparison among younger demographics. |
Research Methodology
Multiple input streams — primary interviews with brand sourcing directors, retail category managers, and sports academy procurement officers; secondary validation through customs trade records, SASO regulatory filings, and marathon participation databases; plus competitor product specification analysis — were reconciled through bottom-up and top-down triangulation. Primary fieldwork engaged footwear brand executives, Gulf-based distributor operations heads, and South African specialty retail buyers. Secondary sources included MOHAP conformity scheme documentation, National Regulator for Compulsory Specifications standards bulletins, and regional e-commerce platform traffic analytics.
Data-stream reconciliation anchored volume and value outputs across product type, end user, distribution channel, and price tier segmentation dimensions, with additional modeling of climate-specific performance engineering adoption patterns. CAGRs were derived through trend extrapolation anchored in marathon participation growth curves, youth fitness program expansion trajectories, and mobile-commerce penetration rates. Forecast inputs incorporated recycled polyester feedstock cost displacement curves and SASO domestic manufacturing incentive evolution.
Underlying measurement precision varies by segment; running shoes and academy procurement channels carry tighter precision than casual sneakers and supermarket distribution due to data availability from institutional tender platforms. Forecasts reflect assumptions around regulatory enforcement continuity, oil price volatility transmission to ethylene-vinyl acetate costs, and Gulf state sports infrastructure investment commitment. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Footwear
E-Commerce Footwear Market
Footwear
Water Shoes Market
Footwear
Refurbished Running Shoes Market
Footwear
Snow Boots Market
Footwear
Platform Boots Market
Footwear
United States Footwear Market
Footwear
Flip Flops Market
Footwear
Premium Shoes Market
Footwear
Sandals Market
Footwear
Self-Lacing Shoes Market
Footwear
Cowboy Boots Market
Footwear
Women's Luxury Footwear Market
Footwear
Training Shoes Market
Footwear
UK Lifestyle Sneakers Market
Footwear
Footwear Testing Services Market
Footwear
Sneaker Boots Market