
 Waterproof Sneakers Market | 2026-2036
Waterproof Sneakers Market Size, Share, and Industry Trends Forecast 2026-2036
Waterproof Sneakers Market Analytics
Advanced knit-to-shape manufacturing with integrated hydrophobic yarn treatment is reshaping how waterproof sneakers achieve seam-free water barriers without sacrificing breathability. Nike leverages vertical integration in textile innovation to control proprietary membrane development from fiber to finished upper. Adidas sustains geographic dominance through European supply chain proximity to Gore-Tex headquarters in Delaware, USA. Vessi specializes in direct-to-consumer channel control, bypassing wholesale markups while capturing urban commuter demand.
Waterproof sneakers are footwear engineered with hydrophobic upper materials, sealed seams, and water-resistant midsole constructions to prevent moisture penetration during sustained exposure to wet conditions, typically rated for hydrostatic head pressure exceeding 10,000 mm. Gore-Tex membranes dominate premium construction through microporous expanded polytetrafluoroethylene layers that block liquid water while permitting vapor transmission, whereas synthetic fabric alternatives compete on cost-adjusted performance in casual and children's segments. Running shoes lead volume through year-round training demand in temperate climates, while hiking sneakers command margin pools from technical trail users requiring ankle support combined with waterproofing. Online retail is displacing specialty stores as the primary growth channel, driven by virtual try-on tools and subscription-based replacement cycles.
The EU's REACH regulation restricts perfluorinated compounds in waterproofing treatments, forcing reformulation of durable water repellent chemistries across supply chains serving European markets. The US Consumer Product Safety Commission monitors phthalate content in children's waterproof footwear, creating compliance thresholds that favor established brands with dedicated testing infrastructure. China's GB standards for footwear safety mandate slip resistance testing that indirectly shapes waterproof outsole compound selection. Stakeholders must monitor evolving chemical restriction lists and biobased material certification schemes to anticipate sourcing disruptions and premium positioning opportunities.
Market Dynamics
Knit-to-shape manufacturing with hydrophobic yarn treatment is compressing production timelines while eliminating seam vulnerabilities that previously required adhesive bonding, forcing incumbent suppliers to retool or cede share to vertically integrated textile innovators.
Growth Catalysts
- REACH perfluorinated compound restrictions:ECHA's phasedown of PFAS in durable water repellent chemistries accelerates reformulation investment by suppliers serving European markets, creating first-mover advantages for brands with compliant material pipelines.
- Urban commuter density in temperate coastal cities:Rainy-climate metropolitan areas including Seattle, Amsterdam, and Shanghai generate sustained replacement demand as waterproof sneakers displace separate rain footwear in daily rotation.
- Microporous membrane lamination:Expanded polytetrafluoroethylene layer bonding to knit uppers enables seam-free construction with hydrostatic head ratings exceeding 10,000 mm, satisfying technical trail users without sacrificing street aesthetics.
Market Restraints
- Petrochemical input volatility:Synthetic upper fabrics and polyurethane midsoles expose margins to crude oil derivative price swings that compress working capital for mid-tier manufacturers lacking forward contracts.
- Gore-Tex supply concentration:Premium membrane sourcing dependence on Delaware-headquartered W.L. Gore creates bottleneck risk for brands without alternative hydrophobic barrier partnerships or in-house membrane development.
- Breathability-performance tradeoff:Hydrophobic treatments sufficient for 10,000 mm ratings reduce vapor transmission rates, limiting adoption among high-output runners generating substantial perspiration.
Strategic Opportunities
- Children's segment underpenetration:GB standards-compliant slip-resistant outsoles meeting China's mandatory footwear safety testing open volume pools in a category where replacement frequency exceeds adult rates.
- Solvent-free adhesive regulatory tailwind:EU Green Deal textile sustainability requirements favor brands with water-based bonding processes, creating positioning distance from competitors reliant on volatile organic compound-heavy construction.
- Direct-to-consumer subscription models:Urban commuters in Germany and the United States accept automated replacement cycles for worn waterproofing, bypassing wholesale markups while capturing predictable recurring revenue.
Industry Challenges
- Biobased material certification complexity:Multiple competing sustainability standards for recycled synthetic fabrics create compliance fragmentation, forcing brands to maintain parallel documentation for EU, US, and Asian market access.
- Knit-to-shape equipment capex intensity:Shoemakers must deploy capital for computerized flat knitting machines with integrated yarn treatment stations, straining balance sheets before volume efficiencies materialize.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Waterproof Sneakers Market |
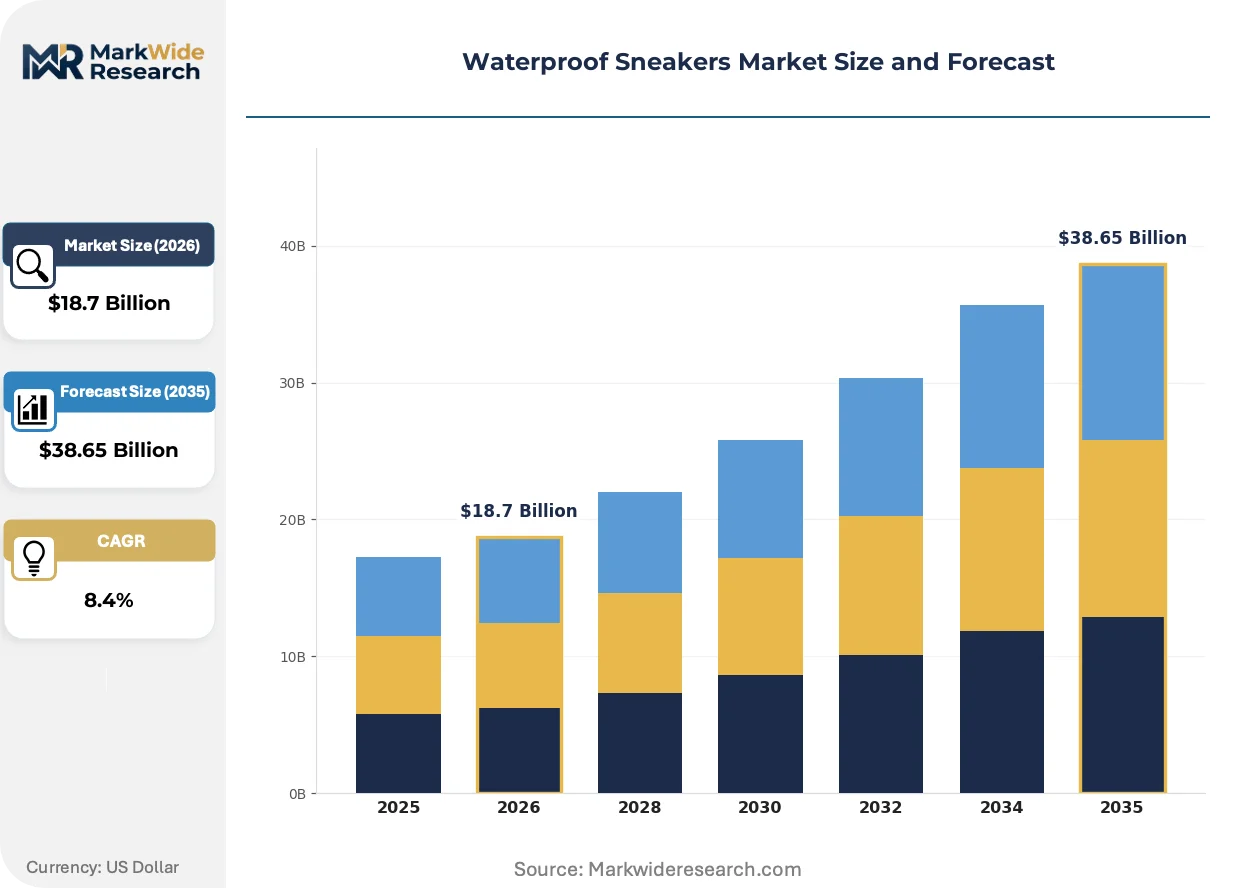
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Running Shoes, Casual Sneakers, Hiking Sneakers, Sports Sneakers Material: Gore-Tex, Rubber, Synthetic Fabric, Neoprene End User: Men, Women, Kids, Athletes Distribution Channel: Online Retail, Specialty Stores, Department Stores, Direct Sales |
| Companies Covered | Converse, Vessi, Adidas, ON Running, Hoka, Salomon, Nike, Puma, New Balance, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Waterproof Sneakers Market Evolving Landscape
Digital integration is penetrating waterproof sneaker development from design through post-purchase engagement, compressing traditional product cycles while enabling predictive replacement models that alter inventory risk distribution.
Integrated sensor arrays embedded in midsole constructions are digitizing performance feedback for training applications. Serious runners in the United States and Germany adopt connected footwear that transmits gait analysis and wear-state data to mobile applications. This connectivity is digitizing warranty claim verification and enabling outcome-based replacement triggers rather than calendar-driven purchases.
REACH restrictions on perfluorinated compounds are forcing reformulation of durable water repellent chemistries across supply chains serving European markets. Manufacturers serving EU-bound production must validate alternative hydrophobic treatments through accelerated aging protocols. Children's waterproof sneakers face the steepest compliance timeline pressure given CPSC phthalate monitoring叠加 ECHA substance restrictions.
Virtual try-on tools are displacing physical fitting room visits in waterproof sneaker purchasing decisions. Specialty outdoor retailers lose foot traffic to direct-to-consumer platforms offering augmented reality size matching and hassle-free waterproofing performance guarantees. This channel migration concentrates most visibly in urban commuter segments across China and Germany where smartphone commerce penetration exceeds general footwear categories.
Waterproof Sneakers Market Segmentation
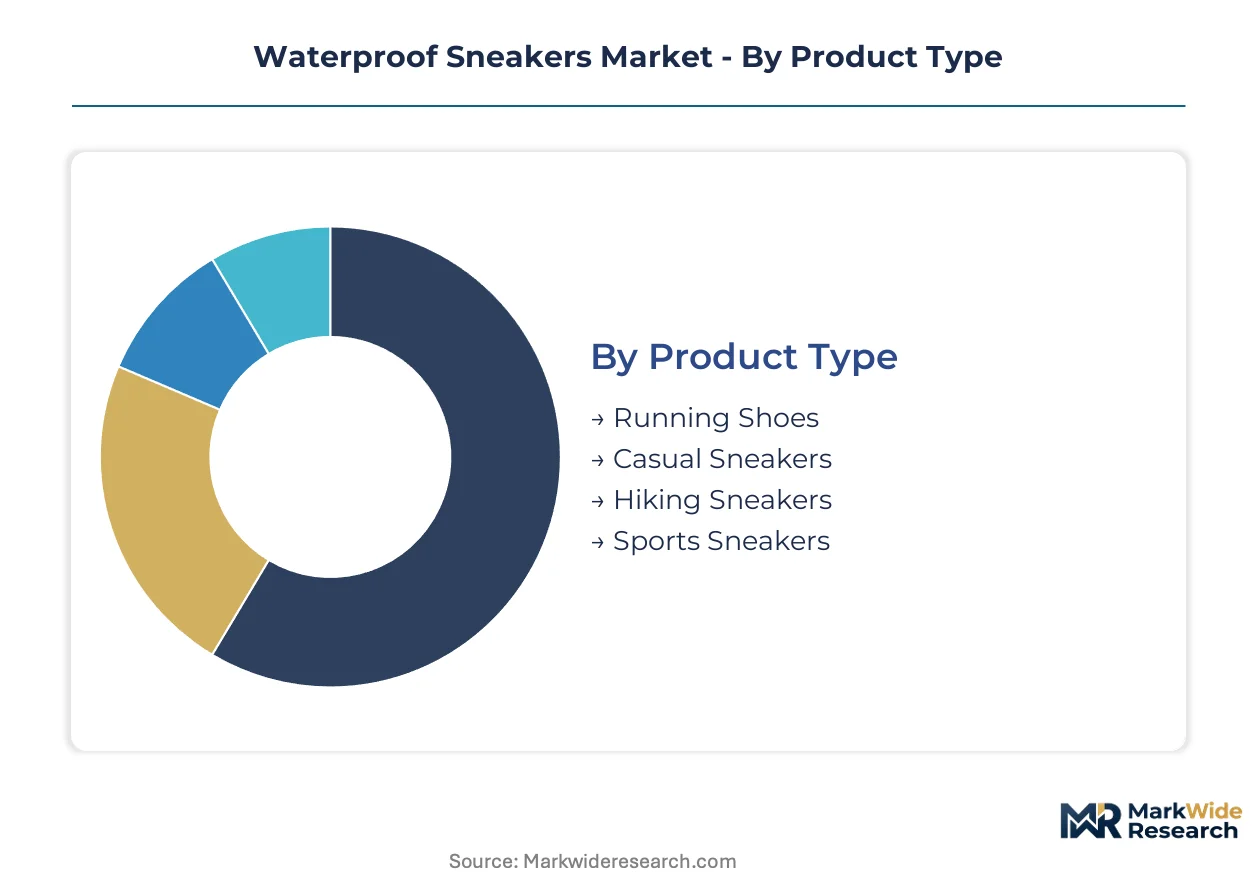
Waterproof sneakers serve divergent performance requirements across daily commuting, technical trail use, and children's recreational wear. Segmentation reveals how membrane technology, distribution economics, and end-user durability expectations reshape product positioning and margin structures.
Product Type:
Use cases span from high-output athletic training to casual urban navigation, with technical specifications scaling to activity intensity.
- Running Shoes:Year-round training demand in temperate climates drives volume concentration. Seattle and Amsterdam urban runners prioritize 10,000 mm hydrostatic ratings for daily mileage without separate rain footwear.
- Hiking Sneakers:Technical trail users require ankle support combined with waterproof barriers. Germany's Black Forest and Pacific Northwest trail systems generate replacement cycles tied to outsole wear rather than membrane degradation.
- Casual Sneakers:Street aesthetics dominate; Shanghai and Amsterdam commuters accept lower breathability ratings for seamless office-to-transit versatility.
- Sports Sneakers:Court and field applications prioritize lateral stability over hydrophobic performance; waterproofing serves secondary weather protection in seasonal training blocks.
Established volume favors Running Shoes; emerging adoption favors Hiking Sneakers as trail participation climbs in Germany and the United States.
Material:
Cost tiers separate premium membrane lamination from commodity hydrophobic treatments, with regulatory compliance adding sourcing complexity.
- Gore-Tex:Microporous expanded polytetrafluoroethylene layers deliver 10,000+ mm ratings with vapor transmission. REACH perfluorinated compound restrictions force reformulation timelines for EU-bound production.
- Synthetic Fabric:Cost-adjusted performance targets casual and children's segments. Chinese manufacturers leverage GB standards compliance for domestic volume and export positioning.
- Rubber:Solid construction eliminates seam vulnerabilities; limited breathability restricts adoption to short-duration urban exposure.
- Neoprene:Insulation properties serve cold-climate commuting; bulk and weight limit athletic applications.
Premium positioning concentrates with Gore-Tex; volume expansion tracks Synthetic Fabric as recycled content requirements tighten under EU Green Deal textile sustainability mandates.
End User:
Replacement frequency and sizing complexity create divergent margin profiles across demographic segments.
- Men:Technical specifications dominate purchasing decisions; trail running and hiking applications drive membrane performance requirements.
- Women:Athleisure crossover demand concentrates in urban commuter corridors; fit customization challenges legacy last designs.
- Kids:Replacement cycles exceed adult rates; CPSC phthalate monitoring and REACH substance restrictions impose steepest compliance timelines.
- Athletes:Performance validation through hydrostatic testing and accelerated aging protocols; sponsorship relationships drive brand concentration.
Volume concentration sits with Men; steepest expansion trajectory belongs to Kids as safety standard harmonization opens cross-border sourcing.
Distribution Channel:
Channel economics determine warranty handling complexity and inventory risk distribution.
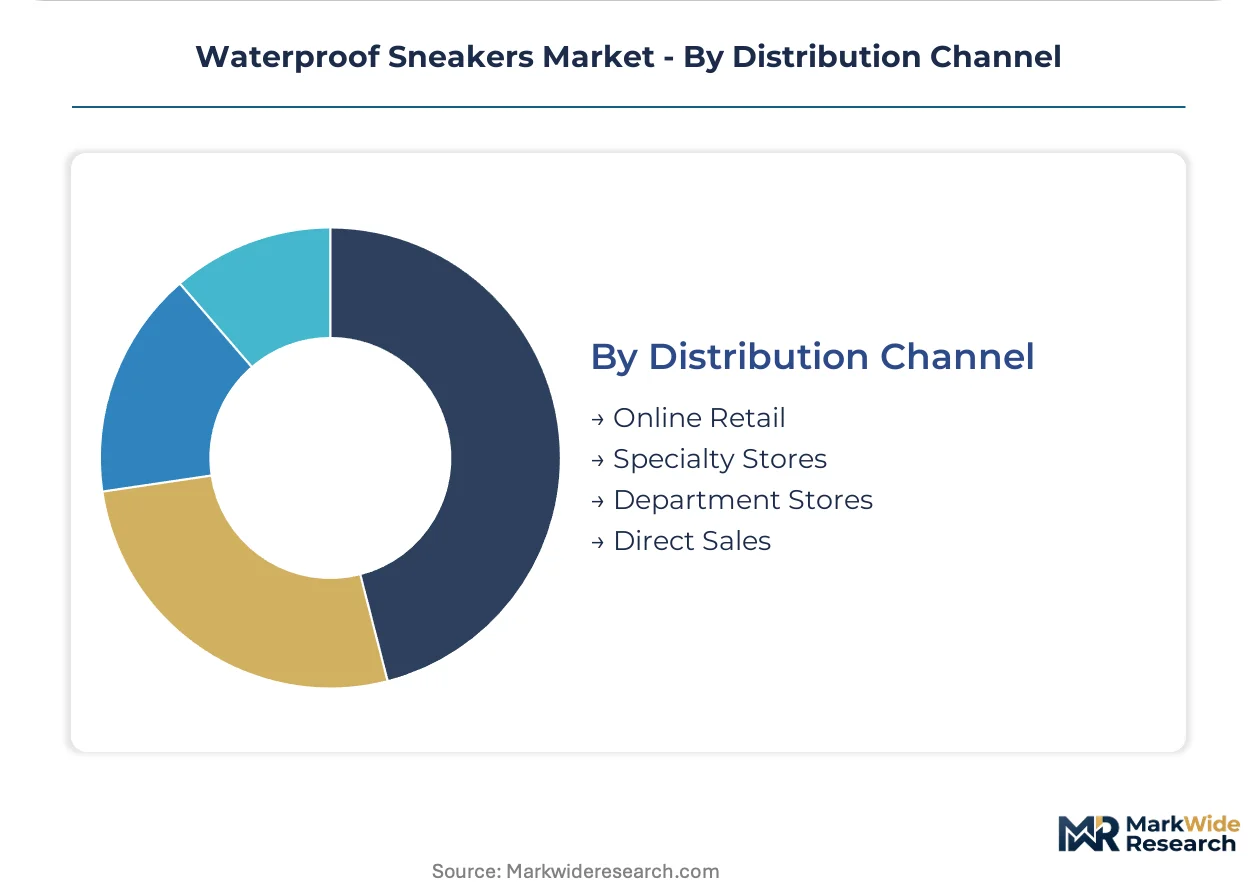
- Online Retail:Virtual try-on tools and subscription replacement cycles displace physical fitting. Germany and China lead smartphone commerce penetration for waterproof sneaker categories.
- Specialty Stores:Technical fitting expertise retains trail runner loyalty; foot traffic erosion accelerates in urban commuter segments.
- Department Stores:Seasonal assortment breadth serves occasional purchasers; waterproofing performance guarantees reduce return rates.
- Direct Sales:Captive margin control supports membrane technology investments; Vessi's channel model demonstrates recurring revenue viability.
Volume migration favors Online Retail; margin protection concentrates with Direct Sales as automated replacement cycles mature in Germany and the United States.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in waterproof sneakers tilt toward import dependence in European and North American consumer markets, while East Asian manufacturing clusters supply membrane components and finished footwear. Currency fluctuations and regulatory divergence shape sourcing patterns across major consumption zones.
United States
Pacific Northwest urban commuters in Seattle and Portland sustain replacement demand for daily waterproof trainers. The US Consumer Product Safety Commission enforces phthalate limits in children's footwear, favoring established brands with dedicated testing infrastructure. Massachusetts and Oregon host technical outdoor retail clusters where specialty fitting expertise retains trail runner loyalty despite online channel erosion.
Germany
Black Forest trail systems and Bavarian Alpine access drive technical hiking sneaker adoption among outdoor enthusiasts. ECHA's REACH perfluorinated compound restrictions force reformulation of durable water repellent chemistries for EU-bound production. Bavaria concentrates membrane lamination R&D partnerships between footwear brands and material suppliers navigating compliance timelines.
China
Shanghai and Guangzhou urban commuters accept lower breathability ratings for office-to-transit versatility in rainy subtropical climates. GB standards for footwear safety mandate slip resistance testing that shapes outsole compound selection across domestic and export production. Fujian and Zhejiang manufacturing clusters supply synthetic fabric uppers with recycled content certification for European market access.
Netherlands
Amsterdam's cycling-integrated commuting culture generates sustained demand for seamless waterproof street aesthetics. EU Green Deal textile sustainability requirements push brands toward solvent-free adhesive processes and recycled synthetic fabrics. Randstad logistics hubs facilitate direct-to-consumer distribution models targeting German and Belgian cross-border purchasers.
Japan
Tokyo and Osaka metropolitan areas prioritize compact, packable waterproof footwear for crowded transit environments. METI's guidance on sustainable material procurement influences brand positioning toward biobased certification schemes. Kansai industrial zones host precision knitting equipment suppliers serving regional footwear manufacturers.
Waterproof Sneakers Market Competitive Landscape
On the supply side, the industry is bifurcated between vertically integrated textile innovators controlling proprietary membrane development and brand marketers dependent on external material sourcing. Three strategic archetypes dominate: performance athletic houses with in-house R&D pipelines, direct-to-consumer specialists bypassing wholesale markups, and outdoor heritage brands leveraging technical credibility. Competitive moves concentrate on knit-to-shape equipment deployment and geographic supply chain repositioning to mitigate REACH compliance costs.
Within the vertically integrated tier, Nike exemplifies captive control over fiber-to-finished-upper membrane development. Adidas occupies a position anchored by European supply chain proximity to Gore-Tex headquarters. Vessi represents the direct-to-consumer archetype, demonstrating recurring revenue viability through subscription-based replacement cycles targeting urban commuter density in temperate coastal cities.
| Leading Market Players |
|---|
| Converse |
| Vessi |
| Adidas |
| ON Running |
| Hoka |
| Salomon |
| Nike |
| Puma |
| New Balance |
| Others |
Value Network & Pricing Analysis
Overcapacity in Fujian and Zhejiang knitting equipment is compressing membrane lamination margins while forcing suppliers toward automated hydrophobic yarn treatment stations that alter both cost structures and buyer negotiation leverage.
Pricing Analysis
Urban commuter buyers anchor a three-tier pricing structure across premium, standard, and economy levels where Gore-Tex certification and hydrostatic head ratings drive price differentiation. Price erosion runs through synthetic fabric tiers as Chinese manufacturers achieve GB standards compliance at scale. Professional trail runners show lowest price sensitivity; children's replacement cycles face highest sensitivity given CPSC phthalate testing costs embedded in landed pricing.
Supply Chain Analysis
Tariff exposure between China and the United States dominates strategic sourcing decisions for brands dependent on Delaware-headquartered Gore-Tex membrane supply. Manufacturing concentrates in Fujian, Zhejiang, and Vietnam for knit-to-shape uppers; polyurethane midsoles and expanded polytetrafluoroethylene layers feed from South Korean and Japanese chemical suppliers. Single-source vulnerability in microporous membrane lamination creates bottleneck risk. Distribution runs through direct-to-consumer platforms and automated replacement cycles in Germany and the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Waterproof sneaker demand is accelerating through knit-to-shape manufacturing disruption as REACH perfluorinated compound restrictions force supply chain repositioning and create first-mover advantages for compliant material pipelines.
For Market Incumbents: Build captive membrane development moats through backward integration into hydrophobic yarn treatment and computerized flat knitting equipment. Adidas and Nike demonstrate divergent paths: European supply chain proximity to Gore-Tex headquarters versus fiber-to-finished-upper control. Defend against direct-to-consumer subscription models by deploying automated replacement cycles that capture urban commuter lifetime value in Seattle and Amsterdam. For New Entrants and Emerging Players: Japan's underpenetrated compact waterproof footwear segment for crowded Tokyo transit environments offers white-space expansion with packable street aesthetics. Target children's segments in China where GB standards-compliant slip-resistant outsoles open volume pools with replacement frequency exceeding adult rates. Launch through virtual try-on platforms with hassle-free waterproofing performance guarantees to bypass specialty retail gatekeepers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across knit-to-shape equipment deployment as computerized flat knitting machines with integrated yarn treatment stations strain balance sheets before volume efficiencies materialize. Five-to-ten year viability favors brands with demonstrated direct-to-consumer recurring revenue models and solvent-free adhesive regulatory positioning under EU Green Deal mandates. Monitor ECHA substance restriction timelines as inflection signals for sourcing disruption and premium positioning opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Knit-to-Shape Equipment Deployment | Computerized flat knitting with hydrophobic yarn treatment eliminates seam vulnerabilities and compresses production timelines. |
| Solvent-Free Adhesive Transition | EU Green Deal textile sustainability requirements favor water-based bonding processes over volatile organic compound-heavy construction. |
| Direct-to-Consumer Subscription Launch | Automated replacement cycles in Germany and the United States capture predictable recurring revenue from urban commuter density. |
| REACH-Compliant Membrane Development | ECHA perfluorinated compound reformulation timelines create first-mover advantages for brands with alternative hydrophobic pipelines. |
| Children's Segment Safety Certification | CPSC phthalate monitoring and GB standards compliance open cross-border sourcing in high-frequency replacement categories. |
Research Methodology
Operator-level perspectives from footwear brand R&D directors, textile manufacturing plant managers, specialty outdoor retail buyers, and direct-to-consumer logistics operators anchored the qualitative base. Primary interviews combined with secondary validation from customs records, SEC footwear sector filings, ECHA substance restriction databases, and GB standards documentation. Bottom-up volume modeling across product type, material tier, end-user demographic, and distribution channel triangulated against top-down market sizing from trade flow analysis.
Scenario-bracketing around REACH compliance timelines and petrochemical input volatility shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type intensity, membrane technology tier, end-user replacement frequency, and channel economics. CAGRs derived from elasticity-adjusted demand curves incorporating urban commuter density indices and outdoor participation rates. Industry-specific inputs encompassed hydrostatic head testing protocols and accelerated aging validation standards.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated textile innovators or regulatory arbitrageurs would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Footwear
UGG Boots Market
Footwear
US Slip Resistant Shoes Market
Footwear
Asia-Pacific Athletic Footwear Market
Footwear
Ankle Boots Market
Footwear
Women's Luxury Footwear Market
Footwear
Hiking Footwear Market
Footwear
Gypsy Jazz Shoes Market
Footwear
Refurbished Running Shoes Market
Footwear
Sneaker Boots Market
Footwear
Barefoot Shoes Market
Footwear
Dance Shoes Market
Footwear
North America Athletic Footwear Market
Footwear
Kids Barefoot Shoes Market
Footwear
Cowgirl Boots Market
Footwear
Men Formal Shoe Market
Footwear
Loafers Market