
 Custom Shoes Market | 2026-2036
Custom Shoes Market Size, Share, and Industry Trends Forecast 2026-2036
Custom Shoes Market Intelligence
3D foot scanning combined with AI-driven design platforms is rewriting how custom shoes move from measurement to production. Nike Inc. leverages its proprietary digital ecosystem to compress design-to-delivery timelines for personalized athletic footwear. Adidas AG anchors its custom operations through Speedfactory-adjacent micro-manufacturing networks that localize production near demand clusters. AliveShoes Inc. differentiates by sustaining a direct-to-creator platform that lets independent designers control their own branded custom shoe lines.
Custom shoes are individually fitted or designed-to-order footwear produced through digital measurement capture, automated or hand-last construction, and material selection tailored to biomechanical or aesthetic preference, with typical production runs of one unit or small batches for specific end users. The primary commercial purpose is eliminating fit-related returns while commanding price premiums through exclusivity and ergonomic precision. Athletic shoes dominate volume within the product type dimension as sports-specific customization becomes standard for serious competitors, while leather commands the deepest margin pools in the material segment due to artisan positioning and durability expectations. Fully customized offerings represent the fastest-growing customization level as consumers trade up from semi-customized configurations for special occasions and performance needs.
FDA oversight of medical-grade orthotic claims intersects with FTC truth-in-advertising standards to shape how US custom shoe brands market health benefits and material sourcing. The EU Green Deal and REACH chemical restrictions are forcing European producers to reformulate adhesives and tanning processes, raising compliance costs but creating competitive barriers for sustainable-certified suppliers. Stakeholders must monitor how digital ownership frameworks and biometric data regulations evolve alongside customization platforms, since foot-scan databases represent both an asset class and a liability exposure that will determine which brands retain consumer trust at scale.
Market Dynamics
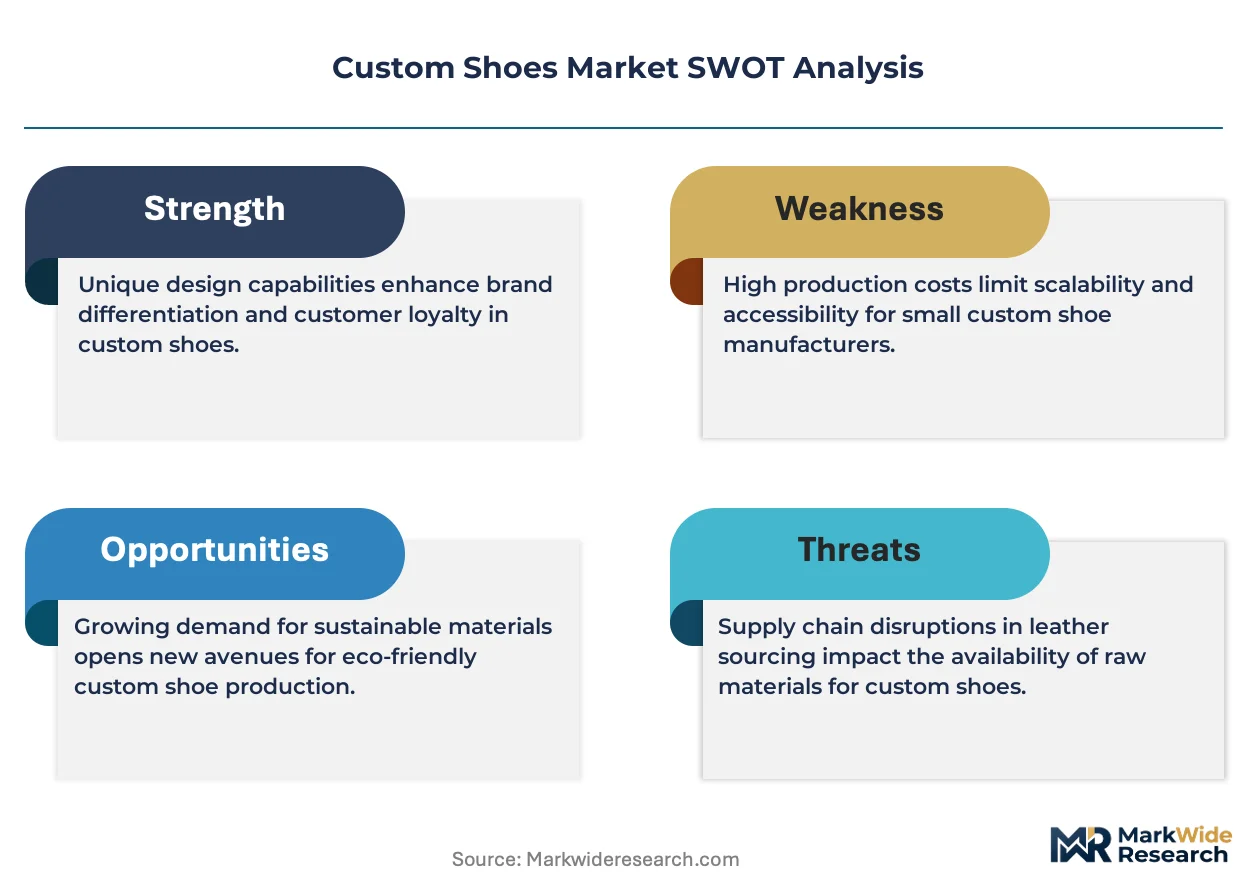
3D foot scanning and AI-driven design platforms are compressing the traditional measurement-to-production pipeline, forcing incumbents to rebuild their digital infrastructure or cede ground to agile micro-manufacturing networks. This technological inflection is simultaneously lowering entry barriers for specialized players while raising capital requirements for legacy operators seeking retrofit compatibility.
Growth Catalysts
- EU Green Deal sustainable material mandates:European producers are reformulating adhesives and tanning processes to meet REACH chemical restrictions, creating certified supplier premiums that reward early compliance investments.
- Professional athlete segment expansion:Performance personalization has become standard for serious competitors, with sports-specific biomechanical customization driving repeat purchase cycles and brand loyalty lock-in.
- China manufacturing cluster maturation:Domestic brands in Dongguan and Wenzhou are capturing rising local consumer interest through vertically integrated bespoke footwear operations with sub-14-day delivery windows.
Market Restraints
- Leather input cost volatility:Artisan-grade hides face supply pressure from livestock cycle fluctuations and competing industrial uses, squeezing margin pools for premium positioning strategies.
- Adhesive formulation technical limitations:Bio-based bonding agents under EU Green Deal compliance timelines currently fail durability stress tests for high-performance athletic applications, forcing hybrid material strategies.
- Medical-grade orthotic regulatory friction:FDA oversight of biomechanical health claims intersects with FTC truth-in-advertising standards, creating multi-agency review bottlenecks for brands marketing ergonomic benefits.
Strategic Opportunities
- India underpenetrated geography:The country's PLI scheme for footwear manufacturing offers cost-competitive production bases for export-oriented custom operations targeting Middle East and African markets.
- Biometric data regulatory tailwind:Evolving GDPR and emerging digital ownership frameworks in the EU create first-mover advantages for brands architecting compliant foot-scan database architectures.
- Direct-to-creator platform convergence:Independent designer marketplaces are hybridizing with micro-manufacturing networks, enabling asset-light brand building without captive production facilities.
Industry Challenges
- Digital-physical integration complexity:Legacy ERP systems require costly API redevelopment to sync with real-time 3D scanning data streams and automated last-generation machinery.
- Orthopedic certification timeline compression:Medical device pathway approvals through notified bodies under EU MDR extend go-to-market schedules by 18-24 months for biomechanical positioning claims.
- Specialized last-making skill scarcity:Master craftsmen capable of translating scan data into hand-finished wooden or polymer lasts are concentrating in aging European and Japanese workshops with limited knowledge transfer pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Custom Shoes Market |
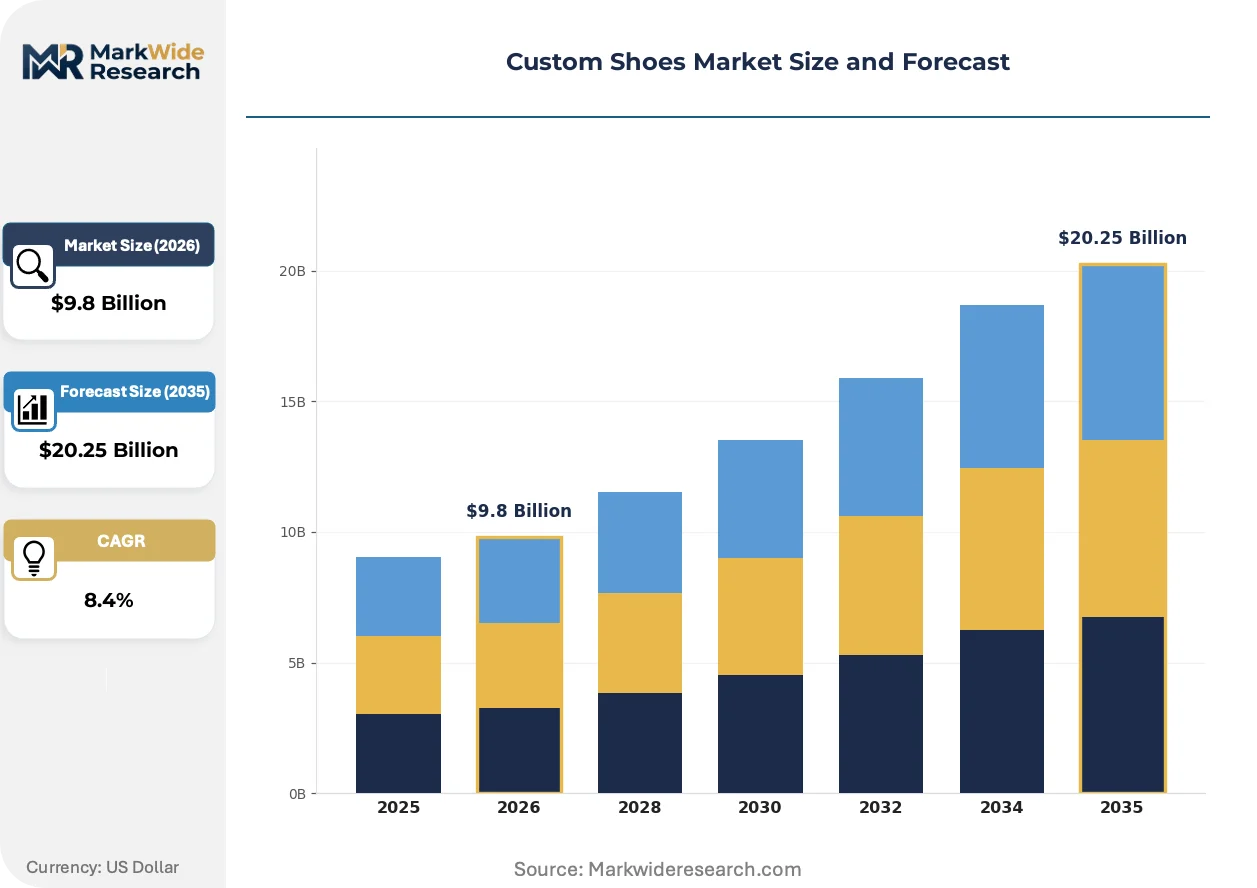
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $20.25 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Athletic Shoes, Dress Shoes, Casual Shoes, Sandals Material: Leather, Canvas, Synthetic, Rubber Customization Level: Fully Customized, Semi-Customized, Pre-Designed, Standard Target Audience: Men, Women, Children, Athletes |
| Companies Covered | Nike Inc., Adidas AG, AliveShoes Inc., John Lobb, Crockett & Jones Ltd., New Balance Athletics Inc., PUMA SE, Italian Shoe Factory, Carmina Shoemaker, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Custom Shoes Market Strategic Shifts & Innovations
Digital measurement capture is converging with automated construction methods to collapse the traditional bespoke footwear timeline from weeks to days. This compression is reshaping competitive positioning around speed-to-customer rather than solely craftsmanship heritage.
Generative design algorithms paired with robotic knitting and selective laser sintering are hybridizing material deposition methods for midsole and upper components. Performance runners and court sport competitors are adopting these hybrid constructions fastest, with professional athletes now expecting same-design-cycle iteration based on competition feedback. The technology is compressing R&D-to-retail timelines from seasonal cycles to continuous release models.
REACH chemical restrictions under the EU Green Deal are forcing systematic reformulation of chrome tanning and solvent-based adhesives across European value chains. Industrial consequence includes 15-30% input cost elevation for compliant material sourcing, with small-batch artisan producers in Italy and Portugal most affected and responding through cooperative certification pooling to amortize compliance auditing.
After-sales unbundling is fragmenting the traditional retail-service bundle as direct-to-consumer brands separate fitting consultation from physical product delivery. Independent podiatrists and physiotherapy clinics are displacing department store shoe departments as the primary measurement touchpoint, with Germany and the Netherlands showing the fastest channel restructuring toward medical-professional referral networks.
Custom Shoes Market Segmentation
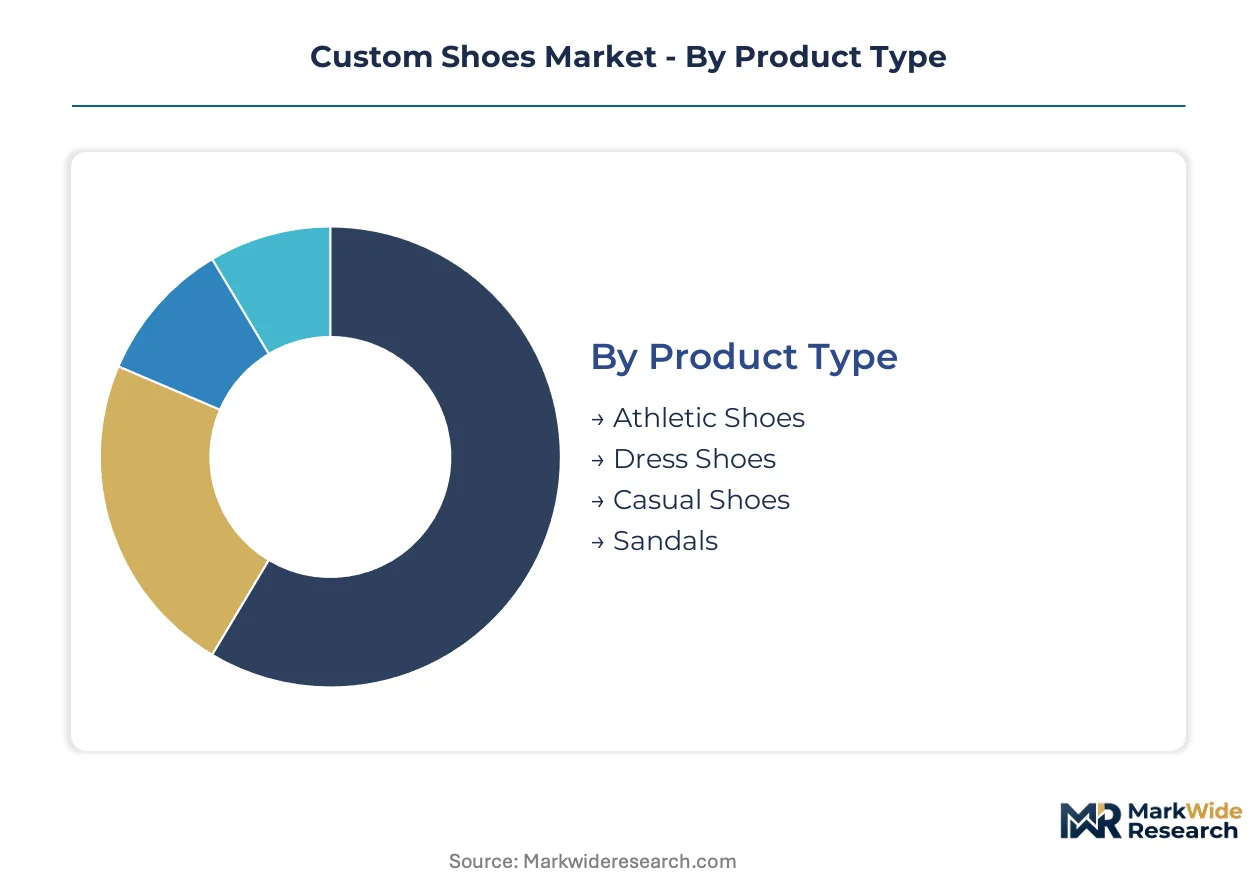
Segmentation in custom footwear determines service intensity, production workflow complexity, and margin architecture. Each dimension carries distinct after-sales obligations and customer lifetime value profiles that shape brand positioning.
Product Type:
Athletic shoes demand the highest post-purchase service density, with gait analysis adjustments and midsole replacement programs sustaining multi-year customer relationships.
- Athletic Shoes:Engineered for biomechanical precision with sports-specific cushioning zones and traction patterns. Serious competitors in the US and Germany drive repeat purchase cycles as performance personalization becomes standard for amateur and professional tiers alike.
- Dress Shoes:Formal silhouettes emphasizing hand-finished patina work and welted construction durability. Italian and Portuguese artisan workshops capture premium positioning through heritage craftsmanship certification and multi-decade recrafting services.
- Casual Shoes:Versatile everyday wear balancing aesthetic flexibility with moderate customization depth.
- Sandals:Open-strap constructions prioritizing heat-moldable footbeds and adjustable closure systems for warm-climate markets.
By volume, Athletic Shoes leads. By growth pace, Dress Shoes is ahead as post-pandemic formal occasion attendance rebounds.
Material:
Material selection governs compliance burden and refurbishment economics, with European tanneries facing the steepest regulatory cost escalations.
- Leather:Full-grain hides processed through vegetable or chrome tanning deliver superior moldability and aging character. REACH chemical restrictions under the EU Green Deal have elevated compliant sourcing costs, squeezing margin pools for small-batch Italian producers most acutely.
- Synthetic:Engineered polymers and recycled PET textiles enabling complex color gradients and weatherproofing. Dongguan manufacturing clusters in China dominate volume production through vertically integrated knitting and bonding operations.
- Canvas:Woven cotton or hemp uppers offering breathability and dye-substitution flexibility for casual applications.
- Rubber:Natural and synthetic compounds for outsoles and waterproof boot constructions in industrial and outdoor end-uses.
Leather commands the deepest margin pools. Synthetic materials are climbing fastest as athletic brands prioritize weight reduction and moisture management.
Customization Level:
Depth of personalization directly correlates with measurement touchpoint frequency and production lead time variability.
- Fully Customized:Individual last creation from 3D scan data with material and aesthetic specification control. Professional athletes and wedding occasion buyers in China and the US trade up from semi-custom configurations, compressing design-to-delivery timelines through AI-driven pattern generation.
- Semi-Customized:Modular component selection across pre-engineered lasts with limited dimensional adjustment. European direct-to-consumer brands leverage this tier to balance personalization depth with sub-10-day fulfillment.
- Pre-Designed:Artist or influencer collaboration templates with size-specific scaling but fixed aesthetics.
- Standard:Off-the-shelf sizing with monogramming or colorway selection as the sole personalization vector.
Fully Customized holds the smallest volume share. Semi-Customized generates the steepest expansion trajectory as brands automate pattern adaptation.
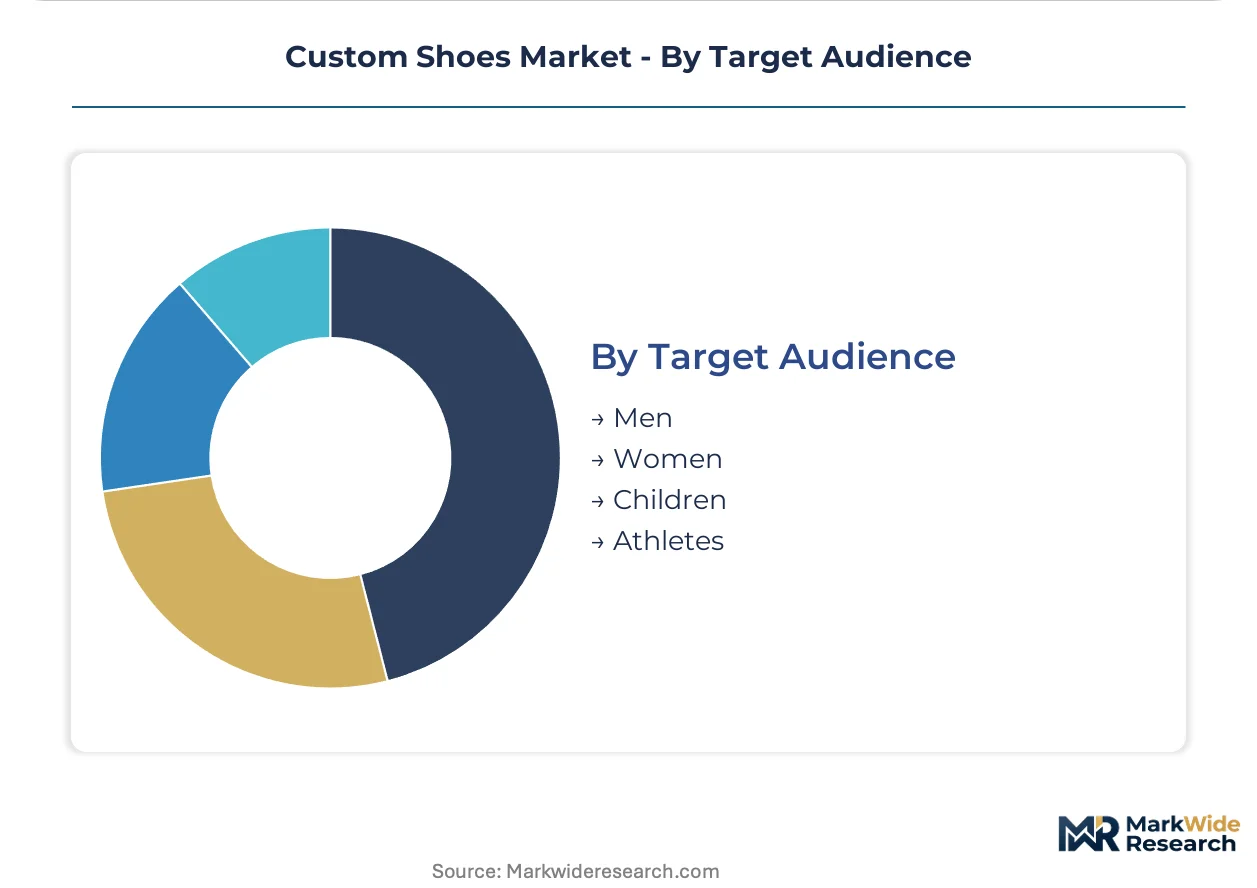
Target Audience:
Audience segmentation shapes channel strategy, with medical-professional referral networks displacing traditional retail for biomechanical positioning.
- Men:Largest absolute spenders across formal and athletic categories, with podiatrist-referred orthotic integration driving premium capture in Germany and the Netherlands.
- Women:Fastest-growing demand for performance running customization as female-specific last engineering gains technical validation.
- Children:Growth-tracking programs with semi-annual refitting subscriptions, concentrated in urban Chinese markets with high parental expenditure on developmental footwear.
- Athletes:Professional and serious amateur competitors requiring same-design-cycle iteration based on competition feedback and injury rehabilitation protocols.
Men account for the greatest revenue concentration. Women are expanding most quickly as sports-specific product development accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Professional athletes and medical-referred orthotic buyers concentrate in the United States and Germany, while China's domestic bespoke segment accelerates through vertically integrated manufacturing clusters.
United States
FDA-regulated biomechanical health claims intersect with FTC truth-in-advertising standards for custom athletic footwear marketing. Podiatrist-referred orthotic integration drives premium capture in metropolitan markets. Boston and Portland host dense concentrations of performance-running customization studios serving collegiate and professional athlete segments.
Germany
EU Green Deal REACH chemical restrictions are reformulating adhesive and tanning processes across Baden-Württemberg tanneries. KBA-adjacent industrial standards influence durability testing protocols for custom automotive-worker safety footwear. Munich and Stuttgart anchor medical-professional referral networks that displace traditional retail fitting consultations.
China
Domestic brands in Dongguan and Wenzhou manufacturing clusters capture rising local consumer interest through sub-14-day bespoke delivery windows. MEE dual carbon goals pressure reformulation of solvent-based bonding agents in Pearl River Delta factories. Beijing and Shanghai concentrate AI-driven 3D scanning platform deployment for wedding-occasion fully customized demand.
Italy
REACH-compliant vegetable tanning cost escalations squeeze margin pools for small-batch artisan producers in Tuscany and Marche regions. Cooperative certification pooling amortizes compliance auditing burdens across independent workshops. Florence and Milan sustain heritage craftsmanship positioning through multi-decade recrafting service commitments.
United Kingdom
GDPR biometric data frameworks shape compliant foot-scan database architectures for direct-to-consumer brands. London's medical-professional referral networks accelerate channel restructuring toward physiotherapy clinic measurement touchpoints. Northampton retains concentrated master last-making craftsmanship capabilities with limited knowledge transfer pipelines.
Custom Shoes Market Key Industry Players
Channel-controlling players compete with product-specialist players across a tiered structure where scale-driven athletic brands, heritage artisan workshops, and direct-to-creator platforms occupy distinct positioning vectors. The vendor base stratifies by production workflow depth, with fully customized last-creation capabilities separating premium-tier operators from modular-configuration competitors. Two strategic archetypes dominate: vertically integrated manufacturers with captive 3D scanning-to-delivery pipelines, and asset-light platform operators orchestrating distributed micro-manufacturing networks. Competitive moves concentrate on M&A absorption of specialized last-making workshops and technology licensing partnerships for AI-driven pattern generation.
Among scale-driven athletic specialists, Nike Inc. and Adidas AG exemplify channel-controlling archetypes with proprietary digital ecosystems compressing design-to-delivery timelines. AliveShoes Inc. occupies a position within the direct-to-creator platform tier, enabling independent designer asset-light brand building without captive production facilities. These three anchors illustrate the competitive spectrum from integrated manufacturing to distributed orchestration.
| Leading Market Players |
|---|
| Nike Inc. |
| Adidas AG |
| AliveShoes Inc. |
| John Lobb |
| Crockett & Jones Ltd. |
| New Balance Athletics Inc. |
| PUMA SE |
| Italian Shoe Factory |
| Carmina Shoemaker |
| Others |
Cost & Logistics Intelligence
Italian and Portuguese tannery clusters anchor premium leather sourcing for artisan-grade custom footwear, concentrating margin capture in heritage-certified workshops that command price premiums through vegetable-tanned hide provenance. REACH chemical restrictions under the EU Green Deal have elevated compliant tanning input costs, compressing margin pools for small-batch producers while rewarding early-certified suppliers with pricing power in the premium tier.
Pricing Analysis
Cost-plus contracts with hide price indexation dominate leather-input sourcing agreements for artisan producers. Three-tier pricing structure across premium, standard, and economy levels separates fully customized last-creation services from semi-customized modular configurations. Pricing pressure stems from bio-based adhesive formulation failures in high-performance athletic applications, forcing hybrid material strategies that elevate production costs. Professional athletes and wedding-occasion buyers in China and the United States exhibit the lowest price sensitivity, while casual semi-customized purchasers in European markets drive volume through promotional responsiveness.
Supply Chain Analysis
Export-control restrictions on advanced 3D scanning hardware and AI-driven pattern generation software limit technology transfer to manufacturing clusters in China and Vietnam. Production gravity centers on Dongguan and Wenzhou for synthetic athletic footwear, Tuscany and Marche for leather dress shoes, and Baden-Württemberg for precision last-making machinery. Raw material dependencies include full-grain hides from European tanneries, engineered polymers from petrochemical suppliers, and rare-earth components for scanning equipment. Single-source vulnerability concentrates in master last-making craftsmanship concentrated in aging Japanese and European workshops. Distribution runs through direct-to-consumer digital platforms and medical-professional referral networks displacing traditional retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward podiatrist-referred orthotic integration and direct-to-creator platforms, fragmenting traditional retail gatekeepers and consolidating demand around biomechanical validation and independent designer marketplaces.
For Market Incumbents: Entrench proprietary 3D scanning-to-delivery pipelines through API redevelopment that syncs legacy ERP systems with real-time foot-scan data streams. Deepen captive supply of master last-making craftsmanship through apprenticeship programs and acquisition of specialized workshops in Northampton and Florence. Defend against agile micro-manufacturing networks by investing in AI-driven pattern generation that compresses design-to-delivery timelines below 10 days. For New Entrants and Emerging Players: Establish a beachhead in India's underpenetrated geography by leveraging PLI scheme incentives for export-oriented production targeting Middle East and African markets. Target the direct-to-creator platform tier by enabling independent designer asset-light brand building without captive production facilities. Deploy a go-to-market angle centered on GDPR-compliant foot-scan database architectures that create first-mover advantages in European biometric data regulation. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated manufacturers with captive 3D scanning-to-delivery pipelines and certified sustainable material sourcing. Long-term viability favors operators that combine AI-driven design platforms with heritage craftsmanship certification. Watch for inflection signals in orthopedic certification timeline compression under EU MDR, where 18-24 month approval extensions separate viable biomechanical positioning claims from marginal competitors.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Driven Pattern Generation Investment | Compresses design-to-delivery timelines for fully customized athletic footwear competing with Nike's proprietary ecosystem. |
| REACH-Compliant Tanning Certification | Creates competitive barriers for Italian and Portuguese artisan workshops facing 15-30% input cost elevation. |
| Direct-to-Creator Platform Launch | Enables independent designers to control branded custom shoe lines without captive production like AliveShoes. |
| Micro-Manufacturing Network Expansion | Localizes production near demand clusters through Speedfactory-adjacent operations modeled on Adidas AG. |
| GDPR-Compliant Foot-Scan Database Architecture | Positions brands for biometric data regulatory tailwinds in EU digital ownership frameworks. |
Research Approach
Initial hypotheses were tested against primary input from custom footwear brand executives, 3D scanning technology providers, tannery procurement managers, and podiatrist clinic operators and refined through secondary validation against customs records, SEC filings from athletic footwear manufacturers, REACH chemical restriction compliance databases, and EU MDR notified body approval tracking. Bottom-up triangulation across production volume estimates from Dongguan and Wenzhou manufacturing clusters converged with top-down demand modeling from wedding-occasion and professional athlete segment expenditure patterns.
Demand-supply balance modeling across the analysis window segmented by product type, material, customization level, and target audience dimensions. CAGRs were derived from regression analysis of historical volume trajectories and forward-looking capacity expansion announcements from vertically integrated manufacturers. Industry-specific forecast inputs included MEE dual carbon goal compliance timelines for solvent-based adhesive reformulation and FDA-FTC intersection review bottlenecks for biomechanical health claims.
Stress conditions across leather input cost volatility, bio-based adhesive durability failures, and orthopedic certification timeline extensions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding EU Green Deal implementation pacing and China domestic brand capture rates. Material shifts in GDPR biometric data enforcement severity or REACH chemical restriction scope expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Footwear
South America Athletic Footwear Market
Footwear
Shoe Rental Service Market
Footwear
Europe Footwear Market
Footwear
Formal Shoes Market
Footwear
Premium Shoes Market
Footwear
Tactical Footwear Market
Footwear
Lace Up Boots Market
Footwear
Gypsy Jazz Shoes Market
Footwear
Cowgirl Boots Market
Footwear
Sports Footwear Market
Footwear
Snow Boots for Women Market
Footwear
Flip Flops Market
Footwear
Women's Sneakers Market
Footwear
Slip Resistant Shoes Market
Footwear
OEM Shoe Manufacturer Service Market
Footwear
Europe Athletic Footwear Market