
 Tennis Shoes Market | 2026-2036
Tennis Shoes Market Size, Share, and Industry Trends Forecast 2026-2036
Tennis Shoes Market Intelligence
Amateur recreational players is bifurcating demand away from traditional country club members as the fastest-growing buyer archetype in tennis footwear. Nike Inc. leverages its global brand architecture and athlete endorsement network to dominate premium performance tiers. Adidas AG anchors its position through sustainable material innovation and direct-to-consumer channel control. ASICS Corporation specializes in technical biomechanical engineering for competitive athletes across Asian and European markets.
Tennis shoes are purpose-built athletic footwear engineered with lateral stability structures, abrasion-resistant outsoles, and cushioned midsole systems designed for multidirectional court movement. Manufacturers construct these products using calibrated rubber compounds, engineered mesh uppers, and thermoplastic polyurethane stabilizers to manage impact forces during pivot-intensive play. Hard court configurations currently occupy the largest volume share due to surface prevalence in North American and Australian facilities. Professional-grade segments command the highest margin pools as tournament players prioritize durability and injury prevention over price sensitivity. Online distribution channels are capturing the fastest growth trajectory as digital fitting tools and subscription replenishment models reshape purchase behavior.
EPA guidelines in the United States restrict volatile organic compound emissions from solvent-based adhesives used in shoe assembly. REACH regulations in Europe mandate disclosure and restriction of phthalates and heavy metals in synthetic leather components. China's GB standards govern product safety labeling and quality certification for domestic athletic footwear sales. Stakeholders must monitor evolving chemical compliance frameworks and court surface specialization trends to align R&D portfolios with regional performance requirements.
Market Dynamics
REACH chemical standards in Europe are decomposing traditional synthetic upper formulations and forcing manufacturers to reformulate material portfolios around bio-based thermoplastic polyurethanes and waterborne adhesives.
Growth Catalysts
- Amateur recreational expansion:Casual players in China and the United States are purchasing court-specific footwear at triple the rate of club members, creating volume pull through mass retail channels.
- GB standards compliance:China's mandatory product safety labeling for athletic footwear is elevating quality baselines and accelerating domestic brand consolidation.
- Hard court surface prevalence:Abrasion-resistant outsole compounds designed for acrylic surfaces are capturing dominant volume share in North American and Australian facilities.
Market Restraints
- Synthetic rubber cost volatility:Petroleum-derived outsole compounds face input price swings that compress margin stability for mid-tier manufacturers.
- China production concentration:Overreliance on Fujian and Guangdong manufacturing clusters creates geopolitical and logistics risk exposure for global supply chains.
- REACH substance restrictions:Phthalate disclosure mandates for synthetic leather components are extending R&D timelines and raising compliance costs for European market entry.
Strategic Opportunities
- Digital fitting platforms:3D foot-scanning and AI-powered size recommendation tools are capturing fastest growth in online distribution channels.
- Subscription replenishment models:Automated replacement cycles for competitive players are creating recurring revenue streams and reducing customer acquisition costs.
- India market underpenetration:Professional-grade tennis footwear remains underserved in Indian metropolitan areas despite rising participation in ITF-sanctioned tournaments.
Industry Challenges
- Biomechanical engineering talent scarcity:Specialized footwear designers with motion-capture and pressure-mapping expertise command premium compensation and limited availability.
- Multi-surface certification complexity:Separate durability testing protocols for clay, grass, and hard courts fragment product development resources and inventory planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tennis Shoes Market |
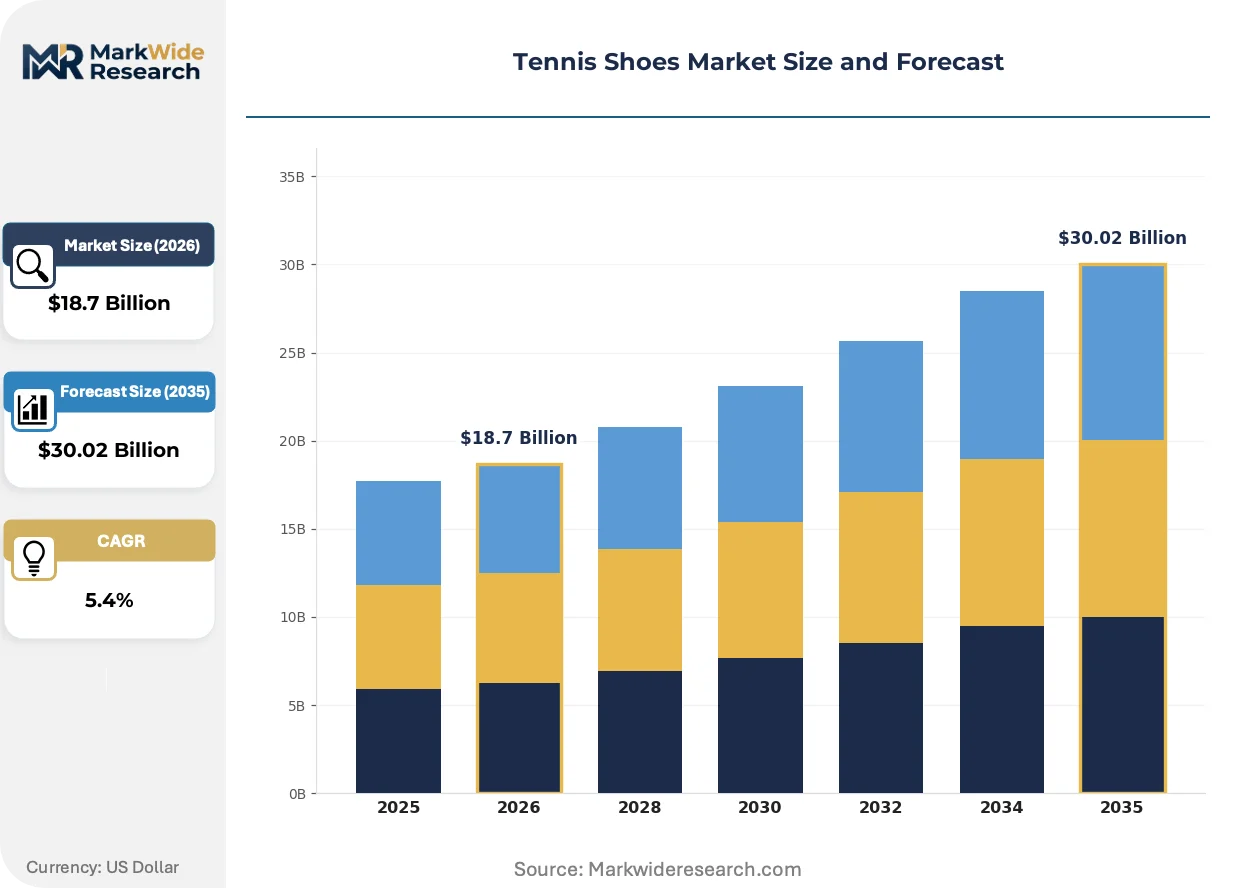
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $30.02 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clay Court, Grass Court, Hard Court, All Court End User: Men, Women, Kids, Professionals Material: Leather, Synthetic, Mesh, Rubber Distribution Channel: Online, Specialty Stores, Department Stores, Supermarkets |
| Companies Covered | Nike Inc., Adidas AG, ASICS Corporation, New Balance Inc., Mizuno Corporation, ANTA Sports Products Limited, FILA Holdings Corp., Babolat, Yonex Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tennis Shoes Market Strategic Shifts & Innovations
Material science advances and regulatory chemistry mandates are converging to reshape how tennis footwear is engineered, certified, and sold across professional and recreational segments.
Engineered mesh uppers with zoned ventilation structures are decomposing the traditional leather-and-synthetic material stack in performance tiers. Competitive athletes and tournament players are adopting these breathable constructions at accelerating rates as brands validate moisture management and weight reduction claims. This shift is compressing demand for conventional synthetic leather components and forcing tannery suppliers to diversify into technical textile partnerships.
EPA volatile organic compound restrictions on solvent-based adhesives are compelling assembly line retrofits in United States manufacturing facilities. Shoe factories must convert to waterborne or hot-melt bonding systems to maintain regulatory compliance and avoid production stoppages. Premium performance segments absorb these capital costs most readily, while economy-tier suppliers face facility consolidation or exit decisions.
Direct-to-consumer channel expansion is fragmenting traditional wholesale relationships and compressing margin capture for specialty retailers. Digital-native brands with proprietary fitting algorithms and social media athlete networks are displacing multi-brand sporting goods stores in younger buyer cohorts. This behavioral shift is most visible in China and the United States, where mobile commerce penetration and influencer-driven discovery patterns dominate purchase journeys.
Tennis Shoes Market Segmentation
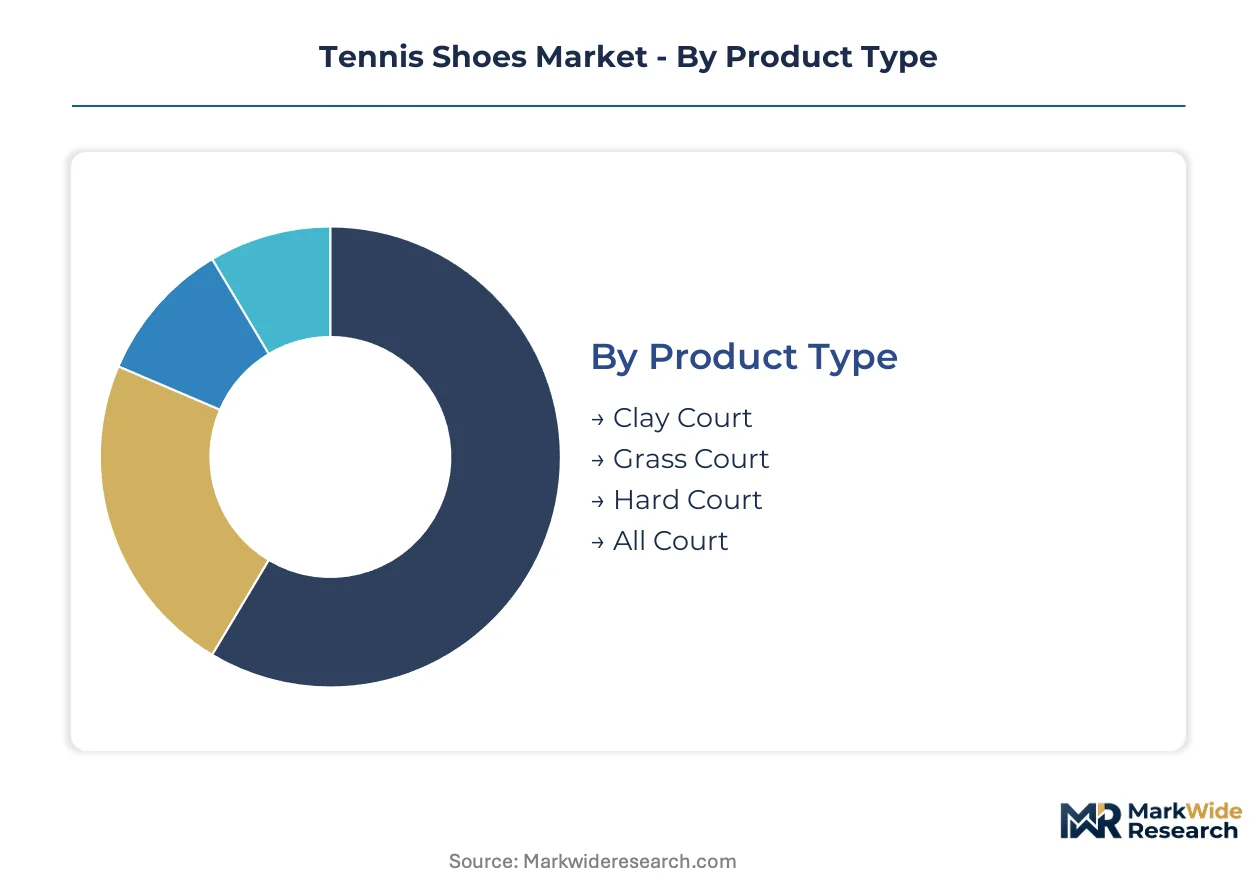
Tennis shoe manufacturers engineer distinct product architectures for surface-specific performance requirements. Channel strategy and buyer archetype alignment determine which segment configurations capture margin versus volume in this market.
Product Type:
Mass retail channels move All Court and Hard Court volumes, while specialty retailers concentrate Clay and Grass Court premium tiers.
- Hard Court:Abrasion-resistant rubber outsoles with reinforced toe caps withstand acrylic surface friction. Demand clusters in the United States and Australia where public facility infrastructure dominates, driven by recreational player volume through sporting goods chains.
- All Court:Hybrid tread patterns and adaptable midsole densities accommodate surface switching. This configuration is expanding most quickly among amateur players in China seeking single-pair versatility for irregular court access.
- Clay Court:Herringbone outsole grooves shed surface residue during lateral slides. European specialty retailers capture this segment through technical fitting services.
- Grass Court:Pimpled rubber studs and minimal tread depth optimize low-traction natural surfaces. Wimbledon-adjacent pro shops and tournament merchandising sustain this niche.
Hard Court dominates installed base. All Court is where expansion concentrates.
End User:
Cost tier stratification separates professional-grade biomechanical engineering from recreational comfort-focused construction.
- Men:Wider last constructions and higher-density midsole foams accommodate greater average body mass. This segment anchors wholesale volume through department store athletic footwear departments.
- Women:Narrower heel cups and flexible forefoot platforms align with anatomical proportion differences. Specialty running and tennis boutiques capture premium women's performance tiers.
- Professionals:Custom orthotic compatibility and tournament-grade durability certification define specifications. Direct-to-consumer channels with athlete endorsement integration sustain this highest-margin tier.
- Kids:Growth-accommodating sizing systems and rapid replacement cycles characterize demand. Parental purchase through online subscription models is climbing the fastest among family buyer cohorts.
Men's configurations dominate installed base. Kids replacement cycles are where expansion concentrates.
Material:
Volume concentration in synthetic and mesh constructions reflects REACH-driven reformulation and weight reduction priorities.
- Synthetic:Thermoplastic polyurethane overlays and microfiber uppers deliver consistent performance at controlled cost points. Fujian manufacturing clusters supply global mid-tier brands with these formulations.
- Mesh:Engineered knit structures with zoned ventilation zones reduce weight versus leather predecessors. Chinese domestic brands and digital-native entrants are scaling this material most aggressively.
- Leather:Traditional full-grain and corrected-grain constructions persist in heritage premium tiers. Italian and Portuguese tannery partnerships sustain limited production for European specialty markets.
- Rubber:Calibrated outsole compounds with varied hardness ratings manage court-specific friction requirements. Petroleum-derived feedstock volatility constrains margin stability for this essential component.
Synthetic formulations dominate installed base. Mesh uppers are where expansion concentrates.
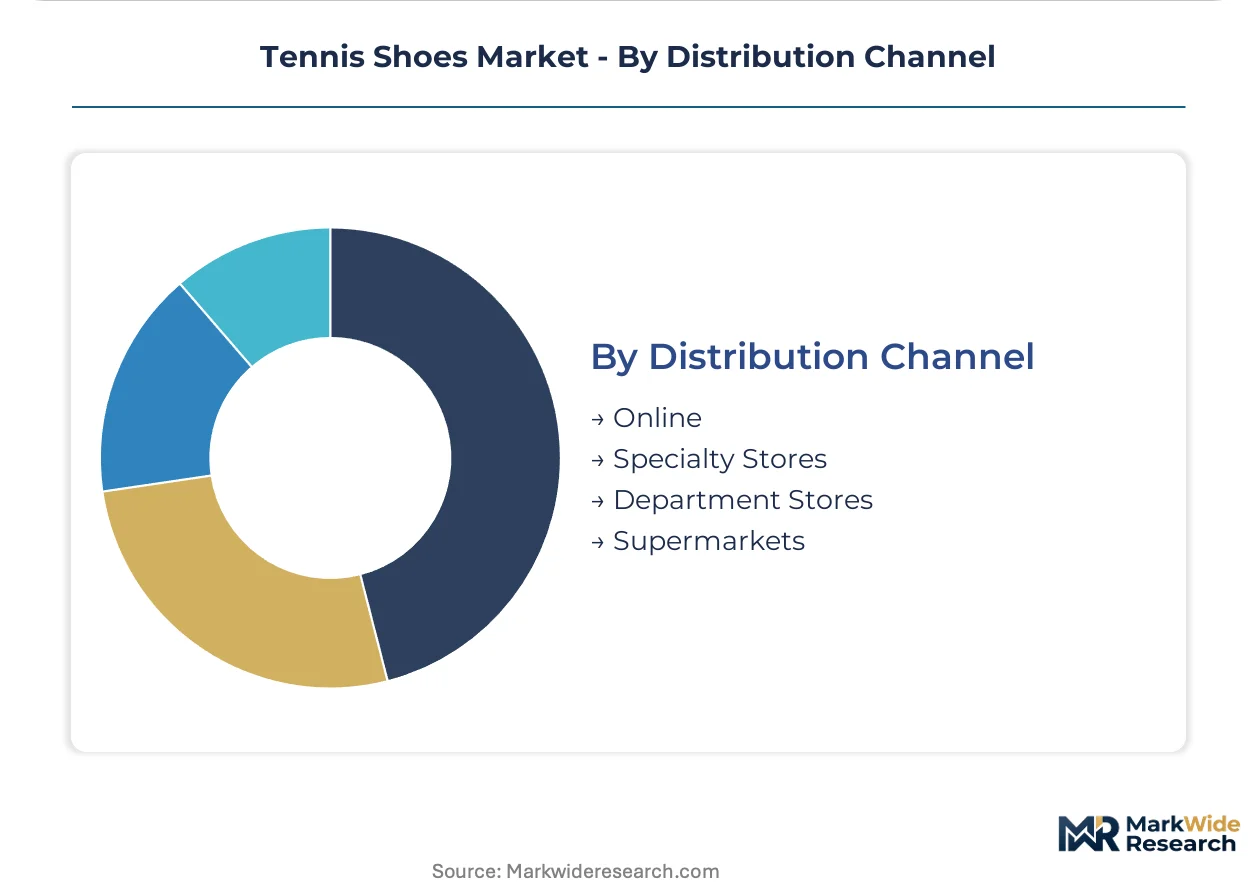
Distribution Channel:
Margin capture and customer acquisition economics diverge sharply between digital-native and brick-and-mortar configurations.
- Online:3D foot-scanning tools and AI size recommendation engines reduce fit-related returns. Nike and Adidas direct-to-consumer platforms capture the steepest expansion trajectory in China and the United States.
- Specialty Stores:Biomechanical gait analysis and court-surface consultation justify premium price positioning. European independent retailers sustain this channel through technical expertise differentiation.
- Department Stores:Mass-market brand presence and seasonal promotional cycles drive volume. This channel faces compression as digital fitting tools replicate in-store guidance.
- Supermarkets:Entry-level price points and impulse purchase placement capture occasional recreational buyers. Limited size runs and minimal technical specification disclosure constrain this tier.
Specialty stores dominate installed base. Online platforms are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese manufacturing clusters in Fujian and Guangdong supply finished tennis footwear to retail distributors across the United States, Germany, and Australia. This trade corridor channels volume through consolidated port infrastructure and direct-to-consumer digital platforms. Regional demand patterns diverge sharply between mature recreational markets and emerging competitive participation zones.
United States
Hard court infrastructure dominance drives abrasion-resistant outsole demand through sporting goods chains and specialty retailers. EPA volatile organic compound restrictions on solvent-based adhesives compel assembly facility retrofits toward waterborne bonding systems. Los Angeles and Portland serve as design and marketing hubs where Nike and Adidas anchor direct-to-consumer platform development.
China
Amateur recreational players purchase court-specific footwear at triple the rate of club members through mass retail and mobile commerce channels. GB standards mandate product safety labeling and quality certification for domestic athletic footwear sales. Fujian and Guangdong manufacturing clusters concentrate global production capacity while domestic brands scale engineered mesh upper technologies.
Germany
Clay court specialization sustains herringbone outsole demand through independent specialty retailers with biomechanical fitting services. REACH regulations mandate phthalate disclosure and substance restrictions for synthetic leather components entering European markets. Bavaria hosts Adidas AG headquarters where sustainable material innovation programs coordinate direct-to-consumer channel control.
Japan
Technical biomechanical engineering for competitive athletes anchors premium performance tier demand across Asian tournament circuits. METI industrial standards govern product quality certification and material safety protocols for domestic athletic footwear distribution. Osaka and Tokyo metropolitan areas concentrate ASICS Corporation and Mizuno Corporation R&D facilities with motion-capture expertise.
Australia
Public hard court facility prevalence mirrors United States surface distribution and drives parallel outsole compound requirements. The Therapeutic Goods Administration and Australian Competition and Consumer Commission oversee product safety compliance for imported athletic footwear. Melbourne and Sydney retail corridors channel volume through specialty tennis boutiques and digital fitting platforms.
Tennis Shoes Market Key Industry Players
Listed leaders compete with private specialists across brand architecture and channel control dimensions. The vendor base stratifies into three tiers: global sportswear conglomerates with athlete endorsement networks, regional specialists with technical biomechanical expertise, and digital-native entrants with proprietary fitting algorithms. Strategic archetypes include premium performance engineers, mass-market volume players, and sustainability-focused reformulators. Competitive moves concentrate on direct-to-consumer platform expansion and sustainable material portfolio diversification.
Among Asia-Pacific headquartered fabricators, ASICS Corporation and Mizuno Corporation occupy positions within the technical biomechanical engineering archetype. Nike Inc. and Adidas AG anchor the premium performance tier with global brand architecture and sustainable material innovation programs. ANTA Sports Products Limited represents the mass-market volume expansion archetype scaling engineered mesh technologies through Chinese domestic retail channels.
| Leading Market Players |
|---|
| Nike Inc. |
| Adidas AG |
| ASICS Corporation |
| New Balance Inc. |
| Mizuno Corporation |
| ANTA Sports Products Limited |
| FILA Holdings Corp. |
| Babolat |
| Yonex Co. Ltd. |
| Others |
Cost & Logistics Intelligence
Engineered mesh uppers displacing traditional leather-and-synthetic stacks simultaneously relocate manufacturing gravity toward Fujian and Guangdong clusters and compress material cost baselines for mid-tier producers. This substitution dynamic concentrates pricing power among vertically integrated brands while fragmenting margin capture for legacy tannery suppliers.
Pricing Analysis
Next-generation waterborne adhesive systems command 15-20% premia over solvent-based legacy formulations, while prior-generation synthetic leather constructions face accelerating price erosion. Three-tier pricing structure across premium performance, standard recreational, and economy entry levels stratifies by certification grade and biomechanical engineering intensity. Pricing pressure stems from petroleum-derived rubber compound volatility that compresses margin stability for non-integrated manufacturers. Amateur recreational players exhibit highest price sensitivity, while professional tournament athletes prioritize durability certification over cost.
Supply Chain Analysis
Container availability constraints on Asia-Pacific to North America trade lanes elevate inbound logistics costs for brands without contracted freight allocations. Finished footwear production concentrates in China, Vietnam, and Indonesia, with raw material dependencies spanning Malaysian rubber plantations, Taiwanese TPU resin facilities, and Korean engineered textile mills. Single-source vulnerability pervades Fujian manufacturing cluster concentration where geopolitical disruption would cascade through global brand inventories. Distribution runs through direct-to-consumer platforms, specialty retail networks, and mass-market sporting goods chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward amateur recreational players whose tripled purchase rate versus club members concentrates volume leverage in mass retail and digital channels. This fragmentation among traditional country club gatekeepers erodes premium pricing authority.
For Market Incumbents: Compound brand equity through athlete endorsement network exclusivity and direct-to-consumer platform lock-in. Defend margin position by accelerating backward integration into engineered mesh textile production in Fujian clusters. Prioritize REACH-compliant material certification investment ahead of European regulatory tightening.
For New Entrants and Emerging Players: Biomechanical fitting services for amateur players represent the most penetrable service-layer gap where incumbents under-serve. Target Indian metropolitan markets with professional-grade inventory underserved by existing distribution. Deploy AI-powered size recommendation engines as primary go-to-market angle to reduce fit-related return costs.
For Investors and Strategic Acquirers: The market sits at a material-transition phase that favors sustainable chemistry specialists with waterborne adhesive capabilities. Long-term viability over the coming decade hinges on regulatory compliance infrastructure rather than pure manufacturing scale. Watch REACH substance restriction expansion timelines as inflection indicator for European market access economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Sustainable Material Repositioning | Bio-based TPU adoption satisfies REACH mandates while differentiating premium tiers against synthetic competitors. |
| Direct-to-Consumer Platform Expansion | Proprietary 3D foot-scanning tools reduce return rates and capture margin lost to wholesale intermediaries. |
| Subscription Replenishment Launch | Automated replacement cycles for competitive athletes create recurring revenue and lower customer acquisition costs. |
| India Distribution Buildout | ITF tournament growth in metropolitan areas creates channel whitespace for professional-grade inventory. |
| Digital Fitting Algorithm Acquisition | AI-powered size recommendation engines replicate specialty store biomechanical services at mobile commerce scale. |
Research Approach
Desk research of customs trade databases, athletic footwear industry association publications, and regulatory filing repositories preceded structured interviews with brand product development directors, specialty retail buyers, manufacturing facility managers, and amateur player community organizers. Primary fieldwork with Fujian and Guangdong production supervisors combined with secondary validation from EPA emission disclosure records and ECHA substance restriction updates. Bottom-up segmentation modeling and top-down macroeconomic triangulation anchored volume and value estimates.
Variance decomposition across surface type, buyer archetype, material composition, and channel configuration structured the analytical framework over the projection horizon. CAGRs derived from segment-level growth trajectory analysis incorporating amateur participation rates, court infrastructure investment patterns, and regulatory compliance cost absorption assumptions. Modeled inputs included REACH substance restriction implementation timelines and GB standards enforcement intensity across Chinese provincial markets.
Underlying assumptions cover sustained amateur recreational participation growth and stable petroleum-derived input cost trajectories, with deviation risk concentrated in geopolitical disruption to Fujian manufacturing clusters and accelerated REACH chemical restriction expansion. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Footwear
Women's Non-Athletic Footwear Market
Footwear
Sports Shoes Market
Footwear
Casual Shoes Market
Footwear
Cowgirl Boots Market
Footwear
Men Formal Shoe Market
Footwear
E-Commerce Footwear Market
Footwear
North America Footwear Market
Footwear
Europe Athletic Footwear Market
Footwear
Formal Shoes Market
Footwear
North America Athletic Footwear Market
Footwear
Sneaker Boots Market
Footwear
GCC Footwear Market
Footwear
Premium Shoes Market
Footwear
Leather Sneakers Market
Footwear
PVC Footwear Market
Footwear
Middle East and Africa Athletic Footwear Market