
 North America Athletic Footwear Market | 2026-2036
North America Athletic Footwear Market Size, Share, and Industry Trends Forecast 2026-2036
North America Athletic Footwear Market Outlook
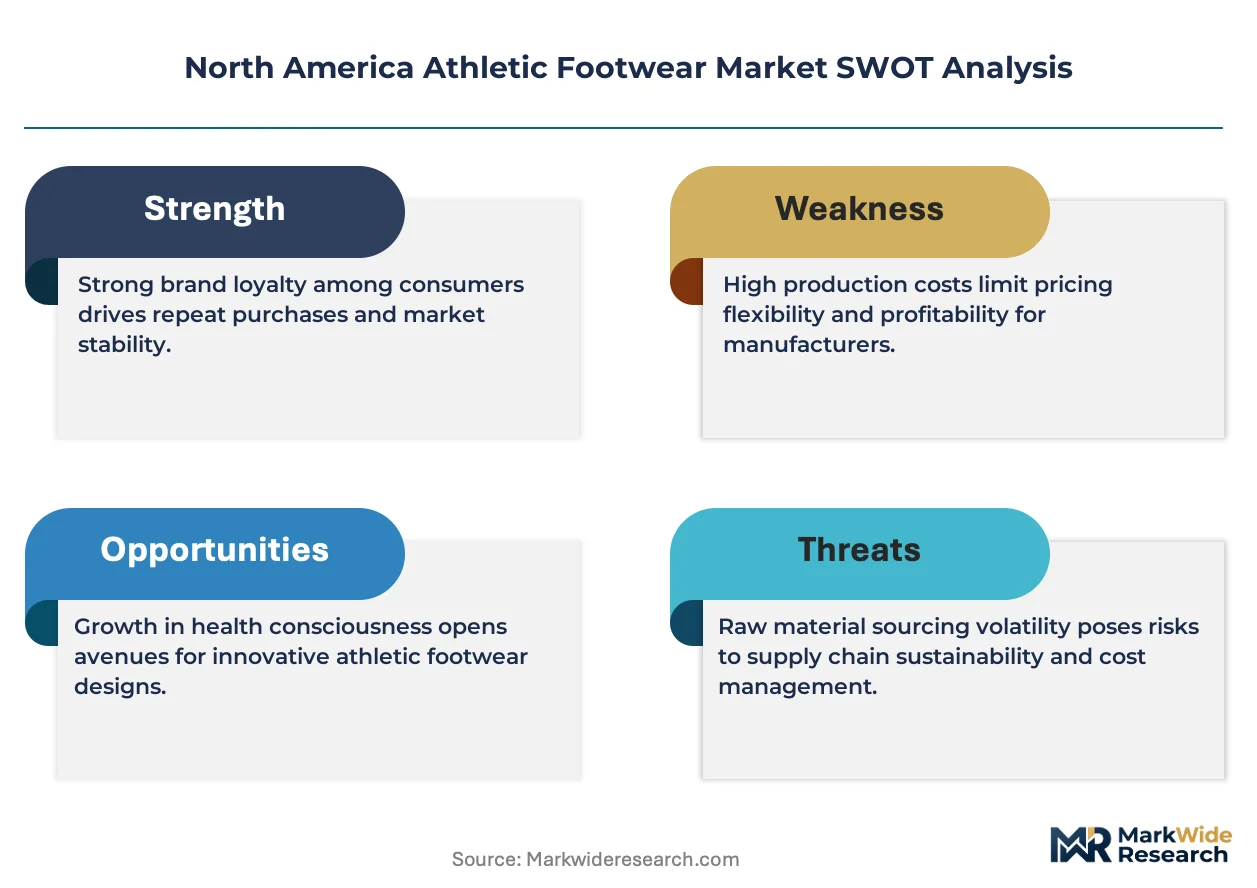
REACH compliance for imported synthetic rubber compounds is rebalancing the cost-of-entry calculus for brands sourcing from European chemical suppliers. Nike Inc leverages vertical integration across its domestic manufacturing network to absorb these regulatory premiums without passing full costs to retail channels. Under Armour Inc sustains R&D intensity in performance knit uppers that reduce dependency on regulated petrochemical inputs. New Balance Athletics Inc anchors its competitive posture through expanded domestic assembly capacity in Massachusetts and Maine, insulating select product lines from cross-border tariff volatility.
North America athletic footwear comprises engineered upper textiles, midsole foam systems, and outsole traction compounds designed for biomechanical performance across running, court, and training modalities. Ethylene-vinyl acetate (EVA) and thermoplastic polyurethane (TPU) formulations dominate midsole construction, with injection-molded processes enabling density gradients that tune energy return and stability for specific gait patterns. Running shoes command the deepest margin pools as consumers trade up for carbon-fiber plate and super-foam configurations, while specialty stores capture disproportionate value through fitted selling and brand exclusivity. Online retail channels are displacing department store volume as direct-to-consumer platforms enable customization tools and subscription replenishment models.
The US Consumer Product Safety Commission enforces flammability standards for textile uppers, while California's Proposition 65 mandates chemical disclosure for chromium and phthalate content in leather tanning and synthetic colorants. Health Canada and the US Federal Trade Commission jointly scrutinize green marketing claims around recycled content percentages and biodegradability timelines, forcing material substantiation across cross-border product lines. Stakeholders must monitor pending state-level extended producer responsibility legislation in Oregon and Colorado that would impose end-of-life collection obligations on athletic footwear placed into regional commerce.
Market Dynamics
Carbon-fiber plate integration in performance running silhouettes is compressing product development cycles and forcing midsole foam chemistry specialization across domestic manufacturing networks.
Growth Catalysts
- REACH compliance for synthetic rubber:European chemical sourcing requirements are accelerating domestic compound formulation capabilities among North American material suppliers.
- Amateur runner segment expansion:Health-conscious lifestyle prioritization among recreational athletes is pulling volume through specialty retail channels with fitted-selling protocols.
- California metropolitan demand density:Fitness culture concentration and disposable income clustering in Los Angeles and San Francisco corridors sustain premium price realization.
Market Restraints
- Petrochemical input volatility:Ethylene-vinyl acetate and thermoplastic polyurethane feedstock costs fluctuate with regional refinery capacity constraints.
- Cross-border assembly concentration:Dependence on Asian manufacturing nodes for injection-molded midsole components exposes brands to tariff regime uncertainty.
- California Proposition 65 disclosure mandates:Chromium and phthalate content labeling requirements add compliance overhead to leather tanning and synthetic colorant sourcing.
Strategic Opportunities
- Domestic assembly expansion:Massachusetts and Maine production facilities insulate select product lines from import duty volatility while shortening lead times.
- Direct-to-consumer platform development:Customization tools and subscription replenishment models capture margin pools previously allocated to wholesale partners.
- Extended producer responsibility legislation:Pending Oregon and Colorado end-of-life collection mandates create first-mover advantage for circular material recovery infrastructure.
Industry Challenges
- Biomechanical engineering talent scarcity:Specialized gait analysis and performance optimization expertise concentrates among limited domestic research institutions.
- Multi-material disassembly complexity:Bonded upper-to-midsole construction complicates automated recycling stream separation for post-consumer collection programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Athletic Footwear Market |
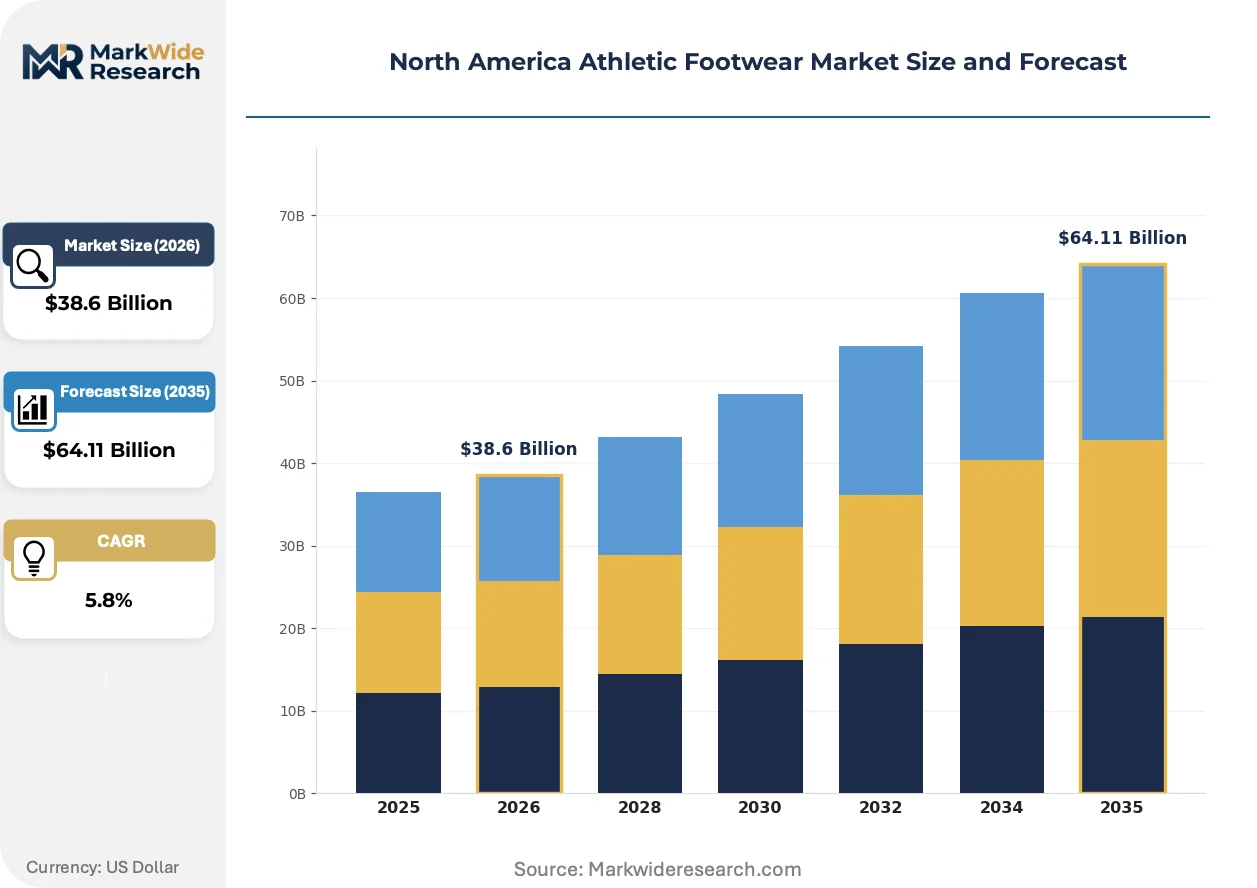
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $64.11 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sneakers, Running Shoes, Cross-Trainers, Sports Sandals End User: Men, Women, Children, Athletes Distribution Channel: Online Retail, Specialty Stores, Department Stores, Discount Retailers Price Tier: Premium, Mid-Range, Budget, Luxury |
| Companies Covered | Nike Inc, Adidas AG, Skechers USA Inc, Under Armour Inc, New Balance Athletics Inc, Puma SE, ASICS Corp, Brooks Sports Inc, Hoka, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Athletic Footwear Market Strategic Shifts
Digital manufacturing workflows and regulatory disclosure requirements are converging to reshape material transparency and production traceability across North American supply chains.
3D-printed lattice midsole structures are automating density gradient customization for individual runner biomechanics. Specialty running stores are adopting foot-scanning platforms that transmit geometry data directly to regional production facilities. This distributed manufacturing model is compressing batch sizes and enabling made-to-order economics at mass-market price points.
The US Consumer Product Safety Commission's updated flammability standards for synthetic textile uppers are mandating revised compound formulations across domestic supply chains. Brands must retest and recertify existing inventory while reformulating future production runs. Running and court shoe categories face the steepest compliance timelines due to higher synthetic upper ratios.
Subscription-based replenishment purchasing is displacing traditional retail replacement cycles among committed amateur runners. Direct-to-consumer platforms capture recurring revenue streams while specialty stores pivot toward experiential fitting and gait analysis services. California and New York metropolitan markets exhibit the highest subscription adoption rates, correlating with fitness app integration and wearable device ownership density.
North America Athletic Footwear Market Segmentation
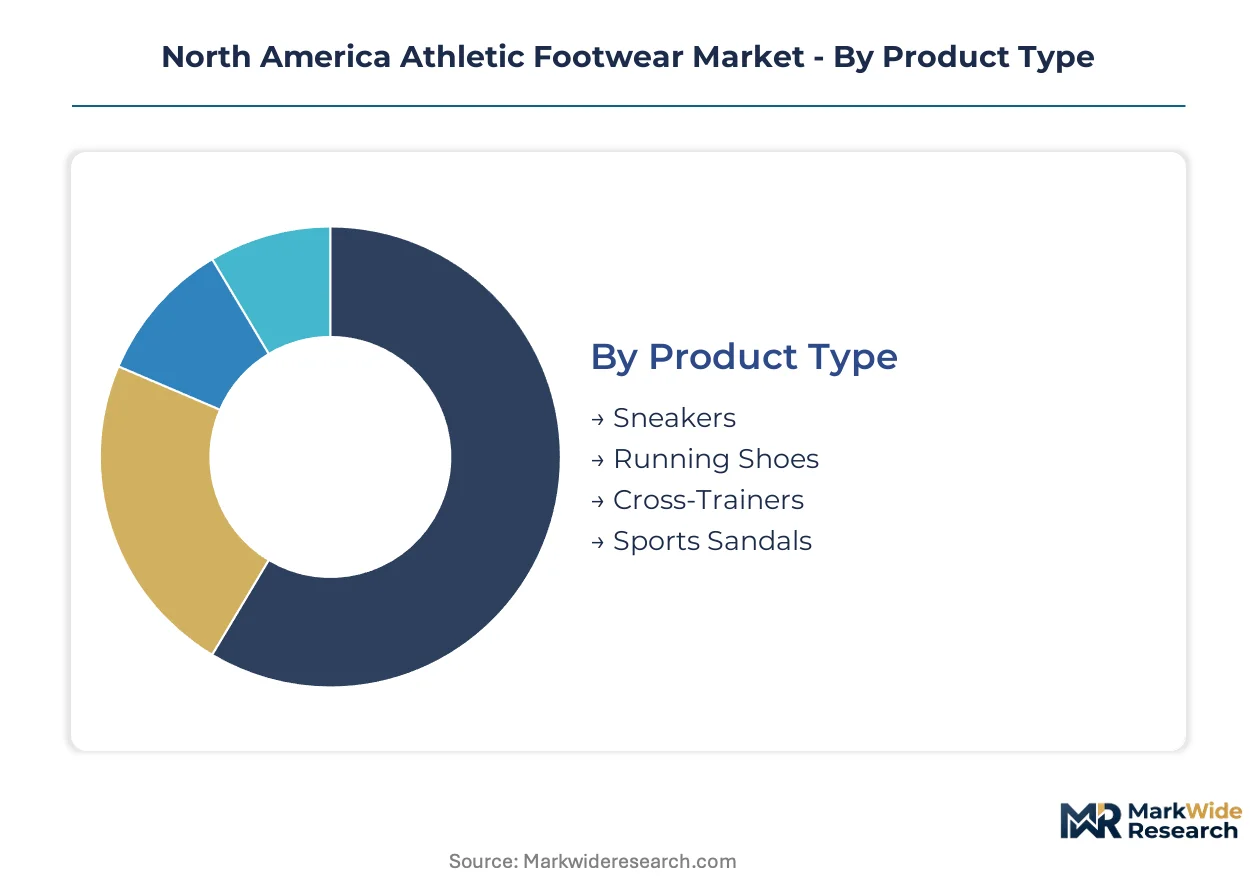
North America athletic footwear segmentation reveals how biomechanical specialization, channel economics, and regulatory exposure fragment commercial opportunity across distinct buyer profiles. Understanding these divides enables targeted material selection and compliance architecture.
Product Type:
Midsole foam chemistry capabilities concentrate manufacturing capacity for specific performance categories, with injection-molded TPU and EVA formulations requiring dedicated tooling investments.
- Running Shoes:Carbon-fiber plate and super-foam configurations dominate engineering R&D spend. Demand concentrates in California's metropolitan corridors where amateur runners prioritize gait-optimized energy return and injury prevention.
- Sneakers:Lifestyle-oriented silhouettes blend casual aesthetics with basic cushioning platforms. Volume concentrates in mass-market channels where fashion cycles compress replacement timelines and colorway refresh frequency drives repurchase.
- Cross-Trainers:Multi-directional stability features serve gym-based interval training modalities.
- Sports Sandals:Open-strap constructions with contoured footbeds address warm-climate recovery and water-adjacent activities.
Today's leader: Running Shoes. Tomorrow's challenger: Sneakers.
End User:
Biomechanical variation across demographic cohorts dictates last geometry, cushioning density, and upper volume engineering specifications.
- Women:Narrower heel-to-ball ratios and elevated arch support requirements drive specialized last development. Demand concentrates in specialty retail channels where fitted-selling protocols address fit complexity.
- Men:Broader forefoot dimensions and higher average body mass influence midsole compression set specifications. Volume flows through direct-to-consumer platforms where subscription replenishment models capture committed recreational runners.
- Children:Rapid growth cycles and durability trade-offs prioritize replaceable cost structures over performance optimization.
- Athletes:Elite and collegiate competitors demand batch-customized specifications with minimal production runs.
Women's technical specifications command premium development resources. Children's replacement velocity offers volume scale.
Distribution Channel:
Margin capture and customer data ownership diverge sharply between wholesale intermediaries and captive digital platforms.
- Online Retail:Direct-to-consumer infrastructure enables customization tools and subscription replenishment with full margin retention. Adoption concentrates in California and New York metropolitan markets correlating with wearable device ownership density.
- Specialty Stores:Foot-scanning platforms and gait analysis services justify price premiums through fitted-selling expertise. Running shoe categories depend on this channel for technical credibility and brand exclusivity.
- Department Stores:Generalist assortment strategies face displacement as athletic footwear technical complexity outstocks staff training levels.
- Discount Retailers:Closeout inventory and prior-season models serve price-sensitive replacement demand with minimal service overhead.
Specialty Stores anchor technical credibility. Online Retail captures margin expansion.
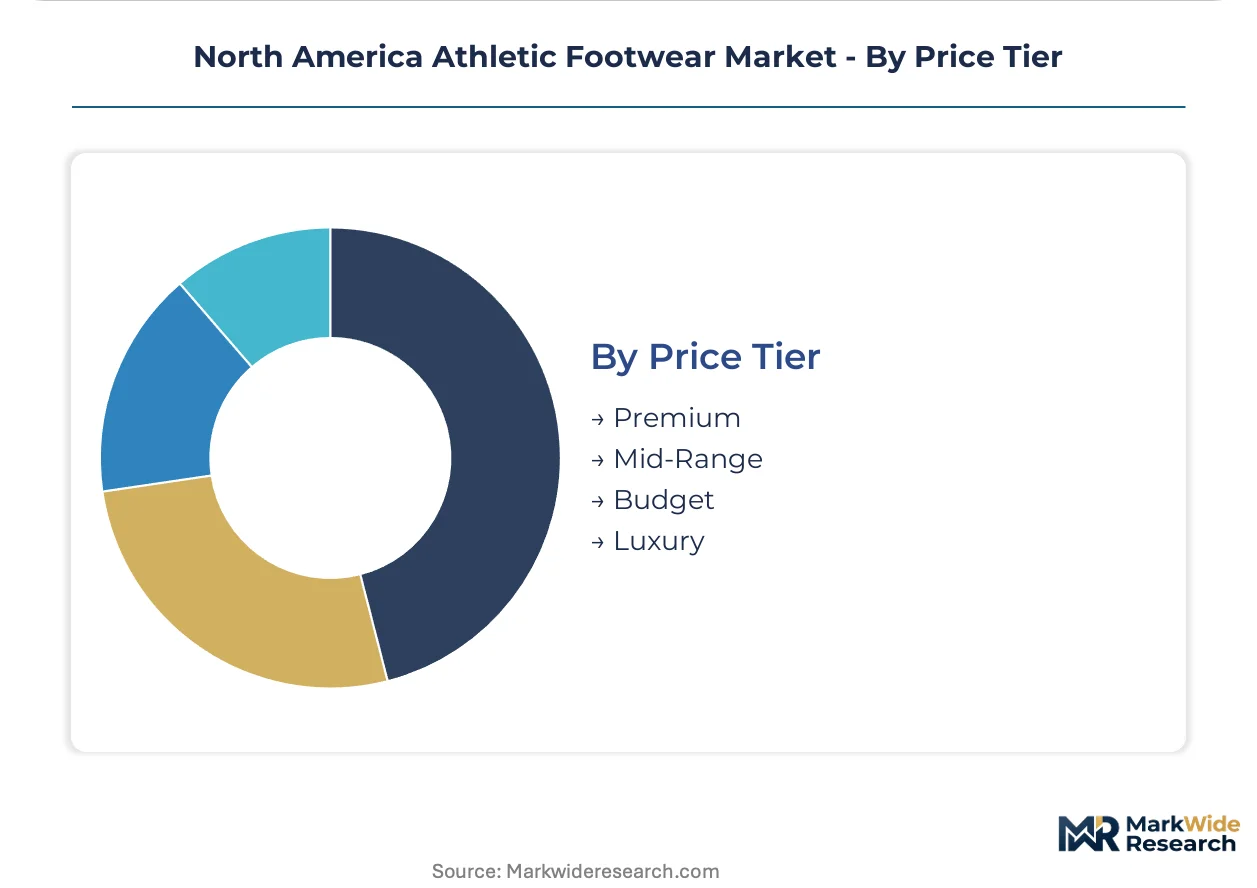
Price Tier:
Material specification tiers align with manufacturing complexity and regulatory compliance cost absorption capacity.
- Premium:Carbon-fiber plate integration and domestic assembly insulate against tariff volatility while justifying elevated price points. REACH-compliant synthetic rubber sourcing and flammability-standard testing add fixed cost burdens absorbed through margin depth.
- Luxury:Limited-edition collaborations and heritage craftsmanship narratives command collector-market premiums with minimal volume scaling requirements.
- Mid-Range:Balanced performance features target committed amateur runners with biennial replacement cycles.
- Budget:Simplified construction and Asian assembly concentration expose margins to cross-border duty regime uncertainty.
Premium tier absorbs regulatory overhead. Budget tier faces tariff exposure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biomechanical engineering talent concentrates in Massachusetts research corridors and California innovation clusters, anchoring domestic product development capabilities for performance-oriented footwear categories.
United States
Amateur runner segment expansion drives volume through specialty retail channels in Los Angeles and San Francisco metropolitan corridors. The US Consumer Product Safety Commission enforces updated flammability standards for synthetic textile uppers, forcing reformulation timelines across domestic supply chains. Massachusetts and Maine host expanded domestic assembly facilities that insulate select product lines from cross-border tariff volatility.
Canada
Health Canada and the US Federal Trade Commission jointly scrutinize green marketing claims around recycled content percentages, forcing material substantiation across cross-border product lines. The country's national consumer protection regulator mandates chemical disclosure protocols that align with California's Proposition 65 thresholds. Toronto and Vancouver metropolitan markets exhibit strong subscription replenishment adoption correlating with wearable device ownership density.
Mexico
Nearshoring momentum in injection-molded midsole component manufacturing reduces lead times for US-bound finished goods. The country's federal economic development programs incentivize automotive supplier diversification into footwear material processing capabilities. Baja California and Chihuahua border states concentrate thermoplastic polyurethane compounding facilities serving cross-border assembly networks.
North America Athletic Footwear Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered price-positioning bands. The vendor base organizes around three strategic archetypes: vertically integrated sportswear giants controlling domestic manufacturing networks, R&D-intensive performance specialists, and value-oriented volume players leveraging Asian assembly concentration. Dominant competitive moves include domestic capacity expansion to absorb regulatory premiums and direct-to-consumer platform development to capture margin pools previously allocated to wholesale partners.
Within the vertically integrated tier, Nike Inc represents backward integration into domestic manufacturing networks that buffer REACH compliance costs. Under Armour Inc exemplifies R&D-intensive positioning through performance knit upper specialization. New Balance Athletics Inc anchors the domestic assembly expansion archetype with Massachusetts and Maine production facilities.
| Leading Market Players |
|---|
| Nike Inc |
| Adidas AG |
| Skechers USA Inc |
| Under Armour Inc |
| New Balance Athletics Inc |
| Puma SE |
| ASICS Corp |
| Brooks Sports Inc |
| Hoka |
| Others |
Value Chain & Pricing Dynamics
Carbon-fiber plate integration in performance running silhouettes simultaneously elevates material cost structures and concentrates manufacturing competency among domestic compound formulators with specialized injection-molding capabilities. This production-method transition reshapes both pricing power at the premium tier and supplier selection criteria across midsole foam sourcing networks.
Pricing Analysis
The bundled-vs-unbundled service split separates fitted-selling specialty stores from direct-to-consumer platforms. Three-tier pricing structure across premium, standard, and economy levels reflects carbon-fiber plate inclusion, domestic assembly location, and REACH compliance certification. Pricing pressure stems from petrochemical input volatility in EVA and TPU feedstocks. Amateur runners in California metropolitan corridors exhibit lowest price sensitivity; budget-tier buyers in mass-market channels show highest elasticity.
Supply Chain Analysis
Freight cost volatility from Asian manufacturing nodes has accelerated nearshoring momentum into Mexico's Baja California and Chihuahua border states. Thermoplastic polyurethane compounding and injection-molded midsole component production concentrate in China, Vietnam, and Mexico. Raw material dependencies include ethylene-vinyl acetate, synthetic rubber compounds, and carbon-fiber sheet. Tariff exposure on cross-border assembly represents the dominant structural risk. Distribution runs through direct-to-consumer platforms, specialty running stores, and remaining department store volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America athletic footwear market functions as a regulatory compounder where the US Consumer Product Safety Commission's updated flammability standards for synthetic textile uppers are accelerating material reformulation investments across domestic supply chains.
For Market Incumbents: Anchor competitive position through expanded Massachusetts and Maine assembly capacity that insulates select product lines from tariff regime uncertainty. Deepen backward integration into domestic TPU and EVA compound formulation to absorb REACH compliance premiums without retail price pass-through. Prioritize R&D allocation toward performance knit uppers that reduce regulated petrochemical input exposure. For New Entrants and Emerging Players: Direct-to-consumer platform development with foot-scanning integration offers the most penetrable entry vector. Target subscription replenishment models in California and New York metropolitan markets where wearable device ownership density correlates with adoption. Pursue white-space positioning in circular material recovery infrastructure ahead of pending Oregon and Colorado extended producer responsibility legislation. For Investors and Strategic Acquirers: Valuations sit cheapest among domestic compound formulators with specialized midsole foam capabilities and established CPSC testing protocols. Long-term viability favors suppliers with captive access to biomechanical engineering talent in Massachusetts research corridors. Watch for inflection signals in state-level extended producer responsibility passage that would mandate end-of-life collection infrastructure investment.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Assembly Expansion | Massachusetts and Maine facilities insulate product lines from cross-border tariff volatility. |
| Direct-to-Consumer Platform Launch | Customization tools and subscription models capture margin pools from wholesale partners. |
| Performance Knit Upper R&D | Reduced petrochemical input dependency lowers REACH compliance cost exposure. |
| Circular Material Recovery Infrastructure | First-mover positioning ahead of Oregon and Colorado extended producer responsibility mandates. |
| Foot-Scanning Technology Integration | Distributed manufacturing compression enables made-to-order economics at mass-market price points. |
Study Parameters
Direct dialogue with brand product development executives, specialty retail buyers, domestic compound formulators, and biomechanical engineering researchers grounded the qualitative foundation. Secondary validation drew from US Consumer Product Safety Commission flammability standard filings, Health Canada chemical disclosure protocols, customs trade data on thermoplastic polyurethane imports, and SEC 10-K supply chain disclosures from publicly traded footwear manufacturers. Bottom-up segment sizing and top-down market triangulation cross-checked volume estimates across the analysis window.
Output projections incorporate modeled segmentation across product type, end user demographic, distribution channel, and price tier dimensions. CAGRs derive from regression analysis of historical volume trajectories adjusted for regulatory milestone impacts and technology adoption curves. Key forecast inputs include amateur runner population growth rates in California metropolitan corridors and domestic assembly capacity expansion timelines.
The model assumes a particular technology adoption path; alternative pathways for 3D-printed lattice midsole structures would alter the outlook for traditional injection-molding capacity requirements. Forecasts reflect documented assumptions around REACH compliance cost absorption and state-level extended producer responsibility passage timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Footwear
Platform Boots Market
Footwear
Second Hand Designer Shoes Market
Footwear
Chunky Sneaker Market
Footwear
Cowgirl Boots Market
Footwear
Kids Barefoot Shoes Market
Footwear
Lace Up Boots Market
Footwear
Sports Footwear Market
Footwear
Flip Flops Market
Footwear
Footwear Manufacturing Machinery Market
Footwear
Formal Shoes Market
Footwear
Golf Footwear Market
Footwear
Tennis Shoes Market
Footwear
Middle East and Africa E-Commerce Footwear Market
Footwear
Mountain Bike Footwear and Socks Market
Footwear
Sneaker Identification Service Market
Footwear
Orthopedic Footwear Market