
 Retort Machine Market | 2026-2036
Retort Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Retort Machine Market Analytics
Skilled retort technician availability is collapsing across North American food processing corridors. JBT Corporation leverages its century-long installed base to sustain aftermarket service revenue. Allpax Products LLC anchors its position through custom-engineered batch retort systems for regional canneries. Fedegari Autoclavi SpA dominates European pharmaceutical sterilization with ASME-stamped pressure vessel expertise.
A retort machine is a pressure vessel that applies saturated steam or water immersion at temperatures exceeding 121°C to achieve commercial sterility in sealed containers. Operating pressures typically range from 1.0 to 3.5 bar gauge depending on product thermal resistance and package geometry. Steam retorts command the largest installed base due to lower capital cost and simpler maintenance protocols. Automated solutions are expanding fastest as labor scarcity pushes canning facilities toward recipe-driven batch control with minimal operator intervention.
The FDA enforces 21 CFR Part 113 for low-acid canned foods, mandating process filing and equipment calibration that directly shapes retort validation service demand. EPA effluent guidelines constrain cooling water discharge from water bath retorts, pushing facilities toward closed-loop heat recovery designs. Forward stakeholders must weigh continuous processing capital intensity against hybrid systems that preserve batch flexibility while trimming energy and labor exposure.
Market Dynamics
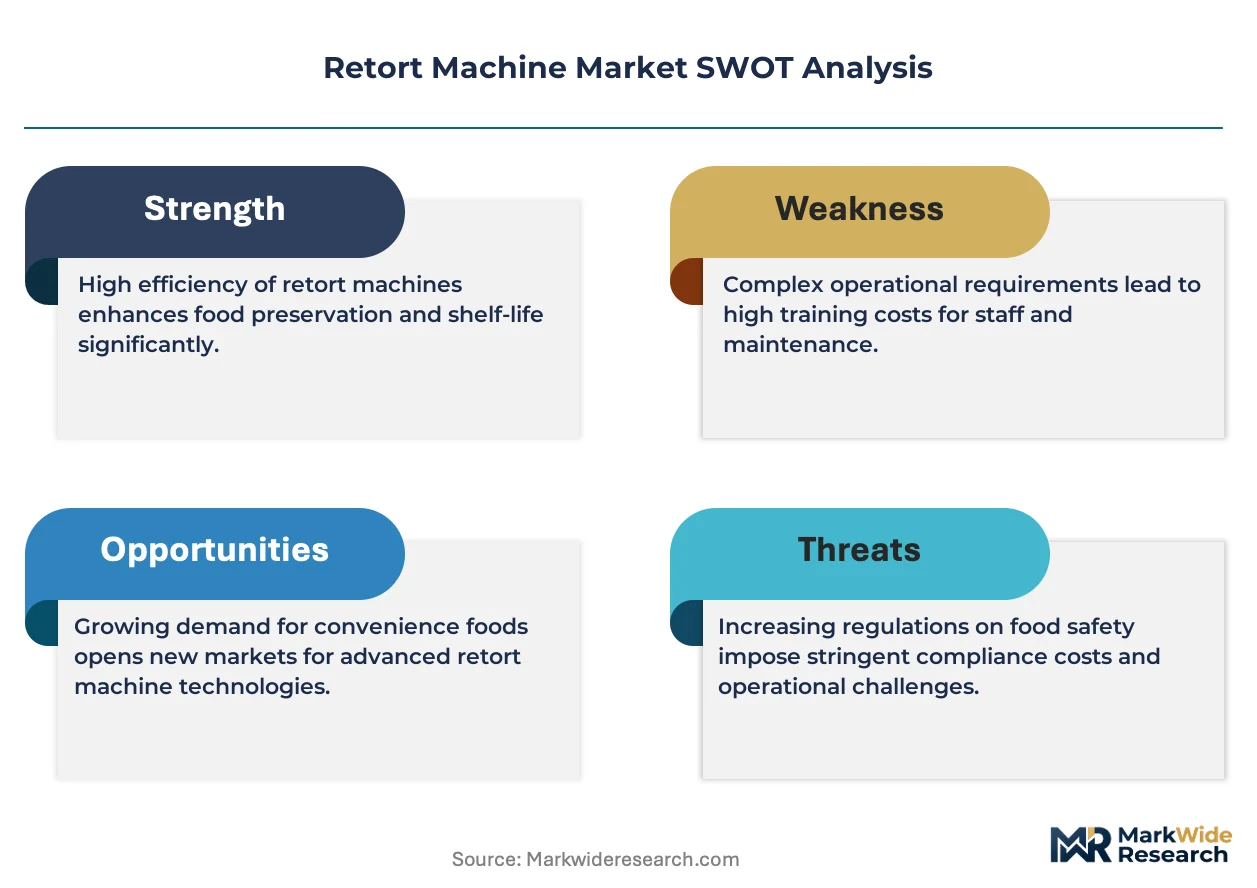
Labor scarcity across food processing corridors is compressing batch cycle times and forcing capital allocation toward autonomous retort systems with recipe-driven control architectures.
Growth Catalysts
- 21 CFR Part 113 enforcement:FDA process filing mandates for low-acid canned foods sustain validation service demand and equipment calibration protocols across US canneries.
- Ready-to-eat meal proliferation:Shelf-stable protein formats drive sterilization capacity expansion in contract manufacturing facilities serving military and emergency relief channels.
- Steam retort retrofit cycles:Aging pressure vessel infrastructure in Midwestern US food corridors triggers replacement demand for ASME-stamped systems with integrated heat recovery.
Market Restraints
- Stainless steel price volatility:316L grade alloy input costs swing with nickel futures, compressing fabricator margins on fixed-price vessel contracts.
- Skilled welder concentration:ASME-certified pressure vessel fabrication clusters in Wisconsin and Ohio, creating geographic chokepoints for delivery timelines.
- Water bath retort substitution limits:Steam-air hybrid systems cannot fully displace water immersion for viscous sauces, preserving legacy capital stock.
Strategic Opportunities
- Closed-loop heat recovery:EPA effluent guidelines push cooling water recirculation retrofits that cut thermal energy intensity by half in California processing plants.
- Pharmaceutical sterilization convergence:Overlapping ASME and cGMP standards let retort fabricators serve biologics containment with validated SIP cycles.
- Regional cannery automation:Pacific Northwest seafood processors adopt batch control systems to offset technician attrition in remote coastal facilities.
Industry Challenges
- Retort operator certification gaps:FDA-mandated thermal processing courses face 18-month backlogs, delaying facility commissioning.
- Legacy control system integration:1990s-era PLC architectures resist seamless handshaking with modern MES platforms, forcing custom middleware development.
- Validation documentation burden:Process authority filings for each new container geometry extend product launch timelines by quarters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Retort Machine Market |
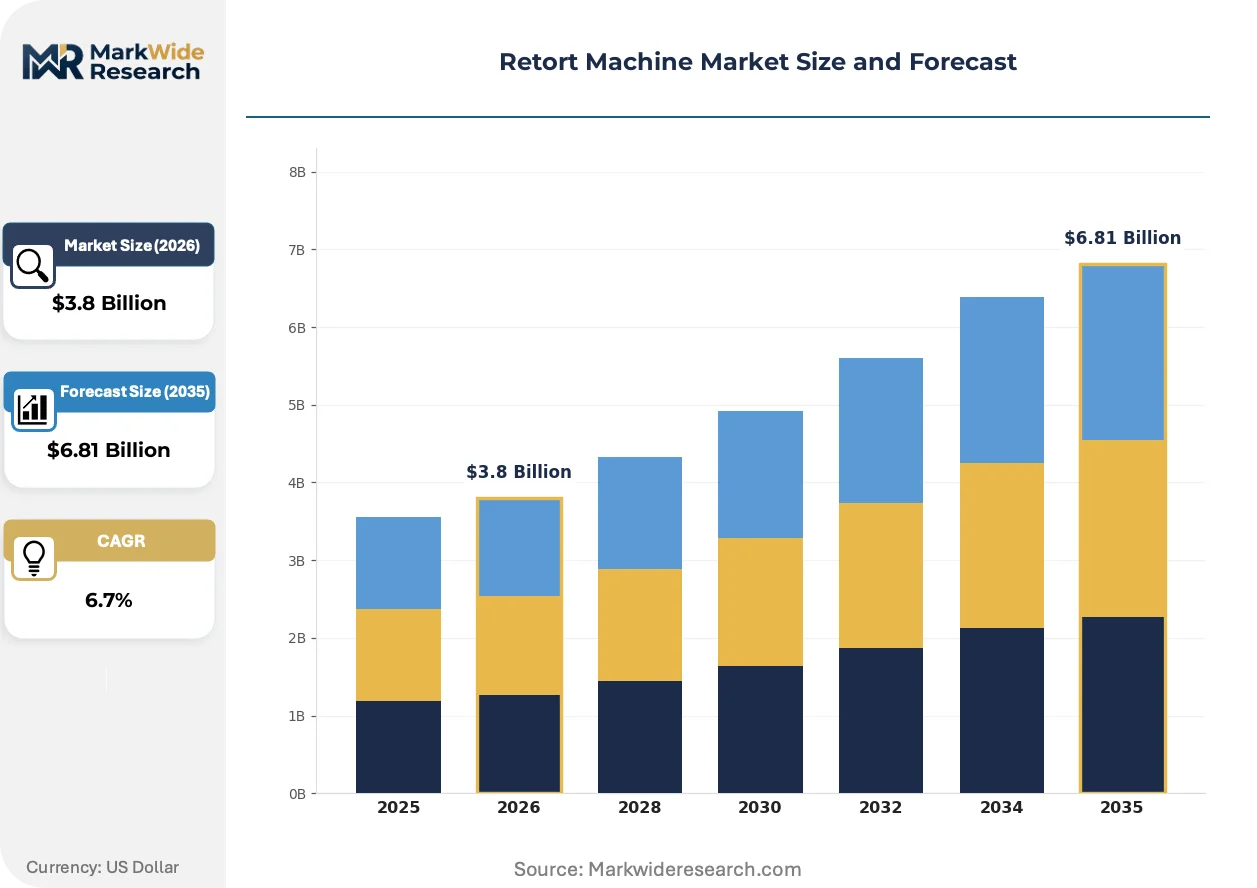
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steam Retorts, Water Bath Retorts, Hydrostatic Retorts, Rotary Retorts Technology: Batch Processing, Continuous Processing, Hybrid Systems, Automated Solutions Application: Food Processing, Pharmaceutical, Beverage, Chemical End User: Manufacturers, Canning Facilities, Research Labs, Industrial Plants |
| Companies Covered | PHC Corporation, Allpax Products LLC, JBT Corporation, Surdry SL, Fedegari Autoclavi SpA, STERIS Corporation, CFT S.p.A., Steriflow SAS, Getinge AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Retort Machine Market Evolving Landscape
Automation architectures are displacing manual retort operation while regulatory pressure on thermal process documentation intensifies equipment validation complexity.
Modular steam-air retort designs are fragmenting the traditional batch sterilization market. These systems combine saturated steam with overpressure air for flexible pouch and tray formats. Regional canneries in Oregon and Washington adopt them to handle seasonal salmon runs without dedicated water bath infrastructure. The technology is fragmenting capital deployment patterns by letting mid-scale processors serve multiple package types from single vessel footprints.
EPA effluent guidelines are tightening cooling water discharge limits for water bath retorts. Facilities must install closed-loop heat exchangers or face permit revocation. California processors bear the steepest compliance costs, accelerating migration toward steam-based systems with integrated energy recovery loops.
After-sales service unbundling is disrupting traditional OEM revenue models. Canneries now procure validation, calibration, and spare parts through third-party service contractors rather than captive vendor programs. This shift concentrates most visibly in Texas and Florida, where independent process authorities compete directly with JBT and Allpax service divisions for recurring maintenance spend.
Retort Machine Market Segmentation
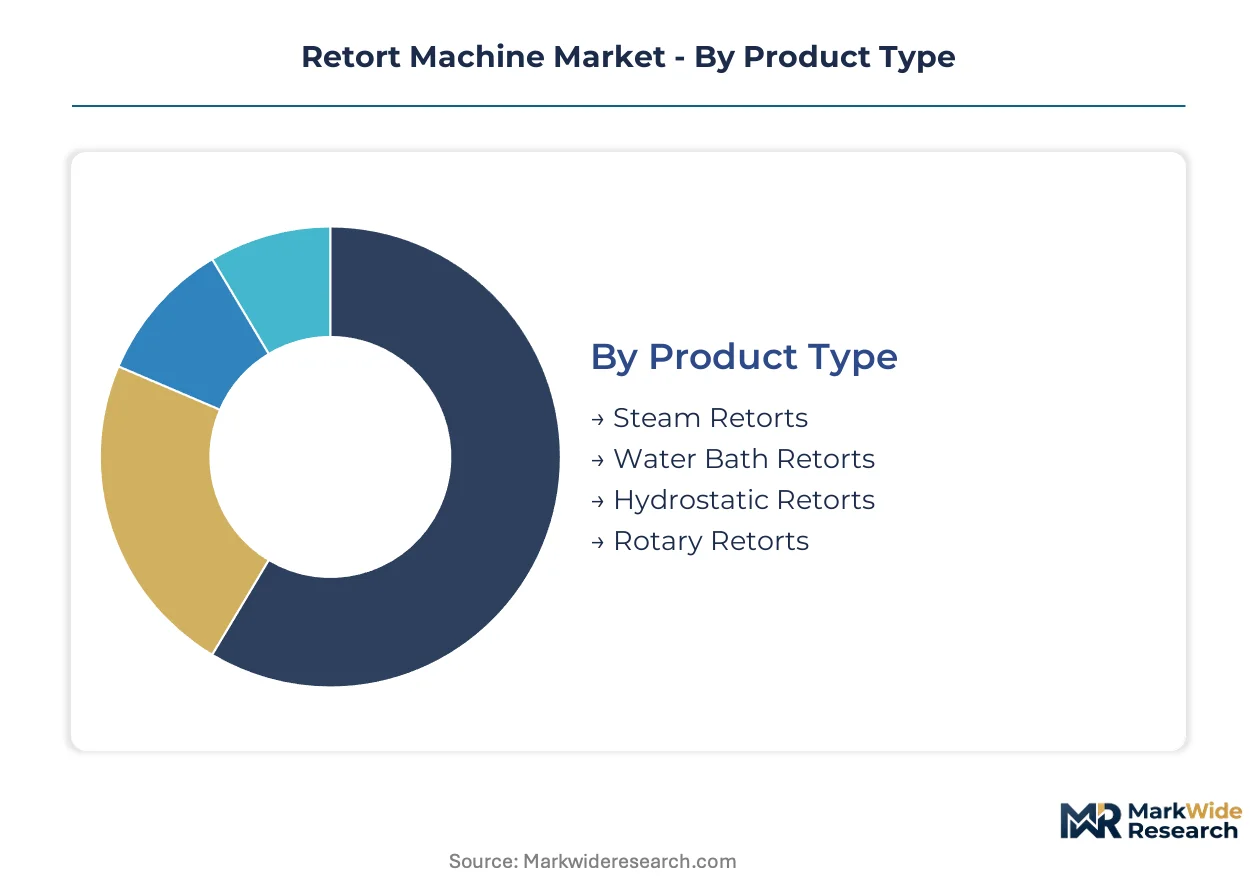
Retort machine procurement channels diverge sharply by operational scale and regulatory exposure. Food canneries favor batch systems with validation support, while pharmaceutical sterilization demands continuous processing with cGMP documentation.
Product Type:
Steam retorts flow through OEM-direct channels to established canneries, while water bath and hybrid configurations reach regional processors through distributor networks.
- Steam Retorts:These vessels deploy saturated steam at 121°C to 135°C through ASME-stamped pressure chambers with carbon steel or 316L stainless construction. Midwestern US food corridors concentrate replacement demand as aging infrastructure triggers retrofit cycles under FDA 21 CFR Part 113 enforcement.
- Water Bath Retorts:Full water immersion systems handle viscous sauces and pouch formats that steam-air hybrids cannot fully displace. California processors face EPA effluent compliance costs that accelerate migration toward closed-loop heat recovery designs or steam-based alternatives.
- Hydrostatic Retorts:Continuous water-column sterilizers serve high-volume canned vegetable lines.
- Rotary Retorts:Agitating vessel designs improve heat penetration for dense food matrices.
Steam retorts dominate installed base. Water bath retorts are where regulatory pressure concentrates most intensely.
Technology:
Cost tiers separate fully automated solutions from manual batch systems, with hybrid architectures capturing mid-scale processors seeking flexibility without continuous line capital intensity.
- Batch Processing:Recipe-driven control architectures with minimal operator intervention address technician attrition in remote coastal facilities. Pacific Northwest seafood processors adopt these systems to offset labor scarcity while preserving seasonal production flexibility.
- Continuous Processing:Hydrostatic and reel-and-spiral configurations maximize throughput for dedicated high-volume lines. Capital intensity limits adoption to military and emergency relief contract manufacturers with predictable year-round demand.
- Hybrid Systems:Steam-air designs serve multiple package types from single vessel footprints.
- Automated Solutions:PLC-integrated batch control with MES handshaking commands premium positioning.
Batch processing retains the largest installed footprint. Automated solutions are climbing the fastest as labor scarcity reshapes capital allocation.
Application:
Volume concentration varies by sterilization standard—commercial sterility for food versus cGMP validation for pharmaceutical—creating divergent equipment specification and service attachment rates.
- Food Processing:Low-acid canned food regulations mandate process filing and equipment calibration that sustain validation service demand. Shelf-stable protein formats drive capacity expansion in contract manufacturing facilities serving institutional channels.
- Pharmaceutical:ASME and cGMP standard convergence lets fabricators serve biologics containment with validated SIP cycles. Fedegari Autoclavi SpA anchors European positioning through pressure vessel expertise applied to sterilization-in-place protocols.
- Beverage:Retort pouch formats for ready-to-drink products require overpressure air systems.
- Chemical:Industrial sterilization of process equipment and containers.
Food processing anchors revenue concentration. Pharmaceutical applications are gaining share fastest through sterilization standard convergence.
End User:
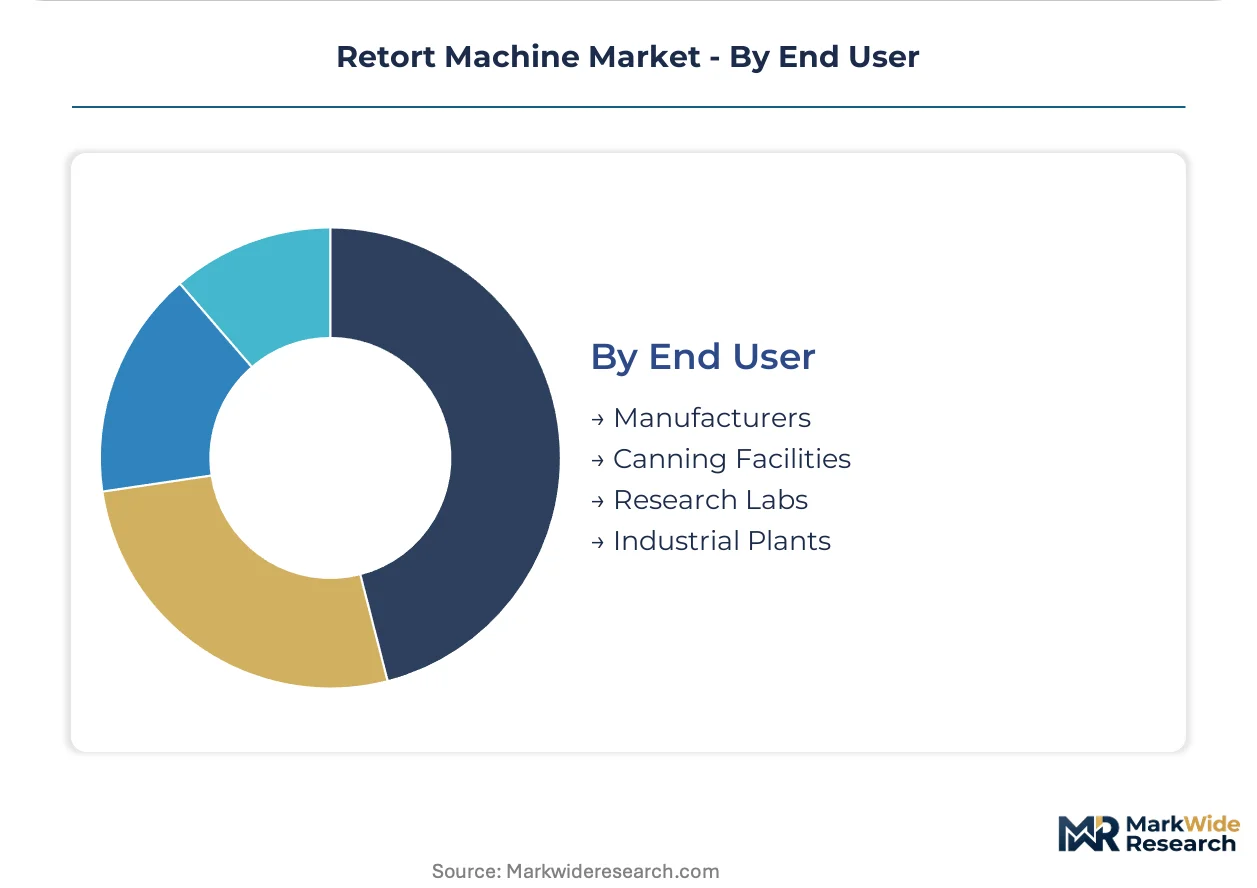
Customer type determines procurement pattern—manufacturers integrate retorts into greenfield lines, while canning facilities prioritize retrofit compatibility and third-party validation services.
- Manufacturers:Integrated food and pharmaceutical producers specify ASME-stamped systems with integrated heat recovery for greenfield capacity. These buyers command volume pricing and captive service contracts from JBT Corporation and Allpax Products LLC.
- Canning Facilities:Regional processors in Oregon and Washington adopt modular steam-air designs to handle seasonal salmon runs without dedicated infrastructure. Independent process authorities in Texas and Florida compete for validation and calibration spend.
- Research Labs:Pilot-scale batch systems for process development and thermal resistance studies.
- Industrial Plants:Chemical and non-food sterilization operations with customized pressure vessel requirements.
Canning facilities represent the broadest addressable base. Manufacturers concentrate the highest value per installation through integrated system procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in retort machine procurement tilts heavily toward United States buyers, while European fabricators extract premium positioning through ASME-cGMP dual certification. This asymmetry shapes capital deployment patterns across food processing corridors.
United States
Midwestern food corridors drive replacement demand for aging pressure vessel infrastructure under tightened FDA 21 CFR Part 113 enforcement. Wisconsin and Ohio fabrication clusters concentrate ASME-certified welder capacity, creating geographic chokepoints for delivery timelines. California processors face EPA effluent compliance costs that accelerate migration toward steam-based systems with integrated heat recovery.
Germany
Precision engineering traditions sustain premium positioning for pressure vessel fabricators serving pharmaceutical sterilization convergence. REACH chemical safety protocols and CE marking requirements shape equipment specification standards across EU member states. Bavarian industrial clusters anchor fabrication expertise for biologics containment applications.
China
Domestic food processing scale drives volume demand for batch sterilization capacity, particularly in Yangtze River Delta canning facilities. GB standards and MIIT equipment safety regulations govern pressure vessel construction for local market supply. Shandong Province seafood processors adopt automated control architectures to offset technician attrition in coastal facilities.
Italy
Specialized fabricators leverage ASME-stamped pressure vessel expertise to serve Mediterranean cannery modernization cycles. EU Green Deal energy efficiency targets push cooling water recirculation retrofits in Emilia-Romagna processing plants. Regional equipment suppliers compete on validation service attachment rates for seasonal tomato and vegetable sterilization lines.
Japan
Compact retort designs address space-constrained urban food processing facilities in Kanto and Kansai industrial zones. METI energy efficiency standards drive heat recovery system adoption in ready-to-eat meal production lines. Domestic fabricators emphasize recipe-driven batch control for minimal operator intervention in aging workforce environments.
Retort Machine Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. The installed base concentrates around century-long equipment suppliers with captive aftermarket service networks, while mid-scale regional fabricators compete on customization velocity. Two strategic archetypes dominate: integrated systems providers with validation service bundling, and specialized pressure vessel shops with ASME-cGMP dual certification. Competitive moves center on aftermarket service unbundling defense and heat recovery technology licensing.
Among North American integrated providers, JBT Corporation and Allpax Products LLC exemplify the systems-plus-service archetype. Fedegari Autoclavi SpA anchors European positioning through pressure vessel expertise applied to sterilization-in-place protocols. These three fabricators represent distinct geographic anchors for technology and certification convergence across food and pharmaceutical sterilization standards.
| Leading Market Players |
|---|
| PHC Corporation |
| Allpax Products LLC |
| JBT Corporation |
| Surdry SL |
| Fedegari Autoclavi SpA |
| STERIS Corporation |
| CFT S.p.A. |
| Steriflow SAS |
| Getinge AB |
| Others |
Value Network & Pricing Analysis
ASME certification requirements for pressure vessel fabrication simultaneously gate supplier qualification and stratify pricing tiers across retort machine procurement. FDA 21 CFR Part 113 validation protocols compound this dual function by mandating documented calibration histories that only established fabricators can reliably supply.
Pricing Analysis
Configured-to-order pricing for custom-engineered batch retorts commands substantial premiums over standard vessel configurations. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and after-sales service bundling. Cost compression in economy-tier steam retorts is intensifying because stainless steel price volatility squeezes fixed-price contract margins. Regional canneries in Oregon and Washington exhibit highest price sensitivity, while pharmaceutical contract manufacturers show lowest sensitivity due to cGMP compliance requirements.
Supply Chain Analysis
Inventory buffers for ASME-certified pressure vessels stretch to 12-18 months given welder certification bottlenecks. Supply concentrates in the United States, Germany, and Italy, with Wisconsin and Ohio fabrication clusters anchoring North American capacity. Raw material dependencies center on 316L stainless steel, nickel alloys, and carbon steel plate. Single-source vulnerability in ASME-certified welder pools creates delivery timeline risk. Distribution runs through OEM-direct channels for integrated systems and regional distributor networks for standard configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Retort machine procurement is evolving into a service-attach opportunity as validation, calibration, and spare parts revenue expand faster than hardware sales. Independent process authorities in Texas and Florida demonstrate how aftermarket unbundling reshapes competitive economics.
For Market Incumbents: Compound installed base advantages by deepening captive service contracts and heat recovery technology licensing. Defend against independent process authority encroachment through integrated validation bundling. Prioritize certification investment in ASME-cGMP dual stamping to capture pharmaceutical sterilization convergence.
For New Entrants and Emerging Players: Anchor in Pacific Northwest seafood processing automation where technician attrition creates urgent demand for recipe-driven batch control. Target mid-scale regional canneries seeking seasonal flexibility without continuous line capital intensity. Pursue go-to-market partnerships with independent service contractors already embedded in Texas and Florida maintenance spend.
For Investors and Strategic Acquirers: FDA 21 CFR Part 113 enforcement reshapes the acquisition landscape by elevating validation service capabilities above pure manufacturing scale. Long-term viability favors fabricators with documented calibration histories and ASME-cGMP dual certification. Monitor EPA effluent guideline expansion as signal for heat recovery technology licensing value inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Heat Recovery Technology Licensing | EPA effluent compliance in California accelerates closed-loop system adoption across water bath retort installations. |
| ASME-cGMP Dual Certification Investment | FDA and EMA sterilization standard convergence opens pharmaceutical biologics containment to food equipment fabricators. |
| Recipe-Driven Batch Control Development | Pacific Northwest seafood processors offset technician attrition through minimal-intervention automation architectures. |
| Independent Validation Service Acquisition | Aftermarket unbundling in Texas and Florida concentrates recurring revenue outside traditional OEM captive programs. |
| Modular Steam-Air Retort Platform Launch | Oregon and Washington canneries serve multiple package formats from single vessel footprints during seasonal salmon runs. |
Research Methodology
A spread of perspectives from retort operators, plant engineers, aftermarket service heads, and FDA process authorities converged on the working assumptions driving this analysis. Primary interviews with maintenance directors at Midwestern food corridors and procurement leads at contract manufacturing facilities combined with secondary validation from FDA 21 CFR Part 113 filings, EPA effluent guideline records, ASME pressure vessel registration databases, and SEC fabricator disclosures. Bottom-up equipment shipment tallies and top-down sterilization capacity estimates were triangulated to establish market sizing.
Segmentation dimensions modeled include retort technology type, processing architecture, application sector, and end-user operational scale across the analysis window. CAGRs were derived from equipment replacement cycle analysis and sterilization capacity expansion trajectories. Forecast inputs incorporated stainless steel price volatility patterns and ASME-certified welder pipeline constraints.
Material uncertainties — regulatory enforcement intensity, nickel futures volatility, and technician certification backlog duration — sit outside the modeled envelope. Forecasts reflect assumptions about sustained FDA process filing mandates and EPA effluent guideline expansion. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aseptic & Retort Packaging
Aseptic Packaging Equipment Market
Aseptic & Retort Packaging
Retort Packaging Market
Aseptic & Retort Packaging
Retort Films Market
Aseptic & Retort Packaging
Global Aseptic Sampling Market
Aseptic & Retort Packaging
Plastic Retort Cans Market
Aseptic & Retort Packaging
Aseptic Transfer System Market
Aseptic & Retort Packaging
Global Aseptic Paper Packaging Market
Aseptic & Retort Packaging
North America Retort Packaging Market
Aseptic & Retort Packaging
APAC Aseptic Packaging Market
Aseptic & Retort Packaging
Europe Aseptic Packaging Market
Aseptic & Retort Packaging
Retort Cartons Market
Aseptic & Retort Packaging
Global Pillow Shape Aseptic Packaging Market
Aseptic & Retort Packaging
Aseptic Fillers Market
Aseptic & Retort Packaging
Latin America Aseptic Packaging Market
Aseptic & Retort Packaging
Aseptic Packaging Market
Aseptic & Retort Packaging
Retort Grade BOPET Films Market