
 Plastic Hopper Loader Market | 2026-2036
Plastic Hopper Loader Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Hopper Loader Market Insights
Market Context
Food-grade and medical-grade specification tiers is reorganizing procurement priorities across the plastic hopper loader landscape. Piovan leverages its integrated drying and conveying systems to anchor premium positioning in European medical molding. Shini sustains manufacturing scale advantages across Asian packaging corridors. Conair differentiates through controls integration that extends machine connectivity for Industry 4.0 workflows.
Technical Definition and Segment Structure
A plastic hopper loader is a materials-handling device that uses vacuum pressure or pneumatic force to transfer resin pellets from bulk containers into the feed throat of processing equipment, typically operating at throughput rates from 50 to 1,000 kg per hour depending on conveying distance and material density. The device serves to automate material delivery, reduce contamination risk, and maintain consistent melt quality in continuous production environments. Vacuum loaders dominate installed bases across injection molding applications where closed-loop material recovery preserves resin integrity, while high-temperature loaders represent the fastest-expanding product category as engineered polymers processing spreads into automotive underhood and electronics connector segments. Centralized systems command the highest margin pools by consolidating controls, filtration, and line balancing across multi-machine cell layouts.
Regulatory Environment and Outlook
The EU F-Gas Regulation and REACH compliance frameworks shape material contact surface specifications and drive sealed-system designs that minimize fugitive emissions during resin transfer. OSHA dust exposure limits and FDA food-contact material regulations in the United States enforce filtration performance and surface finish standards that differentiate equipment tiers. Stakeholders must monitor evolving PFAS restrictions and polymer-specific handling requirements as regulatory scope broadens beyond traditional mechanical safety to encompass chemical exposure pathways.
Market Dynamics
Injection molding cell automation is compressing material handling into synchronized sub-systems, forcing hopper loader suppliers to engineer vacuum receivers that communicate directly with machine controls rather than operate as standalone peripherals.
Growth Catalysts
- EU F-Gas Regulation:Mandates for sealed refrigerant systems in industrial equipment are accelerating replacement cycles across European packaging corridors as processors retrofit vacuum lines to meet leakage thresholds.
- Engineered polymer proliferation:Automotive underhood and electronics connector applications require high-temperature conveying systems capable of handling PEEK and PPS without thermal degradation.
- China injection molding density:Clustering of medical device and consumer electronics manufacturers in Guangdong and Jiangsu provinces sustains concentrated demand for centralized material handling infrastructure.
Market Restraints
- Stainless steel input volatility:Grade 304 and 316 sheet metal price swings compress margin predictability for food-grade and medical-grade equipment fabricators.
- German component supplier concentration:Precision vacuum pump and sensor sourcing remains concentrated among Mittelstand specialists, creating bottleneck exposure for system integrators.
- REACH chemical complexity:Evolving substance restrictions on polymer contact surfaces extend certification timelines and freeze specification decisions during compliance reviews.
Strategic Opportunities
- India medical molding expansion:CDSCO regulatory harmonization with EU MDR standards is attracting diagnostic consumable manufacturers seeking compliant material handling infrastructure.
- Industry 4.0 convergence:Integration of OPC-UA connectivity with predictive filtration monitoring creates aftermarket service revenue streams beyond equipment sales.
- US IRA clean manufacturing incentives:Tax credits for domestic plastics processing equipment procurement favor localized assembly operations serving automotive battery housing markets.
Industry Challenges
- Controls integration expertise gap:Shortage of automation engineers capable of bridging pneumatic conveying hardware with injection molding machine protocols extends commissioning timelines.
- FDA 21 CFR Part 11 validation:Electronic records compliance for medical-grade material traceability demands documentation infrastructure that smaller processors struggle to resource.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Hopper Loader Market |
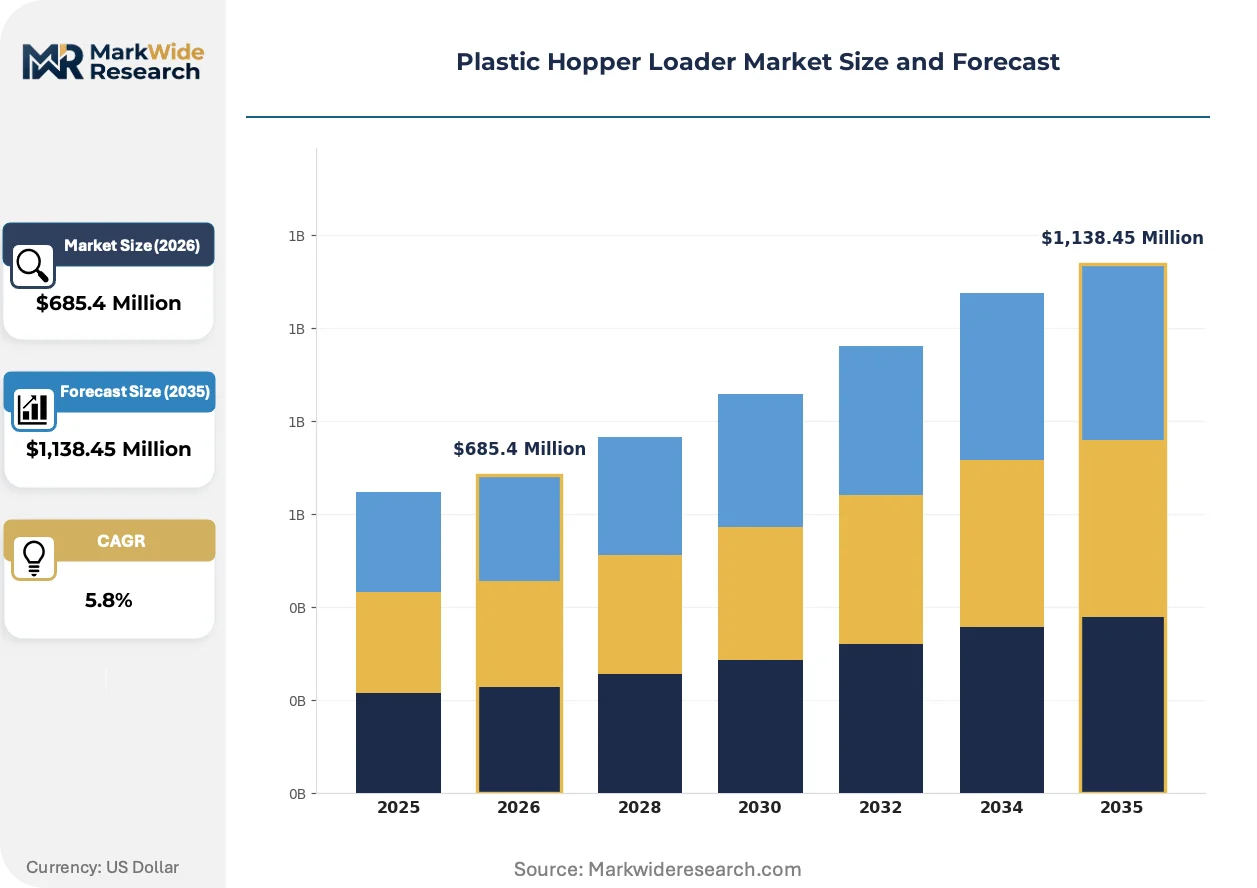
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vacuum Loader, Pneumatic Loader, Manual Loader, High-Temperature Loader Application: Injection Molding, Blow Molding, Extrusion, Thermoforming, Rotational Molding End User Industry: Packaging Manufacturers, Electrical & Electronics, Construction Material Producers, Consumer Goods Fabricators, Agricultural Equipment Makers Installation Type: Standalone Units, Centralized Systems, Portable Loaders, Multi-Point Loading |
| Companies Covered | Piovan, Shini, Conair, Turn Machine (Zhejiang), Novatec, Motan-Colortronic, Koch Technik, Harmo, Wittmann, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Hopper Loader Market Trends and Innovations
Material handling intelligence is migrating from centralized control rooms to edge-mounted sensors, transforming hopper loaders from passive conveyance devices into data-generating nodes that optimize resin flow in real time.
Self-cleaning vacuum receivers with integrated pulse-jet filtration are displacing conventional cartridge-based systems in continuous production environments. Medical device manufacturers in Switzerland and Germany are specifying these units to eliminate cross-contamination risks during resin changeovers. The technology is displacing manual cleaning protocols that previously required 15-20 minute line stoppages, compressing effective equipment utilization rates upward.
The EU F-Gas Regulation is mandating hermetic sealing standards that extend beyond refrigerant systems into ancillary vacuum equipment. Processors in automotive supply chains must now document fugitive emission rates across entire material handling loops. High-temperature loader categories face the steepest compliance costs, as thermal expansion tolerances conflict with gasket integrity requirements under new test protocols.
Buying committees at major packaging groups are consolidating vendor relationships to reduce qualification overhead. Single-source agreements for integrated drying-conveying systems are replacing fragmented procurement of separate components. This concentration is most pronounced among German automotive Tier 1 suppliers, where material traceability requirements favor unified system accountability over best-of-breed component sourcing.
Plastic Hopper Loader Market Segmentation
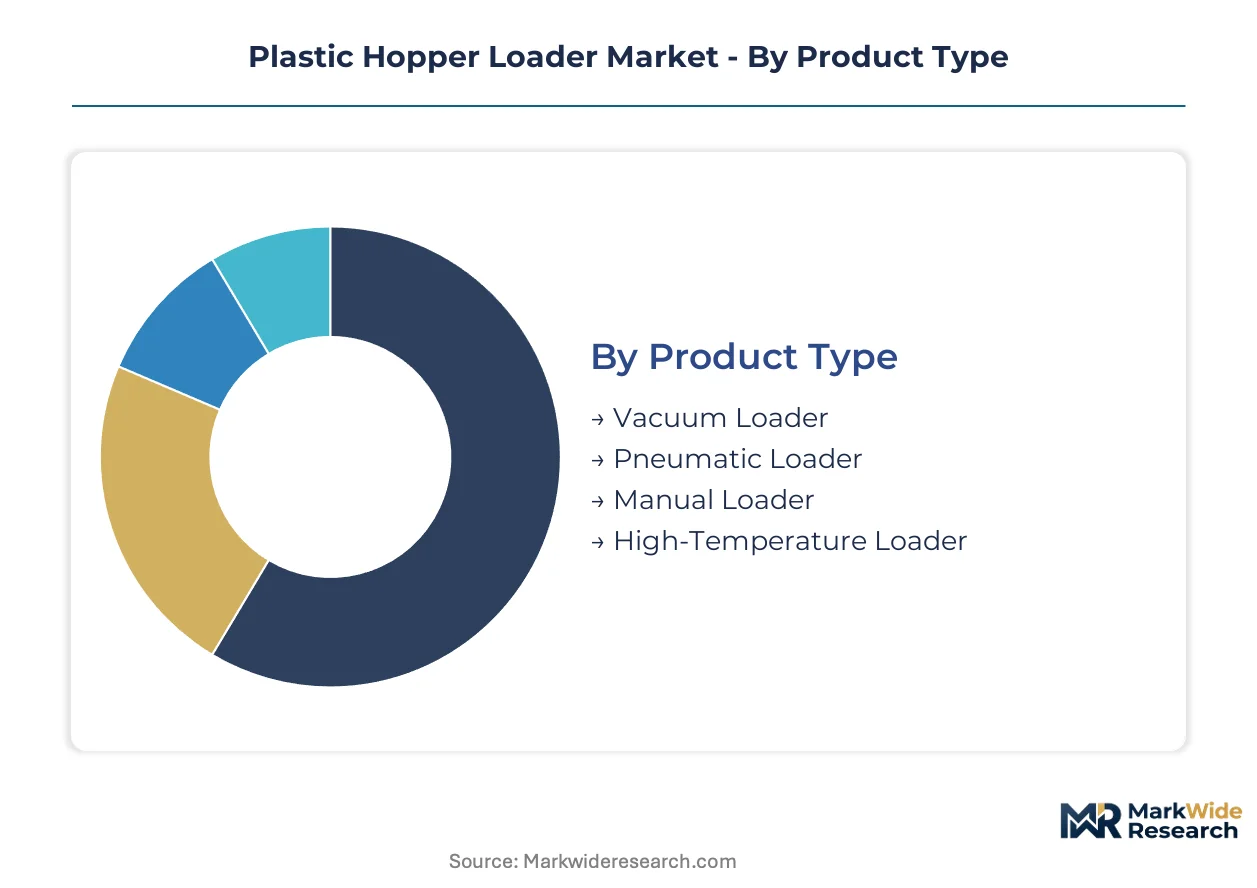
Equipment specification tiers in the plastic hopper loader market map directly to processing complexity and contamination sensitivity. Procurement committees weigh throughput requirements against validation overhead, creating distinct margin architectures across product categories.
Product Type:
Highest margin capture concentrates in sealed-system designs serving regulated industries, while commodity vacuum units compete on throughput density.
- Vacuum Loader:Closed-loop pneumatic conveying systems dominate installed bases across injection molding floors, leveraging negative pressure to transfer resin without atmospheric exposure. Demand clusters in German automotive supply chains where EU F-Gas Regulation mandates hermetic sealing across material handling loops. These units anchor replacement cycles as processors retrofit legacy lines to meet fugitive emission thresholds.
- High-Temperature Loader:Engineered with ceramic-lined receivers and high-heat gaskets, these systems convey PEEK, PPS, and other high-performance polymers without thermal degradation. Automotive underhood component manufacturers in Stuttgart and Wolfsburg specify these units for battery housing and connector applications, driving specification premiums.
- Pneumatic Loader:Positive-pressure systems suit short-distance conveying in packaging corridors where contamination risk remains manageable.
- Manual Loader:Gravity-fed or hand-loaded units persist in small-batch rotational molding shops with low throughput requirements.
The dominant share belongs to Vacuum Loader configurations, while High-Temperature Loader is closing the gap fastest.
Application:
Processing method determines conveying distance, material residence time, and integration complexity with upstream drying systems.
- Injection Molding:Continuous pellet feed demands synchronize hopper loader cycles with screw recovery times, requiring vacuum receivers that communicate via OPC-UA with machine controls. Guangdong province hosts the densest concentration of automated cells, where multi-cavity tooling pressures material handling into sub-30-second cycle compliance.
- Extrusion:Steady-state conveying over longer distances favors centralized blower systems with surge bin buffering. Pipe and profile manufacturers across the US Gulf Coast deploy these architectures for HDPE and PVC compound handling.
- Blow Molding:Parison programming tolerances require consistent melt index, driving demand for dried-air conveying in PET bottle production.
- Thermoforming:Sheet extrusion integration favors inline granulate feeding with minimal elevation changes.
- Rotational Molding:Batch-wise powder handling accommodates simpler loader specifications in tank and playground equipment fabrication.
Injection Molding commands the largest equipment footprint, though Extrusion is expanding most quickly as infrastructure pipe demand accelerates.
End User Industry:
Regulatory exposure and traceability requirements stratify pricing power across customer verticals.
- Packaging Manufacturers:High-throughput lines serving beverage and food containers prioritize reliability over precision, with FDA food-contact compliance driving stainless steel surface specifications. Major groups in Wisconsin and Pennsylvania consolidate vendor relationships to reduce qualification overhead.
- Electrical & Electronics:Connector and housing producers require high-temperature capability for engineering polymers, with flame-retardant compound handling adding filtration complexity. Jiangsu province clustering sustains concentrated demand.
- Construction Material Producers:PVC pipe and siding extrusion tolerates commodity-grade equipment with lower controls integration.
- Consumer Goods Fabricators:Appliance housing and toy molding balance cost sensitivity with color-change flexibility.
- Agricultural Equipment Makers:Large-part rotational molding of tanks and housings operates with intermittent loading cycles.
Packaging Manufacturers retain the dominant procurement volume, while Electrical & Electronics is gaining share fastest on polymer complexity premiums.
Installation Type:
System architecture determines capital allocation between hardware and integration services.
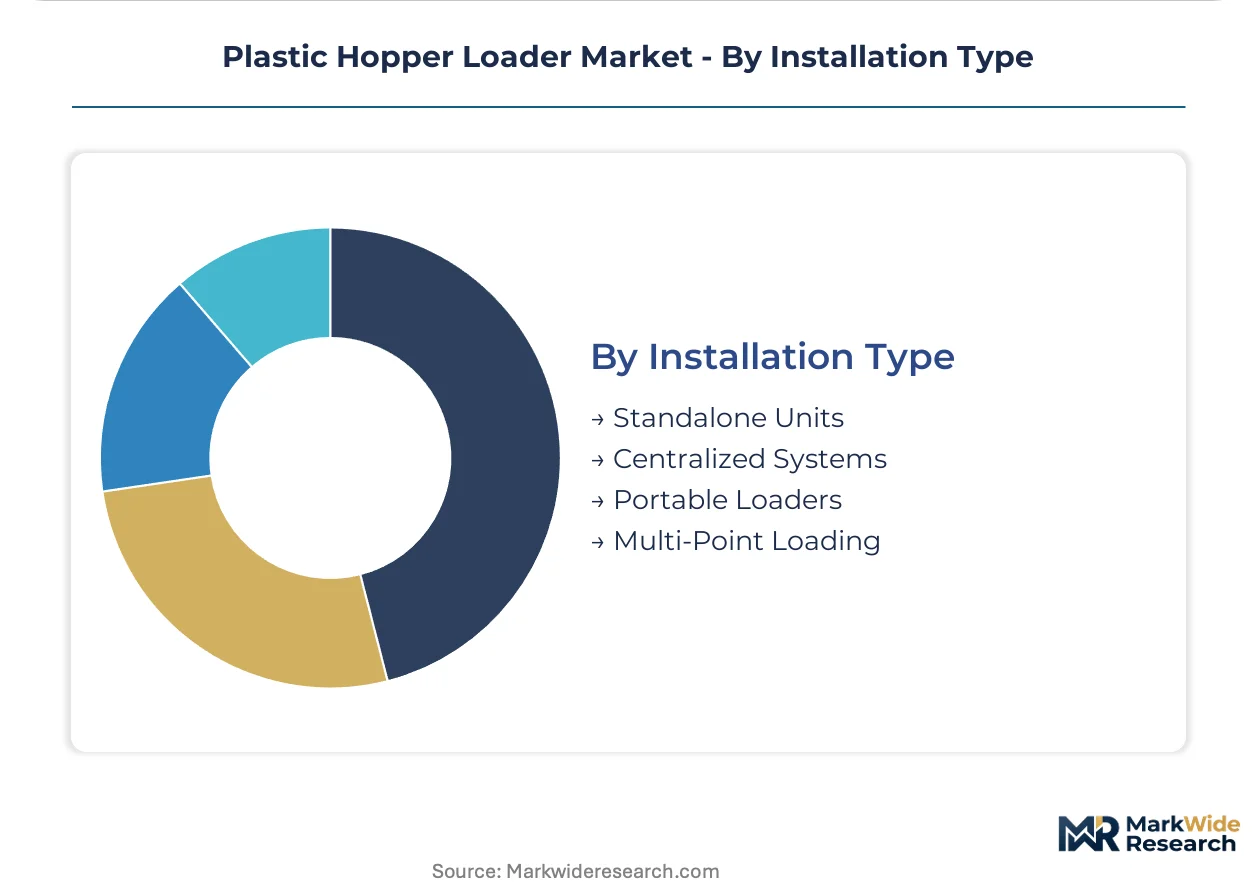
- Centralized Systems:Multi-machine material handling loops consolidate drying, conveying, and controls across injection molding cells, commanding the highest project values. German automotive Tier 1 suppliers favor unified system accountability for traceability compliance.
- Standalone Units:Machine-mounted receivers suit smaller processors with limited capital budgets and simpler material portfolios.
- Portable Loaders:Castor-mounted units serve job shops with frequent resin changeover requirements.
- Multi-Point Loading:Selector valve manifolds enable single blower stations to feed multiple machines, optimizing blower utilization in mid-scale operations.
Centralized Systems capture the dominant project value, while Multi-Point Loading is climbing the fastest as mid-tier processors seek blower efficiency without full centralization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in export-dependent Asian packaging corridors show acute price sensitivity to stainless steel input costs, while German automotive Tier 1 suppliers absorb specification premiums for traceability compliance. Demand elasticity varies sharply across regulatory exposure tiers.
China
Injection molding density in Guangdong and Jiangsu provinces sustains concentrated demand for centralized material handling infrastructure. MIIT energy efficiency mandates and dual carbon goals accelerate equipment replacement cycles toward sealed vacuum systems. Medical device manufacturers in Shenzhen are retrofitting legacy lines to meet EU MDR-equivalent traceability standards for diagnostic consumable exports.
Germany
Automotive underhood component production in Stuttgart and Wolfsburg drives specification premiums for high-temperature PEEK and PPS conveying systems. EU F-Gas Regulation mandates hermetic sealing across entire material handling loops, forcing retrofit investments. Mittelstand vacuum pump specialists in Baden-Württemberg create sourcing bottlenecks for system integrators.
United States
Packaging groups in Wisconsin and Pennsylvania consolidate vendor relationships to reduce FDA food-contact qualification overhead. OSHA dust exposure limits and IRA clean manufacturing tax credits reshape procurement toward domestic assembly operations. Automotive battery housing producers in Michigan leverage incentives for localized plastics processing equipment.
India
CDSCO regulatory harmonization with EU MDR standards attracts diagnostic consumable manufacturers seeking compliant material handling infrastructure. Medical molding expansion concentrates in Maharashtra and Gujarat as contract manufacturers serve export markets. BIS certification timelines extend specification freeze periods during compliance reviews.
Switzerland
Swissmedic-regulated medical device manufacturers specify self-cleaning vacuum receivers to eliminate cross-contamination risks during resin changeovers. Precision molding clusters in Basel and Zurich prioritize equipment utilization rates over capital cost minimization. REACH chemical complexity drives premium-tier procurement for polymer contact surface validation.
Plastic Hopper Loader Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the plastic hopper loader landscape. European specialists anchor premium positioning through integrated drying-conveying systems and controls integration for medical-grade applications. Asian fabricators exploit manufacturing scale advantages across high-throughput packaging corridors. The competitive terrain rewards two dominant moves: vertical consolidation of component supply chains and OPC-UA-enabled service revenue expansion beyond equipment sales.
Within the European integrated-system tier, Piovan S.p.A. and Motan-Colortronic GmbH exemplify premium positioning through unified drying-conveying accountability. Wittmann Group anchors Austrian precision engineering credibility in high-temperature conveying specifications. Shini Plastics Technologies, Inc. represents the scale-driven Asian archetype serving export-oriented packaging manufacturers across Guangdong province clusters.
| Leading Market Players |
|---|
| Piovan |
| Shini |
| Conair |
| Turn Machine (Zhejiang) |
| Novatec |
| Motan-Colortronic |
| Koch Technik |
| Harmo |
| Wittmann |
| Others |
Pricing and Supply Chain Analysis
Manufacturing scale advantages in Guangdong province compress unit economics for commodity vacuum loaders while simultaneously anchoring price floors for premium sealed-system designs. This concentration dynamic forces European specialists to defend margin pools through certification-tier differentiation rather than throughput competition.
Pricing Analysis
EU F-Gas Regulation dictates the pricing tier structure across European procurement committees, separating hermetic-sealed systems from conventional vacuum units. Pricing stratifies across premium, standard, and economy tiers based on FDA 21 CFR Part 11 validation status and OPC-UA controls integration. Cost compression in standard-grade equipment is intensifying because Asian fabricators exploit stainless steel input volatility to undercut margin predictability. Packaging manufacturers in Wisconsin show acute price sensitivity, while Swissmedic-regulated medical device producers absorb specification premiums for traceability compliance.
Supply Chain Analysis
Inventory cycles for Grade 304 and 316 stainless steel sheet metal extend lead times for food-grade and medical-grade equipment fabricators. Component sourcing draws from Germany for precision vacuum pumps, China for blower assemblies, and Japan for ceramic-lined receivers. Single-source vulnerability concentrates among Mittelstand vacuum pump specialists in Baden-Württemberg. Distribution runs through OEM-direct channels for centralized systems and regional distributors for standalone units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. Certification timelines and validation infrastructure create switching costs that protect incumbent positioning.
For Market Incumbents: Secure backward integration into precision vacuum pump production to mitigate German supplier concentration risk. Expand OPC-UA-enabled aftermarket service contracts to convert equipment sales into recurring revenue streams. Capacity addition in Maharashtra addresses CDSCO regulatory harmonization opportunities. For New Entrants and Emerging Players: Predictive filtration monitoring services represent an under-served layer where incumbents lack dedicated software engineering benches. Target mid-tier processors in Gujarat seeking multi-point loading architectures without full centralization capital burden. Go-to-market leverage rests on pay-per-outcome contracting for equipment utilization guarantees. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among controls-integrated system integrators with captive aftermarket service infrastructure. Long-term viability favors acquisition targets with EU MDR-equivalent validation capabilities and established relationships with diagnostic consumable manufacturers. Watch FDA PFAS restriction timelines as an inflection indicator for polymer contact surface specification shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vacuum Pump Manufacturing | Mitigates Mittelstand supplier bottleneck exposure for system integrators serving automotive Tier 1 suppliers. |
| OPC-UA Platform Integration | Enables predictive maintenance revenue streams beyond equipment sales for injection molding cell synchronization. |
| EU MDR-Equivalent Certification Investment | Unlocks diagnostic consumable infrastructure contracts in Maharashtra and Gujarat export corridors. |
| Self-Cleaning Receiver Technology Launch | Eliminates 15-20 minute line stoppages for resin changeovers in Swissmedic-regulated medical molding. |
| Long-Term Service Agreement Expansion | Converts capital equipment relationships into recurring revenue with German automotive battery housing producers. |
Research Methodology
Initial hypotheses were tested against primary input from plant engineers at injection molding facilities, procurement leads at packaging groups, aftermarket service heads at equipment distributors, and regulatory affairs specialists at medical device manufacturers and refined through secondary validation. Sources included customs and trade data for resin handling equipment, SEC filings from listed industrial automation suppliers, EU F-Gas Regulation implementation reports, and CDSCO harmonization documentation. Bottom-up equipment shipment analysis and top-down end-use industry demand modeling were triangulated.
Variance decomposition across product type, application method, end-use industry, and installation architecture shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Industry-specific inputs included injection molding cell density metrics from Guangdong and Jiangsu provinces and EU MDR-equivalent validation timeline data from Indian contract manufacturers.
Underlying assumptions cover stainless steel price stability, regulatory enforcement consistency, and automotive battery housing demand trajectories, with deviation risk concentrated in REACH substance restriction scope expansion. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Equipment
Global End-Of-Line Packaging Market
Packaging Equipment
Coding and Marking Systems Market
Packaging Equipment
Bag Re-Sealer Market
Packaging Equipment
Label Converting Equipment Market
Packaging Equipment
Flatbed Die Cutters Market
Packaging Equipment
Clip Applicator Market
Packaging Equipment
Refrigerated Display Cases Market
Packaging Equipment
Tissue Roll Unwinders Market
Packaging Equipment
PIR Blow Molding Market
Packaging Equipment
Skin Packaging Equipment Market
Packaging Equipment
Global Cap Applicators Market
Packaging Equipment
Depalletizers Market
Packaging Equipment
Burnisher Market
Packaging Equipment
Filling Equipment Market
Packaging Equipment
Sack Tip Stations Market
Packaging Equipment
Cannabis Packaging Equipment Market