
 Stacking Machine Market | 2026-2036
Stacking Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Stacking Machine Market Analytics
Direct-to-fleet sales channels is reconfiguring how original equipment manufacturers reach end-users in the stacking machine industry. Toyota Industries Corporation leverages captive production of electric drive systems to control component costs across Asian markets. Jungheinrich AG anchors its position through intensive R&D spending on lithium-ion powertrains for warehouse fleets. Kion Group competes by sustaining broad geographic coverage across European distribution networks.
A stacking machine is a powered or manually operated material handling device designed to lift, transport, and vertically position palletized loads using fork carriage mechanisms rated typically from 1,000 to 2,000 kilograms. These machines serve manufacturing floors, distribution centers, and retail backrooms where vertical storage density and aisle maneuverability determine operational throughput. Automated stackers now lead capital expenditure flows as warehouse operators pursue labor reduction and pick-accuracy targets, while manual stackers retain share in small-format retail and light assembly settings where load volumes remain intermittent. Electric technology dominates new order books across logistics end-users, displacing hydraulic and pneumatic alternatives where indoor air quality standards restrict emissions.
OSHA workplace safety mandates in the United States and EU machinery directives enforced by national regulators shape product design, operator training requirements, and market access conditions for stacking equipment sold into industrial environments. CE marking under the EU Machinery Directive and ISO 3691 safety standards for industrial trucks establish baseline compliance thresholds that manufacturers must satisfy before commercial placement. Stakeholders should monitor how battery chemistry regulations and autonomous navigation certifications rewrite equipment specifications and service revenue models.
Market Dynamics
Electric powertrain conversion is compressing replacement cycles across warehouse fleets as operators retire internal combustion units ahead of regulatory deadlines. This technology shift is redistributing capital flows from engine suppliers toward battery pack integrators and charging infrastructure providers.
Growth Catalysts
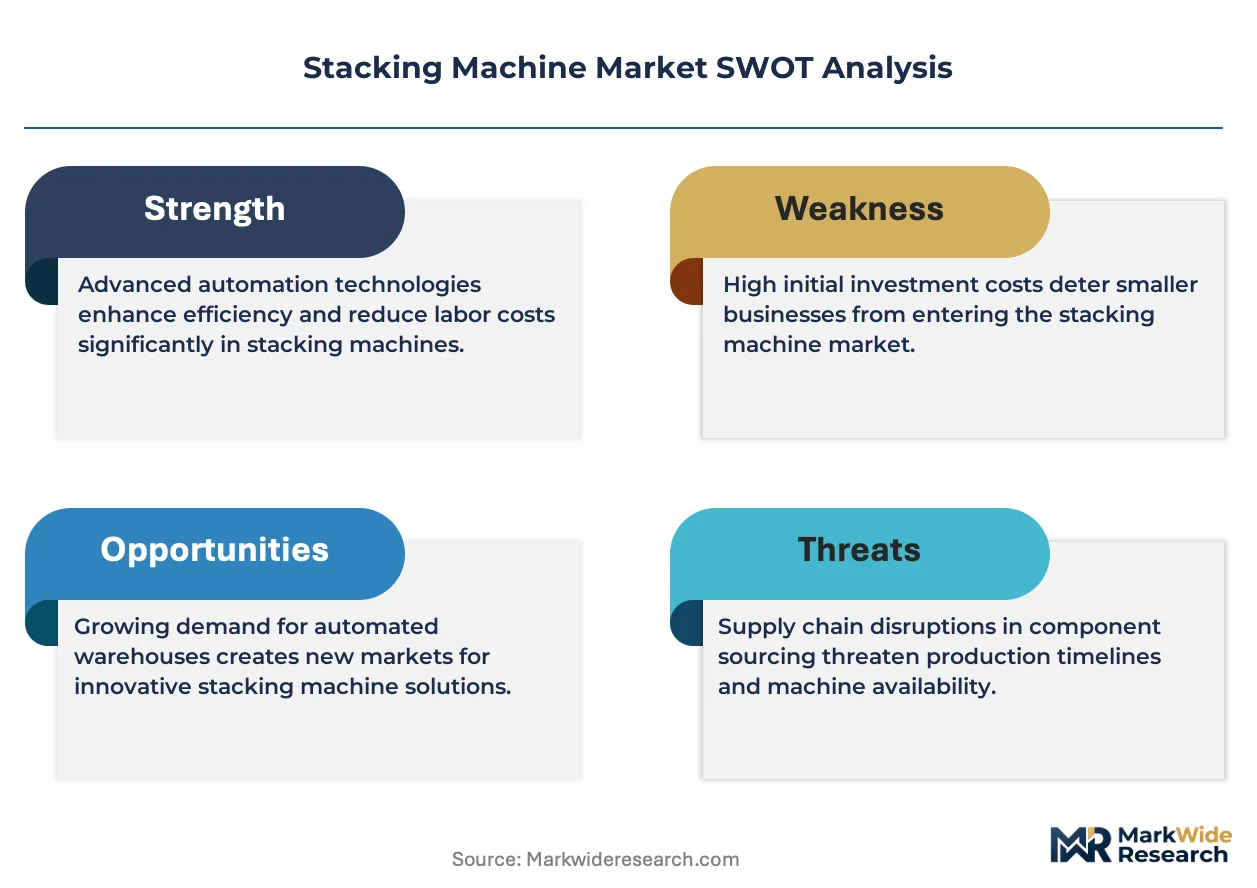
- EU Machinery Directive compliance mandates:Warehouse operators in Germany and France are accelerating fleet turnover to meet CE marking requirements for autonomous navigation systems, pulling forward equipment replacement timelines.
- Lithium-ion battery density improvements:Energy storage advances are extending single-shift operational range for electric stackers, eliminating the productivity penalty that previously favored diesel units in high-throughput distribution centers.
- China coastal logistics hub electrification:Municipal air quality enforcement in Shanghai and Shenzhen is prohibiting diesel equipment from operating within bonded port zones, forcing immediate equipment swaps.
Market Restraints
- Lithium and cobalt price volatility:Raw material cost swings for cathode chemistries are compressing gross margins for electric stacker manufacturers who lack long-term offtake agreements.
- Semiconductor supply concentration:Dependence on Taiwanese and South Korean foundries for motor control chips is extending lead times for variable frequency drive systems by four to six months.
- Lead-acid battery substitution persistence:Price-sensitive small retailers continue specifying flooded lead-acid powertrains, delaying full market conversion to maintenance-free alternatives.
Strategic Opportunities
- India warehouse automation underinvestment:Third-party logistics penetration remains below comparable emerging markets, creating whitespace for automated guided stacker deployments in Mumbai and Delhi distribution corridors.
- Outcome-based fleet availability contracts:Equipment-as-a-service models are replacing capital purchase decisions, shifting revenue streams toward uptime guarantees and predictive maintenance subscriptions.
- EU Green Deal machinery retrofit incentives:National recovery funds in Italy and Spain are subsidizing diesel-to-electric conversions, lowering customer acquisition costs for replacement equipment.
Industry Challenges
- Autonomous navigation certification delays:ISO 3691-4 safety validation protocols require extensive field testing, stretching product launch timelines for sensor-fusion stacker models.
- Legacy warehouse management system integration:Proprietary WMS architectures in established distribution networks resist API standardization, complicating fleet telematics deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stacking Machine Market |
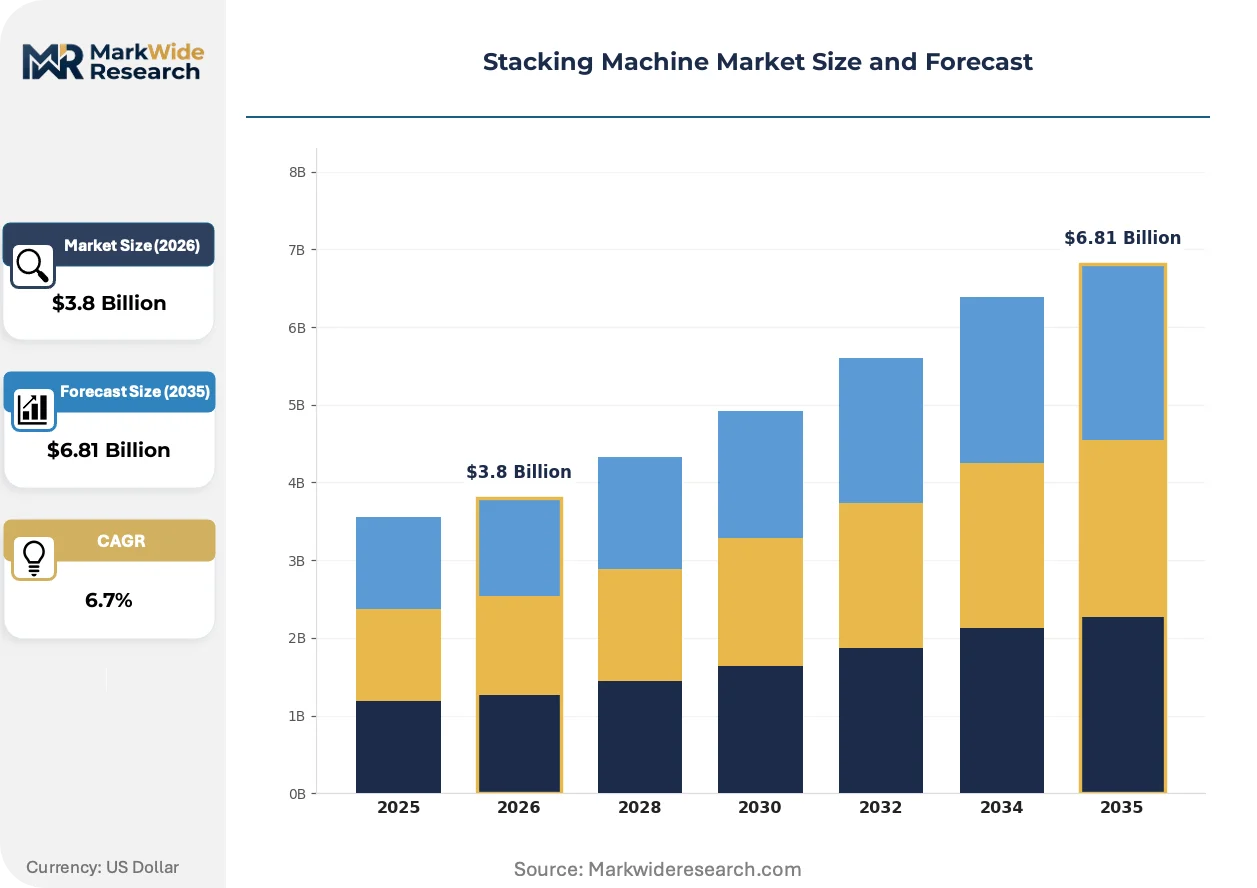
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Stackers, Manual Stackers, Semi-Automated Stackers, Reach Stackers End User: Manufacturing, Logistics, Retail, Warehousing Technology: Hydraulic, Electric, Pneumatic, Mechanical Application: Material Handling, Packaging, Assembly, Inventory Management |
| Companies Covered | Toyota Industries Corporation, Crown Equipment Corporation, Hyster-Yale Materials Handling Inc., Jungheinrich AG, Kion Group, Mitsubishi Logisnext Co. Ltd., Clark Material Handling Company, Doosan Corporation, Hangcha Group Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stacking Machine Market Evolving Landscape
Stacking equipment is converging with warehouse robotics platforms as navigation software and sensor hardware migrate from standalone systems toward integrated automation stacks. This convergence is compressing the boundary between manually operated and fully autonomous material handling.
Lithium-iron-phosphate battery chemistry is migrating from premium product positioning toward standard equipment specification across European warehouse fleets. Mid-size third-party logistics operators in the Netherlands and Belgium are now specifying LFP powertrains as default configurations. The technology is migrating from niche cold-storage applications toward ambient distribution environments, collapsing the price premium that previously separated phosphate and oxide chemistries.
OSHA workplace safety mandates in the United States are tightening operator training documentation requirements for powered industrial trucks. Employers must now maintain electronic certification records accessible to inspectors on demand. Food and beverage distribution centers are responding fastest, driven by liability exposure in high-traffic loading dock environments where pedestrian-stacker interaction frequency peaks.
Direct equipment procurement by fleet operators is displacing distributor-mediated sales channels in large-account segments. National retail chains are establishing preferred supplier agreements that bypass regional equipment dealers. This pattern is most visible in North American grocery and general merchandise distribution, where centralized procurement functions consolidate specifications across fifty-plus facility networks.
Stacking Machine Market Segmentation
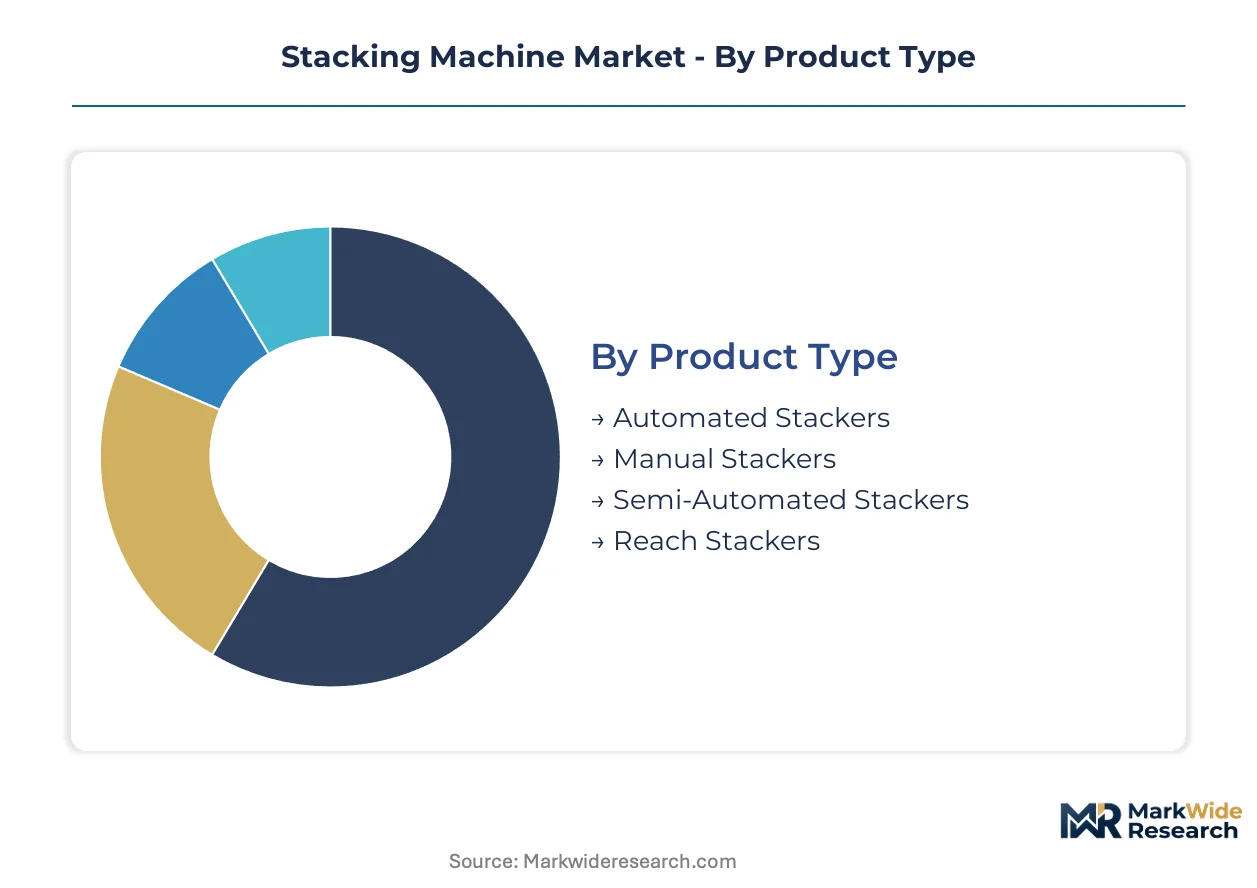
Segmentation in the stacking machine market reveals how equipment specifications align with operational intensity, regulatory environments, and capital deployment strategies across distinct use cases. Understanding these divides exposes where technology substitution accelerates and where legacy configurations retain commercial viability.
Product Type:
Use-case spectrum spans lights-out automation to intermittent manual intervention, with capital intensity and labor substitution determining specification choices.
- Automated Stackers:Sensor-fusion navigation systems integrate LiDAR, camera arrays, and ultrasonic obstacle detection for aisle traversal without human operators. Demand concentrates in Dutch and Belgian third-party logistics hubs where labor costs and ISO 3691-4 safety compliance timelines compress payback periods to under thirty-six months.
- Manual Stackers:Human-powered or pedestrian-operated units with hydraulic lift mechanisms rated to 1,500 kilograms serve intermittent load cycles. Small-format retail backrooms in France and Italy specify these units where daily pallet movements fall below fifteen cycles and capital budgets resist electrification premiums.
- Semi-Automated Stackers:Operator-supervised machines with assisted positioning and collision avoidance systems bridge manual and autonomous workflows.
- Reach Stackers:Heavy-lift variants with extending mast assemblies handle double-deep racking configurations up to twelve meters.
The dominant share belongs to Automated Stackers, while Manual Stackers retain entrenched positions in cost-sensitive segments.
End User:
Customer archetypes range from high-velocity fulfillment networks to stationary production floors with predictable inbound-outbound rhythms.
- Logistics:Third-party distribution operators managing multi-tenant facilities prioritize equipment interoperability and rapid battery swap protocols. German freight forwarders along the Rhine-Alpine corridor are consolidating fleet specifications to simplify maintenance contracts across thirty-plus warehouse locations.
- Warehousing:Dedicated storage operations for retail and industrial clients emphasize vertical density maximization and narrow-aisle maneuverability. Spanish cold-storage networks near Valencia and Barcelona are retrofitting with lithium-iron-phosphate electric stackers to exploit EU Green Deal subsidy streams.
- Manufacturing:Production-integrated material handling connects assembly lines to raw material staging areas through just-in-time delivery protocols.
- Retail:Store-level backroom operations favor compact footprints and pedestrian-scale equipment for direct-to-shelf replenishment.
Logistics commands the largest equipment procurement volumes, though Warehousing is expanding most quickly as e-commerce penetration deepens inventory holding requirements.
Technology:
Powertrain selection reflects indoor air quality enforcement, energy cost structures, and maintenance labor availability across operating environments.
- Electric:Battery-powered AC motor drives with regenerative braking and opportunity charging capability displace combustion alternatives where emissions restrictions apply. Shanghai municipal authorities have prohibited diesel equipment from bonded port zones, forcing immediate fleet turnover among container freight stations.
- Hydraulic:Fluid-power lift systems with internal combustion prime movers persist in outdoor yard operations and heavy-lift applications beyond electric duty-cycle limits. German intermodal terminals continue specifying hydraulic reach stackers for container handling where electrification infrastructure remains underdeveloped.
- Pneumatic:Compressed-air actuation serves explosive atmosphere classifications and cleanroom manufacturing where spark suppression mandates apply.
- Mechanical:Manual or spring-assisted lift mechanisms without external power sources operate in remote facilities lacking electrical distribution.
Electric technology has captured mainstream specification status, while Hydraulic retains defensive positions in outdoor heavy-lift segments.
Application:
Functional deployment patterns track how equipment mobility requirements differ between stationary lifting tasks and continuous transport operations.
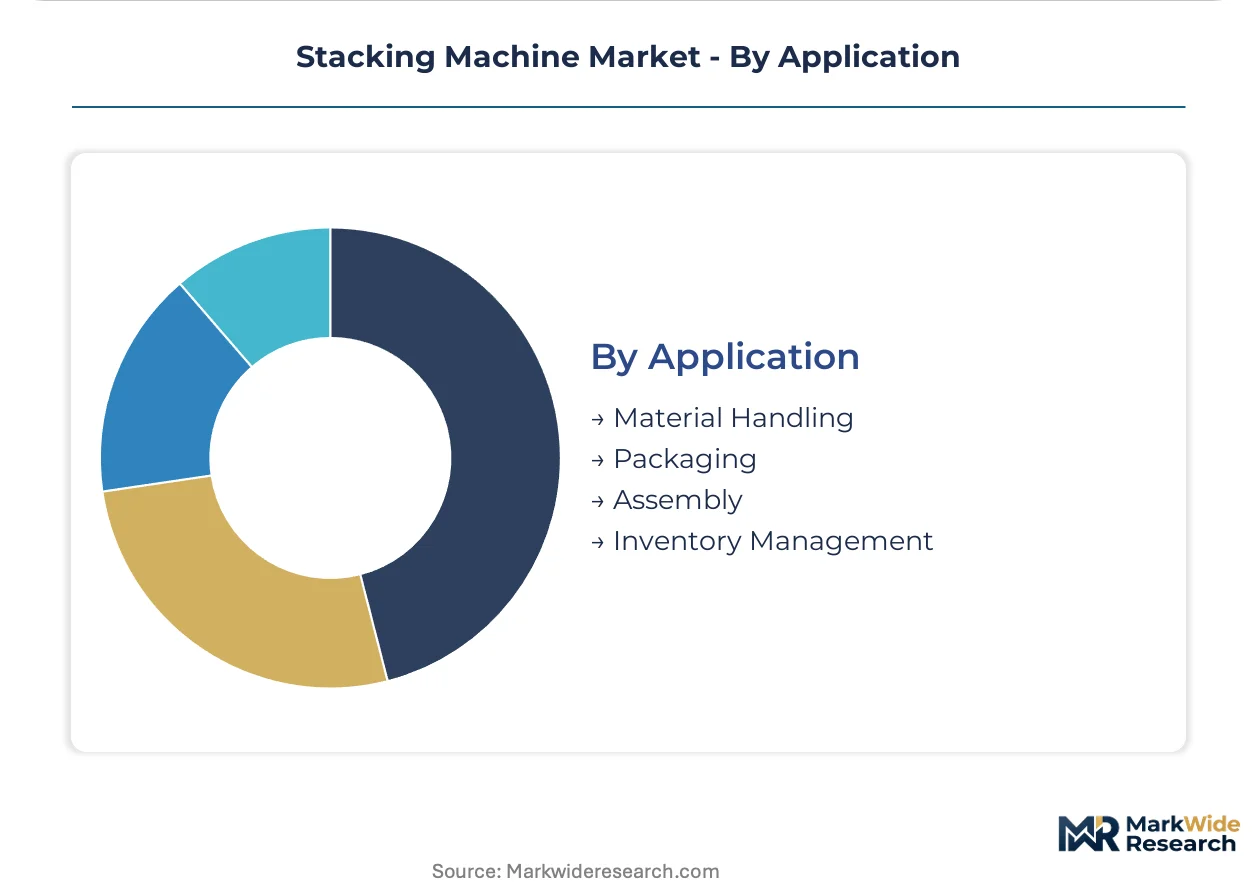
- Material Handling:Horizontal transport combined with vertical positioning constitutes the core stacking machine function across all facility types. High-throughput distribution centers in Shenzhen and Guangzhou specify automated guided variants to minimize labor headcount in pick-and-putaway workflows.
- Inventory Management:Cycle counting, slotting optimization, and real-time location tracking integration demand telematics-equipped fleet assets. Food and beverage distributors in the United States are deploying sensor-enabled stackers to satisfy OSHA electronic certification record requirements for powered industrial truck operations.
- Packaging:End-of-line palletization and stretch-wrapping integration requires precision positioning at conveyor interfaces.
- Assembly:Production-line feeding with sequenced component delivery operates on tightly coupled takt-time synchronization.
Material Handling absorbs the majority of unit shipments, though Inventory Management is climbing the fastest as warehouse management system integration becomes standard procurement criteria.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment pricing power tilts toward German manufacturers commanding premium positioning, while Chinese producers compete on volume economics in coastal logistics corridors. This asymmetry shapes procurement patterns across warehouse fleets and distribution networks worldwide.
Germany
Industrial machinery heritage and precision engineering standards anchor domestic demand for high-specification automated stackers. CE marking requirements under the EU Machinery Directive enforce rigorous safety validation protocols that favor established domestic suppliers. The Rhine-Alpine logistics corridor, stretching from Rotterdam through Cologne to Milan, concentrates fleet procurement decisions for European third-party distribution operators.
United States
OSHA workplace safety mandates tighten operator certification documentation requirements, accelerating fleet turnover toward telematics-equipped electric units. Food and beverage distribution centers in high-traffic loading dock environments respond fastest to liability exposure concerns. The Midwest manufacturing belt, spanning Illinois, Michigan, and Ohio, sustains dense networks of material handling equipment dealers and service providers.
China
Municipal air quality enforcement in Shanghai and Shenzhen prohibits diesel equipment from bonded port zones, forcing immediate fleet swaps toward electric alternatives. MIIT industrial policy prioritizes domestic battery supply chain development for material handling applications. The Yangtze River Delta manufacturing cluster, encompassing Suzhou, Wuxi, and Ningbo, generates concentrated demand for automated guided stacker deployments.
India
Third-party logistics penetration remains below comparable emerging markets, creating whitespace for automated guided stacker deployments in Mumbai and Delhi distribution corridors. BIS certification requirements for industrial machinery establish baseline safety thresholds for imported equipment. The National Capital Region warehousing belt, spanning Gurgaon, Noida, and Faridabad, attracts speculative development from e-commerce fulfillment operators.
Japan
METI energy efficiency standards for industrial equipment drive specification preferences toward regenerative braking systems and opportunity charging protocols. Aging warehouse workforce demographics accelerate interest in semi-autonomous stacker configurations that reduce physical operator strain. The Chubu region around Nagoya maintains dense concentrations of automotive parts distribution centers with synchronized just-in-time delivery requirements.
Stacking Machine Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying battery packs, drive systems, and sensor arrays. The vendor base organizes around three strategic archetypes: diversified industrial conglomerates with captive material handling divisions, pure-play warehouse equipment specialists, and emerging automation platform vendors crossing over from robotics. Consolidation pressure intensifies as fleet operators consolidate procurement across multi-facility networks, favoring suppliers with broad geographic service coverage and standardized maintenance protocols.
Among diversified industrial groups, Toyota Industries Corporation exemplifies the captive technology model through in-house electric drive system production. Jungheinrich AG occupies a position representing European engineering-intensive specialization, while Kion Group anchors the scale-driven consolidation archetype through broad distribution network coverage. These three patterns illustrate how competitive positioning stratifies across technology control, regional density, and operational scale vectors.
| Leading Market Players |
|---|
| Toyota Industries Corporation |
| Crown Equipment Corporation |
| Hyster-Yale Materials Handling Inc. |
| Jungheinrich AG |
| Kion Group |
| Mitsubishi Logisnext Co. Ltd. |
| Clark Material Handling Company |
| Doosan Corporation |
| Hangcha Group Co. Ltd. |
| Others |
Value Network & Pricing Analysis
The Yangtze River Delta manufacturing cluster around Suzhou and Ningbo concentrates electric drive system production, concentrating pricing power among battery pack integrators who supply downstream stacker assemblers. OEMs without captive cell production face margin compression as cathode chemistry costs transmit through tiered supplier contracts.
Pricing Analysis
The customization-premium spread separates configured-to-order automated stackers with ISO 3691-4 navigation certification from standard electric pedestrian units. Three-tier pricing structure across premium, standard, and economy levels tracks battery chemistry grade and telematics integration depth. Cost compression in the economy tier is intensifying because lead-acid substitution persists among price-sensitive small retailers. Fleet operators consolidating multi-facility procurement wield the weakest price sensitivity, while independent warehouse operators in Southern Europe exhibit acute cost consciousness.
Supply Chain Analysis
Extended payment terms from 60 to 90 days now anchor supplier-financing arrangements between Taiwanese motor control chip foundries and German drive system integrators. Component sourcing draws from China for lithium-ion cells, South Korea for power semiconductors, and Germany for precision hydraulic assemblies. Single-source vulnerability concentrates in Taiwanese foundry capacity for variable frequency drives. Distribution runs through authorized dealer networks in mature markets and direct-to-fleet procurement channels for national retail chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Machinery Directive autonomous navigation mandates are compressing product launch timelines and rewriting equipment specifications across warehouse fleets. This regulatory inflection accelerates technology substitution faster than historical replacement cycles.
For Market Incumbents: Harden certification pipelines against ISO 3691-4 validation delays by pre-funding extensive field testing programs. Lock in long-term offtake agreements for lithium and cobalt cathode chemistries before raw material volatility transmits to gross margins. Captive battery pack production represents the critical lever for cost control against emerging automation platform vendors. For New Entrants and Emerging Players: Mid-market third-party logistics operators in India represent the most penetrable entry point, given automation underinvestment relative to comparable emerging markets. Outcome-based fleet availability contracts offer a service-first go-to-market angle that bypasses capital purchase committee resistance. Automated guided stacker deployments in Mumbai and Delhi distribution corridors face limited incumbent saturation. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors battery chemistry specialists with established automotive supply relationships seeking industrial diversification. The five-to-ten year viability window rewards upstream control over cathode material processing rather than downstream equipment assembly. Watch MIIT industrial policy shifts on domestic battery supply chain development as the decisive inflection signal for competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Cell Production | Captive lithium-ion supply insulates Jungheinrich and Toyota Industries from cobalt price volatility transmitted through Korean cathode suppliers. |
| ISO 3691-4 Certification Pre-Investment | Early safety validation funding compresses product launch timelines for sensor-fusion navigation systems ahead of EU Machinery Directive enforcement. |
| Direct-to-Fleet Sales Channel Establishment | Bypassing regional dealers captures procurement consolidation among North American grocery distribution networks spanning fifty-plus facilities. |
| Outcome-Based Fleet Availability Contracts | Uptime guarantee models shift revenue toward predictive maintenance subscriptions and displace capital purchase decisions in logistics end-markets. |
| EU Green Deal Retrofit Incentive Capture | Italian and Spanish national recovery fund subsidies lower customer acquisition costs for diesel-to-electric conversion equipment. |
Research Methodology
Operator-level perspectives from warehouse fleet managers, maintenance directors, OEM procurement teams, and aftermarket service heads anchored the qualitative base. Primary interviews combined with secondary validation from customs trade data, SEC 10-K filings, MIIT industrial policy disclosures, and EU Machinery Directive implementation notices. Bottom-up equipment shipment analysis and top-down logistics capital expenditure triangulation generated volume and value estimates.
Scenario-bracketing around lithium price volatility, semiconductor lead time extension, and autonomous navigation certification delays shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include automation level, powertrain technology, end-use intensity, and regional regulatory cluster. CAGRs derived from equipment replacement cycle compression and fleet electrification penetration curves incorporated opportunity charging infrastructure deployment rates and bonded port zone enforcement timelines.
Practitioners should monitor battery chemistry regulation revisions and autonomous navigation certification protocol updates for early signals of specification shifts. Forecasts reflect assumptions on EU Machinery Directive enforcement consistency and MIIT domestic supply chain prioritization. Macroeconomic contraction in logistics end-markets, regulatory restriction relaxation, or solid-state battery commercialization would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
North America Printing Machinery Market
Packaging Machinery
Face Mask Machines Market
Packaging Machinery
Tray Packing Machine Market
Packaging Machinery
Candy Wrapping Machine Market
Packaging Machinery
Pallet Drum Filler Capper Market
Packaging Machinery
Lidding Machines Market
Packaging Machinery
Capping Machine Market
Packaging Machinery
Aseptic Filling Machines Market
Packaging Machinery
Foil Embossing Machine Market
Packaging Machinery
Flow Wrap Machines Market
Packaging Machinery
Tube Filling Machine Market
Packaging Machinery
Pouch Sealing Machine Market
Packaging Machinery
Bundling Machine Market
Packaging Machinery
Global Form Fill Seal Machines Market
Packaging Machinery
Package Closing Machines Market
Packaging Machinery
Bubble Wrap Machine Market