
 Case Packaging Machinery Market | 2026-2036
Case Packaging Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Case Packaging Machinery Market Outlook
Germany is reconfiguring European case packaging machinery supply dynamics through precision-engineering clusters in Baden-Württemberg and Bavaria. Syntegon Technology GmbH leverages its Stuttgart engineering base to sustain leadership in aseptic case packing systems for dairy and beverage clients. KHS Group anchors its Dortmund operations around high-speed rotary case packers for carbonated soft drink bottlers. Douglas Machine Inc. competes from its Alexandria, Minnesota headquarters with modular horizontal case packer architectures serving North American frozen food processors.
Case packaging machinery encompasses equipment that erects, loads, and seals corrugated containers with product arrays at speeds typically ranging from 10 to 70 cases per minute depending on configuration and payload. These systems employ servo-driven pick-and-place mechanisms, vacuum gripper arrays, or robotic arms to transfer bottles, cartons, pouches, or trays into RSC or HSC corrugated formats for palletized distribution. Horizontal case packers dominate installed base volumes across mature food and beverage operations where legacy line layouts constrain vertical integration, while robotic automation represents the fastest-expanding technology segment as pharmaceutical contract packers retrofit lines for batch-size flexibility and serialization compliance. Mechanical automation retains margin pools in emerging market beverage bottling where total cost of ownership constraints favor pneumatic pusher-bar systems over multi-axis robot cells.
FDA cGMP guidelines and EU MDR traceability mandates compel pharmaceutical end users to specify case packers with integrated vision verification and aggregated serial number printing, elevating equipment specification thresholds. China's SAMR enforces GB/T packaging machinery safety standards that require emergency stop architectures and interlocked guard panels, shaping design requirements for suppliers serving domestic food processors. Stakeholders must monitor regulatory divergence between FDA validation protocols and EU AI Act risk classifications as machine-learning-based defect detection migrates from pilot installations to production-critical case packing lines.
Market Dynamics
Robotic case packing architectures are compressing mechanical automation's installed base dominance as pharmaceutical contract packers prioritize batch-size agility over pneumatic throughput maximization.
Growth Catalysts
- EU Green Deal packaging waste targets:German beverage bottlers are retrofitting lines with automated case erectors and sealers to meet circular economy mandates for reduced corrugated consumption per shipped unit.
- Servo-driven pick-and-place mechanisms:Food processors in China's eastern manufacturing corridor specify these systems for 40-70 case-per-minute throughput on export-bound frozen protein lines.
- Aseptic dairy packaging:Extended shelf-life beverage demand in North American and European markets requires case packers with HEPA-filtered enclosures and sterile transfer corridors.
Market Restraints
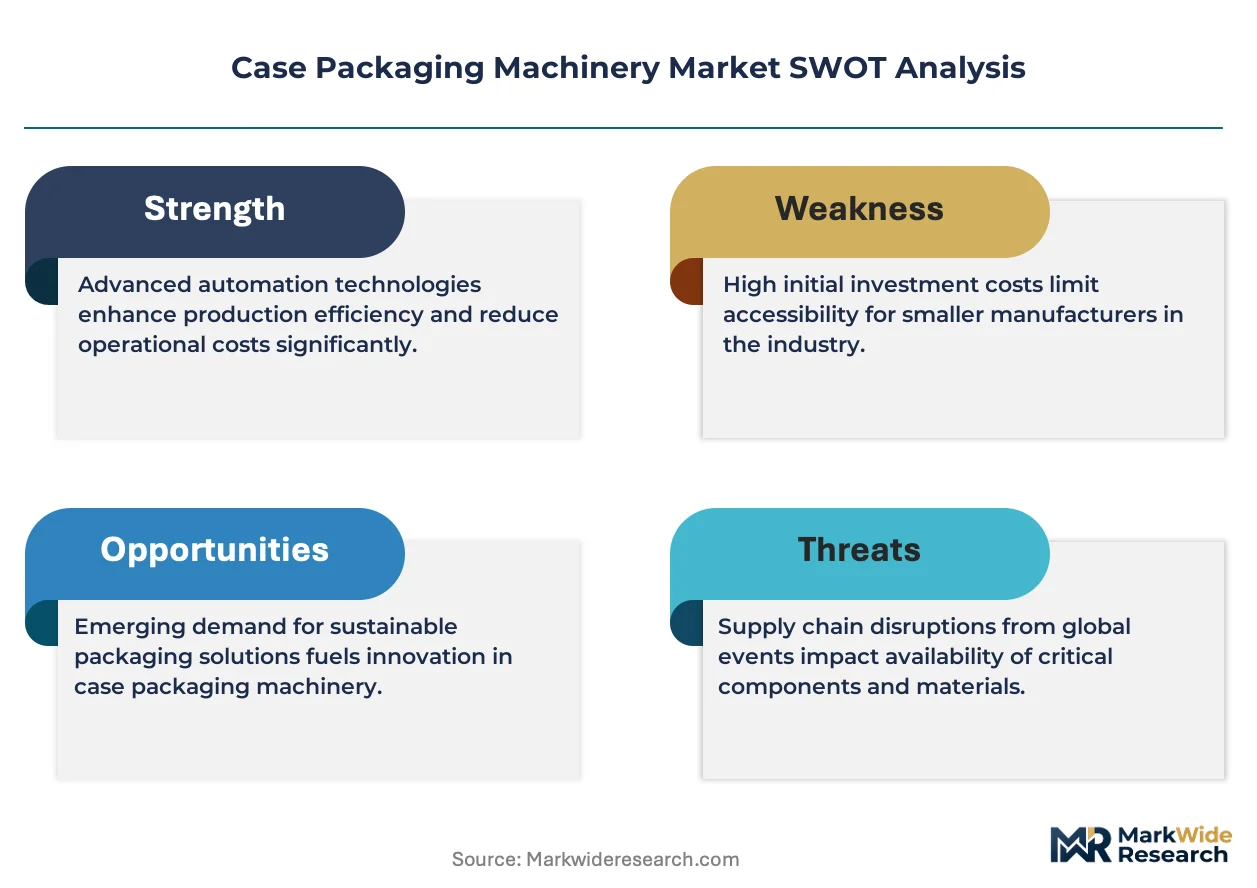
- Stainless steel and servo motor cost volatility:Input price swings for 304-grade steel and precision motion components compress OEM margin pools on fixed-price municipal water bottling contracts.
- Baden-Württemberg precision-engineering cluster concentration:German case packer component sourcing depends on a 150-kilometer radius around Stuttgart for high-tolerance gearbox and vacuum gripper fabrication.
- Pneumatic system substitution threat:Mechanical pusher-bar architectures retain total-cost-of-ownership advantages in emerging market beverage bottling where compressed air infrastructure already exists.
Strategic Opportunities
- India's PLI scheme for food processing:Central government production-linked incentives for cold chain infrastructure are accelerating case packer procurement among domestic dairy cooperatives and spice exporters.
- Serialization-aggregation convergence:Pharmaceutical packers in the EU and US are specifying case packers with integrated track-and-trace modules to satisfy EU MDR and FDA cGMP mandates in single capital deployments.
- Machine-learning defect detection:Vision systems trained on corrugated board integrity and product array verification are virtualizing manual QC stations on high-speed beverage lines.
Industry Challenges
- Multi-axis robot programming expertise scarcity:System integrators face 6-9 month recruitment cycles for technicians capable of calibrating delta robots on pharmaceutical serialization lines.
- FDA validation protocol complexity:Pharmaceutical end users require 12-18 month equipment qualification timelines that compress vendor cash conversion cycles and elevate working capital requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Case Packaging Machinery Market |
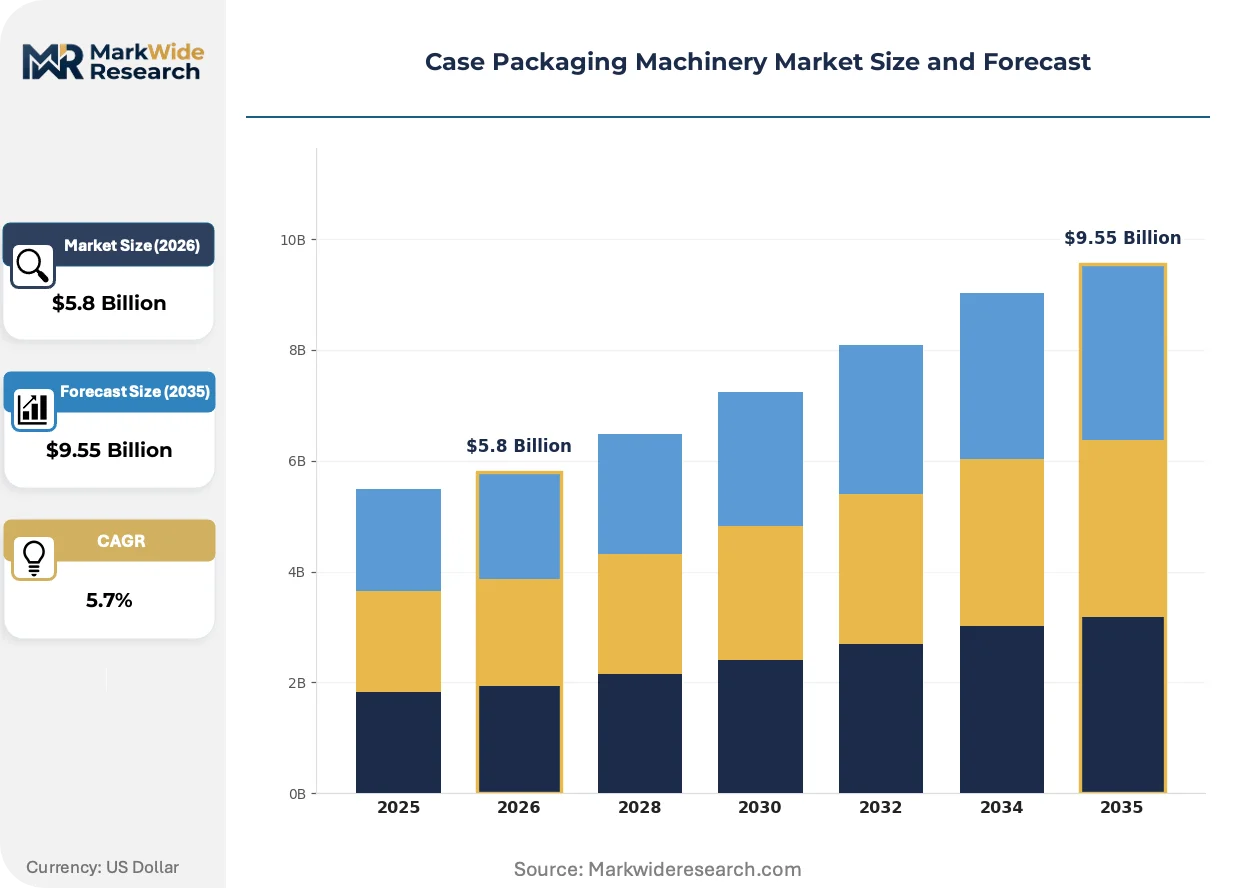
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Horizontal Case Packers, Vertical Case Packers, Automated Case Packers, Semi-Automated Case Packers Technology: Robotic Automation, Mechanical Automation, Pneumatic Systems, Integrated Software Solutions End User: Food & Beverage, Pharmaceuticals, Consumer Goods, Electronics Distribution Channel: Direct Sales, Distributors, Online Platforms, Trade Shows |
| Companies Covered | Douglas Machine Inc., Syntegon Technology GmbH, KHS Group, Tetra Laval Group, ROVEMA GmbH, Cama, Marchesini Group, Coesia S.p.A., I.M.A. Industria Macchine Automatiche S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Case Packaging Machinery Market Strategic Shifts
Digital twin environments are collapsing case packer commissioning timelines from weeks to days while regulatory mandates force hardware-software integration at specification stages previously handled post-installation.
Digital twin software for case packer mechanical verification is virtualizing physical prototyping cycles. OEM engineering teams in Germany and the US deploy these environments to validate servo motion profiles and vacuum gripper trajectories before metal fabrication. Pharmaceutical contract packers are the fastest adopters, using virtual commissioning to compress FDA validation documentation preparation.
EU AI Act risk classifications are reshaping machine-learning deployment on production-critical lines. Case packer suppliers must now document algorithmic decision pathways for vision-based defect detection systems used in pharmaceutical aggregation. This elevates engineering documentation burdens but creates specification advantages for vendors with pre-validated AI architectures.
After-sales service unbundling is fragmenting traditional maintenance contract structures. North American frozen food processors now procure case packer hardware, spare parts, and technical support through separate vendor relationships rather than single-source OEM agreements. This compresses incumbent service revenue pools while opening entry points for third-party automation integrators.
Case Packaging Machinery Market Segmentation
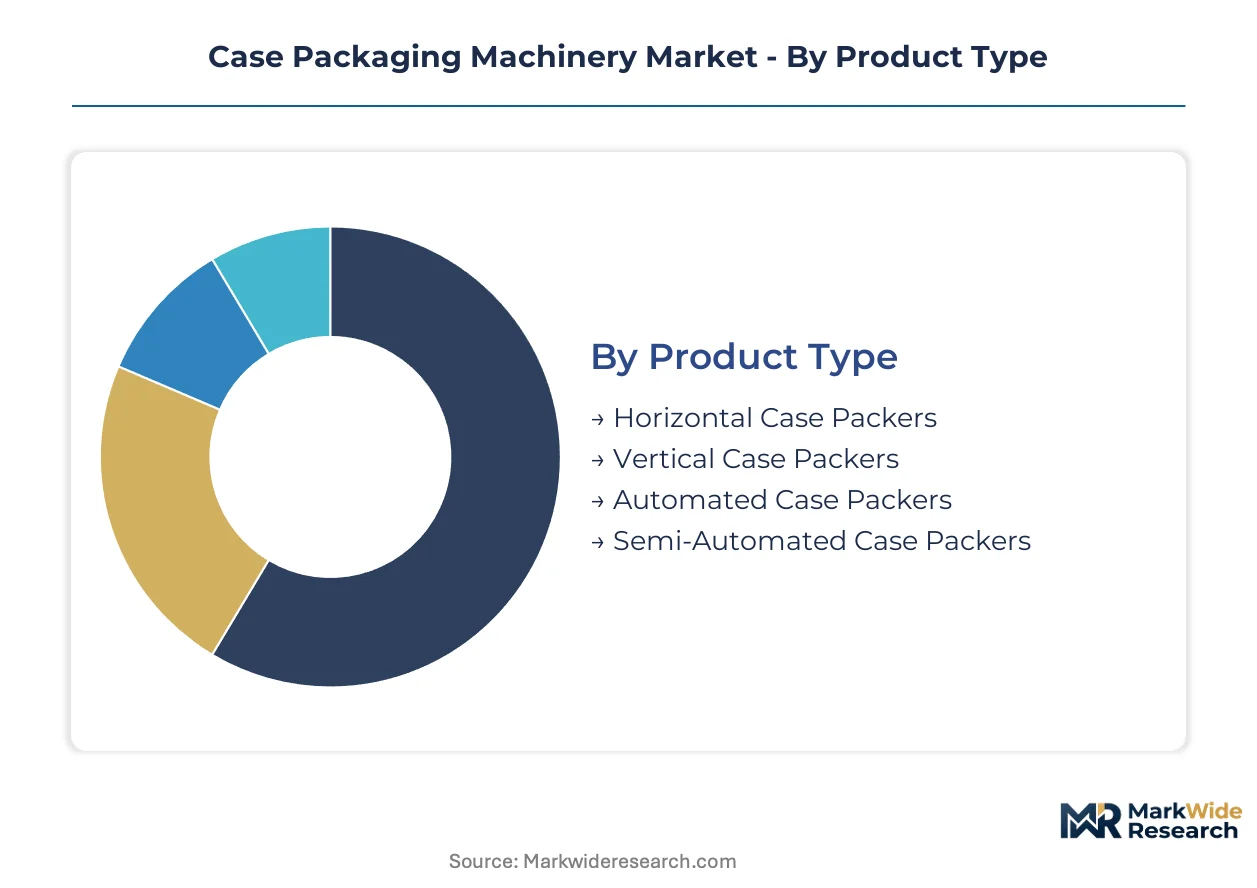
Case packaging machinery segmentation reveals how equipment specifications align with payload characteristics, throughput requirements, and regulatory environments across divergent end-use applications. Understanding these category boundaries enables procurement teams to match capital deployment with operational constraints and compliance mandates.
Product Type:
Horizontal configurations dominate legacy food processing lines where facility layouts constrain vertical integration, while robotic architectures gain traction in pharmaceutical serialization applications demanding batch flexibility.
- Horizontal Case Packers:These systems load products through side-entry mechanisms into corrugated containers at speeds typically reaching 40-70 cases per minute. German beverage bottlers in Baden-Württemberg specify these units for carbonated soft drink lines where existing plant footprints preclude vertical reconfiguration. EU Green Deal packaging waste targets drive retrofit demand for servo-driven horizontal units that optimize corrugated consumption per shipped unit.
- Vertical Case Packers:Top-loading architectures accommodate irregular product geometries and multi-pack configurations common in frozen protein and dairy applications. Chinese export-oriented food processors in the eastern manufacturing corridor deploy these systems for tray-packed seafood and poultry bound for North American retail chains. Compact vertical footprints suit greenfield facilities where ceiling height permits overhead infeed integration.
- Automated Case Packers:Fully integrated lines combine case erection, product loading, and sealing with minimal operator intervention. These systems serve high-volume pharmaceutical contract packers facing FDA cGMP validation timelines.
- Semi-Automated Case Packers:Operator-assisted loading stations bridge manual and fully automated operations for mid-scale dairy cooperatives and spice exporters in India's PLI-supported cold chain infrastructure.
Established volume favors Horizontal Case Packers; emerging adoption favors Automated Case Packers.
Technology:
Cost tier differentiation separates precision servo architectures from pneumatic alternatives, with software integration emerging as a margin expansion vector for OEMs serving regulated industries.
- Robotic Automation:Multi-axis delta and SCARA configurations enable rapid changeover between product formats without mechanical retooling. Pharmaceutical packers in the EU and US specify these systems to satisfy serialization-aggregation convergence requirements under EU MDR and FDA mandates. Vision-guided pick-and-place modules verify product array integrity before container sealing.
- Mechanical Automation:Cam-driven and servo-linked mechanical indexers deliver consistent throughput for standardized product formats at lower capital intensity. North American frozen food processors maintain extensive installed bases of these systems where product mix stability justifies fixed-motion architectures.
- Pneumatic Systems:Compressed air-driven pusher bars and vacuum circuits retain total-cost-of-ownership advantages in emerging market beverage bottling where infrastructure already exists.
- Integrated Software Solutions:Digital twin environments and machine-learning defect detection modules compress commissioning timelines and virtualize quality control stations.
Mechanical Automation retains the largest installed base; Robotic Automation exhibits the steepest expansion trajectory.
End User:
Application maturity varies sharply across end-use segments, with pharmaceutical specifications elevating engineering thresholds through validation protocols and traceability mandates.
- Food & Beverage:Dairy, bottled water, and carbonated soft drink bottlers generate the highest equipment procurement volumes globally. Aseptic packaging requirements for extended shelf-life beverages demand HEPA-filtered case packer enclosures. German precision-engineering clusters supply servo-driven systems meeting EU circular economy targets for reduced packaging material intensity.
- Pharmaceuticals:Contract packers and finished dosage manufacturers specify case packers with integrated track-and-trace modules, vision verification, and aggregated serial number printing. FDA validation protocols and EU MDR traceability mandates extend equipment qualification timelines to 12-18 months.
- Consumer Goods:Personal care and household product packers prioritize changeover speed for seasonal SKU proliferation.
- Electronics:E-commerce fulfillment centers specify gentle-handling case packers for fragile consumer electronics with anti-static and shock-absorbing features.
Food & Beverage commands established procurement volumes; Pharmaceuticals drives specification complexity and margin expansion.
Distribution Channel:
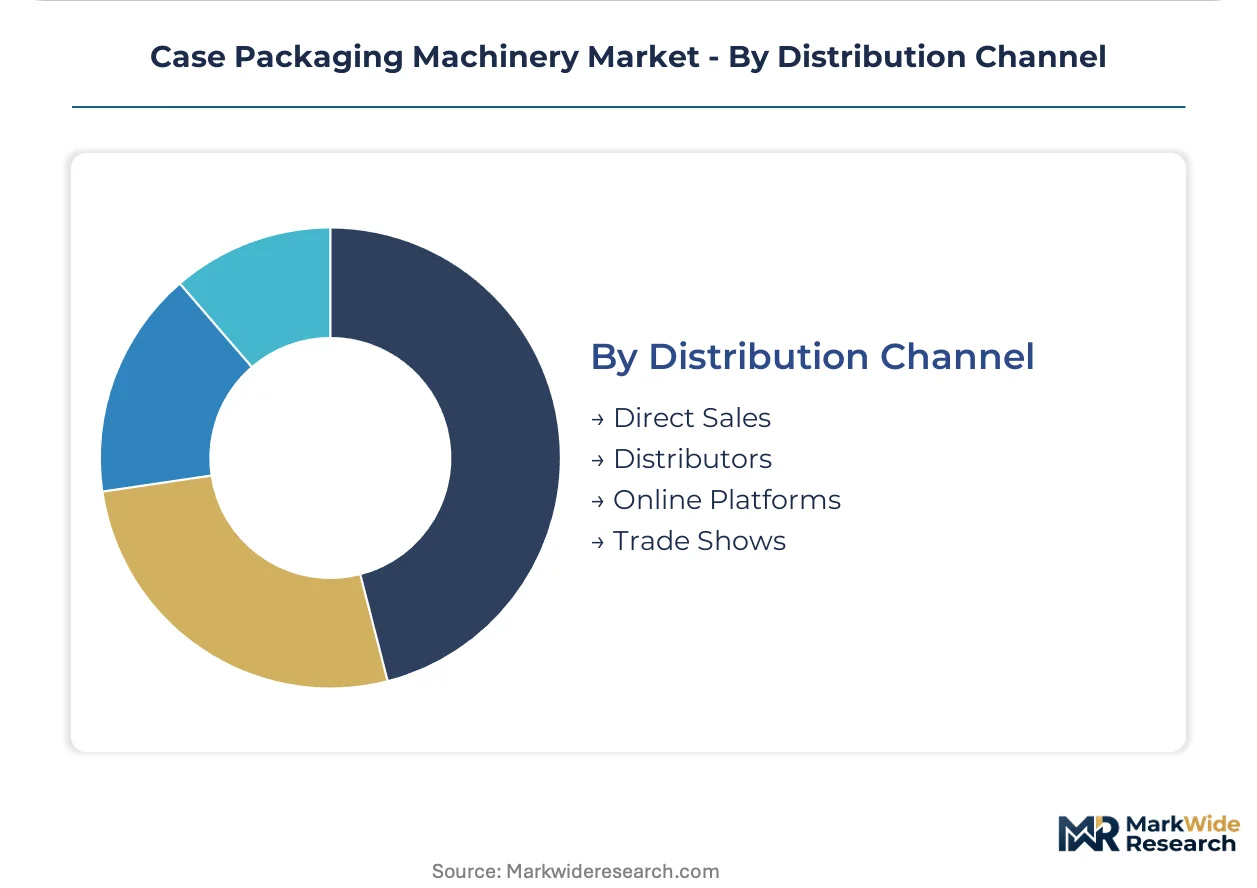
Customer type and transaction scale determine channel selection, with large beverage bottlers favoring direct OEM relationships while mid-tier processors leverage distributor networks for localized service support.
- Direct Sales:OEM engineering teams engage directly with multinational beverage bottlers and pharmaceutical manufacturers for customized line integration. Syntegon Technology and KHS Group deploy Stuttgart and Dortmund-based sales engineers for complex aseptic and high-speed rotary system specifications.
- Distributors:Regional automation integrators provide localized installation, commissioning, and aftermarket support for mid-scale food processors. India's domestic dairy cooperatives access case packer procurement through distributor networks serving PLI scheme beneficiaries.
- Online Platforms:Standardized semi-automated units and spare parts move through B2B industrial marketplaces for price-transparent procurement.
- Trade Shows:Interpack, Pack Expo, and Propak events remain critical venues for demonstrating digital twin commissioning and machine-learning defect detection capabilities to pharmaceutical contract packers.
Direct Sales dominates high-complexity transactions; Distributors capture mid-market volume expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. German beverage bottlers prioritize corrugated optimization under circular economy mandates, while Chinese export processors maximize throughput for frozen protein shipments. Indian dairy cooperatives balance automation ambition against capital constraints.
United States
Frozen food processors in Minnesota and Wisconsin drive horizontal case packer procurement for legacy line retrofits. FDA cGMP guidelines for pharmaceutical contract packers extend equipment qualification timelines to 12-18 months. The Alexandria, Minnesota precision-engineering cluster anchors North American supply for modular packaging architectures.
Germany
Carbonated soft drink bottlers in North Rhine-Westphalia specify high-speed rotary systems for existing plant footprints. EU Green Deal packaging waste targets compel corrugated consumption reductions per shipped unit. The Stuttgart-Dortmund engineering corridor concentrates servo-driven aseptic case packing capability for dairy and beverage clients.
China
Export-oriented food processors in the eastern manufacturing corridor deploy vertical case packers for tray-packed seafood and poultry bound for North American retail. SAMR enforces GB/T packaging machinery safety standards requiring emergency stop architectures and interlocked guard panels. The Yangtze River Delta cluster dominates domestic procurement for cold chain infrastructure.
India
Domestic dairy cooperatives and spice exporters accelerate case packer procurement under central government PLI scheme incentives for food processing cold chains. FSSAI packaging regulations shape equipment specifications for hygienic design in dairy applications. Gujarat and Maharashtra industrial corridors concentrate mid-scale automation deployments for emerging market bottling operations.
Japan
Pharmaceutical dosage manufacturers specify case packers with integrated track-and-trace modules for METI-supported serialization compliance. PMDA quality guidelines elevate vision verification requirements for aggregated serial number printing. The Kanto region around Tokyo anchors precision automation engineering for batch-flexible robotic architectures.
Case Packaging Machinery Market Competitive Environment
Capability concentration sits with German precision-engineering specialists; scale advantage sits with diversified multinational packaging groups. The vendor base organizes into three functional tiers: Stuttgart-Dortmund corridor specialists commanding aseptic and high-speed rotary specifications, Italian and Swiss packaging conglomerates leveraging beverage and pharmaceutical platform breadth, and emerging Asian fabricators competing on total cost of ownership for standardized mechanical systems. Dominant competitive moves include geographic expansion through distributor network capture and technology licensing partnerships for digital twin commissioning capabilities.
Within the German specialist tier, Syntegon Technology GmbH and KHS Group occupy anchor positions representing precision-engineering concentration in Baden-Württemberg and North Rhine-Westphalia respectively. Among diversified packaging conglomerates, Tetra Laval Group exemplifies the multinational platform operator archetype spanning beverage, dairy, and pharmaceutical end uses. Douglas Machine Inc. represents the North American modular architecture specialist competing from Minnesota-based engineering operations. These three company types collectively illustrate how geographic clustering, end-use diversification, and product architecture specialization define competitive positioning in this machinery category.
| Leading Market Players |
|---|
| Douglas Machine Inc. |
| Syntegon Technology GmbH |
| KHS Group |
| Tetra Laval Group |
| ROVEMA GmbH |
| Cama |
| Marchesini Group |
| Coesia S.p.A. |
| I.M.A. Industria Macchine Automatiche S.p.A. |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in Baden-Württemberg precision-engineering clusters is elevating supplier pricing power for servo-driven motion components while compressing OEM margins on fixed-price municipal contracts. German beverage bottlers absorb premium pricing for corrugated-optimization systems as EU Green Deal mandates tighten, whereas emerging market processors face procurement delays when sourcing from the same Stuttgart-Dortmund corridor.
Pricing Analysis
Long-term offtake agreements dominate pharmaceutical case packer procurement, with FDA validation protocols extending contract durations to 18-24 months and embedding service bundles into capital outlays. Price differentiation rests on certification tier—CE-marked aseptic systems command 15-25% premiums over standard mechanical configurations—and after-sales service integration. Cost compression in pneumatic system tiers is intensifying because Brazilian and Indian beverage bottlers prioritize total cost of ownership over servo precision. Dairy cooperatives in India's PLI scheme exhibit highest price sensitivity; pharmaceutical contract packers in Japan and Germany show least sensitivity due to regulatory compliance imperatives.
Supply Chain Analysis
Tariff exposure between Germany and China dominates supply chain risk planning for case packer OEMs sourcing 304-grade stainless steel and precision gearboxes. Component fabrication draws from Germany, Italy, and Japan for high-tolerance motion systems; China and South Korea supply mid-tier servo motors and control electronics. Single-source vulnerability concentrates in Stuttgart-area vacuum gripper suppliers serving aseptic dairy lines. Distribution runs through direct OEM engineering teams for multinational beverage bottlers, with regional automation integrators capturing mid-scale food processor procurement in India and Southeast Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Case packaging machinery sits in early-cycle expansion as pharmaceutical serialization mandates and EU circular economy targets simultaneously penetrate previously mechanical-dominated installed bases. Robotic automation adoption in contract packing represents the clearest penetration tailwind.
For Market Incumbents: Pre-empt margin erosion in pneumatic system tiers by acquiring Indian and Brazilian distributor networks before regional fabricators consolidate channel control. Anchor defensive positioning in aseptic dairy specifications through backward integration into HEPA filtration subsystem production, countering Syntegon Technology's captive supply advantages in Baden-Württemberg. Certification investment in EU AI Act pre-validated vision architectures creates specification lock-in for pharmaceutical aggregation lines. For New Entrants and Emerging Players: India's domestic dairy cooperatives under PLI scheme coverage represent the most penetrable white-space target, with FSSAI hygienic design requirements still fluid enough to permit specification disruption. Semi-automated case packer procurement for spice exporters in Gujarat and Maharashtra industrial corridors offers second entry vector. Go-to-market execution should leverage distributor relationships over direct sales to compress customer acquisition cycles against established German engineering brands. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across robotic automation sub-segments as multi-axis programming expertise scarcity elevates R&D and service infrastructure requirements. Long-term viability favors acquisition targets with validated digital twin commissioning capabilities and pre-established FDA documentation libraries. The signal to watch is pharmaceutical contract packer consolidation—serial acquirers in this segment will prioritize vendors with compressed qualification timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Commissioning Capability | Virtual validation environments collapse FDA documentation preparation timelines for pharmaceutical contract packers. |
| Backward Integration into Motion Components | In-house servo motor and gearbox production insulates margins from Stuttgart-cluster supply constraints. |
| EU AI Act Pre-Validation Investment | Documented algorithmic decision pathways create specification advantages in pharmaceutical vision-system procurement. |
| Distributor Network Capture in India | PLI scheme beneficiaries in Gujarat and Maharashtra require localized installation and aftermarket support. |
| Aseptic Enclosure Technology Licensing | HEPA-filtered transfer corridor IP unlocks extended shelf-life dairy and beverage segments. |
Study Parameters
Operator-level perspectives from plant engineers at beverage bottlers, pharmaceutical contract packers, and frozen food processors anchored the qualitative base for this analysis. Primary interviews with OEM sales engineers, aftermarket service directors, and regional automation integrators combined with secondary validation from SEC 10-K filings, EU MDR guidance documents, and SAMR GB/T standard releases. Customs data on packaging machinery trade flows and FSSAI regulatory circulars provided quantitative triangulation. Bottom-up equipment procurement modeling and top-down market sizing converged on segment-level estimates.
Scenario-bracketing around EU AI Act implementation timelines and PLI scheme extension probabilities framed the projection horizon. Segmentation dimensions modeled include product architecture (horizontal, vertical, robotic), automation technology tier, end-use regulatory intensity (FDA, EMA, SAMR), and regional manufacturing cluster concentration. CAGRs derived from equipment replacement cycle analysis and greenfield capacity addition patterns across the analysis window. Pharmaceutical serialization compliance deadlines and circular economy packaging waste targets served as demand-pull inputs.
Practitioners should monitor stainless steel input cost volatility, FDA validation protocol revisions, and EU AI Act enforcement granularity for early signals requiring forecast adjustment. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Aerosol Filling Machines Market
Packaging Machinery
Vertical Bagging Machine Market
Packaging Machinery
Volumetric Filling Machines Market
Packaging Machinery
Automatic Filling Machine Market
Packaging Machinery
Injectable Liquid Filling Machines Market
Packaging Machinery
Capsule Filling Machines Market
Packaging Machinery
Stick Pack Packaging Machine Market
Packaging Machinery
Slitter Rewinder Machines Market
Packaging Machinery
Form-Fill-Seal (FFS) Packaging Machine Market
Packaging Machinery
Tube Sealing Machines Market
Packaging Machinery
High Vacuum Filling Machine Market
Packaging Machinery
Horizontal Strapping Machine Market
Packaging Machinery
Aseptic Filling Machines Market
Packaging Machinery
Corrugated Box Making Machine Market
Packaging Machinery
EPS Pre-Expander Machines Market
Packaging Machinery
Twist Tie Machines Market