
 Global Specialty Crop Market | 2026-2036
Global Specialty Crop Market Size, Share, and Industry Trends Forecast 2026-2036
Global Specialty Crop Market Foresight
GLOBALG.A.P. certification is unwinding competitive access across the specialty crop value chain, disqualifying smaller growers from European retail supply pools. Olam International leverages integrated origination networks across multiple continents to sustain volume security for nut and spice buyers. United Natural Foods anchors North American distribution through direct-to-retailer channel control. Phoenix Global DMCC competes in Middle Eastern re-export hubs where phytosanitary documentation determines clearance speed.
Specialty crops comprise botanical products cultivated for distinctive flavor profiles, nutritional density, or therapeutic properties rather than commodity caloric output, typically requiring specific soil chemistry, controlled water stress, or defined thermal accumulations to express target compounds. These crops serve pharmaceutical formulators seeking standardized active extracts, cosmetics laboratories requiring cold-pressed carrier oils, and nutraceutical brands pursuing clean-label ingredient narratives. Nuts and exotic fruits command premium positioning in food processing channels where processors prioritize fat profile consistency and sugar-acid ratios for clean-label product lines. Organic farming methods attract margin concentration as certification premiums persist across European and North American wholesale markets. Hydroponics and aquaponics systems are expanding fastest in controlled-environment production of herbs and medicinal plants where water-use efficiency and year-round harvest cycles offset capital intensity.
FDA oversight of dietary supplement labeling under DSHEA shapes ingredient documentation requirements for medicinal plant and nutraceutical crop suppliers entering United States commerce. EMA herbal monographs and EU Novel Food catalog entries govern market access for exotic fruit and spice extracts across European member states, while India's FSSAI and Spices Board standards regulate export quality for cardamom, turmeric, and black pepper shipments. India's PLI scheme for food processing infrastructure is redirecting capital toward integrated spice parks and cold chain consolidation. Stakeholders must monitor divergence between Codex Alimentarius guidelines and emerging national maximum residue limits for botanical pesticides, as compliance fragmentation threatens cross-border shipment economics.
Market Dynamics
Organic certification mandates under USDA National Organic Program and EU Organic Regulation are bifurcating supply eligibility, forcing processors to maintain dual-sourcing networks while smaller growers face exclusion from premium retail channels.
Growth Catalysts
- Nutraceutical Formulation Demand:Pharmaceutical and wellness brands are intensifying procurement of standardized botanical extracts for clean-label supplement lines, pulling volume through contract farming arrangements.
- India's PLI Scheme for Food Processing:Capital subsidies for integrated spice parks and cold chain infrastructure are consolidating origination capacity in Kerala and Gujarat processing clusters.
- Hydroponics Technology Adoption:Controlled-environment agriculture systems are enabling year-round herb and medicinal plant production in water-stressed regions, offsetting seasonal supply volatility.
Market Restraints
- Phytosanitary Documentation Burden:Divergence between Codex Alimentarius guidelines and national maximum residue limits for botanical pesticides is fragmenting compliance economics across export shipments.
- GLOBALG.A.P. Certification Barriers:Third-party audit costs and documentation requirements are disqualifying smallholder growers from European retail supply pools, concentrating origination among capitalized operators.
- Input Cost Volatility:Specialized fertilizer formulations and biological pest control agents required for organic cultivation command pricing premiums that compress farm-level margins during commodity price cycles.
Strategic Opportunities
- EMA Herbal Monograph Alignment:European regulatory harmonization for traditional botanical extracts is opening standardized pathways for Ayurvedic and Traditional Chinese Medicine ingredient commercialization.
- Aquaponics System Convergence:Integration of fish waste nutrient cycling with medicinal plant cultivation is reducing input costs for omega-3 rich nut and seed oil processors seeking closed-loop narratives.
- Middle Eastern Re-Export Hub Penetration:Dubai and Jebel Ali free zones offer phytosanitary clearance speed advantages for Indian and Southeast Asian spice shipments entering African and Levantine markets.
Industry Challenges
- Active Compound Standardization Expertise Gap:Analytical chemistry capabilities for batch-to-batch consistency in therapeutic plant extracts remain scarce outside established pharmaceutical supply regions.
- DSHEA Documentation Complexity:FDA dietary supplement labeling requirements demand extensive botanical identity testing and adverse event reporting infrastructure that mid-tier suppliers struggle to maintain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Specialty Crop Market |
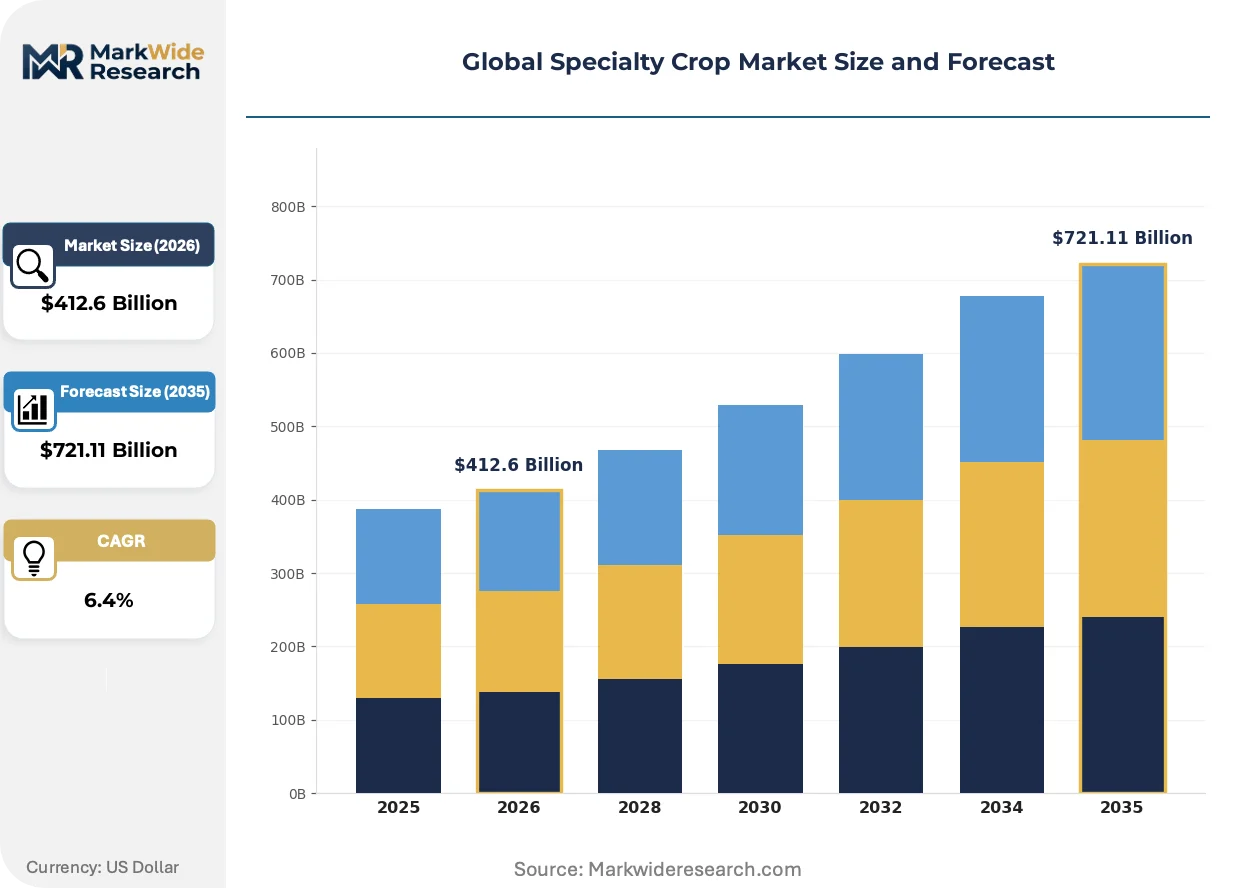
| Market Size in 2026 | $412.6 Billion |
| Market Size in 2035 | $721.11 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Crop Type: Herbs, Spices, Nuts, Exotic Fruits, Medicinal Plants, Flowers Production Method: Organic Farming, Integrated Pest Management, Hydroponics, Aquaponics, Conventional Agriculture End Use: Food Processing, Pharmaceuticals, Cosmetics, Nutraceuticals, Floral Industry Distribution Channel: Direct Sales, Wholesale Markets, Online Retail, Export, Agro-Processing Units |
| Companies Covered | Olam International, United Natural Foods, Specialty Crop Company, Golden Peanut and Tree Nuts, Phoenix Global DMCC, SunWest Foods, Diamond Fruit, SVZ Industrial Fruit & Vegetable, Lamex Food Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Specialty Crop Market Shifts & Advancements
Biotechnology and precision agriculture tools are compressing breeding cycles and extraction yields while regulatory data requirements and buyer consolidation are reshaping how specialty crops move from farm to formulation.
CRISPR-assisted breeding platforms are accelerating development of chemotype-stable medicinal plant varieties with elevated target compound expression. Seed companies and botanical extract houses are deploying these tools to reduce the acreage required for pharmaceutical-grade raw material production. Gene editing is miniaturizing the land footprint needed for high-value therapeutic crop cultivation, enabling vertical farm integration.
EU Novel Food catalog expansion is creating structured entry pathways for exotic fruit and spice extracts previously restricted from European commerce. EFSA safety assessment protocols now govern accelerated approval timelines for superfruit concentrates and adaptogenic botanicals. Functional beverage formulators in Germany and the Netherlands are reconfiguring product development pipelines to align with these regulatory windows.
Direct-to-manufacturer contracting is displacing traditional spot-market procurement for high-volume spice and nut buyers. Food processors and nutraceutical brands are establishing multi-year offtake agreements with origination networks, bypassing commodity auction systems. This pattern concentrates most visibly in Indian cardamom and Vietnamese cashew supply chains, where processor-owned curing facilities are capturing margin previously held by trading intermediaries.
Global Specialty Crop Market Segmentation
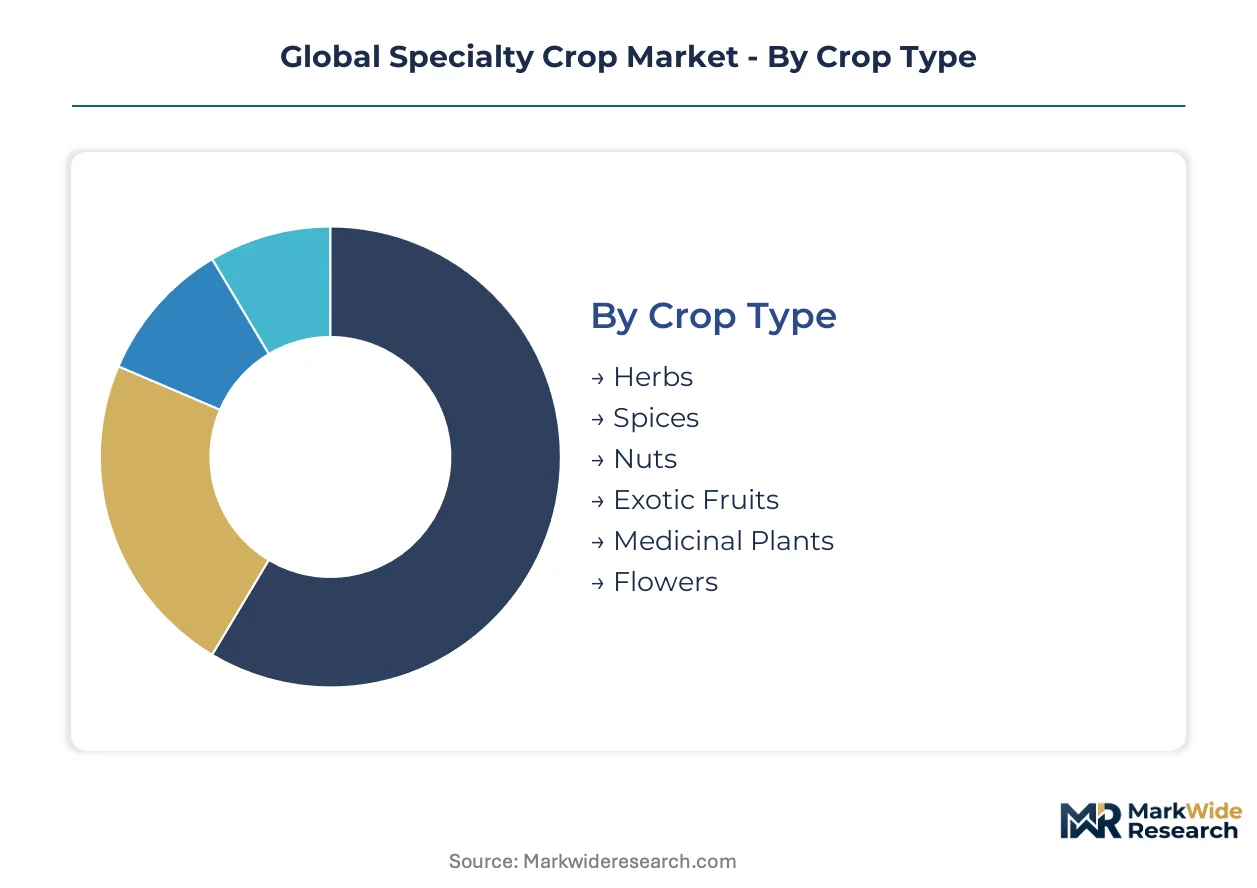
Segmentation in specialty crops determines compliance pathways, margin capture, and buyer access. Crop type dictates regulatory jurisdiction while production method locks in certification tier and pricing power. Distribution channel selection separates commodity traders from integrated formulators seeking traceability.
Crop Type:
Spices and nuts dominate export-led procurement from India and Vietnam, while medicinal plants and flowers concentrate in domestic pharmaceutical and floral supply chains across Germany and the Netherlands.
- Herbs:Leafy botanicals including basil, cilantro, and oregano cultivated for volatile oil content and flavor intensity. Fresh herb demand concentrates in European retail chains where shelf-life specifications favor local greenhouse production over transoceanic shipment.
- Spices:Dried seed, bark, and rhizome products—cardamom, turmeric, black pepper—standardized for curcumin, piperine, and essential oil percentages. Kerala and Gujarat processing clusters in India anchor origination for nutraceutical extractors seeking phytochemical consistency.
- Nuts:Tree nuts and oilseeds including almonds, cashews, and macadamias selected for fat profile stability and aflatoxin compliance. Vietnamese cashew processors and California almond handlers compete on kernel grade uniformity and pasteurization documentation.
- Exotic Fruits:Dragon fruit, rambutan, and mangosteen cultivated for sugar-acid ratios and anthocyanin density. EU Novel Food catalog restrictions limit European penetration, concentrating demand in Middle Eastern and Southeast Asian fresh consumption channels.
- Medicinal Plants:Botanicals cultivated for standardized active extracts—ashwagandha, ginseng, echinacea—governed by pharmacopoeial monographs. Indian Ayurvedic suppliers and Chinese Traditional Medicine networks dominate upstream cultivation.
- Flowers:Ornamental and functional blooms including lavender, chamomile, and marigold for essential oil distillation and floral arrangements. Dutch auction systems and Kenyan highland farms split supply between fragrance houses and European retail floristry.
Spices command the established base. The steepest expansion runs through medicinal plants.
Production Method:
Cost tier stratification separates premium-certified organic and controlled-environment systems from conventional field production serving commodity processors.
- Organic Farming:USDA National Organic Program and EU Organic Regulation compliance prohibits synthetic inputs and mandates multi-year transition protocols. Certification premiums persist across European wholesale markets, attracting margin-focused growers in Italy and Spain.
- Integrated Pest Management:Biological and mechanical control protocols reducing chemical residue loads while maintaining yield targets. Indian spice exporters deploy IPM to meet Codex Alimentarius maximum residue limits for European retail access.
- Hydroponics:Soilless cultivation in nutrient solutions enabling year-round herb and leafy green production. Water-stressed regions in the Middle East and Australia adopt hydroponics to offset seasonal supply volatility and import dependence.
- Aquaponics:Closed-loop integration of fish waste nutrient cycling with medicinal plant cultivation. Omega-3 rich nut and seed oil processors in North America pursue aquaponics for clean-label narrative differentiation and input cost reduction.
- Conventional Agriculture:Field-based production with synthetic fertilizer and pesticide protocols serving commodity spice and nut processors. Volume security and lower unit costs defend position in bulk ingredient procurement contracts.
Conventional agriculture holds volume dominance. Controlled-environment systems are climbing the fastest.
End Use:
Application-driven specifications split supply chains between food-grade commodity handling and pharmaceutical-grade traceability requirements.
- Food Processing:Ingredient procurement for clean-label product lines emphasizing single-origin spice blends and cold-pressed nut oils. German and Dutch formulators prioritize fat profile consistency and microbial safety documentation.
- Pharmaceuticals:Active pharmaceutical ingredient extraction requiring batch-to-batch standardization and pharmacopoeial compliance. Indian and Chinese suppliers dominate upstream cultivation for global generic drug manufacturers.
- Cosmetics:Cold-pressed carrier oils and essential oils for skincare formulations. French and Swiss cosmetics laboratories drive demand for organic-certified lavender, rosehip, and argan with specified fatty acid profiles.
- Nutraceuticals:Standardized botanical extracts for dietary supplement lines governed by FDA DSHEA and EFSA health claim frameworks. Contract farming arrangements in India and Indonesia secure volume for wellness brand procurement.
- Floral Industry:Ornamental blooms and fragrance raw materials for retail floristry and perfume production. Dutch auction cooperatives and Colombian export farms coordinate supply for European luxury fragrance houses.
Food processing anchors volume demand. Nutraceuticals are gaining share fastest.
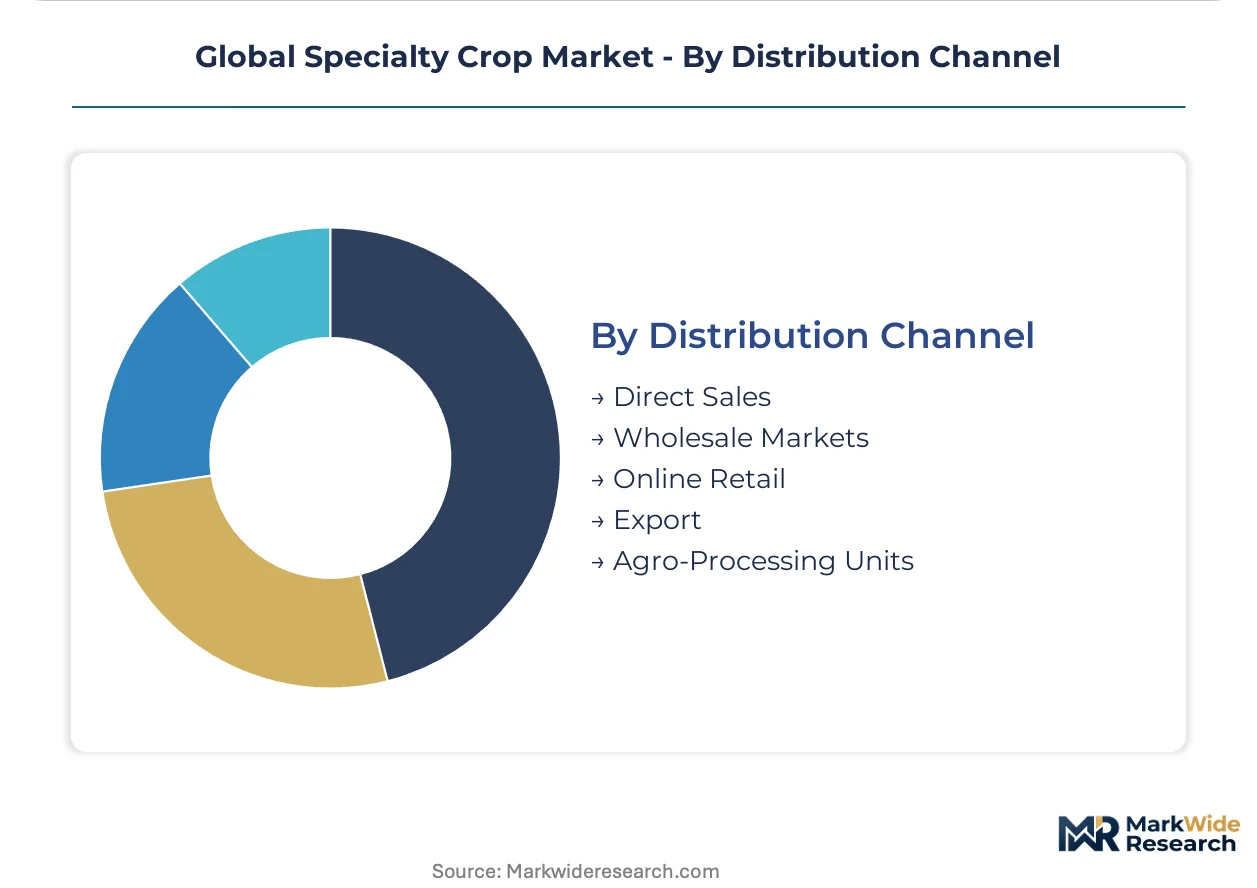
Distribution Channel:
Customer type and margin capture split between direct manufacturer contracting and intermediary-dependent spot markets.
- Direct Sales:Multi-year offtake agreements between origination networks and processors, bypassing commodity auctions. Indian cardamom and Vietnamese cashew supply chains concentrate direct contracting for margin capture.
- Wholesale Markets:Spot-market procurement through terminal markets and trading cooperatives. Price discovery functions dominate in Turkish dried fruit bourses and Indian spice auction platforms.
- Online Retail:Direct-to-consumer channels for specialty herb and medicinal plant products. North American and European e-commerce platforms enable small-scale growers to bypass wholesale intermediaries.
- Export:Cross-border shipment through phytosanitary-controlled corridors. Dubai and Jebel Ali free zones offer clearance speed advantages for Indian spice shipments entering African markets.
- Agro-Processing Units:Integrated curing, drying, and extraction facilities capturing value-add steps at origin. India's PLI-subsidized spice parks in Kerala and Gujarat consolidate origination capacity for export competitiveness.
Wholesale markets retain liquidity dominance. Direct sales are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nutraceutical formulators and organic-certified processors concentrate procurement across distinct origination zones, each shaped by local subsidy regimes and phytosanitary protocols.
India
Spice extractors and Ayurvedic ingredient houses drive procurement of cardamom, turmeric, and black pepper. FSSAI export standards and Spices Board quality protocols govern shipment eligibility. Kerala and Gujarat processing clusters consolidate value-add capacity through PLI-subsidized spice parks and cold chain infrastructure.
United States
Clean-label nut processors and dietary supplement brands demand aflatoxin-compliant almonds and standardized botanical extracts. FDA DSHEA documentation requirements and USDA National Organic Program certification filter supplier eligibility. California's Central Valley anchors almond handling and pasteurization capacity for domestic nutraceutical channels.
Germany
Functional beverage formulators and cosmetics laboratories seek EMA-aligned herbal extracts and cold-pressed carrier oils. EFSA Novel Food assessments and EU Organic Regulation compliance determine import eligibility. Hamburg and Frankfurt processing hubs coordinate superfruit concentrate formulation for wellness brand distribution.
Vietnam
Kernel-grade cashew processors compete on uniformity and moisture specifications for European snack and confectionery channels. Codex Alimentarius maximum residue limits and EU phytosanitary documentation govern export clearance. Binh Phuoc and Dong Nai curing facilities capture margin through direct-to-manufacturer contracting.
Netherlands
Dutch auction cooperatives and fragrance houses drive demand for ornamental blooms and essential oil feedstocks. REACH compliance and ECHA botanical pesticide residue thresholds shape sourcing criteria. Aalsmeer flower auction and Rotterdam re-export infrastructure coordinate supply for German and French cosmetics laboratories.
Global Specialty Crop Market Competitive Landscape
Player mix skews toward integrated origination networks and certified-handler specialists rather than pure trading intermediaries. Tiering separates capitalized operators with GLOBALG.A.P. audit capacity from smallholder-dependent aggregators. Three archetypes dominate: vertically integrated nut and spice processors, organic-certified distribution platforms, and Middle Eastern re-export hub operators. Competitive moves concentrate on multi-year offtake contracting and backward integration into curing and extraction facilities.
Among Asia-Pacific integrated handlers, Olam International exemplifies the multi-continent origination archetype, while United Natural Foods occupies the North American organic distribution tier. Phoenix Global DMCC represents the Middle Eastern re-export specialist model, anchoring Dubai and Jebel Ali clearance speed advantages for Indian spice shipments entering African markets.
| Leading Market Players |
|---|
| Olam International |
| United Natural Foods |
| Specialty Crop Company |
| Golden Peanut and Tree Nuts |
| Phoenix Global DMCC |
| SunWest Foods |
| Diamond Fruit |
| SVZ Industrial Fruit & Vegetable |
| Lamex Food Group |
| Others |
Supply & Pricing Matrix
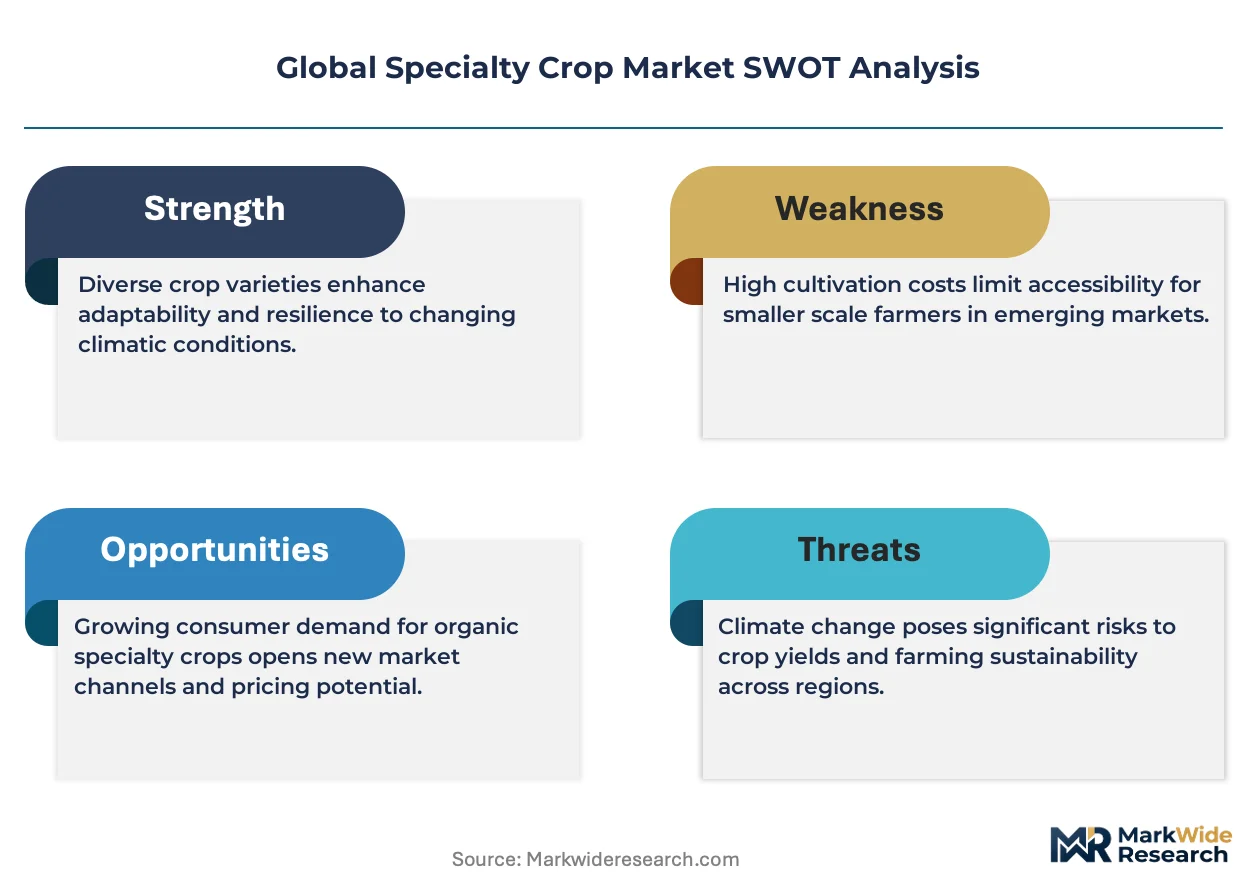
GLOBALG.A.P. certification gates both supply qualification and price differentiation simultaneously, disqualifying uncertified smallholders from European retail channels while concentrating premium pricing power among audited operators with documented traceability systems.
Pricing Analysis
Cost-plus contracts with London Metal Exchange indexation for fertilizer inputs dominate spice and nut procurement, though spot-market volatility in Vietnamese cashew and Indian cardamom auctions introduces price arbitrage opportunities for traders with curing facility access. Three-tier pricing structure across premium, standard, and economy levels separates GLOBALG.A.P.-certified organic lots from IPM-compliant conventional grades and uncertified commodity bulk. Pricing pressure stems from biological pest control agent cost inflation compressing organic farm-level margins. Commodity processors exhibit highest price sensitivity, while pharmaceutical extractors absorb premiums for batch-to-batch standardization.
Supply Chain Analysis
Inbound logistics costs through Mumbai and Ho Chi Minh City port corridors fluctuate with container availability and phytosanitary clearance queues, compressing margin for time-sensitive spice shipments to European nutraceutical formulators. Supply concentrates in India, Vietnam, and California, with Kerala and Gujarat processing clusters anchoring spice origination while Vietnamese cashew curing facilities and California almond handlers compete on kernel uniformity. Raw material dependencies include specialized fertilizer formulations, biological control agents, and aflatoxin-tested nut feedstocks. Single-source vulnerability runs through Indian cardamom monsoon harvest timing. Distribution runs through Dubai and Jebel Ali free zones for African market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates acquisition targets across certification-tier gaps, as nutraceutical procurement shifts toward direct-to-manufacturer contracting displace traditional trading intermediaries.
For Market Incumbents: Compound certification leverage by acquiring IPM-compliant smallholder networks in Kerala and Gujarat before Spices Board quality protocols tighten further. Backward integration into PLI-subsidized spice parks captures margin from auction intermediaries while securing volume for multi-year offtake agreements with European wellness brands. For New Entrants and Emerging Players: Lead with aquaponics system deployment for omega-3 rich medicinal plant cultivation, targeting North American clean-label nutraceutical channels underserved by conventional field suppliers. White-space concentration sits in controlled-environment ashwagandha and ginseng production for FDA DSHEA-compliant extract standardization. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across controlled-environment agriculture sub-segments as hydroponics and aquaponics systems scale for year-round herb production. Viable acquisition targets include mid-tier Indian spice processors with Spices Board export credentials and underutilized curing capacity. Monitor divergence between Codex Alimentarius guidelines and national maximum residue limits as inflection signal for compliance-cost-driven consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Curing Facilities | Indian spice processors capture margin previously held by auction intermediaries through PLI-subsidized infrastructure. |
| GLOBALG.A.P. Certification Investment | European retail access requires third-party audit capacity that disqualifies uncertified competitors from premium channels. |
| Multi-Year Offtake Contracting | Direct-to-manufacturer agreements with nutraceutical brands displace spot-market procurement in cardamom and cashew supply chains. |
| Aquaponics System Deployment | Closed-loop nutrient cycling reduces input costs for omega-3 rich nut oil processors seeking clean-label differentiation. |
| EMA Herbal Monograph Alignment | European regulatory harmonization opens standardized pathways for Ayurvedic extract commercialization across member states. |
Research Methodology
Initial hypotheses were tested against primary input from spice processing cluster managers, nutraceutical procurement directors, and Spices Board export officials and refined through secondary validation against FSSAI quality protocols, EMA herbal monographs, and Codex Alimentarius maximum residue limit frameworks. Bottom-up volume estimates from Kerala and Gujarat origination zones triangulated against top-down demand projections from German functional beverage formulators and North American dietary supplement brands.
Variance decomposition across crop type, production method, end use, and distribution channel dimensions structured the analytical framework throughout the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion assumptions. Industry-specific forecast inputs included PLI scheme infrastructure deployment timelines and EU Novel Food catalog expansion trajectories for exotic fruit extract approvals.
The analysis sits within stated boundaries; outcomes outside sustained certification premium persistence and phytosanitary corridor stability would require recalibration. Forecasts reflect documented assumptions regarding input cost trajectories and regulatory harmonization progress. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Agrimony Market
Agriculture and Agri Products
Mushroom Substrate Market
Agriculture and Agri Products
South America Poultry Feed Market
Agriculture and Agri Products
Specialty Egg Market
Agriculture and Agri Products
Dairy Cattle Feed Market
Agriculture and Agri Products
Seaweed Market
Agriculture and Agri Products
Faba Beans Flour Market
Agriculture and Agri Products
Organic Starter-Grower Chicken Feed Market
Agriculture and Agri Products
North America Hemp Market
Agriculture and Agri Products
Non GMO Soybean Market
Agriculture and Agri Products
Feed Protein Market
Agriculture and Agri Products
United Kingdom Compound Feed Market
Agriculture and Agri Products
Rapeseed Oil Market
Agriculture and Agri Products
American Ginseng Market
Agriculture and Agri Products
Mexico Compound Feed Market
Agriculture and Agri Products
Alfalfa Market