
 Mattress and Mattress Component Market | 2026-2036
Mattress and Mattress Component Market Size, Share, and Industry Trends Forecast 2026-2036
Mattress and Mattress Component Market Outlook
The gap between premium and commodity tiers is restructuring around material traceability and pressure-relief performance rather than brand heritage alone. Tempur Sealy International leverages its proprietary foam chemistry to sustain pricing power in the therapeutic segment. Leggett & Platt anchors the component supply layer with in-house spring and adjustable base production across North American plants.
Mattress and mattress component systems encompass engineered sleep surfaces and their structural supports, typically combining polyurethane or viscoelastic foam layers between 2 and 14 inches thick with fabric-encased coil arrays or slatted foundations designed to distribute body weight and maintain spinal alignment during rest. Memory foam formulations now dominate premium positioning while innerspring platforms retain volume leadership in mass-market retail through lower unit costs and familiar replacement cycles. The hospitality end user segment commands above-average margins due to bulk procurement specifications and brand partnership requirements, whereas online retail channels compete on trial-period policies and compressed-shipping logistics.
The US CPSC maintains mandatory flammability testing under 16 CFR Part 1633, while California's Bureau of Household Goods and Services enforces additional chemical disclosure mandates through SB 1019 that push manufacturers toward certified foam suppliers. ISO 9001 quality management and OEKO-TEX Standard 100 textile certifications increasingly function as market access prerequisites rather than optional differentiators. Stakeholders must monitor how state-level extended producer responsibility proposals reshape end-of-life collection obligations and material recovery economics.
Market Dynamics
Certified foam chemistry and adjustable base integration are compressing replacement cycles while state chemical disclosure mandates force supplier recertification across North American and European procurement networks.
Growth Catalysts
- California SB 1019 disclosure mandates:Chemical transparency requirements push hospitality buyers toward certified foam suppliers, creating tiered procurement specifications that favor documented supply chains.
- Zhejiang manufacturing clusters:Concentrated polyurethane foam production and fabric weaving operations in China's eastern provinces compress component lead times for export-oriented assembly.
- Adjustable base technology:Electromechanical foundation systems command above-average margins in premium residential and hospitality segments through ergonomic positioning features.
Market Restraints
- Polyether polyol price volatility:Petrochemical feedstock fluctuations compress foam producer margins and destabilize long-term contract pricing for mattress assemblers.
- Jiangsu fabric supplier concentration:Geographic clustering of woven textile production creates single-point vulnerability for fire-barrier and ticking supply.
- 16 CFR Part 1633 compliance costs:US CPSC open-flame testing requirements add certification overhead that disadvantages smaller component suppliers without captive laboratory access.
Strategic Opportunities
- Indian hospitality expansion:Underpenetrated branded hotel development in secondary cities creates demand for bulk-certified sleep systems with documented fire-safety credentials.
- Direct-to-installer channels:Bypassing traditional retail distribution through contractor-facing platforms captures renovation and new construction specification decisions earlier in project timelines.
- EU Green Deal circularity requirements:Extended producer responsibility frameworks for furniture waste create first-mover advantage for foam recyclers and modular mattress architectures.
Industry Challenges
- Polymer chemist talent scarcity:Formulation expertise for viscoelastic and high-resilience foams concentrates among retiring specialists without equivalent pipeline development.
- OEKO-TEX Standard 100 timeline compression:Annual recertification cycles for textile components strain quality assurance bandwidth at mid-tier fabric mills.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mattress and Mattress Component Market |
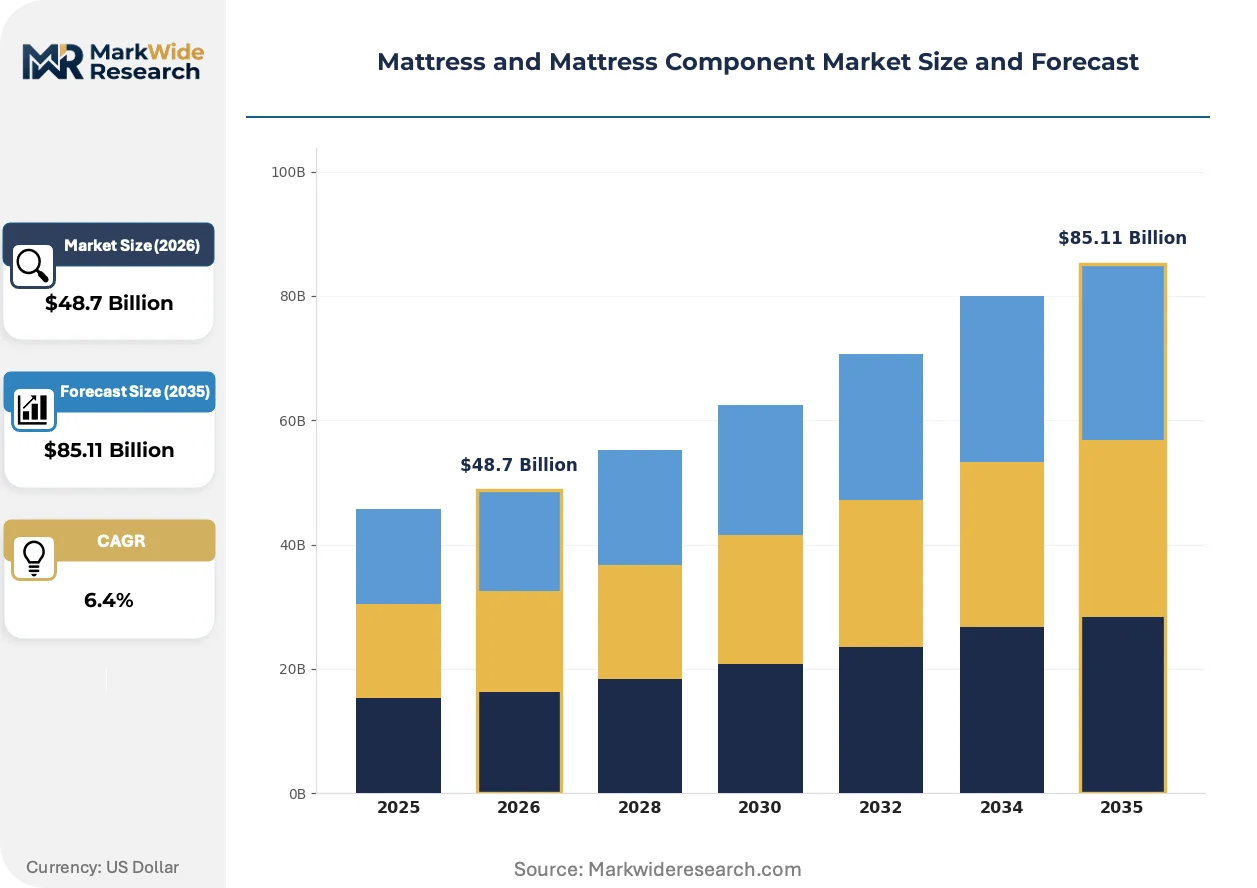
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $85.11 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Memory Foam, Latex, Innerspring, Hybrid Component: Mattress Toppers, Bed Frames, Box Springs, Cushions End User: Residential, Hospitality, Healthcare, Commercial Distribution Channel: Online Retail, Offline Retail, Direct Sales, Wholesalers |
| Companies Covered | Tempur Sealy International, Serta Simmons Bedding, Sleep Number Corporation, Ashley Furniture Industries, Purple Innovation, Casper Sleep Inc., Kingsdown, Leggett & Platt, Saatva, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mattress and Mattress Component Market Strategic Shifts
Sensor-integrated sleep surfaces and compressed-shipping logistics are restructuring how manufacturers capture recurring revenue and reduce last-mile costs across residential and contract channels.
Pressure-mapping sensor arrays embedded in mattress cores is automating biometric feedback collection for hospitality wellness programs and direct-to-consumer subscription services. Hotel operators in Dubai and Singapore are piloting these systems to differentiate premium room categories. The technology is automating guest preference profiling that previously required manual sleep consultation.
REACH SVHC candidate list expansion is forcing reformulation of flame-retardant additives across EU-bound foam production. Manufacturers are substituting phosphorus-based compounds for legacy halogenated systems to maintain market access. German and French bedding brands face the steepest compliance curves due to early adopter positioning in sustainable positioning.
Compressed-roll packaging for hybrid spring-foam mattresses is displacing traditional flat delivery for online residential orders. Third-party logistics providers in the United States and United Kingdom are investing in specialized unboxing equipment to handle return processing at scale. This channel shift concentrates volume with assemblers capable of vacuum-compression without coil deformation.
Mattress and Mattress Component Market Segmentation
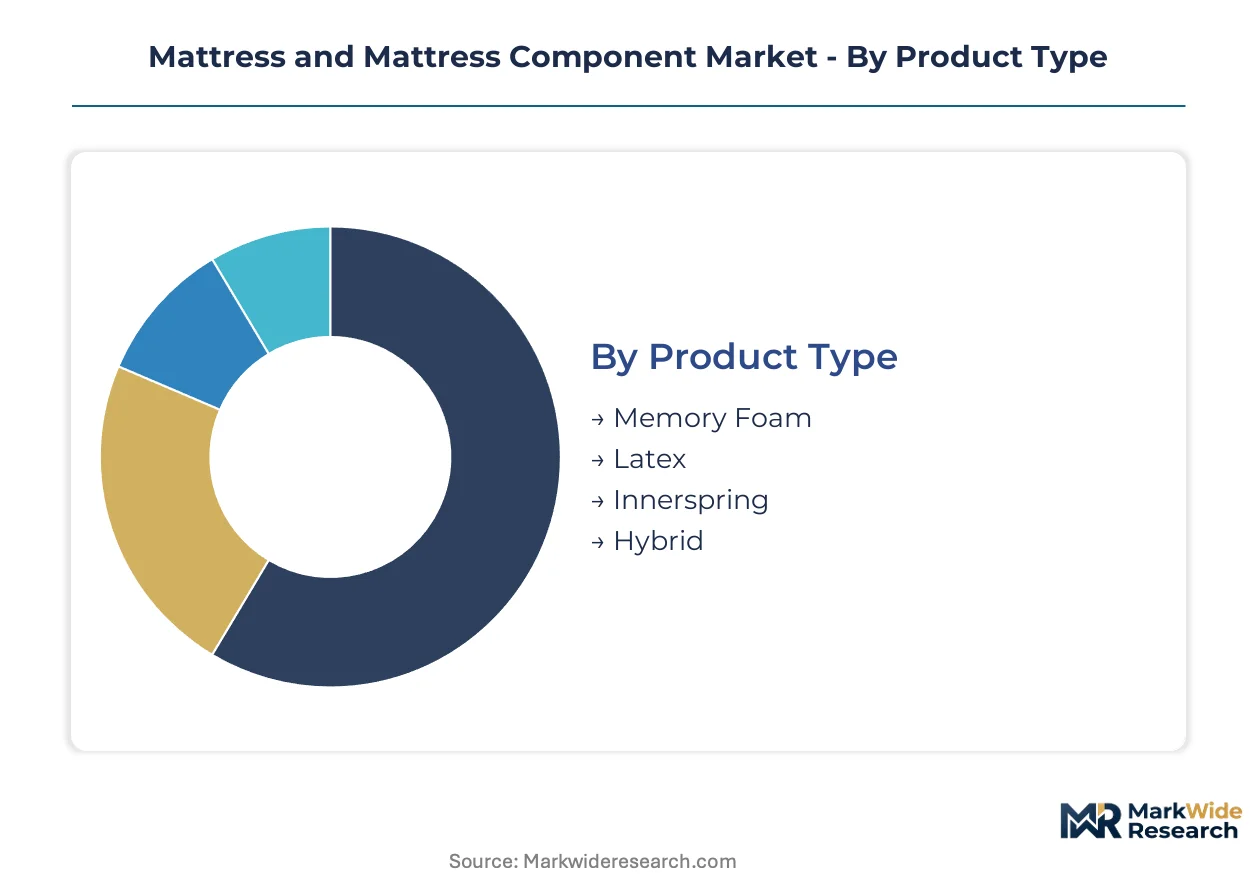
Material chemistry and channel economics split the mattress market into distinct competitive arenas. Procurement specifications vary sharply between bulk hospitality contracts and direct-to-consumer residential purchases.
Product Type:
Volume leadership and premium positioning diverge based on foam chemistry investment and coil integration complexity.
- Innerspring:Open-coil and pocketed spring systems with fabric-encased wire arrays deliver familiar bounce and airflow at lower unit costs. Mass-market retail in the United States and Germany depends on these platforms for replacement-cycle predictability and compressed shipping compatibility.
- Memory Foam:Viscoelastic polyurethane formulations with density ratings between 3 and 5 pounds per cubic foot contour to body weight through temperature-responsive cell structures. Hospitality procurement in Dubai and Singapore specifies these surfaces for wellness-positioning and pressure-relief performance in premium room categories.
- Hybrid:Foam-spring layered architectures combine coil support cores with memory foam comfort layers. These configurations target consumers seeking pressure relief without sacrificing traditional mattress feel.
- Latex:Natural or synthetic rubber foam derived from Hevea brasiliensis sap or styrene-butadiene polymerization. Dunlop and Talalay processing methods yield distinct density and breathability profiles for allergy-sensitive residential buyers.
Mature deployment sits with Innerspring. Newer deployment is concentrated in Memory Foam.
Component:
Margin capture shifts downstream from core mattress assembly toward foundation systems and surface accessories.
- Bed Frames:Metal grid platforms, upholstered foundations, and electromechanical adjustable bases with motorized articulation. Adjustable base integration commands above-average margins in premium residential and hospitality segments through ergonomic positioning features.
- Mattress Toppers:Supplementary foam or fiber layers between 2 and 4 inches thick that modify surface firmness without full mattress replacement. These accessories concentrate in online retail channels with trial-period policies and compressed-shipping logistics.
- Box Springs:Rigid wooden frames with steel spring grids or solid platform decks designed to absorb impact and extend core mattress longevity. These components retain volume in North American brick-and-mortar retail through established replacement cycles.
- Cushions:Loose fill or molded foam inserts for seating and bedding accessories, typically produced from scrap foam reclamation or dedicated high-resilience formulations.
Volume concentration remains with Box Springs. Value expansion is climbing the fastest in Bed Frames.
End User:
Contract specifications and consumer purchase cycles create divergent margin structures across demand sources.
- Residential:Individual household purchases through retail or direct channels with replacement intervals averaging 7 to 10 years. Compressed-roll packaging and trial-period policies now dominate online acquisition in the United States and United Kingdom.
- Hospitality:Bulk procurement by hotel operators and management companies with brand partnership requirements and certified fire-safety credentials. California SB 1019 disclosure mandates push hospitality buyers toward documented foam suppliers, creating tiered procurement specifications.
- Healthcare:Medical facility and long-term care installations requiring pressure-relief surfaces for patient mobility and wound prevention. Medicare reimbursement codes influence product selection for institutional purchasers.
- Commercial:Corporate housing, student dormitories, and military barracks with standardized durability specifications and volume-driven pricing negotiations.
Margin stability characterizes Healthcare. Demand acceleration concentrates in Hospitality.
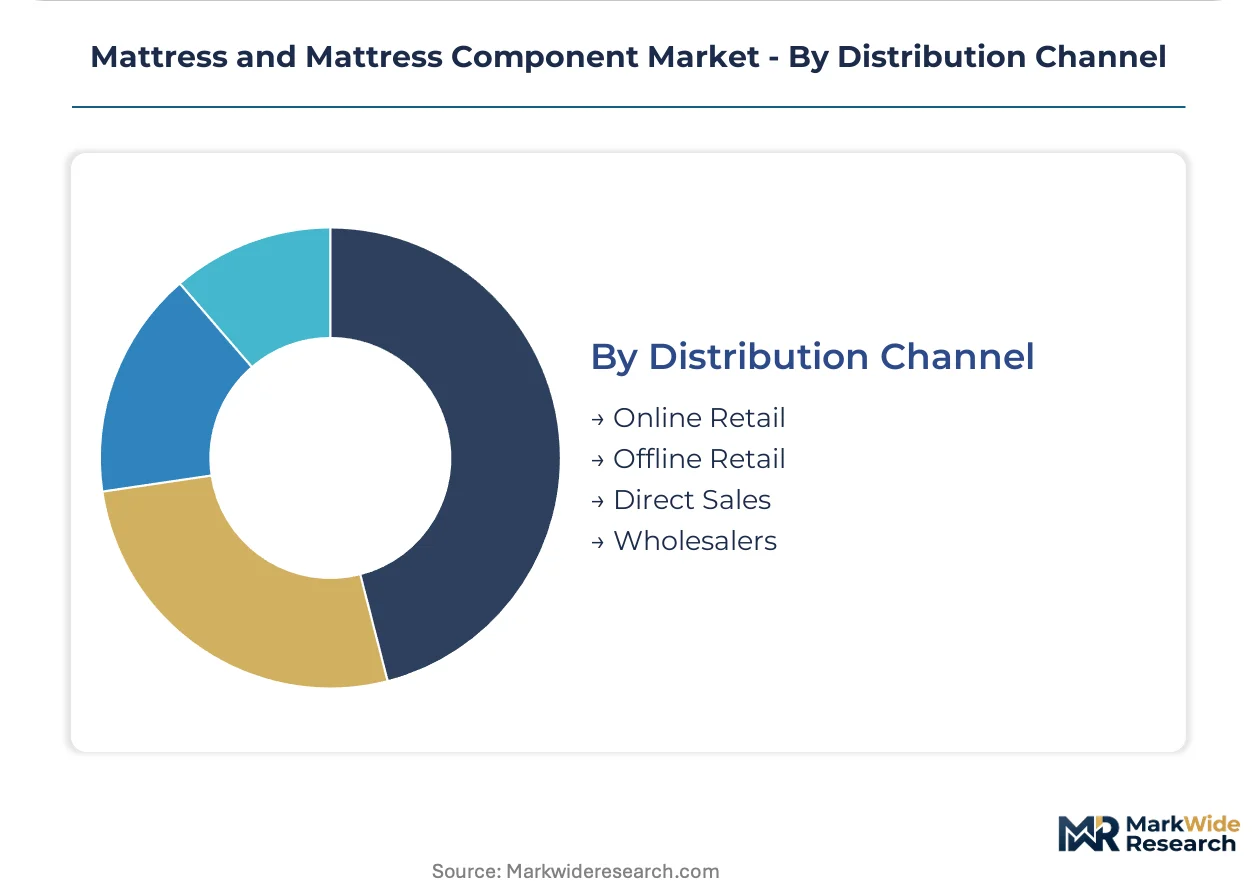
Distribution Channel:
Logistics infrastructure and customer acquisition economics determine channel viability for different product configurations.
- Online Retail:E-commerce platforms with compressed-shipping logistics, trial-period policies, and return processing infrastructure. Third-party logistics providers invest in specialized unboxing equipment to handle scale.
- Offline Retail:Brick-and-mortar showrooms with lie-down testing and immediate delivery coordination. These outlets retain importance for hybrid and innerspring purchases where coil feel influences selection.
- Direct Sales:Manufacturer-owned channels bypassing wholesale markups through company websites or owned-store networks. These routes capture full margin but require captive logistics investment.
- Wholesalers:Intermediary distributors serving furniture retailers, hospitality procurement departments, and institutional buyers with volume pricing and consolidated fulfillment.
Established infrastructure supports Offline Retail. Channel investment is expanding most quickly in Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Zhejiang and Jiangsu provinces anchor polyurethane foam production and fabric weaving for export-oriented mattress assembly, with procurement specifications diverging sharply across North American, European, and Asian hospitality markets.
United States
Hospitality procurement teams in Las Vegas and Orlando prioritize certified sleep systems for guest satisfaction metrics. The US CPSC enforces 16 CFR Part 1633 open-flame testing requirements that reshape material specifications. Carolina and Virginia host dense concentrations of adjustable base manufacturing serving premium residential channels.
China
Manufacturing clusters around Wenzhou and Changzhou compress component lead times for global export assembly. SAMR oversees GB standards compliance for domestic mattress labeling and fire-safety claims. The Yangtze River Delta integrates foam production with automated quilting operations at factory-town scale.
Germany
REACH SVHC candidate list expansions force reformulation of flame-retardant additives across EU-bound foam production. ECHA compliance curves steepen for bedding brands with early sustainable positioning. Bavarian fabric mills concentrate on OEKO-TEX Standard 100 recertification cycles for hospitality textile exports.
India
Branded hotel development in Bangalore and Hyderabad secondary markets creates demand for bulk-certified sleep systems. BIS fire-safety standards and state-level building codes influence procurement specifications. Maharashtra and Gujarat host emerging foam fabrication capacity serving domestic hospitality chains.
United Arab Emirates
Dubai hotel operators pilot sensor-integrated sleep surfaces to differentiate premium room categories. MOHAP product safety frameworks align with Gulf Cooperation Council technical regulations. Jebel Ali free zone logistics infrastructure supports re-export of compressed-roll mattresses to African and South Asian markets.
Mattress and Mattress Component Market Competitive Environment
Premium-margin players sit above commodity-margin players across material chemistry certification and hospitality procurement access. The vendor base stratifies into three tiers: integrated foam-and-spring assemblers with captive chemistry labs, component specialists supplying adjustable base mechanisms and fire-barrier textiles, and direct-to-consumer brands competing on trial-period logistics. Dominant competitive moves include backward integration into polyurethane formulation and strategic partnerships with third-party logistics providers for compressed-shipping infrastructure.
Within the integrated assembler tier, Tempur Sealy International and Serta Simmons Bedding occupy positions defined by proprietary foam chemistry and hospitality contract scale. Leggett & Platt anchors the component supply layer with in-house spring and adjustable base production. Among direct-to-consumer specialists, Casper Sleep Inc. and Purple Innovation exemplify brands built on compressed-roll logistics and online trial-period policies rather than retail showroom presence.
| Leading Market Players |
|---|
| Tempur Sealy International |
| Serta Simmons Bedding |
| Sleep Number Corporation |
| Ashley Furniture Industries |
| Purple Innovation |
| Casper Sleep Inc. |
| Kingsdown |
| Leggett & Platt |
| Saatva |
| Others |
Value Chain & Pricing Dynamics
Polymer chemist talent scarcity in the US Midwest and German chemical hubs widens labor-cost differentials between premium foam formulation tiers and commodity innerspring platforms. California SB 1019 compliance overhead concentrates pricing power with certified suppliers capable of absorbing recertification costs while smaller mills face margin compression.
Pricing Analysis
Outcome-based pricing anchored to guest satisfaction scores and pressure-relief performance metrics dominates hospitality procurement contracts. Three-tier pricing structure across premium, standard, and economy levels separates OEKO-TEX certified memory foam systems from uncertified commodity innersprings. Pricing pressure stems from polyether polyol feedstock volatility compressing foam producer margins. Bulk hospitality buyers exhibit lowest price sensitivity due to brand partnership requirements, while online residential consumers drive aggressive trial-period competition.
Supply Chain Analysis
Direct-to-installer channels handling renovation and new construction specifications bypass traditional retail markups for earlier project capture. Manufacturing gravity centers on China's Zhejiang and Jiangsu provinces for polyurethane foam and woven textiles, with North American adjustable base assembly concentrated in Carolina and Virginia. Raw material dependencies draw from petrochemical feedstocks, steel wire rod, and natural rubber latex. Single-source vulnerability in Jiangsu fabric clustering threatens fire-barrier supply continuity. Distribution runs through hospitality procurement departments, third-party logistics providers with compression equipment, and contractor-facing specification platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where California chemical disclosure mandates and CPSC certification overhead force sub-scale foam suppliers into exit or acquisition.
For Market Incumbents: Extend proprietary foam chemistry advantages through backward integration into polyurethane formulation to capture margin from petrochemical volatility. Lock in hospitality procurement relationships with multi-year certified supply agreements that raise switching costs for Dubai and Singapore hotel operators piloting sensor-integrated wellness positioning.
For New Entrants and Emerging Players: Direct-to-installer digital platforms targeting commercial renovation timelines offer the most penetrable white-space entry, bypassing established retail shelf access barriers. Focus specification capture on Indian secondary-city hotel development in Bangalore and Hyderabad where bulk-certified sleep system demand outpaces incumbent hospitality contract coverage.
For Investors and Strategic Acquirers: Re-rating potential sits with mid-tier foam fabricators holding OEKO-TEX certification and underutilized Zhejiang production capacity given EU Green Deal circularity requirements creating first-mover recovery economics. Monitor REACH SVHC candidate list expansion velocity as the inflection signal for phosphorus-based flame-retardant reformulation investment cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyurethane Formulation | Captures margin from polyether polyol volatility while securing certified foam supply for hospitality contracts. |
| Sensor-Integrated Sleep Surface Development | Enables biometric guest profiling for Dubai and Singapore premium hotel differentiation and recurring data revenue. |
| Direct-to-Installer Channel Establishment | Bypasses retail markups by capturing renovation specification decisions earlier in project timelines. |
| EU Green Deal Circularity Compliance Investment | Positions foam recyclers and modular architectures for extended producer responsibility framework advantage. |
| Adjustable Base Manufacturing Scale-Up | Commands above-average margins in premium residential and hospitality segments through ergonomic positioning features. |
Study Parameters
Multi-period observation of foam density migration patterns, certification adoption curves, and compressed-shipping logistics penetration anchored the trend analysis, supplemented by interviews with hospitality procurement directors, polymer formulation chemists, adjustable base manufacturing engineers, and third-party logistics specialists. Secondary validation drew from US CPSC 16 CFR Part 1633 filings, California Bureau of Household Goods and Services enforcement data, SAMR GB standards documentation, ECHA REACH SVHC candidate lists, and customs trade records. Bottom-up segment sizing triangulated against top-down macroeconomic indicators.
Segment-weighting across product type, component category, end-user vertical, and distribution channel informed the analytical framework throughout the projection horizon. CAGRs derived from elasticity modeling against replacement cycle compression and hospitality development pipelines. Industry-specific forecast inputs included petrochemical feedstock price indices and hotel room supply expansion in target secondary markets.
The model holds under stable regulatory enforcement intensity and continued petrochemical supply availability; deviation in REACH SVHC expansion velocity or polyether polyol supply disruption would shift volume trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
Wall Covering Market
Homecare and Decor
Soundproof Curtains Market
Homecare and Decor
Japan Sustainable Home Decor Market
Homecare and Decor
Fireplace and Stove Market
Homecare and Decor
Asia-Pacific Decorative Laminates Market
Homecare and Decor
India Decorative Laminates Market
Homecare and Decor
Global Wallpaper Market
Homecare and Decor
Mattress Topper Market
Homecare and Decor
Mattresses and Accessories Market
Homecare and Decor
Hospital Bedsheet and Pillow Cover Market
Homecare and Decor
India Wall Decor Market
Homecare and Decor
Bifold Door Market
Homecare and Decor
Smart Vase Market
Homecare and Decor
Garden Sheds Market
Homecare and Decor
Hearth Market
Homecare and Decor
United States Home Decor Market