
 Acid Stable Blue Market | 2026-2036
Acid Stable Blue Market Size, Share, and Industry Trends Forecast 2026-2036
Acid Stable Blue Market Analytics
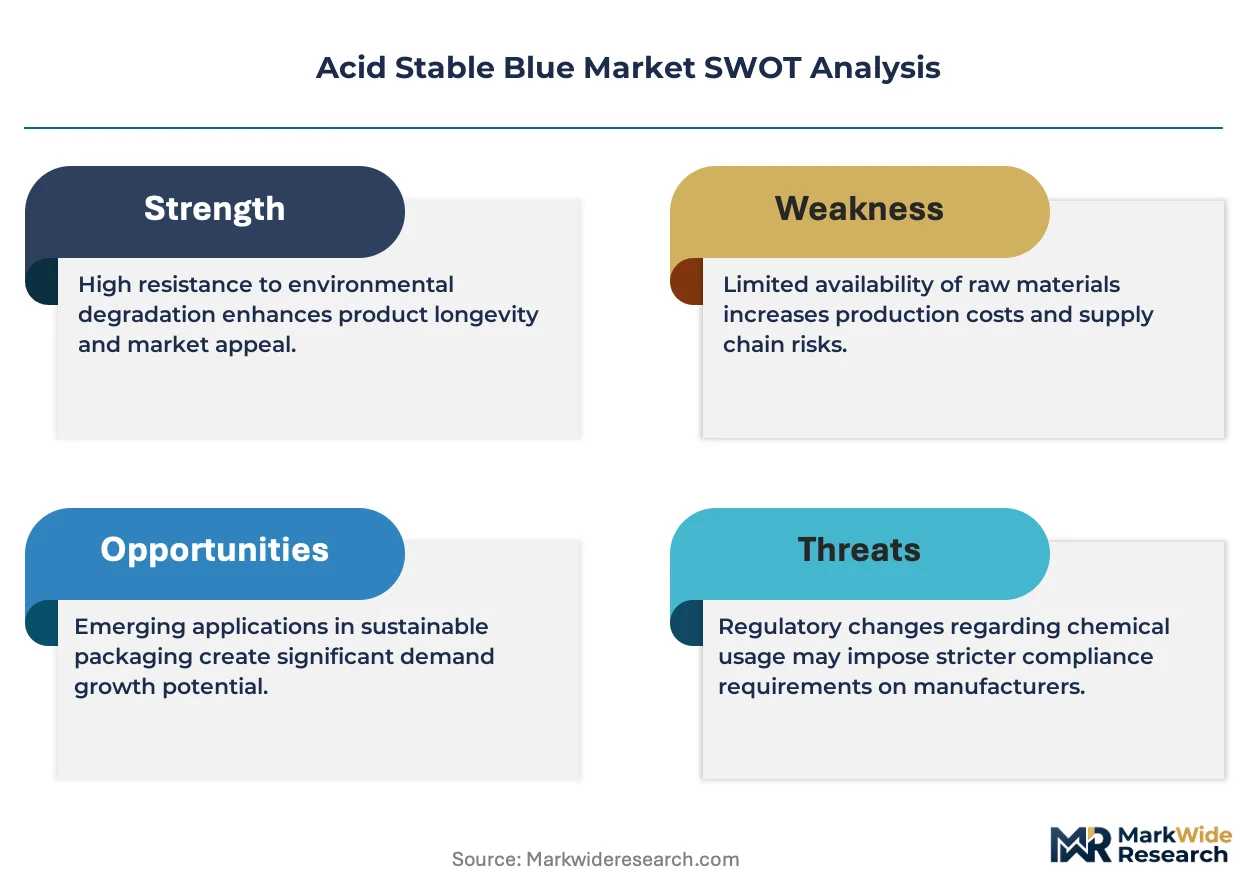
Multi-source procurement among coating formulators is expanding as buyers reduce dependency on single-origin pigment supply. BASF SE leverages its integrated azo pigment complexes to sustain European coating demand, while Clariant International Ltd. anchors specialty distribution across Asian industrial zones. Huntsman International LLC competes through captive intermediates production, and DyStar specializes in acid dye compatibility testing for textile mill clients.
Acid stable blue denotes a class of synthetic colorants engineered to retain chromatic integrity below pH 3.0, typically formulated from copper-phthalocyanine or triphenylmethane derivatives with sulfonic acid substituents that stabilize molecular structure in aggressive acidic environments. These pigments serve coating manufacturers requiring batch-to-batch hue consistency in acidic curing systems and industrial finishes exposed to chemical washdowns. Powder formulations dominate volume throughput due to extended shelf stability and reduced freight costs, while liquid dispersions capture premium positioning in automated ink delivery systems where rapid dispersion kinetics reduce milling time. Textile dyeing applications represent the fastest-expanding demand pool as mills transition from conventional vat dyes to acid-stable alternatives compatible with low-pH exhaustion cycles.
EPA hazardous air pollutant standards for pigment manufacturing shape US facility permitting and emission control investments, while REACH registration requirements in Europe restrict certain arylamine intermediates in acid blue synthesis. China's MEE enforces wastewater colority limits that constrain small-batch dyestuff operations near Yangtze River industrial corridors. Stakeholders must monitor evolving chemical hazard classifications under these overlapping regimes to anticipate reformulation costs and supply qualification timelines.
Market Dynamics
REACH registration requirements in Europe are compressing the supplier base for arylamine intermediates, forcing coating formulators to requalify pigment sources and redirect procurement toward South Asian manufacturers with compliant synthesis pathways.
Growth Catalysts
- Low-pH exhaustion cycles:Textile mills in India are adopting acid-stable alternatives to conventional vat dyes, reducing water consumption and chemical load in dyeing operations while maintaining color fastness.
- EPA hazardous air pollutant standards:Stricter US emission controls on pigment manufacturing are accelerating capital upgrades at domestic facilities, creating competitive advantage for operators with advanced scrubbing and solvent recovery systems.
- Copper-phthalocyanine derivatives:Advances in sulfonic acid substituent engineering are expanding the pH stability window of blue pigments, enabling deployment in aggressive acidic curing systems previously served by less durable colorants.
Market Restraints
- Crude oil derivatives:Phthalic anhydride and phthalonitrile feedstock costs track petrochemical volatility, compressing margin buffers for pigment manufacturers without backward integration into intermediate production.
- Yangtze River corridor:China's MEE wastewater colority enforcement has shuttered small-batch dyestuff operations, concentrating supply among state-backed producers and reducing spot market liquidity.
- Heavy-metal substitution:Cobalt-based blue pigments face displacement pressure as REACH Annex XVII restrictions tighten permissible metal content in consumer-facing applications.
Strategic Opportunities
- Automated ink delivery systems:Liquid dispersion formulations with rapid dispersion kinetics command premium positioning in digital printing installations, where reduced milling time translates to higher effective throughput.
- Brazilian textile clusters:Underpenetrated acid-stable blue adoption in São Paulo state dye houses offers first-mover advantage for suppliers establishing local technical service capabilities.
- EU Green Deal chemical hazard reclassification:Anticipated tightening of substance hazard categories under CLP regulation will accelerate reformulation demand, favoring pigment houses with pre-validated alternative chemistries.
Industry Challenges
- REACH dossier maintenance:Registration update costs and data sharing disputes among SIEF members strain mid-tier pigment houses with limited regulatory affairs staffing.
- Batch-to-batch hue consistency:Coating formulators face qualification delays when switching between acid stable blue sources, as particle size distribution variations disrupt established color matching protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acid Stable Blue Market |
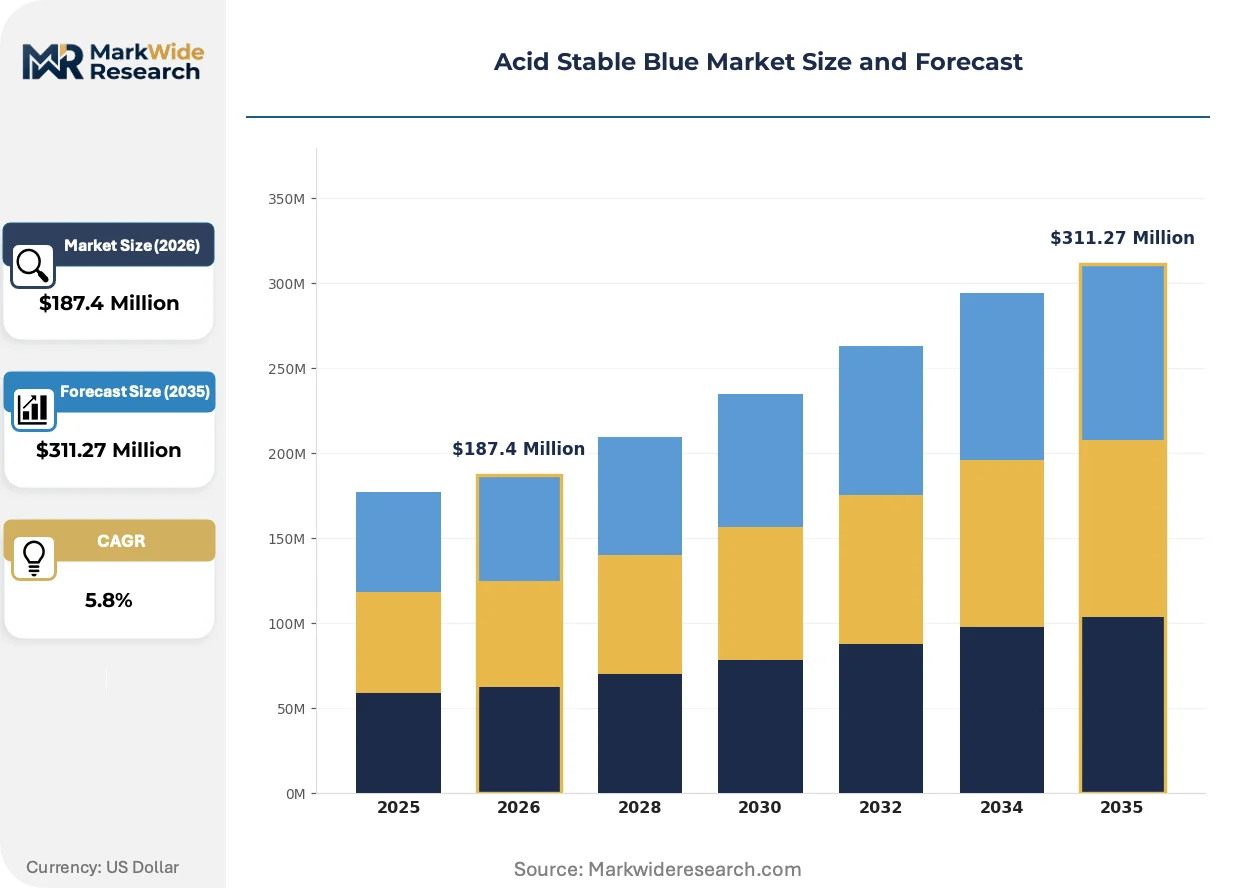
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granule, Paste, Liquid Application: Coating, Textile Dyeing, Inks, Plastics End Use Industry: Chemicals, Paints, Paper, Cosmetics Packaging Type: Drum, Bag, Bottle, Sachet |
| Companies Covered | BASF SE, Clariant International Ltd., Atul Ltd., Huntsman International LLC, DyStar, Hubei Chuyuan, Dikai Chemical, Jihua Group, Solvay, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acid Stable Blue Market Evolving Landscape
Acid stable blue pigment production is fragmenting across multiple technological fronts, with synthesis automation, regulatory compliance tooling, and application-specific formulation services converging to reshape competitive requirements.
Microreactor continuous flow synthesis is decentralizing acid stable blue manufacturing from centralized batch plants toward modular production units. Coating compounders in Germany and the Netherlands are piloting captive pigment synthesis for proprietary color systems. This distributed production model is compressing minimum order quantities and shortening qualification cycles for specialty shade development.
REACH authorization listing procedures are forcing pigment houses to maintain parallel substance portfolios. ECHA's 2024-2026 work program prioritizes arylamine derivative assessments, compelling manufacturers to accelerate substitution research for copper-complexed intermediates. Textile dyeing applications face the steepest compliance timeline pressure, as downstream brands advance their own restricted substance lists ahead of regulatory mandates.
Specification-driven vendor consolidation is concentrating acid stable blue procurement among coating formulators with centralized color management systems. Large automotive refinish operations in the US and Germany are reducing qualified pigment sources from twelve to four suppliers, exchanging volume commitments for technical co-development access. This buyer concentration is most visible in metallic and pearlescent effect coatings, where hue angle precision requirements exceed commodity pigment tolerances.
Acid Stable Blue Market Segmentation
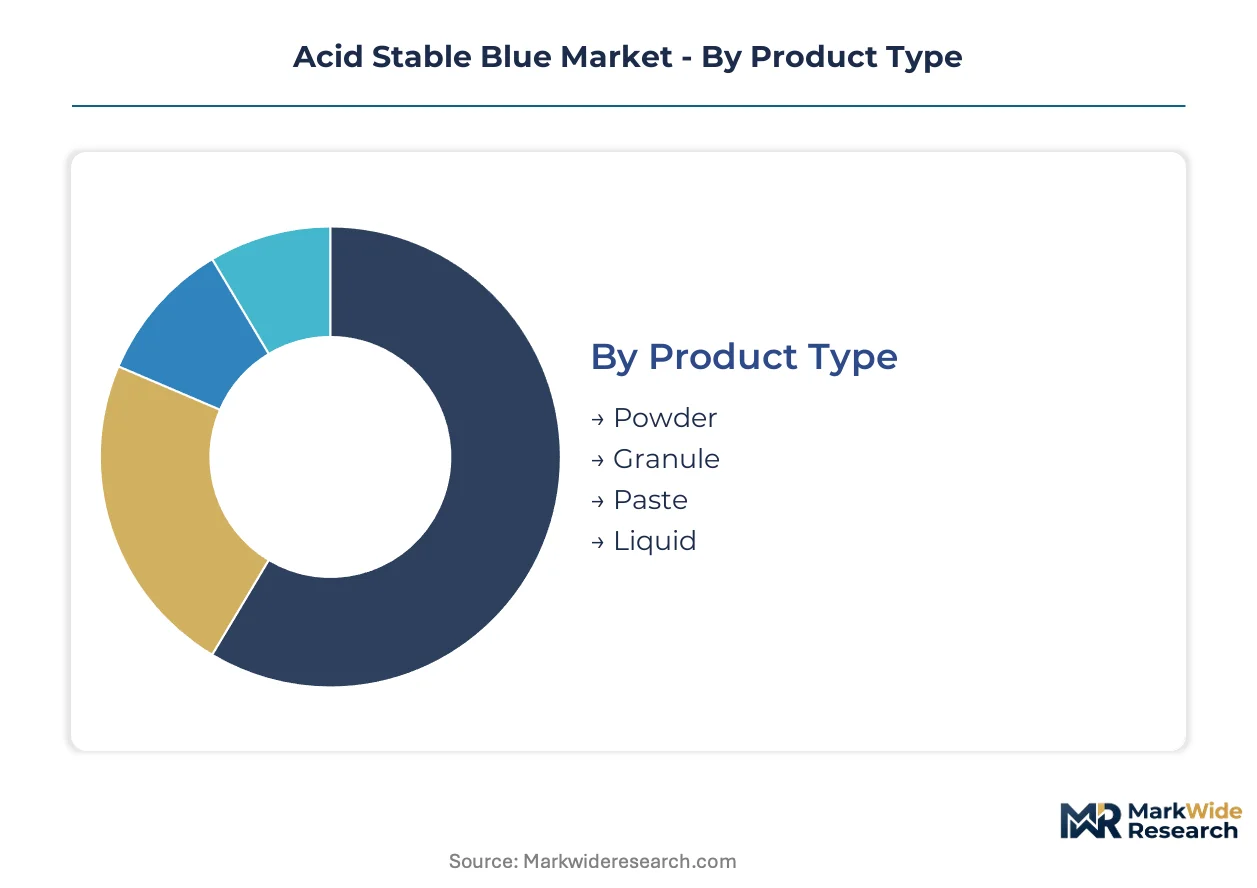
Acid stable blue pigments serve distinct performance requirements across formulation states and end-use environments. Segmentation reveals where copper-phthalocyanine chemistry dominates versus where triphenylmethane derivatives hold technical advantage.
Product Type:
Powder and liquid formulations anchor opposite ends of the integration spectrum—powder operates as standalone inputs requiring downstream dispersion, while liquid dispersions embed pre-milled pigment in delivery-ready systems.
- Powder:Dry pigment concentrates with extended shelf stability and reduced freight costs dominate volume throughput for coating manufacturers operating internal milling operations. Demand concentrates in German and Dutch industrial coating clusters where batch-to-batch hue consistency requirements favor in-house dispersion control.
- Liquid:Pre-dispersed pigment suspensions with engineered particle size distributions capture premium positioning in automated ink delivery systems. Textile mills in India are adopting liquid formats to reduce milling time and water consumption in low-pH exhaustion cycles.
- Granule:Low-dust handling formats with reduced airborne exposure during weighing operations serve specialty chemical manufacturers with stringent OSHA particulate controls.
- Paste:Semi-moist concentrates bridge powder and liquid states for small-batch coating compounders lacking dispersion infrastructure.
Powder leads volumes today; liquid is gaining share fastest.
Application:
Application segments diverge by curing chemistry aggressiveness and color fastness specifications, with coating and textile dyeing representing opposing margin profiles.
- Coating:Industrial finishes and automotive refinish systems requiring batch-to-batch hue consistency in acidic curing environments drive specification-grade procurement. US automotive refinish operations are consolidating qualified pigment sources from twelve suppliers to four, exchanging volume commitments for technical co-development access.
- Textile Dyeing:Low-pH exhaustion cycles compatible with acid-stable alternatives are displacing conventional vat dyes in South Asian mills. REACH compliance tightening in Europe is redirecting procurement toward Indian manufacturers with heavy-metal-compliant synthesis pathways.
- Inks:Digital and conventional printing applications demand rapid dispersion kinetics for automated delivery systems, favoring liquid dispersion formats with premium positioning.
- Plastics:Masterbatch integration requires thermal stability above polymer processing temperatures, limiting acid stable blue deployment to lower-heat engineering resins.
Coating anchors revenue concentration; textile dyeing climbs the fastest.
End Use Industry:
End-use industries segment by regulatory exposure and color performance tier, with paints and chemicals representing mature demand pools versus emerging cosmetics applications.
- Chemicals:Specialty chemical manufacturers serving downstream formulation markets purchase acid stable blue as intermediate inputs for proprietary color systems, with German compounders piloting captive microreactor synthesis.
- Paints:Decorative and protective coating operations specify acid stable blue for chemical washdown resistance in food processing and pharmaceutical facilities, with EPA hazardous air pollutant standards shaping US facility qualification.
- Paper:Specialty packaging and security paper applications require pH-stable colorants for archival durability, though volume remains constrained by digital substitution trends.
- Cosmetics:Personal care colorants face steep REACH Annex XVII heavy-metal restrictions, with cobalt-based blue pigments facing displacement pressure from copper-phthalocyanine alternatives.
Paints dominates absolute consumption; cosmetics expands most quickly.
Packaging Type:
Packaging configurations align with order scale and handling automation, with drums and bags serving opposing ends of the volume spectrum.
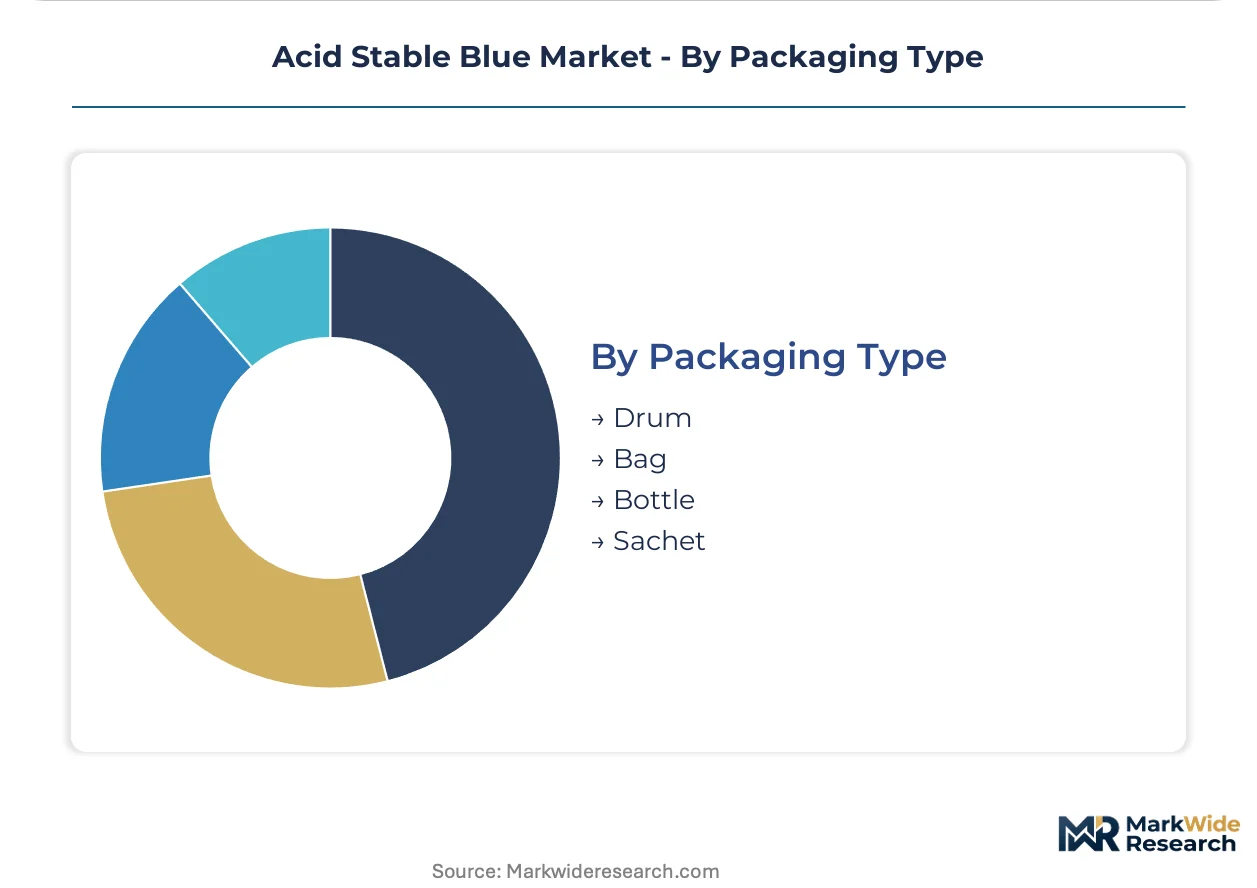
- Drum:Steel and fiber drums with sealed closures accommodate bulk powder and liquid shipments to coating manufacturers with integrated color management systems, reducing per-kilogram handling costs.
- Bag:Multi-wall paper and woven polypropylene bags serve mid-scale textile dye houses in India and Brazil with manual or semi-automated handling infrastructure.
- Bottle:Laboratory and sample-size containers support qualification trials and shade matching protocols for coating formulators requalifying pigment sources.
- Sachet:Single-use foil packets enable precise dosing in small-batch cosmetic and specialty chemical operations with limited weighing equipment.
Drum leads industrial procurement; sachet shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gujarat's chemical manufacturing corridor anchors acid stable blue production capacity, with Indian manufacturers scaling output to serve export-oriented textile clusters across South Asia and Europe.
India
Domestic chemical manufacturers in Gujarat and Maharashtra are expanding acid stable blue synthesis for textile dyeing operations. BIS certification requirements for dye intermediates are tightening quality protocols. Ankleshwar and Vapi industrial zones concentrate new capacity installations targeting REACH-compliant export markets.
Germany
Coating formulators in North Rhine-Westphalia and Bavaria specify acid stable blue for automotive refinish systems requiring batch-to-batch hue precision. ECHA's 2024-2026 arylamine assessment work program is accelerating substitution research. Leverkusen and Ludwigshafen chemical clusters host integrated azo pigment complexes serving European industrial coating demand.
China
Yangtze River Delta pigment houses are consolidating after MEE wastewater colority enforcement shuttered small-batch operations. GB standards for dyestuff manufacturing are elevating environmental compliance costs. Shaoxing and Hangzhou textile chemical zones are redirecting acid stable blue output toward higher-value coating applications.
United States
Automotive refinish operations in Michigan and Ohio are consolidating qualified pigment sources from twelve suppliers to four. EPA hazardous air pollutant standards for pigment manufacturing are accelerating scrubbing and solvent recovery investments. Detroit and Cleveland metropolitan areas concentrate technical service capabilities for specification-grade procurement.
Brazil
São Paulo state dye houses represent underpenetrated acid stable blue adoption in Latin American textile processing. ANVISA cosmetic colorant regulations are displacing cobalt-based pigments in personal care applications. Greater São Paulo industrial zones offer first-mover positioning for suppliers establishing local technical service infrastructure.
Acid Stable Blue Market Competitive Landscape
Global majors compete with regional champions across regulatory compliance capabilities and synthesis automation. The supplier base compresses around integrated azo pigment houses with captive intermediate production and specialty distributors with Asian industrial zone presence. Three archetypes dominate: European chemical conglomerates with REACH dossier expertise, Indian manufacturers with cost-optimized heavy-metal-compliant pathways, and Chinese state-backed producers with scaled phthalocyanine output. Competitive moves concentrate on microreactor continuous flow synthesis adoption and multi-source procurement qualification support for coating formulators.
Within the European integrated chemical tier, BASF SE and Clariant International Ltd. exemplify regulatory affairs depth and specialty distribution anchoring respectively. Among Asia-Pacific manufacturers, Atul Ltd. occupies a position bridging export compliance and domestic scale. These three represent divergent responses to REACH authorization pressures: dossier maintenance infrastructure, regional technical service networks, and backward integration into arylamine intermediates.
| Leading Market Players |
|---|
| BASF SE |
| Clariant International Ltd. |
| Atul Ltd. |
| Huntsman International LLC |
| DyStar |
| Hubei Chuyuan |
| Dikai Chemical |
| Jihua Group |
| Solvay |
| Others |
Value Network & Pricing Analysis
Specification-grade coating procurement separates premium acid stable blue pigments from commodity textile grades through REACH dossier depth and batch-to-batch hue precision, with German automotive refinish buyers paying substantial markups for qualified sources while Indian dye houses optimize for freight-adjusted unit economics. This tier divergence concentrates supply chain leverage among integrated azo pigment houses with captive intermediate production, compressing margin buffers for distributors caught between petrochemical feedstock volatility and downstream price resistance.
Pricing Analysis
Phthalic anhydride and phthalonitrile feedstock costs pass through directly to pigment manufacturers, with powder formulations commanding three-tier pricing structure across premium, standard, and economy levels based on particle size distribution tolerance and REACH registration status. Price differentiation hinges on certification tier—ECHA-registered copper-phthalocyanine derivatives trade at substantial premiums over unregistered alternatives—and volume scale, with automotive refinish buyers locking multi-year offtake agreements. Cost compression in standard-grade powder is intensifying because Yangtze River consolidation has reduced spot market liquidity. Brazilian textile dye houses show highest price sensitivity due to underdeveloped local technical infrastructure, while German coating formulators prioritize hue consistency over unit cost.
Supply Chain Analysis
REACH registration and BIS certification gating concentrates qualified supply among Indian, German, and Chinese producers with established dossier maintenance capabilities, excluding smaller batch operators from specification-grade procurement channels. Raw material dependencies rest on petrochemical-derived phthalic anhydride, copper salt intermediates, and sulfonic acid substituents sourced from integrated chemical complexes. Single-source vulnerability runs through arylamine intermediate supply, where SIEF data-sharing disputes have stranded several manufacturers without compliant synthesis pathways. Distribution runs through specialty chemical distributors with Asian industrial zone presence, feeding coating compounders and textile mills through drum and bag configurations scaled to order volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acid stable blue market functions as a regulatory compounder, with ECHA's 2024-2026 arylamine assessment work program accelerating substitution demand and compressing qualification timelines for non-compliant suppliers.
For Market Incumbents: Hedge REACH authorization risk by accelerating copper-complexed intermediate substitution research and securing captive sulfonic acid substituent production in Gujarat or Maharashtra. Dossier maintenance infrastructure represents the critical defensive lever against mid-tier pigment houses with limited regulatory affairs staffing, while microreactor continuous flow synthesis adoption defends margin position against South Asian cost-optimized entrants. For New Entrants and Emerging Players: São Paulo state dye houses offer the most penetrable buyer archetype, with underdeveloped acid stable blue adoption in Brazilian textile processing and ANVISA cosmetic colorant regulations displacing cobalt-based alternatives. Local technical service capabilities unlock first-mover positioning, while liquid dispersion formats tailored to automated ink delivery systems capture premium positioning in underpenetrated Latin American digital printing installations. For Investors and Strategic Acquirers: Asymmetric upside sits with Indian manufacturers bridging export compliance and domestic scale, particularly those with backward integration into arylamine intermediates and established BIS certification protocols. Long-term viability over a five-to-ten-year window hinges on pre-positioning for EU Green Deal chemical hazard reclassification. The signal to watch is ECHA authorization listing velocity for copper-complexed intermediates, which would trigger immediate reformulation demand and supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Arylamine Intermediates | Captive supply of REACH-compliant inputs insulates margin from SIEF data-sharing disputes and registration update costs. |
| Microreactor Continuous Flow Synthesis | Modular production units in German coating clusters compress minimum order quantities and accelerate specialty shade development cycles. |
| REACH Dossier Maintenance Infrastructure | Regulatory affairs depth preserves qualified supplier status as ECHA's arylamine assessment work program tightens authorization timelines. |
| Local Technical Service Deployment | Brazilian field engineering capabilities unlock São Paulo textile clusters where acid stable blue adoption remains underpenetrated. |
| Liquid Dispersion Format Expansion | Pre-milled pigment suspensions capture premium positioning in Indian textile mills adopting low-pH exhaustion cycles. |
Research Methodology
Multiple input streams—structured interviews with pigment plant managers, procurement leads at German coating formulators, distribution channel partners in Indian textile clusters, and technical R&D directors at integrated azo pigment houses—were reconciled against secondary validation from customs and trade data, Cefic industry reports, SEC 10-K filings, and ECHA registration databases. Bottom-up volume modeling across powder, liquid, granule, and paste formulation tiers was triangulated with top-down value estimates derived from coating and textile dyeing application spending patterns.
Data-stream reconciliation anchored the analytical framework across the projection horizon, with segmentation modeling spanning product type, application environment, end-use industry regulatory exposure, and regional production hub. CAGRs were derived from trend extrapolation of REACH compliance-driven procurement shifts and petrochemical feedstock cost trajectories, incorporating acid dye compatibility testing adoption rates and automated ink delivery system penetration as industry-specific forecast inputs.
Underlying measurement precision varies by segment; coating applications with consolidated automotive refinish procurement carry tighter precision than fragmented Brazilian textile dye house estimates. Forecasts reflect assumptions regarding ECHA authorization timelines, MEE wastewater enforcement continuity, and phthalic anhydride supply stability. A model refresh is warranted upon material change in EU Green Deal chemical hazard reclassification velocity or SIEF data-sharing dispute resolution patterns affecting arylamine intermediate availability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
Europe Hair Colorants Market
Dyes and Pigments
Material Color Matching Booth Market
Dyes and Pigments
Hair Colorants Market
Dyes and Pigments
Arylamide Pigments Market
Dyes and Pigments
Inorganic Color Pigments Market
Dyes and Pigments
North America Hair Colorants Market
Dyes and Pigments
Riboflavin Pigment Market
Dyes and Pigments
Bismuth Vanadate Pigment Market
Dyes and Pigments
Colorants Market
Dyes and Pigments
Phosphorescent Pigments Market
Dyes and Pigments
Indigo Carmine Market
Dyes and Pigments
Synthetic Dyes Market
Dyes and Pigments
Special Effect Pigments Market
Dyes and Pigments
Dyestuff (Black Color) Market
Dyes and Pigments
Global Aluminum Anodizing Dyes Market
Dyes and Pigments
Pearlescent Pigments Market