
 Potential Hydrogen (Ph) Adjusters Market | 2026-2036
Potential Hydrogen (Ph) Adjusters Market Size, Share, and Industry Trends Forecast 2026-2036
Potential Hydrogen (Ph) Adjusters Market Analytics
Subscription-based digital dosing platforms is recalibrating how pH adjuster vendors monetize hardware deployments. BASF leverages its integrated chemical manufacturing footprint to bundle adjuster formulations with sensor-based monitoring services. Novozymes anchors its position through biological acidifier portfolios that reduce mineral acid dependency in agricultural applications. Evonik Industries differentiates via specialty silica-based buffer systems for precision chemical processing.
Potential Hydrogen adjusters comprise acidic or alkaline compounds—typically mineral acids, organic acids, caustic soda, or ammonia derivatives—formulated to shift or stabilize aqueous solution pH within specified tolerance bands, often measured against NIST-traceable reference standards. Liquid acids dominate volume throughput in water treatment and chemical processing, while solid acidifiers gain traction in controlled-release agricultural applications where soil pH management demands gradual alkalinity neutralization. The food industry segment commands premium positioning, as beverage manufacturers require food-grade certified adjusters with documented purity thresholds and batch-level traceability.
EPA effluent limitation guidelines and EU REACH chemical registration requirements are tightening purity documentation and environmental release thresholds for pH conditioning agents. FDA food additive regulations and FSSC 22000 certification protocols shape formulation choices and supplier qualification pathways for beverage manufacturers. ISO 9001 quality management and ISO 14001 environmental compliance have become baseline vendor selection criteria across industrial procurement functions. Stakeholders must weigh captive blending investments against third-party supply security as regulatory documentation burdens intensify.
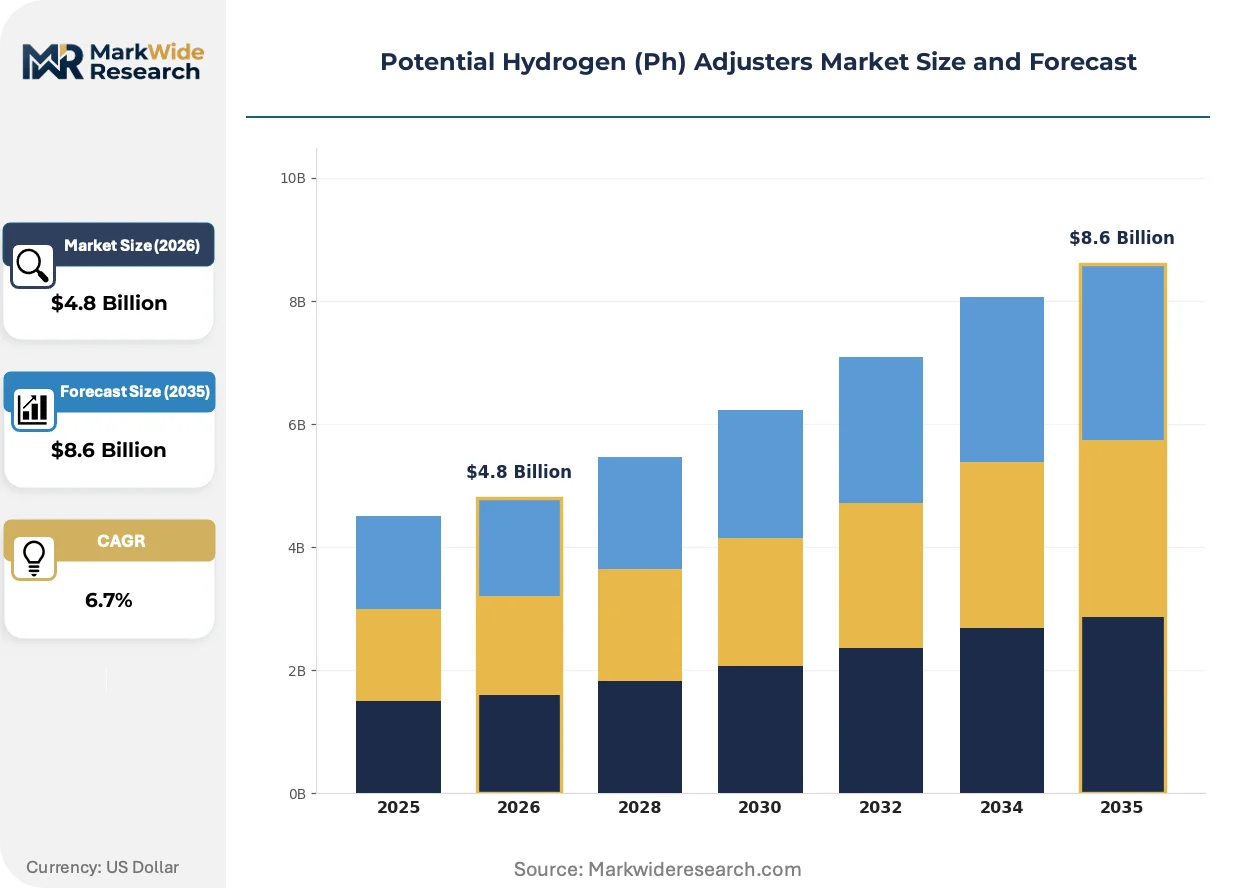
Market Dynamics
Water treatment infrastructure upgrades and tightening effluent standards are compressing pH tolerance bands across municipal and industrial discharge points, forcing facilities to expand buffer capacity and upgrade dosing precision.
Growth Catalysts
- EU REACH chemical registration:Tighter purity documentation requirements for pH conditioning agents are accelerating qualified supplier consolidation among European chemical processors seeking compliant acidifier sources.
- German chemical processing clusters:Concentrated demand from Rhineland industrial corridors drives bulk mineral acid consumption for neutralization and process control applications.
- Sensor-based monitoring integration:Real-time pH telemetry is automating dosing cycles in municipal water treatment, reducing manual intervention and chemical overfeed.
Market Restraints
- Caustic soda price volatility:Energy-intensive chlor-alkali production exposes alkaline adjuster margins to natural gas and electricity cost swings.
- Mineral acid supply concentration:Sulfuric and hydrochloric acid production clusters in coastal China and the US Gulf Coast create geographic vulnerability for European formulators.
- Biological acidifier efficacy limits:Organic acid alternatives from fermentation lack the titration strength for heavy industrial neutralization, restricting substitution in chemical processing.
Strategic Opportunities
- India municipal water expansion:Smart Cities Mission funding is accelerating pH control infrastructure deployment across secondary and tertiary treatment plants in Maharashtra and Gujarat.
- Controlled-release agricultural acidifiers:Solid-form pH adjusters with polymer encapsulation address gradual soil alkalinity neutralization in precision farming applications.
- EU Green Deal industrial decarbonization incentives:Carbon border adjustment mechanisms favor low-emission acidifier production pathways, rewarding electrolytic and bio-based process investments.
Industry Challenges
- FSSC 22000 certification timelines:Food-grade adjuster qualification requires 12-18 month documentation cycles that delay supplier onboarding for beverage manufacturers.
- Legacy dosing system integration:Analog pH control infrastructure in aging municipal plants creates friction when retrofitting digital sensor networks and automated feedback loops.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Potential Hydrogen (Ph) Adjusters Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Acids, Solid Acidifier, Liquid Bases, Solid Base Application: Agriculture, Water Treatment, Chemical Processing, Food Industry End User: Farmers, Water Treatment Plants, Beverage Manufacturers, Chemical Manufacturers Distribution Channel: Direct Sales, Online Retail, Wholesalers, Distributors |
| Companies Covered | Chr. Hansen Holding A/S, DSM, DuPont, Evonik Industries, BASF, Land O'Lakes, Novozymes, Lesaffre, Alltech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Potential Hydrogen (Ph) Adjusters Market Evolving Landscape
Digital dosing platforms and biological formulation advances are restructuring how pH adjuster vendors capture value, shifting revenue models from commodity chemical supply toward integrated process control services.
Electrochemical pH sensors with IoT connectivity are automating closed-loop dosing in municipal water treatment facilities. US utilities operating under EPA effluent limitation guidelines are deploying these systems fastest, with early adopters in California and Texas cutting chemical overfeed by enabling real-time titration adjustments. This compression of manual intervention is reducing labor costs while tightening discharge compliance.
EU REACH framework amendments are expanding substance evaluation obligations for pH conditioning agents used in industrial effluent. The regulatory burden falls heaviest on small and mid-sized formulators lacking dedicated compliance teams, pushing them toward third-party registration consortiums. German chemical processors are responding by consolidating supplier lists to partners with pre-validated dossiers.
Beverage manufacturers are unbundling pH adjuster procurement from equipment service contracts, reversing decade-old bundled supply arrangements. Large-scale bottlers in North America and Western Europe now negotiate chemical supply separately from sensor calibration and maintenance, pressuring vendors to compete on documented purity thresholds rather than installed base relationships. This disaggregation is most advanced in carbonated soft drink production where batch-level traceability commands premium positioning.
Potential Hydrogen (Ph) Adjusters Market Segmentation
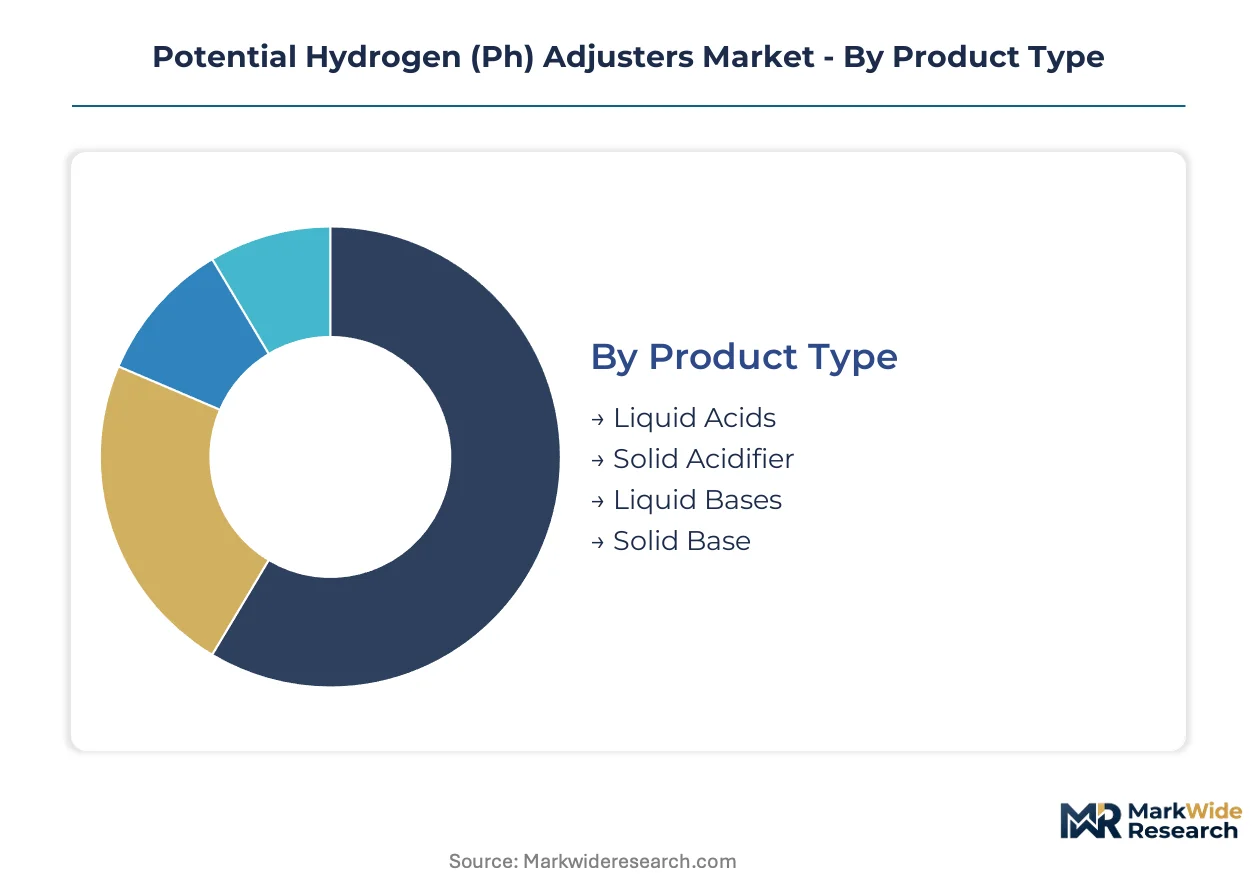
pH adjuster procurement splits across formulation states, application rigor, and certification tiers. Each segment carries distinct documentation burdens and margin structures that reshape vendor qualification pathways.
Product Type:
FDA food additive regulations and EPA effluent guidelines impose tiered purity thresholds that segment liquid from solid formulations.
- Liquid Acids:Mineral acid solutions—sulfuric, hydrochloric, nitric—deliver immediate titration strength for industrial neutralization. Municipal water treatment plants in Texas and California deploy these for real-time pH correction under tightening EPA discharge limits. Energy-intensive production clusters on the US Gulf Coast and coastal China shape supply security calculations.
- Solid Acidifier:Granular or encapsulated organic acids, often citric or sulfamic-based, enable controlled-release alkalinity neutralization. Precision farming operations in Germany's Rhineland corridor favor these for gradual soil pH management without mineral acid runoff. Polymer encapsulation adds formulation cost but reduces application frequency.
- Liquid Bases:Caustic soda and ammonia derivative solutions dominate chemical processing neutralization loops.
- Solid Base:Pelletized alkaline compounds serve specialized applications requiring dry handling and extended shelf stability.
Leading the category by volume: Liquid Acids. Growing fastest: Solid Acidifier.
Application:
End-use environments determine whether FSSC 22000, ISO 14001, or REACH compliance dominates procurement criteria.
- Water Treatment:Municipal and industrial discharge facilities deploy pH adjusters to meet EPA effluent limitation guidelines and EU urban wastewater directives. Smart Cities Mission funding in Maharashtra and Gujarat is accelerating infrastructure deployment across India's secondary treatment plants.
- Food Industry:Beverage manufacturers require food-grade certified adjusters with batch-level traceability under FDA 21 CFR and FSSC 22000 protocols. Carbonated soft drink producers unbundle chemical supply from equipment service contracts, intensifying purity-based competition.
- Agriculture:Soil amendment and irrigation water conditioning drive demand for biological and mineral acid alternatives.
- Chemical Processing:Neutralization loops and process control applications in Germany's industrial corridors consume bulk mineral acids.
Dominant by revenue: Water Treatment. Steepest expansion trajectory: Food Industry.
End User:
Customer scale and technical sophistication fragment procurement patterns across analog and digitally integrated dosing systems.
- Water Treatment Plants:Municipal utilities automate pH control through electrochemical sensors with IoT connectivity, reducing chemical overfeed. Legacy analog infrastructure in aging US facilities creates retrofit friction when integrating digital feedback loops.
- Beverage Manufacturers:Large-scale bottlers negotiate chemical supply separately from sensor calibration contracts, reversing bundled arrangements. Batch-level documentation requirements extend supplier qualification timelines to 12-18 months.
- Farmers:Price-sensitive agricultural operators favor solid-form acidifiers with gradual release profiles.
- Chemical Manufacturers:Process-intensive neutralization demands drive bulk acid and base consumption.
Highest volume concentration: Water Treatment Plants. Procurement sophistication climbing fastest: Beverage Manufacturers.
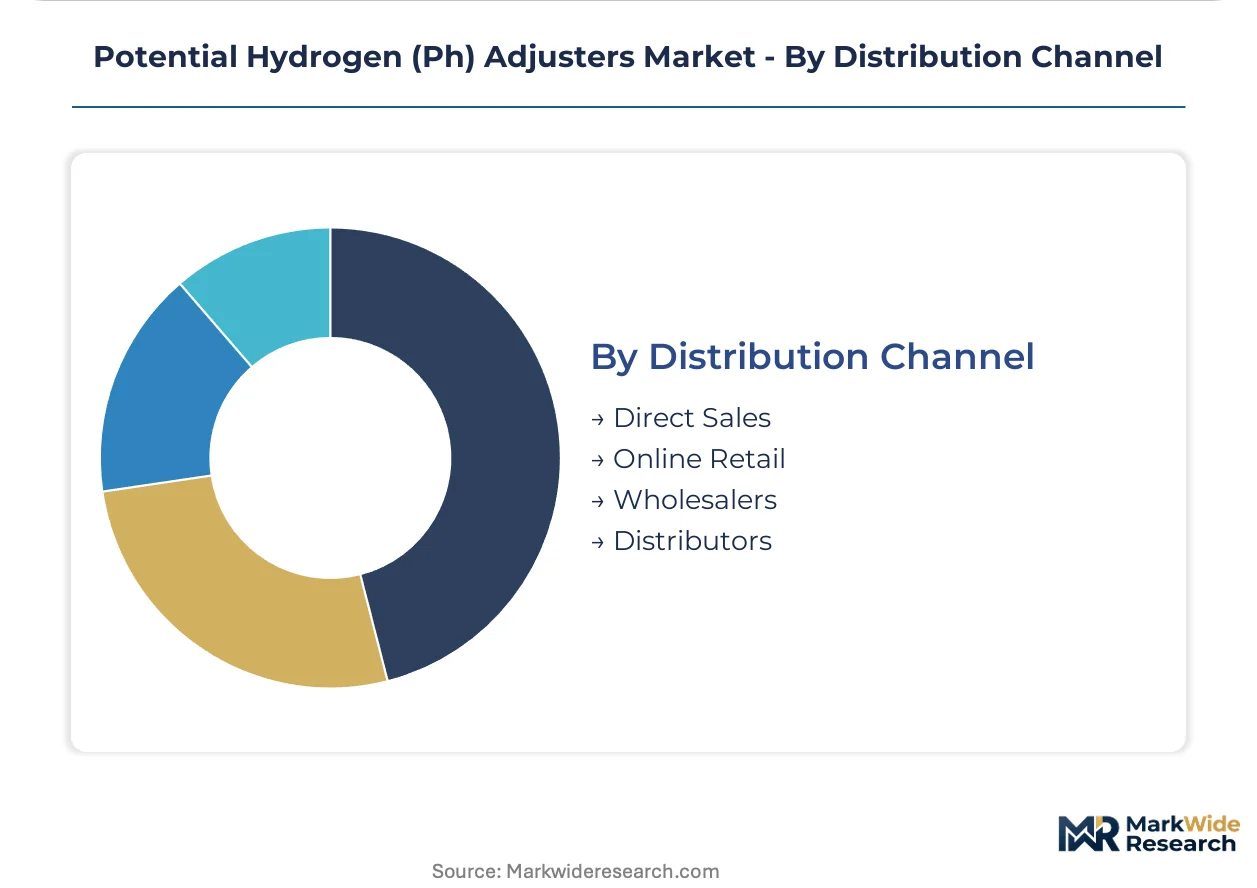
Distribution Channel:
Channel selection reflects customer technical support needs and regulatory documentation intensity.
- Direct Sales:Large water utilities and chemical processors procure through vendor technical service agreements. BASF and Evonik leverage integrated manufacturing footprints to bundle adjuster supply with sensor-based monitoring.
- Distributors:Regional chemical distributors hold inventory for mid-sized municipal plants requiring rapid replenishment.
- Wholesalers:Agricultural supply cooperatives aggregate solid acidifier volumes for farming operations.
- Online Retail:Small-scale agricultural and specialty food producers access certified adjusters through e-commerce platforms.
Channel commanding highest margin: Direct Sales. Expanding most quickly: Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr corridor anchors European pH adjuster consumption, with chemical processing clusters in Duisburg and Leverkusen driving bulk mineral acid demand for neutralization loops and process control applications.
United States
Municipal utilities in California and Texas deploy electrochemical pH sensors with IoT connectivity to automate dosing cycles under EPA effluent limitation guidelines. The US Gulf Coast hosts concentrated sulfuric and hydrochloric acid production capacity. Water treatment facilities in Houston and Los Angeles retrofit aging analog infrastructure with digital feedback loops to tighten discharge compliance.
Germany
Rhineland industrial corridors concentrate demand for bulk acidifiers in chemical neutralization and process control. EU REACH chemical registration requirements accelerate qualified supplier consolidation among European formulators. BASF leverages its integrated manufacturing footprint in Ludwigshafen to bundle adjuster formulations with sensor-based monitoring services.
China
Coastal chlor-alkali production clusters supply caustic soda for alkaline adjuster formulations, though energy-intensive operations expose margins to electricity cost swings. MEE discharge standards tighten permissible pH ranges for industrial effluent. Yangtze River Delta chemical processors expand buffer capacity to meet stricter environmental release thresholds.
India
Smart Cities Mission funding accelerates pH control infrastructure deployment across secondary and tertiary treatment plants in Maharashtra and Gujarat. BIS certification requirements shape supplier qualification pathways for municipal procurement. Water utilities in Mumbai and Ahmedabad install automated dosing systems to reduce manual intervention and chemical overfeed.
Potential Hydrogen (Ph) Adjusters Market Competitive Landscape
Capital-heavy producers compete with asset-light formulation specialists across the pH adjuster value chain. The vendor base fragments between integrated chemical manufacturers, biological acidifier developers, and regional blending operations. Three strategic archetypes dominate: diversified chemical conglomerates bundling hardware and chemistry, fermentation-based specialists reducing mineral acid dependency, and precision buffer system developers serving pharmaceutical and food-grade applications. Competitive moves concentrate on sensor integration partnerships and captive blending investments to secure supply security amid documentation burden intensification.
Among diversified chemical conglomerates, BASF and Evonik Industries occupy positions that exemplify the integrated-manufacturing archetype, leveraging captive production footprints to bundle adjuster supply with process monitoring services. Novozymes represents the biological formulation specialist tier, anchoring market presence through fermentation-derived acidifier portfolios. These three companies collectively illustrate how competitive positioning splits between scale-driven chemical production and biotechnology-enabled substitution strategies.
| Leading Market Players |
|---|
| Chr. Hansen Holding A/S |
| DSM |
| DuPont |
| Evonik Industries |
| BASF |
| Land O'Lakes |
| Novozymes |
| Lesaffre |
| Alltech |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap formulators in Germany's Rhineland corridor anchor supply discipline through captive blending investments, insulating pricing power from commodity volatility while compressing margins for distributors lacking backward integration into mineral acid production.
Pricing Analysis
Throughput-linked pricing anchors value capture for integrated vendors bundling pH adjusters with sensor calibration services. Three-tier pricing structure across food-grade certified, industrial-grade, and agricultural-grade tiers separates beverage manufacturers willing to absorb FSSC 22000 documentation premiums from price-sensitive municipal utilities. Pricing pressure stems from caustic soda feedstock volatility tied to European natural gas benchmarks. Municipal water treatment plants exhibit highest price sensitivity due to fixed-rate tariff structures, while pharmaceutical buffer system buyers show lowest sensitivity given batch failure costs.
Supply Chain Analysis
Empty container return flows and acidifier drum refurbishment networks reduce packaging costs for liquid mineral acid distributors serving repeat municipal customers. Production gravity centers on the US Gulf Coast, coastal China, and Germany's Ludwigshafen complex for sulfuric and hydrochloric acid supply. Feedstock dependency rests on chlor-alkali electrolysis capacity for caustic soda and sulfur combustion for acid production. Single-source vulnerability concentrates around Chinese coastal acid clusters exposed to MEE environmental enforcement actions. Distribution runs through direct technical service agreements for large chemical processors and regional distributors for mid-sized municipal plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chlor-alkali capacity constraints in Europe prop pricing discipline for alkaline adjusters, with electrolytic production bottlenecks limiting supply elasticity across the forecast window.
For Market Incumbents: Hedge caustic soda margin exposure through long-term offtake contracts with Gulf Coast chlor-alkali producers. Deepen backward integration into sulfuric acid production or secure tolling arrangements with Rhineland refiners to defend position against Chinese import volatility. Prioritize FSSC 22000 certification maintenance to preserve food-grade pricing premiums as beverage manufacturers consolidate supplier lists. For New Entrants and Emerging Players: Begin with solid acidifier encapsulation technology for precision farming applications in Germany and the Netherlands, where gradual-release soil pH management commands price premiums unavailable in commodity liquid acid markets. Target agricultural supply cooperatives as channel partners to bypass capital-intensive direct sales infrastructure. Lead with polymer-encapsulated citric acid formulations to differentiate from mineral acid incumbents. For Investors and Strategic Acquirers: Distressed-cycle entries favor biological acidifier specialists with validated fermentation platforms in Denmark and the Netherlands, where Novozymes and DSM have demonstrated scalable organic acid production. Monitor EU REACH substance evaluation timelines as inflection signals—accelerated registration burdens will force small-formulator consolidation, creating acquisition opportunities for buyers with pre-validated dossiers. Long-term viability hinges on carbon border adjustment mechanism positioning favoring low-emission production pathways.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sulfuric Acid Production | Captive supply from Ludwigshafen or Gulf Coast refineries insulates margins from Chinese import volatility. |
| Sensor-Based Monitoring Service Bundling | BASF's integrated hardware-chemistry packages lock in municipal utility customers through subscription contracts. |
| FSSC 22000 Certification Investment | Twelve-month qualification timelines create switching costs that protect food-grade pricing premiums. |
| Controlled-Release Encapsulation R&D | Polymer-encapsulated solid acidifiers open precision farming segments unavailable to liquid mineral acid competitors. |
| EU REACH Registration Consortium Participation | Shared dossier costs reduce compliance burdens for mid-sized formulators lacking dedicated regulatory teams. |
Research Methodology
Document review covered customs/trade data, SEC 10-K filings from chemical conglomerates, and EU REACH registration databases, complemented by interviews with municipal water utility procurement managers, beverage manufacturer technical directors, and agricultural supply cooperative buyers. Primary fieldwork included discussions with plant managers at Rhineland chemical processing facilities and distribution channel partners serving secondary treatment plants. Secondary validation drew from EPA effluent limitation guidelines, FDA food additive regulations, and Cefic industry reports. Bottom-up volume modeling triangulated against top-down chemical consumption benchmarks.
Historical consumption patterns cross-referenced against panel input from procurement executives anchored demand projections across the analysis window. Segmentation dimensions modeled include formulation state, application rigor, certification tier, and regional regulatory cluster. CAGRs derived from weighted average of historical trajectory and expert-informed inflection assumptions. Industry-specific inputs incorporated chlor-alkali capacity utilization rates and Smart Cities Mission infrastructure deployment schedules.
Underlying measurement precision varies by segment; food-grade certified adjusters with batch-level traceability carry tighter precision than commodity industrial grades due to documented purity thresholds. Forecasts reflect assumptions about REACH enforcement intensity and municipal infrastructure funding continuity. Practitioners should monitor EU carbon border adjustment mechanism implementation and MEE discharge standard revisions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemical Intermediates
Epoxy Silanes Market
Chemical Intermediates
Glycidyl Methacrylate Market
Chemical Intermediates
Thioesters Market
Chemical Intermediates
Acetamide MEA Market
Chemical Intermediates
Thiochemicals Market
Chemical Intermediates
Molybdenum Disulfide (MoS2) Market
Chemical Intermediates
US Acids Market
Chemical Intermediates
Global Etoricoxib Intermediate Market
Chemical Intermediates
Cytosine Market
Chemical Intermediates
API Intermediate Market
Chemical Intermediates
Leather Chemicals Market
Chemical Intermediates
2-Acetylthiophene Market
Chemical Intermediates
Ph Controlling Agents Market
Chemical Intermediates
Natural Chelating Agents Market
Chemical Intermediates
Octenylsuccinate Market
Chemical Intermediates
Diethyl Phthalate Market