
 Acetoacetanilide Market | 2026-2036
Acetoacetanilide Market Size, Share, and Industry Trends Forecast 2026-2036
Acetoacetanilide Market Analysis
Specialized organic synthesis chemist availability is bifurcating competitive capacity across the acetoacetanilide supply base. Eastman Chemical Company leverages its integrated ketene chemistry infrastructure to sustain captive intermediate supply for pigment customers. Laxmi Organic Industries Ltd anchors South Asian supply through dedicated acetoacetarylide manufacturing lines serving regional dye houses. Mitsuboshi Chemical Co., Ltd. differentiates via pharmaceutical-grade purification protocols that command specification premiums in regulated end-uses.
Acetoacetanilide is an organic compound with the formula C10H11NO2, synthesized via the condensation of aniline with diketene or ethyl acetoacetate, serving as a critical coupling component for azo pigments and pharmaceutical intermediates. The powder product type dominates volume throughput due to handling efficiency in bulk pigment manufacturing, while liquid formulations capture specialized coating and inkjet ink applications requiring metered dosing precision. Dyes application leads absolute consumption, though pharmaceutical intermediates represent the fastest-expanding margin pool as API manufacturers tighten starting material traceability under pharmacopeial standards.
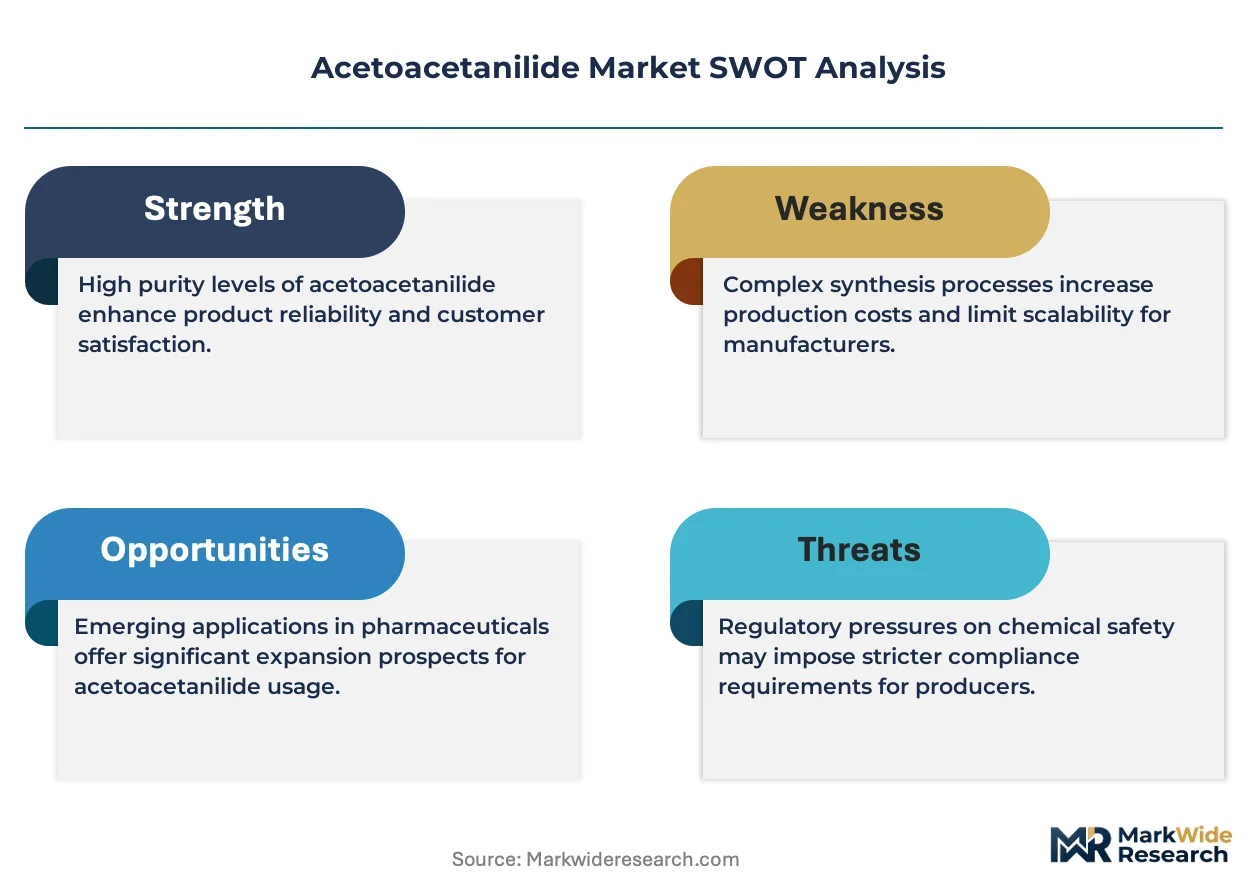
EPA chemical safety evaluations under the Toxic Substances Control Act and REACH substance registration requirements in Europe constrain market access for uncertified producers while elevating compliance costs for incumbent suppliers. China's SAMR and GB standards enforcement around hazardous chemical production licensing further shape capacity expansion feasibility and cross-border trade flows. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate qualification burden shifts and reposition supply chain footprints accordingly.
Market Dynamics
REACH substance registration requirements and EPA Toxic Substances Control Act evaluations are tightening purity specifications faster than legacy suppliers can reformulate, forcing qualification-driven consolidation among azo pigment coupling component manufacturers.
Growth Catalysts
- Textile colorant formulator expansion:Jiangsu and Zhejiang province chemical clusters are scaling azo pigment output for synthetic fiber dyeing, pulling acetoacetanilide demand through dedicated offtake agreements with regional manufacturers.
- Pharmaceutical-grade specification premiums:API manufacturers under pharmacopeial standards are tightening starting material traceability, creating specification-tier pricing power for purified acetoacetanilide lots.
- GB standards enforcement:China's SAMR hazardous chemical production licensing is accelerating facility consolidation, concentrating compliant capacity among licensed producers serving export markets.
Market Restraints
- Aniline feedstock volatility:Crude oil-linked benzene derivatives expose acetoacetanilide margins to petrochemical price swings without effective hedging instruments for mid-scale producers.
- Ketene chemistry infrastructure concentration:Captive diketene supply chains at integrated chemical parks in eastern China create supply security risks for non-integrated Western formulators.
- Substitution pressure from pyrazolone coupling components:Yellow azo pigment chemistries in select coating applications are displacing acetoacetanilide-based formulations where lightfastness requirements permit.
Strategic Opportunities
- Pharmaceutical intermediate traceability mandates:US FDA and EMA starting material qualification pathways reward suppliers with documented impurity profiling and certificate-of-analysis standardization.
- Inkjet ink metered dosing precision requirements:Liquid acetoacetanilide formulations are capturing share in digital textile printing systems requiring controlled droplet deposition chemistry.
- Backward integration into diketene:Regional dye houses in India and Southeast Asia are evaluating captive acetoacetanilide synthesis to secure coupling component supply against Chinese export quota uncertainty.
Industry Challenges
- Specialized organic synthesis chemist scarcity:Ketene handling expertise and aniline condensation process control knowledge are concentrating at legacy chemical parks, constraining greenfield facility staffing.
- Cross-jurisdictional qualification burden divergence:Suppliers must maintain parallel compliance documentation for EPA TSCA Section 5 notifications, REACH registration dossiers, and China GB standard testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acetoacetanilide Market |
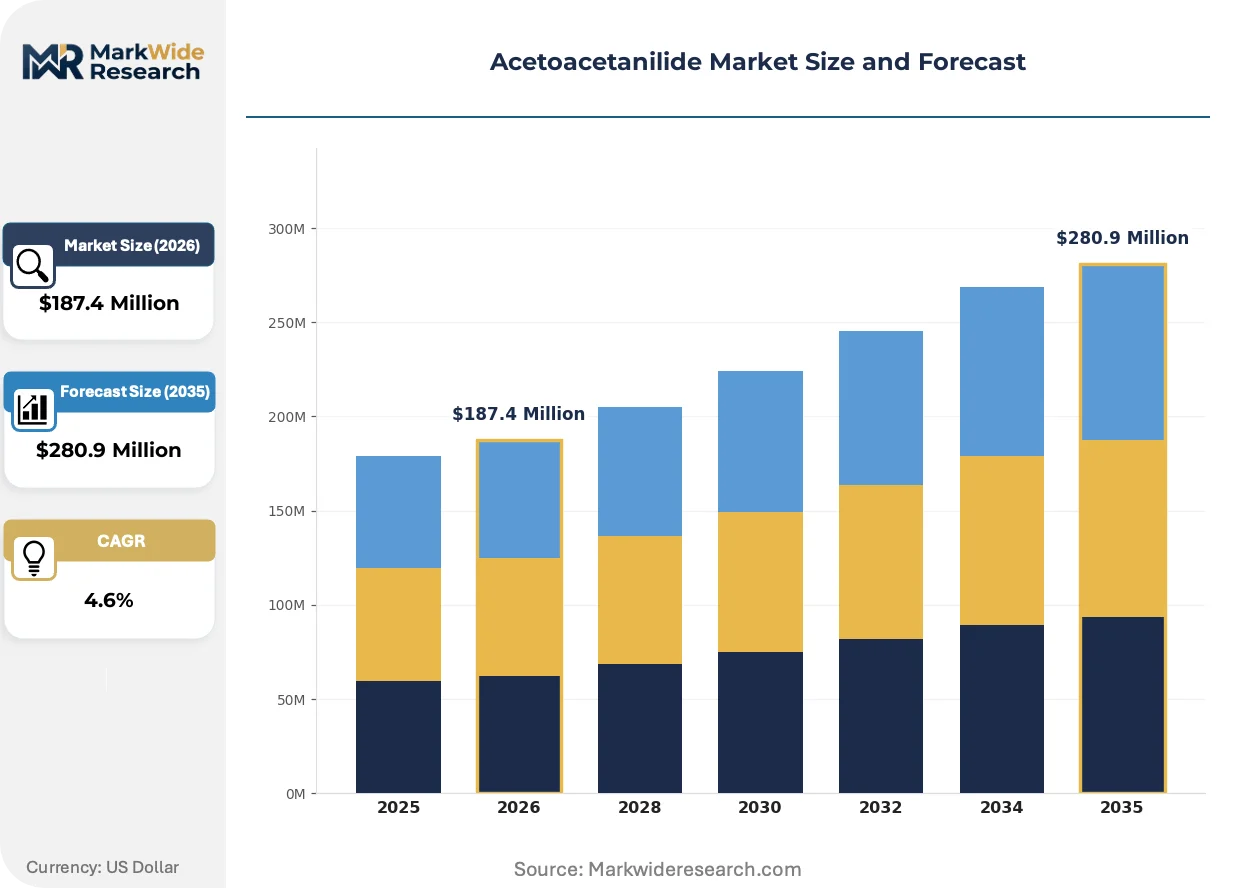
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $280.9 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular, Powder, Liquid, Crystalline Application: Dyes, Pharmaceuticals, Agrochemicals, Intermediates End User: Chemical Manufacturers, Textile Industry, Agriculture Sector, Healthcare Providers Distribution Channel: Direct Sales, Distributors, Online Retail, Third-Party Vendors |
| Companies Covered | Cangzhou Goldlion Chemicals Co., Ltd, Laxmi Organic Industries Ltd, Eastman Chemical Company, Thermo Fisher Scientific Inc., MilliporeSigma, Mitsuboshi Chemical Co., Ltd., Jiangsu Changyu Chemical Co., Ltd., Clariant AG, Nantong Acetic Acid Chemical Co. Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acetoacetanilide Market Emerging Trajectories
Process intensification and regulatory data requirements are restructuring how acetoacetanilide manufacturers compete on specification depth rather than commodity scale.
Continuous flow diketene-aniline condensation systems are replacing batch kettle operations in advanced pigment intermediate plants. Pharmaceutical and high-performance coating formulators are qualifying these outputs for impurity profile consistency. This manufacturing shift is bifurcating the supply base between specification-capable producers and commodity-scale competitors.
REACH Annex XVII restrictions on aromatic amine releases are tightening wastewater discharge standards for azo pigment coupling operations. German and Dutch chemical parks are retrofitting acetoacetanilide lines with closed-loop solvent recovery. Pigment manufacturers serving EU textile markets are consolidating supplier relationships around REACH-registered producers with documented environmental release controls.
API manufacturers are unbundling starting material procurement from traditional chemical distributor channels. Direct qualification relationships with acetoacetanilide producers are replacing multi-tier sourcing for pharmacopeial-grade lots. This pattern concentrates most visibly in US and European generic drug manufacturing hubs where FDA Drug Master File requirements mandate supplier-specific impurity characterization.
Acetoacetanilide Market Segmentation
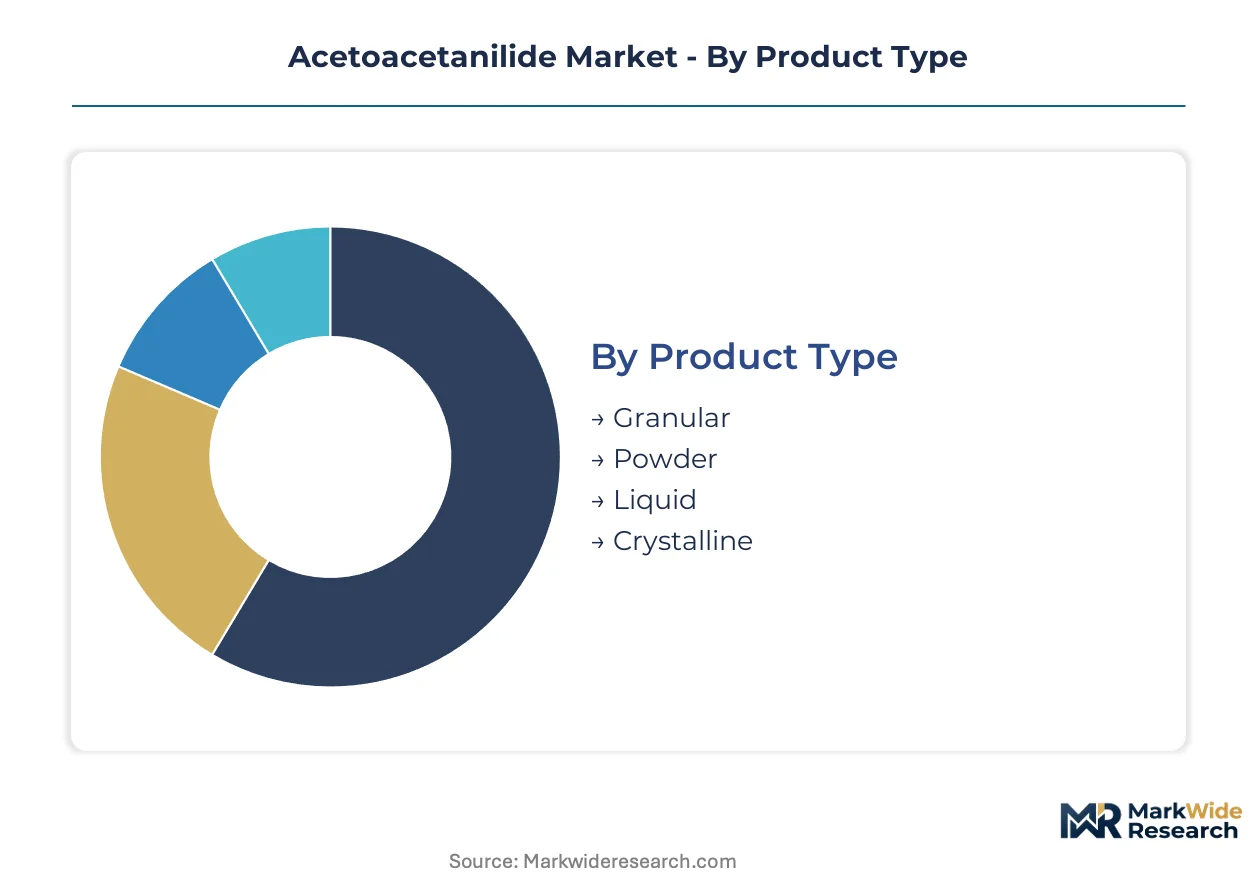
Acetoacetanilide specifications diverge sharply across end-use requirements, with pharmaceutical and pigment applications demanding incompatible purity tiers. Segmentation strategy determines qualification pathways, pricing power, and regulatory documentation burdens for suppliers.
Product Type:
REACH registration dossiers and FDA Drug Master File requirements enforce distinct purity specifications across physical forms, fragmenting supplier capabilities by certification tier.
- Powder:Fine particulate morphology optimizes bulk handling efficiency in azo pigment manufacturing at Jiangsu and Zhejiang chemical clusters. Textile colorant formulators specify powder grades for high-throughput coupling reactions where metered dispersion controls pigment particle size distribution.
- Liquid:Solution formulations enable precise dosing in digital textile printing systems and inkjet ink manufacturing. Coating formulators in regulated European markets specify liquid acetoacetanilide for applications requiring controlled droplet deposition chemistry and reduced airborne particulate exposure.
- Granular:Free-flowing agglomerated particles reduce dust generation during bulk transfer operations. Agrochemical intermediate producers favor granular grades for handling safety in open-system synthesis.
- Crystalline:High-purity recrystallized material meets pharmacopeial standards for API starting material qualification. Pharmaceutical manufacturers require crystalline lots with documented impurity profiling under USP and EP monographs.
Powder handles the majority of throughput; liquid is the fastest mover on share.
Application:
Margin structures stratify by qualification depth, with pharmaceutical intermediates commanding specification premiums unavailable to commodity dye applications.
- Dyes:Dominant consumption channel serving azo pigment synthesis for synthetic fiber coloration. REACH Annex XVII aromatic amine restrictions tighten wastewater discharge standards for coupling operations in German and Dutch chemical parks.
- Pharmaceuticals:API starting material qualification under FDA and EMA pathways rewards suppliers with certificate-of-analysis standardization. Generic drug manufacturers in US and European hubs are unbundling procurement from distributor channels for direct producer relationships.
- Agrochemicals:Intermediate consumption in herbicide and fungicide synthesis. Formulators prioritize cost-efficient powder grades where pharmacopeial traceability is not mandated.
- Intermediates:Captive consumption for downstream acetoacetarylide manufacturing. Regional dye houses in India evaluate backward integration to secure coupling component supply.
Dyes anchor absolute volume; pharmaceuticals are climbing the fastest on margin contribution.
End User:
Procurement sophistication varies by sector, with healthcare providers and chemical manufacturers maintaining divergent supplier qualification protocols.
- Chemical Manufacturers:Integrated pigment intermediate producers with captive diketene supply chains at eastern China chemical parks. These buyers consolidate offtake around REACH-registered producers with documented environmental release controls.
- Textile Industry:Synthetic fiber dye houses scaling azo pigment output through dedicated regional supply agreements. Jiangsu and Zhejiang province clusters dominate both consumption and intermediate production.
- Agriculture Sector:Agrochemical formulators sourcing standard-grade material for pesticide intermediate synthesis. Price sensitivity drives procurement through distributor channels rather than direct producer relationships.
- Healthcare Providers:Pharmaceutical manufacturers requiring pharmacopeial-grade material with impurity characterization for FDA Drug Master File submission. These buyers mandate supplier-specific documentation unavailable from commodity distributors.
Chemical manufacturers absorb the dominant share of volume; healthcare providers are expanding most quickly on specification-premium capture.
Distribution Channel:
Channel selection reflects end-use regulatory intensity, with direct sales displacing intermediaries in qualification-heavy applications.
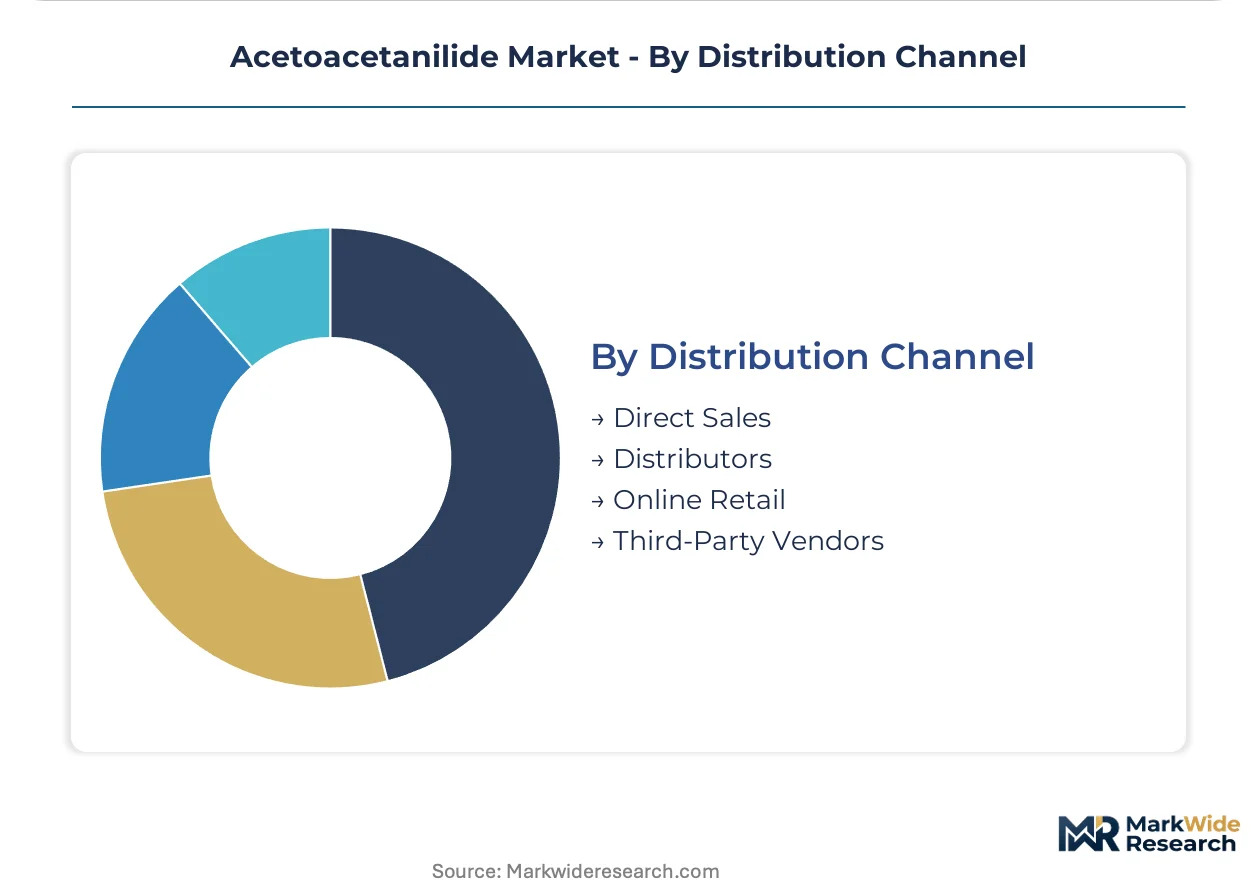
- Direct Sales:Producer-to-manufacturer relationships enabling documented traceability for pharmaceutical and EU textile markets. API manufacturers and REACH-compliant pigment formulators require this channel for supplier-specific impurity characterization.
- Distributors:Multi-tier chemical distribution serving agrochemical and standard dye applications where qualification documentation is less stringent. Regional distributors in India and Southeast Asia aggregate demand from fragmented dye house customers.
- Online Retail:Digital procurement platforms capturing small-volume laboratory and research chemical demand. Limited penetration in bulk industrial applications due to specification verification requirements.
- Third-Party Vendors:Independent traders facilitating spot market transactions for non-integrated formulators facing supply security risks from Chinese export quota uncertainty.
Direct sales command the dominant revenue share; online retail is gaining traction fastest in specialty chemical procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SAMR enforcement of GB standards on hazardous chemical production licensing is consolidating acetoacetanilide capacity within China's eastern chemical parks. This regulatory tightening is reshaping trade flows and supplier qualification requirements across major consuming regions.
China
Jiangsu and Zhejiang province clusters dominate both acetoacetanilide output and downstream azo pigment consumption for synthetic fiber dyeing. SAMR hazardous chemical production licensing is accelerating facility consolidation, concentrating compliant capacity among licensed producers serving export markets. Nantong and Changzhou chemical parks house integrated diketene supply chains that supply regional dye houses through dedicated offtake agreements.
United States
API manufacturers under FDA Drug Master File requirements are tightening starting material traceability, creating specification-tier demand for pharmacopeial-grade acetoacetanilide. EPA Toxic Substances Control Act evaluations constrain market access for uncertified producers while elevating compliance costs for incumbent suppliers. Texas and Louisiana chemical corridors host pigment intermediate distributors serving regional coating formulators.
Germany
REACH Annex XVII restrictions on aromatic amine releases are tightening wastewater discharge standards for azo pigment coupling operations. German chemical parks are retrofitting acetoacetanilide lines with closed-loop solvent recovery systems. Ludwigshafen and Leverkusen industrial zones concentrate REACH-registered producers with documented environmental release controls.
India
Regional dye houses in Maharashtra and Gujarat are evaluating backward integration into acetoacetanilide synthesis to secure coupling component supply against Chinese export quota uncertainty. CDSCO pharmaceutical regulations are tightening impurity profiling requirements for API starting materials. Ankleshwar and Vapi industrial estates host agrochemical intermediate producers sourcing standard-grade material through distributor channels.
Japan
PMDA pharmaceutical regulations mandate supplier-specific documentation for generic drug manufacturers seeking starting material qualification. METI industrial standards enforcement shapes chemical intermediate import protocols. Osaka and Kawasaki chemical ports handle specialized acetoacetanilide shipments for high-performance coating applications requiring controlled droplet deposition chemistry.
Acetoacetanilide Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the acetoacetanilide supply base. The upper tier commands specification premiums through captive ketene chemistry infrastructure and pharmacopeial-grade purification capabilities. The specialist tier competes on regional dye house relationships and batch-scale flexibility. Three archetypes define positioning: integrated chemical conglomerates with diketene backward integration, pharmaceutical-grade purification specialists, and regional pigment intermediate suppliers. Capacity expansion and direct qualification relationships with API manufacturers represent the dominant competitive moves reshaping supplier-customer linkages.
Among integrated chemical producers, Eastman Chemical Company and Mitsuboshi Chemical Co., Ltd. exemplify the premium-tier archetype through their positioning in regulated end-use segments. Laxmi Organic Industries Ltd anchors the South Asian specialist tier. Cangzhou Goldlion Chemicals Co., Ltd. and Jiangsu Changyu Chemical Co., Ltd. represent the China-based volume tier serving regional textile colorant clusters. These named entities illustrate how geographic concentration and certification depth stratify competitive positioning across the supply base.
| Leading Market Players |
|---|
| Cangzhou Goldlion Chemicals Co., Ltd |
| Laxmi Organic Industries Ltd |
| Eastman Chemical Company |
| Thermo Fisher Scientific Inc. |
| MilliporeSigma |
| Mitsuboshi Chemical Co., Ltd. |
| Jiangsu Changyu Chemical Co., Ltd. |
| Clariant AG |
| Nantong Acetic Acid Chemical Co. Ltd |
| Others |
Supply Flow & Price Mechanics
REACH registration dossiers and FDA Drug Master File requirements gate both supply qualification and price differentiation simultaneously, fragmenting the acetoacetanilide market into certification-tiered pricing bands where pharmacopeial-grade crystalline lots command substantial premiums over standard powder grades.
Pricing Analysis
Chinese export pricing for standard powder grades runs 15-25 percent below pharmacopeial crystalline quotations from European producers. Three-tier pricing structure across premium, standard, and economy levels separates REACH-registered pharmaceutical-grade suppliers from regional dye-house commodity producers. Cost compression in standard powder grades is intensifying because aniline feedstock volatility transmits directly through diketene condensation economics. Agrochemical formulators exhibit highest price sensitivity, while API manufacturers under FDA starting material mandates show lowest elasticity.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate landed costs for non-integrated Western formulators sourcing from Jiangsu and Zhejiang chemical parks. Supply concentrates in China, India, and Germany, with captive diketene infrastructure anchoring eastern Chinese capacity. The value chain draws from aniline, diketene, and ethyl acetoacetate feedstocks. Single-source vulnerability concentrates around ketene chemistry expertise at legacy chemical parks. Distribution runs through direct producer relationships for pharmaceutical applications and regional distributor networks for standard dye grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as API manufacturers unbundle procurement from distributor channels, creating niches for specification-capable suppliers with documented impurity profiling capabilities.
For Market Incumbents: Compound specification depth advantages by deepening ketene chemistry captive supply and securing REACH-registered status for environmental release controls. Pyrazolone coupling component substitution in coating applications threatens azo pigment demand; counter through pharmaceutical-grade purification protocol investments that command tiered pricing power unavailable to commodity competitors. For New Entrants and Emerging Players: Anchor in liquid formulation capabilities for inkjet ink metered dosing applications where digital textile printing growth outpaces traditional dye house saturation. Southeast Asian dye houses evaluating backward integration present the most penetrable entry point; pursue toll manufacturing arrangements with regional chemical parks lacking ketene handling expertise. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across continuous flow diketene-aniline condensation systems as process intensification reduces batch-scale labor dependencies. Over the medium-term horizon, target acquisition archetypes are mid-scale regional producers with SAMR-compliant licensing and unexploited pharmaceutical qualification pathways. Signal to monitor: FDA Drug Master File submission rates by non-integrated API starting material suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Diketene | Captive ketene chemistry supply secures margin control against Chinese export quota uncertainty. |
| Pharmaceutical-Grade Purification Investment | USP and EP monograph compliance enables specification-premium capture from generic drug manufacturers. |
| Continuous Flow Process Conversion | Process intensification at German and Dutch chemical parks reduces batch variability for REACH-registered outputs. |
| Direct Qualification Relationship Development | FDA starting material traceability mandates reward suppliers bypassing multi-tier distributor channels. |
| Regional Capacity Expansion in India | CDSCO regulatory alignment positions suppliers for API intermediate demand from Maharashtra and Gujarat hubs. |
Methodological Framework
A standing panel of pigment intermediate plant managers, API procurement leads at generic drug manufacturers, ketene chemistry R&D directors, and REACH regulatory affairs specialists provided ongoing calibration. Primary interview findings combined with customs trade data, Cefic sector reports, SEC chemical company filings, and SAMR hazardous chemical licensing records. Bottom-up capacity modeling and top-down demand segmentation triangulated volume estimates.
Consistency checks validated outputs against external benchmarks including diketene consumption patterns and azo pigment production indices. Segmentation dimensions spanned product form, application grade, end-use regulatory intensity, and regional production hub classification. CAGRs derived from slope analysis of year-over-year progression across the projection horizon. Forecast inputs incorporated aniline price elasticity coefficients and pharmaceutical qualification pathway completion rates.
Material uncertainties — aniline feedstock volatility, REACH Annex XVII enforcement intensity, and Chinese export licensing adjustments — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory stability and substitution technology penetration. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemical Intermediates
Pigment Intermediates Market
Chemical Intermediates
Pharmaceutical Intermediates Market
Chemical Intermediates
Copper Chemicals Market
Chemical Intermediates
Reagent Bottle Market
Chemical Intermediates
Palmitoyl Chloride Market
Chemical Intermediates
Global Biochemical Reagents Market
Chemical Intermediates
3-Chloropropionyl Chloride Market
Chemical Intermediates
Nickel Acetate Market
Chemical Intermediates
Ethylene Urea Market
Chemical Intermediates
Diethyl Phthalate Market
Chemical Intermediates
Global Glycinates Market
Chemical Intermediates
Global Electrophoresis Reagents Market
Chemical Intermediates
Global Chromatography Reagents Market
Chemical Intermediates
Potential Hydrogen (Ph) Adjusters Market
Chemical Intermediates
Butadiene Derivatives Market
Chemical Intermediates
Elemental Formula Market