
 Alpha Lipoic Acid Market | 2026-2036
Alpha Lipoic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Alpha Lipoic Acid Market Analysis
Microencapsulation technology is reshaping bioavailability profiles for alpha lipoic acid formulations, enabling sustained-release delivery that expands therapeutic applications. AlzChem Group AG leverages its German manufacturing base to anchor European pharmaceutical-grade supply. NOW Foods competes through vertical control over retail and online distribution channels. Olon S.p.A specializes in custom synthesis for branded ingredient partnerships.
Alpha lipoic acid is a disulfide-containing organosulfur compound synthesized in mitochondria, functioning as a cofactor for dehydrogenase enzymes and a potent water- and fat-soluble antioxidant. Powder formulations dominate bulk ingredient trade due to stability in controlled-atmosphere packaging and flexibility for downstream formulation. Dietary Supplements represents the largest application segment, though Pharmaceutical-grade material commands premium positioning due to USP and EP certification requirements. Online Retail channels are capturing share from pharmacies as subscription models and telehealth referrals redirect purchasing behavior.
The US FDA regulates alpha lipoic acid as a dietary ingredient under DSHEA with additional pharmaceutical oversight for drug applications, while China's NMPA enforces GB standards for imported raw materials. The European Medicines Agency monitors quality through EP monographs that influence supplier qualification across EU member states. Stakeholders must track evolving pharmacopeial harmonization between USP, EP, and ChP standards to secure multi-regional market access.
Market Dynamics
Microencapsulation technology is compressing formulation timelines for alpha lipoic acid, enabling sustained-release profiles that expand therapeutic applications beyond traditional antioxidant supplements. This technical shift is redistributing value capture toward contract manufacturers with particle engineering capabilities.
Growth Catalysts
- GB Standard Harmonization:China's NMPA has aligned import purity thresholds with EP monographs, reducing re-certification costs for multi-regional suppliers and accelerating raw material flow into domestic pharmaceutical channels.
- Direct-to-Consumer Subscription Models:Telehealth platforms in the United States are bundling alpha lipoic acid into metabolic health protocols, creating recurring revenue streams that bypass traditional pharmacy distribution.
- Clinical Trial Expansion:Investigator-initiated studies targeting diabetic neuropathy and neurodegenerative conditions are generating physician-level demand for pharmaceutical-grade material certified to USP standards.
Market Restraints
- R-Alpha Lipoic Acid Isomer Premium:The biologically active R-enantiomer requires stereoselective synthesis or enzymatic resolution, commanding 3-4x raw material cost over racemic mixtures and compressing margin for generic formulators.
- European API Concentration:Pharmaceutical-grade supply chains concentrate among German and Italian contract manufacturers, creating single-source vulnerability for buyers requiring EP certification.
- Thermal Degradation Constraints:Alpha lipoic acid's disulfide bond undergoes rapid oxidation above 40°C, necessitating cold-chain logistics for liquid formulations and limiting geographic reach without microencapsulation investment.
Strategic Opportunities
- Indian CDMO Partnerships:Underutilized fermentation capacity at Indian contract development organizations offers cost-competitive synthetic routes for racemic material serving dietary supplement demand.
- Nutraceutical-Pharma Convergence:USP-verified dietary supplements are capturing prescription-adjacent positioning as physicians seek reimbursement-flexible alternatives to compounded pharmaceuticals.
- Japan's Specified Health Foods System:FOSHU and FFC regulatory pathways for functional claims create premium positioning for clinically substantiated alpha lipoic acid formulations targeting glucose metabolism.
Industry Challenges
- Pharmacopeial Divergence:USP, EP, and ChP monographs specify different impurity profiles and assay methods, forcing manufacturers to maintain parallel quality systems or exclude markets.
- Stereochemistry Verification:Chiral analytical capability scarcity limits supplier qualification for R-enantiomer production, extending pharmaceutical customer onboarding timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alpha Lipoic Acid Market |
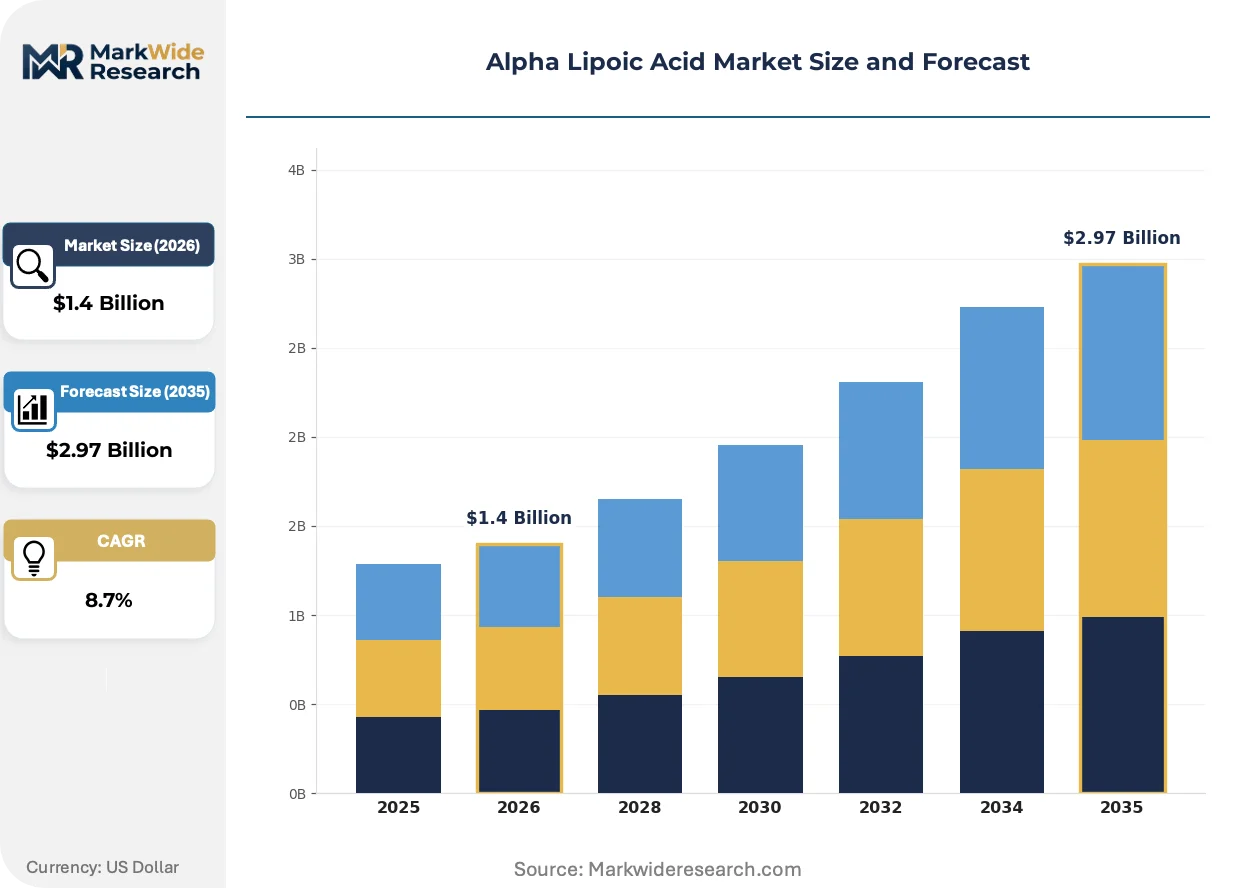
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Capsules, Tablets, Liquid Application: Dietary Supplements, Pharmaceutical, Functional Foods, Personal Care End User: Healthcare Providers, Nutritionists, Retail Consumers, Fitness Enthusiasts Distribution Channel: Online Retail, Pharmacies, Supermarkets, Health Stores |
| Companies Covered | AlzChem Group AG, GeroNova Research Inc., Olon S.p.A, NOW Foods, Suzhou Fushilai Pharmaceutical Co. Ltd., Source Naturals Inc., Haihang Industry, HiMedia Laboratories, Wellona Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alpha Lipoic Acid Market Emerging Trajectories
Formulation science is overtaking synthesis economics as the primary competitive differentiator in alpha lipoic acid markets. Three distinct vectors are reshaping how value flows through the value chain.
Microencapsulation via fluid-bed coating and lipid-based matrices is migrating from specialty pharmaceutical applications toward mass-market dietary supplements. Nutraceutical brands with direct-to-consumer reach are adopting spray-dried complexes at 2-3x the pace of traditional contract manufacturers. This technical migration from batch processing toward continuous manufacturing is compressing minimum viable order quantities and enabling just-in-time inventory models for mid-tier brands.
REACH registration requirements for organosulfur compounds are tightening substance identity documentation across EU supply chains. The European Chemicals Agency's enhanced dossier demands are forcing non-EU raw material suppliers to invest in GLP-compliant analytical laboratories or exit pharmaceutical-grade segments. German and Swiss distributors are consolidating qualified supplier lists, creating preferred vendor tiers that favor integrated manufacturers with in-house toxicology capabilities.
Physician dispensing models are displacing retail pharmacy channels for high-potency alpha lipoic acid formulations. Functional medicine clinics in the United States are establishing captive pharmacies or white-label partnerships to capture margin between wholesale ingredient cost and patient out-of-pocket pricing. This channel compression is most visible in California and Texas, where scope-of-practice regulations permit direct dispensing without pharmacy board oversight.
Alpha Lipoic Acid Market Segmentation
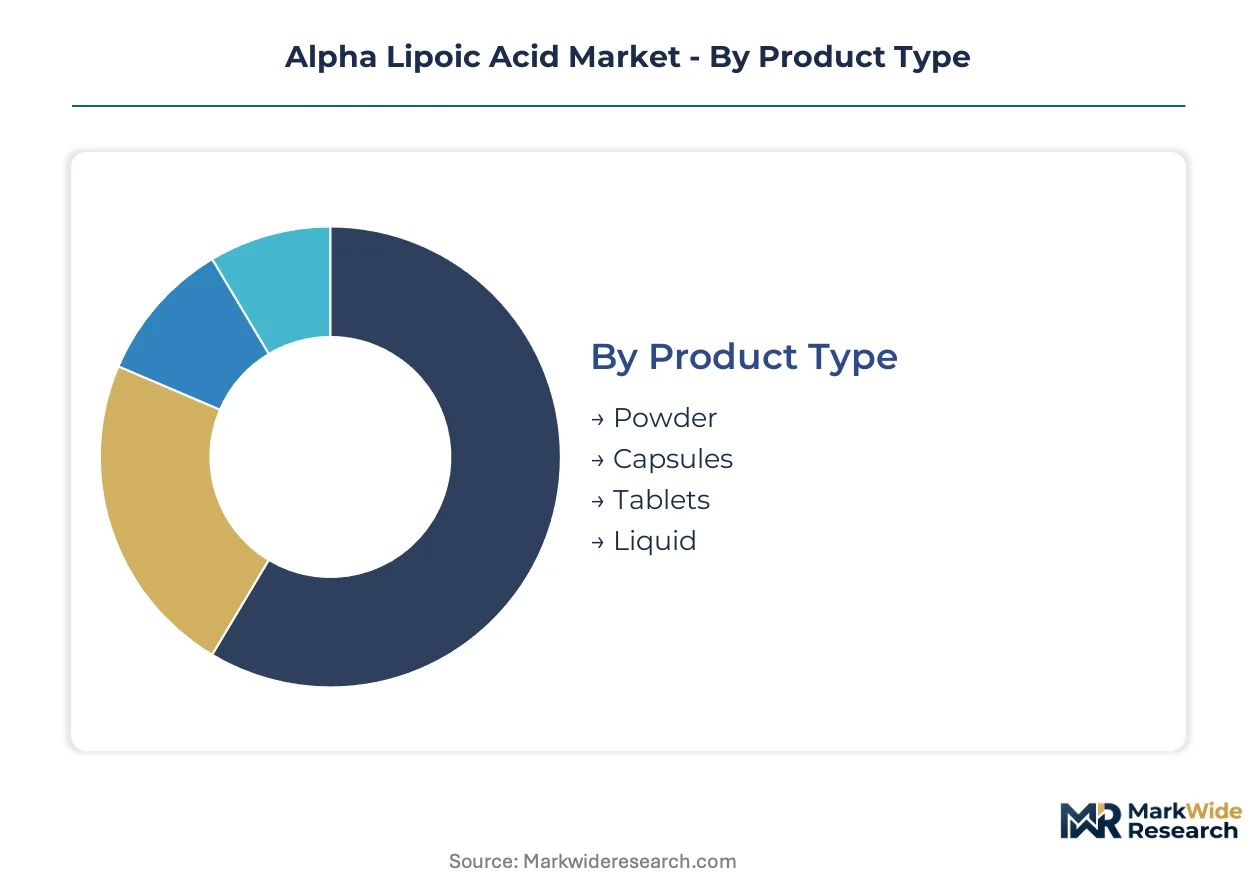
Alpha lipoic acid's bifurcated regulatory status—dietary ingredient versus pharmaceutical active—creates distinct specification tiers across every segmentation dimension. Formulators must match purity grades, delivery formats, and channel requirements to capture value in either nutraceutical or clinical end-uses.
Product Type:
Use-case spectrum spans bulk ingredient procurement through finished dosage convenience, with stability requirements and bioavailability engineering driving format selection.
- Powder:Bulk active pharmaceutical ingredient and dietary supplement raw material, stabilized through controlled-atmosphere packaging and nitrogen flushing. Demand concentrates among contract manufacturers in Germany and Italy seeking EP-certified material for multi-regional formulation, constrained by thermal degradation above 40°C requiring cold-chain investment for liquid conversion.
- Capsules:Hard-shell gelatin and vegetarian variants dominate direct-to-consumer finished products, enabling precise unit-dose antioxidant delivery. US telehealth subscription models and Japanese FOSHU functional claims are expanding physician-dispensed and pharmacy-channel adoption for metabolic health protocols.
- Tablets:Compressed formulations with binders and disintegrants suit mass-market retail placement and institutional procurement.
- Liquid:Solution and suspension formats target pediatric, geriatric, and clinical populations with swallowing difficulties; microencapsulation is mitigating oxidation sensitivity.
Established volume favors powder; emerging adoption favors capsules.
Application:
Cost tier stratification separates commodity nutraceutical positioning from premium pharmaceutical-grade certification requirements.
- Dietary Supplements:Largest volume segment encompassing antioxidant, metabolic support, and nerve health positioning. NOW Foods and comparable vertically integrated brands leverage retail and online distribution control to capture recurring revenue through subscription models, with USP verification enabling prescription-adjacent physician recommendation.
- Pharmaceutical:Prescription and compounded formulations for diabetic neuropathy, neurodegenerative conditions, and chelation therapy requiring USP, EP, or ChP certification. Clinical trial expansion in the United States is generating investigator-initiated demand for R-enantiomer material with stereochemical verification.
- Functional Foods:Beverage fortification and fortified food matrices represent nascent application with stability and taste-masking challenges.
- Personal Care:Topical antioxidant serums and anti-aging formulations leverage alpha lipoic acid's dual solubility for skin penetration.
Margin compression defines functional foods; premium positioning concentrates in pharmaceutical.
End User:
Customer type fragmentation reflects divergent decision-making authority between clinical recommendation and self-directed purchase.
- Healthcare Providers:Physicians, functional medicine practitioners, and hospital systems prescribing or dispensing pharmaceutical-grade material. California and Texas scope-of-practice regulations permit direct dispensing without pharmacy board oversight, enabling captive margin capture.
- Retail Consumers:Self-directed purchasers through e-commerce, mass retail, and health food channels. Online retail subscription models are displacing pharmacy purchasing for maintenance-dose antioxidant regimens.
- Nutritionists:Registered dietitians and certified nutrition specialists recommending therapeutic doses within integrated health protocols.
- Fitness Enthusiasts:Athletic and bodybuilding populations seeking mitochondrial support and recovery optimization through sports nutrition channels.
Volume concentration sits with retail consumers; growth velocity favors healthcare providers.
Distribution Channel:
Geography of purchasing behavior is shifting from physical retail toward digital-native acquisition with telehealth integration.
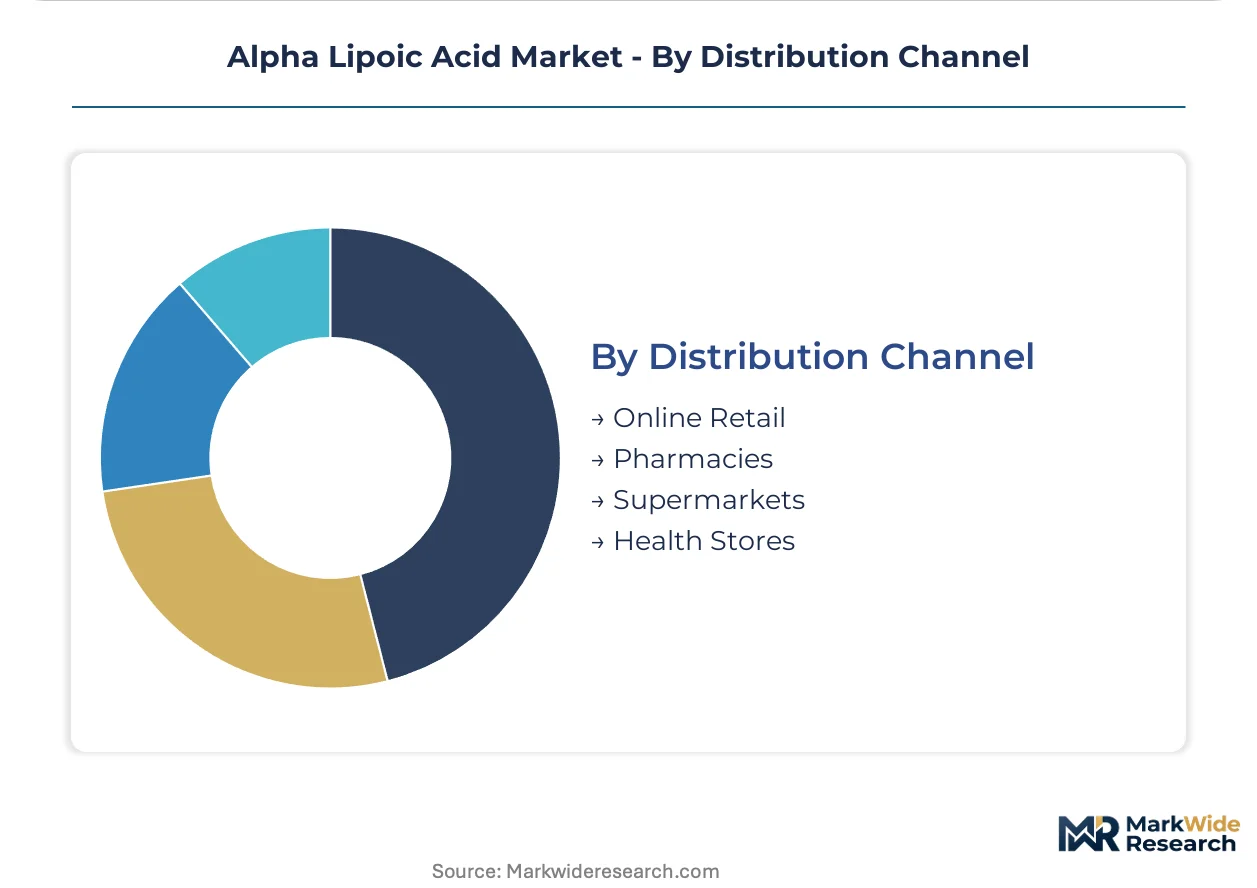
- Online Retail:Direct-to-consumer platforms, subscription services, and telehealth-integrated pharmacies capturing share from traditional dispensaries. US-based telehealth bundling of alpha lipoic acid into metabolic health protocols creates recurring revenue bypassing wholesale distribution.
- Pharmacies:Community and hospital pharmacies retaining pharmaceutical-grade dispensing authority, particularly for R-enantiomer and prescription-adjacent formulations.
- Supermarkets:Mass-market retail placement for commodity dietary supplement positioning with price-competitive private label competition.
- Health Stores:Specialty retailers and natural products channels emphasizing quality certification, organic positioning, and practitioner-grade differentiation.
Legacy infrastructure anchors pharmacies; channel expansion runs through online retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Healthcare providers in the United States drive pharmaceutical-grade procurement, while dietary supplement demand concentrates among direct-to-consumer buyers in Germany and China. Regulatory divergence across FDA, EMA, and NMPA jurisdictions fragments supplier qualification requirements.
United States
Telehealth subscription models bundle alpha lipoic acid into metabolic health protocols, creating recurring revenue streams that bypass traditional pharmacy distribution. The FDA regulates material as a dietary ingredient under DSHEA with additional pharmaceutical oversight for drug applications. Clinical research expansion in California and Texas generates investigator-initiated demand for USP-certified R-enantiomer material.
Germany
AlzChem Group AG anchors European pharmaceutical-grade supply from its domestic manufacturing base, serving contract manufacturers requiring EP certification. ECHA's REACH registration requirements for organosulfur compounds tighten substance identity documentation across supply chains. The Bavarian chemical cluster concentrates qualified suppliers with in-house toxicology capabilities and GLP-compliant analytical laboratories.
China
Suzhou Fushilai Pharmaceutical and comparable domestic producers serve bulk racemic material demand for dietary supplement export markets. The NMPA has aligned import purity thresholds with EP monographs through revised GB standards, reducing re-certification costs for multi-regional suppliers. Manufacturing capacity concentrates in Jiangsu and Zhejiang provinces with fermentation-based synthetic routes.
Japan
FOSHU and FFC regulatory pathways for functional claims create premium positioning for clinically substantiated formulations targeting glucose metabolism. METI oversight of Specified Health Foods system demands rigorous clinical substantiation for permitted claims. Tokyo and Osaka metropolitan areas concentrate distribution infrastructure for pharmacy and online retail channels.
India
Underutilized fermentation capacity at domestic contract development organizations offers cost-competitive synthetic routes for racemic material serving export supplement demand. CDSCO import regulations for active pharmaceutical ingredients require facility registration and quality documentation. Mumbai and Hyderabad clusters house CDMOs seeking partnerships with Western nutraceutical brands.
Alpha Lipoic Acid Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered supply positions. The vendor base separates into integrated manufacturers with captive distribution, pharmaceutical-grade specialists with certification depth, and commodity suppliers serving bulk ingredient trade. Three archetypes dominate: vertically integrated brands with retail and online reach, European contract manufacturers with EP-qualified capacity, and Asian fermentation-based producers with cost-positioned racemic output. Competitive moves concentrate on microencapsulation technology licensing and geographic expansion through distributor qualification.
Among German-anchored pharmaceutical-grade suppliers, AlzChem Group AG exemplifies integrated manufacturing with toxicology capabilities, while Olon S.p.A represents custom synthesis specialists serving branded ingredient partnerships. NOW Foods occupies a position as a vertically integrated North American operator with control over retail and online distribution channels. These three entities illustrate the archetype spectrum from certification-heavy European supply to channel-captive North American brands.
| Leading Market Players |
|---|
| AlzChem Group AG |
| GeroNova Research Inc. |
| Olon S.p.A |
| NOW Foods |
| Suzhou Fushilai Pharmaceutical Co. Ltd. |
| Source Naturals Inc. |
| Haihang Industry |
| HiMedia Laboratories |
| Wellona Pharma |
| Others |
Supply Flow & Price Mechanics
Jiangsu province's fermentation capacity concentration directly shapes downstream pricing power for racemic alpha lipoic acid, with NMPA-aligned GB standards compressing import re-certification costs while EP-certified German output commands sustained premiums.
Pricing Analysis
Cost-plus contracts indexed to organosulfur feedstock volatility dominate bulk racemic transactions, while pharmaceutical-grade R-enantiomer material trades on fixed-price long-term offtakes with stereochemical verification premiums. Pricing stratifies across USP-certified pharmaceutical, EP-compliant technical, and commodity dietary supplement tiers. Cost compression in racemic bulk intensifies because Indian CDMOs are undercutting Chinese export quotes. Dietary supplement brands show highest price sensitivity; pharmaceutical buyers prioritize certification over unit cost.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk assessment for alpha lipoic acid distributors. Manufacturing gravity centers on China, Germany, and India, with Jiangsu and Zhejiang provinces feeding racemic output, AlzChem Group AG anchoring EP-certified pharmaceutical supply, and Mumbai-Hyderabad CDMO clusters targeting cost-positioned export production. Raw material dependencies rest on lipoic acid precursors, fermentation substrates, and stereoselective synthesis catalysts. Single-source vulnerability concentrates among European buyers requiring EP monograph compliance. Distribution runs through qualified ingredient distributors with toxicology dossier capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent alpha lipoic acid suppliers face substitution pressure from next-generation mitochondrial support compounds, requiring defensive positioning against novel antioxidant entrants targeting diabetic neuropathy protocols.
For Market Incumbents: Insulate pharmaceutical-grade positioning by deepening EP and USP certification moats while acquiring microencapsulation technology to defend against sustained-release formulation substitutes. Captive supply of R-enantiomer production capacity in Germany or Italy reduces single-source vulnerability for healthcare provider customers.
For New Entrants and Emerging Players: Mid-tier Indian CDMOs with underutilized fermentation assets represent the most penetrable entry point for racemic material serving dietary supplement demand. Telehealth-integrated subscription models in California and Texas bypass traditional pharmacy distribution. Partner with vertically integrated North American brands lacking backward integration into active ingredient synthesis.
For Investors and Strategic Acquirers: Carve-out targets emerge from European chemical conglomerates with orphaned organosulfur manufacturing units lacking strategic fit. Long-term viability hinges on pharmacopeial harmonization progress and clinical trial expansion for neurodegenerative indications. Monitor NMPA import volume data as inflection signal for Chinese domestic demand absorption.
| Strategic Initiative | Industry Significance |
|---|---|
| Microencapsulation Technology Licensing | Sustained-release delivery expands therapeutic applications beyond traditional antioxidant supplements. |
| EP Certification Investment | European Medicines Agency monograph compliance secures multi-regional pharmaceutical-grade market access. |
| Indian CDMO Partnership Formation | Underutilized fermentation capacity offers cost-competitive synthetic routes for racemic material output. |
| Telehealth Platform Integration | Direct-to-consumer subscription models bypass traditional pharmacy distribution for metabolic health protocols. |
| R-Enantiomer Production Scale-Up | Stereoselective synthesis capability captures pharmaceutical-grade premium over commodity racemic mixtures. |
Methodological Framework
A spread of perspectives from pharmaceutical procurement managers, dietary supplement formulators, contract manufacturing executives, and regulatory affairs specialists converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA docket submissions, EMA assessment reports, NMPA GB standard filings, and customs trade flow records. Bottom-up volume estimates from individual production facilities triangulated against top-down demand aggregation across end-use segments.
Demand-supply balance dynamics anchored the forecast framework across the analysis window. Segmentation modeling incorporated product type, application tier, end-user category, and distribution channel dimensions. CAGRs derived from fitted growth curves applied to base-year estimates, with cross-reference to clinical trial pipeline expansion and telehealth platform adoption rates as alpha lipoic acid-specific demand drivers.
Macroeconomic conditions sit as an overlay; deviation in exchange rate volatility, energy input costs, or pharmaceutical reimbursement policy would shift the trajectory. Forecasts embody documented assumptions regarding regulatory harmonization progress and substitution threat evolution. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dietary Supplements
Australia Nicotine Replacement Therapy Market
Dietary Supplements
Bisglycinate Market
Dietary Supplements
Medicated Confectionery Market
Dietary Supplements
Melatonin Sleep Supplements Market
Dietary Supplements
Mens Health Supplements Market
Dietary Supplements
Concentrated Angelica Pills Market
Dietary Supplements
Cold and Flu Supplements Market
Dietary Supplements
Global Lipid Regulators Market
Dietary Supplements
Pet Allergy Immune Supplements Market
Dietary Supplements
Global Effervescent Tablet Market
Dietary Supplements
Detox Products Market
Dietary Supplements
Immune Health Supplements Market
Dietary Supplements
Global Oral Electrolyte Solutions Market
Dietary Supplements
Canine Weight Loss Drugs Market
Dietary Supplements
Cold Remedies Market
Dietary Supplements
Hair Loss Supplement Market