
 Herbal Tincture Market | 2026-2036
Herbal Tincture Market Size, Share, and Industry Trends Forecast 2026-2036
Herbal Tincture Market Analytics
The EU Green Deal is broadening compliance obligations for botanical extract suppliers across member states. Gaia Herbs leverages certified organic cultivation networks to sustain premium positioning in North American health food channels. Nature's Answer anchors its competitive stance through vertically controlled extraction facilities in the northeastern United States. Blackmores Limited dominates Australasian pharmacy distribution through practitioner-exclusive product tiers.
Herbal tinctures are concentrated liquid preparations produced by macerating plant material in aqueous ethanol solutions typically ranging from 25% to 90% alcohol by volume, followed by filtration and standardization to defined marker compound levels. These extracts serve therapeutic, nutritional, and functional beverage applications across clinical and consumer settings. Liquid extract formats lead volume throughput due to established bioavailability profiles and dosing precision, while powdered extract segments capture margin concentration through extended shelf stability and formulation flexibility in functional food matrices. Distribution through specialty stores retains structural importance for practitioner-guided purchases, whereas online retail channels exhibit the fastest trajectory as direct-to-consumer brands bypass traditional wholesale markups.
The FDA's Current Good Manufacturing Practice regulations for dietary supplements enforce identity testing and contaminant screening that elevates capital requirements for new entrants. EMA's Committee on Herbal Medicinal Products governs well-established use registrations that facilitate cross-border commerce within the European Economic Area. Australia's TGA maintains parallel scheduling controls that determine pharmacy versus open retail access for specific botanical indications. Stakeholders must monitor evolving monograph harmonization efforts between these jurisdictions to anticipate reformulation costs and market access timelines.
Market Dynamics
Botanical extract suppliers face escalating compliance burdens under the EU Green Deal's expanded sustainability mandates, forcing capital reallocation toward certified organic cultivation networks and carbon-accounted supply chains.
Growth Catalysts
- EMA Well-Established Use Registrations:The EMA's Committee on Herbal Medicinal Products streamlines cross-border commerce within the European Economic Area by validating traditional use claims for standardized tincture formulations.
- Wellness Clinic Protocol Expansion:German and United States wellness clinics are embedding botanical therapy into integrative medicine programs, creating institutional demand for practitioner-grade liquid extracts with verified marker compound levels.
- Direct-to-Consumer Channel Maturation:Online retail channels enable direct-to-consumer brands to bypass wholesale markups and capture margin through subscription-based replenishment models.
Market Restraints
- Ethanol Input Cost Volatility:Aqueous ethanol solutions ranging from 25% to 90% alcohol by volume expose manufacturers to agricultural commodity price swings and biofuel policy competition.
- FDA CGMP Compliance Burden:The FDA's Current Good Manufacturing Practice regulations for dietary supplements enforce identity testing and contaminant screening that elevates capital requirements for new entrants.
- Standardized Extract Substitution:Powdered extract formats with extended shelf stability threaten liquid tincture volumes in functional food matrix applications.
Strategic Opportunities
- Australia Practitioner-Exclusive Tiers:The TGA's scheduling controls create pharmacy-access segmentation that rewards brands developing practitioner-only product lines with higher margin capture.
- Carbon-Labeled Supply Chains:The EU Green Deal's sustainability disclosure requirements favor early movers implementing farm-to-bottle traceability systems with verified organic certification.
- Functional Beverage Convergence:Adaptogenic tincture formats are penetrating ready-to-drink beverage applications through co-manufacturing partnerships with craft kombucha and botanical soda producers.
Industry Challenges
- Phytochemistry Analytical Talent Scarcity:Marker compound standardization requires specialized expertise in high-performance liquid chromatography and mass spectrometry that outpaces current training pipeline output.
- Monograph Harmonization Timeline Uncertainty:Divergent botanical monograph requirements between FDA, EMA, and TGA jurisdictions force parallel formulation development and duplicate stability testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Herbal Tincture Market |
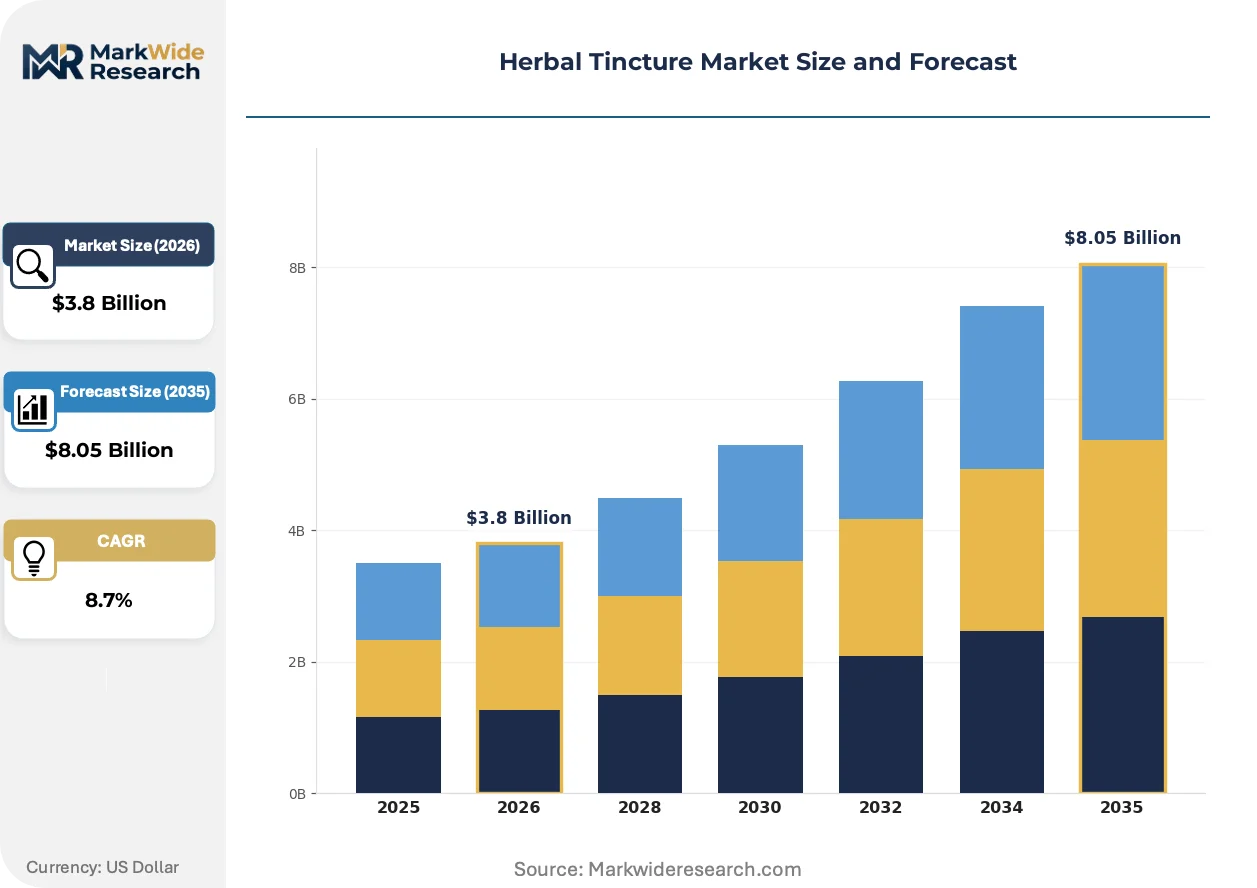
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Extract, Solid Extract, Powdered Extract, Herbal Infusion Ingredient Type: Vegetable, Fruit, Flower, Root Distribution Channel: Online Retail, Specialty Stores, Health Food Stores, Pharmacies End User: Consumers, Herbalists, Health Practitioners, Fitness Enthusiasts |
| Companies Covered | Sawgrass Nutra Labs, Matsun Nutrition, Nature's Answer, Vitaquest International, Canyonside Labs, Gaia Herbs, ENZ Pharmtech, Blackmores Limited, Herbal Hills, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Herbal Tincture Market Evolving Landscape
Ultrasonic-assisted extraction and subcritical CO2 processing are compressing traditional maceration timelines while preserving heat-sensitive bioactive compounds that ethanol-based methods degrade.
Ultrasonic extraction technology is electrifying throughput economics for mid-scale botanical processors. United States contract manufacturers serving wellness clinics and direct-to-consumer brands are retrofitting batch equipment with probe-based sonication systems. The technology is electrifying competitive positioning by enabling same-day extraction-to-bottling workflows that slash working capital requirements.
REACH-compliant solvent recovery mandates are reshaping European extraction facility design. The European Chemicals Agency's tightened volatile organic compound emission thresholds force capital expenditure on closed-loop ethanol reclamation systems. German and French botanical extractors are responding by consolidating production into fewer, larger facilities with integrated distillation recovery infrastructure.
Subscription-based replenishment models are displacing intermittent retail purchasing in North American direct-to-consumer channels. Health food store distributors lose volume as tincture brands build proprietary customer databases through automated reorder algorithms. The shift concentrates most visibly in California and Pacific Northwest metropolitan markets where digital-native wellness consumers predominate.
Herbal Tincture Market Segmentation
Segmentation in herbal tinctures determines regulatory pathway complexity and margin architecture. Product format dictates whether FDA dietary supplement rules, EMA traditional use registrations, or TGA scheduling controls apply.
Product Type:
Certification burdens vary sharply by physical state—liquid extracts face stability testing requirements that powdered formats avoid, while solid extracts trigger novel food assessments in European jurisdictions.
- Liquid Extract:Aqueous ethanol solutions containing 25% to 90% alcohol by volume enable precise dosing and rapid bioavailability. German wellness clinics and United States integrative medicine practices specify liquid formats for protocol standardization, though ethanol input costs create margin pressure.
- Powdered Extract:Spray-dried or freeze-dried concentrates offer extended shelf stability and formulation flexibility in functional foods. Demand concentrates in North American direct-to-consumer channels where subscription models favor lightweight, shippable formats with lower breakage rates than glass-bottled liquids.
- Solid Extract:Highly concentrated viscous preparations produced through vacuum reduction. Australia's TGA scheduling controls classify these as complementary medicines requiring specific label claims.
- Herbal Infusion:Lower-concentration preparations macerated in water or dilute alcohol. Health food stores in California and Oregon metropolitan markets stock these for entry-level consumers.
Leading the category by volume: Liquid Extract. Growing fastest: Powdered Extract.
Ingredient Type:
Raw material sourcing geography drives organic certification requirements and carbon accounting obligations under EU Green Deal mandates.
- Root:Underground plant structures requiring multi-year cultivation cycles and soil quality verification. Echinacea and ginseng root supplies concentrate in certified organic networks across Wisconsin and Ontario to meet North American health food channel specifications.
- Flower:Delicate aerial parts harvested at peak bloom with narrow processing windows. Lavender and chamomile sourcing clusters in Provence and Bulgaria where REACH-compliant solvent recovery infrastructure supports extraction at scale.
- Vegetable:Leaf and stem materials with shorter cultivation timelines. Kale and nettle extracts penetrate functional beverage applications through co-manufacturing partnerships.
- Fruit:Berry and seed preparations with high antioxidant marker compounds. Elderberry demand surged through United States wellness clinic protocols during recent immune support formulation trends.
Root commands premium pricing through cultivation cycle length. Flower exhibits steepest expansion trajectory through cosmetic and aromatherapy cross-selling.
Distribution Channel:
Channel selection determines customer acquisition economics and regulatory touchpoint density—pharmacies require TGA or EMA registrations that online retail circumvents.
- Online Retail:Direct-to-consumer platforms bypass wholesale markups through subscription-based replenishment algorithms. California and Pacific Northwest metropolitan markets show highest digital-native wellness consumer concentration.
- Specialty Stores:Practitioner-guided purchase environments with trained staff consultation. German pharmacy-adjacent herbal shops maintain structural importance for EMA-registered traditional use products.
- Health Food Stores:Mid-tier retail with certified organic positioning requirements. Gaia Herbs and comparable brands leverage these channels for premium margin capture.
- Pharmacies:Regulated access points governed by Australia's TGA scheduling or European pharmacy-only monograph categories. Blackmores Limited dominates this tier through practitioner-exclusive product lines.
Online Retail leads volume growth. Pharmacies retain highest per-unit margins through regulatory barriers.
End User:
User type dictates formulation complexity and dosing precision requirements—health practitioners demand verified marker compound certificates that consumer segments disregard.
- Health Practitioners:Licensed naturopaths and integrative physicians prescribing protocol-specific extracts with HPLC-verified standardization. German and United States wellness clinics drive institutional procurement volumes.
- Consumers:Self-directed purchasers responding to adaptogenic and immune support marketing claims. Subscription models concentrate retention in this segment.
- Herbalists:Trained botanical medicine specialists compounding custom formulations. Smaller volume but highest per-client revenue through consultation fees.
- Fitness Enthusiasts:Athletic performance and recovery positioning. Cordyceps and rhodiola extracts penetrate this segment through functional beverage convergence.
Health Practitioners anchor premium tier pricing. Consumers represent the fastest-growing addressable base through digital channel maturation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's metropolitan wellness corridors generate disproportionate demand for direct-to-consumer tincture brands. German wellness clinics and Australian pharmacy networks anchor institutional procurement volumes across their respective markets.
United States
Integrative medicine protocols in California and Pacific Northwest metros drive practitioner-grade liquid extract procurement. FDA Current Good Manufacturing Practice regulations enforce identity testing and contaminant screening that elevates capital barriers for new entrants. New York and Boston health food channels sustain premium positioning for certified organic cultivation networks.
Germany
Bavarian wellness clinics embed botanical therapy into standardized treatment protocols, creating institutional demand for EMA-registered formulations. The EU Green Deal mandates carbon-accounted supply chains and certified organic verification across member states. Frankfurt and Hamburg extraction facilities consolidate production into integrated distillation recovery infrastructure to meet REACH-compliant solvent recovery thresholds.
Australia
Sydney and Melbourne pharmacy networks dominate practitioner-exclusive product distribution through TGA scheduling controls. The Therapeutic Goods Administration determines pharmacy versus open retail access for specific botanical indications. Queensland cultivation clusters supply certified organic raw materials to meet premium channel specifications.
Canada
Toronto and Vancouver direct-to-consumer channels exhibit fastest trajectory as subscription-based replenishment models displace intermittent retail purchasing. Health Canada maintains parallel scheduling controls that align with TGA and FDA frameworks. British Columbia extraction facilities serve cross-border wellness clinic demand in Pacific Northwest US metros.
United Kingdom
London and Southeast England health practitioner networks specify HPLC-verified marker compound standardization for protocol compliance. EMA Committee on Herbal Medicinal Products registrations facilitate cross-border commerce with German and French pharmacy channels. Midlands distribution hubs consolidate EU-sourced raw materials for domestic formulation.
Herbal Tincture Market Competitive Landscape
The competitive structure tilts toward vertically integrated specialists with captive cultivation networks. Mid-scale contract manufacturers and direct-to-consumer brands populate the remaining tiers, creating a stratified vendor base. Three archetypes dominate: certified organic cultivator-extractors, practitioner-channel specialists with regulatory registrations, and digital-native subscription brands. Capacity consolidation and farm-to-bottle traceability investments constitute the dominant competitive moves.
Among US-based cultivator-extractors, Gaia Herbs and Nature's Answer occupy positions within the certified organic tier, exemplifying backward integration into controlled cultivation networks. Blackmores Limited anchors the practitioner-exclusive pharmacy channel archetype through Australasian regulatory compliance. These three entities represent contrasting geographic and channel specializations without overlapping core positioning.
| Leading Market Players |
|---|
| Sawgrass Nutra Labs |
| Matsun Nutrition |
| Nature's Answer |
| Vitaquest International |
| Canyonside Labs |
| Gaia Herbs |
| ENZ Pharmtech |
| Blackmores Limited |
| Herbal Hills |
| Others |
Value Network & Pricing Analysis
Ethanol input costs cascade through aqueous extraction operations to stratify pricing across practitioner-grade and consumer-tier tincture formats. Agricultural commodity volatility and biofuel policy competition in the United States and Brazil compress margins at mid-market positions while certified organic cultivation premiums sustain top-tier positioning.
Pricing Analysis
Marker compound standardization anchors value-based pricing tiers, with HPLC-verified extracts commanding substantial premiums over unstandardized alternatives. Three-tier pricing structure across premium, standard, and economy levels separates EMA-registered formulations from health food store generics and entry-level herbal infusions. Pricing pressure stems from powdered extract substitution in functional food matrices, eroding liquid format volumes. Health practitioners exhibit lowest price sensitivity due to protocol compliance requirements, while fitness enthusiasts and self-directed consumers drive volume through promotional responsiveness.
Supply Chain Analysis
Direct-to-consumer channels handle subscription-model demand through automated replenishment algorithms that bypass traditional wholesale markups. Raw material sourcing concentrates in certified organic networks across Wisconsin, Ontario, and Queensland, with extraction processing clustering in Germany, France, and the northeastern United States. Ethanol supply draws from agricultural commodity markets with biofuel policy competition, while glass packaging and botanical raw materials face logistics chokepoint exposure through concentrated Atlantic and Pacific shipping lanes. Distribution runs through pharmacy networks in Australia and Germany, specialty stores in North American health food channels, and proprietary digital platforms for subscription brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The herbal tincture market is accelerating into a vertical-integration race, with upstream control over certified organic cultivation and downstream capture of subscription relationships constituting the decisive competitive levers.
For Market Incumbents: Deploy carbon-accounted supply chain certification to defend margin position against EU Green Deal compliance burdens. Consolidate extraction capacity into integrated distillation recovery facilities to meet REACH-compliant solvent recovery mandates. Expand practitioner-exclusive product tiers to lock in pharmacy channel access before TGA scheduling controls tighten.
For New Entrants and Emerging Players: Launch via direct-to-consumer subscription models targeting Pacific Northwest and California metropolitan wellness corridors. Exploit white space in functional beverage co-manufacturing partnerships with craft kombucha and botanical soda producers. Pursue ultrasonic-assisted extraction technology adoption to compress working capital requirements against established maceration timelines.
For Investors and Strategic Acquirers: EMA well-established use registration acceleration is the leading indicator that cross-border commerce scalability is improving. Prioritize acquisition targets with captive certified organic cultivation networks and existing practitioner channel relationships. Monitor monograph harmonization progress between FDA, EMA, and TGA jurisdictions as the critical inflection signal for reformulation cost exposure.
| Strategic Initiative | Industry Significance |
|---|---|
| Carbon-Labeled Supply Chain Certification | Farm-to-bottle traceability systems satisfy EU Green Deal sustainability disclosure mandates. |
| Ultrasonic Extraction Technology Deployment | Probe-based sonication compresses extraction-to-bottling timelines for mid-scale processors. |
| Practitioner-Exclusive Product Tier Development | TGA scheduling compliance captures pharmacy-access segmentation premiums in Australasia. |
| Direct-to-Consumer Subscription Platform Buildout | Automated replenishment algorithms displace health food store distributor volume in North America. |
| Functional Beverage Co-Manufacturing Partnership | Adaptogenic tincture formats penetrate ready-to-drink applications through craft producer alliances. |
Research Methodology
Document review covered FDA dietary supplement enforcement actions, EMA Committee on Herbal Medicinal Products registrations, and TGA scheduling determinations, complemented by interviews with extraction facility operators, wellness clinic procurement directors, health food store category buyers, and certified organic cultivation network managers. Secondary sources included customs trade data for botanical raw materials, SEC filings for publicly traded supplement manufacturers, and EU REACH compliance disclosure databases. Bottom-up volume modeling triangulated against top-down market sizing across product format, ingredient type, and distribution channel segments.
Historical volume trajectories cross-referenced against expert panel input on ethanol cost pass-through dynamics and regulatory timeline acceleration. Segmentation modeling incorporated product format, ingredient sourcing geography, distribution channel, and end-user type dimensions throughout the projection horizon. CAGRs derived from regression analysis of historical growth patterns adjusted for EMA registration pipeline visibility and subscription channel penetration curves. Industry-specific forecast inputs included ultrasonic extraction technology adoption rates and carbon-accounted supply chain investment flows.
Ethanol commodity price volatility, EMA monograph harmonization delays, and TGA scheduling reclassification are the dominant revision risks to base-case projections. Forecasts reflect assumptions regarding wellness clinic protocol expansion sustainability and direct-to-consumer channel retention rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dietary Supplements
Postpartum Health Supplements Market
Dietary Supplements
Cardiovascular Health Supplements Market
Dietary Supplements
Global Nicotine Lozenges Market
Dietary Supplements
Colostrum Chewable Tablets Market
Dietary Supplements
Global Vitamin D Therapy Market
Dietary Supplements
Concentrated Angelica Pills Market
Dietary Supplements
Alpha Lipoic Acid Market
Dietary Supplements
Pet Allergy Immune Supplements Market
Dietary Supplements
Glucosamine Supplements Market
Dietary Supplements
Diabetic Food Market
Dietary Supplements
Magnesium Glycinate Market
Dietary Supplements
Soft Gel Capsule Market
Dietary Supplements
Global Slimming Aids Market
Dietary Supplements
Bisglycinate Market
Dietary Supplements
Pet Skin and Coat Health Supplement Market
Dietary Supplements
Herbal Medicine Market