
 Diabetes Supplements Market | 2026-2036
Diabetes Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Diabetes Supplements Market Analysis
Direct-to-consumer online channels is narrowing as pharmacy networks and specialist health food stores reclaim patient trust through pharmacist-counselled supplement selection. Abbott Laboratories anchors its position through clinical credibility and hospital-affiliated retail programs. Nature's Bounty competes on shelf-space dominance in mass-market pharmacy chains across North America. NOW Foods differentiates via third-party testing transparency and practitioner-exclusive professional lines.
Diabetes supplements comprise formulated ingestible products containing bioactive compounds such as chromium picolinate, alpha-lipoic acid, cinnamon extract, and soluble fiber designed to modulate postprandial glucose response and support insulin sensitivity in individuals with impaired glycemic control. Manufacturing typically employs controlled-release coating technologies and standardized botanical extracts to ensure batch-to-batch potency consistency for metabolic efficacy claims. Herbal extracts command premium positioning due to complex supply chains for traceable botanical sourcing and extraction method verification. Tablet and capsule delivery modes dominate volume through convenience and dose precision, though powder formats gain traction among elderly end users seeking flexible titration. Adults represent the core consumption base, while elderly segments drive fastest growth as polypharmacy-aware physicians recommend adjunctive nutritional protocols.
FDA structure-function claim regulations and FTC advertising substantiation requirements enforce rigorous clinical evidence thresholds, elevating compliance costs for market entrants. India's FSSAI and CDSCO impose dual-layer scrutiny on Ayurvedic-integrated diabetes formulations, creating differentiated approval pathways for traditional versus synthetic active ingredients. Stakeholders must monitor evolving pharmacovigilance reporting obligations and adapt label transparency standards to preempt enforcement actions across multiple jurisdictions.
Market Dynamics
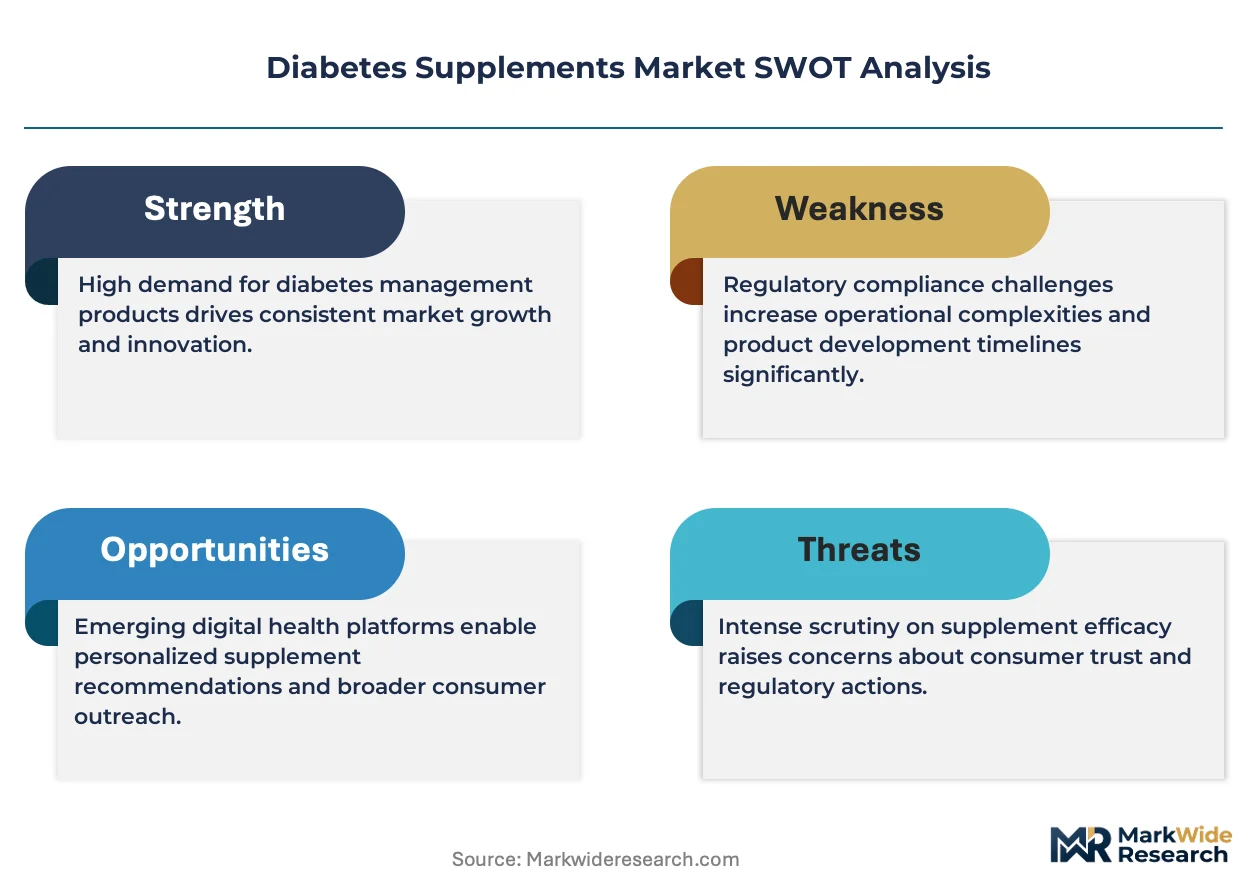
FTC advertising substantiation requirements and FDA structure-function claim regulations are compressing formulation timelines while elevating compliance spend, forcing manufacturers to front-load clinical evidence generation before commercialization.
Growth Catalysts
- Prediabetic Prevention Protocols:Endocrinology clinics in the United States are integrating chromium picolinate and alpha-lipoic acid into adjunctive care pathways, expanding reimbursable supplement recommendations.
- Ayurvedic-Integrated Formulations:India's FSSAI has streamlined traditional medicine approval pathways, accelerating cinnamon extract and bitter melon gourd product launches through pharmacy chain distribution.
- Controlled-Release Coating Technologies:Soluble fiber and botanical extract manufacturers are adopting modified-release tablet systems to improve postprandial glucose modulation consistency.
Market Restraints
- Traceable Botanical Sourcing Costs:Herbal extract supply chains face price volatility due to climate-sensitive cultivation regions and extraction method verification requirements.
- Dual-Layer Regulatory Scrutiny:India's CDSCO imposes separate approval tracks for synthetic versus traditional active ingredients, extending time-to-market for hybrid formulations.
- Clinical Evidence Threshold Elevation:FTC enforcement actions against unsubstantiated metabolic efficacy claims have raised legal defense costs for structure-function marketing.
Strategic Opportunities
- Elderly Flexible Titration Formats:Powder delivery systems are capturing polypharmacy-aware physician referrals in geriatric care settings where dose customization matters.
- Pharmacist-Counselled Channel Reclamation:Specialist health food stores and pharmacy networks are rebuilding patient trust through trained staff consultation, displacing unvetted direct-to-consumer platforms.
- Third-Party Testing Transparency:Professional practitioner-exclusive lines are differentiating via independent laboratory verification protocols that command premium positioning.
Industry Challenges
- Pharmacovigilance Reporting Obligations:Evolving adverse event documentation requirements across FDA and EMA jurisdictions are straining post-market surveillance infrastructure.
- Batch-to-Batch Potency Consistency:Standardized botanical extract manufacturing demands capital-intensive quality control systems to maintain metabolic efficacy claim defensibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diabetes Supplements Market |
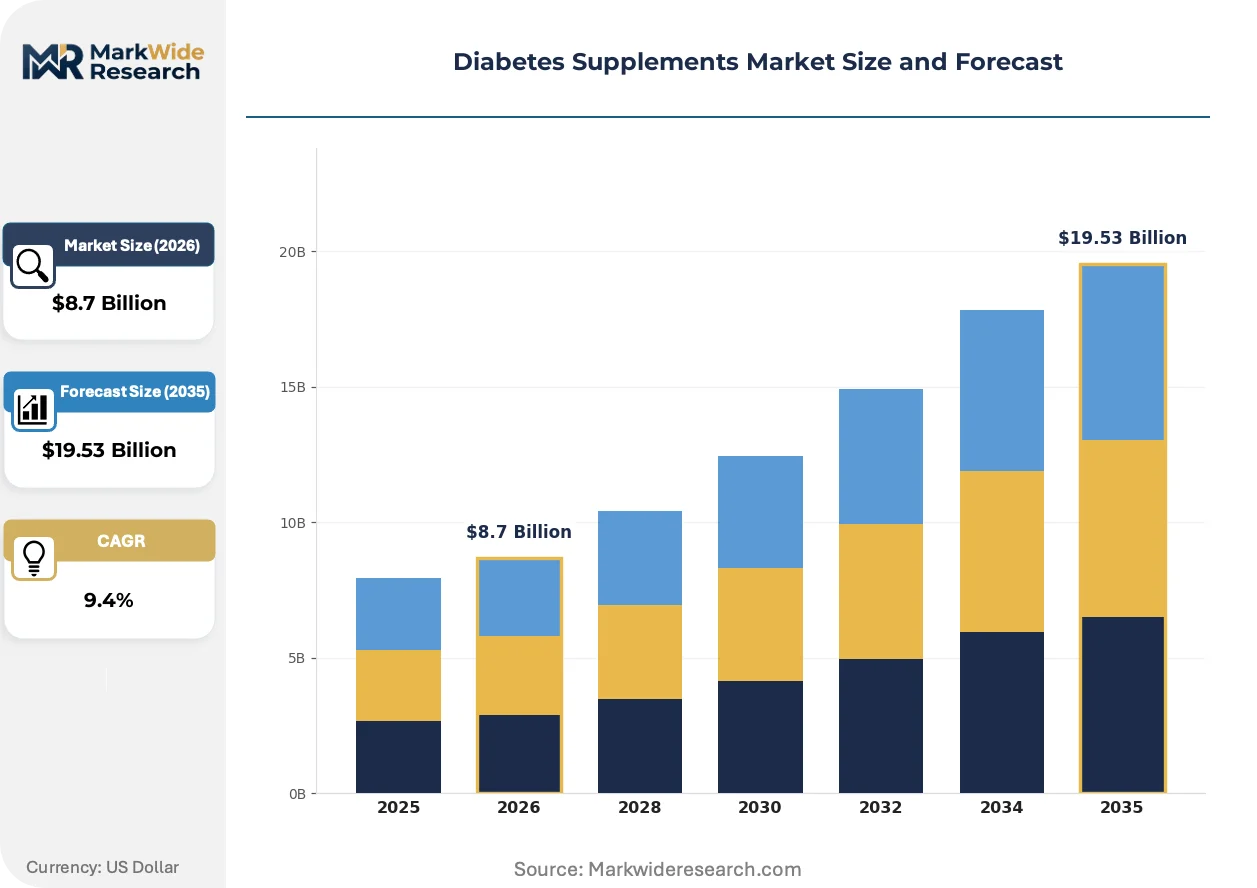
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Minerals, Herbal Extracts, Fiber Supplements Delivery Mode: Tablets, Capsules, Powders, Liquid End User: Adults, Elderly, Children, Athletes Distribution Channel: Online Stores, Pharmacies, Supermarkets, Health Food Stores |
| Companies Covered | Herbalife Nutrition, Abbott Laboratories, Amway (Nutrilite), Nestlé Health Science, Glanbia plc, Nature's Bounty, NOW Foods, Nature's Way Products, Swanson Health Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diabetes Supplements Market Emerging Trajectories
Formulation science and distribution architecture are undergoing parallel reinvention as evidence standards tighten and patient acquisition channels fragment. Three developments are restructuring competitive positioning.
Controlled-release coating technologies are migrating from pharmaceutical applications into diabetes supplement manufacturing. Manufacturers of chromium picolinate and alpha-lipoic acid tablets are licensing modified-release polymer systems to flatten glucose response curves. This technology transfer is compressing the efficacy gap between clinical-grade and consumer-grade metabolic support products.
REACH and EU Green Deal sustainability mandates are reshaping botanical extract supply chains. European manufacturers must now document carbon footprint and solvent recovery rates for cinnamon and fenugreek sourcing. Herbal extract suppliers are responding by vertically integrating into controlled cultivation partnerships in traceable growing regions.
Specialist channel preference is displacing mass-market pharmacy dominance among high-engagement diabetes patients. Pharmacist-counselled selection in health food stores and clinic-affiliated retail is capturing adults seeking personalized dosing guidance. This behavioral shift concentrates in United States metropolitan areas where endocrinology practices maintain captive supplement dispensaries.
Diabetes Supplements Market Segmentation
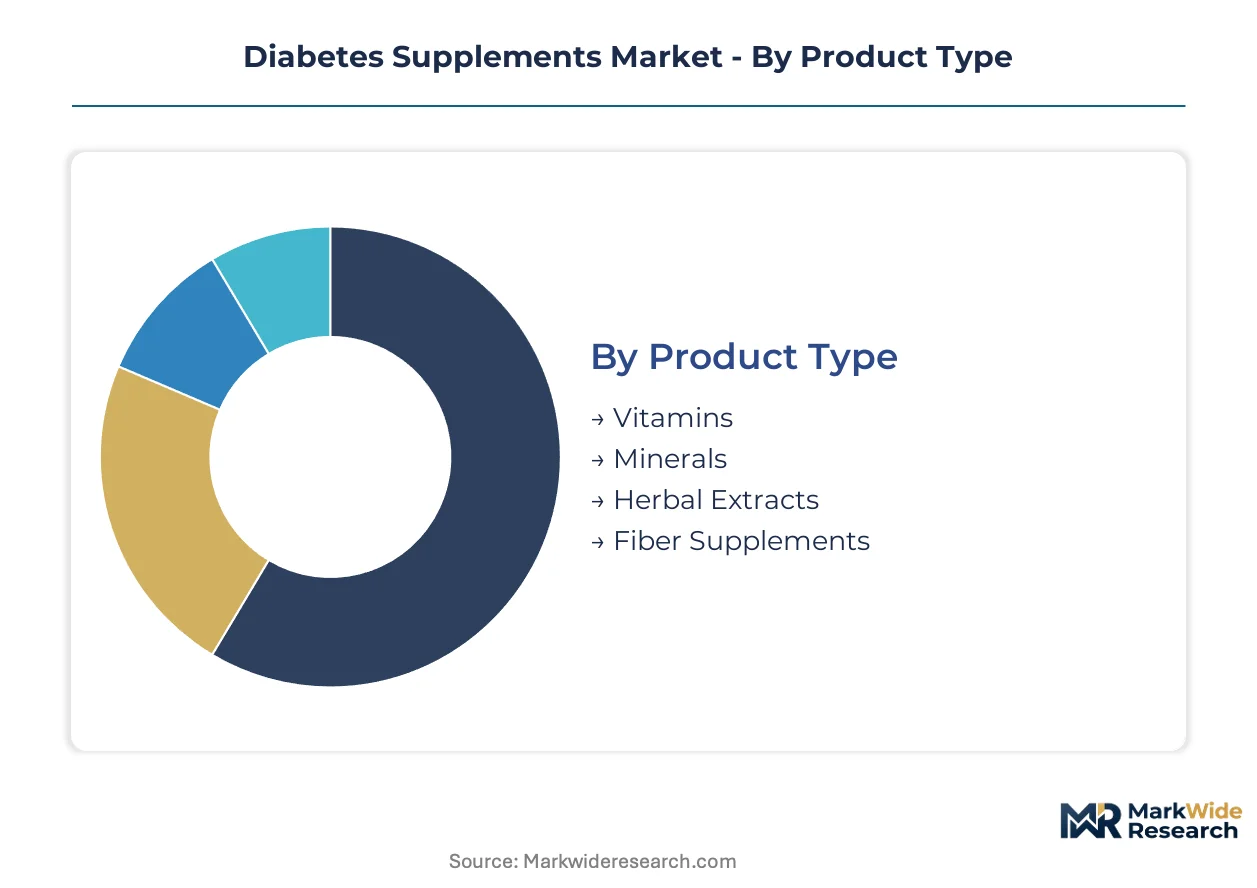
Segmentation in diabetes supplements determines formulation complexity, regulatory pathway selection, and channel strategy. Each dimension carries distinct margin profiles and compliance burdens that reshape competitive positioning across the value chain.
Product Type:
After-sales intensity varies sharply across product types, with herbal extracts demanding traceability documentation and batch-specific potency verification that synthetic alternatives rarely require.
- Herbal Extracts:Standardized botanical concentrates from cinnamon, bitter melon, and fenugreek require extraction method verification and climate-resilient sourcing partnerships. India's FSSAI has streamlined traditional medicine approvals, accelerating pharmacy chain distribution for Ayurvedic-integrated formulations.
- Minerals:Chromium picolinate and magnesium formulations employ controlled-release coating technologies to flatten postprandial glucose curves. Endocrinology clinics in the United States are integrating these into reimbursable adjunctive care protocols for prediabetic patients.
- Vitamins:B-complex and D3 variants serve baseline metabolic support with simpler regulatory pathways.
- Fiber Supplements:Soluble fiber products target postprandial modulation with flexible dosing formats.
Herbal extracts hold the largest share; momentum sits with minerals as clinical evidence thresholds elevate.
Delivery Mode:
Cost tier separation runs through delivery technology, with modified-release systems commanding premium positioning against commodity immediate-release formats.
- Tablets:Modified-release polymer coatings licensed from pharmaceutical applications improve glucose response consistency. Manufacturers are migrating controlled-release technologies into consumer-grade metabolic support products.
- Capsules:Gelatin and vegetarian shells enable precise dosing for chromium picolinate and alpha-lipoic acid combinations. Elderly end users in geriatric care settings drive demand as polypharmacy-aware physicians recommend adjunctive protocols.
- Powders:Flexible titration formats capture physician referrals where dose customization matters.
- Liquid:Rapid absorption positioning serves patients with swallowing difficulties or acute glycemic events.
Tablets dominate volume; powders are expanding most quickly among elderly segments seeking dose personalization.
End User:
Application concentration determines formulation strength and clinical positioning, with elderly protocols requiring lower-dose, multi-ingredient stacks versus adult-focused single-compound products.
- Elderly:Polypharmacy-aware physicians in United States metropolitan areas recommend multi-ingredient adjunctive stacks with flexible titration. Specialist health food stores and clinic-affiliated retail capture this segment through pharmacist-counselled selection.
- Adults:Working-age prediabetic populations drive preventive spending on chromium picolinate and alpha-lipoic acid protocols. India's urban centers concentrate demand where endocrinology clinics integrate supplements into structured management programs.
- Children:Pediatric formulations face elevated safety documentation requirements and limited clinical evidence bases.
- Athletes:Glycogen modulation and recovery positioning serves niche performance nutrition channels.
Adults represent the core consumption base; elderly segments show the steepest expansion trajectory as physician referral networks formalize.
Distribution Channel:
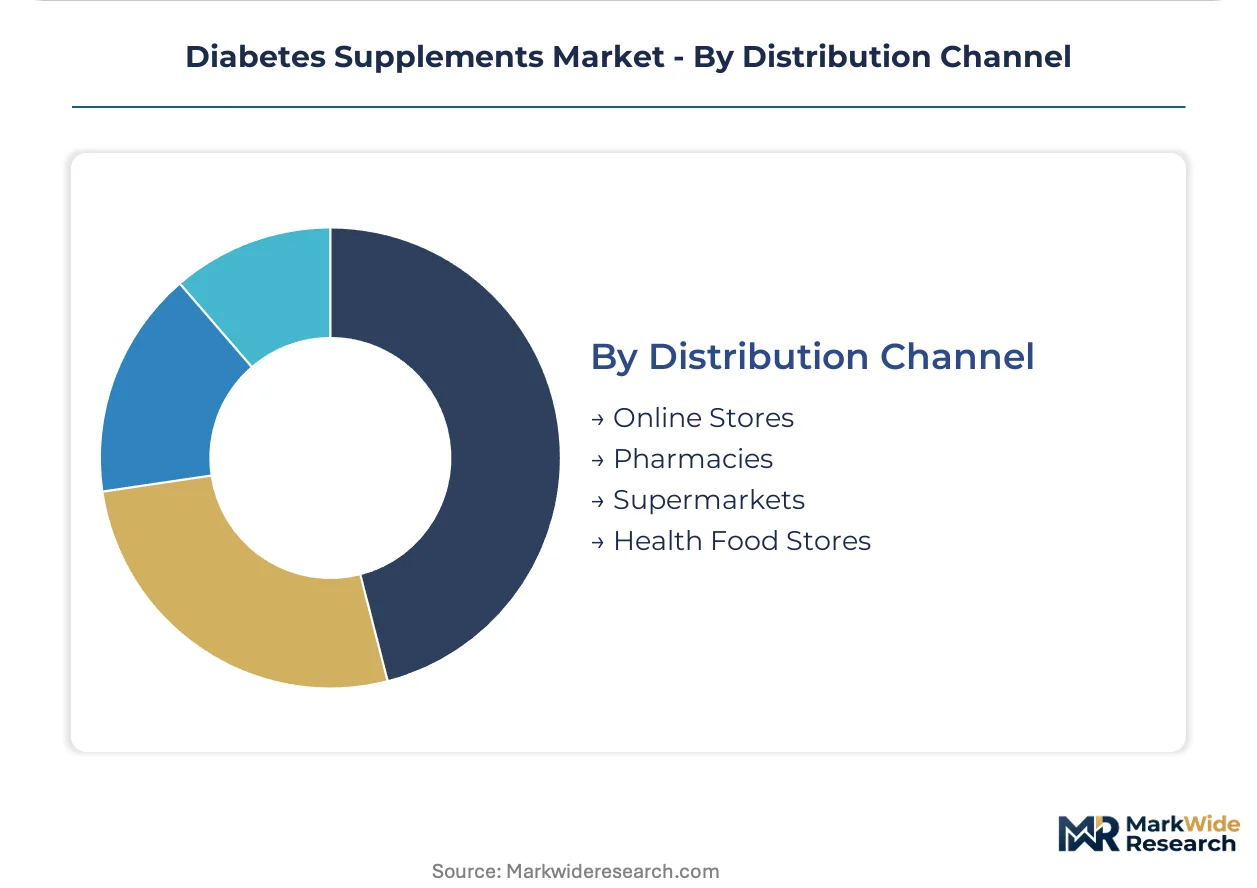
Customer trust patterns are fragmenting acquisition channels, with pharmacist-counselled formats reclaiming share from direct-to-consumer platforms that dominated earlier expansion phases.
- Pharmacies:Mass-market chains and hospital-affiliated retail programs leverage clinical credibility and trained staff consultation. Abbott Laboratories anchors positioning through these channels with professional line distribution.
- Health Food Stores:Specialist retailers differentiate via third-party testing transparency and practitioner-exclusive professional lines. NOW Foods competes here through independent laboratory verification protocols.
- Online Stores:Direct-to-consumer platforms face narrowing trust as FTC enforcement actions against unsubstantiated claims reshape patient acquisition patterns.
- Supermarkets:Convenience positioning captures low-engagement replenishment purchases with limited clinical guidance.
Pharmacies hold the largest share; health food stores are gaining share fastest through trust-based consultation models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States where endocrinology clinics command premium positioning for clinical-grade formulations, while Indian manufacturers compete on Ayurvedic-integrated cost structures that undercut Western mineral-based products by 40-60 percent.
United States
Prediabetic prevention protocols drive chromium picolinate and alpha-lipoic acid demand through reimbursable adjunctive care pathways. FDA structure-function claim regulations enforce rigorous clinical evidence thresholds that elevate compliance costs for new entrants. Endocrinology practices in metropolitan areas maintain captive supplement dispensaries that capture high-engagement patients seeking pharmacist-counselled selection.
India
Ayurvedic-integrated diabetes management protocols gain traction among urban pharmacy chains and endocrinology clinics in Mumbai and Delhi. FSSAI has streamlined traditional medicine approval pathways while CDSCO maintains separate scrutiny for synthetic active ingredients. Bitter melon gourd and cinnamon extract products accelerate through pharmacy chain distribution networks concentrated in Maharashtra and Karnataka.
Germany
REACH and EU Green Deal sustainability mandates reshape botanical extract supply chains for cinnamon and fenugreek sourcing. EMA pharmacovigilance reporting obligations strain post-market surveillance infrastructure for herbal extract manufacturers. Industrial clusters in Bavaria and Baden-Württemberg develop controlled cultivation partnerships to document carbon footprint compliance.
China
Domestic demand for soluble fiber and mineral formulations expands through hospital-affiliated retail programs in Beijing and Shanghai. NMPA imposes batch-to-batch potency consistency requirements that demand capital-intensive quality control systems. Yangtze River Delta manufacturers adopt modified-release polymer systems licensed from pharmaceutical applications.
Japan
Elderly polypharmacy-aware physicians recommend multi-ingredient adjunctive stacks with flexible titration formats. PMDA safety documentation requirements elevate barriers for pediatric formulations with limited clinical evidence bases. METI supports controlled-release coating technology transfers into consumer-grade metabolic support products manufactured in the Kanto region.
Diabetes Supplements Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in botanical extraction and mineral synthesis. The vendor base organizes around three strategic archetypes: multinational nutrition conglomerates with clinical credibility programs, mass-market pharmacy chains competing on shelf-space dominance, and transparency-focused specialists leveraging third-party testing verification. Competitive moves concentrate on pharmacist-counselled channel reclamation and controlled-release technology licensing from pharmaceutical partners.
Among clinical-credibility anchors, Abbott Laboratories represents the hospital-affiliated retail archetype, while Nature's Bounty exemplifies mass-market pharmacy chain positioning. NOW Foods occupies the transparency-specialist tier through practitioner-exclusive professional lines. These three entities collectively illustrate the trust-based fragmentation reshaping patient acquisition patterns away from direct-to-consumer platforms.
| Leading Market Players |
|---|
| Herbalife Nutrition |
| Abbott Laboratories |
| Amway (Nutrilite) |
| Nestlé Health Science |
| Glanbia plc |
| Nature's Bounty |
| NOW Foods |
| Nature's Way Products |
| Swanson Health Products |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on Indian and Chinese botanical extract suppliers determines both tiered pricing spreads and supply chain configuration for diabetes supplement manufacturers. Climate-sensitive cinnamon and bitter melon cultivation regions concentrate extraction capacity in Maharashtra and Karnataka, while chromium picolinate synthesis clusters in Yangtze River Delta industrial zones.
Pricing Analysis
Configured-to-order pricing for practitioner-exclusive professional lines commands 35-50 percent premiums over standard pharmacy shelf formats. Three-tier pricing structure across premium, standard, and economy levels separates third-party tested herbal extracts from commodity mineral tablets and private-label supermarket offerings. Cost compression in the economy tier intensifies as mass-market chains consolidate shelf-space negotiations. Polypharmacy-aware elderly patients in United States metropolitan areas show lowest price sensitivity, while working-age prediabetic adults in Indian urban centers drive volume through cost-optimized Ayurvedic-integrated protocols.
Supply Chain Analysis
Upstream feedstock for standardized botanical extracts draws from climate-resilient cultivation partnerships in India, China, and Vietnam, with extraction method verification adding 15-20 percent to raw material costs. Chromium picolinate and alpha-lipoic acid manufacturing rests on pharmaceutical-grade mineral synthesis from German and Japanese chemical suppliers. Tariff exposure on herbal extract imports strains margin structures for European manufacturers facing REACH sustainability documentation requirements. Distribution runs through pharmacist-counselled health food stores and hospital-affiliated retail programs that bypass direct-to-consumer platform intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Diabetes supplements represent an early-cycle expansion story as prediabetic prevention protocols formalize reimbursable adjunctive care pathways across United States endocrinology networks. Penetration remains below 25 percent among diagnosed prediabetic adults, creating sustained adoption headroom.
For Market Incumbents: Harden clinical evidence dossiers against FTC enforcement actions by front-loading controlled-release technology licensing costs before structure-function claim submissions. Deepen backward integration into traceable cinnamon and fenugreek cultivation partnerships to defend margin position against climate-driven botanical price volatility. Capture pharmacist-counselled channel control through exclusive professional line distribution agreements with hospital-affiliated retail programs.
For New Entrants and Emerging Players: Pursue white-space positioning in elderly flexible titration formats where polypharmacy-aware physician referrals concentrate in United States geriatric care settings. Target India's FSSAI-streamlined traditional medicine approval pathway for Ayurvedic-integrated bitter melon gourd formulations distributed through Maharashtra pharmacy chain networks. Anchor go-to-market strategy through third-party testing transparency that commands premium positioning in specialist health food store channels.
For Investors and Strategic Acquirers: The market sits at a clinical-evidence-escalation phase that favors transparency-focused specialists with established practitioner-exclusive professional lines over mass-market shelf-space competitors. Long-term viability over the next decade hinges on regulatory compliance infrastructure rather than brand marketing scale. Watch for FTC enforcement action frequency as the inflection indicator separating defensible structure-function claim holders from liability-exposed legacy portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| Controlled-Release Technology Licensing | Modified-release polymer systems from pharmaceutical partners flatten glucose response curves for clinical-grade positioning. |
| Third-Party Testing Transparency Program | Independent laboratory verification protocols differentiate practitioner-exclusive lines in pharmacist-counselled channels. |
| Traceable Cultivation Partnership | Climate-resilient cinnamon and fenugreek sourcing secures batch-to-batch potency consistency for metabolic efficacy claims. |
| FSSAI Traditional Medicine Approval | Streamlined Ayurvedic-integrated pathways accelerate bitter melon gourd product launches through Indian pharmacy chains. |
| Hospital-Affiliated Retail Program | Captive supplement dispensaries in United States metropolitan endocrinology practices capture high-engagement patient segments. |
Methodological Framework
Cross-validation between primary interviews with industry stakeholders and secondary regulatory filings anchors the qualitative findings in documented evidence standards. Endocrinology clinic directors, pharmacy chain procurement managers, FSSAI regulatory affairs consultants, and herbal extract quality control directors provided operational perspective. FDA structure-function claim submissions, FTC enforcement action databases, FSSAI approval registries, and EMA pharmacovigilance reports supplied secondary validation. Bottom-up demand modeling across delivery modes and top-down market sizing through value chain analysis enabled triangulation.
Calibration against historical adoption curves for preventive metabolic health products shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, delivery mode, end user age cohort, and distribution channel archetype. CAGRs derived from regression analysis of preventive health spending elasticity and regulatory approval velocity. Forecast inputs incorporated prediabetic population screening expansion rates and pharmacist-counselled channel share migration patterns.
Sensitivities concentrate around FTC enforcement intensity and climate-driven botanical supply disruptions. Forecasts reflect assumptions on regulatory stability and cultivation yield consistency. Cross-checking against CMS Medicare supplement reimbursement data and Indian pharmacy chain sales audits is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dietary Supplements
Global Effervescent Tablet Market
Dietary Supplements
Magnesium Glycinate Market
Dietary Supplements
Serotonin Supplement Market
Dietary Supplements
Global Lipid Regulators Market
Dietary Supplements
Detox Products Market
Dietary Supplements
Folic Acid Tablets Market
Dietary Supplements
Womens Health and Beauty Supplements Market
Dietary Supplements
Canine Weight Loss Drugs Market
Dietary Supplements
Hair Loss Supplement Market
Dietary Supplements
Pet Allergy Immune Supplements Market
Dietary Supplements
Postpartum Health Supplements Market
Dietary Supplements
Postnatal Health Supplements Market
Dietary Supplements
Medicated Confectionery Market
Dietary Supplements
Bone and Joint Health Supplements Market
Dietary Supplements
Veterinary Dietary Supplements Market
Dietary Supplements
Colostrum Chewable Tablets Market