
 Pet Calming Products Market | 2026-2036
Pet Calming Products Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Calming Products Market Analytics
Veterinary clinic prescribing is shifting toward non-pharmaceutical calming protocols before pharmaceutical intervention. Pet specialty retailers now stock expanded calming assortments. Zesty Paws dominates the chews segment through flavor innovation and subscription channel control. NaturVet anchors the herbal ingredient niche with veterinarian-formulated positioning. VetriScience competes on clinical validation and veterinary-exclusive distribution.
Pet calming products encompass ingestible and environmental formulations designed to mitigate stress behaviors in companion animals through neurochemical modulation, typically containing L-theanine, valerian root, pheromone analogs, or synthetic GABAergic compounds at concentrations between 5 mg and 250 mg per dose. These products serve commercial purposes spanning pre-visit veterinary preparation, travel acclimation, noise phobia management, and multi-pet household integration. The chews category leads volume due to palatability and dosing convenience, while the organic ingredient segment captures expanding margin pools as clean-label preferences migrate from human to pet nutrition. E-commerce distribution is accelerating fastest among channels, though veterinary clinics retain premium pricing power through professional endorsement.
The FDA Center for Veterinary Medicine regulates calming product label claims and ingredient safety assessments for products marketed in the United States. The National Animal Supplement Council provides industry self-regulation through quality seal programs that influence retailer stocking decisions. AAFCO model bills guide state-level enforcement of pet product labeling standards. Stakeholders must monitor evolving veterinary telehealth regulations, as remote prescribing authority will reshape which distribution channels capture professional-recommended calming product sales.
Market Dynamics
Veterinary prescribing protocols are pivoting toward non-pharmaceutical calming interventions before pharmaceutical escalation, reshaping distribution hierarchies and professional endorsement economics across the companion animal wellness sector.
Growth Catalysts
- FDA Center for Veterinary Medicine label guidance:The agency's clarified distinction between nutritional supplements and unapproved animal drugs reduces regulatory uncertainty for manufacturers, accelerating new product introductions.
- Telehealth prescribing authority expansion:Remote veterinary consultation platforms in the United States now incorporate calming product recommendations into digital care protocols, opening professional-channel access without clinic visits.
- L-theanine microencapsulation:This delivery technology improves bioavailability in chew formulations, enabling precise dosing that satisfies veterinary efficacy standards and drives repeat purchase rates.
Market Restraints
- Valerian root supply concentration:Raw material sourcing clusters in Eastern European agricultural zones, exposing formulators to weather-driven harvest volatility and geopolitical transit disruptions.
- AAFCO model bill adoption variance:State-level enforcement inconsistency creates labeling compliance fragmentation, forcing manufacturers to maintain multiple packaging SKUs for interstate distribution.
- Pharmaceutical anxiolytic substitution:Generic fluoxetine and trazodone formulations maintain strong veterinary preference for severe anxiety cases, capping the addressable market for nutraceutical alternatives.
Strategic Opportunities
- Subscription commerce penetration:Direct-to-consumer auto-ship platforms capture recurring revenue with higher lifetime value than retail, particularly among urban millennial pet owners.
- Pheromone diffuser veterinary exclusives:Clinic-dispensed environmental calming devices command premium pricing through professional installation services and follow-up monitoring protocols.
- USDA organic certification migration:Clean-label positioning aligned with human wellness trends opens margin expansion in specialty retail and natural grocery channels.
Industry Challenges
- Veterinary nutritionist talent scarcity:Formulation expertise bridging human supplement science and companion animal metabolism remains concentrated among a limited pool of credentialed specialists.
- Clinical validation timeline compression:Peer-reviewed efficacy studies require 18-24 month investment horizons, misaligned with fast-follower competitive pressure from private-label entrants.
- Multi-channel inventory synchronization:Differential pricing between veterinary, retail, and e-commerce channels demands sophisticated demand forecasting to prevent arbitrage erosion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet Calming Products Market |
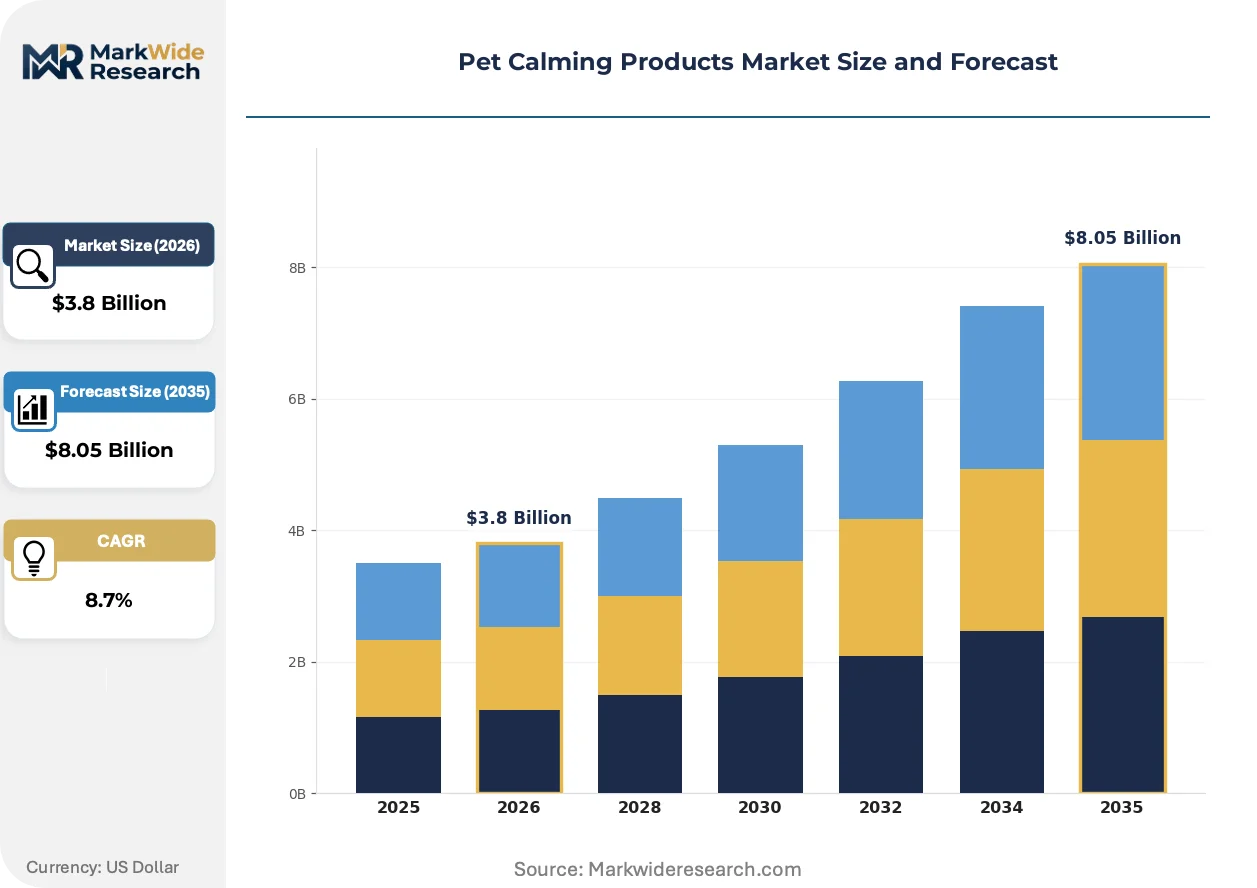
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chews, Sprays, Diffusers, Wearables Ingredient: Herbal, Synthetic, Organic, Nutraceutical End User: Pet Owners, Veterinarians, Pet Stores, Online Retailers Distribution Channel: Retail, E-commerce, Wholesale, Veterinary Clinics |
| Companies Covered | Solid Gold, VetIQ, Nutri-Vet, Pupford, VetriScience, NaturVet, Zesty Paws, PetPax Co., Premium Care, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Calming Products Market Evolving Landscape
Formulation science and distribution architecture are undergoing parallel transformation, with bioavailability engineering reshaping product efficacy claims and digital-first channels capturing professional recommendation flows.
Microencapsulation of active compounds is converging with palatability engineering to create chew matrices that mask herbal bitterness while protecting pheromone and amino acid integrity through gastric transit. Veterinary clinics in metropolitan United States markets are adopting these advanced formulations at accelerated rates, substituting them for compounded preparations. This convergence is compressing the efficacy gap between nutraceutical and pharmaceutical interventions, forcing incumbent drug manufacturers to defend prescription volumes through combination therapy positioning.
REACH chemical registration requirements in Europe are extending to novel synthetic pheromone analogs, imposing toxicological dossier obligations that favor established suppliers with regulatory affairs infrastructure. The industrial consequence is a consolidation threshold for new market entrants, particularly those sourcing Chinese-manufactured active ingredients. Pheromone diffuser manufacturers with EU distribution ambitions are responding by vertically integrating toxicology testing and establishing Brussels-based regulatory liaison functions.
Subscription auto-replenishment is displacing episodic retail purchase as the dominant acquisition model for chronic anxiety management products, with pet owners accepting algorithmic dosing reminders and automated delivery scheduling. Specialty e-commerce platforms and veterinary telehealth portals are capturing this behavioral shift, while brick-and-mortar pet retailers face traffic compression in the calming category. This pattern concentrates most visibly in coastal United States urban markets, where household penetration of pet wellness subscriptions already exceeds national averages by substantial margins.
Pet Calming Products Market Segmentation
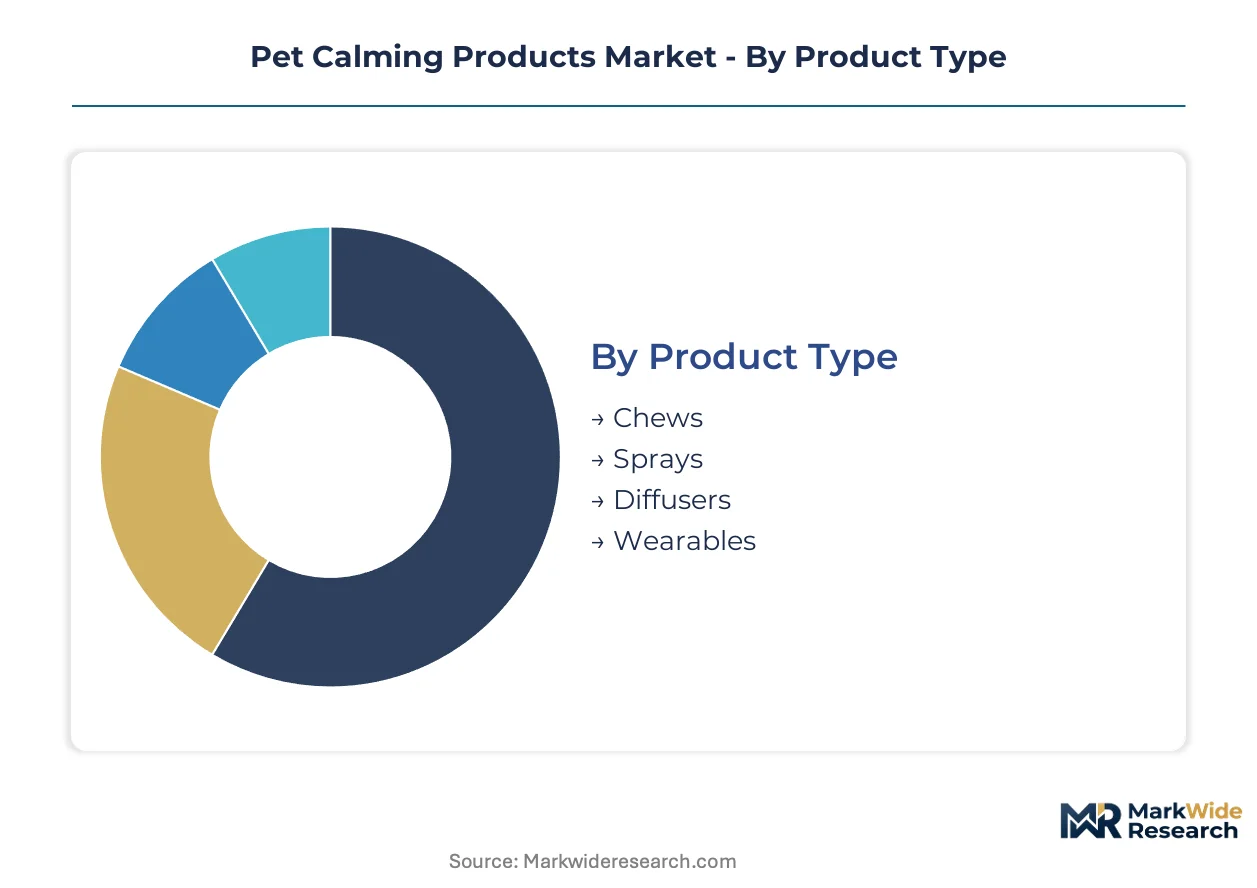
Segmentation in pet calming products determines regulatory pathway complexity and channel access. FDA Center for Veterinary Medicine scrutiny intensifies for synthetic formulations, while organic certifications unlock premium retail placement. Understanding these divides clarifies where formulation investment and distribution partnerships yield highest returns.
Product Type:
Chews and diffusers carry distinct certification burdens: chews face AAFCO nutritional adequacy review and state feed control approvals, while pheromone diffusers trigger EPA pesticide device registration if efficacy claims cross into pest behavioral modification territory.
- Chews:Palatable matrices combining L-theanine, valerian root, or tryptophan in 5-250 mg doses, microencapsulated to survive gastric transit. Demand concentrates in United States urban households with noise-phobic dogs, driven by subscription auto-replenishment models that lock in recurring revenue.
- Diffusers:Plug-in devices emitting synthetic pheromone analogs mimicking canine appeasing pheromone or feline facial pheromone. Veterinary clinics in metropolitan United States markets capture premium pricing through professional installation protocols and follow-up monitoring services.
- Sprays:Topical environmental applications for travel crates and bedding, requiring precise concentration labeling under FDA guidance.
- Wearables:Collar-integrated pheromone reservoirs and pressure-applying wraps, regulated as animal health devices with variable state-by-state classification.
Leading the category by volume: Chews. Growing fastest: Diffusers through veterinary exclusive distribution.
Ingredient:
Cost tier stratification separates commodity botanical sourcing from precision-synthetic manufacturing, with organic certification adding 15-40% formulation cost premiums that transfer to shelf price.
- Herbal:Valerian root, chamomile, and passionflower extracts standardized to marker compound concentrations. Supply concentrates in Eastern European agricultural zones, exposing formulators to harvest volatility and transit disruptions through Black Sea corridor instability.
- Synthetic:Laboratory-manufactured pheromone analogs and GABAergic compounds with batch-to-batch consistency. REACH chemical registration requirements in Europe impose toxicological dossier obligations favoring established suppliers with regulatory affairs infrastructure.
- Organic:USDA-certified botanicals and amino acids meeting human-grade processing standards. Clean-label positioning captures margin expansion in specialty retail and natural grocery channels as human wellness trends migrate to pet nutrition.
- Nutraceutical:L-theanine, melatonin, and alpha-casozepine at clinically validated doses, bridging supplement and pharmaceutical efficacy claims.
Highest margin capture: Organic. Steepest expansion trajectory: Nutraceutical as veterinary protocols shift toward evidence-based non-pharmaceutical intervention.
End User:
Application context dictates formulation sophistication and dosing precision requirements, with veterinary endorsement commanding price premiums over direct-to-consumer channels.
- Pet Owners:Direct purchasers managing chronic anxiety, travel stress, and noise phobia in household companion animals. E-commerce platforms and subscription services dominate acquisition, particularly among millennial urban demographics.
- Veterinarians:Professional prescribers integrating calming protocols into pre-visit preparation and behavioral modification programs. Telehealth prescribing authority expansion now incorporates calming product recommendations into digital care protocols.
- Pet Stores:Specialty retailers curating expanded calming assortments with trained staff consultation, competing on immediate availability versus online convenience.
- Online Retailers:Algorithmic recommendation engines and auto-ship functionality capturing chronic condition management with higher lifetime value than episodic purchase.
Deepest pricing power: Veterinarians. Fastest channel shift: Online Retailers displacing brick-and-mortar traffic.
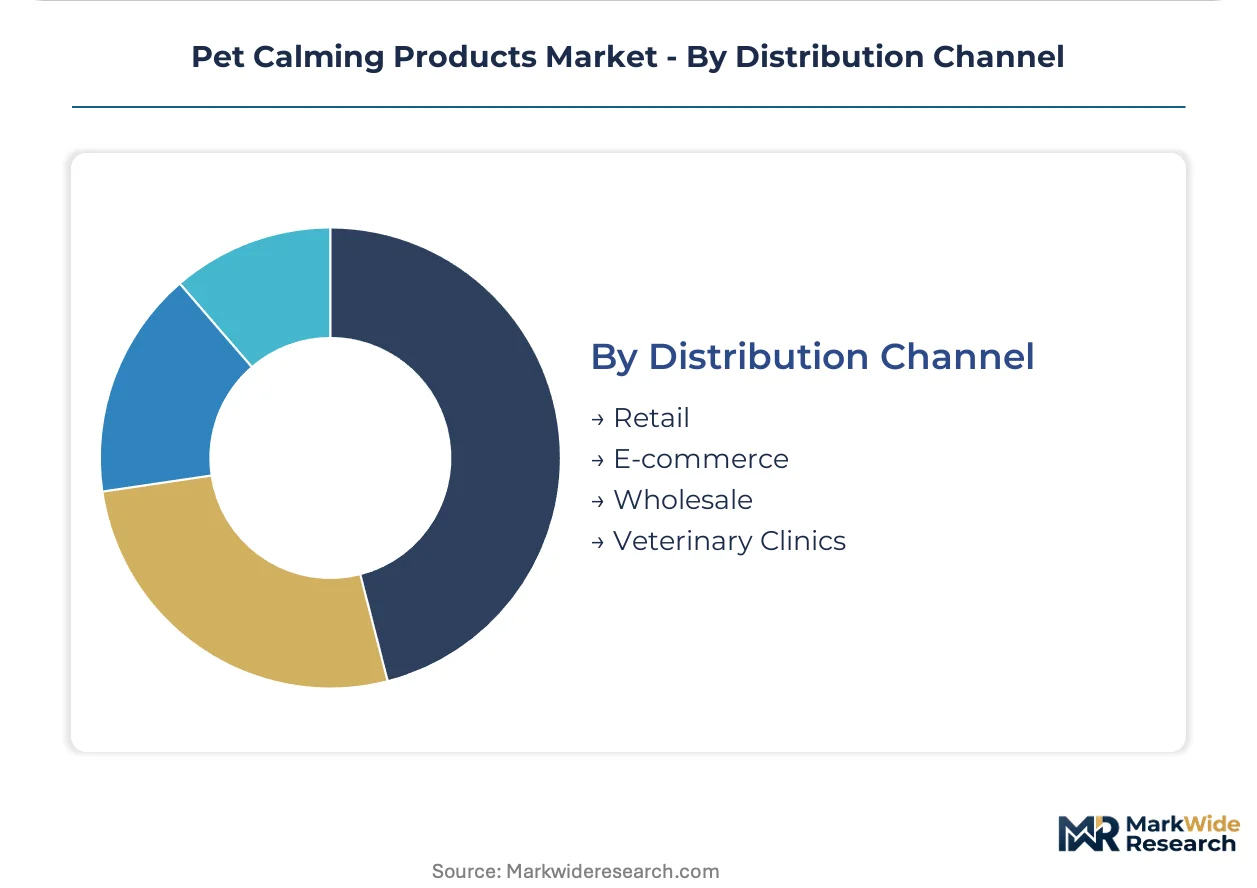
Distribution Channel:
Channel selection determines margin structure and professional endorsement access, with veterinary exclusives sustaining premium positioning against retail commoditization pressure.
- Retail:Mass-market and specialty pet stores competing on shelf placement and promotional velocity. Brick-and-mortar traffic faces compression as subscription models capture chronic anxiety management.
- E-commerce:Direct-to-consumer platforms and marketplace aggregators with algorithmic replenishment and dosing reminder functionality. Coastal United States urban markets show household penetration exceeding national averages.
- Wholesale:Bulk supply to veterinary distributors and private-label retailers, requiring inventory synchronization across differential pricing tiers.
- Veterinary Clinics:Professional-channel dispensing with clinical validation requirements and follow-up protocol integration. Clinic-dispensed environmental devices command premium pricing through installation services.
Highest average transaction value: Veterinary Clinics. Most rapid volume migration: E-commerce.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of pheromone analogs and herbal extracts clusters in select production zones, while consumption concentrates in affluent urban pet-owning populations across North America, Europe, and developed Asia-Pacific markets.
United States
Pet humanization trends and premium spending power drive demand in coastal metropolitan corridors. The FDA Center for Veterinary Medicine enforces label claim distinctions between supplements and unapproved animal drugs. Los Angeles and New York veterinary clinics pioneer subscription-based calming protocol programs.
Germany
REACH chemical registration requirements impose toxicological dossier obligations on synthetic pheromone manufacturers. ECHA compliance infrastructure favors established suppliers with regulatory affairs capabilities. Bavaria hosts concentrated production of veterinary-grade botanical extracts serving EU distribution networks.
United Kingdom
Veterinary telehealth adoption accelerates professional-channel access for calming product recommendations. The Veterinary Medicines Directorate aligns with EU regulatory frameworks post-Brexit. London specialty pet retailers curate expanded organic and clean-label assortments for affluent urban demographics.
Japan
Aging pet populations and single-person households elevate anxiety management spending per animal. PMDA oversight ensures stringent safety assessments for imported calming formulations. Tokyo veterinary practices integrate environmental calming devices into pre-visit preparation protocols.
Australia
High pet ownership rates and outdoor lifestyle stressors sustain demand for travel and noise-phobia solutions. The TGA regulates therapeutic claims on animal health products. Melbourne and Sydney e-commerce platforms capture subscription auto-replenishment growth exceeding national averages.
Pet Calming Products Market Competitive Landscape
Top-tier vendors anchor veterinary-exclusive and premium retail channels, while mid-tier competitors populate mass-market and private-label segments. The vendor base stratifies across three tiers: clinically validated formulators with professional endorsement, flavor-engineered direct-to-consumer specialists, and contract manufacturers serving retailer private labels. Competitive moves concentrate on subscription platform acquisition and USDA organic certification migration.
Within the clinically validated tier, VetriScience and NaturVet occupy positions emphasizing veterinary-formulated positioning and herbal ingredient specialization. Zesty Paws anchors the direct-to-consumer vector through flavor innovation and subscription channel control. These three entities exemplify divergent archetypes: professional-channel validation, botanical niche dominance, and palatability-driven mass-market penetration.
| Leading Market Players |
|---|
| Solid Gold |
| VetIQ |
| Nutri-Vet |
| Pupford |
| VetriScience |
| NaturVet |
| Zesty Paws |
| PetPax Co. |
| Premium Care |
| Others |
Value Network & Pricing Analysis
Valerian root harvest volatility in Eastern European agricultural zones propagates through formulation costs to veterinary-exclusive pricing tiers, compressing margins for manufacturers lacking long-term supply contracts or captive cultivation relationships.
Pricing Analysis
Margin tightening in mass-market chews reflects raw material cost pass-through limitations and private-label substitution pressure. Three-tier pricing structure across premium, standard, and economy levels separates USDA-certified organic formulations from conventional botanical blends and economy private-label alternatives. Veterinary clinics retain least price sensitivity through professional endorsement premiums, while mass-market retail buyers exhibit highest elasticity to promotional discounting.
Supply Chain Analysis
Regional distribution centers in the United States, Germany, and Japan coordinate hub-and-spoke patterns for pheromone diffuser deployment. Raw material sourcing draws from Eastern European valerian cultivation, Chinese amino acid manufacturing, and Japanese precision pheromone synthesis. Single-source vulnerability concentrates in Black Sea corridor transit routes for botanical extracts. Distribution runs through veterinary distributors, direct-to-consumer fulfillment centers, and specialty retail replenishment networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into raw material cultivation and captive pheromone manufacturing capacity represents the decisive competitive race, with upstream control over valerian supply and synthetic analog production determining margin sustainability.
For Market Incumbents: Extend clinical validation pipelines to defend against nutraceutical commoditization, while securing multi-year valerian supply contracts from Bulgarian and Romanian agricultural cooperatives. Backward integration into microencapsulation technology protects formulation differentiation from fast-follower replication. For New Entrants and Emerging Players: Launch via subscription-first direct-to-consumer models targeting coastal United States urban millennials, where pet wellness subscription penetration exceeds national benchmarks. USDA organic certification unlocks natural grocery channel access with premium positioning against established mass-market brands. For Investors and Strategic Acquirers: FDA Center for Veterinary Medicine telehealth prescribing guidance expansion is the leading indicator that professional-channel revenue pools will concentrate among platforms integrating remote consultation with product fulfillment. Acquisition targets should demonstrate veterinary-exclusive distribution relationships and proprietary bioavailability delivery technologies. Long-term viability hinges on regulatory affairs infrastructure capable of navigating evolving supplement-drug distinction enforcement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Raw Material Cultivation | Captive valerian supply from Bulgarian agricultural zones insulates margin from harvest volatility. |
| USDA Organic Certification Migration | Clean-label positioning captures specialty retail shelf space and natural grocery channel expansion. |
| Veterinary Telehealth Platform Partnership | Remote prescribing authority integration secures professional-channel access without clinic infrastructure. |
| Microencapsulation Technology Acquisition | Bioavailability engineering patents create formulation differentiation defensible against generic replication. |
| Subscription Commerce Infrastructure Buildout | Auto-replenishment algorithms capture recurring revenue with superior lifetime value metrics. |
Research Methodology
Multi-period observation of veterinary prescribing protocol shifts, e-commerce channel migration rates, and raw material cost indices anchored the trend analysis, supplemented by interviews with veterinary behaviorists, pet specialty retail category managers, contract manufacturing executives, and regulatory affairs consultants. Secondary validation drew from FDA Center for Veterinary Medicine guidance documents, AAFCO model bill adoption tracking, EPA pesticide device registration databases, and customs trade data for botanical extract imports. Bottom-up segment sizing triangulated against top-down market envelope estimates.
Input-output matrices modeled volume and value trajectories across product type, ingredient certification tier, end-user application context, and distribution channel structure throughout the forecast period. CAGRs derived from regression analysis of historical veterinary expenditure patterns, pet ownership demographic shifts, and premiumization trend velocities. Industry-specific forecast inputs included telehealth adoption curves and organic certification penetration rates.
Regulatory enforcement variance across state jurisdictions, raw material supply disruption events, and pharmaceutical substitution preference shifts are the dominant revision risks to projection accuracy. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
UTI Cat Food Market
Pet Care Products
Large Breed Dog Food Market
Pet Care Products
Modern Cat Furniture Market
Pet Care Products
Argentina Pet Food Market
Pet Care Products
North America Pet Treats Market
Pet Care Products
Germany Pet Clothing Market
Pet Care Products
Plant-Based Pet Food Market
Pet Care Products
Pet Grooming Supplies Market
Pet Care Products
Japan Pet Food Market
Pet Care Products
Global Cat Trees and Towers Market
Pet Care Products
Robotic Pets Market
Pet Care Products
Pet Accessories Market
Pet Care Products
UAE Dog Food Market
Pet Care Products
Dog Clothing and Accessories Market
Pet Care Products
Outdoor Cat House Market
Pet Care Products
Dog Float Market