
 Dog Food for Small Breeds Dogs Market | 2026-2036
Dog Food for Small Breeds Dogs Market Size, Share, and Industry Trends Forecast 2026-2036
Dog Food for Small Breeds Dogs Market Insights
Buyer concentration among millennial and Gen Z pet owners is shifting toward premium subscription channels and direct-to-consumer platforms. Mars Petcare leverages its veterinary clinic networks to sustain recurring purchase patterns. Hill's Pet Nutrition anchors its position through prescription-grade small-breed formulations. Blue Buffalo differentiates via grain-free positioning and natural ingredient claims.
Dog food for small breeds dogs denotes nutritionally dense formulations engineered for dogs under 20 pounds, with kibble dimensions typically below 10 millimeters to accommodate smaller jaw structures and faster metabolic rates. These products incorporate elevated protein-to-calorie ratios and enhanced omega fatty acid profiles to address dental health and weight management needs in compact breeds. Dry food occupies the dominant volume position due to shelf stability and cost efficiency, while raw food segments command premium margins through freeze-dried and refrigerated delivery models. Limited ingredient diets are gaining traction among owners managing food sensitivities common in toy breeds such as Yorkshire Terriers and Shih Tzus.
The FDA Center for Veterinary Medicine enforces ingredient safety and facility sanitation standards that directly shape formulation costs and recall exposure for manufacturers. AAFCO nutrient profiles establish minimum thresholds for small-breed-specific claims, creating compliance barriers for new entrants without dedicated veterinary nutritionists. State-level feed control officials in California and Texas conduct parallel inspections that amplify regulatory complexity for national distribution. Stakeholders must monitor evolving clean-label demands alongside tightening traceability requirements for novel protein sources.
Market Dynamics
Millennial and Gen Z pet owners are forcing a channel restructuring toward direct-to-consumer subscription models, bypassing traditional retail intermediaries that historically controlled shelf placement and pricing power in the small-breed segment.
Growth Catalysts
- AAFCO Nutrient Profiles:Mandatory minimum thresholds for breed-specific claims create compliance moats that filter out undercapitalized competitors and reward manufacturers with dedicated veterinary nutritionists.
- Freeze-Dried Protein Processing:Cold-chain logistics improvements are expanding raw food distribution beyond coastal urban centers into secondary metropolitan markets.
- Urban Household Density:Apartment-dwelling pet ownership rates in dense US cities drive demand for compact-packaging formats and odor-mitigating formulations.
Market Restraints
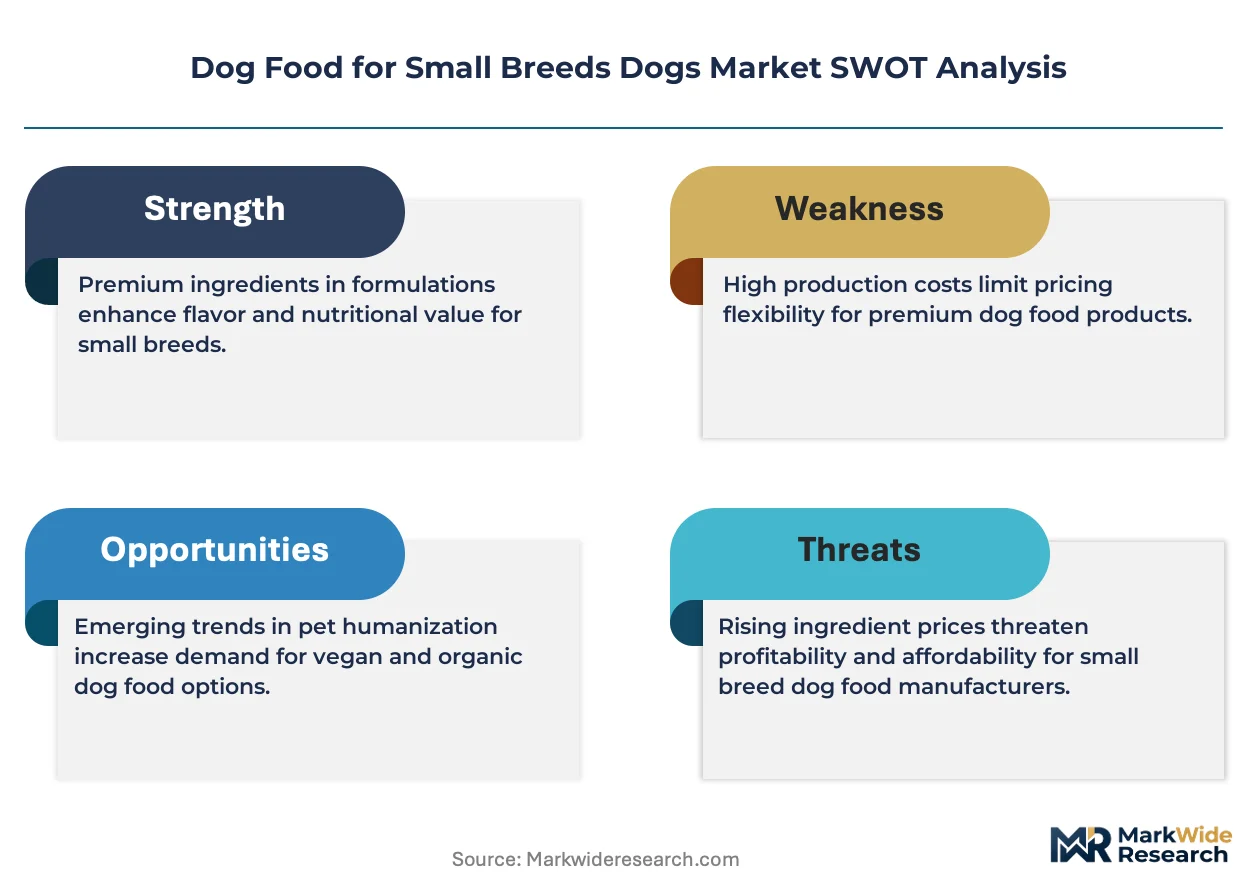
- Animal Protein Input Volatility:Chicken meal and salmon oil prices fluctuate with commodity agriculture cycles, compressing margin predictability for mid-tier brands.
- FDA Recall Exposure:Pathogen detection mandates for raw food facilities impose catastrophic liability risk that discourages regional co-packer entry.
- Substitution by Human-Grade Fresh:Refrigerated pet meal services using USDA-inspected kitchens capture premium spend from small-breed owners seeking ingredient transparency.
Strategic Opportunities
- Veterinary Telehealth Integration:Remote consultation platforms enable prescription diet recommendations without physical clinic visits, opening rural and exurban markets.
- Novel Insect Protein Sources:Black soldier fly larvae cultivation offers sustainable amino acid profiles with lower land-use intensity than conventional livestock.
- State-Level Organic Feed Incentives:California and Vermont tax credits for certified organic production reward capital investment in supply chain upgrading.
Industry Challenges
- Veterinary Nutritionist Talent Scarcity:Board-certified specialists command compensation premiums that strain R&D budgets at sub-scale manufacturers.
- Legacy ERP Integration Friction:Batch-level traceability requirements for FDA compliance conflict with decades-old inventory management systems at family-owned mills.
- Co-Packer Capacity Constraints:Qualified small-batch facilities face 12-18 month qualification queues, delaying new product commercialization timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dog Food for Small Breeds Dogs Market |
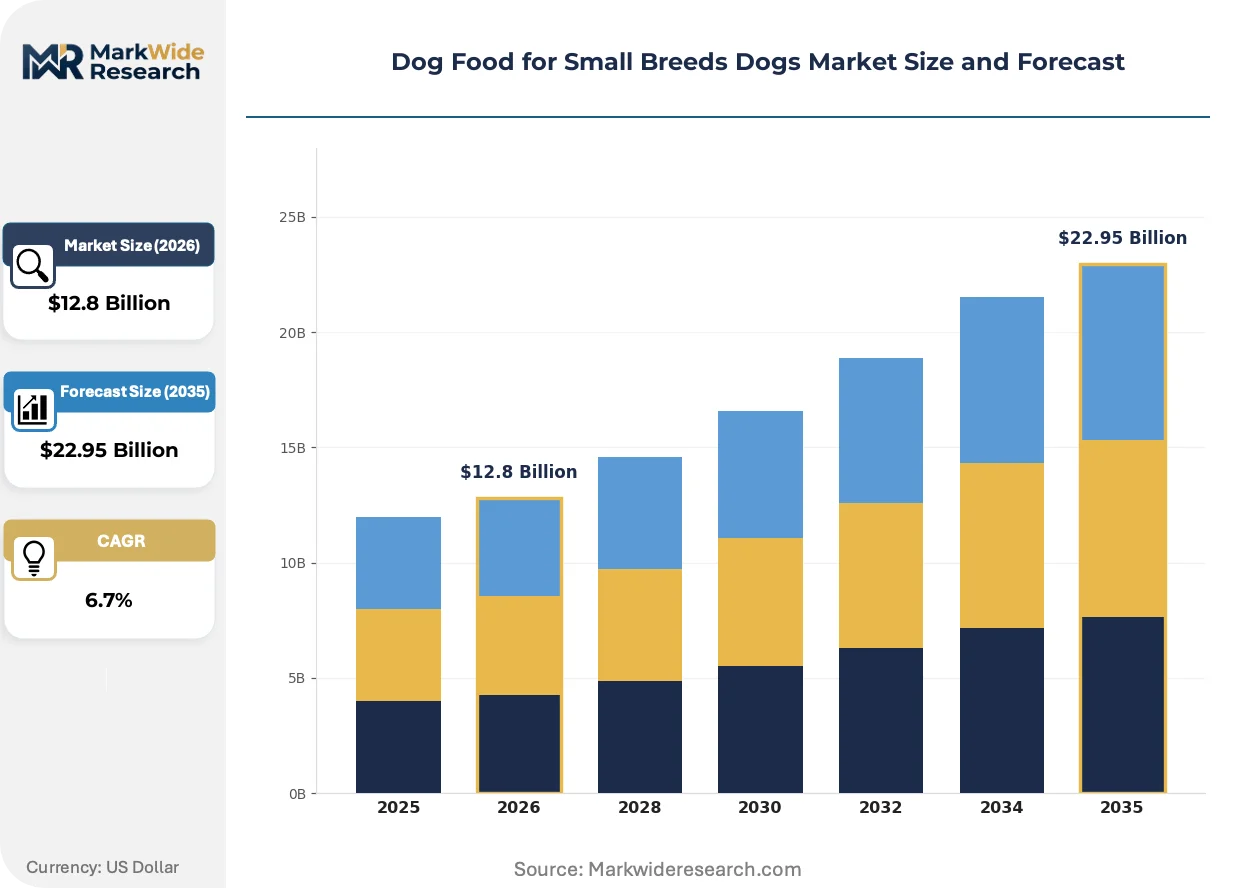
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Treats, Raw Food Ingredient Type: Organic, Grain-Free, High-Protein, Limited Ingredient Life Stage: Puppy, Adult, Senior, All Life Stages Packaging Type: Bags, Cans, Pouches, Bulk |
| Companies Covered | Nestlé Purina Pet Care, Mars Petcare, Hill's Pet Nutrition, General Mills, Royal Canin, Blue Buffalo, Wellness CORE, Orijen, Merrick, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dog Food for Small Breeds Dogs Market Trends and Innovations
Formulation science and distribution infrastructure are converging to enable personalized nutrition at scale, collapsing the traditional trade-off between mass manufacturing efficiency and individual pet health optimization.
Microbiome testing kits paired with algorithmic diet recommendation engines are modularizing the relationship between diagnostic data and feeding protocols. Subscription services in Seattle and Austin integrate at-home stool sample collection with monthly kibble adjustments. This convergence is modularizing veterinary nutrition from a clinic-delivered service into a data-driven consumer product.
The FDA's updated pet food labeling requirements are forcing ingredient declaration granularity down to sub-component percentages. Facilities must revalidate nutritional databases and reformulate recipes that previously relied on composite ingredient descriptions. Small-breed wet food lines face disproportionate reformulation costs due to higher ingredient counts per calorie density.
Subscription auto-shipment models are displacing periodic retail replenishment among time-constrained urban professionals. Direct-to-consumer platforms capture recurring revenue streams that grocery and big-box channels cannot replicate. California and New York metropolitan areas exhibit the highest subscription penetration rates, with toy breed owners showing 40% lower churn than large-breed counterparts.
Dog Food for Small Breeds Dogs Market Segmentation
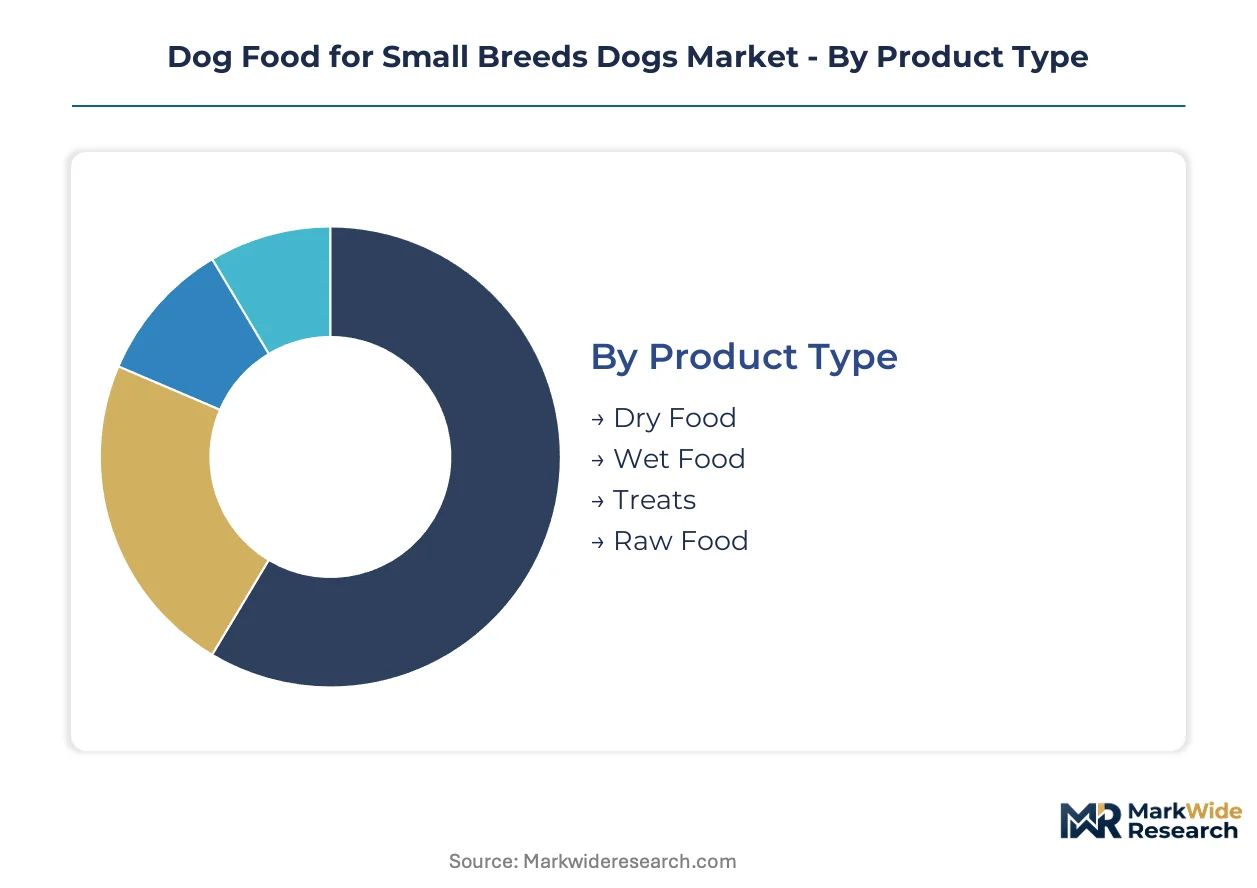
Segmentation in the small-breed dog food market reflects divergent owner priorities: cost-conscious buyers favor shelf-stable formats while premium seekers prioritize ingredient provenance and metabolic customization. Manufacturers must align formulation density, packaging geometry, and protein sourcing to specific breed-size requirements rather than generic canine nutrition standards.
Product Type:
Dry food commands volume leadership through manufacturing scale and distribution efficiency, yet margin concentration is shifting toward minimally processed alternatives.
- Dry Food:Extruded kibble under 10 millimeters targets dental health and calorie density for toy breeds with accelerated metabolisms. Demand clusters in multi-pet households across Texas and Florida where cost-per-serving calculations dominate purchase decisions. Shelf stability enables warehouse club penetration that wet formats cannot match.
- Wet Food:Moisture-rich formulations address hydration deficits common in brachycephalic breeds like Pugs and French Bulldogs. Premium positioning in urban coastal markets leverages palatability advantages for picky eaters. Retort processing costs constrain regional brand participation.
- Treats:Functional dental chews and training rewards occupy impulse purchase occasions with minimal brand loyalty.
- Raw Food:Freeze-dried and refrigerated segments capture subscription revenue through cold-chain logistics investments.
Mature deployment sits with Dry Food. Newer deployment is concentrated in Raw Food.
Ingredient Type:
Clean-label positioning has fragmented the ingredient landscape, with certification costs creating tiered entry barriers that favor scaled organic handlers.
- Organic:USDA-certified supply chains command 20-40% price premiums in California and Vermont markets where state-level tax credits incentivize production conversion. Sourcing constraints limit national distribution to brands with captive agricultural partnerships.
- Grain-Free:Legume and tuber substitutes address documented sensitivities in Yorkshire Terriers and Shih Tzus. FDA investigations into dilated cardiomyopathy links have forced formulation adjustments using taurine supplementation. Litigation exposure concentrates in class-action jurisdictions.
- High-Protein:Elevated animal protein ratios target weight management in neutered small breeds prone to obesity.
- Limited Ingredient:Single-source protein diets serve elimination protocols for allergic dogs requiring veterinary supervision.
Grain-Free represents the most volatile trajectory. Organic exhibits the steadiest expansion trajectory.
Life Stage:
Puppy formulations concentrate nutritional density for developmental windows, while senior segments address declining dental function and joint mobility.
- Puppy:Elevated DHA and calcium-phosphorus ratios support neurodevelopment and skeletal formation in breeds under 20 pounds. Breeders and first-time owners in suburban Atlanta and Phoenix drive trial purchases. Veterinary endorsement requirements filter mass-market participation.
- Adult:Maintenance formulations balance palatability with weight control for spayed and neutered pets with reduced caloric needs.
- Senior:Glucosamine fortification and softer textures accommodate periodontal disease prevalence in aging toy breeds.
- All Life Stages:Simplified inventory appeals to multi-dog households with varying ages but sacrifices optimization for any single developmental phase.
Adult maintains volume concentration. Puppy is gaining share fastest.
Packaging Type:
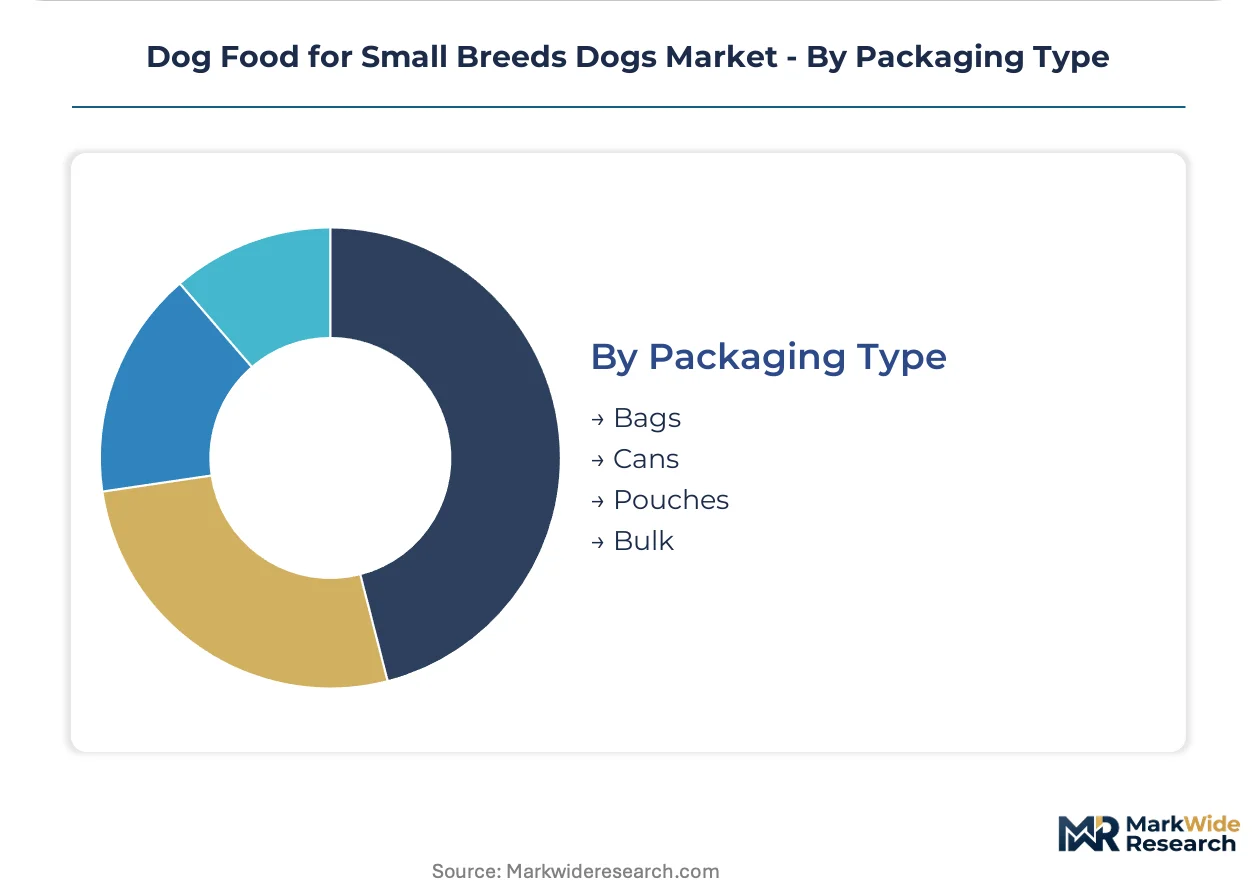
Format selection reflects channel strategy: brick-and-mortar relies on shelf-ready bags while direct-to-consumer experiments with portion-controlled pouches.
- Bags:Multi-layer barrier films protect lipid oxidation in omega-3 enriched formulations. Stand-up pouches with resealable closures dominate mass retail resets. Recycling program participation varies by municipal infrastructure availability.
- Cans:Steel and aluminum containers preserve wet food sterility without refrigeration. Weight and cube inefficiency disadvantage e-commerce fulfillment.
- Pouches:Flexible single-serve formats reduce portion waste for small appetites and enable trial sampling.
- Bulk:Refill stations in specialty retail appeal to zero-waste consumers in Portland and Austin metropolitan areas.
Bags anchor mainstream distribution. Pouch adoption is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Midwestern grain belts and Pacific Northwest salmon fisheries anchor raw material sourcing for small-breed formulations. Urban pet ownership density and veterinary infrastructure concentration determine finished product demand distribution across major economies.
United States
Apartment-dwelling millennial pet owners in Seattle and Austin drive subscription auto-shipment penetration. The FDA Center for Veterinary Medicine enforces pathogen detection mandates for raw food facilities. California's state-level organic feed tax credits incentivize supply chain conversion among coastal manufacturers.
Germany
Discerning Dachshund and Pomeranian owners in Berlin and Munich prioritize grain-free and limited-ingredient diets. EFSA guidelines on novel protein safety assessments shape insect-based formulation development. Bavarian specialty retailers anchor premium distribution networks for imported North American brands.
Japan
Declining birth rates and aging demographics elevate pet humanization trends among Tokyo and Osaka households. METI standards for pet food manufacturing facility sanitation create compliance barriers for foreign entrants. Kanto region veterinary clinics concentrate prescription diet recommendation authority.
United Kingdom
French Bulldog and Cavalier King Charles Spaniel ownership in Greater London and Manchester sustains wet food demand for brachycephalic breeds. FSA enforcement of post-Brexit import certification requirements complicates EU supply chain integration. Midlands-based co-packers face capacity constraints from qualified facility qualification queues.
Australia
Inner-Sydney and Melbourne apartment living patterns mirror US urban pet ownership dynamics. TGA parallel import regulations for veterinary prescription diets limit direct-to-consumer channel expansion. Queensland agricultural zones supply novel kangaroo protein for limited-ingredient formulations targeting food-sensitive toy breeds.
Dog Food for Small Breeds Dogs Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue subscription-native and direct-to-consumer channels. Three-tier concentration persists: multinational CPG conglomerates with captive veterinary networks, mid-scale natural-positioned specialists, and venture-backed fresh-food disruptors. Dominant competitive moves include veterinary clinic network acquisitions and cold-chain logistics infrastructure buildouts.
Within the veterinary-prescription tier, Hill's Pet Nutrition and Royal Canin exemplify clinically anchored positioning. Mars Petcare occupies a scale-driven position spanning mass retail and professional channels. Blue Buffalo represents the natural-specialist archetype competing on ingredient transparency claims.
| Leading Market Players |
|---|
| Nestlé Purina Pet Care |
| Mars Petcare |
| Hill's Pet Nutrition |
| General Mills |
| Royal Canin |
| Blue Buffalo |
| Wellness CORE |
| Orijen |
| Merrick |
| Others |
Pricing and Supply Chain Analysis
Captive integration into veterinary clinic networks anchors supply position and pricing power for prescription-grade small-breed formulations, while outsourced co-packer relationships constrain margin capture among mid-tier natural brands. This structural divergence separates subscription-native players with cold-chain control from retail-dependent competitors exposed to slotting fee escalation.
Pricing Analysis
Subscription auto-shipment bundling with microbiome testing and telehealth consultations separates premium pricing from unbundled retail SKUs. Three-tier pricing structure across prescription veterinary, natural premium, and mass-market economy levels reflects certification grade and channel control. Pricing pressure stems from refrigerated fresh meal services capturing ingredient-transparent spend. Cost-conscious multi-pet households in Texas and Florida exhibit highest price sensitivity, while urban millennial owners in Seattle and Austin show lowest.
Supply Chain Analysis
Dual-sourcing mandates for novel protein inputs require simultaneous qualification of black soldier fly larvae cultivators and conventional livestock suppliers. The United States, Canada, and Australia anchor supply for omega-3 enriched salmon oil and kangaroo protein limited-ingredient diets. Raw material dependencies rest on chicken meal, legume substitutes, and freeze-dried protein inputs. Single-source vulnerability concentrates in qualified small-batch co-packer capacity facing 12-18 month qualification queues. Distribution runs through veterinary clinic networks, direct-to-consumer cold-chain platforms, and mass retail warehouse clubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Co-packer capacity scarcity props pricing across mid-tier natural brands, constraining volume expansion for entrants lacking captive manufacturing or veterinary network control.
For Market Incumbents: To counter venture-backed fresh-food disruptors capturing subscription revenue, Mars Petcare and Hill's Pet Nutrition should deepen veterinary clinic network acquisitions and expand in-house freeze-drying capacity. Prescription diet recommendation authority through telehealth integration offers defensive channel control against direct-to-consumer erosion. For New Entrants and Emerging Players: Algorithmic diet personalization technology enables white-space entry into microbiome-customized subscription services for food-sensitive toy breeds. Veterinary telehealth partnerships in rural and exurban markets represent the most penetrable geography, with at-home diagnostic kit bundling as the go-to-market anchor. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by CPG conglomerates seeking veterinary-prescription tier access. Five-to-ten year viability favors brands with captive organic supply chains and FDA-compliant cold-chain infrastructure. The signal to watch is state-level organic feed incentive expansion accelerating supply chain conversion in California and Vermont.| Strategic Initiative | Industry Significance |
|---|---|
| Veterinary Clinic Network Acquisition | Mars Petcare's clinic ownership locks prescription diet recommendation authority away from retail competitors. |
| Cold-Chain Logistics Infrastructure Buildout | Freeze-dried raw food distribution expansion beyond coastal urban centers opens secondary metropolitan markets. |
| Novel Insect Protein Supply Agreement | Black soldier fly larvae cultivation partnerships reduce land-use intensity and commodity agriculture price exposure. |
| Microbiome Testing Platform Integration | Algorithmic diet recommendation engines modularize veterinary nutrition into data-driven consumer products. |
| State-Level Organic Certification Investment | California and Vermont tax credit capture rewards capital deployment in USDA-certified supply chain upgrading. |
Research Methodology
Regulatory filings from the FDA Center for Veterinary Medicine, AAFCO nutrient profile databases, and state-level feed control inspection records formed the secondary backbone for supply chain and compliance mapping. Primary interviews with veterinary nutritionists, pet food brand managers, co-packer operations directors, and subscription platform executives combined with secondary validation through bottom-up and top-down triangulation.
Historical trendline analysis of small-breed ownership rates, veterinary service utilization, and channel shift patterns anchored the projection framework. Segmentation dimensions modeled include product type, ingredient certification tier, life stage, and packaging format across the analysis window. CAGRs derived from trend extrapolation adjusted for regulatory inflection points and cold-chain logistics maturity.
Several conditions sit outside the modeled scope, including unannounced FDA enforcement actions, novel protein allergenicity findings, and macroeconomic shocks to discretionary pet spending. Forecasts reflect documented assumptions about millennial pet owner behavior persistence and veterinary telehealth adoption curves. Deviation in co-packer qualification timelines or state organic incentive repeal would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Cat Calming Treats Market
Pet Care Products
Herbal Pet Shampoo Market
Pet Care Products
Cat Backpacks Market
Pet Care Products
Canada Pet Training Services Market
Pet Care Products
Cat Food Toppers Market
Pet Care Products
Cat Cage Market
Pet Care Products
North America Dog Food Market
Pet Care Products
Pet Hair Care Market
Pet Care Products
Organic Dog Food Market
Pet Care Products
Europe Pet Treats Market
Pet Care Products
Pet Transporting Service Market
Pet Care Products
Pet Pens Market
Pet Care Products
Asia Pacific Dog Food Market
Pet Care Products
Thunder Jacket for Dogs Market
Pet Care Products
Dog Food and Snacks Market
Pet Care Products
Mobile Pet Care Market