
 Europe Pet Treats Market | 2026-2036
Europe Pet Treats Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Pet Treats Market Insights
European pet food manufacturers is repositioning capacity toward functional and clean-label treat production. Mars Incorporated leverages its pan-European manufacturing footprint to sustain consistent supply across multiple retail channels. Nestlé Purina PetCare anchors its competitive stance through specialized veterinary-formulated treat lines. VAFO Group a.s. differentiates via regional sourcing networks that navigate complex ingredient provenance standards.
Europe pet treats comprise formulated nutritional supplements and reward products manufactured through extrusion, baking, or freeze-drying processes, with protein content, moisture levels, and additive profiles governed by EU feed legislation. Their primary commercial purpose centers on bonding reinforcement, dental hygiene support, and dietary supplementation for companion animals. Chews and soft treats command the largest volume positions, while freeze-dried formats capture premium margin pools as pet owners prioritize minimal processing. E-commerce distribution channels are expanding fastest, though supermarkets and pet stores retain dominant shelf-space control across core European markets.
EFSA, EU Green Deal frameworks, and REACH chemical standards collectively shape ingredient approval pathways, packaging material restrictions, and sustainability disclosure obligations for treat producers operating in Europe. EMA veterinary guidelines further influence functional claim substantiation, particularly for products targeting digestive or joint health outcomes. Stakeholders must monitor evolving EU packaging waste regulations and carbon footprint labeling requirements as compliance costs reshape competitive economics across the value chain.
Market Dynamics
EFSA nutritional guidelines and EU Green Deal sourcing mandates are compressing formulation flexibility while forcing capital redeployment toward traceable supply chains and clean-label production infrastructure.
Growth Catalysts
- Pet Humanization Trajectory:European dog and cat owners now allocate treat budgets comparable to human snack categories, expanding purchase frequency and premium tier willingness across Germany, France, and the United Kingdom.
- REACH Chemical Standards:Stricter additive approval pathways under ECHA frameworks are accelerating R&D investment in natural preservative systems and plant-derived palatants.
- E-Commerce Infrastructure:Specialized pet platforms and veterinary telehealth integrations are bypassing traditional supermarket shelf-space constraints, opening direct-to-consumer channels for functional treat lines.
Market Restraints
- Protein Input Volatility:Wild-caught fish and free-range poultry sourcing costs fluctuate with North Atlantic quota systems and avian influenza surveillance protocols, compressing margin predictability.
- Freeze-Drying Capacity Concentration:Industrial-scale lyophilization equipment for premium segment production clusters in Northern Italy and Southern Germany, creating geographic supply bottlenecks.
- EFSA Claim Substantiation:Veterinary health outcome assertions require multi-year clinical validation, extending new product introduction timelines beyond conventional treat development cycles.
Strategic Opportunities
- Eastern European Penetration Gap:Poland and Romania exhibit treat spending per pet at roughly half Western European levels, presenting volume expansion potential as retail infrastructure modernizes.
- CSRD Sustainability Disclosure:Early compliance with corporate sustainability reporting requirements enables premium positioning through carbon footprint labeling and regenerative agriculture partnerships.
- Freeze-Dried and Air-Dried Convergence:Hybrid dehydration technologies combining nutrient retention with production throughput economics are opening mid-premium price bands previously unreachable for minimal-processing formats.
Industry Challenges
- Veterinary Nutritionist Scarcity:Functional treat development requires cross-disciplinary expertise spanning animal metabolism, regulatory science, and sensory palatability, with qualified talent concentrated in Netherlands and UK university programs.
- Legacy Extrusion Retooling:Conventional baked and extruded treat lines require substantial capital modification to achieve clean-label ingredient compatibility without texture degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Pet Treats Market |
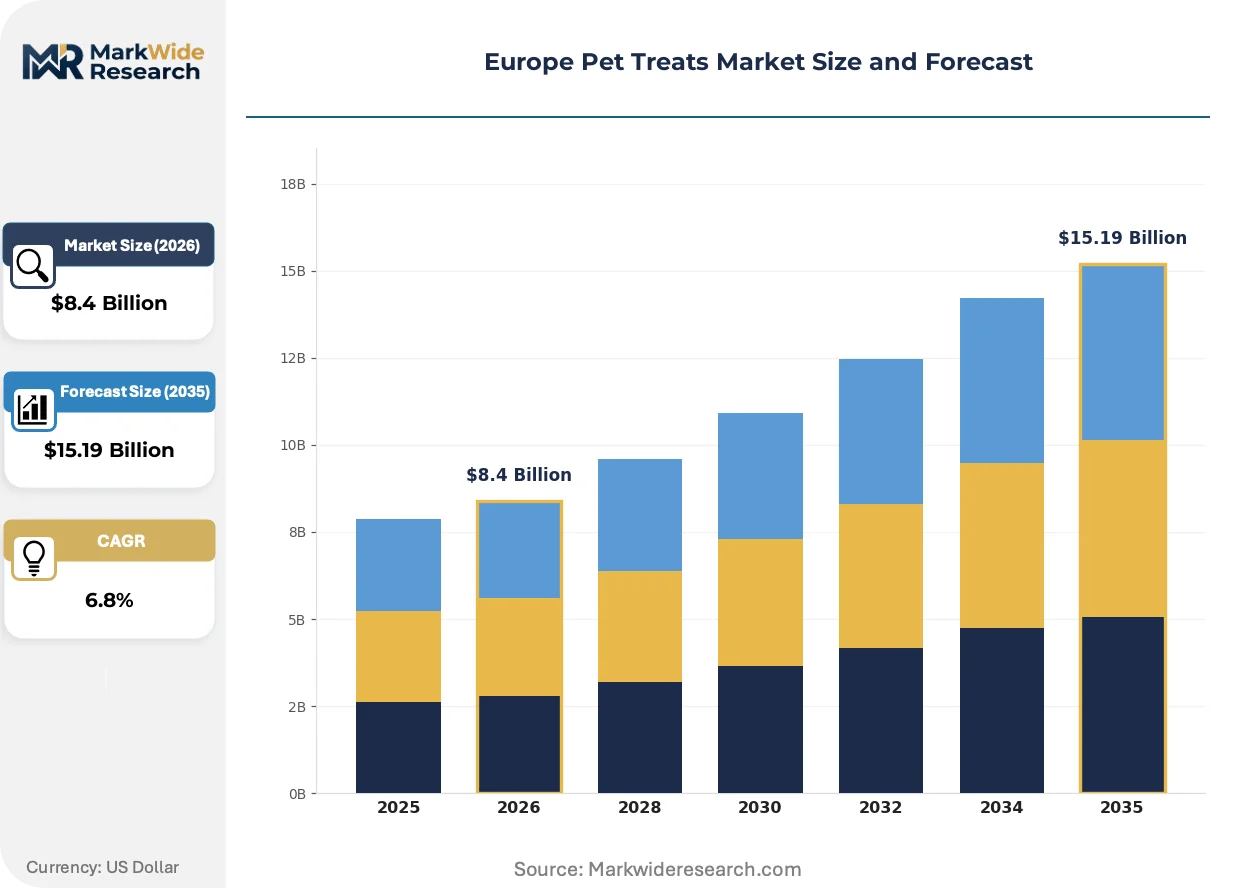
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chews, Biscuits, Soft Treats, Freeze-Dried Treats End User: Dog Owners, Cat Owners, Specialty Retailers, Online Retailers Packaging Type: Bags, Tubes, Boxes, Pouches Distribution Channel: Supermarkets, Pet Stores, E-Commerce, Convenience Stores |
| Companies Covered | Affinity Petcare S.A., ADM, Mars Incorporated, Heristo Aktiengesellschaft, General Mills Inc., Nestlé Purina PetCare, VAFO Group a.s., Virbac, Colgate-Palmolive Company (Hill's Pet Nutrition), Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Pet Treats Market Trends and Innovations
Processing technology convergence and regulatory transparency mandates are compressing traditional competitive advantages while elevating supply chain visibility and formulation specificity as primary differentiation vectors.
Freeze-drying technology is consolidating control over premium segment economics by enabling single-ingredient treat formats with extended shelf stability without synthetic preservatives. Specialist manufacturers in Germany and the Czech Republic are expanding capacity to serve veterinary-exclusive and direct-to-consumer channels. This consolidation is compressing margins for conventional baked treat producers unable to replicate nutrient density claims.
EU Green Deal carbon border adjustment mechanisms and packaging waste directives are forcing ingredient provenance documentation and recyclable material transitions. EFSA parallel-track review processes for novel protein sources are accelerating approval timelines for insect-based and cultivated protein formulations. Small-to-midscale producers in Scandinavia and Benelux are responding fastest, leveraging regional sustainability credentials for retail partnership access.
Subscription-based replenishment models are displacing episodic supermarket purchasing among urban millennial and Gen Z pet owners. Veterinary clinic networks and telehealth platforms are capturing recurring treat revenue through personalized dietary recommendation engines. France and the United Kingdom represent the most visible adoption geographies, with specialized pet insurers now bundling treat allowances into wellness policy tiers.
Europe Pet Treats Market Segmentation
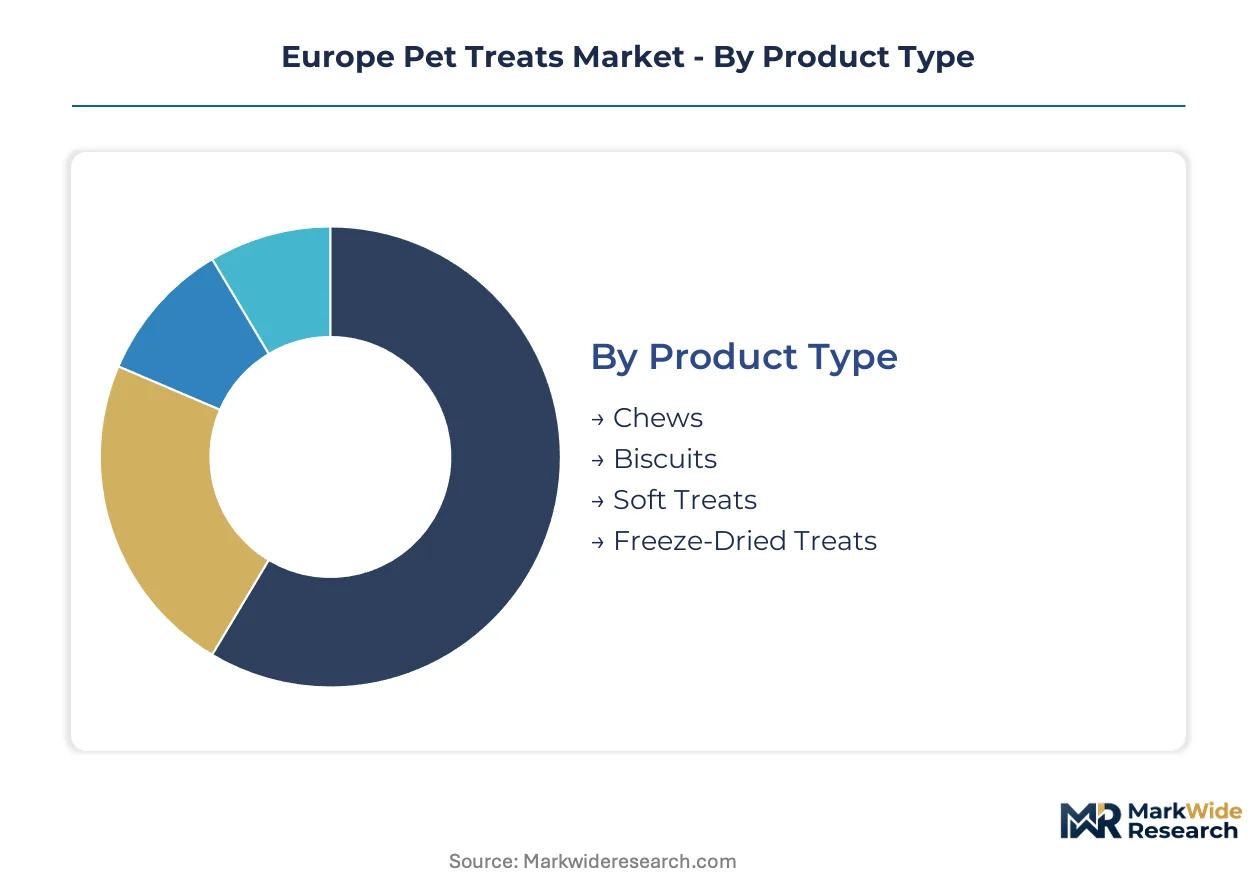
Segmentation in the Europe pet treats market reveals how EFSA compliance burdens and EU Green Deal traceability requirements concentrate differently across product formats, buyer types, and distribution pathways. Manufacturers must align R&D investment and certification timelines with the specific regulatory intensity of each segment.
Product Type:
EFSA nutritional guidelines impose distinct substantiation requirements across treat formats, with functional health claims triggering multi-year clinical validation for certain categories while others navigate simpler additive approval pathways.
- Chews:Extruded or pressed formulations combining collagen, starch, and vegetable glycerin deliver extended mechanical action for dental hygiene support. Demand clusters in Germany and the United Kingdom where veterinary dental programs drive bulk purchasing through clinic networks. EFSA considers these borderline between feed and veterinary products, creating regulatory friction for manufacturers pursuing joint health positioning.
- Freeze-Dried Treats:Single-ingredient or limited-formulation products processed through industrial lyophilization retain nutrient density without synthetic preservatives. Premium positioning in France and Benelux markets accelerates as pet owners prioritize minimal processing transparency. EFSA novel protein approvals for insect-based formulations are opening formulation flexibility unavailable to conventional baked alternatives.
- Biscuits:Baked formulations with defined moisture content and shelf-stable packaging dominate volume production across Central European manufacturing clusters.
- Soft Treats:High-moisture extruded products with enhanced palatability systems serve training and bonding applications with shorter formulation development cycles.
Chews sit at the top of the volume ranking, with freeze-dried treats climbing the fastest.
End User:
Procurement authority and quality sensitivity diverge sharply between individual consumers and institutional buyers, reshaping margin structures and certification investment priorities.
- Dog Owners:Individual purchasers with elevated treat spending per pet in Germany, France, and the United Kingdom drive premium tier expansion. Humanization trends translate into ingredient provenance demands and subscription-based replenishment preferences that bypass traditional retail markup structures.
- Online Retailers:Platform operators including specialized pet marketplaces and generalist e-commerce giants capture fastest-expanding channel share through direct-to-consumer logistics and data-driven personalization engines. These buyers demand batch-level traceability documentation to satisfy EU Green Deal disclosure obligations and consumer transparency expectations.
- Cat Owners:Smaller absolute population with higher per-treat price tolerance but lower overall consumption frequency compared to dog-owning households.
- Specialty Retailers:Independent pet stores and boutique chains curate premium assortments with emphasis on regional sourcing credentials and veterinary endorsement.
Dog owners command the largest absolute spend base, while online retailers are gaining share fastest through logistics infrastructure consolidation.
Packaging Type:
EU packaging waste directives and carbon footprint labeling requirements are forcing material transitions that segment cost structures and recyclability performance.
- Pouches:Flexible multilayer constructions with high barrier properties dominate soft treat and freeze-dried formats. Mono-material innovations responding to Extended Producer Responsibility schemes in Germany and France are reshaping supplier relationships and equipment investment timelines.
- Bags:Conventional paper-plastic laminates serve high-volume biscuit and chew segments with established recycling infrastructure.
- Tubes:Rigid plastic or aluminum constructions for premium positioning and portion control in dental and functional treat categories.
- Boxes:Corrugated and folding carton formats for gift assortments and veterinary-exclusive product lines with higher shelf presence requirements.
Bags retain volume leadership across mass-market distribution, with pouches expanding most quickly through premium channel penetration.
Distribution Channel:
Channel selection determines exposure to EFSA claim scrutiny, with veterinary-adjacent pathways demanding stricter functional substantiation than general retail.
- E-Commerce:Direct-to-consumer platforms and veterinary telehealth integrations bypass supermarket shelf-space constraints while capturing recurring revenue through subscription mechanics. France and the United Kingdom show steepest adoption curves as specialized pet insurers bundle treat allowances into wellness policies.
- Pet Stores:Dedicated retail networks in Germany and the Netherlands maintain curated assortments with emphasis on regional sourcing and clean-label credentials. Staff training investments create differentiation against mass-market alternatives.
- Supermarkets:Concentrated purchasing power across Carrefour, Tesco, and REWE systems drives volume but compresses margin through private-label competition and promotional intensity.
- Convenience Stores:Impulse-oriented formats with limited SKU depth targeting urban pet owners in transit and travel contexts.
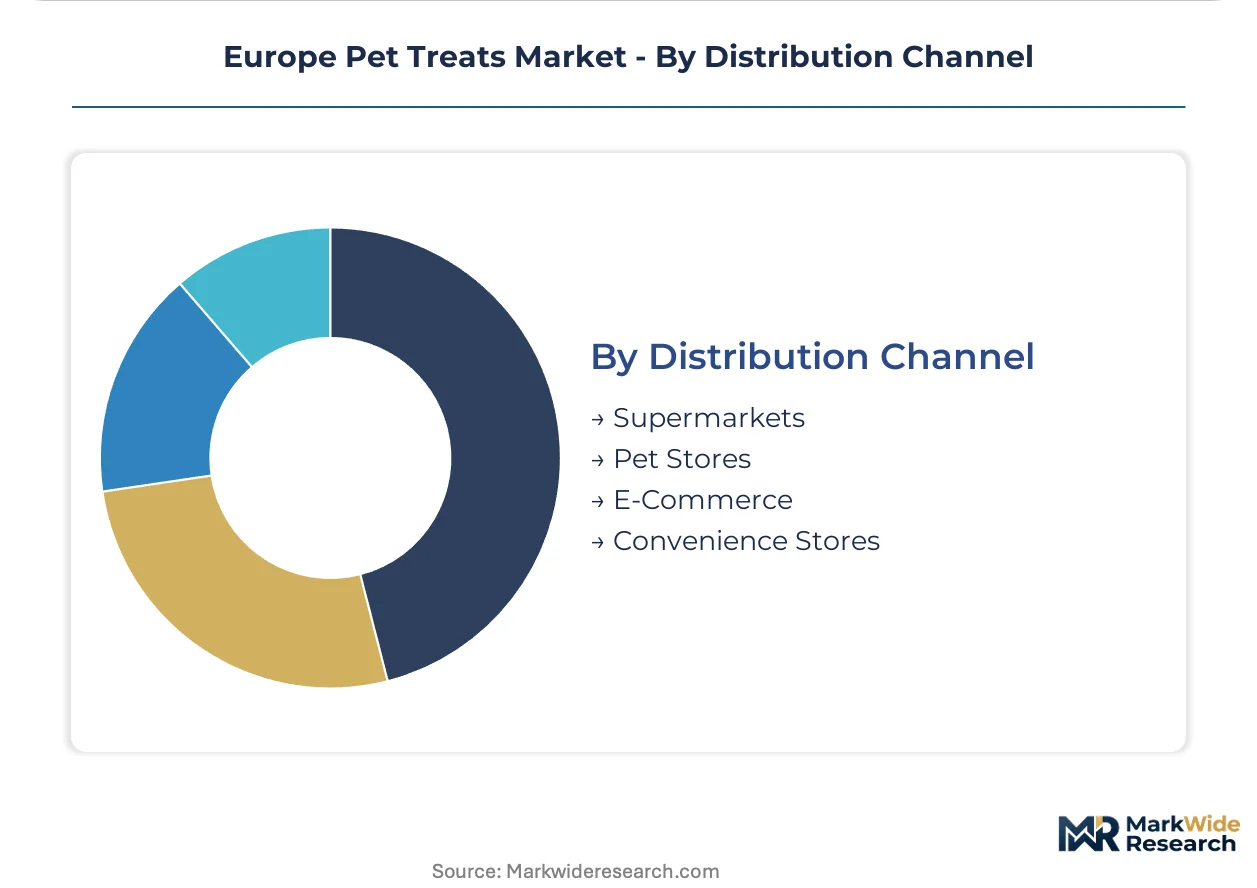
Supermarkets maintain the largest transaction volume, with e-commerce climbing the fastest through logistics infrastructure and subscription model maturation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as manufacturers migrate capacity toward jurisdictions offering streamlined EFSA compliance pathways and lower carbon-border adjustment exposure.
Germany
Veterinary clinic networks and pet specialty retailers drive premium treat consumption across metropolitan corridors. EFSA nutritional substantiation requirements and REACH chemical standards enforce rigorous additive documentation. Manufacturing clusters in Bavaria and North Rhine-Westphalia concentrate freeze-drying capacity serving direct-to-consumer subscription channels.
France
Humanization trends elevate treat spending per pet to levels matching human snack categories in Paris and Lyon metro areas. EU Green Deal carbon footprint labeling mandates accelerate regenerative agriculture partnerships. Production facilities in the Grand Est region specialize in single-ingredient formats for veterinary-exclusive distribution.
United Kingdom
Telehealth-integrated treat subscriptions capture recurring revenue from urban millennial pet owners in London and Manchester. Post-Brexit regulatory divergence from EFSA frameworks creates parallel approval pathways for novel protein formulations. Manufacturing investment concentrates in Midlands food processing corridors.
Italy
Family-owned pet food traditions sustain regional brand loyalty in northern industrial zones. CSRD sustainability disclosure requirements reshape supplier audit protocols for packaging material traceability. Lyophilization equipment clusters in Emilia-Romagna serve export demand across Mediterranean markets.
Poland
Treat spending per pet remains roughly half Western European levels despite accelerating retail modernization in Warsaw and Krakow. EU structural funds support clean-label production infrastructure upgrades. Emerging manufacturing zones in Silesia attract capacity migration from higher-compliance-cost jurisdictions.
Europe Pet Treats Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue functional and freeze-dried specialization. The vendor base stratifies across three tiers: multinational consumer goods conglomerates with pan-European distribution, mid-scale regional specialists leveraging local sourcing credentials, and niche innovators targeting veterinary-exclusive channels. Strategic archetypes include sustainability-first positioning through CSRD early compliance, subscription-based direct-to-consumer bypass of retail markup structures, and hybrid dehydration technology deployment for mid-premium price band capture. Dominant competitive moves encompass M&A activity consolidating freeze-drying capacity and strategic partnerships with veterinary telehealth platforms securing recurring revenue streams.
Among diversified consumer goods conglomerates, Mars Incorporated and Nestlé Purina PetCare exemplify scale-driven archetypes with extensive manufacturing footprints. VAFO Group a.s. occupies a specialist position within the regional sourcing tier. These three entities represent distinct competitive positioning strategies without implying specific market share figures or operational metrics.
| Leading Market Players |
|---|
| Affinity Petcare S.A. |
| ADM |
| Mars Incorporated |
| Heristo Aktiengesellschaft |
| General Mills Inc. |
| Nestlé Purina PetCare |
| VAFO Group a.s. |
| Virbac |
| Colgate-Palmolive Company (Hill's Pet Nutrition) |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal carbon border adjustment mechanisms gate both qualified supply and premium-tier pricing access, forcing manufacturers to document ingredient provenance or forfeit high-margin retail placement. REACH chemical standards and EFSA nutritional guidelines further stratify cost structures, with compliant suppliers commanding pricing power over conventional alternatives.
Pricing Analysis
Retailer markup compression in supermarket channels intensifies pricing pressure as Carrefour, Tesco, and REWE systems leverage private-label alternatives. Three-tier pricing structure across premium freeze-dried, standard baked, and economy extruded levels separates veterinary-exclusive formats from mass-market positioning. Price differentiation hinges on EFSA claim substantiation status and EU Green Deal carbon footprint certification. Dog owners in Germany and France exhibit lowest price sensitivity, while Polish and Romanian retail modernization drives volume-tier competition.
Supply Chain Analysis
Veterinary nutritionist scarcity in Netherlands and UK university programs constrains functional treat development capacity across Northern European manufacturing zones. Protein inputs draw from North Atlantic wild-caught fisheries and free-range poultry operations in France and Germany, with Italian lyophilization equipment serving Mediterranean export demand. Single-source vulnerability concentrates in Southern Germany and Northern Italy for industrial-scale freeze-drying capacity. Distribution runs through veterinary clinic networks and direct-to-consumer subscription platforms alongside conventional pet specialty retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe pet treats function as a geographic-arbitrage play, with EFSA compliance costs in Western Europe running substantially above Polish and Romanian manufacturing zones where EU structural funds subsidize clean-label infrastructure upgrades.
For Market Incumbents: Deepen backward integration into regional protein sourcing networks to mitigate North Atlantic quota volatility and avian influenza surveillance disruptions. Acquire freeze-drying capacity in Czech Republic or Germany to secure premium segment access. Expand veterinary telehealth platform partnerships to lock recurring subscription revenue against supermarket private-label erosion. For New Entrants and Emerging Players: Direct-to-consumer veterinary telehealth integrations offer the most penetrable route for bypassing established retail shelf-space constraints. Target Polish and Romanian treat spending gaps through e-commerce infrastructure partnerships with modernizing retail platforms. Pursue CSRD early compliance for carbon footprint labeling differentiation in French and German premium channels. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale regional specialists with underutilized clean-label production capacity in Eastern Europe. Long-term viability centers on regulatory arbitrage sustainability and freeze-drying technology convergence. Watch EFSA novel protein approval timelines for insect-based and cultivated protein formulations as inflection indicators for formulation flexibility premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Freeze-Drying Capacity Expansion | Industrial lyophilization investment in Germany and Czech Republic secures premium segment economics. |
| Veterinary Telehealth Integration | Subscription partnerships with French and UK clinic networks capture recurring revenue streams. |
| CSRD Early Compliance Program | Carbon footprint labeling and regenerative agriculture partnerships enable retail premium positioning. |
| Eastern European Manufacturing Migration | Capacity relocation to Poland and Romania exploits EU structural fund subsidies and lower compliance costs. |
| Novel Protein Formulation Pipeline | EFSA parallel-track approvals for insect-based proteins open differentiation unavailable to conventional producers. |
Research Methodology
Multiple input streams — executive interviews with European pet food manufacturers, regulatory affairs specialists at EFSA and national veterinary authorities, and category buyers at major retail chains — were reconciled against trade data from Eurostat customs records, FEDIAF industry reports, and EU Green Deal implementation documentation. Primary fieldwork captured formulation development timelines, capacity utilization rates, and channel margin structures. Bottom-up production capacity modeling and top-down retail audit triangulation validated volume estimates across Germany, France, United Kingdom, Italy, and Poland.
Data-stream reconciliation anchored the analytical framework across the projection horizon, with segmentation modeling across product format, end user type, packaging material, and distribution channel. CAGRs derived from production capacity expansion schedules, retail scanner data trends, and veterinary channel subscription growth trajectories. Industry-specific inputs included EFSA novel protein approval timelines and EU packaging waste directive implementation phases.
The model assumes a particular technology adoption path; alternative pathways for hybrid air-dried and freeze-dried convergence would alter the outlook for mid-premium price band capture. Forecasts reflect assumptions regarding EFSA claim substantiation efficiency and carbon border adjustment enforcement intensity. Material deviation in veterinary nutritionist training pipeline output or REACH chemical standard amendment schedules warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Europe Organic and Natural Pet Food Market
Pet Care Products
Europe Pet Clothing Market
Pet Care Products
China Pet Training Services Market
Pet Care Products
Pet Gadgets Market
Pet Care Products
Natural Pet Food Market
Pet Care Products
Pet Grooming Market
Pet Care Products
Dog Shampoo Market
Pet Care Products
Weight Management Dog Food Market
Pet Care Products
GCC Cat Food Market
Pet Care Products
Smart Dog Collar Market
Pet Care Products
Asia Pacific Dog Food Market
Pet Care Products
GPS Dog Collar Market
Pet Care Products
Cat Litter Boxes Market
Pet Care Products
Pet Food Pulverizer Market
Pet Care Products
Poland Pet Food Market
Pet Care Products
Philippines Pet Food Market