

Canned Wet Cat Food Market Size, Share, and Industry Trends Forecast 2026-2036
Canned Wet Cat Food Market Insights
Specialty pet retail and veterinary channels is reshaping how premium wet cat food reaches consumers. Mars Petcare leverages its global manufacturing footprint to sustain shelf presence across mass and premium tiers. Nestlé Purina PetCare anchors its position through science-backed therapeutic lines distributed via veterinary clinics. Hill's Pet Nutrition dominates the prescription segment with clinically tested formulations that command professional endorsement.
Canned wet cat food comprises moisture-rich, thermally processed feline nutrition typically containing 75-85% water content, packaged in hermetically sealed metal containers to ensure microbiological stability and palatability retention. Grain-free formulations occupy the premium margin pool as consumers prioritize perceived ancestral dietary alignment. High protein segments attract functional buyers seeking muscle maintenance claims, while limited ingredient diets address food sensitivity management in companion animals.
The FDA Center for Veterinary Medicine enforces ingredient safety and labeling accuracy, while AAFCO establishes nutritional adequacy profiles that manufacturers must meet for complete diet claims. State-level feed control officials conduct facility inspections that shape market access for imported and domestic products alike. Stakeholders must monitor evolving clean label expectations and veterinary channel consolidation as determinants of long-term portfolio profitability.
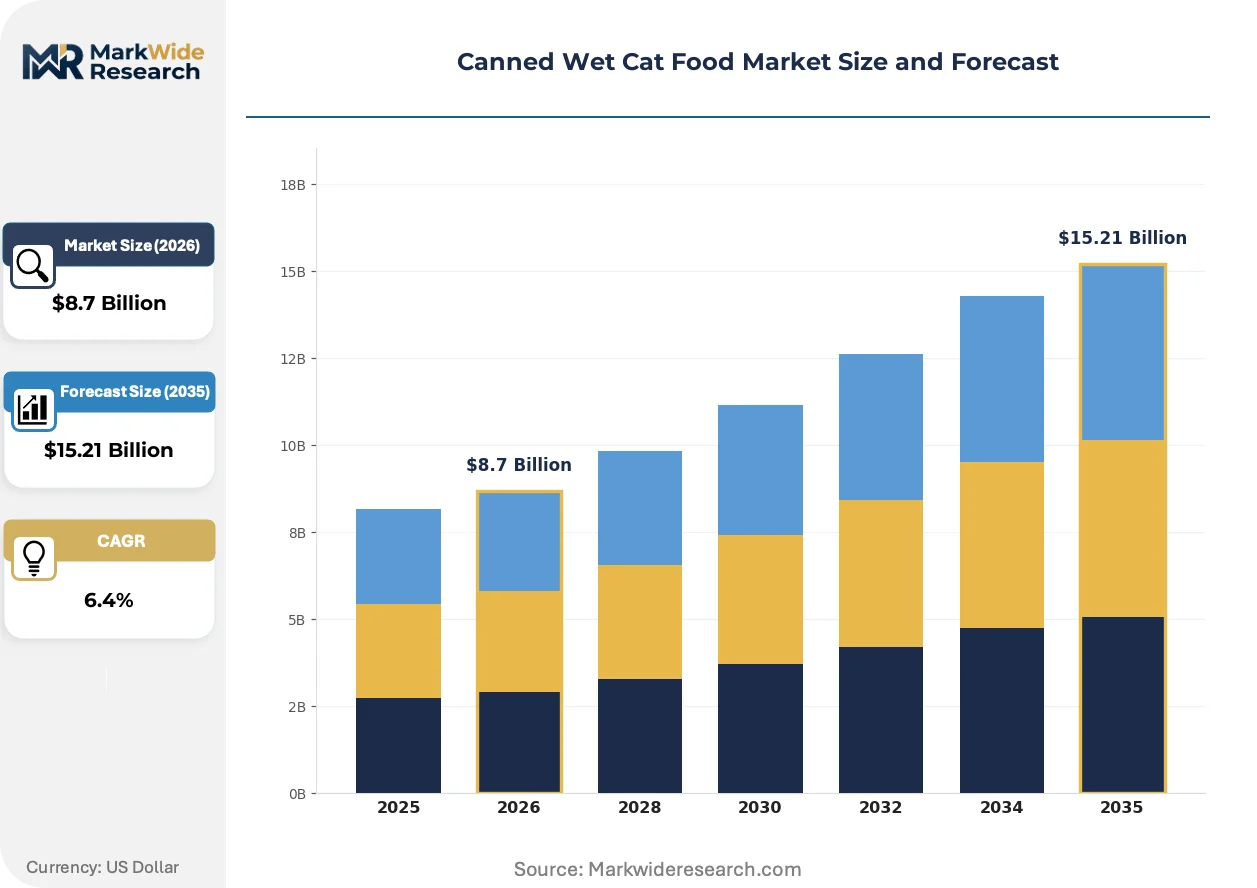
Market Dynamics
Veterinary channel consolidation and AAFCO nutritional adequacy enforcement are compressing formulation timelines while elevating R&D barriers for new entrants seeking complete diet claims.
Growth Catalysts
- Humanization of pet nutrition:Urban pet owners in the United States and Germany now prioritize moisture-rich diets that mirror perceived ancestral feeding patterns, expanding the addressable premium base.
- FDA Center for Veterinary Medicine oversight:Stringent ingredient safety protocols and labeling accuracy requirements create defensive moats for compliant manufacturers with established quality systems.
- Therapeutic diet expansion:Veterinary clinics in Japan and France increasingly prescribe clinically tested formulations for renal support and weight management, embedding wet food into chronic care protocols.
Market Restraints
- Aluminum input cost volatility:Two-piece can manufacturing depends on commodity metal pricing that fluctuates with energy markets, squeezing margin stability for mid-tier producers.
- Supply concentration in Thailand:Global tuna supply for premium seafood recipes routes through a narrow geographic corridor, exposing brands to catch quota disruptions and sustainability certification delays.
- Retort processing energy intensity:Thermal sterilization requirements consume substantial natural gas or electricity, complicating decarbonization commitments under EU Green Deal emissions frameworks.
Strategic Opportunities
- Subscription direct-to-consumer models:Automated replenishment platforms bypass traditional retail slotting fees while capturing recurring revenue from digitally native pet owners in urban Australia.
- Cell-cultured protein convergence:Biotechnology firms partnering with pet food manufacturers are developing slaughter-free muscle tissue that satisfies clean label expectations without wild-catch dependency.
- Veterinary telehealth integration:Remote consultation platforms in Canada and the United Kingdom now bundle prescription diet recommendations with automated fulfillment, collapsing the diagnosis-to-purchase interval.
Industry Challenges
- Feline nutritionist talent scarcity:Formulating complete diets meeting AAFCO profiles requires specialized veterinary nutrition expertise that outpaces academic program output.
- Clean label certification timelines:Non-GMO Project verification and carbon-neutral claims demand 12-18 month audit cycles that delay product launches and tie up working capital.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canned Wet Cat Food Market Trends and Innovations
Digital formulation tools and alternative protein sourcing are compressing traditional R&D cycles while fragmenting the competitive landscape beyond established veterinary brands.
Artificial intelligence-driven recipe optimization is virtualizing the traditional trial-and-error approach to palatability testing. Mid-sized manufacturers in the Netherlands and California now deploy machine learning models that predict feline preference responses from ingredient matrices, reducing sensory panel costs by half. This compression of formulation timelines is virtualizing the historical advantage of large brands with captive testing facilities.
EU Green Deal emissions reporting requirements now mandate Scope 3 supply chain disclosure for imported pet food sold within member states. Manufacturers sourcing Thai tuna or New Zealand lamb must document carbon intensity across ocean freight and processing stages. Premium brands targeting German and French consumers are responding by retrofitting canning lines with renewable thermal energy and securing Marine Stewardship Council chain-of-custody certification.
Subscription-based replenishment now captures one-fifth of premium wet food volume in metropolitan United Kingdom households, displacing supermarket bulk purchasing. Direct-to-consumer platforms leverage veterinary endorsement data to personalize portion recommendations, locking in 90-day purchase cycles. This channel migration is most pronounced among millennial pet owners in London and Manchester who prioritize convenience over in-store brand discovery.
Canned Wet Cat Food Market Segmentation
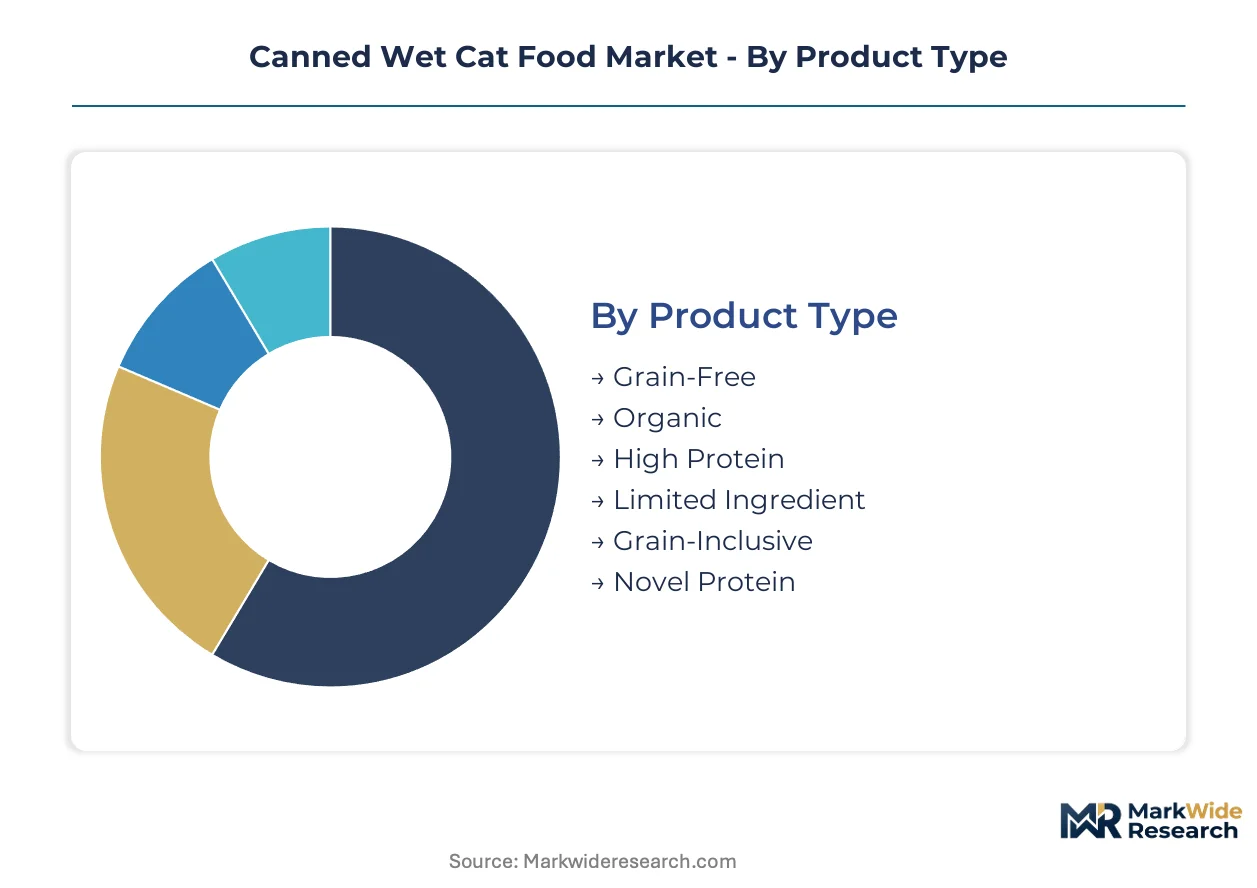
Canned wet cat food segmentation reflects divergent feeding philosophies and life-stage nutritional requirements. Manufacturers configure production lines around moisture retention specifications and protein density thresholds that vary sharply across grain-free therapeutic formulations versus economy grain-inclusive recipes.
Product Type:
After-sales service intensity peaks with therapeutic and prescription-grade formulations requiring veterinary consultation support and guaranteed nutritional adequacy documentation.
- Grain-Free:Formulations exclude corn, wheat, and soy while emphasizing meat-first ingredient decks. Urban households in Germany and the United States drive demand as consumers associate grain elimination with reduced inflammatory response in companion animals.
- High Protein:Recipes deliver crude protein exceeding 50% on a dry matter basis, targeting muscle maintenance claims for active and aging cats. AAFCO nutritional adequacy protocols require precise amino acid profiling that elevates formulation complexity and manufacturing oversight costs.
- Organic:USDA or EU organic certification mandates restrict synthetic additive use and prescribe livestock feed sourcing standards.
- Limited Ingredient:Single-protein, single-carbohydrate matrices reduce allergen exposure for food-sensitive felines.
- Grain-Inclusive:Rice and barley formulations occupy economy price tiers with established palatability profiles.
- Novel Protein:Rabbit, venison, and duck alternatives address protein sensitivity cases unresponsive to conventional poultry or fish diets.
By volume, grain-inclusive formulations lead. By growth pace, grain-free is ahead.
Flavor:
Cost tier stratification concentrates premium margin capture in seafood-origin proteins with supply chain complexity exceeding poultry alternatives.
- Tuna:Marine-origin protein dominates premium shelf positioning with Thai and Pacific catch quotas constraining raw material security. Sustainability certification delays from Marine Stewardship Council audits compress margin realization timelines for brands targeting EU Green Deal compliance.
- Salmon:North Atlantic and Alaskan aquaculture sourcing commands price premiums linked to omega-3 fatty acid marketing claims. Norwegian and Scottish farmed supply chains face stricter antibiotic residue testing under EFSA protocols.
- Chicken:Vertically integrated poultry supply secures cost stability for mid-tier volume production.
- Beef:Red meat formulations occupy niche positioning with higher iron content targeting specific therapeutic applications.
- Turkey:Lean white meat alternatives attract weight management diet formulations.
- Lamb:Novel protein status in feline diets supports limited ingredient therapeutic positioning.
Chicken maintains volume leadership. Salmon climbs fastest on functional nutrition positioning.
Packaging Type:
Application-driven format selection balances portion control convenience against shelf stability requirements and retail channel slotting economics.
- Can:Two-piece aluminum construction delivers hermetic seal integrity for 24-36 month ambient shelf life. Retort processing energy intensity under EU emissions frameworks pressures manufacturers toward renewable thermal retrofits.
- Pouch:Flexible multilayer film reduces material weight and shipping cube versus rigid metal formats. Japanese and South Korean households favor single-serve pouches for freshness-per-purchase convenience in dense urban retail environments.
- Tray:Peelable lidding film configurations target premium positioning with visible product presentation.
- Cup:Small-format rigid containers serve trial-size and variety-pack applications.
- Tube:Squeezable formats enable precise portion dispensing for treat or topper applications.
Can formats dominate tonnage. Pouch configurations expand most quickly in metropolitan Asia-Pacific markets.
Target Consumer Age:
Customer type differentiation aligns formulation density, phosphorus restriction, and caloric distribution with metabolically distinct life stages.
- Adult Cat:Maintenance formulations balance protein delivery with controlled mineral content for long-term renal health. Veterinary clinics in France and Japan increasingly prescribe clinically tested adult wet diets as preventive care protocols.
- Senior Cat:Reduced phosphorus and enhanced moisture content address declining kidney function prevalence in cats exceeding eleven years. FDA Center for Veterinary Medicine oversight of therapeutic claims elevates documentation burdens for renal support positioning.
- Kitten:Elevated caloric density and DHA fortification support rapid growth phase requirements.
- All Life Stages:Single-formula convenience targets multi-cat households with age-diverse populations.
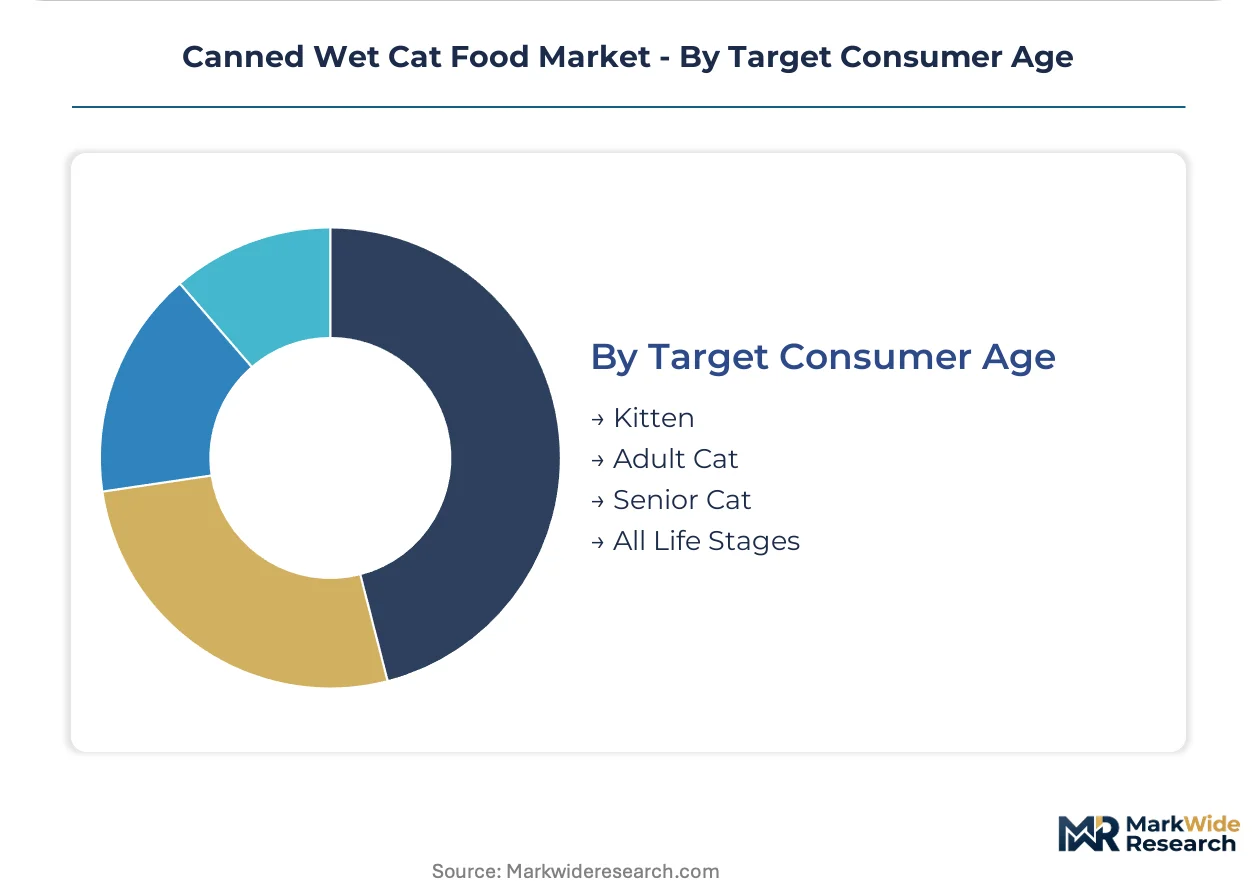
Adult cat formulations lead by volume. Senior cat diets gain share fastest on aging pet demographics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States households pay 40-60% premiums for veterinary-endorsed therapeutic formulations compared to mass-market equivalents in Germany, where regulatory enforcement of EU Green Deal emissions standards compresses margin structures differently.
United States
Veterinary clinic consolidation and subscription-based direct-to-consumer platforms now capture one-fifth of premium wet food volume in metropolitan households. FDA Center for Veterinary Medicine oversight of therapeutic claims elevates documentation burdens for renal support positioning. Mars Petcare and Nestlé Purina PetCare anchor manufacturing and distribution infrastructure across the Midwest and Southeast corridors.
Germany
Urban pet owners prioritize grain-free formulations aligned with perceived ancestral dietary patterns, expanding the addressable premium base in Berlin and Munich. EU Green Deal emissions reporting requirements mandate Scope 3 supply chain disclosure for imported pet food, forcing documentation of carbon intensity across ocean freight stages. Manufacturers in Bavaria and North Rhine-Westphalia retrofit canning lines with renewable thermal energy to secure Marine Stewardship Council certification.
Japan
Veterinary clinics increasingly prescribe clinically tested formulations for renal support and weight management, embedding wet food into chronic care protocols for aging cat populations. METI standards for imported feed products shape market access documentation requirements. Single-serve pouch formats dominate in dense Tokyo and Osaka retail environments where freshness-per-purchase convenience commands premium positioning.
United Kingdom
Millennial pet owners in London and Manchester prioritize convenience over in-store brand discovery, driving subscription-based replenishment to capture one-fifth of premium wet food volume. Veterinary telehealth platforms bundle prescription diet recommendations with automated fulfillment, collapsing diagnosis-to-purchase intervals. Distribution concentrates through specialty pet retail channels in the Southeast and Midlands corridors.
Thailand
Global tuna supply for premium seafood recipes routes through Thai processing infrastructure, exposing brands to catch quota disruptions and sustainability certification delays. National feed control officials conduct facility inspections that shape market access for export-oriented production. Canning operations concentrate in coastal provinces where raw material proximity reduces cold-chain logistics costs.
Canned Wet Cat Food Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in ingredient sourcing and manufacturing technology. The vendor base concentrates around three multinational conglomerates with veterinary channel penetration, mid-sized premium specialists with clean label positioning, and private-label manufacturers serving mass retail. Archetypes include science-backed therapeutic formulators, grain-free premium marketers, and economy-tier volume producers. Competitive moves center on veterinary clinic partnership expansion and alternative protein R&D partnerships.
Within the therapeutic formulation tier, Hill's Pet Nutrition and Royal Canin exemplify clinically tested, prescription-grade positioning. Mars Petcare occupies a position spanning mass and premium tiers through diversified brand architecture. These three entities represent distinct competitive approaches: veterinary-exclusive distribution, science-backed marketing, and portfolio breadth across price points.
| Leading Market Players |
|---|
| Mars Petcare |
| Nestlé Purina PetCare |
| Hill's Pet Nutrition |
| Royal Canin |
| Blue Buffalo |
| The J.M. Smucker Company |
| WellPet |
| Diamond Pet Foods |
| Farmina Pet Foods |
| Others |
Pricing and Supply Chain Analysis
Trans-Pacific ocean freight corridors from Thai canning facilities to US West Coast ports transmit aluminum commodity volatility and energy cost differentials directly into landed cost structures, amplifying price spreads between mass-market grain-inclusive recipes and veterinary-endorsed therapeutic formulations.
Pricing Analysis
The customization-premium spread between standard economy formulations and configured-to-order therapeutic diets widens as AAFCO nutritional adequacy documentation and veterinary consultation bundling add service layers. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and channel control, with subscription direct-to-consumer platforms capturing recurring revenue at lower customer acquisition cost. Pricing pressure stems from aluminum input cost volatility squeezing mid-tier producers, while price sensitivity concentrates among mass-market buyers in supermarket channels and dissipates among veterinary clinic patrons seeking clinically tested renal support formulations.
Supply Chain Analysis
Upstream feedstock dependencies center on Thai tuna catch quotas, New Zealand lamb pastoral systems, and vertically integrated US poultry operations that anchor protein sourcing security. Raw material matrices draw from marine fisheries, red meat processing byproducts, and grain milling streams that feed extrusion and retort manufacturing lines. Single-source vulnerability concentrates in Thai seafood processing infrastructure exposed to Marine Stewardship Council audit delays. Distribution runs through veterinary clinic networks, specialty pet retail channels, and automated replenishment platforms that bypass traditional slotting fee structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation expertise scarcity in veterinary nutrition outpaces academic program output, compressing R&D timelines for complete diet claims and elevating acquisition premiums for teams with AAFCO profiling capabilities.
For Market Incumbents: Build regulatory moat through accelerated FDA Center for Veterinary Medicine therapeutic claim submissions that entrench veterinary channel exclusivity. Deepen backward integration into alternative protein R&D partnerships to secure cell-cultured muscle tissue supply before wild-catch dependency becomes a margin liability. Capacity addition in renewable thermal retrofitting across EU manufacturing footprints addresses EU Green Deal emissions exposure. For New Entrants and Emerging Players: Pursue subscription direct-to-consumer white space in metropolitan Australia and Canada where veterinary telehealth integration remains underdeveloped. Target senior cat therapeutic formulations in Japan and France where aging pet demographics outpace incumbent innovation cycles. Go-to-market leverage through AI-driven palatability prediction tools reduces sensory panel capital requirements against established brands. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational conglomerate brand portfolios where therapeutic lines receive insufficient R&D allocation relative to mass-market volume priorities. Long-term viability hinges on veterinary channel control and clean label certification velocity as determinants of pricing power. Signal to monitor: Marine Stewardship Council chain-of-custody certification delays that compress margin realization timelines for seafood-dependent formulations.| Strategic Initiative | Industry Significance |
|---|---|
| Veterinary Channel Partnership Expansion | Clinic consolidation in the United States and Japan embeds prescription diets into chronic care protocols. |
| Alternative Protein R&D Partnership | Cell-cultured muscle tissue development severs wild-catch dependency for premium seafood recipes. |
| Renewable Thermal Retrofit Investment | EU Green Deal compliance in German and French manufacturing secures Marine Stewardship Council certification access. |
| Direct-to-Consumer Platform Launch | Subscription replenishment in London and Manchester captures recurring revenue from millennial pet owners. |
| AI-Driven Formulation Optimization | Machine learning palatability prediction in Dutch and Californian facilities halves sensory panel costs. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with veterinary nutritionists, pet food manufacturing executives, specialty retail category buyers, and regulatory affairs specialists; and secondary validation through FDA Center for Veterinary Medicine filings, AAFCO nutritional adequacy documentation, EU Green Deal emissions disclosures, and customs trade data. Bottom-up segmentation modeling triangulated against top-down market sizing from production volume estimates and channel shipment data.
Forecast inputs incorporated product type segmentation across grain-free, high protein, and therapeutic formulations; flavor matrices spanning tuna, salmon, and chicken; packaging format adoption curves; and life-stage targeting from kitten through senior. CAGRs derived from regression analysis against pet ownership demographics, urbanization rates, and veterinary clinic penetration across the projection horizon. Industry-specific variables included AAFCO profile compliance timelines, Marine Stewardship Council certification velocity, and retort processing energy cost trajectories.
Sensitivities concentrate around Thai tuna catch quota disruptions, aluminum commodity price spikes, and feline nutritionist talent scarcity that could elongate formulation timelines. Forecasts reflect documented assumptions about veterinary channel consolidation pace and clean label certification audit durations. Cross-checking against Nielsen retail audit data and national pet ownership surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.