
 Indoor Soft Play Market | 2026-2036
Indoor Soft Play Market Size, Share, and Industry Trends Forecast 2026-2036
Indoor Soft Play Market Analysis
China is narrowing its cost advantage in foam molding and textile fabrication as Southeast Asian suppliers scale capacity for soft play components. Go Play Systems leverages domestic manufacturing to control lead times for custom installations across North American family entertainment centers. KidSteam sustains competitive positioning through specialized aquatic-themed soft play lines that differentiate from commodity offerings. Soft Play anchors European demand with EN 1176-certified product ranges that comply with stringent fall-height and impact-absorption standards.
Indoor soft play encompasses engineered foam structures, padded platforms, and textile-wrapped climbing elements designed for controlled-impact recreation in enclosed environments, typically constructed from polyurethane foam cores with vinyl or PVC-coated fabric skins rated for abrasion resistance and flame retardancy. These installations serve commercial operators seeking liability-managed recreation spaces that absorb kinetic energy from child users. Activity playsets and soft playground equipment dominate installed base value, though inflatable structures represent the fastest-expanding product category as operators prioritize portable, reconfigurable layouts that reduce permanent construction costs. Small play areas and medium play zones capture the majority of unit volume, while large play complexes concentrate margin pools through integrated design contracts that bundle installation, theming, and maintenance services.
ASTM International maintains F1918 and F2373 standards governing soft-contained play equipment in the United States, while the European Committee for Standardization enforces EN 1176 and EN 1177 for playground safety and impact-absorbing surfaces, respectively; both frameworks mandate periodic third-party testing that elevates compliance costs for smaller manufacturers. China's GB standards for toy safety and GB 6675 for mechanical properties create additional certification layers for exporters targeting domestic distribution. Stakeholders must monitor evolving flame-retardant chemical restrictions under REACH and state-level disclosure laws, as material reformulation timelines could disrupt established supply relationships and force accelerated R&D commitments.
Market Dynamics
Modular foam fabrication systems are compressing installation timelines for family entertainment centers while ASTM F1918 compliance testing extends vendor certification cycles, creating a structural tension between speed-to-market and safety verification depth.
Growth Catalysts
- Modular retrofit demand:Family entertainment centers in the United States are replacing fixed-structure installations with reconfigurable foam systems to extend facility lifecycles without full rebuilds.
- EN 1176 certification premium:European operators increasingly specify EN 1176-certified equipment to satisfy liability insurers and municipal leasing requirements for public venues.
- Polyurethane foam density standards:Tightening flame-retardancy specifications under REACH are accelerating material reformulation investments that differentiate compliant suppliers from commodity producers.
Market Restraints
- Petrochemical input volatility:Polyurethane foam cores depend on isocyanate and polyol feedstocks whose price swings compress margin predictability for mid-scale manufacturers.
- Southeast Asian supply concentration:Textile fabrication for vinyl and PVC-coated skins concentrates in Vietnam and Indonesia, exposing procurement to regional logistics disruptions.
- Permanent installation substitution:Inflatable structures with rapid deployment cycles capture budget-conscious operators seeking lower capital commitment than fixed foam builds.
Strategic Opportunities
- Secondary city penetration:Tier-two metropolitan areas in the United States lack purpose-built family entertainment centers, creating whitespace for modular soft play deployments in repurposed retail footprints.
- Aquatic-themed product lines:Water park operators are expanding into year-round indoor recreation, opening demand for moisture-resistant foam composites and marine-grade textile skins.
- Integrated maintenance contracts:Long-term service agreements bundling inspection, cleaning, and component replacement address operator liability concerns while locking in recurring revenue streams.
Industry Challenges
- Third-party testing bottlenecks:ASTM F1918 and EN 1176 certification queues at accredited laboratories extend product launch timelines by four to six months.
- Specialized installation labor scarcity:Foam cutting, textile wrapping, and structural anchoring require trained crews whose limited availability constrains nationwide rollout velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indoor Soft Play Market |
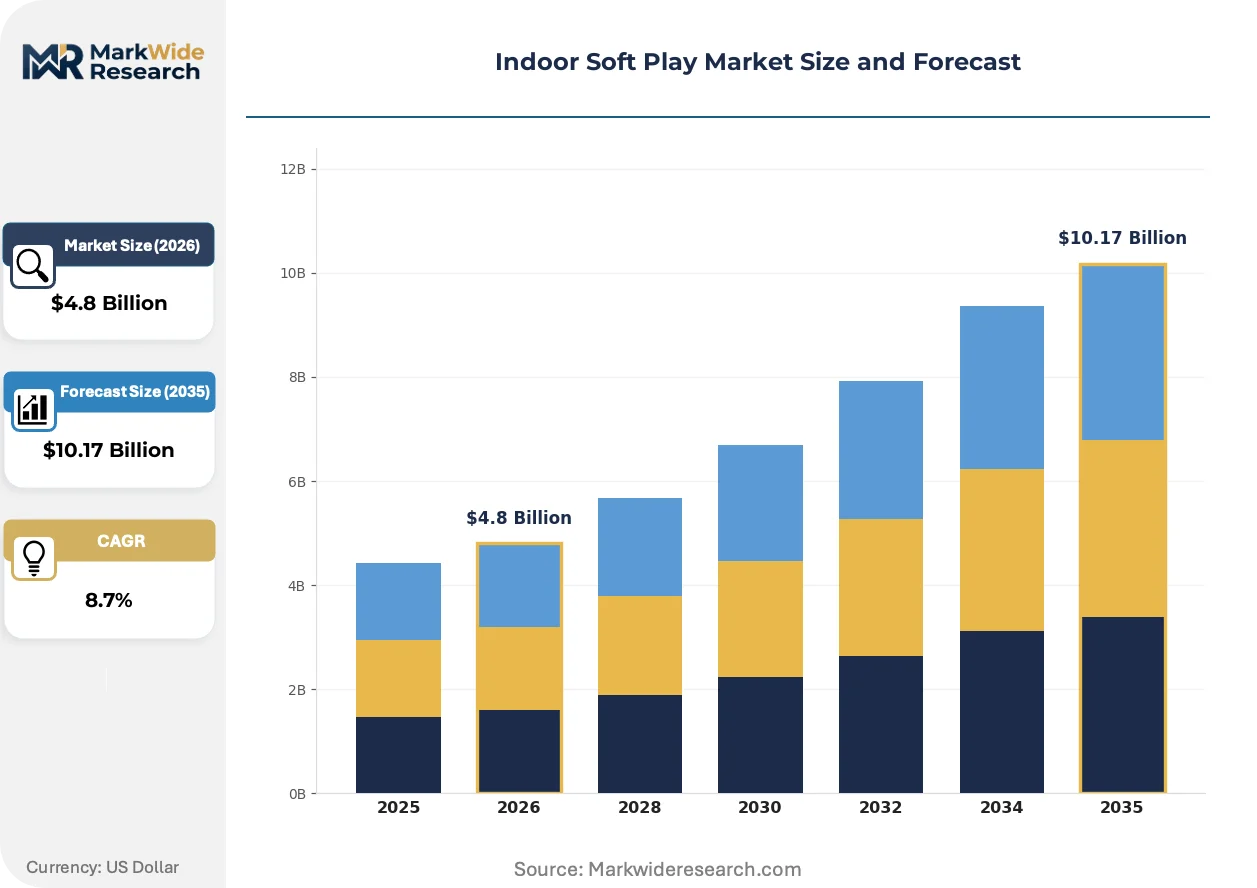
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Activity Playsets, Inflatable Structures, Soft Playground Equipment, Interactive Games End User: Children's Play Centers, Family Entertainment Centers, Schools, Daycare Facilities Application: Recreational Use, Educational Programs, Birthday Parties, Skill Development Sessions Size: Small Play Areas, Medium Play Zones, Large Play Complexes, Custom Design Installations |
| Companies Covered | Go Play Systems, KidSteam, Soft Play, FlyFun Amusement, iPlayCo, Angel Playground Equipment, Indoor Playgrounds International, United Play, Cheer Amusement, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indoor Soft Play Market Emerging Trajectories
Digital design tools and automated cutting systems are compressing the gap between concept visualization and physical installation, while regulatory disclosure requirements for chemical content reshape material selection protocols across supply chains.
Computer-aided foam cutting with CNC routing is collapsing the traditional fabrication timeline for custom play structures. Family entertainment center operators now expect six-week turnaround from design approval to on-site delivery, down from sixteen-week norms. This compression is collapsing the competitive advantage of standardized catalog offerings against bespoke configurations.
REACH flame-retardant chemical disclosure mandates are forcing polyurethane foam reformulation across European supply chains. Manufacturers must document halogen-free additive compositions through the SCIP database, elevating R&D overhead for export-oriented Chinese producers. Small and mid-scale fabricators without in-house chemistry capabilities are exiting the European market rather than absorbing compliance costs.
Outcome-based procurement contracts are displacing traditional equipment purchase models among United States chain operators. Lease-to-own structures with bundled maintenance and recertification services transfer capital risk from venue operators to equipment vendors. This shift concentrates contract awards with vertically integrated manufacturers capable of underwriting long-term performance guarantees.
Indoor Soft Play Market Segmentation
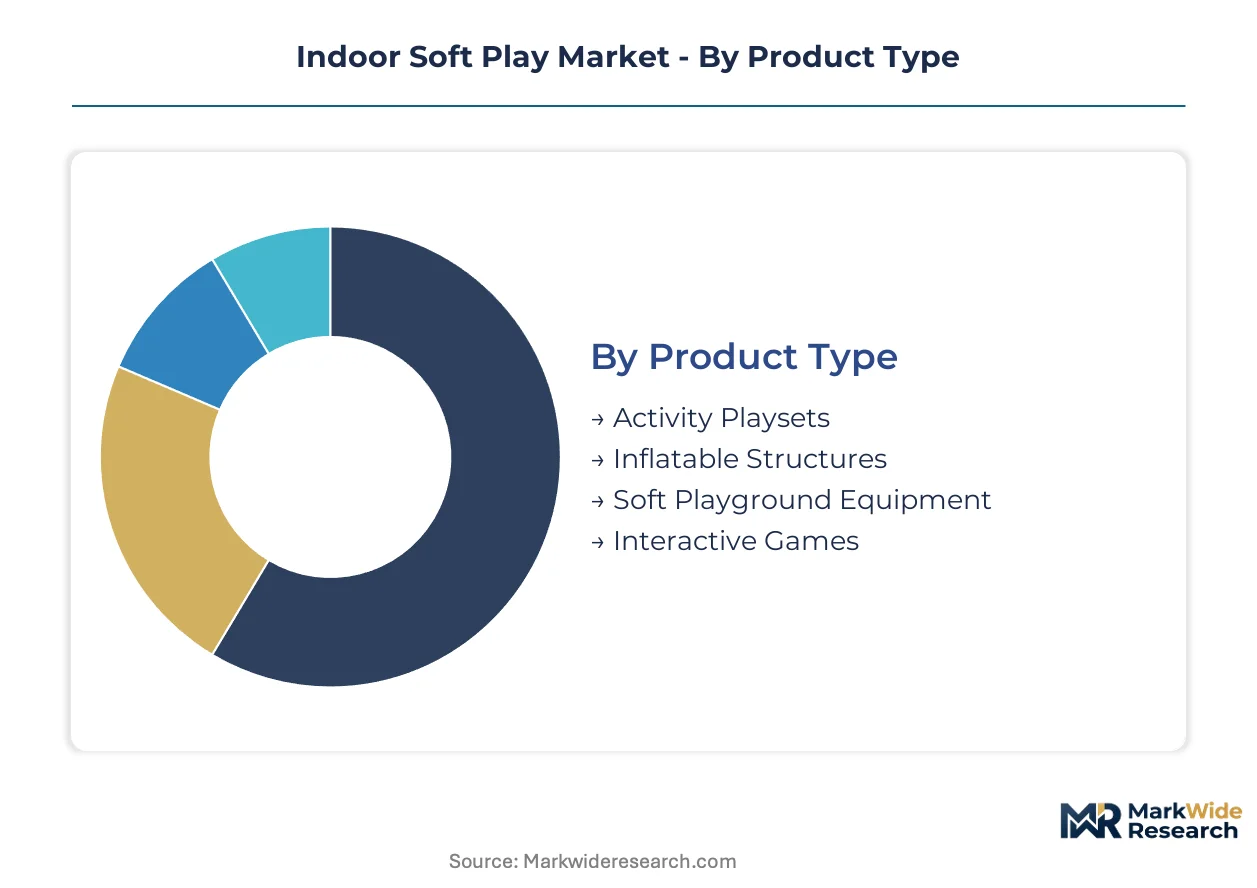
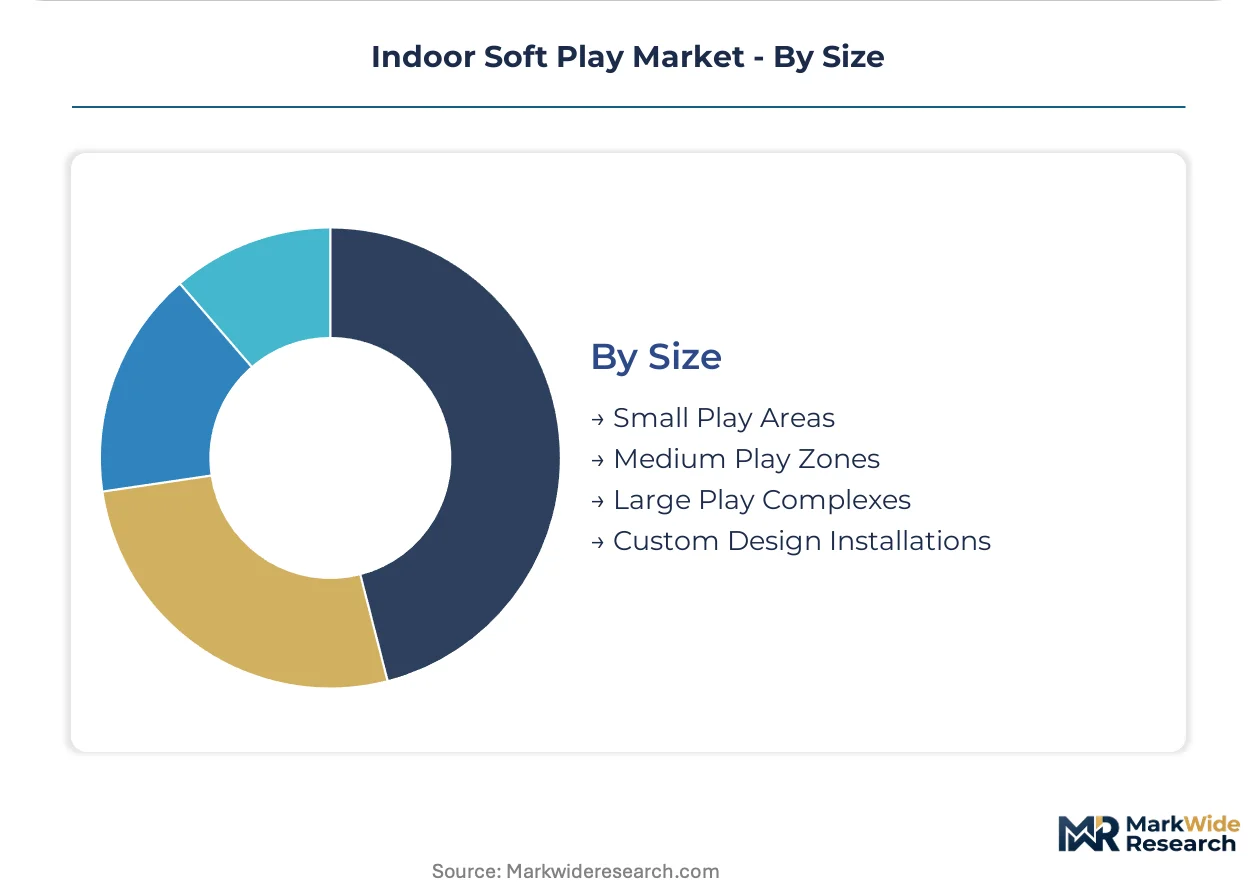
Segmentation in the Indoor Soft Play Market reveals distinct procurement patterns across product architectures, venue types, and spatial configurations. Each dimension shapes compliance requirements, installation complexity, and lifecycle economics differently for operators and suppliers.
Product Type:
Cost tier separates commodity foam systems from engineered interactive platforms, with certification depth and material specification driving price stratification.
- Activity Playsets:Modular foam structures with polyurethane cores and vinyl skins rated for ASTM F1918 impact absorption. Family entertainment centers in the United States prioritize these for retrofit installations where rapid deployment minimizes revenue disruption.
- Inflatable Structures:Portable air-supported configurations using PVC-coated textiles with rapid inflation systems. Budget-conscious operators favor these for seasonal reconfiguration and lower permanent capital commitment.
- Soft Playground Equipment:Fixed climbing frames and padded platforms engineered to EN 1176 fall-height standards.
- Interactive Games:Sensor-integrated foam elements combining physical play with digital feedback systems.
Activity Playsets holds installed capacity. Inflatable Structures is rotating up the share rankings.
End User:
Customer type determines liability exposure thresholds and maintenance contract structures across venue categories.
- Family Entertainment Centers:Commercial operators running multi-attraction venues with high throughput and accelerated equipment wear cycles. Chains like Chuck E. Cheese drive replacement demand for aging fixed installations with modular retrofits.
- Children's Play Centers:Dedicated soft play facilities emphasizing contained environments for toddler-to-elementary age groups. Operators here specify EN 1176-certified equipment to satisfy municipal leasing requirements and insurer mandates.
- Schools:Educational institutions integrating soft play into physical education curricula and recess facilities.
- Daycare Facilities:Licensed childcare operators requiring compliant surfaces under state-level early childhood safety regulations.
Family Entertainment Centers dominates procurement volume. Children's Play Centers is climbing the fastest in specification intensity.
Application:
Volume distribution across use cases reflects revenue model differentiation between admission-based and event-based economics.
- Recreational Use:General admission play sessions generating baseline throughput for fixed-cost venues. This application concentrates in United States metropolitan markets where disposable income supports repeat visitation.
- Birthday Parties:Private event bookings with premium pricing and dedicated party room integration. Operators bundle themed decorations and catering to capture celebration spending.
- Educational Programs:Structured curricula linking physical activity to developmental milestones.
- Skill Development Sessions:Targeted programming for motor coordination and sensory integration.
Recreational Use anchors daily utilization rates. Birthday Parties is gaining share fastest in revenue-per-visit metrics.
Size:
Spatial scale dictates project economics from catalog components to integrated design-build contracts.
- Small Play Areas:Compact configurations under 500 square feet targeting retail adjacencies and restaurant co-location. These systems ship as prefabricated modules with minimal on-site assembly.
- Large Play Complexes:Multi-level installations exceeding 5,000 square feet with integrated theming, maintenance contracts, and recertification services. Design-build vendors capture margin through bundled offerings.
- Medium Play Zones:Mid-scale footprints serving standalone children's centers and community recreation facilities.
- Custom Design Installations:Bespoke configurations shaped to irregular architectural constraints or branded intellectual property requirements.
Small Play Areas holds unit volume leadership. Large Play Complexes is rotating up the margin pool concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ASTM F1918 standards anchor demand concentration in the United States, where chain operators and independent family entertainment centers drive replacement cycles for aging foam installations. European procurement centers on EN 1176 compliance premiums, while Asian supply chains reshape cost structures through scaled textile and foam fabrication capacity.
United States
Chuck E. Cheese and regional FEC chains accelerate modular retrofit investments to extend facility lifecycles without full reconstruction. State-level childcare licensing boards mandate flame-retardant surface documentation under OSHA workplace safety frameworks. Dallas-Fort Worth and Atlanta metropolitan clusters concentrate installation contractor networks serving the Southeast and Southwest replacement markets.
Germany
Municipal leasing requirements for public venues elevate EN 1176-certified equipment specifications above commodity alternatives. ECHA REACH disclosure mandates for halogen-free flame retardants compress supplier qualification timelines. The Rhine-Ruhr industrial corridor hosts specialized polyurethane foam compounders reformulating core materials for export-compliant production.
United Kingdom
Independent children's play centers prioritize liability-managed recreation spaces to satisfy insurer risk assessments. Health and Safety Executive guidelines align with EN 1176 fall-height standards for contained play environments. Greater Manchester and West Midlands urban regeneration projects repurpose retail vacancies into dedicated soft play facilities.
China
GB 6675 mechanical property standards create additional certification layers for domestic distribution alongside export compliance. MIIT industrial upgrading programs support automated foam cutting and CNC routing investments in manufacturing bases. The Yangtze River Delta concentration of textile fabricators scales vinyl and PVC-coated skin production for component supply.
Australia
Shopping center operators integrate compact soft play modules as tenant mix diversification tools in secondary metropolitan markets. Standards Australia maintains AS 4685 playground equipment benchmarks with cross-reference to EN 1176 impact-absorption protocols. Melbourne and Sydney peripheral growth corridors attract purpose-built children's entertainment venue developments.
Indoor Soft Play Market Vendor Landscape
Domestic manufacturers and export-oriented fabricators split the market along certification depth and lead-time flexibility vectors. The vendor base concentrates around three strategic archetypes: vertically integrated design-build operators controlling installation and maintenance workflows; specialized foam compounders supplying certified core materials to third-party assemblers; and modular system integrators compressing deployment timelines through prefabricated component platforms. Competitive positioning hardens through ASTM F1918 pre-certification investments and long-term service contract underwriting.
Among North American design-build specialists, Go Play Systems and KidSteam exemplify contrasting geographic anchoring strategies. Soft Play occupies a position within the European compliance-tier, leveraging EN 1176 certification depth to access municipal and insurer-mandated procurement channels. These three entities represent the archetype spectrum from domestic manufacturing control to specialized aquatic-themed differentiation and regulatory-premium positioning.
| Leading Market Players |
|---|
| Go Play Systems |
| KidSteam |
| Soft Play |
| FlyFun Amusement |
| iPlayCo |
| Angel Playground Equipment |
| Indoor Playgrounds International |
| United Play |
| Cheer Amusement |
| Others |
Supply Flow & Price Mechanics
REACH flame-retardant disclosure mandates in Europe compress supplier qualification timelines and force polyurethane foam reformulation investments, creating pricing tier spreads that separate EN 1176-certified European producers from commodity Asian fabricators while reshaping procurement toward vertically integrated manufacturers capable of underwriting compliance costs.
Pricing Analysis
United States family entertainment centers pay premiums of fifteen to twenty-five percent above Southeast Asian spot prices for ASTM F1918-certified equipment with bundled installation and recertification services. Three-tier pricing structure across premium, standard, and economy levels separates design-build vendors with maintenance contracts from modular catalog suppliers and inflatable rental operators. Cost compression in the mid-tier intensifies because petrochemical feedstock volatility compresses margin predictability for polyurethane foam compounders without captive polyol supply. Budget-conscious independent operators exhibit highest price sensitivity, while liability-insured chain venues prioritize certification depth over unit cost.
Supply Chain Analysis
Polyurethane foam cores draw from isocyanate and polyol feedstocks concentrated in China, Germany, and the United States, with textile fabrication for vinyl and PVC-coated skins clustering in Vietnam and Indonesia. Raw material dependencies rest on MDI isocyanate, propylene oxide derivatives, and marine-grade coated fabrics rated for abrasion resistance. Single-source vulnerability concentrates in Southeast Asian textile finishing capacity exposed to regional logistics disruptions. Distribution runs through direct design-build contracts for large complexes and distributor networks for prefabricated small play area modules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Modular foam fabrication systems and REACH chemical disclosure mandates are disrupting competitive positioning in indoor soft play, compressing timelines between design approval and installation while elevating compliance investments that favor capitalized incumbents over small-scale fabricators.
For Market Incumbents: Harden market position by acquiring specialized installation contractor networks in Dallas-Fort Worth and Atlanta metropolitan clusters where trained crew scarcity constrains rollout velocity. Deepen upstream control over polyurethane foam compounding in the Rhine-Ruhr corridor to secure REACH-compliant core material supply against Chinese exporter withdrawal from European certification markets. For New Entrants and Emerging Players: Tier-two metropolitan areas in the United States with repurposed retail vacancies represent the most penetrable entry point for modular soft play deployments lacking purpose-built family entertainment center competition. Water park operators expanding into year-round indoor recreation present adjacent demand for moisture-resistant foam composites. A lease-to-own go-to-market structure with bundled maintenance contracts transfers capital risk from venue operators and accelerates customer acquisition against cash-sale incumbents. For Investors and Strategic Acquirers: Design-build specialists with captive installation capabilities and long-term service contract books present the strongest acquisition target archetype for exposure to recurring revenue streams in a replacement-cycle market. Long-term viability hinges on regulatory compliance depth rather than manufacturing scale alone. The signal to monitor is EN 1176 certification queue lengths at accredited European laboratories, as extended timelines indicate supply constraint and pricing power accrual to pre-certified vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foam Compounding | REACH-compliant polyurethane core production secures European market access against exporter withdrawal. |
| Installation Contractor Network Acquisition | Trained crew scarcity in United States secondary cities constrains competitor rollout velocity. |
| Integrated Maintenance Contract Launch | Long-term service agreements lock in recurring revenue and transfer liability risk from venue operators. |
| Aquatic-Themed Product Line Expansion | Water park indoor expansion creates demand for marine-grade textile skins and moisture-resistant composites. |
| Prefabricated Module Platform Development | Six-week turnaround expectations from family entertainment center operators collapse catalog competitive advantage. |
Methodological Framework
The analysis maps activity playsets, inflatable structures, soft playground equipment, and interactive games, each validated through facility operators, installation contractors, polyurethane foam compounders, and liability insurance underwriters, combining primary interviews with trade association filings, ASTM and CEN certification databases, customs import records, and petrochemical feedstock price indices, with bottom-up facility counts triangulated against top-down addressable spend estimates.
Fixed assumptions across the projection horizon include sustained ASTM F1918 and EN 1176 enforcement intensity, continued petrochemical price volatility within historical bands, and modular retrofit preference over new construction among United States family entertainment centers. Segmentation dimensions modeled encompass product architecture, venue type, spatial scale, and application use case, with CAGRs derived from replacement cycle timing, facility expansion rates, and certified equipment penetration curves across regional regulatory clusters.
Stress conditions across isocyanate price spikes, REACH additive ban accelerations, and Southeast Asian logistics disruptions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about certification queue lengths and contractor availability. Cross-checking against family entertainment center capital expenditure disclosures and municipal leasing records is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Toys and Games
Global Blind Boxes Market
Toys and Games
Plush Toy Market
Toys and Games
Drone for Kids Market
Toys and Games
Arcade Games Machine Market
Toys and Games
Toys and Games Market
Toys and Games
Decompression Toys Market
Toys and Games
Toy Cars Market
Toys and Games
Board Games and Puzzles Market
Toys and Games
Snooker Tables Market
Toys and Games
Global Educational Toy Market
Toys and Games
Kids Toys Market
Toys and Games
Autonomous Robot Toys Market
Toys and Games
Action Figures Market
Toys and Games
Blind Box Toys Market
Toys and Games
Glow Sticks Market
Toys and Games
Bath Toy Market