
 Pet Clothing Market | 2026-2036
Pet Clothing Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Clothing Market Intelligence
Direct-to-consumer digital storefronts is tilting toward subscription and membership models as primary customer acquisition engines. Ruffwear leverages technical outdoor performance credentials to command premium positioning across mountain-state retail networks. H&M competes through fast-fashion velocity and seasonal drop cadence that mirrors human apparel cycles. Maxbone anchors its growth in influencer-driven social commerce, converting TikTok engagement into repeat purchases through limited-edition collaborations.
Pet clothing encompasses functional and decorative garments engineered from woven, knitted, or bonded textiles to protect companion animals from environmental exposure or express owner aesthetic preferences; fleece-lined jackets with waterproof nylon shells achieve thermal resistance ratings comparable to human outdoor gear while maintaining four-way stretch for unrestricted movement. Cotton and polyester blends dominate unit volume due to cost-efficient dye sublimation compatibility and machine-wash durability, though wool and recycled fleece segments attract outsized margin pools as sustainability credentials harden into purchase criteria. Dog-specific SKUs generate disproportionate revenue concentration given canine body-size standardization and walk-culture accessory attachment, while cat apparel remains structurally constrained by fit tolerance and lower outdoor exposure.
FDA's textile contact-safety guidelines for pet products, California's Proposition 65 labeling mandates, and REACH substance restrictions in Europe collectively elevate compliance costs for synthetic dye formulations and flame-retardant treatments. These frameworks advantage suppliers with pre-certified material libraries and documented supply-chain transparency, squeezing smaller private-label importers. Stakeholders must monitor how evolving extended-producer-responsibility legislation for textiles reshapes cost allocation between brands and contract manufacturers.
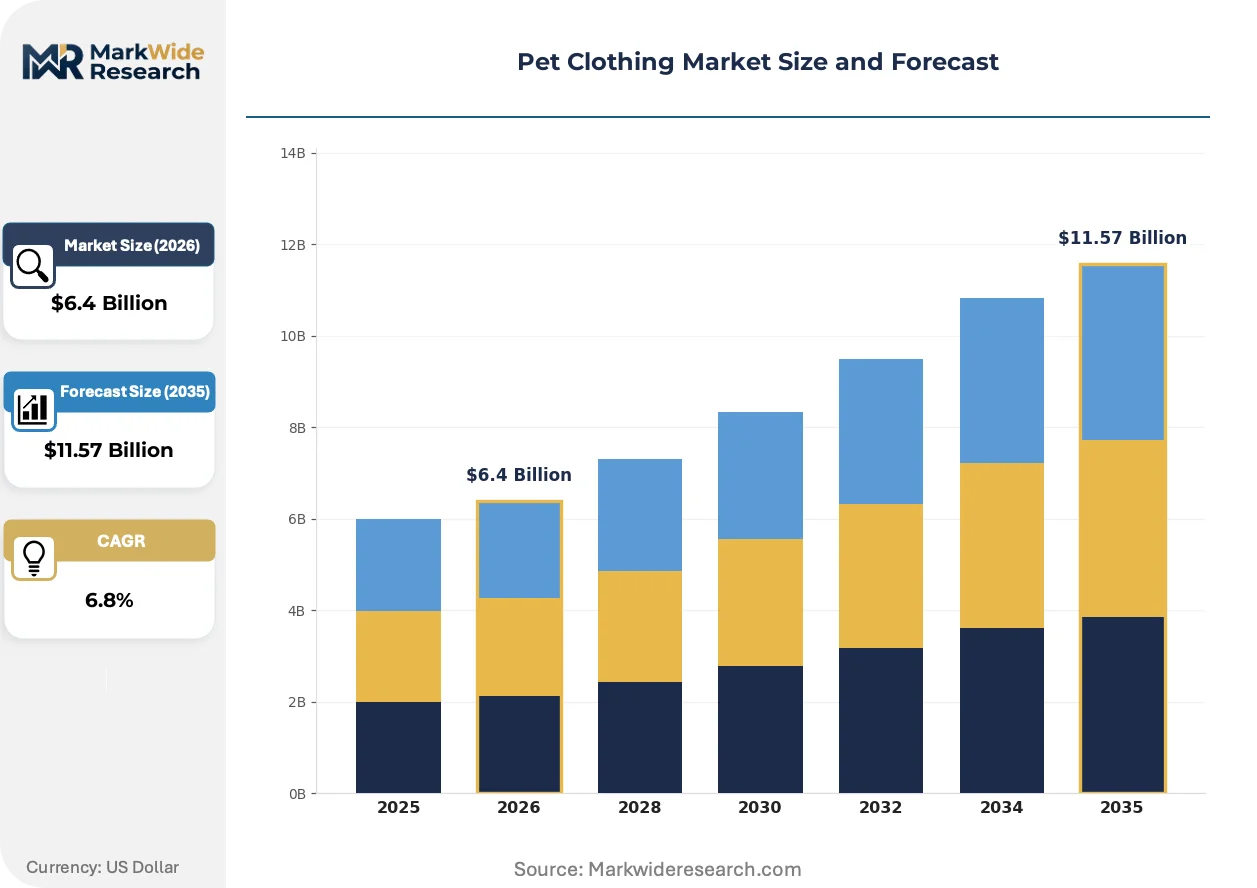
Market Dynamics
Humanization of companion animals has compressed product development cycles to mirror human fashion calendars, forcing brands to manage seasonal inventory risk against pet-specific sizing constraints and veterinary safety approvals.
Growth Catalysts
- REACH substance restrictions:European chemical compliance mandates are accelerating certified organic cotton adoption across premium supply chains, creating defensible positioning for early certifiers.
- Urban walk culture:Dense metropolitan dog ownership in Tokyo and New York generates consistent demand for weather-protective outerwear with leash-integrated hardware.
- Recycled polyester feedstocks:Post-consumer plastic conversion technologies are lowering sustainable material cost premiums to parity with virgin synthetics in bulk orders.
Market Restraints
- California Proposition 65 labeling:Warning requirements for synthetic dyes and flame retardants impose documentation burdens that disproportionately burden small private-label importers.
- Asian textile concentration:Overreliance on Zhejiang and Guangdong province manufacturers exposes brands to shipping rate volatility and geopolitical trade friction.
- Feline fit tolerance:Structural resistance to garment acceptance among cats limits addressable market expansion regardless of owner spending willingness.
Strategic Opportunities
- German extended-producer-responsibility frameworks:Pending textile waste legislation creates first-mover advantage for brands with pre-established take-back infrastructure and circular design capabilities.
- Veterinary therapeutic crossover:Compression garments for post-surgical recovery and anxiety management represent reimbursable expense categories in pet insurance plans.
- TikTok-native social commerce:Limited-edition drops tied to influencer collaborations convert engagement directly to purchase without traditional retail markup.
Industry Challenges
- Size standardization deficits:Absence of universal measurement protocols across breeds forces costly custom pattern development and elevates return rates.
- Multi-jurisdiction certification timelines:Simultaneous FDA contact-safety review and EU REACH dossier preparation extend product launch windows by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet Clothing Market |
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $11.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Jackets, Sweaters, Raincoats, Costumes, Booties Material: Cotton, Polyester, Fleece, Wool, Nylon Pet Type: Dogs, Cats, Rabbits, Ferrets, Guinea Pigs Distribution Channel: Online Retailers, Specialty Stores, Supermarkets, Veterinary Clinics |
| Companies Covered | Ruffwear, Fab Dog, Ralph Lauren, Little Beast, Weatherbeeta, H&M, Hurtta, Maxbone, Gucci Pet Collection, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Clothing Market Strategic Shifts & Innovations
Material science advances and regulatory tightening are converging to redefine acceptable performance benchmarks, while digital-native distribution models compress traditional wholesale relationships.
Biodegradable polymer coatings is migrating from experimental outdoor gear applications into mainstream pet rainwear production. Technical apparel manufacturers in the Pacific Northwest are piloting corn-derived waterproof membranes that decompose within industrial composting cycles. This transition is pressuring conventional polyurethane suppliers to accelerate bio-based R&D or cede premium positioning.
EU Green Deal textile strategy implementation is forcing supply chain disclosure requirements that extend to tier-three chemical suppliers. Brands must now document dye house water treatment and energy sourcing to maintain market access. German and French retailers are already rejecting shipments lacking digital product passport compatibility.
Subscription-based wardrobe refresh programs are displacing single-transaction purchasing among millennial pet owners in London and Amsterdam. These services aggregate sizing data across breeds to improve fit algorithms and reduce return friction. The model concentrates customer lifetime value but demands sophisticated inventory pooling across multiple sizing tiers.
Pet Clothing Market Segmentation
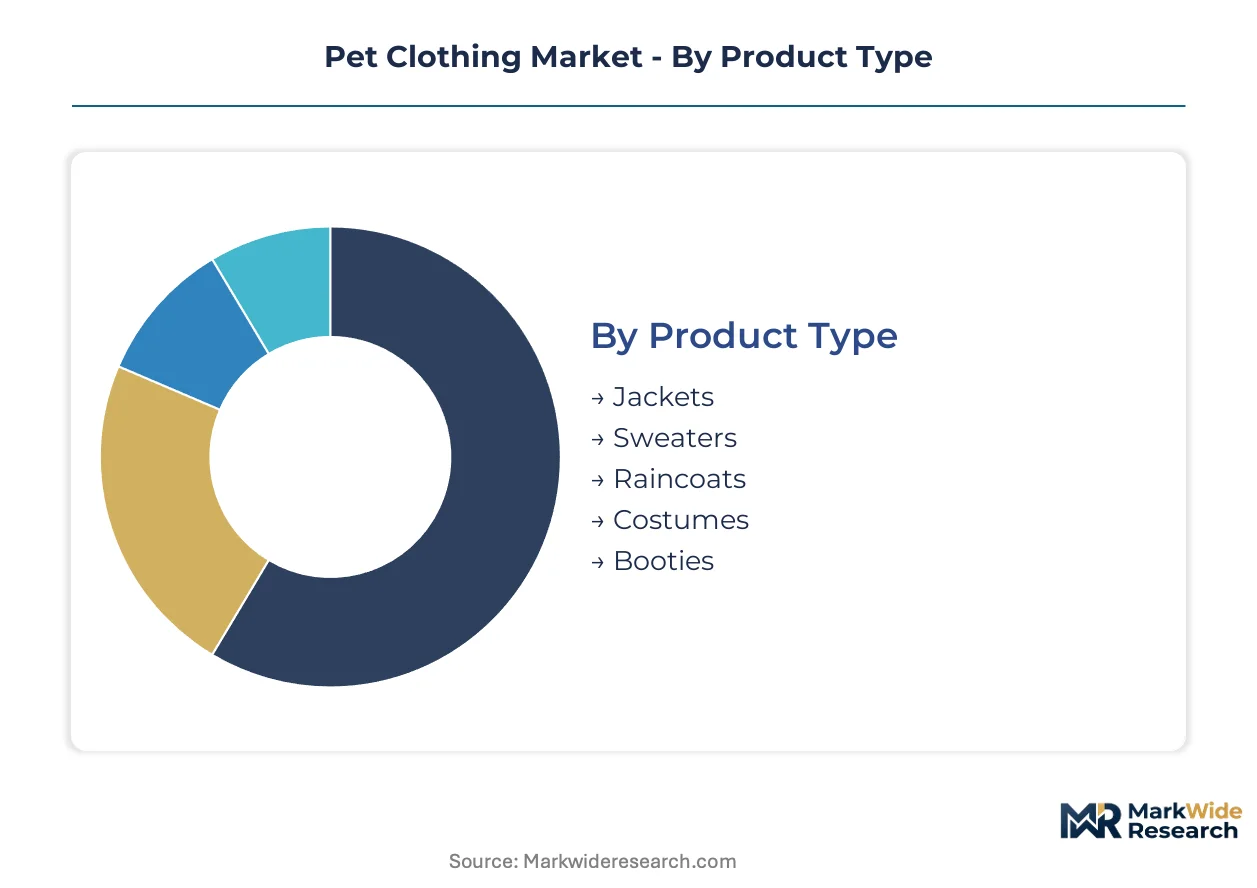
Segmentation in pet clothing reflects divergent purchasing logics across functional need, aesthetic expression, and species-specific fit constraints. Brands must calibrate inventory depth and margin targets differently across each axis to avoid mismatches between production scale and demand concentration.
Product Type:
Mature outerwear categories coexist with emerging novelty segments that carry higher margin volatility.
- Jackets:Waterproof nylon shells with fleece lining achieve thermal ratings matching human outdoor gear; four-way stretch panels accommodate unrestricted movement. Demand concentrates in premium urban corridors including New York and Tokyo where walk culture necessitates weather protection with leash-integrated hardware.
- Sweaters:Knitted constructions in wool or cotton blends dominate transitional season purchasing; machine-wash durability drives repeat buying. California and London generate disproportionate volume as owners prioritize layering flexibility amid variable coastal climates.
- Raincoats:Lightweight polyurethane-coated fabrics with reflective trim address visibility requirements; biodegradable polymer coatings are migrating from experimental applications into mainstream production.
- Costumes:Seasonal novelty items tied to Halloween and holiday calendars carry inventory risk from compressed selling windows; limited-edition drops through TikTok-native channels reduce markdown exposure.
- Booties:Silicone or rubber-soled designs protect paw pads from salt and thermal extremes; adoption remains constrained by fit tolerance and training requirements.
Jackets handle the majority of throughput; costumes are expanding most quickly on share through social commerce velocity.
Material:
Cost tier stratification separates certified sustainable feedstocks from commodity synthetics.
- Cotton:Organic certification commands measurable premiums as EU REACH substance restrictions and California Proposition 65 labeling squeeze conventional dye formulations. German and French retailers now reject shipments lacking documented supply chain transparency.
- Polyester:Recycled post-consumer plastic feedstocks have achieved cost parity with virgin synthetics at bulk order scales; dye sublimation compatibility sustains volume dominance in graphic-intensive applications.
- Fleece:Recycled polyester variants attract outsized margin pools as sustainability credentials harden into purchase criteria; Pacific Northwest technical apparel manufacturers pilot corn-derived waterproof membranes.
- Wool:Natural thermal regulation and odor resistance support premium positioning; sourcing concentrates in certified merino supply chains with documented animal welfare protocols.
- Nylon:High tenacity variants provide abrasion resistance for active outdoor use; bio-based R&D acceleration is pressuring conventional polyurethane suppliers.
Polyester retains volume leadership; organic cotton is climbing the fastest as regulatory compliance reshapes procurement priorities.
Pet Type:
Body-size standardization determines addressable market economics across species.
- Dogs:Breed measurement databases enable algorithmic fit prediction; subscription wardrobe services aggregate sizing data to reduce return friction. Canine SKUs generate disproportionate revenue concentration given walk-culture accessory attachment.
- Cats:Structural resistance to garment acceptance limits expansion regardless of owner spending willingness; smaller accessory formats including bandanas outperform full-body coverage.
- Rabbits:Temperature-sensitive physiology creates demand for lightweight thermal layers; veterinary therapeutic crossover applications include post-surgical compression.
- Ferrets:Elongated body proportions require specialized pattern development; addressable market remains constrained by population scale.
- Guinea Pigs:Social media visibility drives novelty purchasing; product lifecycles align with owner acquisition rather than replacement cycles.
Dogs absorb the dominant share of production capacity; rabbits are gaining share fastest through veterinary channel expansion.
Distribution Channel:
Customer acquisition economics favor digital-native models with membership retention mechanics.
- Online Retailers:Direct-to-consumer storefronts are tilting toward subscription and membership models; sizing algorithm improvement concentrates customer lifetime value across multiple refresh cycles.
- Specialty Stores:Curated assortments with fitting services command premium positioning; mountain-state retail networks leverage technical outdoor performance credentials.
- Supermarkets:Mass-market velocity depends on seasonal drop cadence mirroring human apparel cycles; private-label importers face margin compression from compliance documentation burdens.
- Veterinary Clinics:Therapeutic garment categories including compression and anxiety management represent reimbursable expense categories in pet insurance plans.
Online retailers process the highest transaction volume; veterinary clinics are expanding most quickly as therapeutic applications formalize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU REACH substance restrictions and California's Proposition 65 labeling mandates are reshaping procurement geography across the pet clothing industry. Millennial and Gen Z pet owners in dense urban corridors are driving premium apparel demand through humanization trends.
United States
California's Proposition 65 warning requirements for synthetic dyes impose documentation burdens that squeeze small private-label importers. The FDA maintains textile contact-safety guidelines for pet products that elevate compliance timelines. New York City anchors walk-culture demand for weather-protective outerwear with leash-integrated hardware.
Germany
Extended-producer-responsibility frameworks for textile waste create first-mover advantage for brands with pre-established take-back infrastructure. ECHA REACH dossier preparation extends product launch windows alongside FDA review cycles. Berlin and Munich concentrate subscription-based wardrobe refresh services among millennial pet owners.
United Kingdom
London generates disproportionate sweater volume as owners prioritize layering flexibility amid variable coastal climates. The UK's post-Brexit regulatory alignment with EU chemical standards maintains REACH-equivalent substance restrictions. Premium urban corridors drive demand for organic cotton certification across supply chains.
Japan
Tokyo's dense metropolitan dog ownership generates consistent demand for technical outerwear with four-way stretch panels. METI standards influence textile safety protocols that align with international export requirements. The Kanto region anchors fast-fashion velocity mirroring human apparel seasonal cycles.
France
French retailers are rejecting shipments lacking digital product passport compatibility under EU Green Deal textile strategy implementation. ANSM oversight extends to veterinary therapeutic crossover applications including post-surgical compression garments. Paris concentrates influencer-driven social commerce converting TikTok engagement into repeat purchases.
Pet Clothing Market Key Industry Players
On the supply side, the industry is bifurcated between technical outdoor specialists and fast-fashion velocity players. Consolidation pressure concentrates among subscription-model digital natives and heritage outdoor brands with certified material libraries. Three strategic archetypes dominate: performance-technical, fast-fashion seasonal, and influencer-driven social commerce. Competitive moves center on circular design capabilities and sizing algorithm development to reduce return friction.
Within the performance-technical tier, Ruffwear exemplifies mountain-state retail network penetration with technical outdoor credentials. Hurtta occupies a position among Nordic-origin specialists emphasizing weather-protective engineering. Maxbone anchors the influencer-driven social commerce archetype, converting platform engagement through limited-edition collaboration drops.
| Leading Market Players |
|---|
| Ruffwear |
| Fab Dog |
| Ralph Lauren |
| Little Beast |
| Weatherbeeta |
| H&M |
| Hurtta |
| Maxbone |
| Gucci Pet Collection |
| Others |
Cost & Logistics Intelligence
Zhejiang and Guangdong province textile manufacturers anchor upstream supply, concentrating margin capture with certified organic cotton and recycled polyester suppliers who command premiums from REACH-compliant brands. This geographic concentration funnels pricing power toward pre-certified material libraries while squeezing private-label importers absorbing Proposition 65 documentation costs.
Pricing Analysis
Volume-discount tiering structures separate subscription wardrobe services from single-transaction retailers, with premium-mid-economy pricing differentiation driven by certification grade and after-sales bundling. Cost compression in economy tiers intensifies because private-label importers lack certified supply chains. Subscription-based buyers show lowest price sensitivity; mass-market supermarket channels face highest margin pressure.
Supply Chain Analysis
Extended payment terms from Zhejiang dye houses to contract manufacturers are tightening as REACH compliance documentation extends cash conversion cycles. Raw material sourcing draws from certified organic cotton suppliers, post-consumer recycled polyester feedstocks, and corn-derived biodegradable polymer developers. Single-source vulnerability concentrates in waterproof membrane coating facilities. Distribution runs through direct-to-consumer digital storefronts with membership retention mechanics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pet clothing demand follows seasonal fashion calendars, creating cyclical inventory risk compression each autumn as brands accelerate drops ahead of holiday purchasing windows.
For Market Incumbents: Entrench certified material libraries against emerging subscription-model digital natives by accelerating backward integration into organic cotton supply chains and locking tier-three dye house transparency documentation. Priority investment centers on sizing algorithm development to reduce return friction.
For New Entrants and Emerging Players: Build out veterinary therapeutic crossover applications including post-surgical compression and anxiety management garments, the most penetrable segment given reimbursable pet insurance coverage. Direct-to-consumer launch with TikTok-native influencer collaboration protocol captures engagement-to-purchase conversion.
For Investors and Strategic Acquirers: Capital is best deployed toward technical outdoor specialists with mountain-state retail network penetration and pre-established take-back infrastructure for extended-producer-responsibility compliance. The signal to watch is German textile waste legislation implementation accelerating circular design capability premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Certified Organic Cotton Backward Integration | REACH compliance mandates defensible positioning for early certifiers against conventional dye suppliers. |
| Subscription Wardrobe Service Launch | Membership retention mechanics concentrate customer lifetime value across multiple sizing refresh cycles. |
| Veterinary Therapeutic Garment Development | Post-surgical compression categories unlock reimbursable pet insurance expense channels. |
| TikTok-Native Influencer Collaboration Protocol | Limited-edition drops convert platform engagement directly to purchase without retail markup. |
| Extended-Producer-Responsibility Infrastructure Buildout | Pre-established take-back capabilities create first-mover advantage under pending German textile waste frameworks. |
Research Approach
A spread of perspectives from brand supply chain directors, specialty retail category buyers, veterinary clinic procurement managers, and contract manufacturing executives converged on the working assumptions underlying this analysis. Primary fieldwork combined with secondary validation from customs trade records, EU ECHA REACH dossier filings, FDA textile contact-safety guidance documents, and digital commerce platform transaction data. Bottom-up sizing by product-material-pet type-channel segments triangulated against top-down market value reconstructions.
Demand-supply-balance framing across the analysis window modeled seasonal inventory risk against certified feedstock availability constraints. Segmentation dimensions included functional versus decorative garment purpose, sustainable versus conventional material tier, canine versus feline species economics, and direct-to-consumer versus wholesale channel mix. CAGRs derived from trend extrapolation of humanization-driven spending elasticity, adjusted for regulatory compliance cost pass-through assumptions and subscription-model customer lifetime value concentration.
Stress conditions across REACH substance restriction enforcement intensity, shipping rate volatility from Asian textile concentration, and feline fit tolerance adoption ceilings were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about millennial and Gen Z pet owner spending persistence. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Pet Odor Absorber Market
Pet Care Products
Dog Hats Market
Pet Care Products
Fish Based Pet Food Market
Pet Care Products
Pet Rugs Market
Pet Care Products
Pet Jerky Treat Market
Pet Care Products
Natural Dog Treat Market
Pet Care Products
North America Pet Food Market
Pet Care Products
North America Cat Food Market
Pet Care Products
Pet Treats and Chews Market
Pet Care Products
United States Pet Market
Pet Care Products
Pet Clean-Up and Odor-Control Products Market
Pet Care Products
Europe Pet Food Market
Pet Care Products
UAE Dog Food Market
Pet Care Products
Europe Farrier Products Market
Pet Care Products
Australia Pet Boarding Market
Pet Care Products
Cat Food Toppers Market