
 Large Breed Dog Food Market | 2026-2036
Large Breed Dog Food Market Size, Share, and Industry Trends Forecast 2026-2036
Large Breed Dog Food Market Foresight
Premium therapeutic formulations is reorganizing competitive dynamics in large breed nutrition. Mars Incorporated leverages its veterinary hospital network to channel prescription large breed diets through licensed practitioners. Nestlé Purina PetCare anchors its position through breed-specific Pro Plan lines that address hip and joint maintenance in giant breeds. Hill's Pet Nutrition dominates the clinical segment with Science Diet formulations calibrated for controlled growth rates in susceptible puppies.
Large breed dog food denotes nutritionally engineered diets formulated with controlled calcium-to-phosphorus ratios, glucosamine enrichment, and reduced caloric density to mitigate skeletal developmental disorders in dogs exceeding fifty pounds at mature weight. Manufacturing employs extrusion conditioning with precise thermal profiles to preserve heat-labile chondroprotective compounds while achieving pathogen elimination standards. Dry kibble commands the volume base due to shelf stability and cost efficiency, though freeze-dried segments capture disproportionate margin pools through raw nutrition positioning and minimal processing claims. Functional ingredients including omega-3 fatty acids and green-lipped mussel extract are gaining traction as owners seek proactive musculoskeletal support.
AAFCO nutrient profiles and FDA Center for Veterinary Medicine oversight establish minimum thresholds for large breed puppy formulations, restricting calcium levels to prevent panosteitis and osteochondritis dissecans. NRC canine nutrition guidelines inform state-level feed control official inspections that govern interstate commerce compliance. Pet specialty retailers and veterinary clinics must monitor evolving regulatory distinctions between therapeutic diets and wellness-positioned premium foods to optimize assortment and avoid misbranding exposure.
Market Dynamics
Veterinary nutrition protocols are hardening around developmental orthopedic disease prevention, forcing manufacturers to revalidate calcium-phosphorus ratios through AAFCO-compliant feeding trials before commercial release.
Growth Catalysts
- AAFCO Nutrient Profiles:Mandatory calcium ceilings for large breed puppy formulations create technical barriers that filter out commodity competitors and reward R&D-intensive manufacturers with shelf access.
- Glucosamine Enrichment Processes:Thermal conditioning advances preserve chondroprotective bioactivity through extrusion, enabling functional claims that command veterinary endorsement and retail placement.
- United States:Elevated per-pet therapeutic diet spending and giant breed ownership concentration generate disproportionate revenue pools for compliant formulations.
Market Restraints
- Animal Protein Input Volatility:Rendering-grade poultry meal and fishmeal prices fluctuate with commodity cycles, compressing margin stability for mid-tier producers without backward integration into protein supply.
- Regulatory Friction:FDA Center for Veterinary Medicine distinctions between therapeutic diets and wellness-positioned premium foods create misbranding exposure for retailers optimizing assortments across channels.
- Freeze-Dried Substitution:Raw nutrition positioning in minimally processed segments captures margin pools that kibble manufacturers cannot access without capital-intensive line reconfiguration.
Strategic Opportunities
- Green-Lipped Mussel Extract Convergence:Omega-3 fatty acid pairing with novel marine bioactives creates differentiated musculoskeletal support positioning for proactive owner segments.
- Veterinary Channel Expansion:Prescription diet authorization through licensed practitioners unlocks recurring revenue streams insulated from price-based retail competition.
- Pet Specialty Retail Innovation:Breed-specific planogram segmentation and in-store nutrition counseling services deepen basket penetration among first-time large breed adopters.
Industry Challenges
- Formulation Scientist Scarcity:Veterinary nutrition PhD recruitment lags demand for AAFCO protocol-compliant product development, extending time-to-market for new large breed lines.
- Extrusion Line Capex Intensity:Precision thermal profile equipment for chondroprotective preservation requires seven-figure capital deployment that fragments manufacturing scale economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Large Breed Dog Food Market |
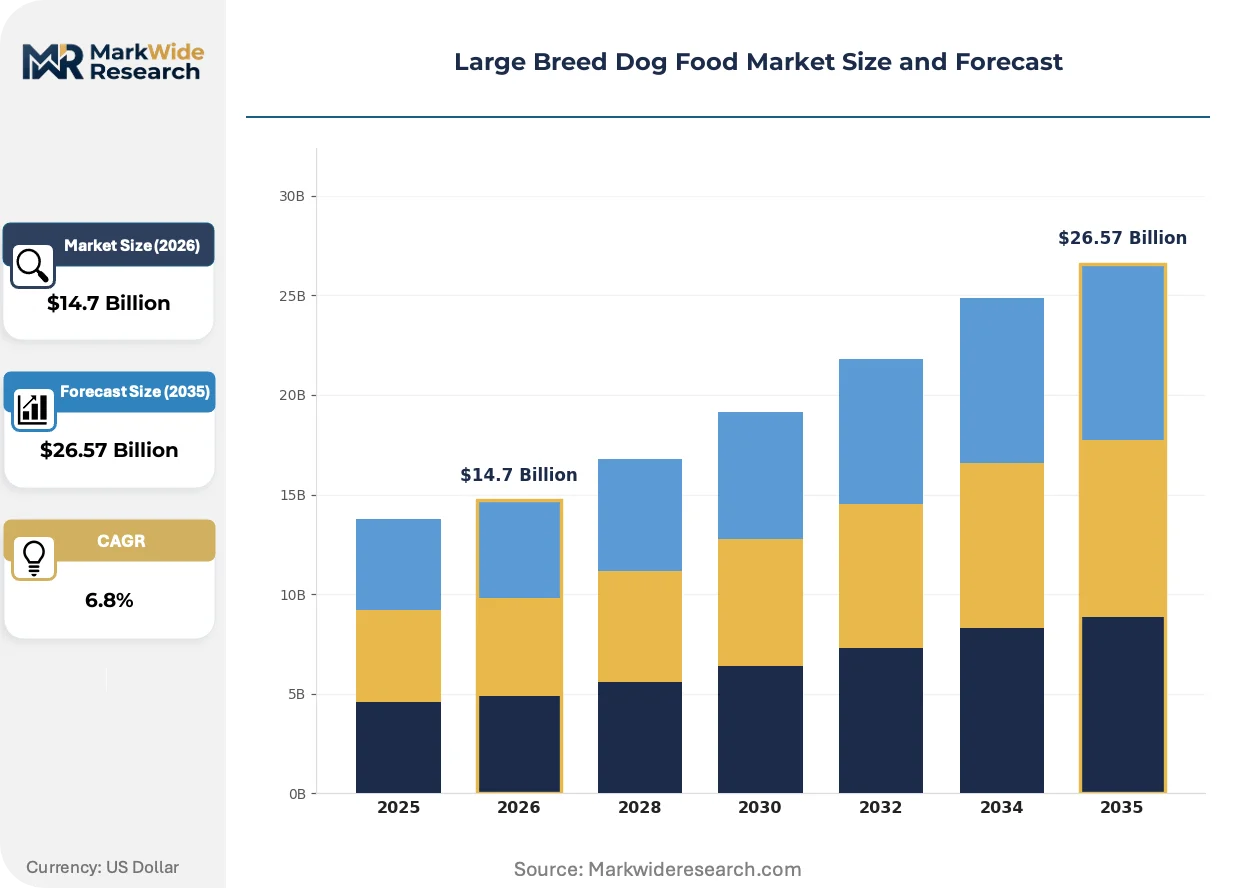
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $26.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Kibble, Wet Food, Freeze-Dried, Raw Diet Ingredient Type: Meat-Based, Grain-Free, Organic, Functional Ingredients Distribution Channel: Online Retail, Pet Specialty Stores, Supermarkets, Direct Sales Brand Type: Premium Brands, Private Label, Natural Brands, Others |
| Companies Covered | Mars Incorporated, Nestlé Purina PetCare, Hill’s Pet Nutrition, The J.M. Smucker Company, General Mills, Colgate-Palmolive, Blue Buffalo, Diamond Pet Foods, Royal Canin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Large Breed Dog Food Market Shifts & Advancements
Cold-processing technologies and marine-derived functional ingredients are redrawing formulation boundaries, while regulatory tightening around growth-stage nutrition redefines competitive compliance costs.
High-pressure processing is supplanting conventional extrusion for raw-coated kibble applications, preserving enzyme activity and probiotic viability that thermal methods destroy. Premium pet specialty retailers are expanding refrigerated case space for these SKUs at 3-4x the rate of conventional dry food facings. The technology is compressing shelf-life expectations and forcing logistics partnerships with cold-chain operators previously outside pet food supply networks.
EU F-Gas Regulation phase-down schedules are accelerating refrigerant transitions in freeze-drying operations, raising energy costs for European manufacturing facilities processing raw nutrition products. Irish and Dutch production sites face the steepest compliance timelines, with facility retrofits consuming 18-24 month capital deployment cycles. Manufacturers are responding by consolidating freeze-dried capacity in non-EU jurisdictions with less stringent fluorinated gas restrictions.
Subscription-based auto-replenishment is displacing periodic bulk purchasing among large breed owners managing chronic conditions requiring therapeutic diet consistency. Veterinary clinics are white-labeling these programs to capture recurring revenue and improve patient compliance tracking. The United States exhibits the highest penetration, with specialty retailers launching proprietary platforms to retain customers bypassing brick-and-mortar replenishment cycles.
Large Breed Dog Food Market Segmentation
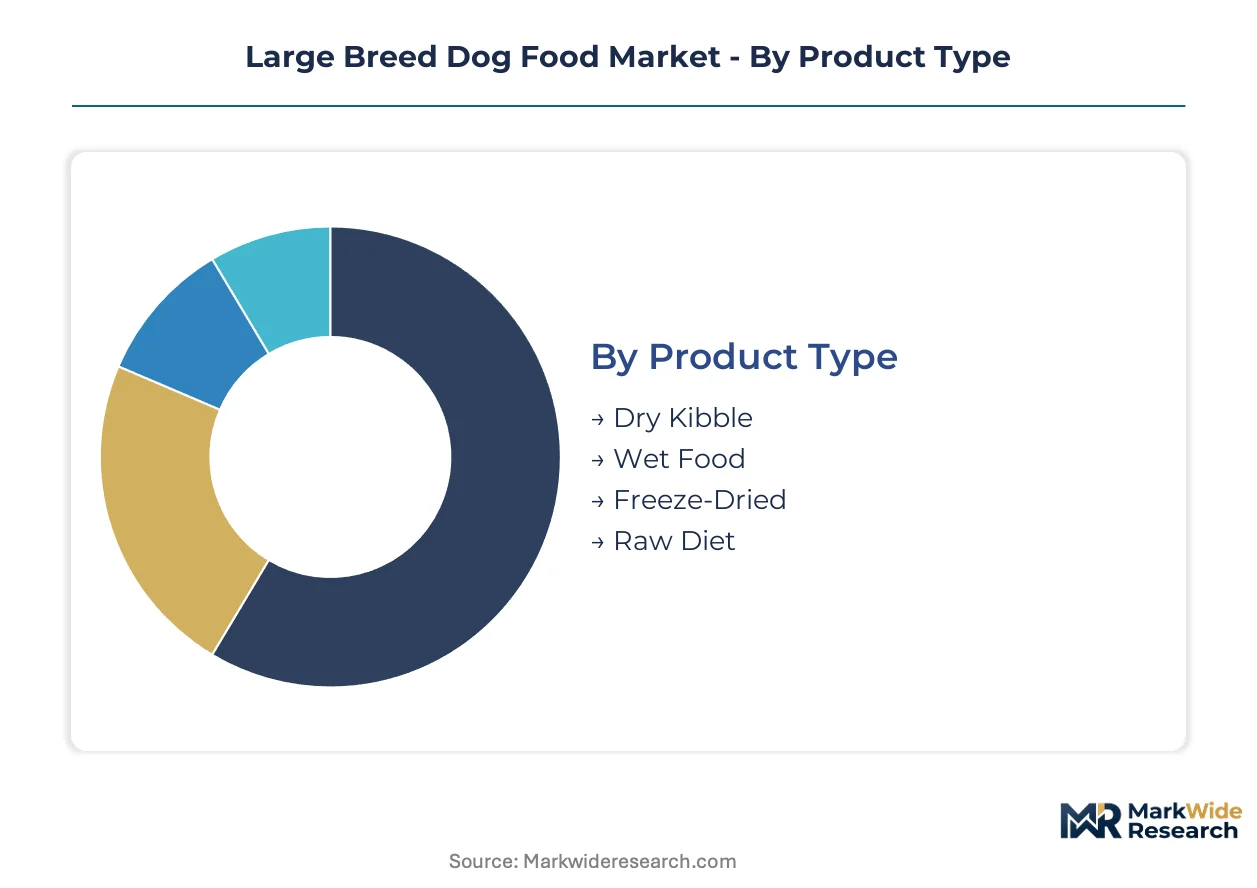
Large breed dog food segmentation reflects divergent owner priorities across convenience, clinical efficacy, and ingredient philosophy. Manufacturers must align formulation investments with channel-specific margin structures and veterinary endorsement pathways.
Product Type:
Freeze-dried and raw alternatives exert substitution pressure on conventional formats as owners prioritize minimal processing claims and probiotic preservation.
- Dry Kibble:Extrusion-conditioned formulations achieve shelf stability through precise thermal profiles that balance pathogen elimination against chondroprotective compound degradation. Demand concentrates in United States pet specialty retailers where bulk purchasing and auto-replenishment programs sustain volume throughput despite margin compression.
- Freeze-Dried:Sublimation dehydration preserves raw nutritional integrity while eliminating refrigeration requirements, capturing premium positioning through HPP-treated coatings. Growth accelerates fastest in urban United States markets where apartment-dwelling large breed owners prioritize storage convenience alongside processing minimalism.
- Wet Food:Retort-pouched formulations deliver moisture enrichment for giant breeds with renal sensitivity or hydration challenges.
- Raw Diet:Commercial frozen or refrigerated preparations compete with home-prepared alternatives through pathogen-tested sourcing and AAFCO nutritional adequacy verification.
Dry kibble retains volume leadership; freeze-dried holds the steepest expansion curve.
Ingredient Type:
Cost tier stratification separates commodity protein formulations from clinically positioned functional variants commanding veterinary channel premiums.
- Functional Ingredients:Glucosamine, omega-3 fatty acids, and green-lipped mussel extract target developmental orthopedic disease prevention in susceptible giant breeds. United States veterinary clinics drive prescription authorization for these formulations as AAFCO calcium ceilings harden around growth-stage nutrition protocols.
- Meat-Based:Rendering-grade poultry meal and fishmeal supply protein density calibrated for lean muscle maintenance in large working breeds. Supply volatility in commodity animal proteins constrains margin stability for mid-tier producers lacking backward integration into rendering operations.
- Grain-Free:Legume and tuber carbohydrate substitutes address owner concerns around gluten sensitivity despite FDA investigations into dilated cardiomyopathy correlations.
- Organic:USDA-certified ingredient sourcing satisfies owner preference for pesticide-free supply chains with limited clinical differentiation.
Meat-based formulations retain volume leadership; functional ingredients hold the steepest expansion curve.
Distribution Channel:
Channel profitability varies sharply across veterinary authorization requirements, cold-chain infrastructure, and customer acquisition economics.
- Pet Specialty Stores:Breed-specific planogram segmentation and in-store nutrition counseling deepen basket penetration among first-time large breed adopters. United States chains expand refrigerated case space for HPP-treated and freeze-dried SKUs at multiples of conventional dry food facings.
- Online Retail:Subscription auto-replenishment displaces periodic bulk purchasing for therapeutic diet consistency in chronic condition management. Logistics partnerships with cold-chain operators extend reach for refrigerated raw formulations previously confined to brick-and-mortar.
- Supermarkets:Mass-market placement captures price-sensitive volume through standard kibble assortments with limited functional ingredient positioning.
- Direct Sales:Veterinary clinic white-label programs capture recurring revenue and improve patient compliance tracking through prescriptive authorization.
Pet specialty stores retain volume leadership; online retail holds the steepest expansion curve.
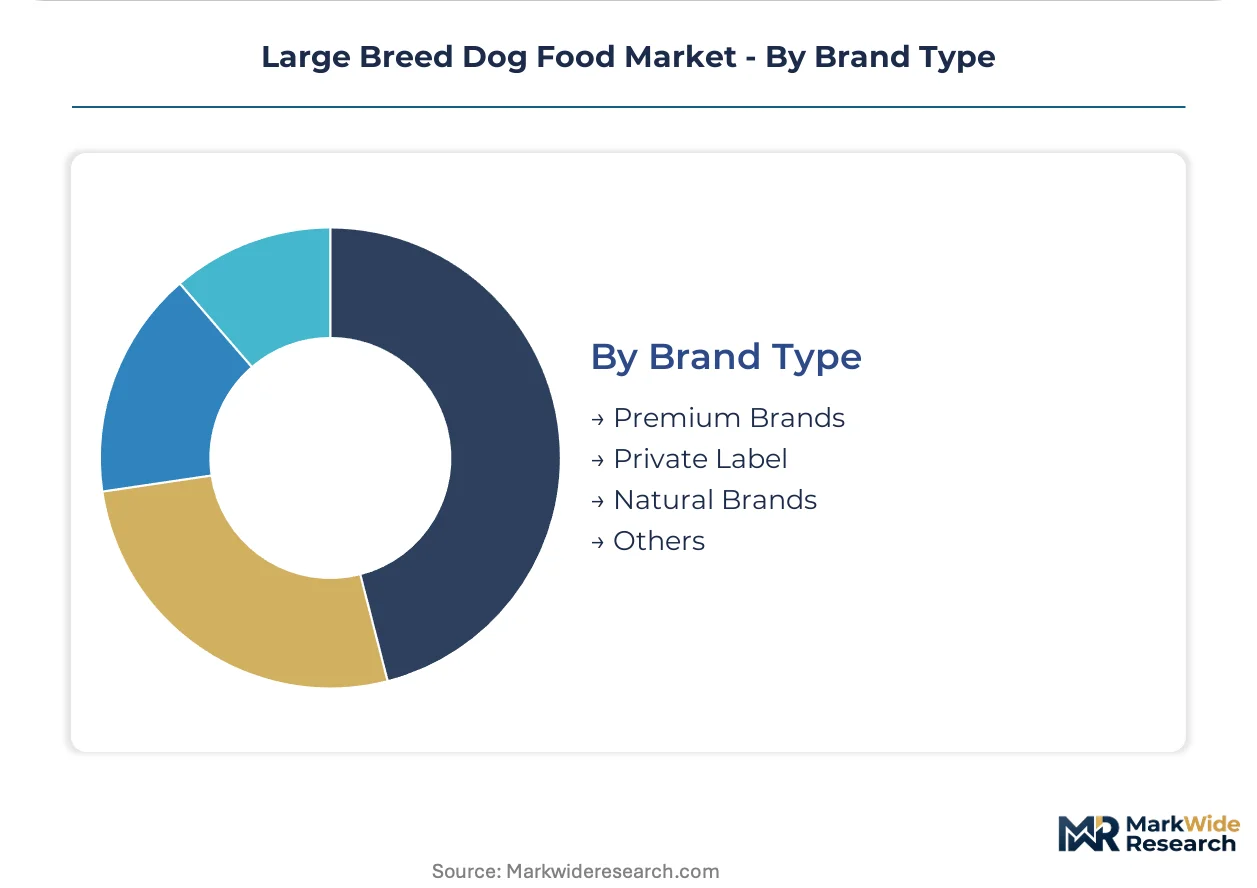
Brand Type:
Margin structure separates clinically validated premium positioning from private label alternatives competing on shelf price.
- Premium Brands:AAFCO-compliant feeding trials and veterinary hospital network distribution sustain price positioning through clinical credibility. Mars Incorporated and Nestlé Purina PetCare anchor this tier through prescription authorization pathways and breed-specific line extensions.
- Natural Brands:Clean-label positioning emphasizes ingredient traceability and processing transparency without therapeutic diet claims that trigger FDA Center for Veterinary Medicine oversight.
- Private Label:Contract manufacturing arrangements enable retailer margin capture through comparable formulations at reduced marketing overhead.
- Others:Regional and emerging entrants compete through novel protein sources or limited-ingredient positioning for allergy-prone breeds.
Premium brands retain volume leadership; natural brands hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows concentrate in North American and European manufacturing clusters serving import-dependent markets across Asia-Pacific and Latin America. Veterinary channel density and cold-chain infrastructure determine regional value capture.
United States
Therapeutic diet authorization through FDA Center for Veterinary Medicine protocols drives prescription large breed formulations. Mars Incorporated and Nestlé Purina PetCare anchor production in Missouri and Iowa manufacturing corridors. Pet specialty retailers in California and Texas expand refrigerated case space for HPP-treated SKUs.
Germany
Freeze-dried capacity consolidates here despite EU F-Gas Regulation phase-down schedules raising energy costs. EFSA nutrient profile guidelines inform AAFCO-aligned export formulations. Dutch and Irish facilities face steeper compliance timelines, shifting investment toward German extrusion conditioning infrastructure.
China
Domestic large breed ownership expands in tier-one cities where per-pet spending converges with Western levels. SAMR feed safety standards tighten import requirements for American and European therapeutic formulations. Yangtze River Delta manufacturing clusters develop contract production for premium private label export.
Brazil
Rendering-grade poultry meal supply supports regional kibble production cost advantages. ANVISA veterinary product registration creates compliance friction for imported prescription diets. São Paulo pet specialty chains expand breed-specific planogram segmentation targeting first-time large breed adopters.
United Kingdom
Post-Brexit regulatory divergence from EU F-Gas schedules enables freeze-dried manufacturing retention. FSA feed hygiene regulations govern interstate commerce with Northern Ireland. London and Southeast England veterinary clinics white-label subscription auto-replenishment programs for therapeutic diet compliance.
Large Breed Dog Food Market Competitive Landscape
Concentration sits with diversified consumer packaged goods conglomerates possessing veterinary hospital networks and prescription authorization pathways. Three archetypes define competitive structure: vertically integrated nutrition-science specialists, mass-market brand licensors, and contract manufacturing-dependent private label suppliers. Dominant moves include M&A to capture veterinary channel access and capacity expansion into HPP-treated and freeze-dried segments.
Within the nutrition-science specialist tier, Mars Incorporated, Nestlé Purina PetCare, and Hill's Pet Nutrition represent the clinical credibility archetype. Mars anchors position through veterinary hospital network distribution. Nestlé Purina occupies the breed-specific formulation vector. Hill's exemplifies controlled-growth protocol leadership. These three conglomerates sit within a tier where AAFCO-compliant feeding trials and prescription authorization sustain price positioning inaccessible to commodity competitors.
| Leading Market Players |
|---|
| Mars Incorporated |
| Nestlé Purina PetCare |
| Hill's Pet Nutrition |
| The J.M. Smucker Company |
| General Mills |
| Colgate-Palmolive |
| Blue Buffalo |
| Diamond Pet Foods |
| Royal Canin |
| Others |
Supply & Pricing Matrix
Ninety-day raw material lead times for rendering-grade poultry meal and fishmeal concentrate pricing power with backward-integrated conglomerates while fragmenting margin stability for contract manufacturers dependent on spot-market protein sourcing. This inventory exposure cascades through formulation costs and channel markups, compressing mid-tier producers between commodity input volatility and veterinary channel price ceilings.
Pricing Analysis
Pet specialty retailers anchor a three-tier pricing structure across premium, standard, and economy levels, with AAFCO-compliant therapeutic formulations commanding veterinary channel premiums against mass-market kibble. Price differentiation rests on clinical validation depth and cold-chain infrastructure investment, with freeze-dried segments capturing margin pools inaccessible to conventional extrusion manufacturers. Pricing pressure stems from freeze-dried substitution as urban owners prioritize minimal processing claims, eroding kibble price premiums. Mass-market supermarket buyers exhibit highest price sensitivity; veterinary-authorized prescription purchasers show lowest sensitivity due to compliance requirements.
Supply Chain Analysis
Strategic stockpiling of marine-derived functional ingredients dominates inventory strategy as green-lipped mussel extract and omega-3 fatty acid suppliers face seasonal harvest constraints and quality variability. Geographic supply concentration centers on United States rendering corridors, German extrusion conditioning infrastructure, and Chinese contract manufacturing clusters developing private label export capacity. Raw material dependencies include rendering-grade poultry meal, fishmeal, and novel marine bioactives. Single-source vulnerability in freeze-drying equipment supply creates capex bottlenecks for capacity expansion. Distribution runs through veterinary clinic networks, pet specialty retail chains, and cold-chain logistics partnerships for refrigerated raw formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives against minimally processed freeze-dried and raw nutrition alternatives capturing margin pools and veterinary endorsement trajectories previously reserved for extruded kibble formulations.
For Market Incumbents: Fortify veterinary channel control through prescription authorization pathway exclusivity and captive supply of green-lipped mussel extract to secure functional ingredient differentiation. Expand HPP-treated capacity in Missouri and Iowa manufacturing corridors to capture premium positioning without full freeze-dried capex exposure. Freeze-dried entrants threaten kibble volume leadership; backward integration into rendering operations insulates against protein input volatility.
For New Entrants and Emerging Players: Differentiate on marine bioactive convergence by pairing omega-3 fatty acids with novel chondroprotective extracts for proactive musculoskeletal support positioning. Target urban United States apartment-dwelling large breed owners through subscription auto-replenishment platforms bypassing brick-and-mortar shelf competition. Direct-to-veterinary white-label programs offer lowest channel friction for therapeutic diet authorization.
For Investors and Strategic Acquirers: Carve-out targets emerge from consumer packaged goods conglomerates divesting non-core pet nutrition assets lacking veterinary hospital network integration. Long-term viability favors manufacturers with AAFCO-compliant feeding trial infrastructure and cold-chain logistics partnerships spanning the projection horizon. Acquisition focus: mid-tier producers with freeze-dried capacity stranded by EU F-Gas compliance costs. Signal to monitor: SAMR feed safety standard tightening velocity in China as import barrier escalation indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Veterinary Channel Expansion | Prescription authorization through licensed practitioners unlocks recurring revenue insulated from retail price competition. |
| Freeze-Dried Capacity Addition | Sublimation dehydration infrastructure captures urban owner demand for minimal processing claims and storage convenience. |
| Functional Ingredient Integration | Green-lipped mussel extract and omega-3 pairing creates differentiated musculoskeletal support positioning for giant breeds. |
| Cold-Chain Logistics Partnership | HPP-treated and refrigerated raw distribution extends reach beyond brick-and-mortar pet specialty retail footprints. |
| Subscription Platform Development | Auto-replenishment programs improve therapeutic diet compliance tracking and capture recurring revenue from chronic condition management. |
Research Methodology
A standing panel of veterinary nutritionists, pet specialty retail category managers, contract manufacturing procurement leads, and FDA Center for Veterinary Medicine regulatory affairs specialists provided ongoing calibration against secondary validation through AAFCO nutrient profile databases, FDA feeding guideline publications, USDA organic certification records, and customs trade flow data. Primary interviews with formulation scientists and extrusion equipment engineers combined with bottom-up production capacity assessments and top-down expenditure flow analysis to triangulate market sizing.
Consistency checks against veterinary channel shipment data and pet specialty retail scanner databases validated volume and value outputs across the analysis window. Segmentation modeling incorporated product format, ingredient philosophy, distribution channel authorization requirements, and regional regulatory cluster variations. CAGRs were derived from weighted average growth assumptions calibrated to historical therapeutic diet penetration patterns and freeze-dried substitution elasticities. Forecast inputs included large breed ownership demographic projections, per-pet therapeutic diet spending trajectories, and extrusion line capacity deployment announcements.
Forecasts assume regulatory continuity in FDA Center for Veterinary Medicine oversight and AAFCO nutrient profile enforcement; material policy shifts would require re-modeling of prescription authorization economics and commercial feeding trial compliance costs. Revision becomes warranted when SAMR feed safety standard implementation crosses thresholds that structurally alter import access for American and European therapeutic formulations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Pet Car Seat Market
Pet Care Products
UK Pet Boarding Market
Pet Care Products
Australia Pet Food Market
Pet Care Products
Asia Pacific Dog Food Market
Pet Care Products
Cat Mat Market
Pet Care Products
Pet Meal Kit Delivery Services Market
Pet Care Products
Pet Hair Care Market
Pet Care Products
Pet Collar Market
Pet Care Products
Dog Vitamins Market
Pet Care Products
Pet Odor Absorber Market
Pet Care Products
Dog Pen Market
Pet Care Products
High Protein Dog Food Market
Pet Care Products
Dog Sunglasses Market
Pet Care Products
Spain Pet Food Market
Pet Care Products
Dog Hats Market
Pet Care Products
Pet Gadgets Market