
 Spain Pet Boarding Market | 2026-2036
Spain Pet Boarding Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Pet Boarding Market Insights
Subscription-based wellness packages is expanding the revenue model beyond per-night stays toward recurring monthly contracts. Posh Pets Spain leverages its premium facility network to sustain higher-margin grooming add-ons. DogBuddy competes through a digital-first platform that anchors customer retention via app-based booking and real-time photo updates. Eurodog differentiates by specializing in breed-specific exercise protocols across its Madrid and Barcelona locations.
Spain pet boarding encompasses commercial temporary care facilities providing supervised housing, feeding, exercise, and veterinary oversight for companion animals during owner absence, with operational parameters typically including climate-controlled kennel environments averaging 2–4 square meters per large dog and mandatory vaccination verification. The primary commercial purpose centers on enabling urban household labor participation while ensuring animal welfare compliance. Overnight boarding occupies the dominant revenue position due to extended-stay pricing multiples, while daycare represents the fastest-expanding segment driven by remote-work hybrid schedules. Home-based facilities capture concentrated margin pools through lower fixed-cost structures and personalized service premiums.
Spain's Ley de Protección de los Animales de Compañía and regional ordinances enforced by autonomous community veterinary services mandate facility licensing, staff ratios, and space requirements that elevate operational barriers for new entrants. Municipal zoning regulations in cities such as Madrid, Barcelona, and Valencia restrict commercial kennel placement to designated industrial or peripheral zones, constraining supply expansion in premium neighborhoods. Stakeholders must monitor evolving autonomous community welfare enforcement intensity and assess whether home-based operator registration thresholds will tighten or relax.
Market Dynamics
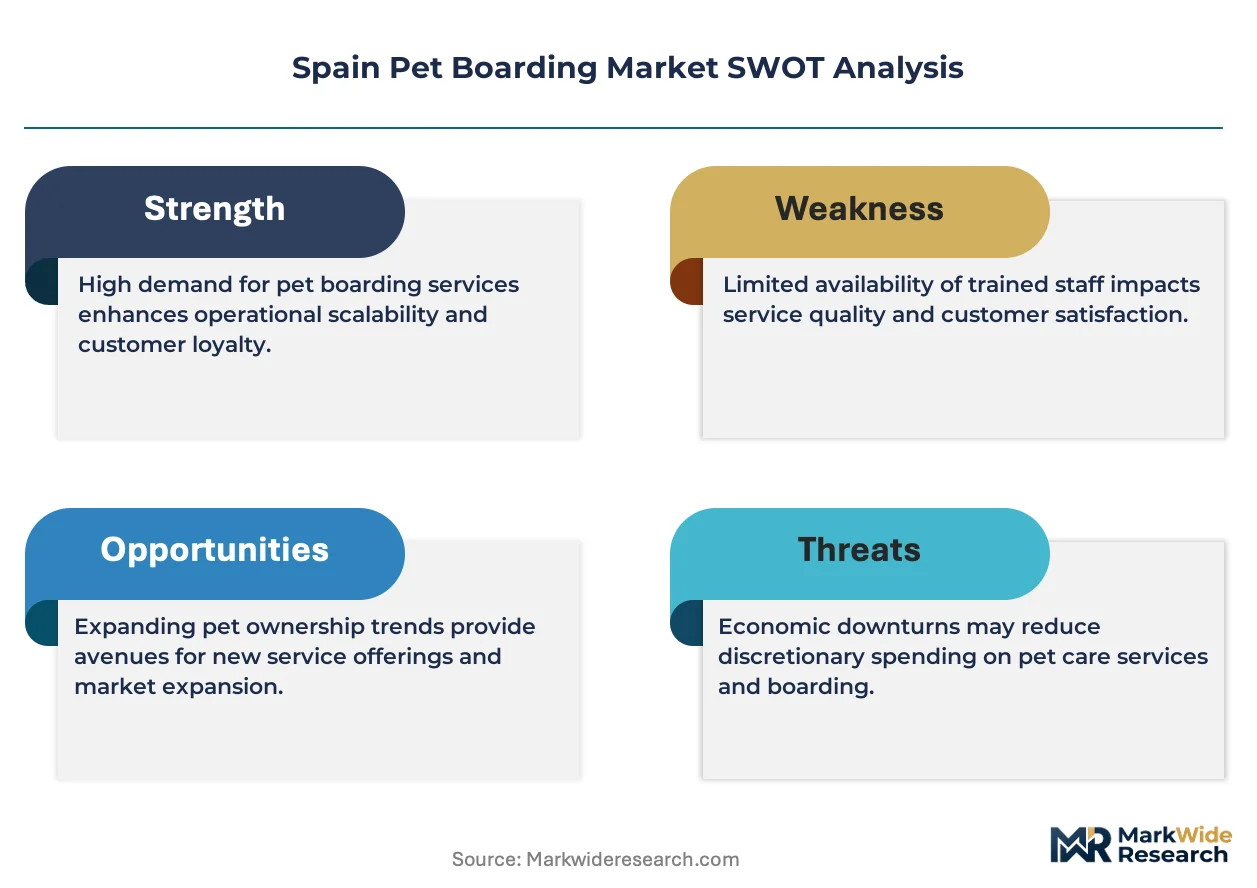
Spain's Ley de Protección de los Animales de Compañía is compressing operational margins for unlicensed operators while accelerating consolidation among compliant chains. Madrid and Barcelona municipal zoning further constrains greenfield facility placement in premium neighborhoods.
Growth Catalysts
- Hybrid work normalization:Barcelona and Madrid professionals now split weeks between home and office, generating predictable midweek daycare demand that smooths revenue seasonality.
- Regional welfare enforcement:Andalusia's tightened veterinary inspection protocols are disqualifying informal home-based operators, redirecting volume toward licensed commercial facilities.
- IoT-enabled monitoring:Climate sensors and live video feeds are converging with traditional boarding to justify premium pricing tiers in Catalonia's competitive urban corridors.
Market Restraints
- Input cost volatility:Commercial pet food and pharmaceutical supplies face price pressure from euro-denominated import exposure, squeezing facility margins.
- Zoning supply concentration:Madrid's industrial-peripheral kennel placement restrictions limit supply response in high-income districts where demand concentrates.
- Substitution threat:Professional pet-sitting platforms and neighbor-based care networks capture price-sensitive owners seeking home-environment alternatives.
Strategic Opportunities
- Underpenetrated secondary cities:Valencia and Seville exhibit licensed facility shortages relative to pet ownership density, creating first-mover expansion corridors.
- Veterinary integration:Co-located wellness clinics and boarding operations capture recurring revenue streams beyond episodic stays.
- Subscription model innovation:Monthly daycare packages are displacing per-day transactions, improving cash flow predictability and customer lock-in.
Industry Challenges
- Certified veterinary nurse scarcity:Regional licensing requirements exceed qualified labor supply in Catalonia and Andalusia, extending hiring timelines.
- Facility capex intensity:Climate-controlled kennel construction and soundproofing standards demand substantial upfront investment before revenue generation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Pet Boarding Market |
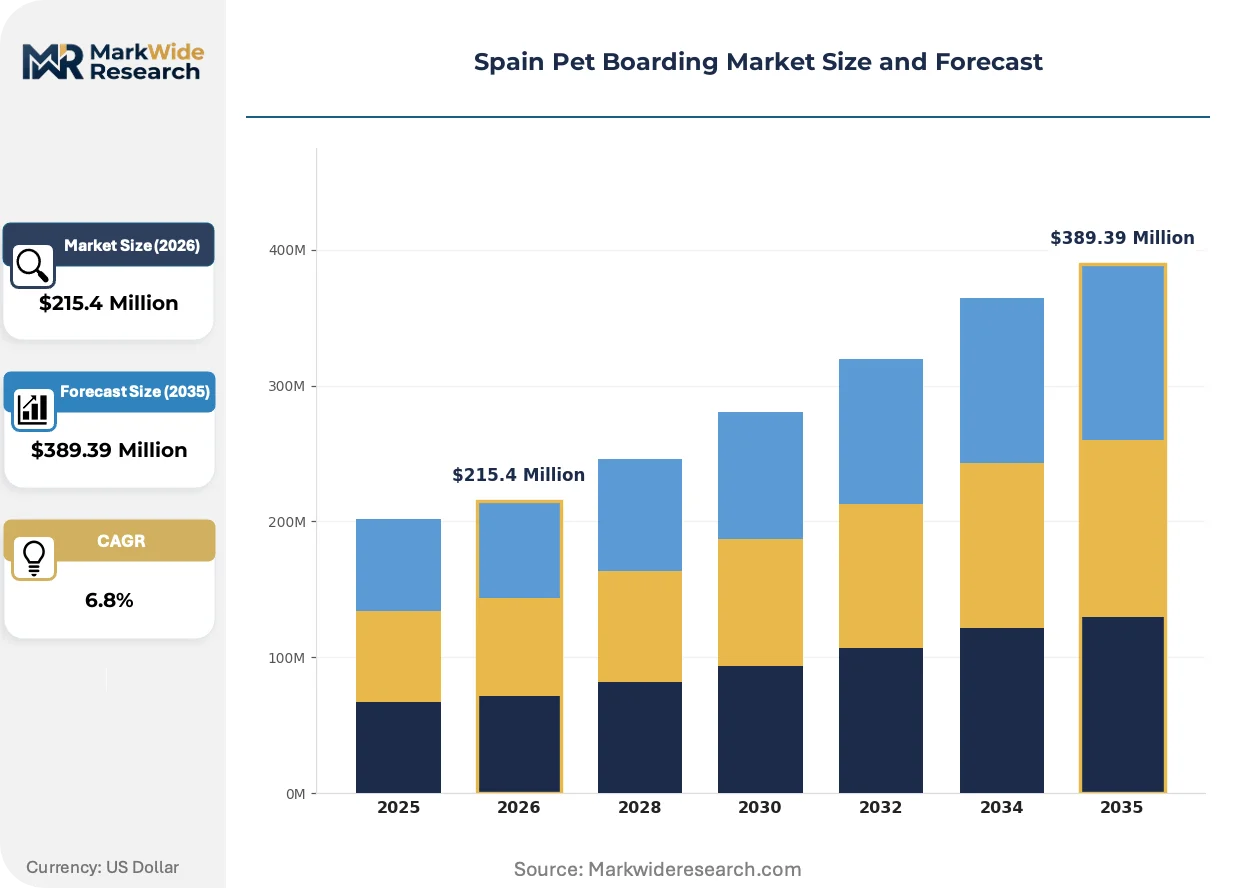
| Market Size in 2026 | $215.4 Million |
| Market Size in 2035 | $389.39 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Overnight Boarding, Daycare, Grooming, Training Animal Type: Dogs, Cats, Birds, Exotic Pets Facility Type: Luxury Boarding, Standard Boarding, Home-based, Kennels Customer Type: Pet Owners, Breeders, Shelters, Rescue Organizations |
| Companies Covered | Rover, American Pet Resort, Posh Pets Spain, Paradise 4 Paws, Airpets International, Eurodog, Dogtopia Enterprises, DogBuddy, Wag Group Co, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Pet Boarding Market Trends and Innovations
Digital service layers are restructuring how Spanish pet owners evaluate and purchase temporary animal care. Technology deployment now separates premium operators from commodity competitors.
Biometric pet identification systems using nose-print recognition and embedded microchip scanners are converging with check-in protocols to eliminate paperwork friction. Madrid's luxury boarding chains deploy these tools to accelerate intake processing and reduce staffing ratios during peak holiday periods. The technology is converging with mobile app architectures to enable fully automated self-service drop-off in suburban Barcelona locations.
Spain's autonomous communities are harmonizing facility inspection standards under the national animal welfare framework, reducing regulatory arbitrage between regions. Catalonia's veterinary services now coordinate with Andalusian counterparts on cross-border operator blacklisting. Small home-based providers in Valencia face accelerated compliance timelines as regional enforcement intensity aligns with Madrid's stricter precedent.
Pet owners now demand real-time visual confirmation of animal welfare during separation periods, displacing traditional end-of-day summary reports. Premium facilities deploy dedicated photography staff and AI-curated highlight reels to satisfy this expectation. This behavioral shift is most visible among dual-income households in Barcelona's Eixample and Madrid's Salamanca districts, where hourly photo updates command 15-20% pricing premiums over standard service tiers.
Spain Pet Boarding Market Segmentation
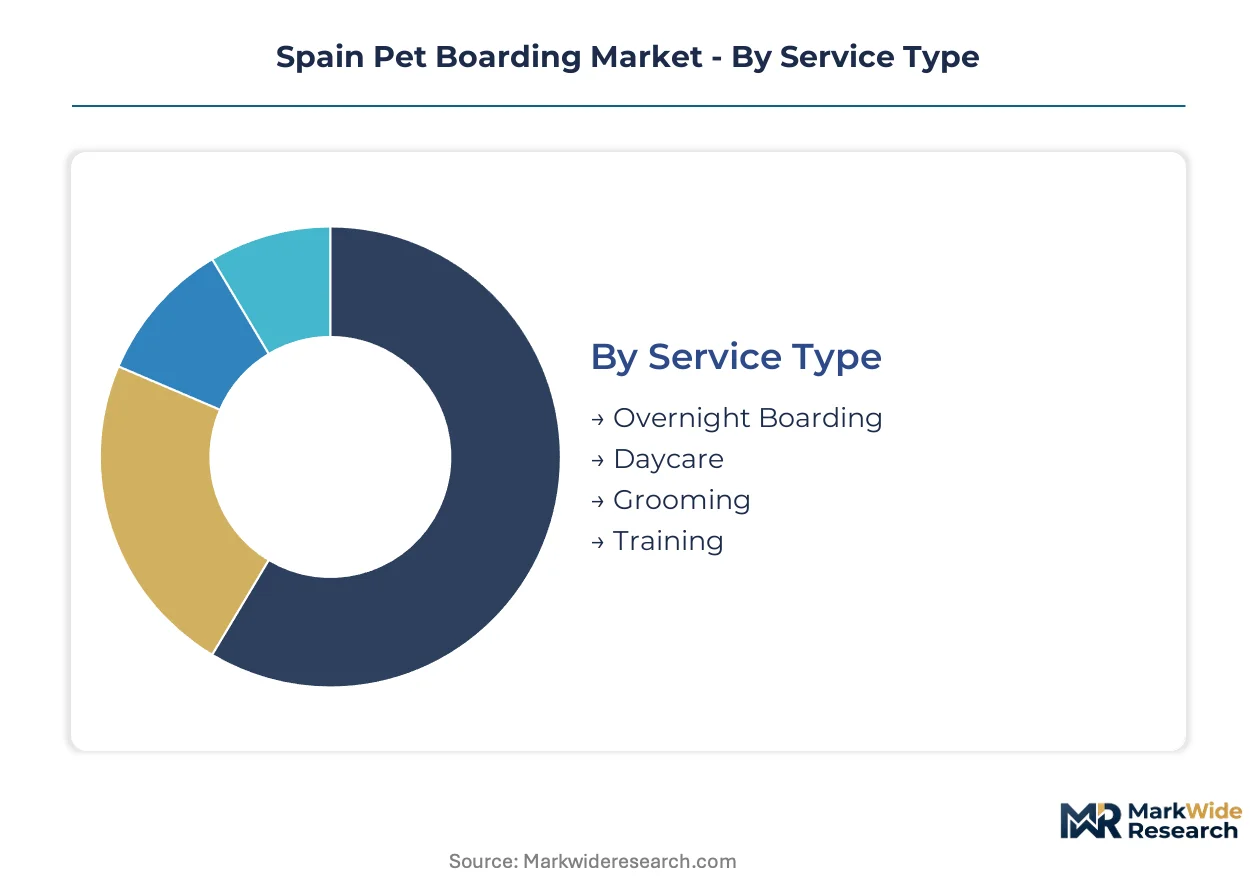
Spain's pet boarding market fragments across service intensity, animal physiology, facility capital requirements, and customer procurement patterns. Each dimension carries distinct regulatory footprints under the Ley de Protección de los Animales de Compañía and autonomous community enforcement protocols.
Service Type:
Overnight boarding demands full veterinary certification and climate-controlled infrastructure under Madrid and Barcelona municipal codes. Daycare operates under lighter staffing ratios but requires real-time monitoring compliance in Catalonia.
- Overnight Boarding:Extended-stay facilities averaging 2–4 square meters per large dog with mandatory vaccination verification and 24-hour veterinary oversight. Revenue concentrates in Barcelona's Eixample and Madrid's Salamanca districts where dual-income households absorb premium pricing multiples for holiday periods.
- Daycare:Supervised daytime housing with exercise protocols and socialization management. Hybrid work normalization in Madrid and Barcelona generates predictable midweek demand that smooths seasonal revenue volatility for compliant operators.
- Grooming:Hygiene and aesthetic services bundled with boarding stays or offered standalone. Catalonia's veterinary services mandate parasite screening before salon admission.
- Training:Behavioral modification and obedience programs integrated with extended boarding packages. Andalusia requires certified canine educator credentials for commercial operators.
Overnight boarding sits at the top of the volume ranking, with daycare climbing the fastest.
Animal Type:
Facility design and staffing expertise diverge sharply across species physiology and regulatory risk profiles. Spain's welfare law mandates species-specific housing temperatures and isolation protocols.
- Dogs:Dominant revenue source requiring breed-specific exercise areas and noise mitigation infrastructure. Large-breed kennel construction in Madrid's industrial zones absorbs disproportionate capex before licensing approval.
- Cats:Feline-only facilities command premium isolation from canine stressors with vertical climbing structures and separate HVAC systems. Home-based operators in Valencia capture concentrated margin pools through lower fixed-cost structures.
- Birds:Avian boarding demands specialized ventilation and quarantine protocols for psittacosis prevention. Limited licensed supply concentrates in Barcelona metropolitan area.
- Exotic Pets:Reptile, small mammal, and amphibian housing requires precise humidity and temperature control. Regional veterinary inspection intensity varies, creating compliance arbitrage between Andalusia and Madrid.
Dogs anchor absolute revenue volume, though exotic pet boarding gains share fastest among urban professionals seeking differentiated service portfolios.
Facility Type:
Capital intensity and zoning accessibility stratify competitive positioning across Madrid, Barcelona, and secondary cities. Municipal regulations constrain greenfield placement while rewarding operational compliance.
- Luxury Boarding:Premium facilities with private suites, webcam access, and concierge services. Posh Pets Spain leverages this tier to sustain higher-margin grooming add-ons through subscription-based wellness packages.
- Standard Boarding:Mid-market kennel operations with shared runs and basic veterinary oversight. Eurodog specializes in breed-specific exercise protocols across Madrid and Barcelona locations within this tier.
- Home-based:Residential operators with lower fixed-cost structures and personalized service premiums. Andalusia's tightened veterinary inspection protocols are disqualifying informal providers, redirecting volume toward licensed commercial alternatives.
- Kennels:Traditional high-density housing with industrial zoning compliance. Madrid's peripheral placement restrictions limit supply response in high-income districts where demand concentrates.
Standard boarding maintains volume leadership, while home-based services face compression from regional enforcement harmonization.
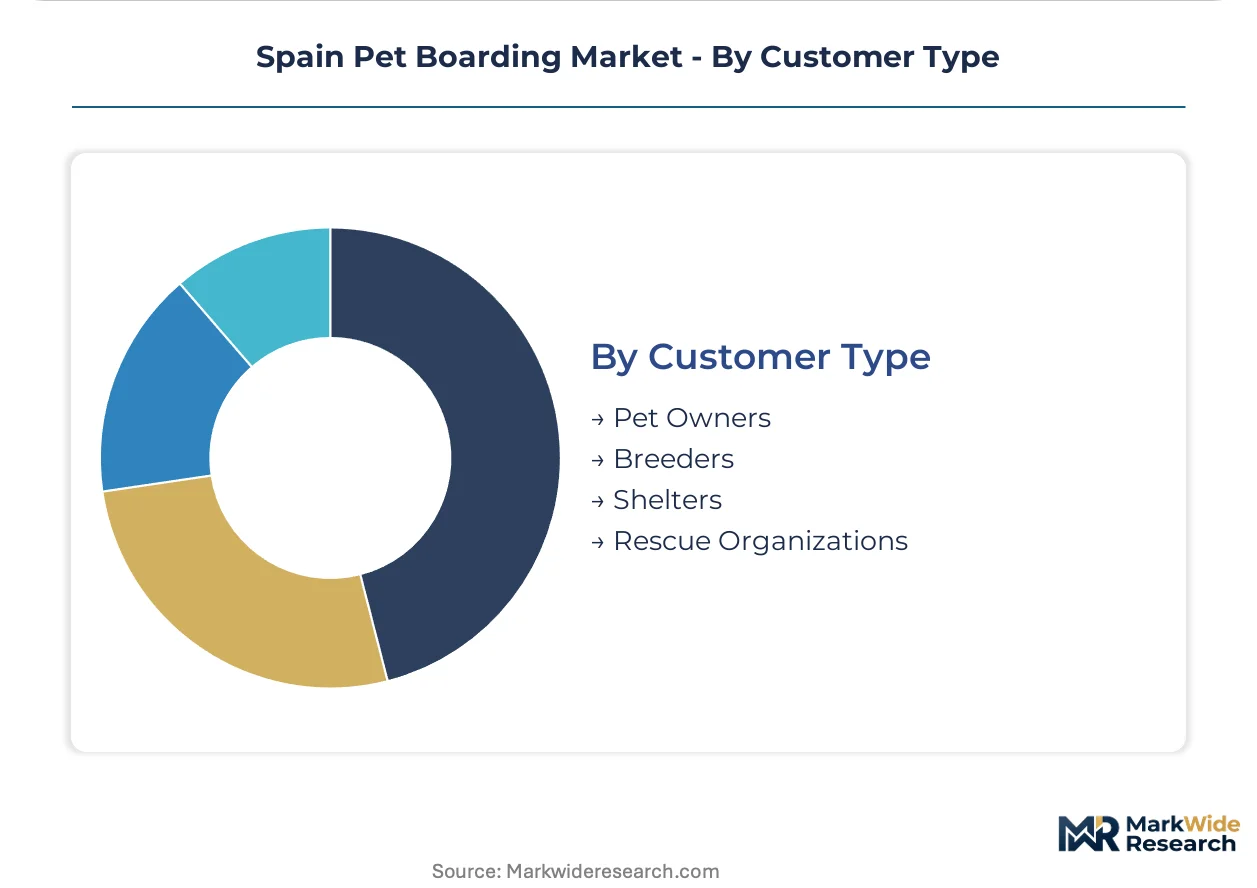
Customer Type:
Procurement patterns and price sensitivity diverge across individual owners versus institutional volume buyers. Contract structures range from episodic transactions to recurring monthly agreements.
- Pet Owners:Individual households seeking temporary care during travel or work commitments. Barcelona and Madrid professionals now split weeks between home and office, generating predictable demand patterns.
- Breeders:Commercial breeding operations requiring quarantine facilities and whelping services. Certification requirements exceed standard boarding thresholds under national welfare frameworks.
- Shelters:Municipal and private overflow housing with volume-based pricing and extended-stay discounts. Valencia and Seville exhibit licensed facility shortages relative to intake density.
- Rescue Organizations:Non-profit operators with veterinary integration needs and grant-dependent procurement. Co-located wellness clinics capture recurring revenue streams beyond episodic stays.
Pet owners dominate transaction volume, with rescue organizations expanding procurement fastest through veterinary partnership models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's pet boarding sector operates under stricter municipal zoning than Spain, while France exhibits comparable welfare enforcement intensity. Both markets inform competitive positioning strategies for Spanish operators seeking cross-border expansion.
Madrid
Madrid's dual-income households in Salamanca and Chamberí districts generate concentrated demand for premium overnight boarding. The city's municipal veterinary services enforce Ley de Protección de los Animales de Compañía licensing with particular rigor in central districts. Industrial-peripheral zoning restrictions limit new facility placement, compressing supply response in high-revenue neighborhoods.
Catalonia
Barcelona's Eixample and Gràcia neighborhoods exhibit the densest daycare penetration in Spain, driven by hybrid work normalization among professionals. Catalonia's autonomous veterinary services coordinate cross-border operator blacklisting with Andalusia, tightening compliance timelines for home-based providers. IoT-enabled facilities with live video feeds command pricing premiums in this competitive urban corridor.
Andalusia
Seville and Málaga demonstrate licensed facility shortages relative to pet ownership density, creating first-mover expansion opportunities. Andalusia's tightened veterinary inspection protocols are disqualifying informal home-based operators, redirecting volume toward compliant commercial chains. Coastal tourism corridors generate seasonal demand spikes that strain existing capacity.
Valencia
Valencia's home-based operators face accelerated compliance timelines as regional enforcement intensity aligns with Madrid's stricter precedent. The metropolitan area exhibits growing rescue organization procurement through veterinary partnership models. Municipal zoning in peripheral districts offers more flexible greenfield placement than Madrid or Barcelona.
Basque Country
Bilbao and San Sebastián display lower commercial kennel density relative to household pet ownership rates. Basque autonomous community welfare enforcement maintains consistency with national frameworks without additional regional layering. Industrial conversion opportunities in former manufacturing zones provide alternative facility locations.
Spain Pet Boarding Market Competitive Landscape
Top-tier vendors anchor premium facility networks, while mid-market chains compete on breed specialization and digital service layers. The vendor base stratifies across three tiers: luxury boarding with concierge services, standard kennel operations with veterinary integration, and home-based providers facing regulatory compression. Two dominant competitive moves are reshaping positioning: subscription-based wellness packages displacing per-night transactions, and IoT-enabled monitoring justifying premium pricing tiers.
Among Spain-based operators, Posh Pets Spain occupies the luxury tier through premium facility networks, while Eurodog exemplifies breed-specific specialization across Madrid and Barcelona locations. DogBuddy represents the digital-first archetype, anchoring customer retention via app-based booking architectures. These three companies illustrate how service intensity, animal expertise, and technology deployment define competitive differentiation in this market.
| Leading Market Players |
|---|
| Rover |
| American Pet Resort |
| Posh Pets Spain |
| Paradise 4 Paws |
| Airpets International |
| Eurodog |
| Dogtopia Enterprises |
| DogBuddy |
| Wag Group Co |
| Others |
Pricing and Supply Chain Analysis
Dual-income households in Barcelona's Eixample and Madrid's Salamanca districts concentrate demand for premium overnight boarding, anchoring a subscription-heavy pricing model that rewards compliant operators with predictable recurring revenue streams.
Pricing Analysis
Capacity additions in Valencia and Seville are reshaping price floors for standard boarding tiers while Madrid and Barcelona operators defend premium positioning through IoT-enabled monitoring bundles. Three-tier pricing structure across premium, standard, and economy levels differentiates facilities by veterinary integration depth and real-time update frequency. Cost compression in economy tiers intensifies because informal home-based operators face disqualification under Andalusia's tightened inspection protocols. Price-sensitive individual pet owners in secondary cities drive transactional per-night demand, while least-sensitive dual-income professionals absorb 15-20% premiums for concierge-tier services.
Supply Chain Analysis
Regional distribution centers in Madrid and Barcelona operate hub-and-spoke patterns radiating to secondary cities, with veterinary pharmaceutical supplies drawing from Spain, Germany, and France. Commercial pet food inputs rest on corn and poultry protein sourcing from domestic agriculture and Brazilian imports. Single-source vulnerability concentrates in specialized climate-control equipment for kennel construction, where Madrid's industrial-peripheral zoning restricts facility placement. Distribution runs through licensed veterinary service networks that enforce Ley de Protección de los Animales de Compañía compliance before product admission.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain pet boarding functions as a stable compounder, with hybrid work normalization generating predictable midweek daycare demand that smooths revenue volatility for compliant operators.
For Market Incumbents: Anchor defensive positioning through backward integration into in-house veterinary clinics and subscription-based wellness packages that lock in recurring revenue. Certification investment in breed-specific exercise protocols creates differentiation against emerging digital-first platforms. Channel control over municipal licensing relationships in Madrid and Barcelona constrains greenfield competition. For New Entrants and Emerging Players: The price-point gap between Posh Pets Spain luxury suites and informal home-based operators presents white-space opportunity in Valencia and Seville licensed facility shortages. Veterinary partnership models with rescue organizations offer the most penetrable entry vector. Go-to-market execution should emphasize IoT-enabled transparency features that justify premium positioning against unlicensed substitutes. For Investors and Strategic Acquirers: Private equity firms with pet services portfolio experience are the most active acquirer in this space, targeting mid-market chains with veterinary integration capabilities. Five-to-ten year viability hinges on autonomous community enforcement harmonization accelerating consolidation. Monitor Andalusia's inspection protocol expansion as the signal for regulatory-driven volume redistribution toward compliant chains.| Strategic Initiative | Industry Significance |
|---|---|
| Veterinary Integration | Co-located wellness clinics capture recurring revenue beyond episodic boarding stays. |
| Subscription Model Transition | Monthly daycare packages displace per-day transactions and improve cash flow predictability. |
| IoT-Enabled Monitoring Deployment | Live video feeds and climate sensors justify premium pricing tiers in competitive urban corridors. |
| Secondary City Expansion | Valencia and Seville licensed facility shortages create first-mover corridors relative to pet ownership density. |
| Regulatory Compliance Investment | Ley de Protección de los Animales de Compañía certification accelerates volume capture from disqualifying informal operators. |
Research Methodology
Coverage spans Madrid, Barcelona, Catalonia, Andalusia, and Valencia, with primary inputs from each autonomous community's veterinary services and facility operators. The approach combines interviews with licensed kennel operators, municipal veterinary inspectors, and pet owner focus groups with secondary validation from Spain's autonomous community welfare enforcement databases, Ley de Protección de los Animales de Compañía regulatory filings, and municipal zoning records. Bottom-up facility capacity modeling and top-down household pet ownership estimates triangulate market sizing.
Granularity-level modeling extends to service type, animal physiology, facility capital tier, and customer procurement pattern dimensions across the projection horizon. CAGRs derive from segment-level growth rate synthesis anchored in licensed facility capacity expansion timelines and hybrid work normalization penetration curves. Forecast inputs incorporate autonomous community enforcement intensity differentials and veterinary nurse labor supply constraints in Catalonia and Andalusia.
The model assumes a particular technology adoption path for IoT-enabled monitoring; alternative pathways for biometric pet identification and automated self-service check-in would alter the outlook. Forecasts reflect documented assumptions about regulatory harmonization pace and enforcement resource allocation across autonomous communities. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Indestructible Dog Toys Market
Pet Care Products
Dog Perfume Market
Pet Care Products
Aquarium and Fish Bowls Market
Pet Care Products
Frozen and Freeze-Dried Pet Food Market
Pet Care Products
Large Breed Dog Food Market
Pet Care Products
Sensitive Stomach Cat Food Market
Pet Care Products
Dog Coats for Winter Market
Pet Care Products
South America Cat Food Market
Pet Care Products
United States Pet Market
Pet Care Products
Tofu Cat Litter Market
Pet Care Products
Europe Pet Diet Market
Pet Care Products
Pet Grooming Products Market
Pet Care Products
Pet Pee Pads Market
Pet Care Products
Dog Treats Market
Pet Care Products
Pet Food Nutraceutical Market
Pet Care Products
Japan Pet Clothing Market