
 United States Organic and Natural Pet Food Market | 2026-2036
United States Organic and Natural Pet Food Market Size, Share, and Industry Trends Forecast 2026-2036
United States Organic and Natural Pet Food Market Intelligence
Direct-to-consumer subscription technology is fragmenting traditional retail distribution for organic and natural pet food brands. Stella & Chewy's LLC leverages its freeze-dried raw specialization to anchor premium positioning in specialty channels. Merrick Pet Care sustains broad SKU coverage across wet and dry formats through its Texas-based manufacturing network. Newman's Own competes on certified organic credentials and charitable attribution, differentiating its portfolio in a crowded premium aisle.
Organic and natural pet food comprises formulations manufactured without synthetic pesticides, antibiotics, artificial preservatives, or genetically modified organisms, typically bearing USDA Organic or Association of American Feed Control Officials (AAFCO) nutritional adequacy designations. The category serves companion animal owners seeking ingredient transparency and reduced chemical exposure for pets with sensitivities or longevity concerns. Dry food retains volume leadership due to shelf stability and lower per-feeding cost, while wet food and treats capture disproportionate margin pools as humanization trends elevate palatability expectations. Ingredient source segmentation reveals meat-first formulations dominating premium positioning, with vegetables and fruits functioning as functional add-ins for digestive and antioxidant claims.
The FDA Center for Veterinary Medicine enforces pet food labeling and contaminant standards, while USDA Organic certification governs ingredient sourcing and handling protocols for products bearing the seal. State departments of agriculture in California, Texas, and New York conduct additional feed safety inspections that shape regional market access requirements. AAFCO model regulations influence state-level nutritional adequacy claims, creating a layered compliance environment that elevates formulation costs for new entrants. Stakeholders must monitor evolving state legislative proposals on pet food ingredient disclosure and the potential federal alignment of organic pet food standards with human food safety benchmarks.
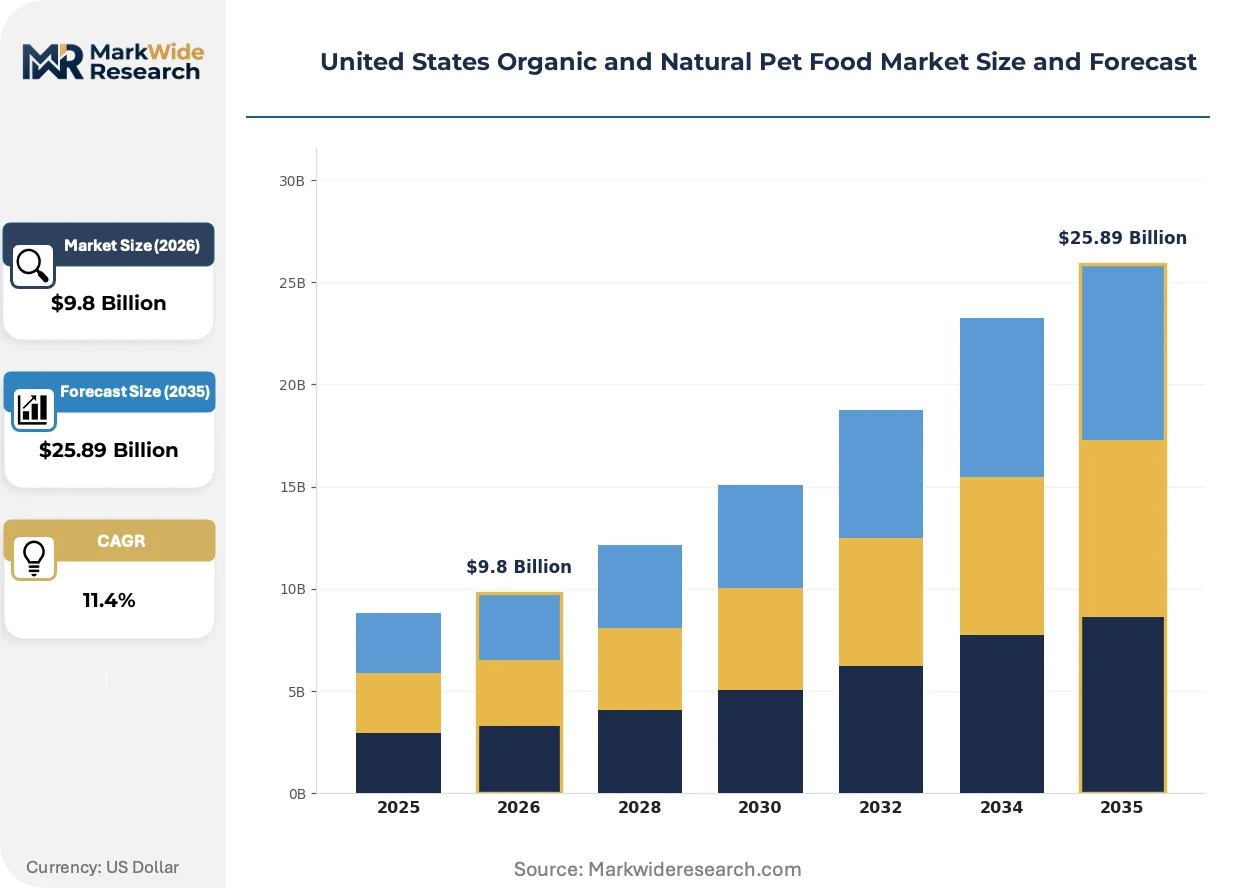
Market Dynamics
Direct-to-consumer subscription models are fragmenting traditional retail distribution for organic and natural pet food brands, while USDA Organic certification requirements and state-level pet food safety statutes tighten ingredient traceability standards across the value chain.
Growth Catalysts
- USDA Organic Certification Mandate:Federal organic labeling standards create premium pricing power for certified formulations and lock out uncertified competitors from high-margin shelf space in specialty channels.
- Freeze-Dried Raw Technology:Advanced dehydration processes preserve nutrient density without refrigeration, opening distribution to e-commerce fulfillment centers lacking cold-chain infrastructure.
- Urban Millennial Concentration:Pet owner density in Austin, Denver, and Portland accelerates trial rates for human-grade positioning and drives word-of-mouth adoption through veterinary influencer networks.
Market Restraints
- Organic Protein Input Volatility:Certified organic meat and poultry supply concentrates among limited USDA-accredited processors, exposing margins to agricultural commodity swings.
- AAFCO Nutritional Adequacy Testing:State-level adoption of Association of American Feed Control Officials feeding trial protocols imposes six-figure formulation validation costs that deter small-batch entrants.
- Wet Food Substitution Pressure:Refrigerated fresh pet food delivery services capture palatability-sensitive owners who reject shelf-stable dry formats despite higher per-pound organic pricing.
Strategic Opportunities
- Southeastern Veterinary Channel:Underpenetrated independent veterinary practices in Florida and Georgia represent white space for prescription-grade organic formulations with clinical validation.
- State Incentive Alignment:California Department of Food and Agriculture grants for sustainable protein sourcing reward brands establishing in-state organic supply chain partnerships.
- Smart Feeder Integration:Convergence of portion-control hardware with subscription replenishment APIs creates captive consumption data and locks in recurring revenue.
Industry Challenges
- Organic Certification Timeline:USDA-accredited certifier backlogs extend new product qualification by 8-14 months, delaying seasonal formulation launches.
- Legacy ERP Integration:Batch-level ingredient traceability requirements force mid-tier manufacturers to replace inventory systems incapable of lot-tracking organic certificates through co-packer networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Organic and Natural Pet Food Market |
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $25.89 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Treats, Supplements Ingredient Source: Meat, Grains, Vegetables, Fruits Packaging Type: Bags, Cans, Pouches, Bulk Distribution Channel: Online, Pet Stores, Supermarkets, Specialty Retailers |
| Companies Covered | PetGuard, Natural Planet Pet Foods, Newman's Own, Stella & Chewy's LLC, Evanger's, Organic Pet Boutique, Dr. Geoff's Real Food, Merrick Pet Care, Party Animal Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Organic and Natural Pet Food Market Strategic Shifts & Innovations
Humanization of pet nutrition is compressing the innovation cycle for organic formulations, with technology convergence and regulatory tightening reshaping how brands build trust and capture lifetime value.
High-pressure processing is collapsing the safety validation timeline for raw organic diets. Premium brands in the Pacific Coast corridor are adopting HPP pasteurization to eliminate pathogen risk without thermal nutrient degradation. This technology is collapsing the historical trade-off between raw feeding ideology and retail liability exposure, enabling freeze-dried expansion into mass-market grocery.
State-level pet food safety statutes in California, Texas, and New York are mandating ingredient disclosure beyond federal minimums. These statutes force reformulation of proprietary premixes and accelerate competitive intelligence through transparent sourcing. Wet food manufacturers with complex multi-vitamin blends face the steepest compliance reconfiguration.
Subscription auto-replenishment is displacing episodic retail purchasing among urban Millennial households. Direct-to-consumer platforms capture consumption data that informs personalized formulation recommendations. This shift concentrates in Northeast corridor metropolitan statistical areas with highest pet insurance penetration and veterinary telehealth adoption.
United States Organic and Natural Pet Food Market Segmentation
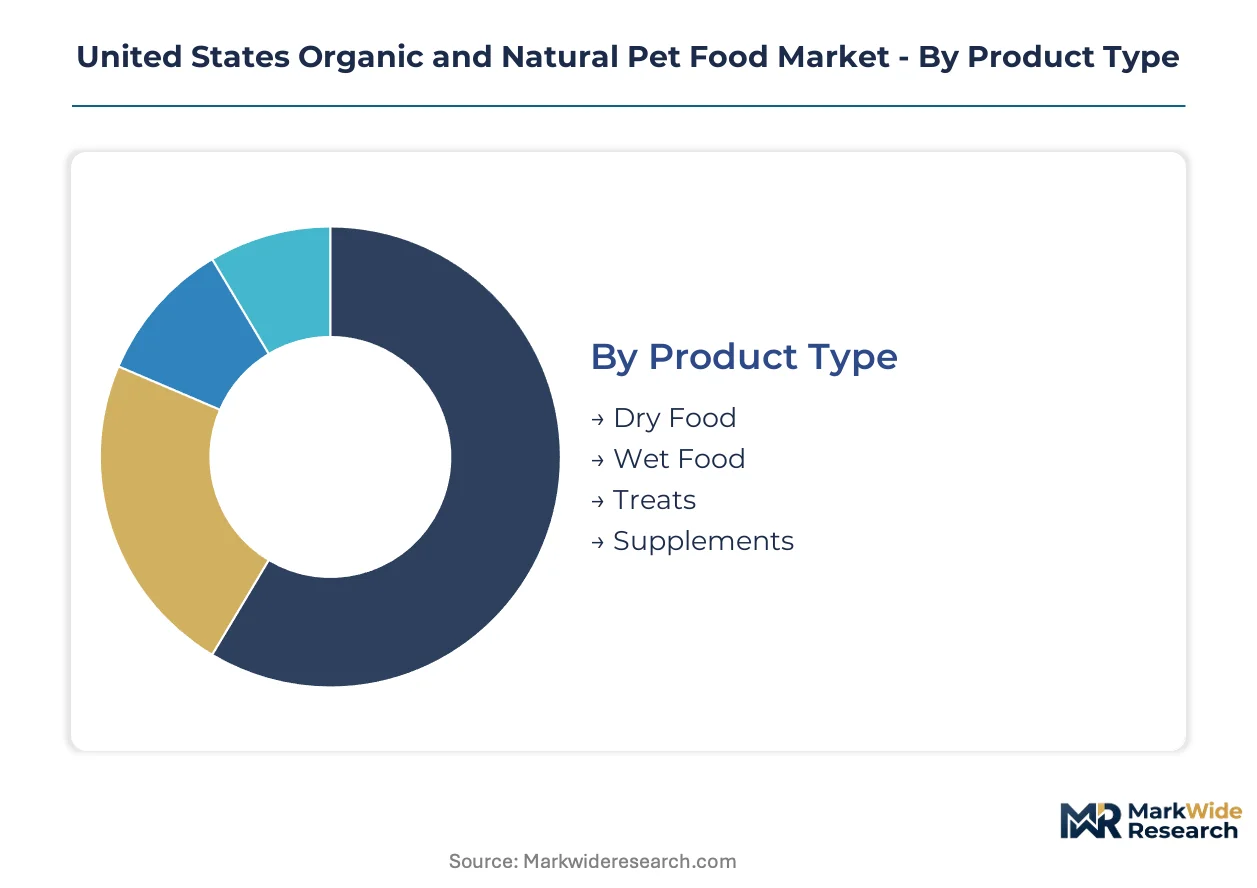
Segmentation in the United States organic and natural pet food market reveals how purchasing behavior fragments across feeding formats, ingredient philosophies, and channel preferences. Understanding these divisions exposes where margin pools concentrate and which customer cohorts drive repeat purchase velocity.
Product Type:
Dry food turns inventory slowest due to extended shelf stability, while wet food and treats cycle faster through households with palatability-sensitive pets or training-intensive routines.
- Dry Food:Kibble formulations with USDA Organic certification dominate household penetration due to cost-per-feeding efficiency and storage convenience. Demand clusters in suburban markets across Texas and Florida where multi-pet households prioritize budget predictability.
- Wet Food:Canned and tray formats deliver higher moisture content and palatability for aging pets or those with urinary health concerns. Urban Millennial owners in Portland and Denver over-index on wet food subscription trials driven by veterinary telehealth recommendations.
- Treats:Functional and training treats carry premium positioning through limited-ingredient claims.
- Supplements:Probiotic and joint-health add-ins target geriatric pet cohorts with condition-specific formulations.
Dry food anchors the volume base while wet food gains share at the steepest rate.
Ingredient Source:
Cost tier stratification runs deepest here, with meat-first formulations commanding shelf space premiums and plant-forward alternatives capturing sustainability-motivated buyers.
- Meat:USDA-certified organic poultry, beef, and fish supply the amino acid density required for AAFCO nutritional adequacy claims. Sourcing concentrates among accredited processors in the Midwest, exposing brands to agricultural commodity volatility.
- Grains:Organic brown rice and oats serve as carbohydrate binders in conventional kibble, though grain-free positioning has displaced volume in premium channels.
- Vegetables:Sweet potato and pumpkin function as fiber sources for digestive health claims.
- Fruits:Blueberry and cranberry extracts deliver antioxidant marketing hooks with minimal formulation cost.
Meat-based formulations retain the dominant revenue share while vegetable inclusions expand most quickly as functional positioning intensifies.
Packaging Type:
Volume scale and margin extraction diverge sharply here, with bulk formats serving price-sensitive multi-pet households and single-serve pouches capturing trial-driven urban buyers.
- Bags:Multi-layer film packaging for dry food supports 6-18 month shelf life and pallet-efficient logistics. The format dominates mass-market grocery distribution in California and New York metropolitan corridors.
- Cans:Steel and aluminum containers for wet food enable retort sterilization without chemical preservatives. Recycling infrastructure gaps in secondary markets create sustainability messaging friction.
- Pouches:Flexible stand-up formats reduce shipping cube and support portion-controlled feeding.
- Bulk:Refill and bin programs appeal to zero-waste retailers in Austin and Boulder.
Bags sustain the volume foundation while pouches climb the fastest as e-commerce fulfillment prioritizes dimensional weight efficiency.
Distribution Channel:
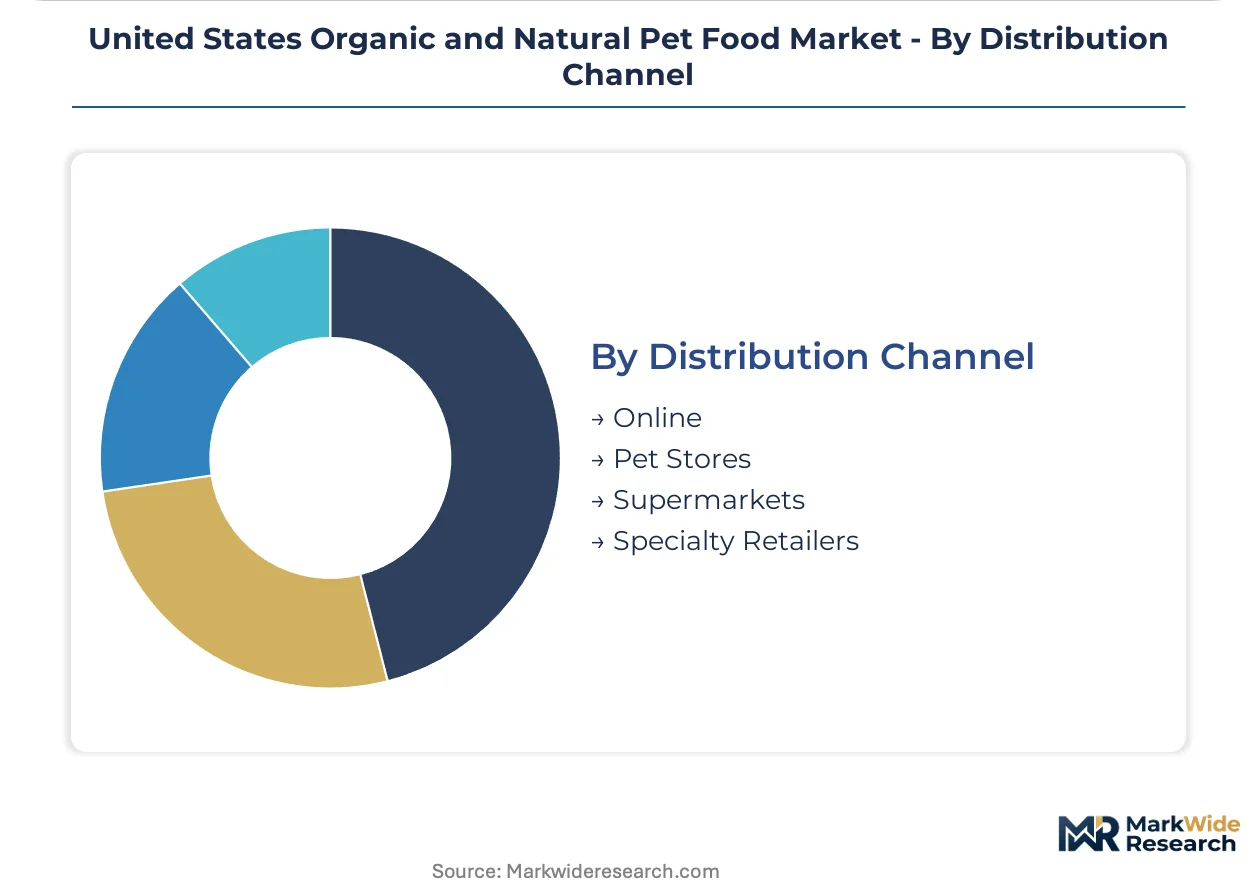
Customer acquisition economics and lifetime value trajectories separate dramatically across these pathways, with online subscriptions capturing consumption data and specialty retailers anchoring premium credibility.
- Online:Direct-to-consumer platforms and Amazon-first brands leverage auto-replenishment APIs to lock in recurring revenue. Northeast corridor households with pet insurance coverage over-index on subscription adoption.
- Pet Stores:Petco and PetSmart provide shelf space for freeze-dried raw and limited-ingredient SKUs requiring education-heavy purchase decisions.
- Supermarkets:Kroger and Whole Foods carry USDA Organic dry food for convenience-driven shoppers.
- Specialty Retailers:Independent natural grocers and veterinary clinics prescribe clinical-grade organic formulations.
Pet stores anchor the volume base while online channels gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Organic pet food production flows from Midwest meat-processing hubs to coastal metropolitan consumption centers, with USDA-accredited certifiers in Iowa and Nebraska validating ingredients destined for Pacific Coast and Northeast corridor retail channels.
Pacific Coast
Millennial pet owner density in Portland and Seattle accelerates subscription adoption for freeze-dried raw formats. California Department of Food and Agriculture grants incentivize sustainable protein sourcing partnerships. High-pressure processing clusters in Los Angeles County enable pathogen elimination without thermal degradation, opening mass-market grocery distribution for raw-positioned brands.
Mountain West
Denver and Austin veterinary telehealth networks drive trial rates for human-grade formulations among urban professionals. Colorado Department of Agriculture enforces feed safety inspections that exceed federal minimums for ingredient disclosure. Boulder-based zero-waste retailers pioneer bulk refill programs that reduce packaging costs for multi-pet households.
Texas Triangle
Dallas-Fort Worth and Houston multi-pet households prioritize dry food cost-per-feeding efficiency across suburban markets. Texas Department of State Health Services conducts regional feed safety inspections that shape distribution access requirements. Merrick Pet Care anchors manufacturing capacity in Hereford, leveraging proximity to organic beef supply chains for wet and dry format production.
Northeast Corridor
New York Metro and Boston households with pet insurance coverage over-index on direct-to-consumer subscription platforms. New York State Department of Agriculture and Markets mandates ingredient traceability protocols that force ERP system upgrades among mid-tier manufacturers. Independent veterinary practices in Connecticut and New Jersey represent underpenetrated white space for prescription-grade organic formulations.
Southeast
Florida and Georgia independent veterinary channels remain underpenetrated relative to national organic adoption rates. State departments of agriculture in both jurisdictions align with AAFCO model regulations for nutritional adequacy claims. Atlanta and Miami specialty retailers carry limited-ingredient SKUs requiring education-heavy purchase decisions for aging pet cohorts with urinary health concerns.
United States Organic and Natural Pet Food Market Key Industry Players
Channel-controlling players compete with product-specialist players across fragmented shelf space in specialty retail and e-commerce fulfillment. The vendor base stratifies into three tiers: freeze-dried raw specialists commanding premium positioning, broad-format manufacturers sustaining SKU coverage across wet and dry categories, and certified organic pure-plays differentiating through charitable attribution and transparency marketing. Consolidation pressure concentrates among mid-tier private-label manufacturers lacking USDA certification timelines. Dominant competitive moves include backward integration into organic protein sourcing and API-based subscription platform development to capture recurring revenue.
Among the named participants, Stella & Chewy's LLC and Merrick Pet Care exemplify contrasting scale-specialist positioning within the freeze-dried raw and broad-format archetypes respectively. Newman's Own occupies a position anchored in certified organic credentials and charitable attribution, differentiating its portfolio in crowded premium aisles. These three entities represent the strategic diversity visible across the competitive set, spanning technology-enabled raw specialization, Texas-based manufacturing scale, and purpose-driven brand equity.
| Leading Market Players |
|---|
| PetGuard |
| Natural Planet Pet Foods |
| Newman's Own |
| Stella & Chewy's LLC |
| Evanger's |
| Organic Pet Boutique |
| Dr. Geoff's Real Food |
| Merrick Pet Care |
| Party Animal Inc |
| Others |
Cost & Logistics Intelligence
Hereford, Texas anchors domestic organic beef processing capacity for Merrick Pet Care and regional wet food manufacturers, concentrating upstream supply leverage that translates into shelf-stable pricing power against coastal brands dependent on third-party protein sourcing.
Pricing Analysis
Freeze-dried raw technology commands a generational premium over conventional kibble, while high-pressure processed formats occupy a mid-tier position and legacy thermal-treated products face margin compression. Three-tier pricing structure across USDA-certified organic, natural non-certified, and conventional economy levels stratifies the market, with certification grade and volume scale as primary differentiation drivers. Cost compression in the economy tier intensifies because refrigerated fresh delivery services capture palatability-sensitive owners. Multi-pet households in suburban Texas and Florida exhibit highest price sensitivity, while urban Millennial subscribers in Portland and Denver demonstrate lowest elasticity due to pet insurance coverage and veterinary telehealth anchoring.
Supply Chain Analysis
Midwest contract manufacturers in Iowa and Nebraska hold the majority of USDA-accredited organic certification capacity for ingredient preprocessing and batch validation. Geographic supply concentration clusters in the United States Midwest for organic meat and poultry, with supplementary vegetable inputs drawn from California's Central Valley and Pacific Northwest organic farms. Single-source vulnerability concentrates among limited USDA-accredited organic protein processors, exposing brands to agricultural commodity volatility and certifier backlog delays. Distribution runs through a hybrid structure blending direct-to-consumer subscription platforms, specialty pet retail, and mass-market grocery, with e-commerce fulfillment centers increasingly bypassing cold-chain requirements through freeze-dried format adoption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against refrigerated fresh pet food delivery services that are substituting shelf-stable formats among palatability-sensitive urban owners, eroding the organic premium through superior convenience positioning.
For Market Incumbents: Insulate subscription revenue by integrating smart feeder APIs that lock in recurring replenishment through portion-control hardware, neutralizing fresh delivery convenience advantages. Deepen backward integration into organic protein sourcing through partnerships with Midwest USDA-accredited processors, reducing exposure to agricultural commodity volatility and certifier timeline delays that plague competitors dependent on spot-market inputs.
For New Entrants and Emerging Players: Build out presence in underpenetrated independent veterinary channels across Florida and Georgia, where prescription-grade organic formulations lack clinical validation competitors. Target the Southeastern veterinary segment through white-label partnerships with regional distributors, leveraging the absence of established freeze-dried raw specialists to capture education-heavy purchase decisions for aging pet cohorts.
For Investors and Strategic Acquirers: Carve-out targets emerge from mid-tier private-label manufacturers lacking USDA certification timelines, stranded by ERP upgrade requirements for batch-level traceability compliance. Long-term viability favors brands with captive organic supply chain partnerships and API-based subscription infrastructure. Monitor USDA-accredited certifier backlog duration as the inflection indicator—shortening timelines signal margin recovery for certified players, while extended delays accelerate consolidation pressure.
| Strategic Initiative | Industry Significance |
|---|---|
| Smart Feeder API Integration | Locks recurring revenue through portion-control hardware convergence with subscription replenishment in Northeast corridor households. |
| USDA Organic Certification Acceleration | Shortens 8-14 month qualification timeline through dedicated certifier relationships, enabling seasonal formulation launches. |
| High-Pressure Processing Adoption | Enables pathogen elimination without thermal degradation, opening mass-market grocery distribution for raw-positioned Pacific Coast brands. |
| Southeastern Veterinary Channel Entry | Captures underpenetrated Florida and Georgia practices through prescription-grade formulations with clinical validation requirements. |
| Backward Integration into Organic Protein | Reduces margin exposure to limited USDA-accredited processor concentration through captive Midwest supply partnerships. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA Center for Veterinary Medicine labeling guidance, USDA Organic certification databases, and AAFCO model regulation adoptions by state departments of agriculture. Primary interviews engaged brand managers at organic pet food manufacturers, category buyers at specialty retailers, procurement leads at co-packer networks, and regulatory affairs specialists navigating multi-state compliance. Secondary sources incorporated customs records for organic ingredient imports, SEC filings for publicly traded parent entities, and state-level feed safety inspection reports from California, Texas, and New York. Bottom-up SKU-level volume estimates triangulated against top-down category expenditure data from retail audit services.
Forecast inputs incorporate feeding format adoption curves, generational pet owner demographics, and regulatory compliance cost trajectories across the projection horizon. Segmentation dimensions modeled include product type, ingredient source philosophy, packaging format, and distribution channel, with additional weighting for USDA certification status and geographic veterinary telehealth penetration. CAGRs derived from regression analysis of historical category growth against pet ownership rates, disposable income elasticity, and premiumization trend indicators. Industry-specific inputs include organic protein supply availability and high-pressure processing capacity expansion timelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by refrigerated fresh delivery services or rapid FDA alignment of organic pet food standards with human food benchmarks would shift outcomes. Quarterly review of USDA-accredited certifier backlog duration, smart feeder hardware shipment volumes, and state-level ingredient disclosure legislative proposals is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
GCC Organic and Natural Pet Food Market
Pet Care Products
Spain Pet Food Market
Pet Care Products
South America Cat Food Market
Pet Care Products
Natural Dog Treat Market
Pet Care Products
Malaysia Pet Food Market
Pet Care Products
Inflatable Pet Collars Market
Pet Care Products
Australia Pet Food Market
Pet Care Products
Plant-Based Pet Food Market
Pet Care Products
Pet Food Market
Pet Care Products
Insulated Dog House Market
Pet Care Products
Dog Water Bottle Market
Pet Care Products
Pet Tag Market
Pet Care Products
UK Pet Training Services Market
Pet Care Products
North America Cat Food Market
Pet Care Products
United Kingdom Pet Food Market
Pet Care Products
Pet Noise Anxiety Market