
 UAE Pet Food Market | 2026-2036
UAE Pet Food Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Pet Food Market Intelligence
Domestic manufacturing capacity across the Gulf is expanding as local blenders invest in extrusion and packaging lines to reduce import dependency. Mars Petcare leverages its regional distribution network to sustain shelf presence in hypermarkets and veterinary channels throughout the Emirates. Nestlé Purina PetCare anchors its position through specialized therapeutic formulations distributed via Eurovets Veterinary Suppliers. Agthia Group competes on price-accessible dry food portfolios aimed at mass-market pet owners in Sharjah and northern emirates.
Pet food comprises formulated nutritional products manufactured through extrusion, baking, or retort processing to deliver complete diets meeting species-specific protein, fat, vitamin, and mineral requirements. Dry food dominates volume throughput due to extended shelf stability and lower logistics costs in arid climates, while wet food commands premium positioning among owners seeking hydration-focused diets for cats. Treats represent the fastest-growing margin pool as functional reward products incorporating dental or joint-support additives gain traction. Veterinary Clinics channel controls the highest-value transactions through prescription diet authorization and recurring subscription models.
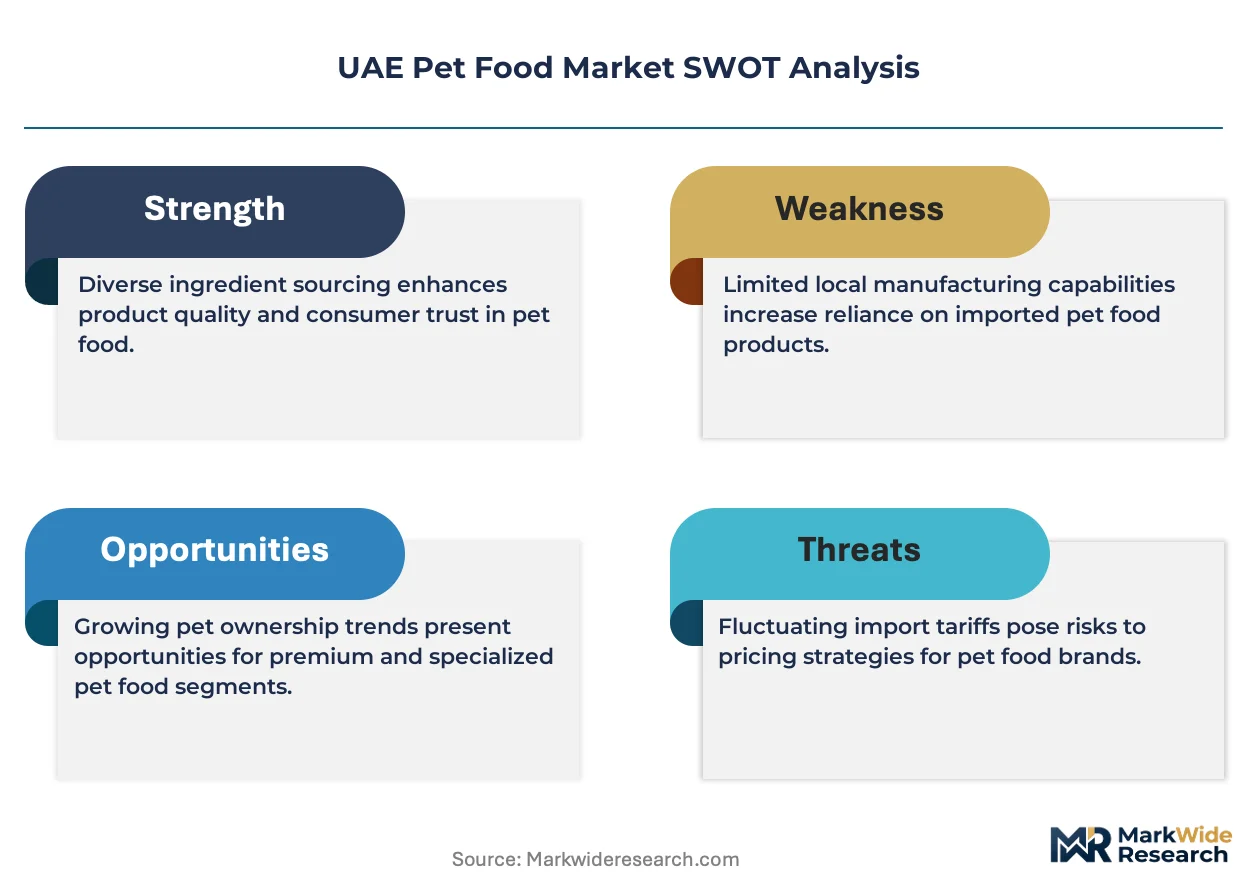
MOHAP enforces veterinary product registration and labeling standards that mandate Arabic-language ingredient disclosure and prohibit unsubstantiated health claims. The UAE's food safety regulator applies parallel scrutiny through import permits and halal certification requirements for animal-derived proteins. Stakeholders must monitor evolving feed additive approvals and local manufacturing incentive programs as the Emirates advances its food security agenda. Decisions on backward integration into protein sourcing or captive treat production will determine margin resilience against import cost volatility.
Market Dynamics
MOHAP's tightened veterinary product registration requirements are compressing import timelines while simultaneously elevating compliance costs for nutritional claim substantiation across Dubai and Abu Dhabi distribution channels.
Growth Catalysts
- Urban Premiumization:Rising disposable incomes in Dubai and Abu Dhabi are expanding ownership of high-maintenance breeds requiring specialized life-stage formulations.
- Therapeutic Diet Authorization:Eurovets Veterinary Suppliers and comparable channels are building recurring revenue through prescription diet subscriptions authorized by licensed veterinarians.
- Halal Certification Alignment:The UAE's food safety regulator has streamlined import permits for animal-derived proteins meeting halal standards, reducing clearance friction for compliant suppliers.
Market Restraints
- Import Dependency Concentration:Over 80% of finished pet food volumes still originate from extrusion facilities in Thailand and European Union member states, exposing distributors to shipping cost volatility.
- Protein Input Cost Volatility:Global fishmeal and poultry meal markets fluctuate with climate-driven catch variations and grain-feed price cycles, compressing blender margins on mid-tier formulations.
- Arabic Labeling Compliance Burden:MOHAP mandates dual-language ingredient disclosure with specific nutritional terminology, requiring reformulation of packaging assets originally designed for English-only markets.
Strategic Opportunities
- Northern Emirates Penetration:Sharjah, Ajman, and Ras Al Khaimah exhibit lower brand saturation than Dubai, creating first-mover potential for price-accessible dry food portfolios with localized distribution.
- Functional Treat Expansion:Dental hygiene and joint-support additive categories remain underdeveloped relative to mature European markets, offering margin expansion for captive treat production investments.
- Local Manufacturing Incentives:The Emirates' food security agenda includes capital subsidies for backward integration into extrusion and packaging lines, reducing exposure to import tariff fluctuations.
Industry Challenges
- Veterinary Nutritionist Talent Scarcity:Formulation of therapeutic diets requires professionals credentialed in both animal nutrition and MOHAP registration protocols, a skill combination concentrated in limited Dubai-based consultancies.
- Cold Chain Infrastructure Gaps:Wet food distribution into northern emirates faces temperature excursion risks due to fragmented refrigerated logistics networks outside Abu Dhabi and Dubai metropolitan zones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Pet Food Market |
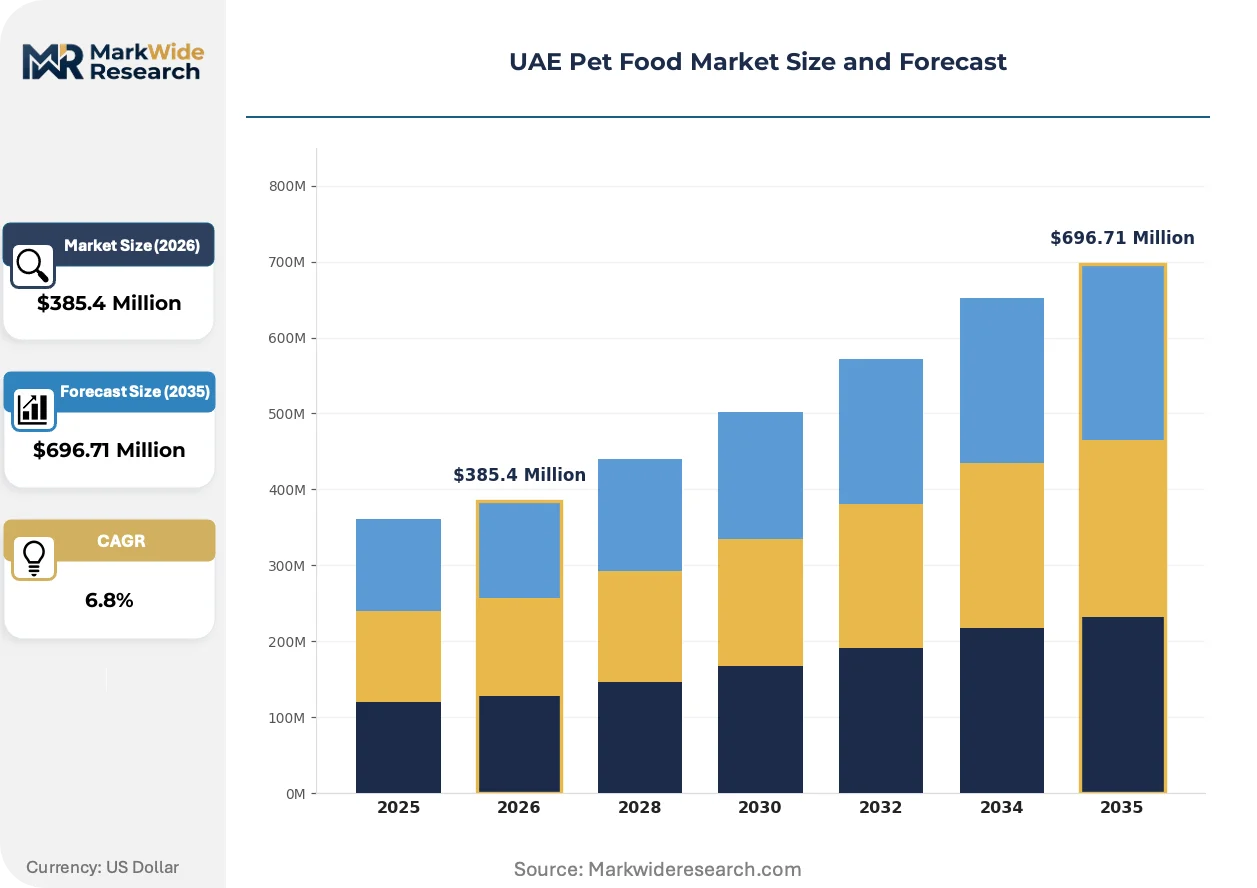
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $696.71 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Treats, Supplements Animal Type: Dogs, Cats, Fish, Birds Distribution Channel: Online Retail, Pet Shops, Supermarkets, Veterinary Clinics Customer Type: Pet Owners, Resellers, Breeders, Kennels |
| Companies Covered | Agthia Group, Armitage Pet Care, Mars Petcare, United Petfood, Ainawi Group, Nestlé Purina PetCare, Del Monte, Eurovets Veterinary Suppliers, Hill's Pet Nutrition, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Pet Food Market Strategic Shifts & Innovations
Formulation science and channel digitization are converging to reshape how nutritional products reach pet owners across the Emirates, with regulatory compliance increasingly embedded as a competitive differentiator rather than a cost center.
Extrusion technology incorporating precision moisture control and alternative protein binding is electrifying the dry food segment's capacity to mimic wet food palatability without refrigeration requirements. Mars Petcare and regional blenders are retrofitting existing lines with these systems to capture shelf-stable premium positioning. The technology is compressing the traditional wet-dry price gap while extending distribution reach into climate-stressed storage environments.
MOHAP's 2024 updated veterinary product registration framework mandates pre-market submission of clinical trial data for any therapeutic nutritional claim, creating a de facto barrier to unsubstantiated marketing. This policy shift is elevating R&D investment requirements for brands seeking prescription channel access. Veterinary clinics in Dubai Healthcare City and Abu Dhabi's Al Maryah Island medical district are responding by consolidating supplier relationships around registrants with established dossier capabilities.
Subscription-based replenishment models are displacing episodic retail purchasing among multi-pet households in high-income Dubai neighborhoods such as Emirates Hills and Palm Jumeirah. Eurovets Veterinary Suppliers and hypermarket loyalty programs are capturing recurring revenue through automated delivery of breed-specific formulations. This behavioral shift is most visible among expatriate professionals with limited time for store visits and high willingness to delegate nutritional decision-making to algorithmic recommendation engines.
UAE Pet Food Market Segmentation
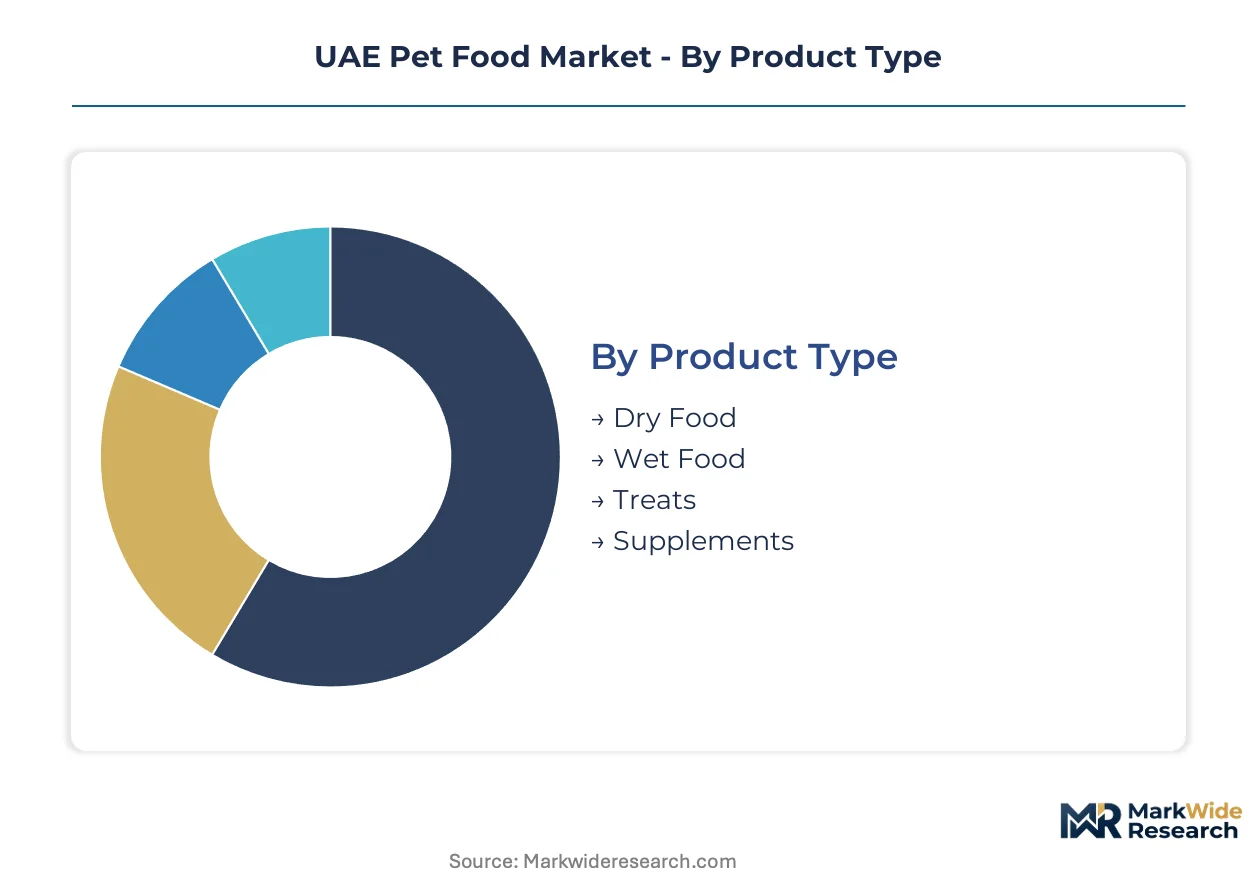
Segmentation in the UAE pet food market reveals distinct procurement patterns across product formats and channel preferences. Breed-specific dietary requirements and climate-driven storage constraints shape how owners allocate spending across dry, wet, and functional nutrition categories.
Product Type:
Cost tier drives product selection more than brand loyalty among mass-market purchasers.
- Dry Food:Extruded kibble formulations deliver complete nutrition with moisture content below 10%, enabling ambient storage in Dubai's high-temperature warehousing. Sharjah and northern emirates households prioritize 15-20kg bulk sacks for multi-pet cost efficiency.
- Wet Food:Retort-processed cans and pouches contain 75-85% moisture, addressing hydration needs for cats in air-conditioned indoor environments. Premium positioning concentrates in Abu Dhabi's Al Maryah Island and Dubai Healthcare City veterinary clinics.
- Treats:Functional reward products incorporating dental abrasives or glucosamine additives gain traction among urban professionals seeking behavioral training tools.
- Supplements:Omega fatty acid and probiotic formats target aging pet demographics with veterinarian-directed dosing protocols.
Volume sits with Dry Food; growth tilts toward Treats.
Animal Type:
Application-specific formulation requirements create divergent R&D investment priorities.
- Dogs:Large-breed puppy formulations with controlled calcium-phosphorus ratios dominate therapeutic diet authorizations through Eurovets channels. German Shepherd and Golden Retriever ownership in Emirates Hills drives demand for joint-support adult maintenance.
- Cats:Obligate carnivore protein requirements mandate minimum 26% crude protein content, with urinary pH control formulations capturing recurring subscription revenue.
- Fish:Specialized flake and pellet nutrition for ornamental aquarium species serves hobbyist segments in Ras Al Khaimah and Ajman.
- Birds:Seed blends and extruded pellets for psittacine species represent a niche category with concentrated distribution through dedicated pet shops.
Spending concentrates with Dogs; margin expansion tilts toward Cats.
Distribution Channel:
Customer type determines channel selection more than price sensitivity alone.
- Online Retail:Subscription-based replenishment models automate delivery of breed-specific formulations to Palm Jumeirah and Dubai Marina multi-pet households.
- Pet Shops:Staff-assisted consultation drives trial conversion for premium transitions, with localized inventory in Sharjah catering to price-accessible portfolios.
- Supermarkets:Mars Petcare and Agthia Group maintain shelf presence through hypermarket loyalty programs with rotating promotional cycles.
- Veterinary Clinics:Prescription diet authorization controls highest-value transactions through recurring subscription models and clinical trial-backed therapeutic claims.
Transaction value concentrates with Veterinary Clinics; volume throughput tilts toward Supermarkets.
Customer Type:
Procurement scale and decision authority separate commercial from household purchasers.
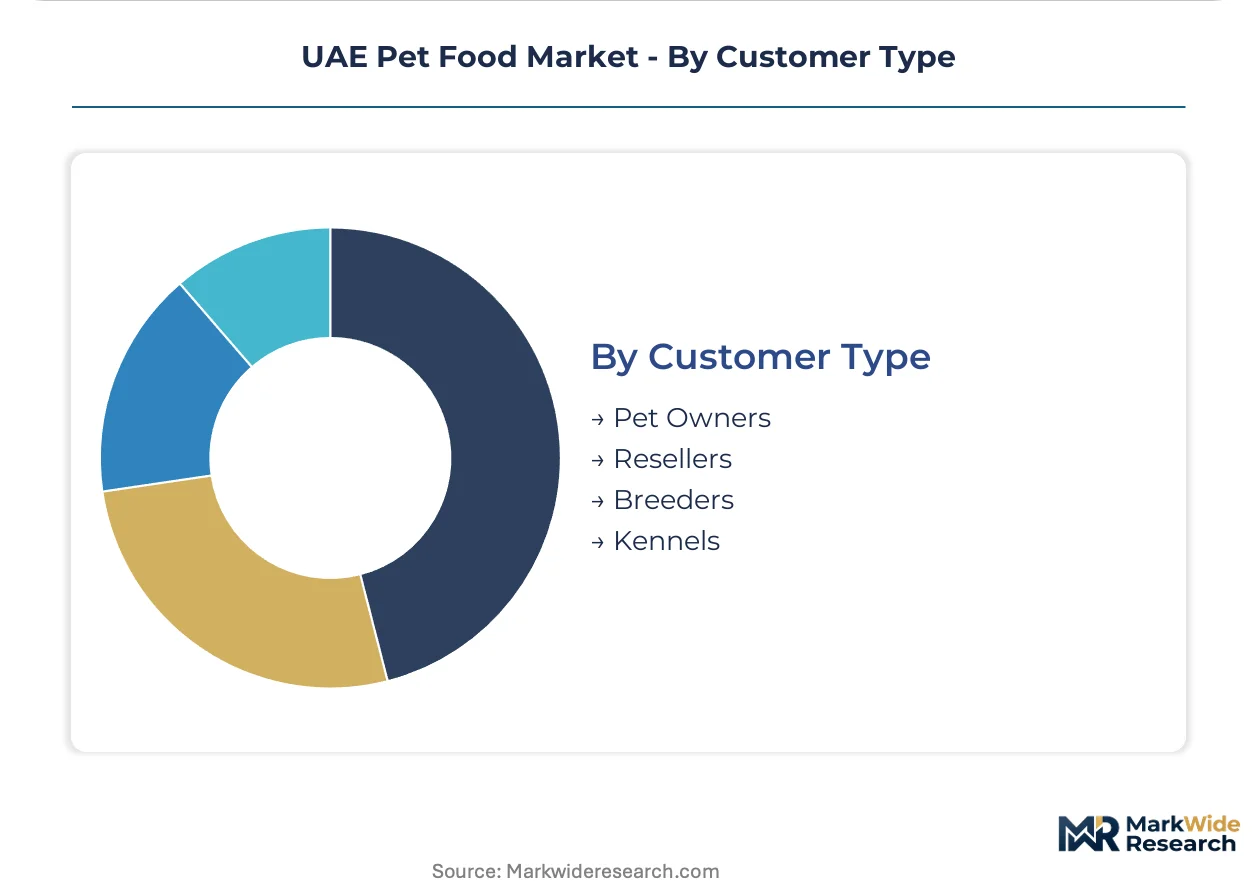
- Pet Owners:Individual households in Dubai and Abu Dhabi exhibit strongest willingness to pay for halal-certified animal proteins and Arabic-labeled packaging.
- Resellers:Independent pet shop operators in northern emirates aggregate demand for price-accessible dry food with flexible minimum order quantities.
- Breeders:Commercial kennel operations require life-stage specific formulations in pallet-scale procurement with extended payment terms.
- Kennels:Boarding facilities prioritize cost-efficient maintenance diets with bulk packaging and simplified feeding protocols.
Margin capture concentrates with Breeders; frequency of purchase tilts toward Pet Owners.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Poultry meal processing facilities in Jebel Ali anchor the Emirates' protein supply chain for extruded formulations. Local blenders source rendered proteins from integrated abattoirs while halal certification requirements shape cross-border procurement patterns.
Dubai
Emirates Hills and Palm Jumeirah households drive premium therapeutic diet subscriptions through veterinary channels. MOHAP's registration protocols mandate Arabic-label packaging for all retail distribution. Jebel Ali Free Zone concentrates extrusion and packaging investments targeting re-export to GCC markets.
Abu Dhabi
Al Maryah Island veterinary clinics authorize prescription diets for large-breed maintenance and life-stage formulations. The emirate's food security agenda subsidizes local manufacturing capacity expansion. Khalifa Industrial Zone attracts backward integration projects for captive protein rendering.
Sharjah
Multi-pet households in industrial zones prioritize bulk dry food procurement for cost efficiency. The emirate's logistics corridors enable price-accessible distribution into northern emirates. Sharjah's pet retail clusters serve price-sensitive segments with flexible minimum order quantities.
Northern Emirates
Ajman and Ras Al Khaimah exhibit lower brand saturation and fragmented cold chain infrastructure. Wet food distribution faces temperature excursion risks outside metropolitan zones. Local pet shops aggregate demand for economy-tier portfolios with simplified feeding protocols.
UAE Pet Food Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue functional treat specialization and subscription-based distribution. The market structures around three tiers: multinational manufacturers with regional distribution networks, domestic blenders competing on price-accessible portfolios, and veterinary channel specialists authorizing therapeutic formulations. Strategic archetypes include scale-driven extrusion operators, halal-certified protein integrators, and prescription diet registrants. Competitive moves concentrate on local manufacturing incentives capture and MOHAP registration dossier accumulation.
Among multinational operators, Mars Petcare and Nestlé Purina PetCare exemplify scale-driven archetypes with established shelf presence across hypermarket and veterinary channels. Agthia Group occupies a position within the domestic blender tier, competing on price-accessible dry food portfolios. Eurovets Veterinary Suppliers represents the prescription channel specialist archetype, anchoring therapeutic diet authorization and recurring subscription models. These three entities collectively illustrate the competitive segmentation between mass-market volume and premium-margin clinical positioning.
| Leading Market Players |
|---|
| Agthia Group |
| Armitage Pet Care |
| Mars Petcare |
| United Petfood |
| Ainawi Group |
| Nestlé Purina PetCare |
| Del Monte |
| Eurovets Veterinary Suppliers |
| Hill's Pet Nutrition |
| Others |
Cost & Logistics Intelligence
Family-owned protein rendering operations in Jebel Ali anchor mid-tier supply, translating feedstock cost discipline into price stability for bulk dry food while multinational operators extract premium through halal-certified therapeutic formulations. Sovereign-backed manufacturing incentives in Khalifa Industrial Zone are compressing landed-cost advantages for import-dependent distributors.
Pricing Analysis
Veterinary consultation bundling separates prescription diet pricing from unbundled retail formats, with Eurovets channels capturing recurring subscription value through clinical trial-backed authorization. Three-tier pricing structure across premium, standard, and economy levels stratifies by halal certification grade and Arabic-label compliance investment. Cost compression in mid-tier extruded kibble is intensifying because Thai and EU import dependency exposes blenders to shipping volatility. Mass-market purchasers in Sharjah industrial zones exhibit highest price sensitivity; Emirates Hills multi-pet households show least.
Supply Chain Analysis
Poultry meal and fishmeal supply rests on integrated abattoirs in Brazil, Thailand, and the EU, with rendered proteins feeding Jebel Ali extrusion facilities. Extrusion equipment, laminated packaging films, and vitamin premixes constitute critical input dependencies. Single-source vulnerability concentrates in EU-sourced therapeutic diet formulations subject to MOHAP registration delays. Distribution runs through hypermarket loyalty programs and veterinary clinic subscription networks, with cold chain fragmentation limiting wet food reach beyond Dubai and Abu Dhabi metropolitan zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MOHAP's 2024 veterinary product registration framework functions as a cost-of-compliance moat, elevating R&D investment requirements that filter out speculative entrants while rewarding dossier-capable incumbents with prescription channel access.
For Market Incumbents: Lock in veterinary nutritionist talent through Dubai-based consultancy partnerships to secure therapeutic diet authorization pipelines. Accumulate MOHAP registration dossiers for functional treat categories before halal-certified competitors replicate Mars Petcare's shelf presence. Emerging domestic blenders with sovereign-backed capital subsidies threaten mid-tier margin compression. For New Entrants and Emerging Players: Subscription-based digital channels in Palm Jumeirah and Dubai Marina offer lowest customer acquisition friction among time-constrained expatriate professionals. Northern Emirates pet retail clusters in Ajman and Ras Al Khaimah present first-mover white space for price-accessible dry food with localized Arabic labeling. Target staff-assisted pet shop consultation as the go-to-market anchor for trial conversion. For Investors and Strategic Acquirers: Eurovets Veterinary Suppliers consolidating supplier relationships around registrants with established dossier capabilities is the leading indicator that prescription channel economics are hardening. Five-to-ten year viability favors halal-certified protein integrators with backward rendering capacity. Watch MOHAP feed additive approval expansions as the inflection signal for local manufacturing incentive capture.| Strategic Initiative | Industry Significance |
|---|---|
| MOHAP Registration Dossier Accumulation | Clinical trial-backed therapeutic claims unlock Eurovets prescription channel recurring revenue. |
| Backward Integration into Protein Rendering | Khalifa Industrial Zone subsidies reduce exposure to Thai and EU import tariff volatility. |
| Functional Treat Production Investment | Dental and joint-support additive categories remain underdeveloped relative to European benchmarks. |
| Subscription-Based Replenishment Launch | Automated delivery algorithms capture Palm Jumeirah multi-pet household lifetime value. |
| Arabic Labeling Compliance Pre-Build | Dual-language packaging assets accelerate northern emirates distribution penetration. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across veterinary clinic operators, pet shop proprietors, hypermarket category buyers, extrusion facility managers, and MOHAP registration consultants. Bottom-up demand modeling triangulated against top-down value chain analysis using Emirates Authority for Standardization and Metrology halal certification databases, MOHAP veterinary product registries, and Jebel Ali Free Zone investment disclosures.
Product type, animal species, distribution channel, and customer procurement scale were modeled at segment-level granularity across the analysis window. CAGRs derived from historical volume trajectories projected through elasticity-adjusted demand curves incorporating disposable income growth in Dubai and Abu Dhabi, therapeutic diet authorization rates through Eurovets channels, and local manufacturing capacity buildout in Khalifa Industrial Zone.
The model holds under stable MOHAP registration timelines and halal certification throughput; deviation in feed additive approval delays or cold chain infrastructure investment shortfalls would shift volume assumptions. Forecasts reflect documented base conditions with acknowledged sensitivity to import cost volatility and sovereign subsidy program continuity. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
United States Organic and Natural Pet Food Market
Pet Care Products
Raw Pet Food Market
Pet Care Products
Dog Food and Snacks Market
Pet Care Products
Dog Muzzle Market
Pet Care Products
Cat Litter Product Market
Pet Care Products
Disposable Absorbent Pet Pad Market
Pet Care Products
Paw Plunger Market
Pet Care Products
Asia-Pacific Pet Treats Market
Pet Care Products
Mink Oil Market
Pet Care Products
Flea, Tick, and Heartworm Products Market
Pet Care Products
Hair Dryer for Pets Market
Pet Care Products
Dog Vest Market
Pet Care Products
Pet Grooming Gloves Market
Pet Care Products
Cat Mat Market
Pet Care Products
Smart Dog Collar Market
Pet Care Products
Dog Clothing and Accessories Market