
 Organic Pet Food Market | 2026-2036
Organic Pet Food Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Pet Food Market Intelligence
Heightened consumer scrutiny over ingredient sourcing, reinforced by certifications like the USDA National Organic Program, is restructuring demand patterns. This shift favors brands with transparent supply chains, where WellPet leverages its brand presence in specialty retail. Newman's Own differentiates through its focus on organic ingredients and philanthropic initiatives, while Blue Buffalo competes with a broad portfolio.
Organic pet food refers to animal nutrition products manufactured using ingredients grown without synthetic pesticides, fertilizers, or genetic modification. These formulations must adhere to strict production and handling standards, often involving certified organic meat, grains, and vegetables to ensure purity. Dry food formulations continue to dominate sales volume due to shelf stability, while the wet food category represents a premium, high-margin segment. Demand from dog owners currently outpaces that from cat owners, but the latter shows accelerated interest in specialized organic options.
The USDA's National Organic Program in the United States and the EU's organic farming regulations provide the primary legal frameworks for certification and labeling. These standards govern everything from ingredient sourcing to processing facilities, creating significant barriers to entry for new participants. For manufacturers, navigating the fragmented landscape of international organic certifications while managing supply chain integrity remains a critical strategic challenge.
Market Dynamics
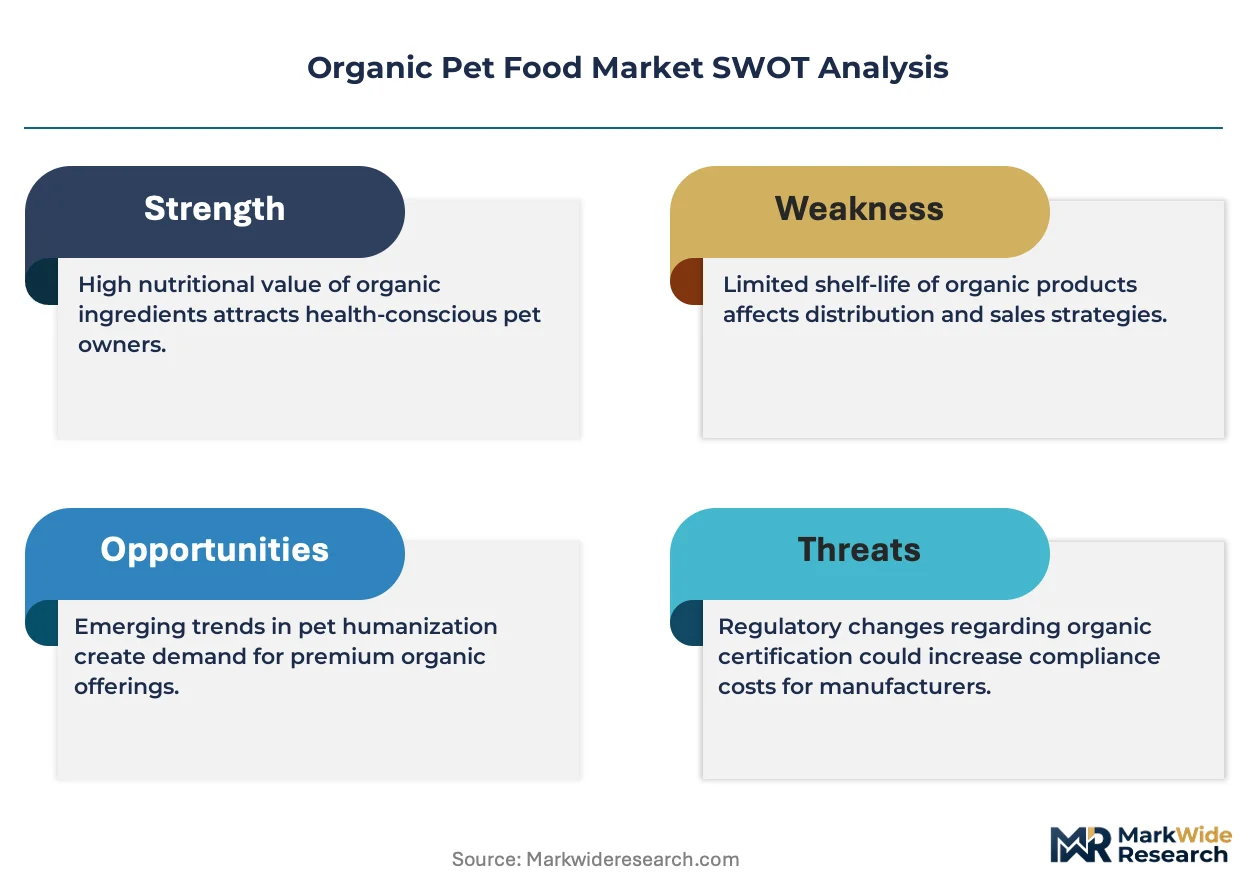
Heightened consumer demand for ingredient transparency, anchored by government-backed certification, is the central force structuring the organic pet food market. This pressure compels manufacturers to verify supply chain integrity from farm to bowl, directly influencing formulation, labeling, and brand positioning.
Growth Catalysts
- Humanization of Pets:A growing tendency among owners to view pets as family members is driving spending on premium, human-grade foods, particularly for dogs in affluent metropolitan areas of the United States and Germany.
- Regulatory Frameworks:The USDA's National Organic Program and corresponding EU organic farming regulations provide clear, enforceable standards that build consumer trust and justify premium pricing for certified products.
- E-commerce Expansion:The proliferation of online retailers and direct-to-consumer subscription services makes niche organic products more accessible to a wider consumer base, bypassing traditional retail limitations.
Market Restraints
- Input Cost Volatility:Manufacturers face significant margin pressure from fluctuating prices of key inputs like certified organic meats and grains, which are subject to weather and variable agricultural yields.
- Fragmented Ingredient Supply:The limited number of certified organic farms creates a constrained supply chain, leading to potential sourcing bottlenecks and high dependency on a few key agricultural producers.
- Certification Hurdles:The substantial cost, extensive documentation, and rigorous inspections required to obtain and maintain organic certification from bodies like the USDA act as a major barrier to entry for smaller brands.
Strategic Opportunities
- Specialized Formulations:There is a clear opportunity in developing organic diets for pets with specific health issues, such as allergies or digestive sensitivities, especially for the underserved but fast-growing cat food segment.
- Alternative Protein Sources:Incorporating novel, certified organic proteins, including insects or yeast-based ingredients, can appeal to consumer demand for sustainable and ethical sourcing.
- Geographic Expansion:Penetrating markets in Asia-Pacific, where a rising middle class is beginning to adopt premium pet care habits, represents a significant long-term growth vector.
Industry Challenges
- Supply Chain Integrity:Ensuring end-to-end traceability and preventing fraudulent organic claims across a global network of suppliers remains a persistent and complex operational challenge for manufacturers.
- Consumer Education Gap:Differentiating the benefits of "certified organic" from vaguer marketing terms like "natural" or "holistic" requires sustained investment in marketing to justify the higher price point.
- Processing Segregation:Maintaining separate production lines and handling protocols to prevent cross-contamination between organic and conventional products requires significant capital investment in dedicated facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Pet Food Market |
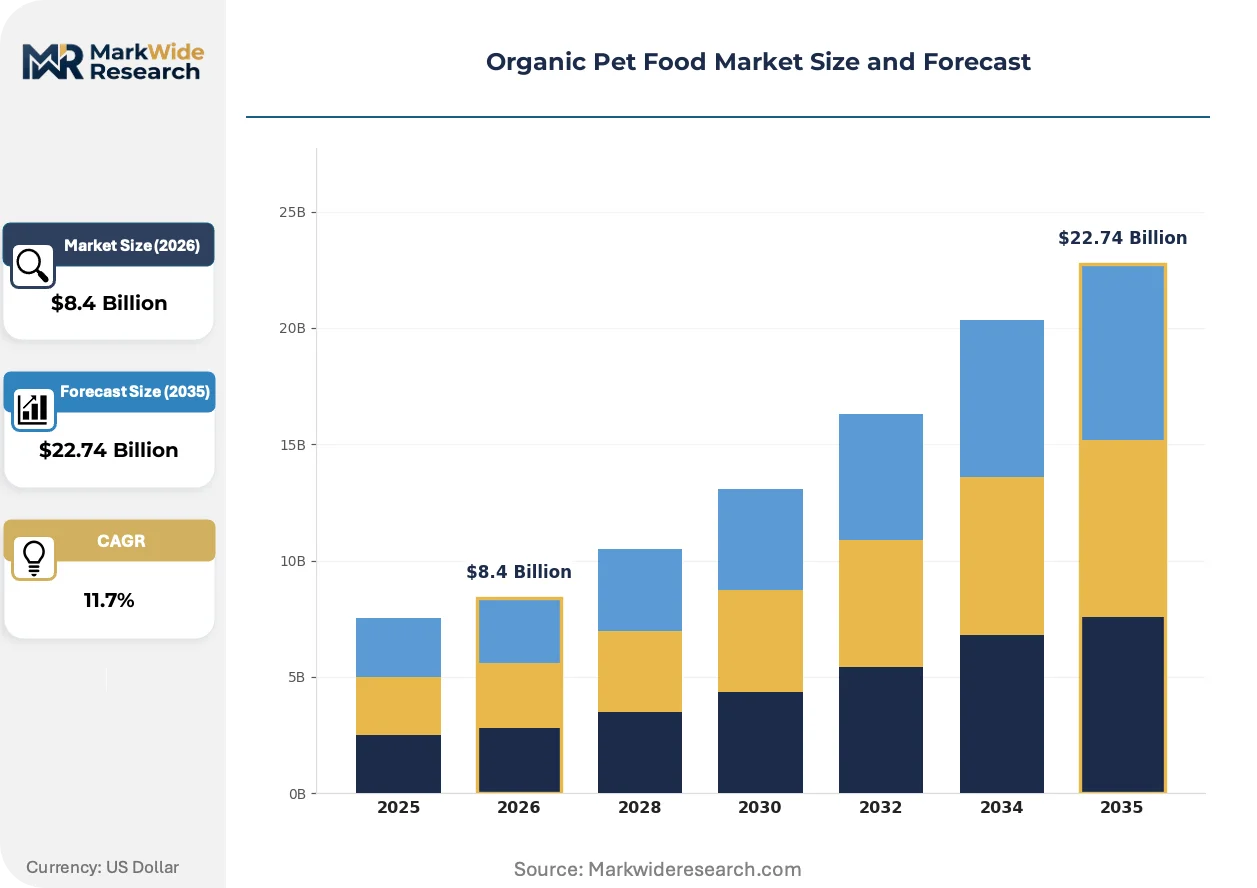
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $22.74 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Treats, Supplements End User: Dog Owners, Cat Owners, Retailers, Veterinarians Distribution Channel: Online Stores, Supermarkets, Specialty Pet Stores, Veterinary Clinics Ingredient Source: Meat, Vegetables, Grains, Fruits |
| Companies Covered | PetGuard, Natural Planet Pet Foods, Newman's Own, Blue Buffalo, Evanger's, Organic Pet Boutique, Dr. Geoff's Real Food, WellPet, Party Animal, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Pet Food Market Strategic Shifts & Innovations
Technological advancements in food preservation and processing are converging with evolving consumer ethics around sustainability. These shifts are creating new product categories and business models, fundamentally changing how organic pet food is produced, marketed, and sold.
High-Pressure Processing (HPP) is a non-thermal pasteurization method that preserves the nutritional value and sensory qualities of raw ingredients. Premium brands are adopting HPP for their refrigerated and fresh pet food lines to satisfy owner demand for less-processed options. This cold pasteurization technology is overtaking traditional heat-based sterilization for high-margin products, enabling a new class of nutrient-dense organic pet foods.
The EU's Farm to Fork strategy, a core component of the European Green Deal, mandates an increase in land dedicated to organic farming. This policy is designed to bolster the regional supply of certified organic ingredients, reducing reliance on imports for European pet food manufacturers. Companies in Germany and France are most impacted, benefiting from more stable local supply chains but also facing stricter sustainability and reporting obligations under the new framework.
Direct-to-consumer (DTC) subscription services offering customized organic meal plans are disrupting traditional retail channels. These platforms use online questionnaires to tailor food formulations to a pet's specific attributes, such as breed, age, and activity level, delivering pre-portioned meals directly to the customer. This model is gaining significant traction in urban centers across the United States, where convenience and personalization are key purchasing criteria.
Organic Pet Food Market Segmentation
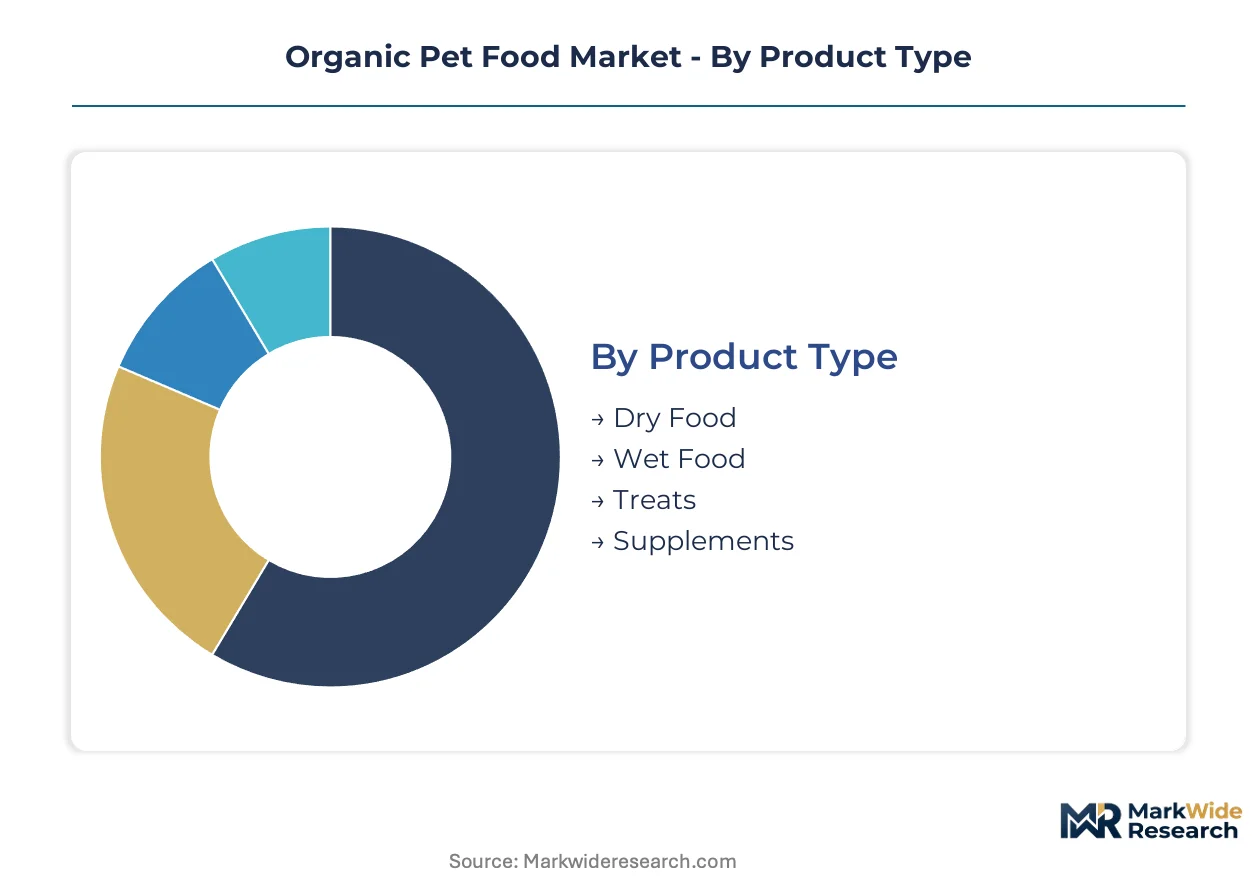
Understanding the varied segments within the organic pet food market is crucial for identifying areas of investment and strategic focus. Each segment presents unique operational demands and consumer preferences, influencing product development and market penetration strategies for manufacturers.
Product Type:
The initial capital outlay for production facilities varies significantly across product types within the organic pet food market.
- Dry Food:These formulations typically involve extrusion processes, resulting in low moisture content and extended shelf life. Demand from dog owners in the United States and Germany heavily concentrates on dry organic options due to convenience and cost-effectiveness.
- Wet Food:Characterized by high moisture content, wet food often comes in cans or pouches, representing a premium, high-margin segment. This product type sees significant demand from cat owners, particularly in urban areas seeking less processed options.
- Treats:These complementary products serve as rewards or training aids, formulated with organic ingredients.
- Supplements:Organic supplements provide targeted nutritional support for pets with specific health needs.
Most installed capacity flows through Dry Food. Expansion is steepest in Wet Food.
End User:
Understanding the end-user base reveals distinct purchasing behaviors and price sensitivities for organic pet food products.
- Dog Owners:These consumers increasingly view pets as family members, driving spending on premium, human-grade organic foods. Demand is strongest in affluent metropolitan areas of the United States and Germany.
- Cat Owners:This segment shows accelerated interest in specialized organic options, particularly for high-margin wet food products. Demand for specific dietary needs is growing among cat owners.
- Retailers:These entities serve as intermediaries, influencing brand visibility and product accessibility across various channels.
- Veterinarians:They recommend specialized organic diets for health-conscious pet owners, influencing purchasing decisions for therapeutic products.
The largest volume of organic pet food sales targets Dog Owners. The segment expanding most quickly is Cat Owners.
Distribution Channel:
The choice of distribution channel significantly impacts market reach and operational costs for organic pet food manufacturers.
- Online Stores:These platforms offer unparalleled convenience, a wider product selection, and direct-to-consumer subscription services. Demand for customized organic meal plans is gaining traction in urban centers across the United States.
- Supermarkets:These channels provide mass market accessibility and convenience for general pet owners. They serve as a primary point of purchase for many consumers seeking organic options.
- Specialty Pet Stores:These stores offer curated selections of premium organic pet food and expert advice.
- Veterinary Clinics:These facilities distribute therapeutic or specialized organic diets, often recommended by pet health professionals.
The widest market penetration occurs through Supermarkets. Online Stores sales channels are gaining share fastest.
Ingredient Source:
Ingredient sourcing dictates both product formulation and supply chain complexity within the organic pet food sector.
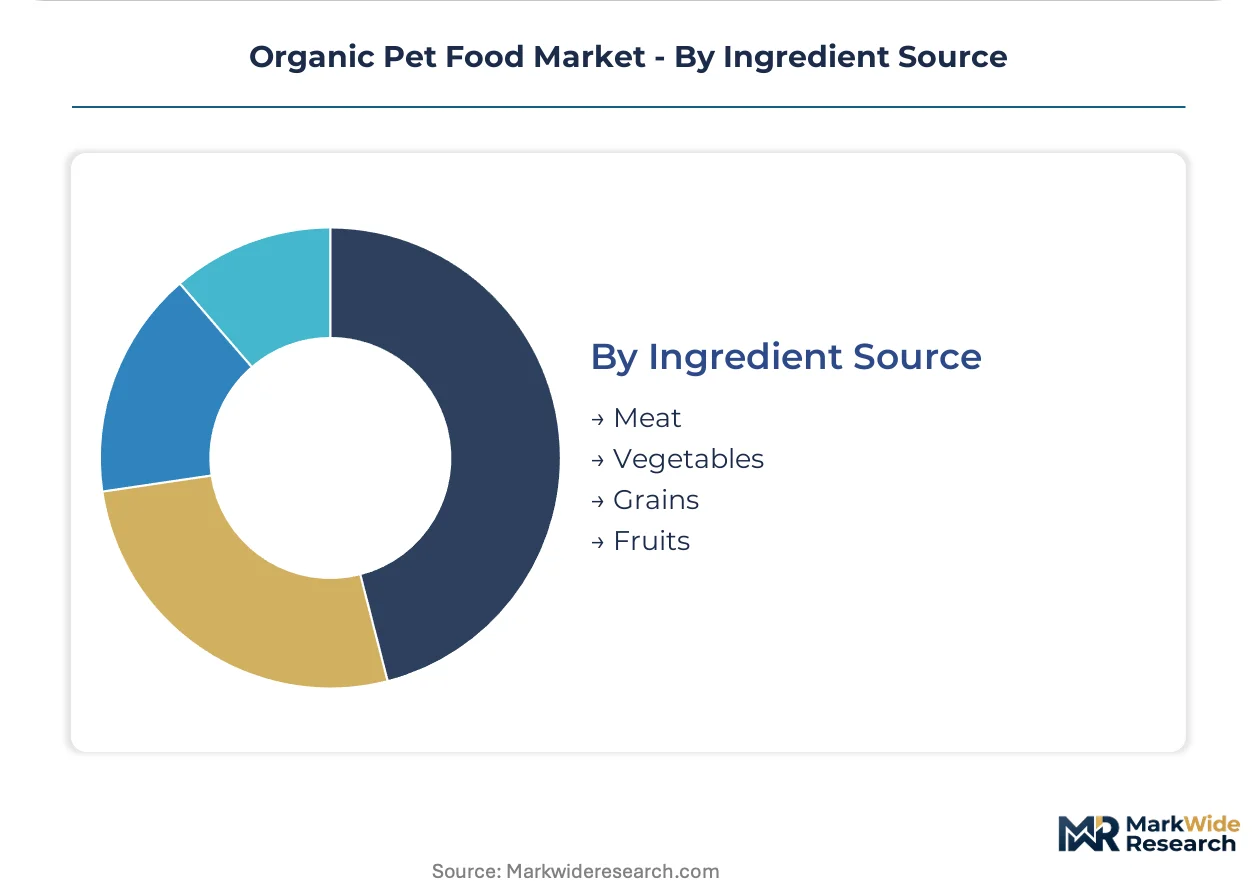
- Meat:This represents a core protein source for many organic pet food formulations, subject to input cost volatility. Sourcing relies on a limited number of certified organic farms.
- Vegetables:These ingredients provide essential vitamins, minerals, and fiber in organic pet food. Sourcing often benefits from regional organic farming regulations, particularly in the EU.
- Grains:Organic grains offer carbohydrate energy and texture to dry pet food formulations.
- Fruits:Used for natural flavors, antioxidants, and nutritional enhancement in organic pet food products.
The largest volume of raw material procurement focuses on Meat. Demand for certified Vegetables is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Organic pet food traces its origins to consumer demand for natural ingredients. This segment gained traction as pet owners increasingly viewed their animals as family members. Early adoption of organic principles in pet nutrition began in developed Western markets.
United States
Dog owners in the United States drive significant demand for human-grade organic pet foods. The USDA National Organic Program provides stringent regulatory oversight for product certification. Urban centers like New York and Los Angeles exhibit high adoption rates for premium organic pet food selections.
Germany
Consumer spending on premium pet products in Germany supports a robust organic pet food market. EU organic farming regulations govern ingredient sourcing and product formulation. Metropolitan areas such as Berlin and Munich concentrate substantial organic pet food consumption.
France
The EU's Farm to Fork strategy aims to bolster local organic ingredient supply for French manufacturers. Strict EU organic farming regulations influence production standards across the country. Paris and Lyon are key centers for the distribution of specialized organic pet food products.
United Kingdom
Growing interest in transparently sourced pet foods fuels demand for organic options in the United Kingdom. The Food Standards Agency (FSA) oversees organic food standards and labeling. The London metropolitan area shows high spending on premium organic pet food varieties.
Japan
Rising middle-class adoption of premium pet care habits drives interest in organic pet foods in Japan. The Ministry of Agriculture, Forestry and Fisheries (MAFF) sets national organic standards. Tokyo and Osaka urban centers exhibit increasing demand for specialized organic pet food options.
Organic Pet Food Market Key Industry Players
Capital-heavy producers compete with asset-light designers for market share. The organic pet food market exhibits a tiered structure, from large diversified brands to specialized niche players. Strategic archetypes include established conventional pet food companies diversifying into organic, pure-play organic specialists, and direct-to-consumer innovators. Dominant competitive moves involve portfolio diversification and strategic partnerships to secure organic ingredient supply.
Within the philanthropic and organic ingredient-focused tier, Newman's Own exemplifies a brand leveraging its mission for market differentiation and consumer trust. Blue Buffalo represents a large-scale player with a broad product portfolio, effectively integrating organic options into its extensive lines to cater to a wider consumer base. WellPet occupies a position among brands emphasizing transparent supply chains and a strong presence in specialty retail, appealing to discerning pet owners seeking premium, certified products. These companies collectively illustrate the varied approaches to market penetration and brand positioning within the organic pet food sector.
| Leading Market Players |
|---|
| PetGuard |
| Natural Planet Pet Foods |
| Newman's Own |
| Blue Buffalo |
| Evanger's |
| Organic Pet Boutique |
| Dr. Geoff's Real Food |
| WellPet |
| Party Animal |
Cost & Logistics Intelligence
Captive supply of certified organic inputs anchors both ingredient availability and premium pricing power within the organic pet food market. This strategic control over sourcing directly influences a manufacturer's ability to maintain consistent product quality and justify higher retail prices.
Pricing Analysis
A tiered pricing structure across premium, standard, and economy levels characterizes the organic pet food market. Price differentiation stems from the specific organic certification level, such as USDA Organic, and the established brand premium associated with transparent supply chains. Pricing pressure stems from input cost volatility for certified organic meats and grains, especially in the standard product tiers. Dog owners in metropolitan areas exhibit lower price sensitivity for human-grade options, while general supermarket consumers remain highly price-conscious.
Supply Chain Analysis
Workforce availability for organic agricultural practices in the United States and Germany influences the upstream supply of organic pet food ingredients. The supply chain for organic pet food concentrates on certified organic farms primarily in the US and EU, particularly for essential inputs like organic meats, grains, and vegetables. Commodity price volatility for these specialized organic inputs represents a significant structural risk. Distribution runs through a hybrid model, combining mass-market supermarkets with expanding online stores and specialized pet retailers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The organic pet food market presents a geographic-arbitrage opportunity, given the cost differential between sourcing certified organic ingredients in the EU due to Farm to Fork policies versus reliance on imports in other regions.
For Market Incumbents: Anchor supply chain integrity by investing in long-term contracts with certified organic farms, particularly in the EU where Farm to Fork policies bolster local supply. Diversify product portfolios with specialized organic formulations for cats to counter margin pressure from emerging "natural" brands. Expand processing segregation capabilities to prevent cross-contamination, protecting brand reputation and USDA National Organic Program certification.
For New Entrants and Emerging Players: Online retailers offer a direct path to market entry for niche organic pet food brands, bypassing traditional distribution hurdles. Target the underserved cat owner segment with novel alternative protein sources, such as insect-based organic options, focusing on digestive sensitivities. Leverage subscription services to build customer loyalty in urban centers, emphasizing customization and convenience as key go-to-market angles.
For Investors and Strategic Acquirers: Consolidation pressure builds where certified organic ingredient supply remains fragmented and costly, favoring players with established procurement networks. Long-term viability over a five-to-ten year window favors brands with strong regulatory compliance and transparent supply chains. Seek acquisition targets with proprietary HPP technology or direct-to-consumer platforms to capture premium market share. The signal to watch is the sustained growth in online subscription service penetration in new metropolitan areas.
| Strategic Initiative | Industry Significance |
|---|---|
| Secure Long-Term Organic Ingredient Contracts | Stabilizes input costs for manufacturers and ensures supply chain integrity for certified products. |
| Invest in High-Pressure Processing (HPP) Technology | Enables premium refrigerated pet food lines, satisfying owner demand for less-processed options. |
| Expand Direct-to-Consumer (DTC) Subscription Services | Reaches urban consumers seeking customized organic meal plans and personalized pet nutrition. |
| Develop Specialized Organic Cat Food Formulations | Addresses accelerated interest from cat owners in specialized organic options for specific dietary needs. |
| Geographic Expansion into Asia-Pacific Markets | Leverages rising middle-class pet care spending, particularly in Japan and other emerging economies. |
Research Approach
Multiple input streams — primary interviews, secondary research, and market intelligence databases — were reconciled for this analysis. Primary insights gathered from pet food manufacturers, specialty retailers, veterinarians, and organic farmers provided qualitative depth. Secondary validation drew from USDA National Organic Program documents, EU organic farming regulations, and industry trade publications. Bottom-up data aggregation and top-down market sizing ensured robust triangulation.
Data-stream reconciliation informed the analytical framework across the analysis window, integrating historical trends with future projections. Segmentation dimensions modeled included product type, end user, distribution channel, ingredient source, and geographical region. Compound Annual Growth Rates were derived from historical market performance and projected industry dynamics. Pet ownership rates and organic certification costs served as key industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory changes and agricultural yields. Forecasts reflect assumptions concerning market dynamics and consumer spending shifts. Material deviation in these named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Smart Cat Eye Market
Pet Care Products
Cat Window Perches and Wall Shelves Market
Pet Care Products
Indonesia Pet Food Market
Pet Care Products
UK Pet Boarding Market
Pet Care Products
Automatic Cat Feeder Market
Pet Care Products
Pet Meal Kit Delivery Services Market
Pet Care Products
DTC Pet Food Market
Pet Care Products
Dog Water Bottle Market
Pet Care Products
Spain Pet Boarding Market
Pet Care Products
Japan Pet Food Market
Pet Care Products
Organic and Natural Dog Foods Market
Pet Care Products
Kitten Milk Replacer and Formula Market
Pet Care Products
Dog Bowl Market
Pet Care Products
Pet Stairs Market
Pet Care Products
Asia-Pacific Pet Travel Services Market
Pet Care Products
Saudi Arabia Dog Food Market