
 Cat Calming Treats Market | 2026-2036
Cat Calming Treats Market Size, Share, and Industry Trends Forecast 2026-2036
Cat Calming Treats Market Insights
Pet owner purchasing power is decoupling from traditional veterinary gatekeepers as direct-to-consumer channels capture growing share of calming treat transactions. Nestlé Purina Petcare leverages its retail shelf dominance to anchor mainstream distribution in mass-market outlets. PetHonesty competes through subscription-based models that sustain recurring revenue and deepen customer retention. Virbac differentiates by positioning its formulations within professional veterinary channels where clinical credibility commands premium positioning.
Cat calming treats are functional nutritional supplements formulated with bioactive compounds such as L-theanine, chamomile extract, or valerian root, typically delivered via palatable matrices designed for voluntary feline consumption and intended to modulate stress responses without prescription pharmacological intervention. Soft chews dominate volume due to their moisture content and palatability advantages over tablets, while CBD-infused variants represent the fastest-growing active ingredient segment despite lingering regulatory ambiguity. Distribution through pet specialty stores captures the highest margin pool as educated staff drive conversion for premium formulations, whereas online retail extends reach to subscription-dependent repeat buyers seeking convenience.
FDA Center for Veterinary Medicine scrutiny of structure-function claims shapes product labeling and marketing permissible on packaging and digital channels. The National Animal Supplement Council guidelines further constrain how manufacturers communicate efficacy, creating compliance thresholds that favor established players with regulatory affairs infrastructure. Stakeholders must monitor evolving state-level CBD permissibility frameworks and veterinary telehealth expansion, as both forces will determine whether prescription-free calming solutions retain their market position against reinvigorated pharmaceutical alternatives.
Market Dynamics
Direct-to-consumer distribution channels are eroding veterinary gatekeeper control over calming treat access, while FDA Center for Veterinary Medicine scrutiny of structure-function claims forces manufacturers to rebuild labeling compliance infrastructure from the ground up.
Growth Catalysts
- Veterinary telehealth expansion:Remote consultation platforms in the United States normalize prescription-free anxiety management recommendations, channeling cat owners toward over-the-counter calming solutions without clinic visits.
- L-theanine formulation advances:Purified amino acid extraction methods from green tea sources improve bioavailability in feline metabolism, elevating efficacy claims above herbal competitor products.
- Subscription commerce infrastructure:Automated replenishment platforms lock in recurring revenue streams while reducing customer acquisition costs through predictive reorder algorithms.
Market Restraints
- CBD regulatory ambiguity:State-level permissibility fragmentation across the United States creates compliance patchwork that elevates legal risk for interstate distribution of hemp-derived active ingredients.
- Palatability R&D concentration:Flavor masking expertise for bitter botanical compounds clusters among three specialized suppliers, creating input bottleneck vulnerability.
- Prescription anxiolytic substitution:Generic fluoxetine and gabapentin formulations maintain veterinary preference for severe anxiety cases, capping addressable market for nutraceutical alternatives.
Strategic Opportunities
- Senior feline demographic expansion:Geriatric cat populations in Japan and Western Europe drive demand for cognitive dysfunction syndrome adjunct therapies combining calming with nootropic actives.
- Pet specialty staff education investment:Trained floor associates at independent retailers convert premium formulation trials at rates unmatched by mass-market self-service aisles.
- National Animal Supplement Council certification:Third-party quality seals differentiate compliant manufacturers in digital channels where direct claims face platform advertising restrictions.
Industry Challenges
- Veterinary nutritionist talent scarcity:Feline-specific formulation expertise commands premium compensation, constraining mid-tier manufacturer R&D pipeline velocity.
- Stability testing timeline compression:Accelerated shelf-life validation for novel delivery matrices (extruded strips, lickable pastes) extends product development cycles beyond typical supplement category norms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cat Calming Treats Market |
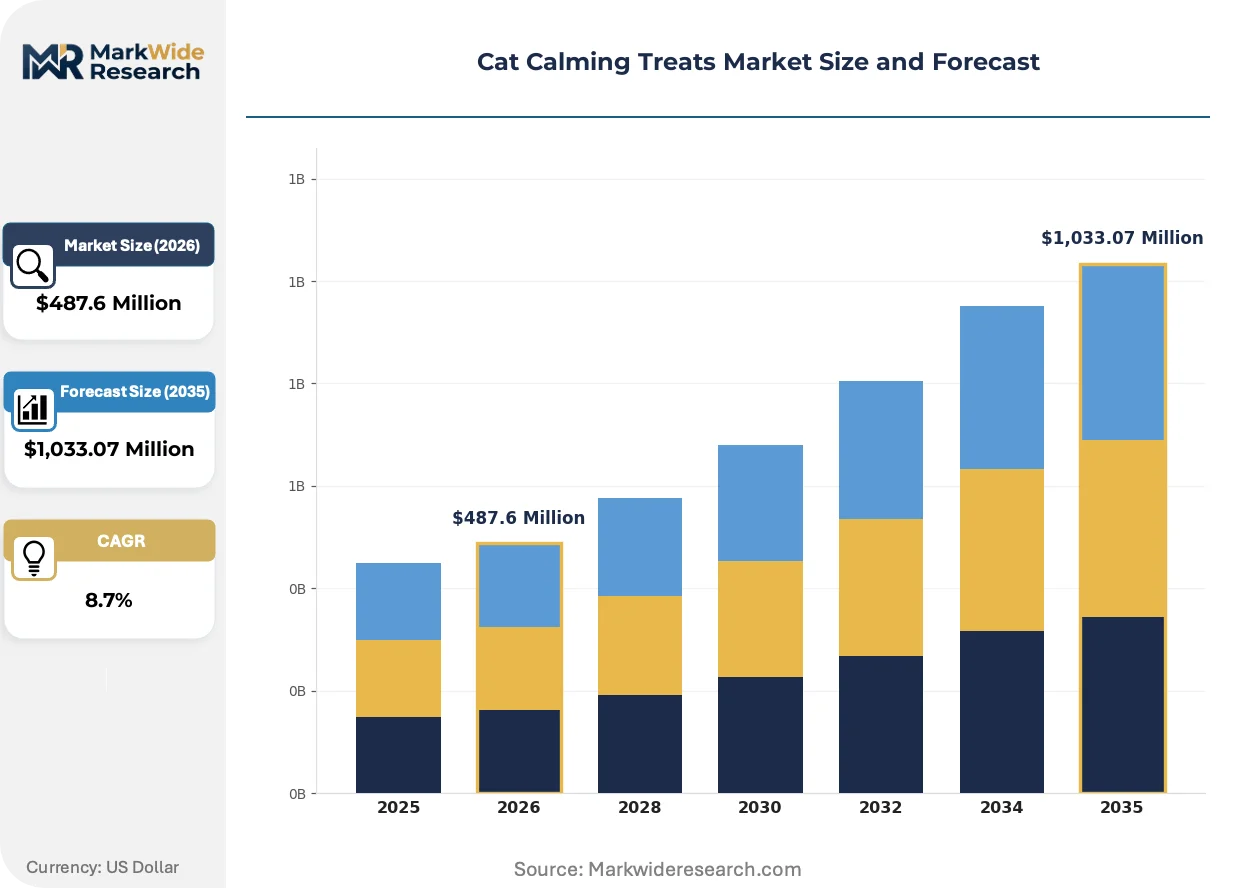
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soft Chews, Crunchy Treats, Liquid Formulas, Tablets Active Ingredient: Chamomile, L-Theanine, Valerian Root, CBD Distribution Channel: Online Retail, Pet Specialty Stores, Supermarkets, Veterinary Clinics Target Age Group: Kittens, Adult Cats, Senior Cats, All Ages |
| Companies Covered | Nestlé Purina Petcare, PetHonesty, Zesty Paws, Virbac, Zoetis Inc., PetIQ, LLC., CEVA (ADAPTIL), GARMON CORP. (NaturVet), NOW Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cat Calming Treats Market Trends and Innovations
Functional treat matrices are absorbing pharmaceutical-grade delivery technologies as human supplement manufacturing capabilities migrate into pet-focused production facilities, compressing the quality gap between species-specific formulations.
Microencapsulation technology for volatile botanical actives is consolidating competitive positioning among manufacturers with access to spray-drying equipment capable of protecting heat-sensitive compounds through extrusion processing. Premium private-label suppliers in the United States and Germany are adopting these methods to extend proven stability claims from 12 to 24 months. The capital barrier is compressing mid-tier competitors into contract manufacturing relationships or exit.
FDA Center for Veterinary Medicine draft guidance on structure-function claims is tightening permissible language for stress and anxiety-related marketing, forcing reformulation of packaging and digital advertising assets across the category. Manufacturers must now distinguish between behavioral support and therapeutic intent with precision that elevates legal review costs. Direct-to-consumer brands with lean compliance infrastructure face disproportionate adaptation burden compared to established players with in-house regulatory affairs teams.
Subscription-dependent repeat purchasing is displacing episodic retail buying as the dominant replenishment model for multi-cat households with chronic anxiety management needs. Chewy and Amazon Subscribe & Save capture the bulk of this behavioral shift, while independent pet specialty retailers respond with loyalty program investments. The pattern concentrates most visibly in coastal United States metropolitan markets where delivery density supports same-day fulfillment economics.
Cat Calming Treats Market Segmentation
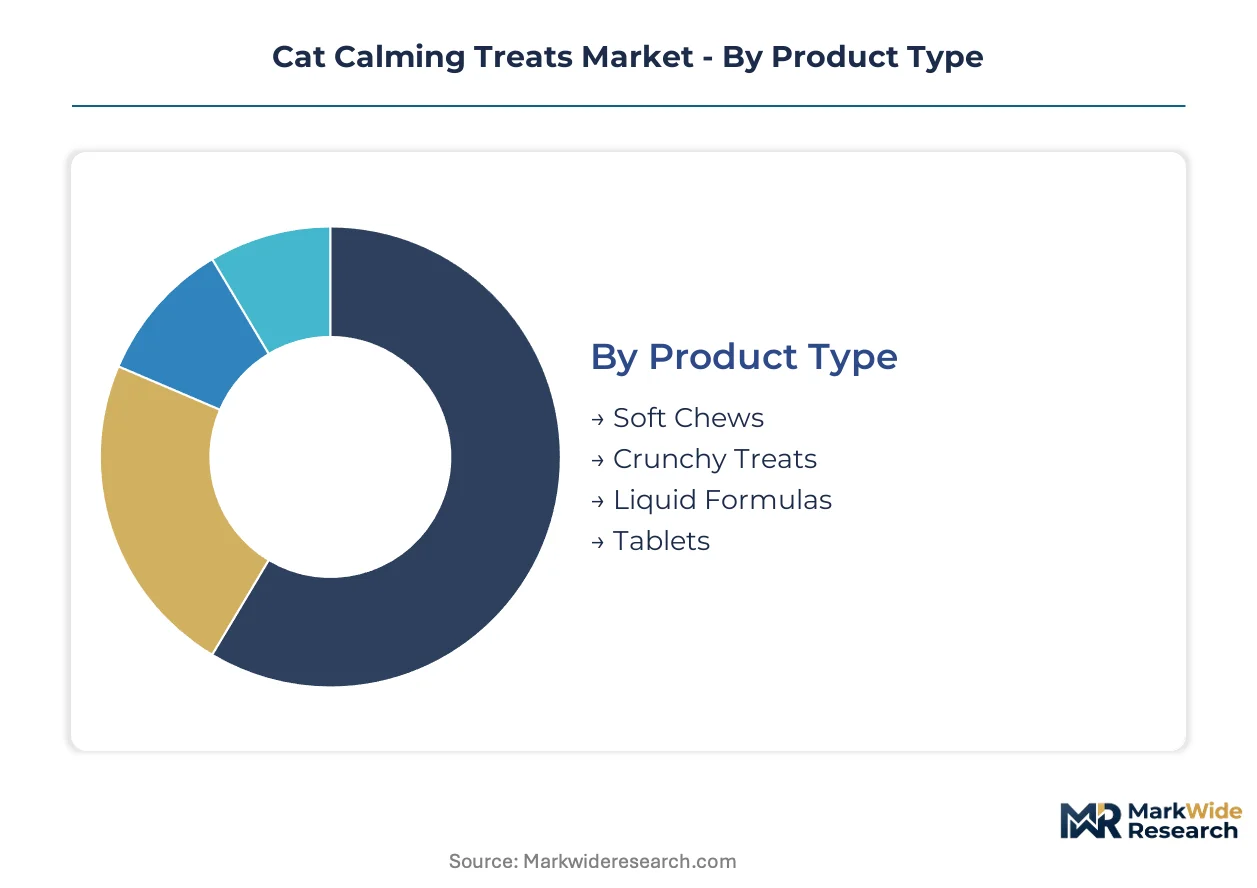
Segmentation in the cat calming treats market reveals how formulation chemistry, delivery mechanics, and purchase context combine to create distinct margin pools. Manufacturers must align R&D investment with the specific stress-response pathways and consumption preferences that define each buyer cohort.
Product Type:
Texture and moisture content differentiate buyers by feline palatability thresholds and owner administration convenience.
- Soft Chews:Moisture-rich matrices incorporating hydrocolloid gelling agents mask bitter botanical actives while enabling precise dosing. Demand concentrates in multi-cat United States households where daily administration routines favor grab-and-feed convenience over preparation time.
- Liquid Formulas:Aqueous suspensions with emulsified lipid carriers achieve rapid buccal absorption for acute stress events like veterinary transport. Coastal metropolitan markets with same-day delivery infrastructure drive subscription replenishment for this format.
- Crunchy Treats:Extruded kibble-based delivery systems leverage existing feline feeding rituals but sacrifice active ingredient stability to heat exposure during processing.
- Tablets:Compressed powder formulations requiring pill pockets or manual administration retain niche positioning among owners trained in veterinary medication techniques.
Soft chews lead volumes today; liquid formulas are gaining share fastest.
Active Ingredient:
Biochemical mechanism of action determines regulatory pathway and clinical credibility with veterinary professionals.
- L-Theanine:Purified amino acid isolated from Camellia sinensis leaf extract crosses the blood-brain barrier to modulate glutamate receptor activity. Japanese and Western European geriatric cat populations drive demand for cognitive dysfunction syndrome adjunct applications combining calming with nootropic effects.
- CBD:Hemp-derived cannabinoid formulations target the endocannabinoid system for anxiolytic effects without sedation. State-level permissibility fragmentation across the United States creates compliance patchwork that elevates legal risk for interstate distribution.
- Chamomile:Apigenin-rich floral extracts provide mild sedative properties through GABA receptor modulation, appealing to owners seeking recognizable botanical ingredients.
- Valerian Root:Valerenic acid-containing rhizome extracts produce pungent volatile compounds requiring aggressive flavor masking but offering rapid onset for acute anxiety episodes.
L-theanine formulations dominate current prescription-free recommendations; CBD represents the steepest expansion trajectory pending regulatory clarification.
Distribution Channel:
Channel selection reflects owner information-seeking behavior and the role of intermediary expertise in purchase validation.
- Pet Specialty Stores:Independent retailers with trained floor associates convert premium formulation trials through educated staff guidance. Staff education investment at these outlets sustains margin premiums unmatched by self-service environments.
- Online Retail:Chewy and Amazon Subscribe & Save capture automated replenishment for chronic anxiety management in multi-cat households. Predictive reorder algorithms lock in recurring revenue while compressing customer acquisition costs.
- Veterinary Clinics:Professional channel positioning commands premium pricing through clinical credibility, though telehealth expansion erodes gatekeeper control over access.
- Supermarkets:Mass-market shelf presence reaches episodic purchasers seeking immediate availability without specialty store travel.
Pet specialty stores anchor premium volume; online retail is climbing the fastest as subscription infrastructure matures.
Target Age Group:
Life-stage physiology dictates metabolic processing capacity and the specific stressors requiring intervention.
- Senior Cats:Geriatric feline populations with declining hepatic function require adjusted dosing protocols and cognitive dysfunction syndrome adjunct therapies. Japan and Western Europe drive demand for formulations combining calming actives with nootropic compounds.
- Adult Cats:Prime-age animals experiencing environmental stressors like relocation or new pet introduction represent the core volume base for standard calming applications.
- Kittens:Juvenile animals undergoing socialization windows require gentle formulation strength appropriate for developing neurological systems.
- All Ages:Universal formulations sacrifice age-specific optimization for manufacturing scale economies and simplified inventory management.
Adult cats sustain current volume leadership; senior cats are expanding most quickly as demographic aging accelerates in developed markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates premium feline wellness spending at levels unmatched by any other national market, while Japan's geriatric cat demographic creates specialized demand for cognitive-support formulations that blend calming actives with nootropic compounds.
United States
Coastal metropolitan markets from Seattle to Boston drive subscription-based replenishment through same-day delivery infrastructure, with multi-cat households normalizing daily calming treat administration. FDA Center for Veterinary Medicine oversight of structure-function claims tightens permissible packaging language, elevating compliance costs for direct-to-consumer entrants. Manufacturing clusters in the Midwest and Southeast supply extruded soft chew matrices to mass-market and specialty channels nationwide.
Japan
Geriatric feline populations exceeding twelve years of age generate sustained demand for L-theanine formulations positioned as cognitive dysfunction syndrome adjuncts. METI guidelines on functional food labeling extend to pet supplements, creating substantiation requirements that favor established domestic pharmaceutical manufacturers. Tokyo-Osaka corridor distribution networks prioritize veterinary clinic channels where clinical credibility commands premium positioning.
Germany
Independent pet specialty retailers in Bavaria and North Rhine-Westphalia convert premium formulation trials through educated floor staff, sustaining margin premiums above self-service environments. EFSA guidance on botanical extract safety influences permissible active ingredient lists for products distributed across EU member states. Baden-Württemberg manufacturing facilities specialize in microencapsulation equipment for volatile botanical compound stability.
United Kingdom
London and Southeast England metropolitan areas concentrate online retail penetration for subscription-dependent chronic anxiety management in multi-cat households. Veterinary Medicines Directorate oversight distinguishes between nutraceutical supplements and prescription anxiolytics, shaping permissible marketing claims. Midlands-based contract manufacturers supply private-label calming treats to supermarket and pet specialty chains.
Australia
Urban cat ownership restrictions in Sydney and Melbourne elevate demand for behavioral management solutions addressing indoor stressors. TGA consultation frameworks on CBD in animal health products create regulatory uncertainty that constrains hemp-derived active ingredient adoption. Victorian and New South Wales pet specialty retail chains invest in staff education programs to drive premium formulation conversion.
Cat Calming Treats Market Competitive Landscape
United States producers anchor the mass-market and direct-to-consumer tiers; European specialists hold veterinary-channel positioning through clinical credibility frameworks. The vendor base stratifies across three tiers: multinational consumer packaged goods conglomerates with retail shelf dominance, subscription-native digital brands with automated replenishment infrastructure, and professional veterinary pharmaceutical houses with prescription-adjacent positioning. Consolidation pressure concentrates among mid-tier contract manufacturers lacking proprietary delivery technology or regulatory affairs capacity. Dominant competitive moves include portfolio diversification into adjacent functional treat categories and strategic partnerships with flavor masking technology suppliers.
Within the multinational tier, Nestlé Purina Petcare exemplifies mass-market distribution scale, while Virbac occupies a position representing professional veterinary channel credibility. PetHonesty anchors the subscription-native archetype with recurring revenue infrastructure. These three entities collectively illustrate the strategic segmentation between retail dominance, clinical positioning, and digital-first customer retention models that define competitive dynamics across the category.
| Leading Market Players |
|---|
| Nestlé Purina Petcare |
| PetHonesty |
| Zesty Paws |
| Virbac |
| Zoetis Inc. |
| PetIQ, LLC. |
| CEVA (ADAPTIL) |
| GARMON CORP. (NaturVet) |
| NOW Foods |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between NASC-compliant premium formulations and unverified economy alternatives manifests in both pricing power and sourcing complexity. FDA Center for Veterinary Medicine substantiation requirements elevate compliance costs that concentrate among established manufacturers with regulatory affairs infrastructure, while contract manufacturers serving budget tiers face margin compression from input volatility.
Pricing Analysis
Capacity additions in the United States are reshaping price floors for extruded soft chew matrices as Midwest manufacturing clusters expand output. Three-tier pricing structure across premium, standard, and economy levels differentiates by certification grade and veterinary endorsement depth. Pricing pressure stems from palatability R&D concentration among three specialized flavor masking suppliers. Mass-market supermarket buyers exhibit highest price sensitivity; veterinary clinic channels demonstrate lowest sensitivity due to clinical credibility premiums.
Supply Chain Analysis
Regional distribution centers in the United States, Germany, and Japan anchor hub-and-spoke patterns for temperature-sensitive liquid formulations requiring cold chain integrity. Raw material dependencies center on green tea-derived L-theanine isolates, hemp biomass for CBD extraction, and proprietary hydrocolloid gelling agents. Single-source vulnerability clusters in spray-drying equipment for microencapsulation technology. Distribution runs through pet specialty retail networks for premium tiers and automated replenishment platforms for subscription-dependent households.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cat calming treats market functions as a stable compounder where recurring subscription revenue from multi-cat households generates predictable cash flow streams.
For Market Incumbents: Cement regulatory affairs capacity as a defensive moat against FDA Center for Veterinary Medicine structure-function claim tightening. Deepen backward integration into flavor masking technology to reduce supplier bottleneck exposure. Prioritize NASC certification investment to differentiate digital channel positioning where direct claims face platform advertising restrictions. For New Entrants and Emerging Players: The mid-tier price-point gap between Virbac-positioned veterinary premiums and mass-market economy alternatives offers white-space entry. Target senior feline cognitive dysfunction syndrome adjunct formulations in Japan and Western Europe where geriatric demographics concentrate. Pursue direct-to-consumer launch with automated replenishment infrastructure to capture subscription-dependent repeat buyers. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier contract manufacturers lack proprietary delivery technology or regulatory affairs capacity. Frame long-term viability around pharmaceutical-grade manufacturing migration into pet-focused production facilities. Monitor veterinary telehealth expansion rates as inflection indicator for prescription-free solution accessibility against reinvigorated pharmaceutical alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| NASC Certification Investment | Third-party quality seals differentiate compliant manufacturers in restricted digital advertising environments. |
| Microencapsulation Technology Acquisition | Spray-drying equipment access protects heat-sensitive botanical actives through extrusion processing. |
| Subscription Infrastructure Buildout | Automated replenishment platforms lock in recurring revenue while compressing customer acquisition costs. |
| Veterinary Channel Partnership | Professional positioning commands premium pricing through clinical credibility in telehealth expansion. |
| Senior Feline Formulation Extension | Geriatric cognitive dysfunction syndrome adjuncts capture aging demographic demand in Japan and Western Europe. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement captured formulation chemists at contract manufacturers, regulatory affairs directors at supplement houses, category buyers at pet specialty retailers, and veterinary telehealth platform operators. Secondary validation drew from FDA Center for Veterinary Medicine guidance documents, National Animal Supplement Council certification records, customs trade data for botanical extract imports, and Nielsen retail audit data. Bottom-up segment sizing and top-down macroeconomic triangulation anchored value estimates.
Segment-weighting approaches distributed volume across formulation chemistry, delivery mechanics, and purchase context dimensions. Active ingredient mechanism of action, texture and moisture content, distribution channel expertise requirements, and life-stage physiological targeting shaped the analytical framework across the analysis window. CAGRs derived from trend extrapolation of veterinary telehealth penetration, subscription commerce adoption curves, and geriatric feline demographic trajectories. Price elasticity assumptions incorporated palatability R&D cost pass-through and certification premium sustainability.
Caveats apply where FDA Center for Veterinary Medicine draft guidance finalization or state-level CBD permissibility shifts could materially shift the outlook. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and telehealth platform recommendation patterns. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Dog Seat Belt Market
Pet Care Products
Germany Pet Food Market
Pet Care Products
Thailand Pet Food Market
Pet Care Products
Pet Relaxants Market
Pet Care Products
Smart Pet Camera Market
Pet Care Products
Pet Jerky Treat Market
Pet Care Products
Dog Bathing Systems Market
Pet Care Products
Cat Food Toppers Market
Pet Care Products
Pet Bathing Supplies Market
Pet Care Products
South Africa Pet Training Services Market
Pet Care Products
Pet Toys Market
Pet Care Products
GPS Dog Collar Market
Pet Care Products
Interactive Dog Toys Market
Pet Care Products
Bird Toy Market
Pet Care Products
Dog Treats Market
Pet Care Products
Vegan Cat Food Market