
 UK Pet Treats Market | 2026-2036
UK Pet Treats Market Size, Share, and Industry Trends Forecast 2026-2036
UK Pet Treats Market Insights
FSA pet food labeling reform is realigning the cost-of-entry calculus for new treat manufacturers entering the UK market. Mars Incorporated leverages its veterinary nutrition heritage to sustain premium positioning across dental and functional treat lines. Lily's Kitchen competes through grain-free and organic formulations that command shelf space in Waitrose and Ocado. Pets Choice anchors private-label supply for major grocery multiples, extending manufacturing scale across its Lancashire production base.
UK pet treats comprise formulated edible products fed intermittently to companion animals, typically containing proteins, carbohydrates, and functional additives processed through extrusion, baking, or air-drying to achieve specified moisture content and texture profiles. Their primary commercial purpose centers on reward-based training, dental hygiene maintenance, and emotional bonding between owners and pets. Dental treats lead product type revenue pools due to recurring purchase frequency and veterinary endorsement, while functional ingredient formulations are expanding fastest as owners seek joint support, digestive health, and anxiety management claims. Online retailers are capturing disproportionate growth within distribution channels, driven by subscription models and direct-to-consumer brands that bypass traditional wholesale markups.
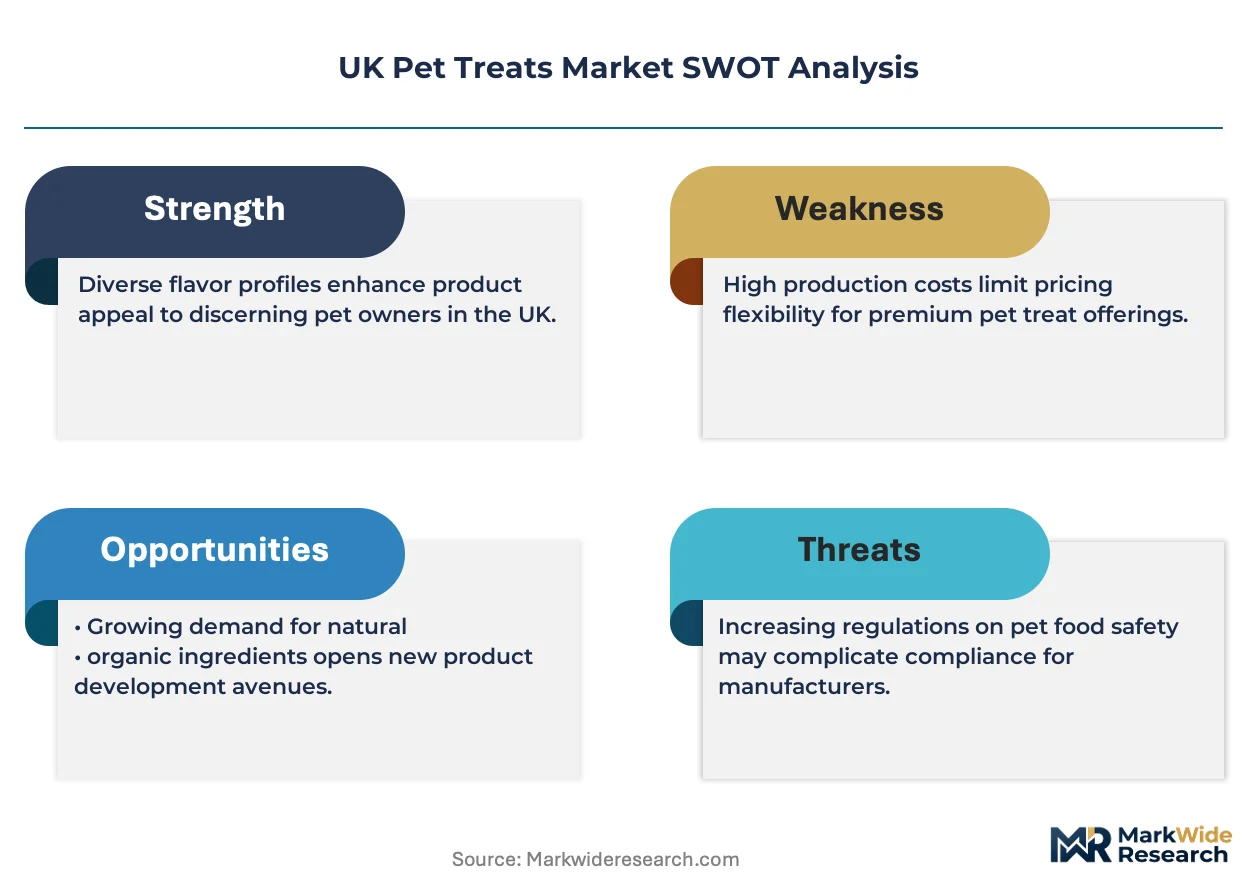
Defra, the FSA, and Trading Standards collectively enforce pet food safety through the Animal Feed Regulations and PFMA codes of practice, shaping product standards from raw material sourcing to finished-goods traceability. These frameworks elevate compliance burdens but simultaneously protect established operators with robust quality systems. Stakeholders must monitor evolving novel ingredient approvals and post-Brexit divergence from EU FEDIAF guidelines, as regulatory misalignment could fragment formulation strategies across UK and European production networks.
Market Dynamics
FSA labeling reform is compressing formulation timelines for UK treat manufacturers while millennial pet owners accelerate premiumization through human-grade ingredient demands.
Growth Catalysts
- The Animal Feed Regulations:Defra's traceability mandates elevate quality thresholds that favor manufacturers with integrated supply chains, filtering out marginal operators.
- Urban millennial pet ownership:London and South East concentration of dual-income households sustains premium price tolerance for functional and dental treat categories.
- Cold-pressed processing:Lower-temperature manufacturing preserves heat-sensitive nutrients, enabling novel protein claims that differentiate shelf positioning.
Market Restraints
- Raw material cost volatility:Poultry meal and salmon oil prices fluctuate with global aquaculture and avian supply disruptions, compressing margin predictability.
- Post-Brexit regulatory friction:Divergence from EU FEDIAF guidelines fragments formulation strategies for manufacturers operating UK and continental production networks.
- Substitution by fresh food:Raw feeding and home-prepared diets displace packaged treats in high-engagement owner segments.
Strategic Opportunities
- Subscription commerce:Direct-to-consumer platforms bypass wholesale markups while capturing recurring revenue through personalized treat boxes.
- Veterinary channel expansion:Prescription treat formulations endorsed by Vets4Pets and independent practices lock in professional recommendation networks.
- Novel protein approvals:Insect-based and cultivated protein pathways through FSA novel food consultations open allergen-free positioning.
Industry Challenges
- Pet food technologist scarcity:Formulation chemistry expertise concentrated with legacy manufacturers limits R&D velocity for emerging brands.
- Dual certification timelines:Parallel FSA and Trading Standards approvals extend product launch cycles by four to eight months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Pet Treats Market |
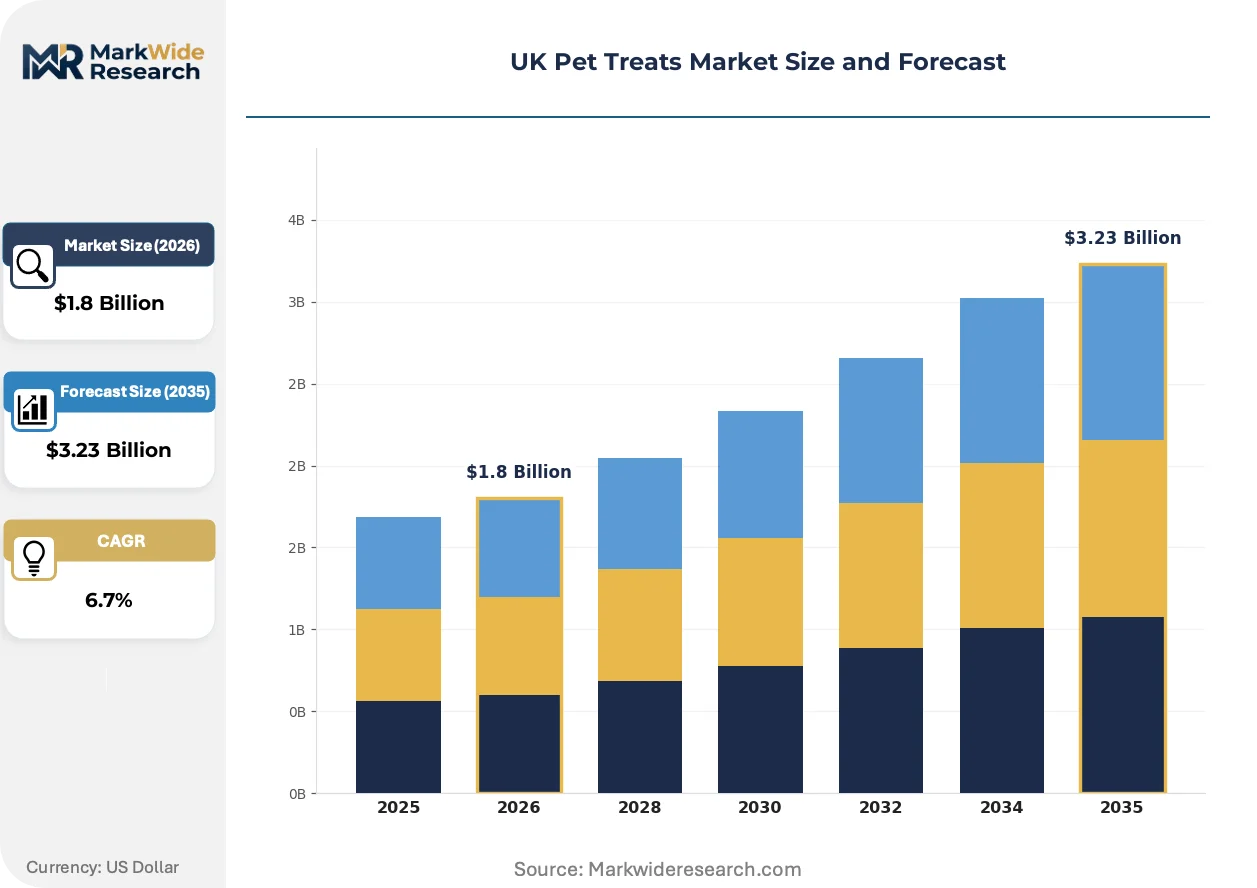
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chews, Biscuits, Jerky, Dental Treats Ingredient Type: Meat-Based, Grain-Free, Organic, Functional Packaging Type: Bags, Tubs, Boxes, Pouches Distribution Channel: Pet Stores, Supermarkets, Online Retailers, Specialty Shops |
| Companies Covered | Real Pet Food Co, Inspired Pet Nutrition, Mars Incorporated, Pets Choice, Lily's Kitchen, Nestle Purina Petcare, VAFO Group, Forthglade, Colgate-Palmolive Company (Hill's Pet Nutrition Inc), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Pet Treats Market Trends and Innovations
Cold-pressed manufacturing and novel protein pathways are redrawing competitive boundaries, while regulatory divergence forces parallel formulation strategies.
Extrusion technology is decentralizing treat production away from centralized Lancashire manufacturing hubs. Regional micro-facilities in Bristol and Manchester adopt compact extrusion lines to serve local subscription brands. This geographic fragmentation reduces transport emissions while enabling batch customization for niche dietary requirements.
FSA's evolving pet food labeling requirements are tightening compliance thresholds for treat manufacturers. The 2024 guidance on percentage declaration and ingredient origin statements forces reformulation of legacy product lines. Dental treat producers face the steepest adaptation costs due to complex functional additive disclosures.
Millennial pet owners in Greater London and the South East are consolidating purchases through subscription models that displace impulse buying at grocery checkouts. Ocado and direct-to-consumer platforms capture disproportionate growth through personalized delivery schedules. This channel shift compresses traditional wholesale relationships while elevating data-driven retention strategies.
UK Pet Treats Market Segmentation
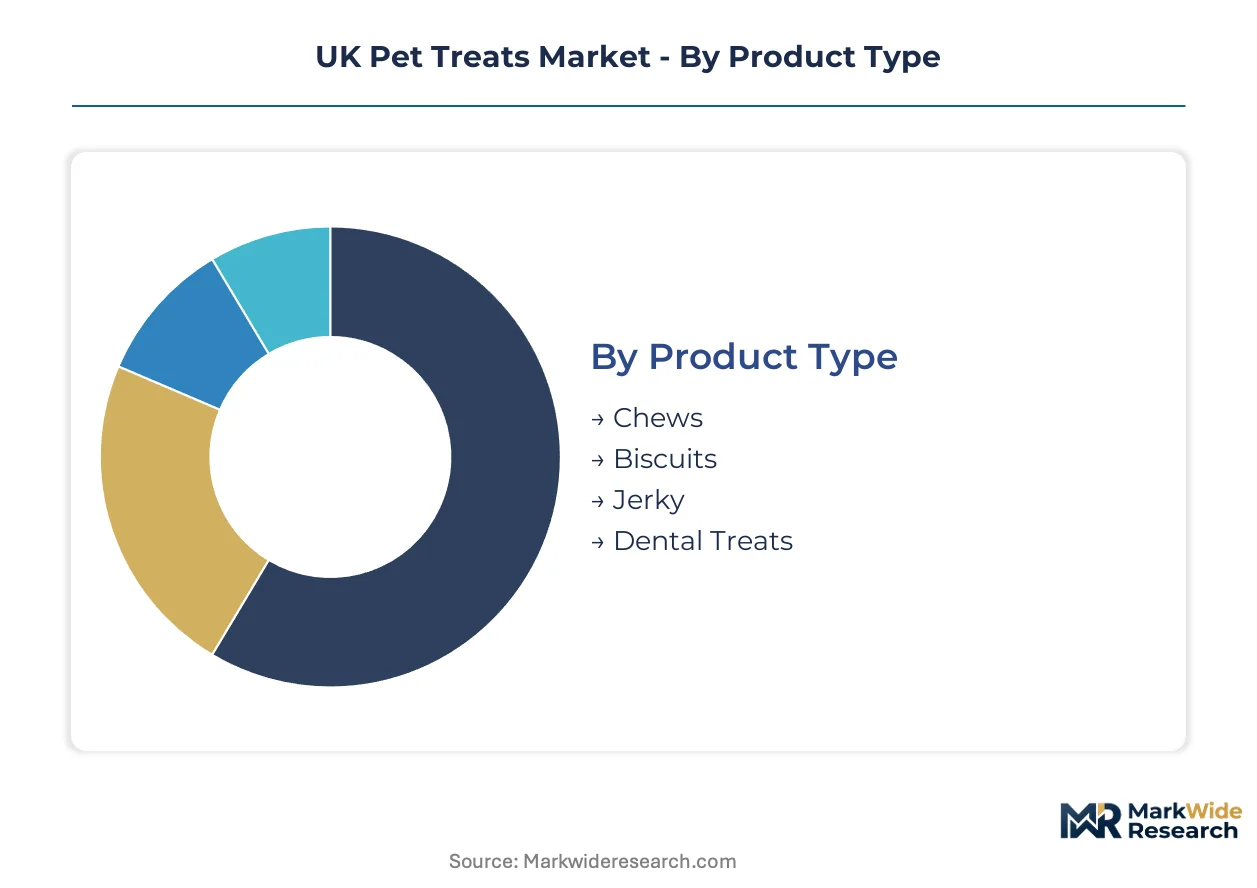
Segmentation in UK pet treats reveals how regulatory compliance burdens and channel economics concentrate margin capture. Manufacturers must align formulation investments with the certification requirements each product tier demands.
Product Type:
Dental Treats and Chews carry the heaviest FSA novel additive disclosure obligations, while Biscuits and Jerky face lighter documentation thresholds for single-ingredient sourcing.
- Dental Treats:Extruded or molded formulations containing enzymatic additives, chlorhexidine, or abrasive textures for plaque reduction. Demand concentrates in Greater London veterinary practices and subscription boxes where recurring purchase patterns lock in household penetration.
- Chews:Compressed rawhide, yak milk, or vegetable-based products engineered for extended engagement. South East urban households sustain premium positioning through human-grade ingredient specifications that trigger higher FSA scrutiny.
- Biscuits:Baked flour-based products with lower moisture content enabling ambient distribution. Ocado and Waitrose listings require full ingredient percentage declarations under updated labeling guidance.
- Jerky:Dehydrated meat strips with minimal processing steps. Artisan producers in Bristol and Manchester micro-facilities exploit simplified cold-pressed pathways to bypass centralized manufacturing economics.
Dental Treats sit at the top of the volume ranking, with Jerky climbing the fastest.
Ingredient Type:
Cost tier stratification separates commodity formulations from premium positioning, with Functional and Organic commanding shelf space through certification premiums.
- Functional:Probiotic, glucosamine, or CBD-infused formulations targeting joint mobility, digestive health, or anxiety reduction. Greater London pet owners drive disproportionate demand through veterinary endorsement networks.
- Organic:Soil Association-certified ingredients with full traceability documentation. Waitrose and Ocado exclusivity agreements filter out mid-tier competitors lacking certification infrastructure.
- Meat-Based:Poultry, beef, or fish protein as primary caloric input. Poultry meal price volatility compresses margin predictability for volume manufacturers.
- Grain-Free:Tapioca, sweet potato, or legume carbohydrate substitutes. Lily's Kitchen and similar brands leverage this positioning in premium grocery multiples.
Meat-Based formulations dominate absolute volume, with Functional gaining share fastest.
Packaging Type:
Channel economics favor resealable formats for subscription commerce, while single-serve portions capture impulse velocity in physical retail.
- Pouches:Flexible film structures with zip-lock closures preserving freshness across multi-week consumption cycles. Direct-to-consumer brands in Manchester and Bristol specify pouch formats for automated fulfillment efficiency.
- Bags:Stand-up or flat-bottom paper and plastic laminates dominating supermarket aisle placement. FSA labeling reform forces larger panel sizes for percentage declaration compliance.
- Tubs:Rigid plastic containers for semi-moist or pate-style treats. Veterinary channel distribution favors tub formats for prescription positioning.
- Boxes:Carton-based secondary packaging for gift sets or multi-flavor assortments. Seasonal demand spikes concentrate in Greater London and South East postal codes.
Bags maintain volume leadership, with Pouches expanding most quickly.
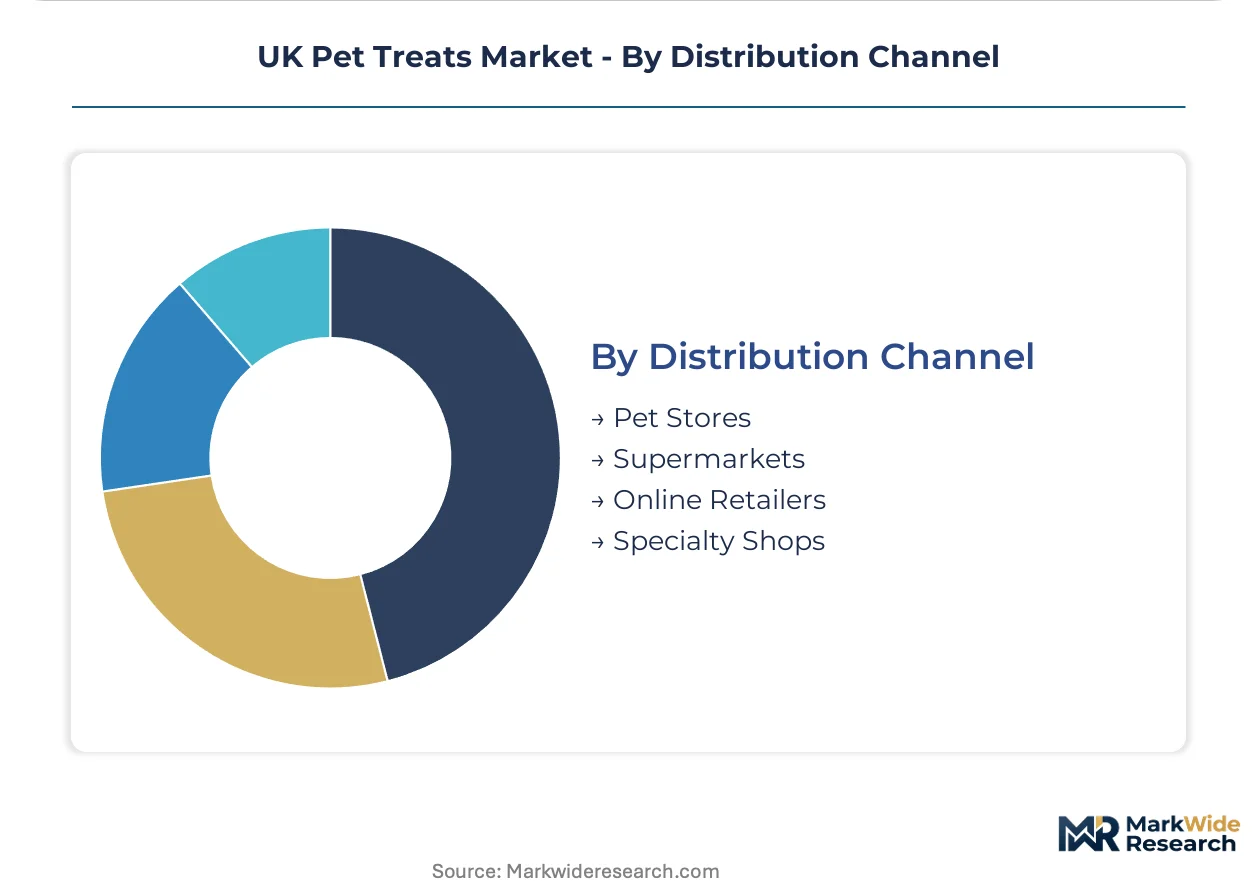
Distribution Channel:
Customer type fragmentation splits between professional endorsement networks and self-directed discovery platforms.
- Online Retailers:Subscription models and direct-to-consumer platforms bypassing wholesale markups. Ocado and specialist pet platforms capture disproportionate growth through personalized delivery algorithms.
- Pet Stores:Pets at Home and independent specialists providing tactile evaluation and staff recommendation. Physical footprint concentrates in suburban retail parks across Greater London commuter belts.
- Supermarkets:Tesco, Sainsbury's, and Waitrose commanding impulse purchase velocity at checkout proximity. Private-label supply through Pets Choice and similar manufacturers anchors volume economics.
- Specialty Shops:Independent boutiques and garden centers serving niche dietary requirements. Cold-pressed and novel protein formats find initial market validation here.
Supermarkets retain volume dominance, with Online Retailers scaling fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pet food technologists and veterinary nutritionists concentrate in Greater London and the South East, anchoring formulation expertise for UK treat manufacturers.
London and the South East
Dual-income millennial households sustain premium price tolerance for functional and dental treat categories. The FSA's evolving labeling requirements force reformulation of legacy product lines across manufacturing bases. Subscription commerce platforms in Greater London bypass traditional wholesale markups through personalized delivery algorithms.
Midlands
Central England hosts concentrated cold-pressed manufacturing facilities serving regional subscription brands. Defra's Animal Feed Regulations elevate traceability mandates that favor integrated supply chains. Birmingham and Leicester micro-facilities adopt compact extrusion lines for batch customization of niche dietary formulations.
North England
Lancashire production bases anchor private-label supply for major grocery multiples. Trading Standards enforcement shapes product standards from raw material sourcing to finished-goods traceability. Manchester regional facilities exploit simplified processing pathways to serve local direct-to-consumer brands.
Scotland
Edinburgh and Glasgow veterinary practices drive demand for prescription treat formulations. Post-Brexit regulatory divergence from EU FEDIAF guidelines fragments formulation strategies for manufacturers with cross-border operations. Scottish micro-producers specialize in novel protein pathways through artisan dehydration methods.
Wales
Rural pet ownership patterns sustain demand for extended-engagement chew products. The FSA's novel food consultation process opens insect-based protein approvals for allergen-free positioning. Cardiff-area facilities focus on sustainable packaging innovations for eco-conscious owner segments.
UK Pet Treats Market Competitive Landscape
The competitive structure tilts toward diversified multinationals with veterinary heritage. Established operators with robust quality systems capture disproportionate margin pools through professional endorsement networks. Three archetypes dominate: legacy nutrition conglomerates, premium organic specialists, and private-label scale manufacturers. Strategic moves concentrate on cold-pressed technology licensing and subscription platform partnerships.
Within the premium-tier vector, Lily's Kitchen exemplifies grain-free and organic positioning through grocery exclusivity agreements. Mars Incorporated and Nestle Purina Petcare occupy positions anchored by veterinary nutrition heritage across functional treat lines. Pets Choice represents the private-label archetype, manufacturing scale concentrated in Lancashire production bases for supermarket distribution.
| Leading Market Players |
|---|
| Real Pet Food Co |
| Inspired Pet Nutrition |
| Mars Incorporated |
| Pets Choice |
| Lily's Kitchen |
| Nestle Purina Petcare |
| VAFO Group |
| Forthglade |
| Colgate-Palmolive Company (Hill's Pet Nutrition Inc) |
| Others |
Pricing and Supply Chain Analysis
Pet food technologist concentration in Lancashire and Greater London creates labor-cost differentials that widen spreads between economy private-label and premium functional tiers. Cold-pressed manufacturing skills command wage premiums that feed into subscription-channel pricing, while commodity extrusion operations in regional micro-facilities anchor mass-market positioning.
Pricing Analysis
Bundled subscription services versus unbundled transactional purchases split the UK pet treats market into divergent pricing logics. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and veterinary endorsement intensity. Pricing pressure stems from poultry meal cost volatility compressing margin predictability in meat-based formulations. Economy-tier supermarket private-label buyers exhibit highest price sensitivity, while Greater London millennial subscribers in functional and dental categories tolerate premium positioning.
Supply Chain Analysis
Workforce availability for pet food technologists concentrates in Lancashire production bases and Greater London formulation hubs. Raw material sourcing draws from UK poultry processing, Norwegian salmon aquaculture, and emerging insect-protein cultivation facilities. Single-source vulnerability runs through concentrated poultry meal supply from integrated agricultural processors. Distribution runs through Ocado fulfillment centers and Pets at Home regional distribution networks, with direct-to-consumer platforms bypassing wholesale markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK pet treats market offers margin-expansion pathways through cold-pressed processing premiums and subscription-channel capture that offset raw material cost volatility. Veterinary endorsement networks and FSA compliance infrastructure create defendable positioning for operators with integrated quality systems.
For Market Incumbents: Anticipate raw feeding substitution threats by locking veterinary channel partnerships through prescription treat formulations. Deepen backward integration into novel protein supply through FSA novel food consultation pathways. Cold-pressed technology licensing to regional micro-facilities extends manufacturing footprint without capital-heavy expansion. For New Entrants and Emerging Players: Capture white-space in insect-based protein treats awaiting FSA approval clearance. Manchester and Bristol micro-facility clusters offer lowest barrier-to-entry for artisan positioning with simplified processing pathways. Direct-to-consumer subscription launch with personalized delivery algorithms bypasses grocery multiple listing fees. For Investors and Strategic Acquirers: Consumer goods conglomerates with veterinary nutrition heritage are the most active acquirer in this space, seeking premium-brand tuck-ins. Five-to-ten year viability hinges on regulatory compliance infrastructure amortization across UK-EU dual certification requirements. Monitor FSA-EU FEDIAF divergence negotiations as inflection signal for formulation strategy fragmentation risk.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Pressed Technology Licensing | Regional micro-facilities in Bristol and Manchester adopt compact extrusion lines for batch customization. |
| Veterinary Channel Partnership | Vets4Pets and independent practices lock in professional recommendation networks for prescription formulations. |
| Novel Protein Approval Pathway | FSA novel food consultations open insect-based and cultivated protein positioning for allergen-free claims. |
| Subscription Platform Integration | Ocado and direct-to-consumer platforms capture recurring revenue through personalized delivery algorithms. |
| Backward Integration into Supply | Integrated poultry and salmon oil sourcing mitigates raw material cost volatility compression. |
Research Methodology
Bottom-up pet owner demand modeling reconciled against top-down manufacturing capacity tracking forms the analytical core of this study. Primary interviews with pet food technologists, veterinary nutritionists, supermarket category buyers, and subscription platform operators combined with secondary validation from FSA guidance documents, Defra Animal Feed Regulations, PFMA industry reports, and Nielsen retail audit data. Triangulation between channel shipment data and consumer panel purchasing patterns ensures volume reconciliation.
Input-output matrices map ingredient cost structures through processing value-add stages across the projection horizon. Segmentation dimensions include product type, ingredient certification tier, packaging format, and distribution channel intensity. CAGRs derive from curve-fitting historical volume trajectories against demographic and regulatory scenario weights. Forecast inputs incorporate millennial pet ownership density gradients and FSA labeling reform implementation pace.
Regulatory divergence acceleration, novel protein approval delays, and raw material supply disruption are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions about veterinary endorsement network stability and subscription commerce penetration ceilings. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Cat Cage Market
Pet Care Products
Smart Pet Camera Market
Pet Care Products
Dog Clothes Market
Pet Care Products
Canada Pet Food Market
Pet Care Products
Pet Feeder Market
Pet Care Products
Dog Sunglasses Market
Pet Care Products
Netherlands Pet Boarding Market
Pet Care Products
Pet Treats and Chews Market
Pet Care Products
Saudi Arabia Pet Boarding Market
Pet Care Products
India Pet Food Market
Pet Care Products
North America Pet Food Nutraceuticals Market
Pet Care Products
Pet Grooming Products Market
Pet Care Products
Aquarium Supplies Market
Pet Care Products
United States Organic and Natural Pet Food Market
Pet Care Products
UAE Cat Food Market
Pet Care Products
Canned Wet Cat Food Market