
 Plant-Based Dog Food Market | 2026-2036
Plant-Based Dog Food Market Size, Share, and Industry Trends Forecast 2026-2036
Plant-Based Dog Food Market Insights
Ingredient sourcing and certification services is reconfiguring margin pools away from commodity grain trading toward traceable supply chain verification. V-Dog leverages its direct-to-consumer platform to sustain premium pricing power across North American metro markets. Wild Earth anchors its position through biotechnology-driven protein fermentation, while Benevo competes on European organic certification depth and retailer compliance expertise.
Plant-based dog food comprises formulated canine nutrition wherein animal-derived proteins, fats, and by-products are wholly or substantially replaced with plant-derived inputs such as pea protein isolate, potato starch, and supplemented taurine, L-carnitine, and vitamin D3 to meet AAFCO or FEDIAF nutritional adequacy profiles. Dry food formulations occupy the largest volume share due to manufacturing scalability and extended shelf stability, though wet food and refrigerated fresh formats are capturing faster growth among health-conscious owners seeking moisture-rich, minimally processed alternatives. Ingredient source segmentation reveals legume-based proteins generating the highest gross margins, while grain-inclusive recipes dominate mass-market price tiers through raw material cost efficiency.
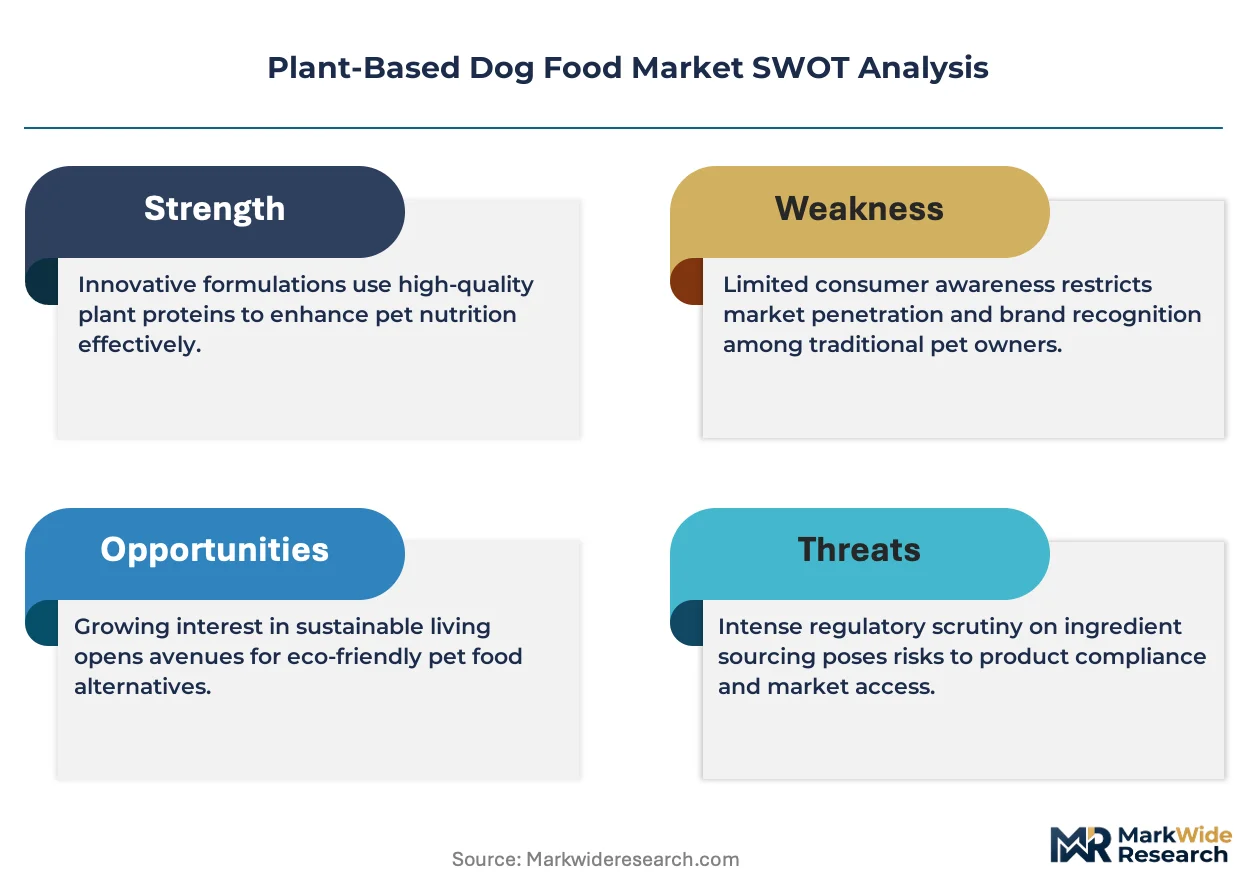
The FDA Center for Veterinary Medicine oversees pet food labeling and facility safety in the United States, while the EU Green Deal and REACH frameworks govern agricultural input sustainability disclosures across European supply chains. FEDIAF nutritional guidelines establish minimum amino acid and micronutrient thresholds that plant-based formulations must meet through precision supplementation. Stakeholders must monitor evolving regulatory divergence between jurisdictions, as compliance costs and formulation requirements will determine which regional markets permit scaled plant-based pet food entry.
Market Dynamics
Precision fermentation of mycoprotein and single-cell algae is collapsing the cost curve for complete amino acid profiles, forcing legacy extrusion plants to retrofit or exit as bioreactor capacity scales across contract manufacturing networks.
Growth Catalysts
- EU Green Deal agricultural sustainability mandates:The EU Green Deal and Farm to Fork Strategy are tightening carbon disclosure requirements for pet food ingredients, creating preferential procurement lanes for verified low-carbon plant proteins.
- Millennial and Gen Z pet owner cohort expansion:Urban households in the United States, Germany, and United Kingdom are driving substitution away from conventional kibble toward labeled vegan formulations with traceable supply chains.
- Biotechnology-driven protein production:Precision fermentation and biomass cultivation are delivering taurine, L-carnitine, and methionine at pharmaceutical-grade purity without animal-derived inputs.
Market Restraints
- Legume protein concentrate supply concentration:Yellow pea and fava bean protein isolates depend on Canadian Prairie and Baltic state processing capacity, exposing formulators to crop yield volatility and export tariff shifts.
- Vitamin D3 and taurine synthesis bottlenecks:Synthetic taurine production remains concentrated among Chinese chemical manufacturers, creating single-source risk for AAFCO-compliant formulations.
- Veterinary professional skepticism:The American Veterinary Medical Association and country-level veterinary chambers in Germany maintain cautious position statements on long-term cardiac health in plant-fed canines, dampening clinical endorsement velocity.
Strategic Opportunities
- Fresh refrigerated format penetration:Cold-chain direct-to-subscription models in the United States and United Kingdom are capturing lifetime value multiples above dry kibble through auto-replenishment algorithms.
- FEDIAF organic certification depth:The EU regulatory framework rewards multi-ingredient organic supply chains with retailer slotting fee reductions and shelf placement premiums across German and French pet specialty networks.
- Biotechnology-cold chain convergence:Integration of precision-fermented protein with flash-freezing and modified atmosphere packaging is enabling clean-label wet food with six-month refrigerated stability.
Industry Challenges
- Formulation biochemist talent scarcity:The intersection of veterinary nutrition science and industrial food engineering lacks accredited training pipelines, forcing brands to recruit from human plant-based meat R&D divisions.
- Dual-jurisdiction compliance complexity:Simultaneous AAFCO and FEDIAF nutritional adequacy verification requires parallel feeding trials and analytical testing, extending product launch timelines by eight to fourteen months.
- Ingredient provenance verification infrastructure:Blockchain and mass-balance certification systems demand capital deployment upstream of margin-positive scale, straining mid-tier brand balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant-Based Dog Food Market |
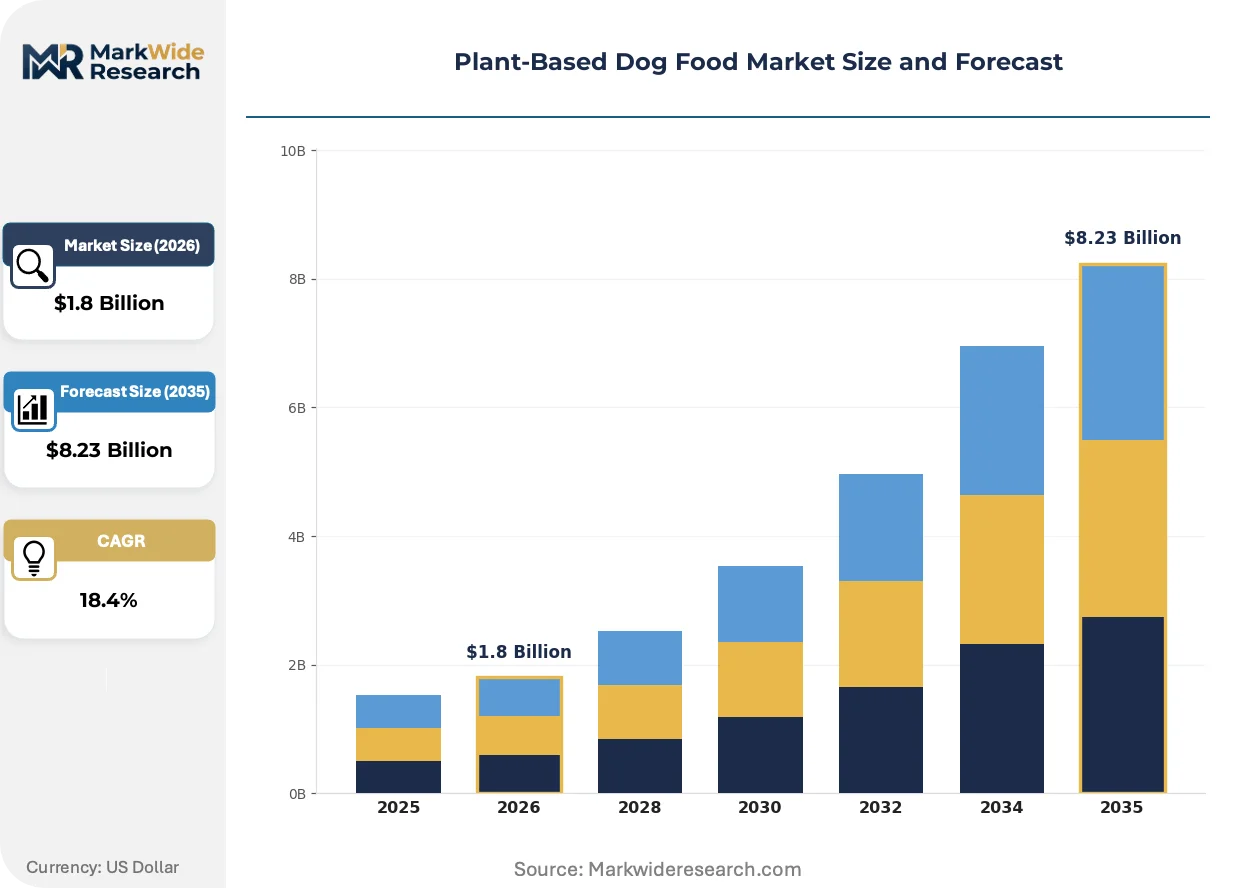
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.23 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Treats, Supplements Ingredient Source: Legumes, Grains, Vegetables, Fruits Target Customer: Health-Conscious Owners, Vegan Owners, Pet Specialty Stores, Online Retailers Packaging Type: Bags, Cans, Pouches, Bulk |
| Companies Covered | V-Dog, Wild Earth, Benevo, Yarrah Organic Petfood, Halo Purely for Pets, Ami Pet Foods, Bond Pet Foods, Sprout Pet Products, Lily's Kitchen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant-Based Dog Food Market Trends and Innovations
Biotechnology-enabled protein production and regulatory carbon accounting are converging to redefine competitive advantage away from commodity sourcing toward verified molecular precision and supply chain transparency.
Precision fermentation of fungal mycoprotein is rendering obsolete traditional soy and wheat gluten concentrates as the primary protein backbone in premium formulations. North American and European brands with direct-to-consumer channels are adopting biomass-derived complete proteins at pilot scale, compressing the R&D-to-shelf cycle from thirty-six months to eighteen months as contract bioreactor networks achieve food-grade certification.
REACH framework agricultural input sustainability disclosures are mandating Scope 3 carbon accounting across European supply chains. Pet food manufacturers importing legume proteins must now document cultivation emissions and land-use change impacts, favoring suppliers with certified regenerative agriculture partnerships and disadvantaging traders lacking traceability infrastructure.
Veterinary recommendation networks are fragmenting purchasing authority away from retail shelf selection toward clinic-dispensed prescription formats. Specialty and emergency veterinary hospitals in the United States and United Kingdom are piloting plant-based therapeutic diets for food-sensitive dermatology and gastrointestinal cases, creating a professional endorsement channel distinct from mass-market advertising.
Plant-Based Dog Food Market Segmentation
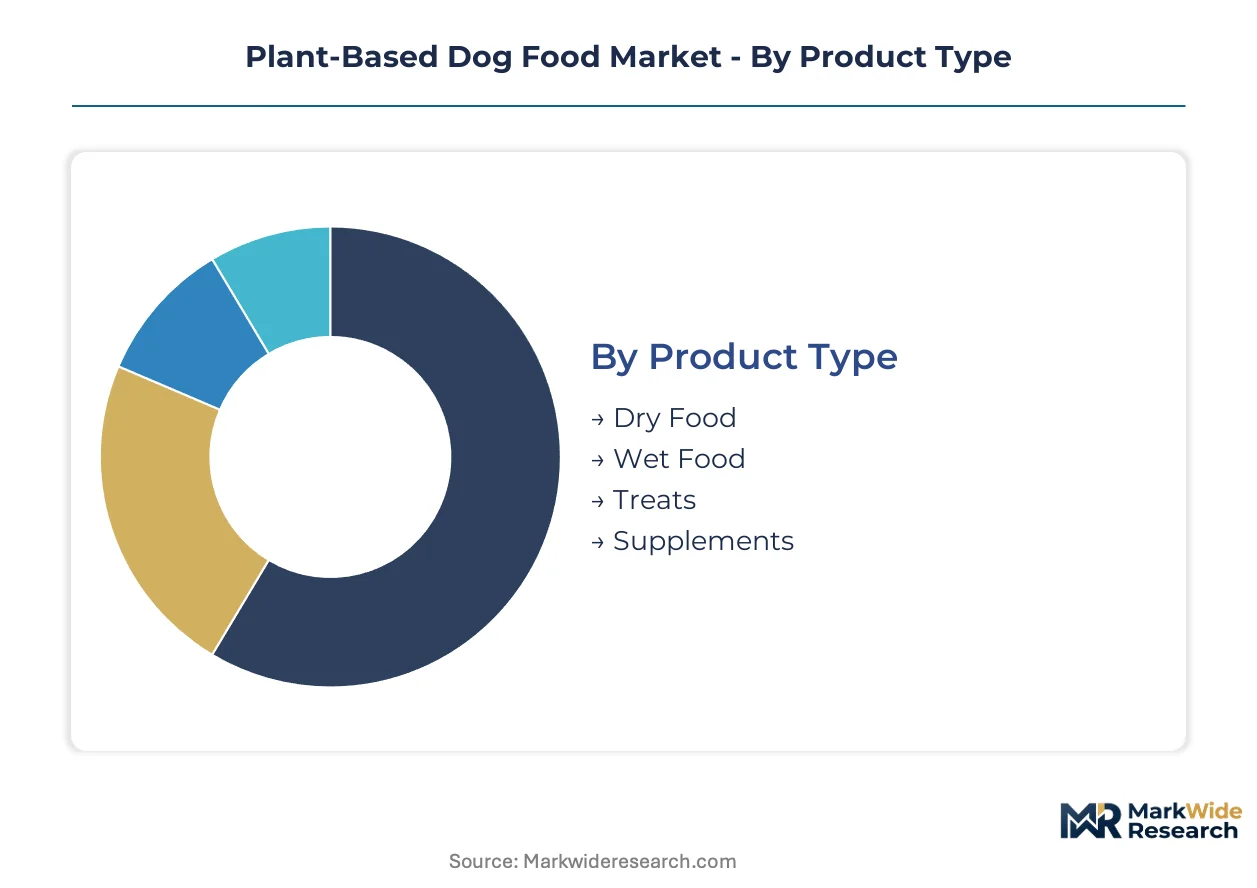
Plant-based dog food segmentation reveals how formulation technology, ingredient sourcing, and distribution channel economics fragment addressable demand. Each dimension carries distinct margin profiles and regulatory compliance burdens that determine competitive viability.
Product Type:
The use-case spectrum spans shelf-stable convenience to fresh nutrition delivery, with each format demanding different manufacturing infrastructure and cold-chain investment.
- Dry Food:Extruded kibble formulations leverage pea protein isolate and potato starch matrices for shelf stability exceeding twelve months. Manufacturing scales efficiently through legacy pet food plants in the United States and Germany, though retrofit costs for dedicated allergen-free lines constrain mid-tier entrants.
- Wet Food:High-moisture formulations in gravy or pate textures require retort processing or aseptic filling, with canning lines concentrated among co-manufacturers in Thailand and the Netherlands. Premium positioning in United Kingdom urban markets is accelerating as refrigerated fresh formats gain trial.
- Treats:Baked and air-dried formats utilize chickpea flour and sweet potato binders for training reward applications.
- Supplements:Powdered taurine, L-carnitine, and algae-derived omega-3 additions target homemade diet households seeking nutritional adequacy verification.
The dominant share belongs to Dry Food, while Wet Food is closing the gap fastest.
Ingredient Source:
Cost tier differentiation separates commodity grain formulations from premium legume concentrates, with protein digestibility coefficients driving veterinary endorsement.
- Legumes:Yellow pea and fava bean protein isolates deliver amino acid scores exceeding 0.85, meeting FEDIAF lysine and methionine thresholds through precision blending. Canadian Prairie processing capacity and Baltic state fractionation facilities supply North American and European formulators respectively, with regenerative agriculture certifications commanding procurement premiums.
- Grains:Oat and rice-based formulations occupy mass-market price tiers through raw material cost efficiency, though glycemic index concerns limit clinical recommendation in diabetic canine management protocols.
- Vegetables:Sweet potato, pumpkin, and carrot inclusions provide fiber matrices and beta-carotene fortification for digestive health positioning.
- Fruits:Blueberry and cranberry extracts supply antioxidant marketing claims with limited functional dosage requirements.
Legumes command the premium tier, yet Grains retain volume leadership through private-label penetration.
Target Customer:
Customer type determines channel economics and marketing spend allocation, from direct-to-consumer subscription models to veterinary clinic dispensing.
- Health-Conscious Owners:Urban millennials in United States coastal metros and German cities prioritize clean-label ingredient decks and carbon footprint disclosures, accepting per-kilogram pricing multiples above conventional kibble. Auto-replenishment algorithms and personalized portion recommendations drive lifetime value capture.
- Vegan Owners:Ethical consistency between human and companion animal diets concentrates demand in Brighton, Portland, and Berlin, with cross-referencing to human plant-based meat purchase patterns enabling predictive targeting.
- Pet Specialty Stores:Independent retailers in France and the Netherlands curate assortments based on FEDIAF organic certification depth and local brand origin stories.
- Online Retailers:Amazon and Chewy marketplace algorithms favor review velocity and subscription conversion rates over margin structure.
Health-Conscious Owners generate the highest per-unit economics, while Online Retailers are scaling fastest through algorithmic demand generation.
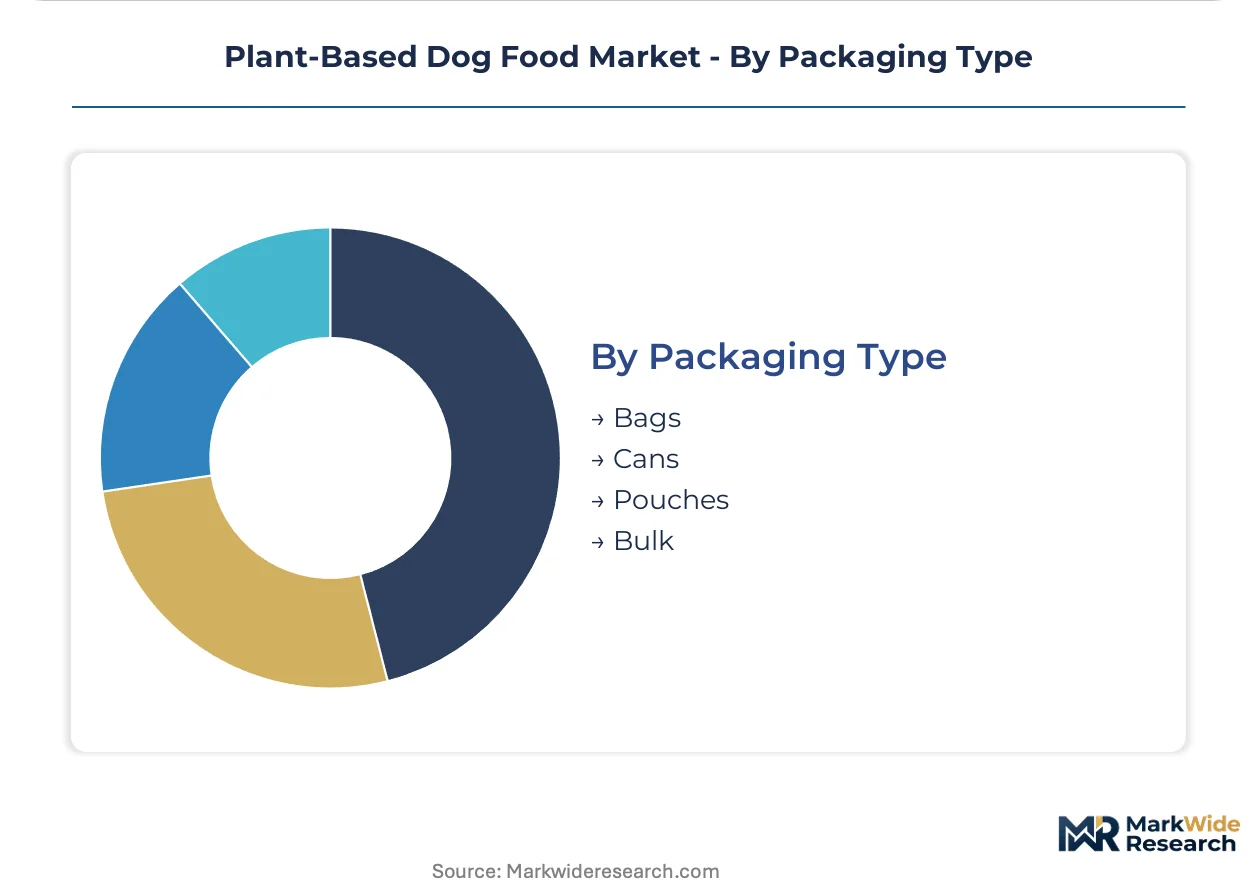
Packaging Type:
Packaging format selection reflects shelf-life requirements, sustainability positioning, and retail channel slotting fee structures.
- Bags:Multi-layer polyethylene and paper laminates dominate dry food distribution, with recyclable mono-material structures gaining traction in German packaging extended producer responsibility frameworks.
- Cans:Steel and aluminum containers for wet food face circular economy scrutiny, though infinite recyclability claims resonate in Scandinavian markets.
- Pouches:Flexible stand-up formats reduce shipping cube and enable portion-controlled fresh food delivery in United Kingdom subscription services.
- Bulk:Refill station infrastructure in zero-waste retail concepts in California and the Netherlands targets plastic-elimination positioning.
Bags retain format dominance, though Pouches are expanding most quickly through refrigerated fresh segment growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for plant-based dog food diverges sharply across markets. German and United Kingdom buyers absorb 40-60% price premiums for certified organic formulations, while United States mass-market penetration depends on achieving cost parity with conventional kibble through scale.
United States
Millennial pet owners in Portland, Austin, and Brooklyn drive subscription-format trial for refrigerated fresh products. FDA Center for Veterinary Medicine labeling requirements create compliance barriers for imported European formulations. California's Los Angeles-San Francisco corridor hosts the densest concentration of direct-to-consumer brand headquarters and contract bioreactor pilot facilities.
Germany
Berlin and Hamburg urban households exhibit the highest per-capita vegan dog ownership rates in Europe. EU Green Deal Farm to Fork Strategy mandates Scope 3 carbon disclosure for all imported legume proteins, favoring Baltic state suppliers with certified regenerative partnerships. Bavaria's Munich-Stuttgart axis anchors specialty retail expansion for FEDIAF-organic certified products.
United Kingdom
Brighton, Bristol, and London postcodes show clustering of ethical-consistency purchasers who mirror human plant-based meat consumption patterns. REACH framework agricultural input sustainability disclosures require full cultivation emission documentation for Canadian pea protein imports. The Midlands distribution hub concentrates cold-chain logistics infrastructure for refrigerated fresh format national rollout.
Netherlands
Amsterdam and Utrecht municipalities lead municipal procurement pilots for plant-based therapeutic diets in veterinary clinic networks. Packaging Extended Producer Responsibility frameworks incentivize mono-material recyclable structures over multi-layer laminates. The Randstad logistics corridor enables same-day delivery coverage for subscription services targeting Belgian and German border regions.
Canada
Toronto and Vancouver metropolitan areas concentrate health-conscious owner demand for grain-free legume formulations. Canadian Prairie yellow pea processing capacity supplies North American protein isolate demand, though export tariff exposure to United States markets creates margin volatility. Montreal's pet specialty retail networks curate European import assortments based on organic certification depth.
Plant-Based Dog Food Market Competitive Landscape
Capability concentration sits with biotechnology-enabled protein developers; scale advantage sits with legacy extrusion manufacturers retrofitting for allergen-free production. The market exhibits tiered structure with three to four dominant positioning vectors. Strategic archetypes include direct-to-consumer subscription specialists, fermentation-technology anchors, and European organic certification depth players. Competitive moves center on bioreactor capacity partnerships and cold-chain logistics integration for fresh format penetration.
Within the biotechnology-driven tier, Wild Earth exemplifies precision-fermentation positioning, while V-Dog anchors direct-to-consumer scale in North American metro markets. European organic certification depth is represented by Benevo, which occupies a compliance-specialist position across German and United Kingdom retailer networks. These three archetypes illustrate how competitive advantage is fragmenting along technology, channel, and regulatory-approval vectors rather than consolidating around traditional manufacturing scale.
| Leading Market Players |
|---|
| V-Dog |
| Wild Earth |
| Benevo |
| Yarrah Organic Petfood |
| Halo Purely for Pets |
| Ami Pet Foods |
| Bond Pet Foods |
| Sprout Pet Products |
| Lily's Kitchen |
| Others |
Pricing and Supply Chain Analysis
The Randstad logistics corridor's cold-chain cost dynamics amplify price differentiation between refrigerated fresh formats and shelf-stable kibble, while Canadian Prairie yellow pea processing concentration grants incumbent formulators procurement leverage over subscription-format entrants competing on landed cost parity.
Pricing Analysis
Auto-replenishment subscription revenue drives lifetime value capture above transactional dry kibble sales. Three-tier pricing structure across premium, standard, and economy levels separates fermentation-enabled formulations from legume concentrates from grain-inclusive recipes. Cost compression in mass-market tiers intensifies because private-label grain formulations exploit oat and rice cost efficiency. Health-conscious owners in United States coastal metros exhibit lowest price sensitivity, while mass-market buyers in suburban United States markets resist per-kilogram premiums above conventional kibble.
Supply Chain Analysis
Yellow pea and fava bean protein feedstock draws from Canadian Prairie fractionation facilities, Baltic state processing plants, and Chinese synthetic taurine manufacturers. Precision-fermented mycoprotein and single-cell algae protein inputs rest on bioreactor capacity expansion across North American contract manufacturing networks. Single-source vulnerability concentrates in Chinese pharmaceutical-grade taurine synthesis. Distribution runs through direct-to-consumer subscription platforms, pet specialty retail networks, and veterinary clinic dispensing channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among subscription-platform algorithms and veterinary clinic networks, fragmenting traditional retail shelf authority and compressing slotting fee leverage for mid-tier brands.
For Market Incumbents: Entrench fermentation-technology partnerships to defend against precision-fermentation entrants collapsing protein input costs. Secure captive supply of Baltic state organic legume processing capacity before FEDIAF carbon disclosure mandates tighten. Certification investment in EU Green Deal regenerative agriculture verification creates retailer slotting fee advantages. For New Entrants and Emerging Players: Pursue refrigerated fresh format penetration in United Kingdom and United States urban corridors where cold-chain infrastructure enables six-month stability claims. Veterinary clinic therapeutic diet dispensing represents the most penetrable channel, bypassing saturated retail shelf competition. Direct-to-consumer launch with personalized portion algorithms captures lifetime value multiples. For Investors and Strategic Acquirers: Biotechnology-enabled protein developers with food-grade bioreactor certification represent the priority acquisition archetype. Long-term viability hinges on defensible intellectual property in complete amino acid fermentation rather than commodity extrusion scale. Watch for FDA Center for Veterinary Medicine novel ingredient approval velocity as inflection indicator for platform valuation expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Precision-Fermentation Capacity Partnership | Wild Earth's mycoprotein platform demonstrates how bioreactor scale collapses input cost curves. |
| Cold-Chain Logistics Integration | United Kingdom refrigerated fresh rollout depends on Midlands hub flash-freezing infrastructure. |
| FEDIAF Organic Certification Investment | Benevo's compliance depth secures German retailer slotting fee reductions unavailable to non-certified entrants. |
| Veterinary Clinic Dispensing Channel | Amsterdam municipal procurement pilots validate prescription-format endorsement for food-sensitive dermatology cases. |
| Direct-to-Consumer Platform Scale | V-Dog's subscription algorithms sustain premium pricing power across North American metro markets. |
Research Methodology
Initial hypotheses were tested against primary input from plant-based pet food formulators, veterinary nutrition specialists, pet specialty retail category buyers, and precision-fermentation technology developers and refined through secondary validation against FDA Center for Veterinary Medicine labeling guidance documents, FEDIAF nutritional guideline publications, EU Green Deal Farm to Fork Strategy implementation frameworks, and REACH agricultural input sustainability disclosure requirements. Bottom-up demand modeling across product type, ingredient source, and distribution channel segments was triangulated against top-down market sizing.
Demand-supply balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product format, protein source technology, certification tier, and regional regulatory cluster. CAGRs were derived from growth driver elasticity coefficients applied to baseline penetration rates. Industry-specific forecast inputs incorporated veterinary professional endorsement velocity and cold-chain infrastructure rollout timelines.
Macroeconomic conditions sit as an overlay; deviation in consumer discretionary spending indices and legume commodity price volatility would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory approval timelines and biotechnology scale-up curves. Cross-checking against AAFCO and FEDIAF feeding trial completion databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Cat Accessories Market
Pet Care Products
Vegan Dog Food Market
Pet Care Products
Smart Cat Eye Market
Pet Care Products
Indestructible Dog Toys Market
Pet Care Products
UK Dog Food Market
Pet Care Products
Pet Beds Market
Pet Care Products
Cat Nail Clippers Market
Pet Care Products
Insulated Dog House Market
Pet Care Products
Sensitive Stomach Cat Food Market
Pet Care Products
Asia-Pacific Pet Clothing Market
Pet Care Products
Indonesia Pet Care Market
Pet Care Products
Dog Carrier Bags Market
Pet Care Products
South America Pet Diet Market
Pet Care Products
Bird Toy Market
Pet Care Products
South America Dog Food Market
Pet Care Products
Dog Treats Market