
 Brazil Food Additives Market | 2026-2036
Brazil Food Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Food Additives Market Outlook
Market Overview
Brazil is reconfiguring its food additive supply base through expanded domestic blending capacity and import substitution programs. Ingredion Incorporated leverages its Brazilian corn wet milling infrastructure to anchor regional starch and sweetener derivative supply. Cargill, Incorporated competes through integrated oilseed processing that extends into lecithin and emulsifier production for local bakery and confectionery channels. Kerry Group plc differentiates via taste and nutrition solutions tailored to Brazilian palate preferences in meat and savory applications.
Food additives comprise substances added to food products to preserve quality, enhance sensory attributes, or improve processing characteristics, including synthetic and natural preservatives, colorants, emulsifiers, and flavor modulators regulated by Codex Alimentarius specifications and ANVISA resolutions. These inputs serve industrial food manufacturing by controlling oxidation, microbial spoilage, texture degradation, and flavor loss across extended distribution chains. Preservatives command the largest product type position due to tropical climate stress on shelf stability, while flavor enhancers represent the fastest-expanding category as Brazilian processors reformulate for reduced sodium and sugar profiles. Emulsifiers concentrate margin pools where bakery and dairy applications require specialized lipid-water interface stabilization.
ANVISA maintains Brazil's food additive positive list system under RDC resolutions, with Mercosur harmonization creating cross-border formulation standards that manufacturers must navigate for regional export eligibility. The National Health Surveillance Agency's updated toxicological re-evaluation protocols are forcing reformulation cycles among legacy preservative systems. Stakeholders must monitor ANVISA's pending novel food and additive consultations, where enzyme-based clean-label alternatives face regulatory pathway uncertainty that will determine competitive positioning in premium product segments.
Market Dynamics
ANVISA's toxicological re-evaluation protocols are forcing simultaneous reformulation across Brazil's preservative-reliant food manufacturing base, compressing product development cycles while opening formulation service contracts to specialized ingredient houses.
Growth Catalysts
- Tropical shelf-life mandates:Processed meat and poultry processors operating under Mercosur distribution requirements are expanding synthetic and natural preservative loads to combat microbial spoilage in ambient supply chains.
- São Paulo industrial corridor concentration:Bulk procurement volumes from concentrated food manufacturing clusters in Brazil's southeastern state are driving emulsifier and stabilizer demand at contract scale.
- Clean-label enzyme approvals:ANVISA's pending novel food consultations are creating regulatory pathways for enzyme-based alternatives that bypass traditional preservative declaration requirements.
Market Restraints
- Corn wet milling concentration:Domestic starch derivative supply depends on a narrow base of corn processing infrastructure, exposing formulators to agricultural input volatility and single-source risk.
- Positive list compliance friction:ANVISA's RDC resolution system requires pre-market authorization for new additives, extending time-to-market for reformulated products against regional competitors.
- Import substitution bottlenecks:Local blending capacity expansion lags behind demand growth for specialized lipid-water emulsifiers, forcing continued reliance on imported lecithin and mono-diglyceride systems.
Strategic Opportunities
- Northeastern manufacturing expansion:Underpenetrated food processing capacity in Pernambuco and Ceará states offers first-mover positioning for regional distribution hubs serving expanding consumer markets.
- Reduced-sodium savory reformulation:Flavor modulator and yeast extract applications in meat processing are capturing demand from ANVISA-mandated sodium reduction targets in processed foods.
- Clean-label certification convergence:Integration of natural preservation with organic and non-GMO certification standards is opening premium channel access for differentiated ingredient suppliers.
Industry Challenges
- Formulation chemist scarcity:Technical talent capable of navigating ANVISA's positive list while optimizing tropical stability profiles remains concentrated among legacy multinational ingredient houses.
- Dual certification timelines:Products requiring both ANVISA approval and Mercosur harmonization face extended regulatory review periods that compress commercialization windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Food Additives Market |
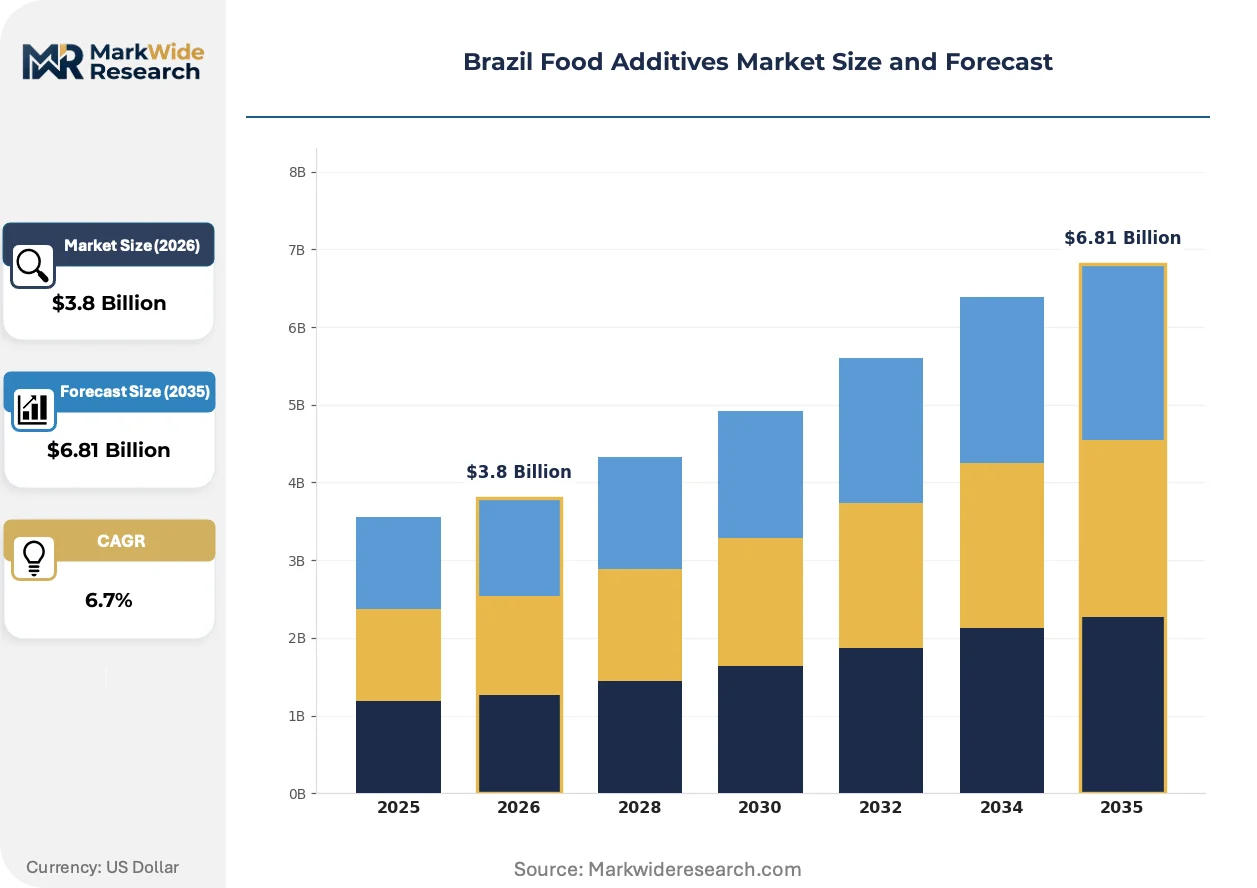
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Preservatives, Flavor Enhancers, Colors, Emulsifiers Form: Liquid, Powder, Granular, Paste Application: Bakery, Beverages, Dairy, Confectionery End User: Food Manufacturers, Restaurants, Retailers, Home Cooking |
| Companies Covered | Ingredion Incorporated, Archer Daniels Midland Company, BASF SE, Givaudan SA, Tate & Lyle plc, Cargill, Incorporated, Kerry Group plc, Corbion NV, DuPont de Nemours, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Food Additives Market Strategic Shifts
Enzymatic preservation systems and fermentation-derived alternatives are displacing synthetic chemistries across Brazil's reformulation pipeline, while regulatory pressure on maximum residue limits accelerates clean-label transition timelines.
Microencapsulation technology for volatile antimicrobial compounds is rendering obsolete conventional spray-dried preservative systems that degrade under tropical humidity exposure. Bakery and confectionery manufacturers in São Paulo state's industrial corridor are adopting these systems at pilot scale. The shift is compressing margins for legacy preservative suppliers while expanding contract manufacturing opportunities for encapsulation specialists.
ANVISA's updated toxicological re-evaluation protocols under RDC resolutions are forcing systematic replacement of legacy benzoate and sorbate systems in beverage and sauce applications. Manufacturers must submit new safety data packages for existing formulations. The meat processing segment is responding fastest, accelerating natural antioxidant and cultured dextrose adoption to preempt regulatory delisting.
Direct procurement relationships between large food manufacturers and domestic starch processors are displacing traditional distributor intermediaries in emulsifier and texturizer categories. Minas Gerais dairy processors and Rio de Janeiro beverage conglomerates are negotiating volume contracts directly with corn wet milling operations. The disintermediation is most visible in southeastern Brazil, where concentrated manufacturing bases support dedicated supply agreements.
Brazil Food Additives Market Segmentation
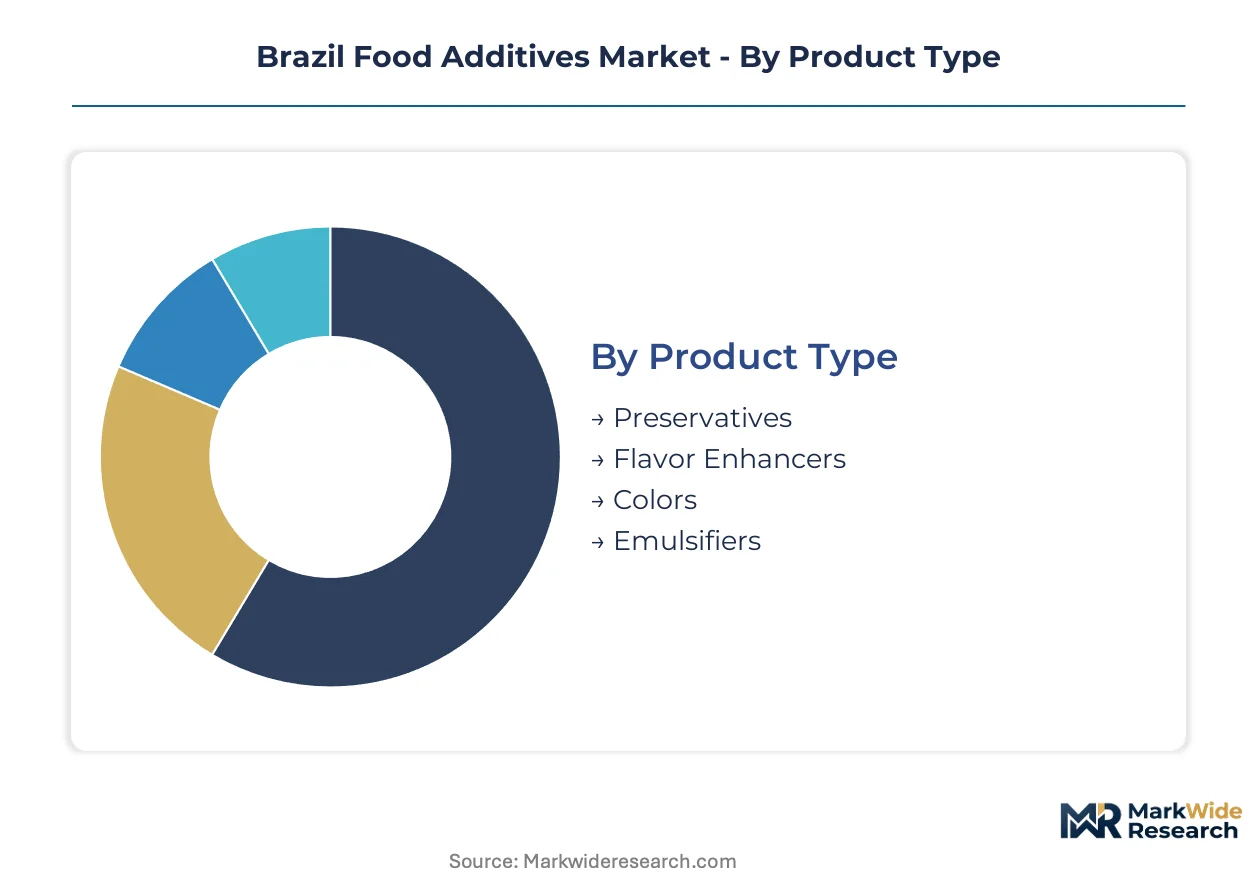
Food additive procurement patterns in Brazil diverge sharply across product categories and user types, with tropical climate stress and ANVISA compliance requirements creating distinct service intensity profiles. Manufacturers in São Paulo state's industrial corridor demand formulation support that smaller retail channels rarely require.
Product Type:
After-sales service intensity peaks where shelf-life failure carries the highest commercial cost, creating tiered supplier relationship models across Brazil's food manufacturing base.
- Preservatives:Synthetic benzoates, sorbates, and natural cultured dextrose systems control microbial spoilage in ambient distribution chains. São Paulo meat processors deploy these at highest load rates to meet Mercosur export shelf-life mandates under tropical humidity stress.
- Flavor Enhancers:Yeast extracts, nucleotides, and savory peptide systems reduce sodium while maintaining taste intensity. ANVISA's processed food sodium reduction targets are accelerating adoption across Minas Gerais dairy and Rio de Janeiro beverage operations.
- Colors:Carotenoid, anthocyanin, and caramel-based systems replace synthetic azo dyes in clean-label positioning.
- Emulsifiers:Lecithin and mono-diglyceride systems stabilize lipid-water interfaces in bakery and confectionery applications.
By volume, Preservatives leads. By growth pace, Flavor Enhancers is ahead.
Form:
Physical form selection in Brazil tracks directly against manufacturing automation levels and tropical storage infrastructure quality.
- Liquid:Pumpable concentrates integrate into continuous processing lines with minimal dust exposure. Large beverage and sauce manufacturers in Rio de Janeiro and São Paulo prefer liquid systems for automated dosing accuracy.
- Powder:Spray-dried and agglomerated formats offer extended stability and lower transport costs. Regional bakeries in Pernambuco and Ceará rely on powder systems where cold chain infrastructure remains limited.
- Granular:Free-flowing particulates reduce caking in high-humidity environments.
- Paste:Semi-solid concentrates suit small-batch artisanal producers.
Powder dominates procurement tonnage. Liquid commands the highest per-kilogram value realization.
Application:
End-use concentration in Brazil's southeastern industrial corridor creates demand clustering that shapes regional supply chain configuration.
- Bakery:Emulsifier and enzyme systems control crumb structure and mold inhibition in extended-shelf-life bread. São Paulo's concentrated baking industry drives bulk contract structures for SSL and CSL emulsifiers.
- Beverages:Acidulants, preservatives, and color stabilizers maintain product integrity across ambient distribution. ANVISA's benzoate re-evaluation is forcing reformulation investment among legacy juice and soft drink processors.
- Dairy:Stabilizers and texturizers manage syneresis and mouthfeel in fermented products.
- Confectionery:Glazing agents and humectants control moisture migration in sugar-based systems.
Bakery generates the largest absolute additive volume. Beverages is climbing fastest on clean-label reformulation cycles.
End User:
Customer scale and technical capability determine whether suppliers provide formulation services or deliver commodity ingredients.
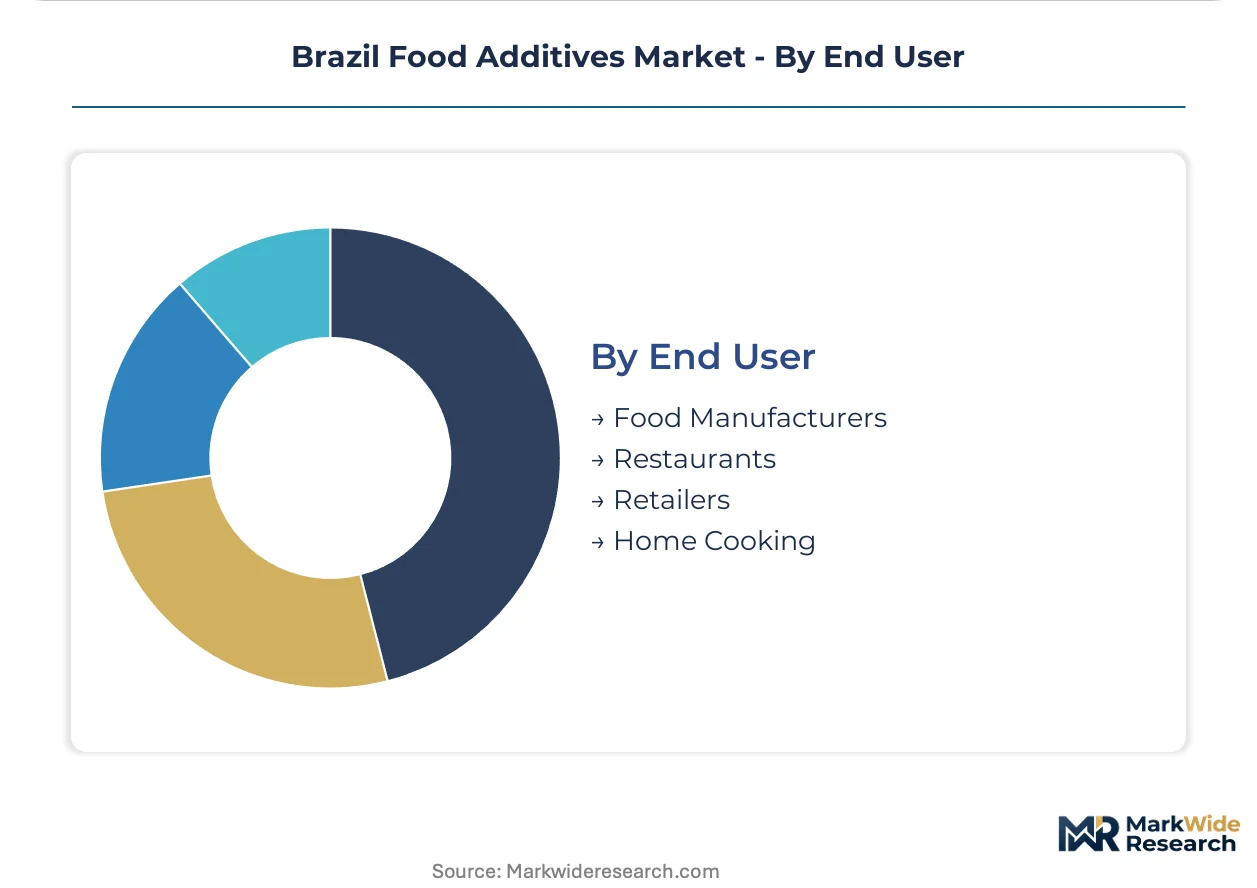
- Food Manufacturers:Industrial processors require integrated application laboratories and regulatory submission support. Multinational meat and dairy conglomerates negotiate direct supply agreements bypassing traditional distribution.
- Restaurants:Foodservice channels demand portion-controlled formats and rapid technical response for menu development.
- Retailers:Private-label programs require specification consistency across multiple co-manufacturing sites.
- Home Cooking:Consumer-packaged formats prioritize shelf stability and clear labeling over performance optimization.
Food Manufacturers command the deepest supplier relationships. Restaurants is expanding most quickly on foodservice recovery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic corn wet milling infrastructure anchors Brazil's food additive supply base, with southeastern manufacturing clusters consuming the majority of emulsifier and preservative volumes. ANVISA's regulatory harmonization with Mercosur partners creates cross-border formulation requirements that concentrate technical expertise in São Paulo state. The analysis examines five sub-regions where industrial food manufacturing and additive demand concentrate.
São Paulo
Meat processors and bakery conglomerates in the state's industrial corridor drive bulk procurement of synthetic preservatives and SSL emulsifiers. ANVISA's RDC resolutions on maximum residue limits force reformulation cycles among legacy beverage manufacturers headquartered in Greater São Paulo. Campinas and Sorocaba host concentrated food manufacturing parks where direct supply agreements with starch processors are displacing traditional distribution channels.
Minas Gerais
Dairy cooperatives and cheese processors generate sustained demand for stabilizers and texturizers that control syneresis in fermented products. The state's agricultural regulator enforces strict cold chain protocols that extend additive shelf-life requirements beyond national baselines. Uberlândia and Belo Horizonte anchor a processing belt where yeast extract flavor enhancers are capturing reformulation contracts from sodium-reduction mandates.
Rio de Janeiro
Beverage conglomerates and sauce manufacturers consume acidulants and color stabilizers at volumes that justify dedicated technical service teams from ingredient suppliers. Federal environmental licensing delays for new blending capacity are compressing margins for processors dependent on imported lecithin systems. Duque de Caxias and Nova Iguaçu host concentrated liquid additive formulators serving the state's automated dosing requirements.
Rio Grande do Sul
Poultry processors operating under Mercosur export protocols deploy natural antioxidant systems at load rates exceeding national averages. The state's integration with Argentine supply chains creates dual-certification complexity for cross-border additive shipments. Porto Alegre and Caxias do Sul concentrate meat processing capacity where cultured dextrose alternatives are displacing synthetic benzoate systems ahead of ANVISA's pending re-evaluation deadlines.
Bahia
Underpenetrated food manufacturing capacity in the Salvador metropolitan zone offers expansion terrain for regional distribution hubs serving northeastern consumer markets. Federal development incentives for the region lag behind southeastern infrastructure quality, extending reliance on powder-format additives where cold chain gaps persist. Camaçari's petrochemical complex is attracting downstream interest for domestic emulsifier blending investments.
Brazil Food Additives Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in Brazil's food additive supply structure. The market presents a consolidated top tier where multinational ingredient houses control corn wet milling and oilseed processing infrastructure, while mid-scale domestic blenders occupy specialized niches. Three archetypes dominate: integrated agribusiness processors with captive raw material supply, specialized fermentation houses delivering clean-label alternatives, and formulation service providers bundling regulatory submission support. Competitive intensity concentrates on backward integration into agricultural inputs and geographic expansion toward underpenetrated northeastern manufacturing zones.
Within the integrated processor tier, Ingredion Incorporated and Cargill, Incorporated exemplify scale-driven positioning anchored in Brazilian corn and oilseed infrastructure. Kerry Group plc occupies a distinct formulation-services archetype, bundling taste and nutrition solutions with ANVISA compliance support. These three entities represent contrasting strategic postures: captive agricultural supply versus technical application expertise.
| Leading Market Players |
|---|
| Ingredion Incorporated |
| Archer Daniels Midland Company |
| BASF SE |
| Givaudan SA |
| Tate & Lyle plc |
| Cargill, Incorporated |
| Kerry Group plc |
| Corbion NV |
| DuPont de Nemours, Inc. |
| Others |
Value Chain & Pricing Dynamics
Campinas and Sorocaba's concentrated food manufacturing parks anchor Brazil's additive pricing power through captive corn wet milling capacity that insulates domestic starch processors from import cost volatility. Direct supply agreements between these southeastern clusters and ingredient houses are compressing distributor margins while elevating volume-based contract leverage for large meat and beverage processors.
Pricing Analysis
ANVISA's RDC resolution system dictates the pricing tier structure across Brazil's food additive market. Three-tier pricing separates premium clean-label enzyme systems from standard synthetic preservatives and economy-grade commodity emulsifiers. Price differentiation rests on certification grade and after-sales formulation support intensity. Cost compression in the synthetic preservatory tier is intensifying because ANVISA's toxicological re-evaluations are accelerating reformulation demand. Small regional bakeries in Pernambuco and Ceará exhibit highest price sensitivity, while multinational meat processors in São Paulo state prioritize technical service over unit cost.
Supply Chain Analysis
Corn wet milling infrastructure in Brazil, Argentina, and the United States feeds Brazil's starch derivative and lecithin supply base. Domestic production draws from yellow corn feedstock, imported palm oil fractions, and fermentation-derived enzyme cultures. Single-source vulnerability concentrates in specialized lipid-water emulsifiers where local blending capacity lags demand growth. Distribution runs through direct procurement relationships between large manufacturers and integrated processors, bypassing traditional distributor networks in southeastern industrial corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against enzyme-based clean-label substitutes that ANVISA's pending novel food consultations could fast-track into premium positioning, eroding synthetic preservative margins.
For Market Incumbents: Build regulatory submission expertise as a moat by expanding ANVISA compliance support teams and pre-approving reformulation pathways ahead of RDC resolution updates. Secure backward integration into domestic corn processing to reduce agricultural input volatility exposure. Accelerate natural antioxidant and cultured dextrose capacity to preempt synthetic benzoate delisting. For New Entrants and Emerging Players: Bahia's underpenetrated food manufacturing base offers first-mover positioning for regional distribution hubs serving northeastern consumer markets with powder-format additives suited to cold chain gaps. Target Pernambuco and Ceará dairy cooperatives with yeast extract flavor enhancers addressing sodium reduction mandates. Enter through formulation service contracts that bundle regulatory submission support with product supply. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because ANVISA's positive list compliance friction favors scaled ingredient houses with dedicated toxicological assessment capabilities over fragmented domestic blenders. Acquire mid-scale fermentation houses delivering clean-label alternatives before regulatory pathway clarity drives valuation expansion. Monitor ANVISA's novel food consultation outcomes as the inflection signal determining competitive positioning in premium segments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Corn Wet Milling | Captive starch supply insulates Ingredion and Cargill from agricultural commodity swings. |
| Clean-Label Certification Convergence | Integration of natural preservation with organic standards opens premium channel access. |
| Regional Distribution Hub Expansion | Northeastern hubs in Bahia reduce logistics costs for underpenetrated manufacturing zones. |
| Formulation Service Bundling | Technical application laboratories deepen supplier relationships with São Paulo meat processors. |
| Microencapsulation Technology Adoption | Volatile antimicrobial encapsulation renders conventional spray-dried systems obsolete in tropical humidity. |
Study Parameters
Desk research of ANVISA regulatory filings, Mercosur harmonization protocols, and Brazilian agricultural trade statistics preceded structured interviews with food manufacturing procurement directors, formulation chemists at ingredient houses, and regulatory affairs specialists. Primary fieldwork with corn wet milling operations and dairy cooperatives in Minas Gerais validated secondary estimates. Bottom-up volume modeling triangulated against top-down value projections from customs and production data.
Assumptions held ANVISA's RDC resolution timeline and Mercosur export shelf-life mandates constant across the projection horizon. Segmentation modeling incorporated product type, physical form, application, and end-user scale dimensions. CAGRs derived from trend extrapolation of procurement volumes in São Paulo's industrial corridor, adjusted for northeastern manufacturing expansion potential. Forecast inputs included corn yield volatility patterns and clean-label enzyme approval probability assessments.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Argentine ingredient exporters or accelerated ANVISA novel food approvals would shift outcomes beyond modeled ranges. Cross-checking against Brazilian Food Processors Association procurement surveys and ANVISA pre-market authorization databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Russia Anti Caking Market
Food Additives and Ingredients
Non-GMO Citric Acid Market
Food Additives and Ingredients
Microencapsulated Phytosterols Market
Food Additives and Ingredients
Oleic Acid Market
Food Additives and Ingredients
Synthetic Food Preservatives Market
Food Additives and Ingredients
Antimicrobial Packaging Ingredients for Food Packaging Market
Food Additives and Ingredients
Brazil Food Acidulants Market
Food Additives and Ingredients
South America Food Acidulants Market
Food Additives and Ingredients
Argentina Food Preservatives Market
Food Additives and Ingredients
Beverage Stabilizer Market
Food Additives and Ingredients
Global Oleate Esters Market
Food Additives and Ingredients
North America Fermented Ingredient Market
Food Additives and Ingredients
Germany Food Enzymes Market
Food Additives and Ingredients
Potassium Polymetaphosphate Food Additives Market
Food Additives and Ingredients
Natural Ferulic Acid Market
Food Additives and Ingredients
Food Grade Ammonium Carbonate Market