
 Europe Pet Food Market | 2026-2036
Europe Pet Food Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Pet Food Market Analysis
Specialty retail is fragmenting across Europe as digital platforms and veterinary clinics capture incremental share from traditional supermarkets. Mars, Incorporated leverages its veterinary clinic partnerships to lock in prescription diet customers. Nestle (Purina) sustains dominance in kibble through manufacturing scale across British and French plants. Deuerer GmbH anchors its position in private-label production for German discounters.
Europe pet food encompasses nutritionally formulated products manufactured through extrusion, retorting, or freeze-drying processes to deliver complete or complementary diets for domestic animals. Extrusion temperatures typically reach 120–150°C to gelatinize starches and ensure pathogen elimination while preserving protein digestibility. Kibble occupies the largest volume share given its shelf stability and lower per-kilogram logistics cost, though raw food represents the fastest-expanding margin pool as cold-chain infrastructure improves. Premium price tiers command disproportionate profit contribution despite mid-range products moving the highest absolute tonnage.
The EU Green Deal and F-Gas Regulation are tightening cold-chain emissions standards, directly elevating compliance costs for canned and raw food producers. EFSA nutritional adequacy guidelines and REACH chemical safety protocols shape ingredient sourcing decisions across formulations. Stakeholders must monitor evolving packaging waste directives and veterinary channel consolidation to anticipate where margin compression or pricing power will emerge next.
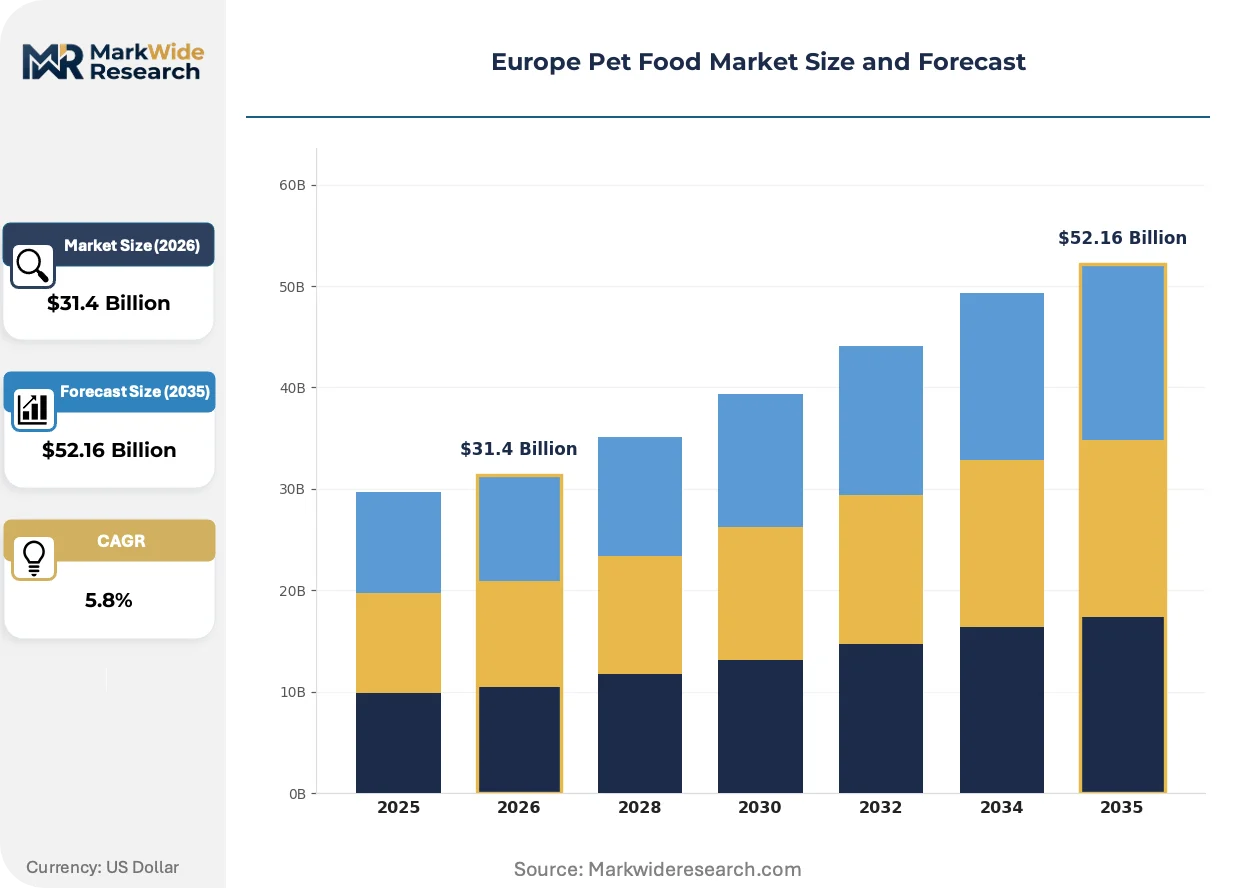
Market Dynamics
The EU Green Deal and F-Gas Regulation are compressing margins for wet and raw food producers while veterinary channel consolidation reshapes customer access. Cold-chain compliance costs now rival ingredient spend in premium segments.
Growth Catalysts
- Humanization of pet diets:Owners increasingly seek fresh, minimally processed formats that mirror their own nutritional preferences. EFSA nutritional adequacy guidelines provide a trusted framework for product positioning.
- Veterinary channel expansion:Prescription diet sales through clinics lock in recurring revenue streams. Mars, Incorporated leverages its Banfield and BluePearl networks to capture lifetime customer value.
- Freeze-drying technology maturation:Cold-chain infrastructure improvements reduce spoilage losses for raw food distribution. Germany and France lead capital deployment in this preservation method.
Market Restraints
- Protein input cost volatility:Fish meal and poultry by-product prices swing with aquaculture and meatpacking cycles. Formulators lack hedging instruments for these commodity streams.
- REACH chemical safety protocols:Additive approval timelines extend 18-24 months for novel preservatives. European producers face asymmetric compliance burdens versus non-EU imports.
- Substitution by home-prepared diets:Subscription meal-kit services for pets capture price-sensitive households. These direct-to-consumer models bypass retail markup structures entirely.
Strategic Opportunities
- Underpenetrated Eastern European markets:Poland and Romania exhibit kibble consumption growth without corresponding premium wet food adoption. First-mover brands can establish category definitions.
- Insect protein regulatory tailwind:EFSA novel food approvals for black soldier fly larvae unlock sustainable ingredient sourcing. Early formulations gain carbon-footprint marketing differentiation.
- Pharmacy channel integration:Boots and similar health retailers in the United Kingdom test pet wellness sections. This convergence of human and animal health retail creates new shelf space.
Industry Challenges
- Extrusion engineering talent scarcity:Operators who optimize 120-150°C process parameters for protein digestibility command premium wages. Technical training pipelines remain underdeveloped.
- Packaging waste directive compliance:Recyclable mono-material films for retort pouches require capital-intensive line conversions. Smaller canneries delay investment due to payback uncertainty.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Pet Food Market |
| Market Size in 2026 | $31.4 Billion |
| Market Size in 2035 | $52.16 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Kibble, Canned Food, Treats, Raw Food Animal Type: Dogs, Cats, Birds, Small Mammals Distribution Channel: Online Stores, Pet Specialty Retailers, Supermarkets, Veterinary Clinics Price Tier: Premium, Mid-Range, Economy, Budget |
| Companies Covered | General Mills Inc., Archer Daniels Midland (ADM), Mars, Incorporated, Virbac, Heristo aktiengesellschaft, Nestle (Purina), Affinity Petcare S.A, Deuerer GmbH, Colgate-Palmolive Company (Hill's Pet Nutrition, Inc.), Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Pet Food Market Emerging Trajectories
Refrigerated pet food formats are migrating from niche specialty toward mainstream distribution as cold-chain infrastructure matures and owner preferences shift toward fresh nutrition.
High-pressure processing is migrating from human juice applications into raw pet food sterilization. Premium raw brands in France and the United Kingdom adopt this non-thermal method to eliminate pathogens without nutrient degradation. Shelf-life extension from 7 to 45 days enables conventional retail placement previously impossible for unprocessed formats.
REACH chemical safety protocols now mandate expanded substance testing for packaging migrants entering food contact. Retort pouch suppliers reformulate adhesive layers to eliminate bisphenol analogs. German and British manufacturers accelerate compliance timelines ahead of 2027 enforcement windows to secure retail listings.
Subscription replenishment models displace supermarket bulk purchasing among urban dog owners. Direct-to-consumer platforms capture recurring revenue through algorithmic portion sizing. London and Paris exhibit the highest penetration of these auto-ship services, with veterinary endorsement driving trial conversion.
Europe Pet Food Market Segmentation
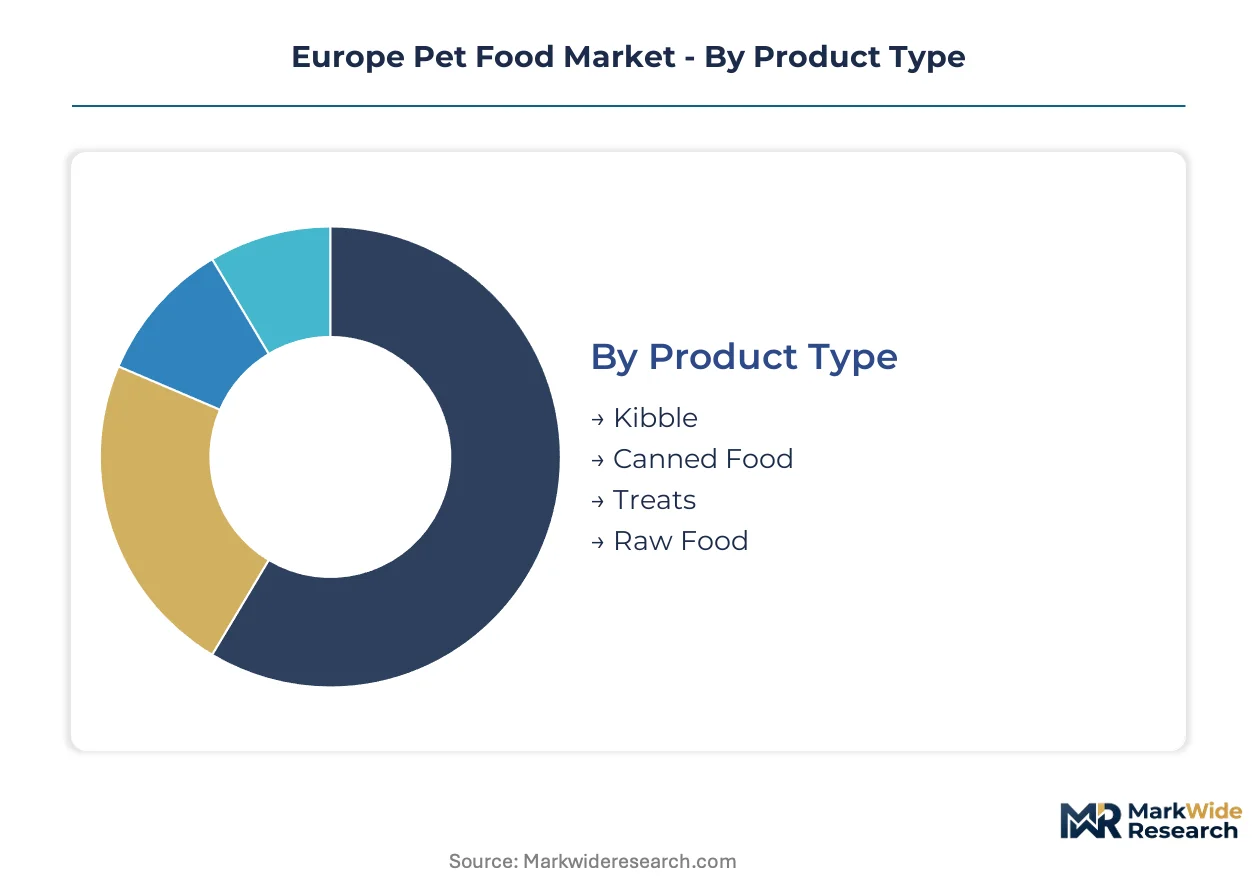
Pet food manufacturers must align production capabilities with distinct consumption patterns across product formats, species requirements, and channel economics. Segmentation reveals where formulation investments generate returns and where distribution partnerships determine market access.
Product Type:
After-sales service intensity varies sharply across product types, with raw and wet formats demanding cold-chain support and nutritional consultation that dry kibble rarely requires.
- Kibble:Extruded dry formulations processed at 120–150°C achieve shelf stability through moisture reduction below 10%. German and French manufacturing plants optimize throughput for this format, leveraging lower logistics costs to serve price-sensitive households across Eastern Europe.
- Canned Food:Retort-sterilized wet products deliver higher moisture content and palatability for senior animals and medical diets. The EU Green Deal and F-Gas Regulation elevate cold-chain compliance costs for producers distributing these formats through veterinary channels in the United Kingdom and France.
- Treats:Complementary snacks span functional dental chews to high-protein training rewards. EFSA nutritional adequacy guidelines constrain health claim positioning for functional formulations.
- Raw Food:Minimally processed frozen or freeze-dried diets mirror human fresh-food preferences. High-pressure processing adoption in France and the United Kingdom extends shelf life from 7 to 45 days, enabling conventional retail placement.
Kibble holds the largest share; momentum sits with raw food as cold-chain infrastructure matures.
Animal Type:
Formulation complexity and margin structure diverge significantly across species, with canine and feline diets commanding dedicated R&D investment while smaller segments rely on adapted portfolios.
- Dogs:Complete diets span growth, maintenance, and therapeutic life stages with breed-specific kibble sizing. German households drive premiumization intensity, with prescription diet sales through veterinary clinics locking recurring revenue for manufacturers.
- Cats:Obligate carnivore physiology demands higher protein inclusion and taurine supplementation. United Kingdom consumers lead wet food attachment, though kibble retains volume dominance for free-feeding convenience.
- Birds:Seed blends and formulated pellets target psittacine nutritional requirements. Specialized avian veterinary networks in France and Germany concentrate distribution for premium formulations.
- Small Mammals:Rabbits, guinea pigs, and rodents require high-fiber, low-carbohydrate profiles distinct from carnivore formulations. Private-label producers serving German discounters anchor volume in this commoditized segment.
Dogs command the greatest revenue concentration; cats exhibit the steepest premiumization trajectory.
Distribution Channel:
Channel selection determines customer acquisition economics and brand positioning latitude, with veterinary and digital routes displacing traditional retail for high-margin segments.
- Online Stores:Direct-to-consumer platforms capture urban dog owners through algorithmic portion sizing and subscription replenishment. London and Paris show highest auto-ship penetration, with veterinary endorsement driving trial conversion.
- Pet Specialty Retailers:Independent and chain stores provide assortment breadth and staff consultation for format-switching owners. Specialty retail fragments across Europe as digital platforms capture incremental share.
- Supermarkets:Mass retail moves highest absolute tonnage in mid-range and economy tiers. Shelf space compression favors suppliers with manufacturing scale across British and French plants.
- Veterinary Clinics:Prescription diet sales lock lifetime customer value through medical endorsement. Mars, Incorporated leverages Banfield and BluePearl networks to defend this channel.
Veterinary clinics deliver the highest margin per kilogram; online stores are expanding most quickly.
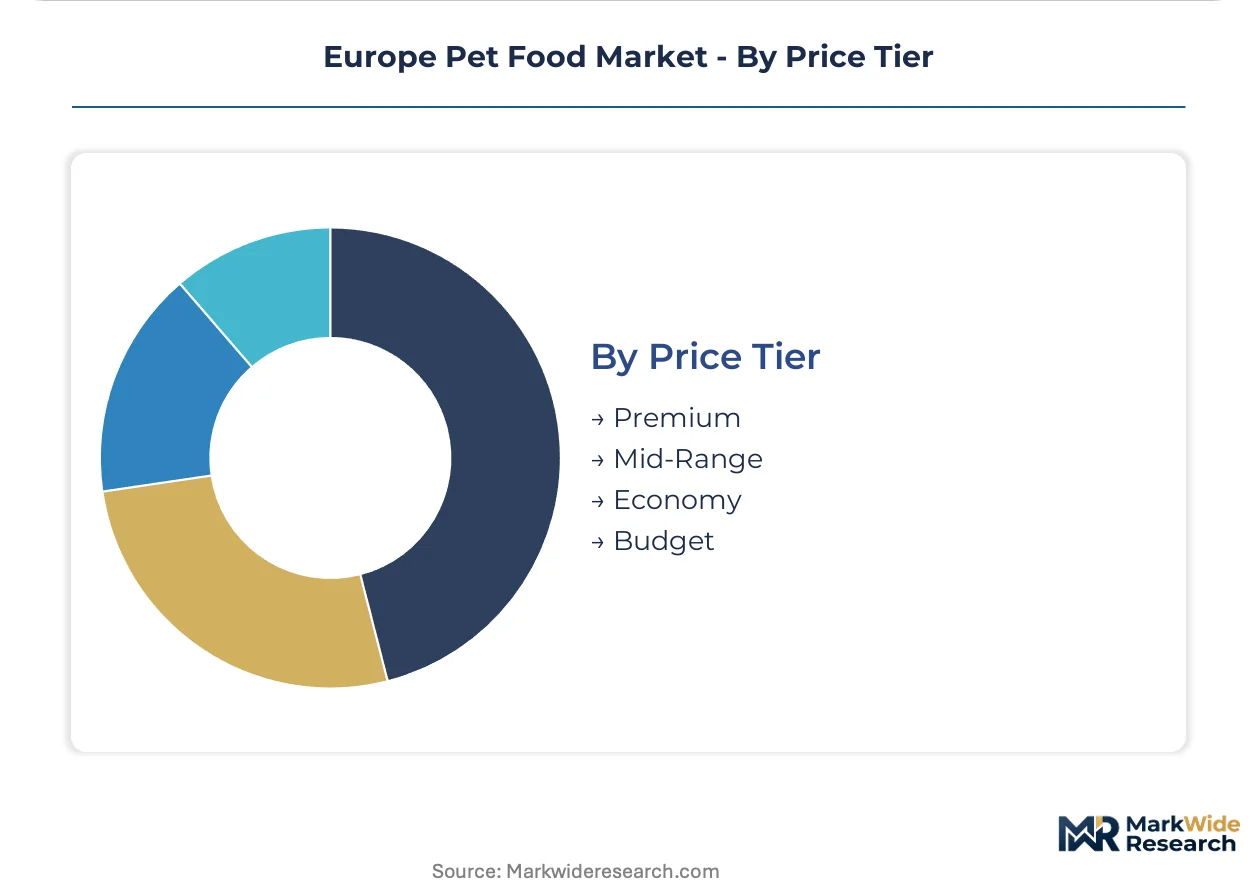
Price Tier:
Pricing architecture reflects ingredient sourcing intensity, manufacturing complexity, and certification burden rather than simple brand premium extraction.
- Premium:Human-grade proteins, novel ingredients like insect meal, and freeze-dried formats command disproportionate profit contribution. EFSA novel food approvals for black soldier fly larvae unlock sustainable sourcing differentiation.
- Mid-Range:Balanced nutrition at accessible price points moves highest absolute tonnage. REACH chemical safety protocols and extended additive approval timelines compress margin for European producers versus non-EU imports.
- Economy:Standard extruded kibble serves price-sensitive households through supermarket and discounter channels. Deuerer GmbH anchors private-label production for German discounters in this tier.
- Budget:Basic formulations meet minimum nutritional adequacy with commodity protein inputs. Fish meal and poultry by-product price volatility constrains formulator hedging capacity.
Premium tiers generate disproportionate profit contribution; mid-range products move the highest absolute tonnage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA nutritional adequacy guidelines anchor regulatory harmonization across the European Union, shaping formulation standards from Lisbon to Tallinn. National implementations vary in enforcement intensity and veterinary channel penetration, creating differentiated competitive terrain for manufacturers.
Germany
German households drive premiumization intensity across canine and feline segments, with prescription diet sales through veterinary clinics locking recurring revenue streams. The EU Green Deal and F-Gas Regulation elevate cold-chain compliance costs for wet food producers distributing through Bavarian and North Rhine-Westphalia veterinary networks. Manufacturing gravity concentrates in Lower Saxony and Baden-Württemberg, where extrusion plants optimize throughput for Eastern European export markets.
France
French consumers exhibit the strongest wet food attachment for cats, driven by veterinary endorsement of moisture-rich formulations for renal health. ANSM and EFSA coordinate on novel food approvals, with black soldier fly larvae gaining traction as sustainable protein inputs. Industrial clustering in Brittany and the Loire Valley supports retort canning capacity serving both domestic demand and Benelux export channels.
United Kingdom
London and Paris exhibit the highest penetration of subscription-based pet food replenishment, with algorithmic portion sizing capturing urban dog owners. Boots and comparable health retailers test pet wellness sections, converging human and animal health retail formats. Cold-chain infrastructure improvements in the Southeast enable refrigerated format distribution previously limited to veterinary clinics.
Poland
Polish households exhibit kibble consumption growth without corresponding premium wet food adoption, creating first-mover opportunities for category-defining brands. REACH chemical safety protocols impose asymmetric compliance burdens versus non-EU imports, favoring established European producers. Manufacturing investment concentrates in the Łódź and Wrocław regions, serving price-sensitive Eastern European markets.
Italy
Italian pet owners demonstrate growing attachment to freeze-dried and minimally processed formats mirroring human fresh-food preferences. EFSA novel food approval timelines constrain rapid ingredient innovation, though Lombardy-based formulators leverage Swiss and Austrian sourcing relationships. Veterinary channel consolidation in Emilia-Romagna and Veneto reshapes prescription diet access for aging pet populations.
Europe Pet Food Market Vendor Landscape
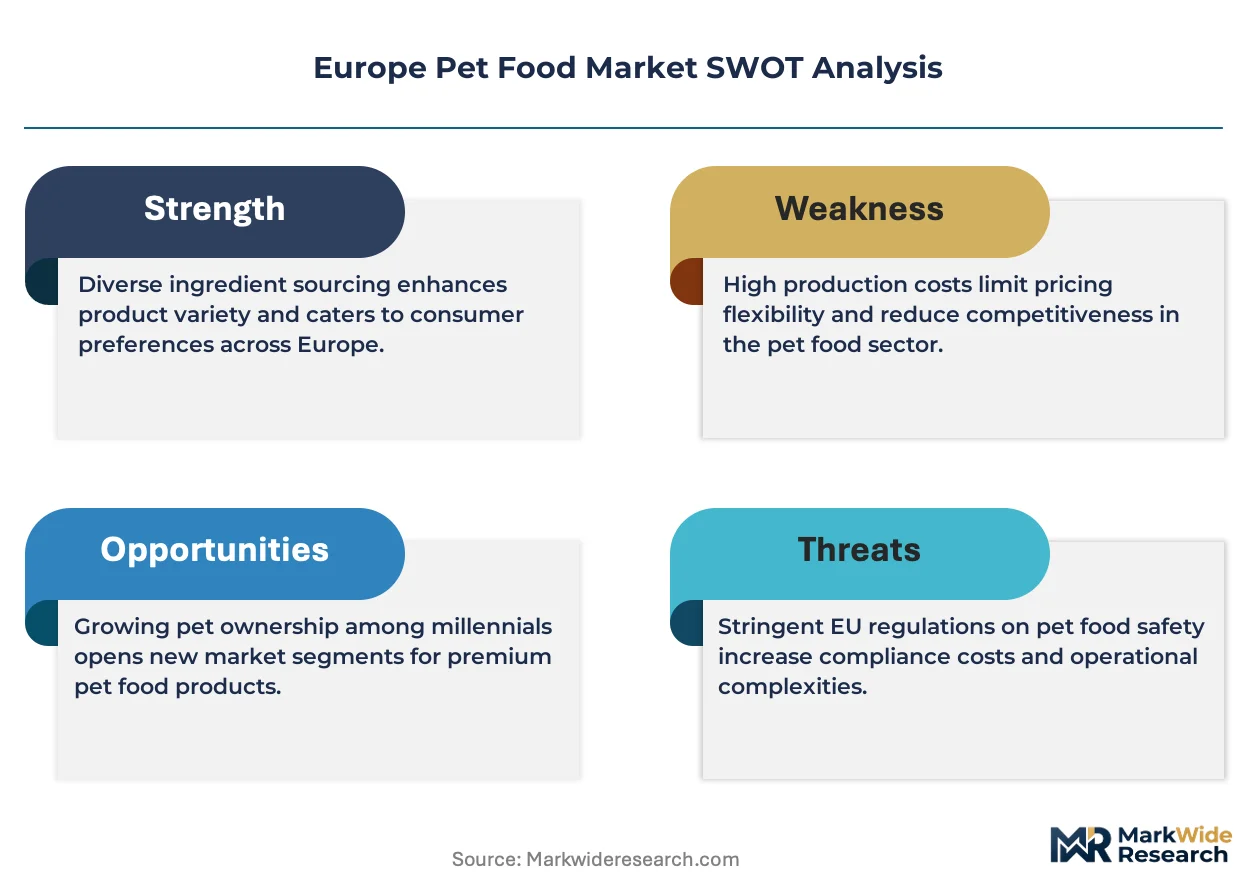
Vertically integrated multinationals and specialized private-label producers split the market along premium-versus-economy fault lines. Mars, Incorporated and Nestle (Purina) anchor the consolidated tier through manufacturing scale and veterinary channel ownership, while mid-cap specialists occupy differentiated nutrition niches. Strategic archetypes include prescription diet specialists leveraging clinic networks, private-label manufacturers serving discounter channels, and novel ingredient innovators awaiting regulatory clearance. Competitive moves concentrate on veterinary clinic acquisitions and cold-chain capacity expansion for raw format distribution.
Within the prescription diet tier, Mars, Incorporated and Colgate-Palmolive Company exemplify clinic-network-dependent models, while Deuerer GmbH anchors private-label production for German discounters. Nestle (Purina) occupies a position bridging mass-market scale and premium positioning through British and French manufacturing assets. These three entities represent distinct strategic postures: veterinary channel lock-in, discounter supply efficiency, and manufacturing scale across multiple price tiers.
| Leading Market Players |
|---|
| General Mills Inc. |
| Archer Daniels Midland (ADM) |
| Mars, Incorporated |
| Virbac |
| Heristo aktiengesellschaft |
| Nestle (Purina) |
| Affinity Petcare S.A |
| Deuerer GmbH |
| Colgate-Palmolive Company (Hill's Pet Nutrition, Inc.) |
| Others |
Supply Flow & Price Mechanics
The Rotterdam-Frankfurt freight corridor shapes cost dynamics across wet and raw food distribution, concentrating supply leverage with German and French producers while forcing price differentiation between cold-chain-dependent formats and shelf-stable kibble. Cold-chain compliance costs under the EU Green Deal now rival ingredient spend, compressing margins for canned producers and amplifying pricing power for extrusion-based manufacturers serving Eastern European markets.
Pricing Analysis
The customization-premium spread widens as subscription-based portion sizing captures urban dog owners willing to pay algorithmic-configuration premiums, while standard kibble pricing faces compression from discounter private-label competition. Three-tier pricing structure across premium, standard, and economy levels reflects ingredient certification intensity, with EFSA novel food approvals for insect proteins enabling carbon-footprint premiums. Price differentiation hinges on veterinary channel endorsement and cold-chain service bundling. Price-sensitive households concentrate in Poland and Romania, while least-sensitive buyers cluster in German veterinary clinic networks.
Supply Chain Analysis
Upstream feedstock flows from German meatpacking clusters, French aquaculture operations, and Dutch insect farming facilities anchor protein input availability for formulators. Raw material dependencies center on fish meal, poultry by-products, and emerging black soldier fly larvae streams. Single-source vulnerability concentrates in freeze-dried ingredient supply, where limited European capacity creates bottleneck risk. Distribution runs through veterinary clinic networks for prescription diets, direct-to-consumer platforms for subscription models, and mass retail for economy kibble.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe pet food operates as a service-attach opportunity where nutritional consultation and cold-chain logistics expand faster than base product manufacturing, with subscription replenishment models capturing recurring revenue previously lost to supermarket bulk purchasing.
For Market Incumbents: Harden veterinary channel control through exclusive prescription diet formulations that lock lifetime customer value, while consolidating freeze-drying capacity in Germany and France to defend against raw format entrants. Deepen backward integration into insect protein supply as EFSA approvals mature, securing sustainable ingredient differentiation before novel food windows close.
For New Entrants and Emerging Players: Mid-market wet food adoption gaps in Poland and Romania represent the most penetrable entry point for category-defining brands, with pharmacy channel integration in the United Kingdom offering secondary white-space. First-mover positioning in high-pressure processed raw formats enables conventional retail placement without legacy cold-chain infrastructure burdens.
For Investors and Strategic Acquirers: Carve-out targets emerge from multinational consumer goods parents seeking portfolio simplification, particularly private-label manufacturers with discounter relationships or regional freeze-drying specialists with underutilized capacity. Long-term viability favors assets with veterinary channel access and regulatory clearance pipelines. The signal to watch is consolidation velocity in Emilia-Romagna and Veneto clinic networks as prescription diet gatekeeping intensifies.
| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Capacity Expansion | EU Green Deal compliance investments in retort canning and refrigerated logistics secure wet food margin structure against regulatory compression. |
| Veterinary Clinic Network Acquisition | Banfield and BluePearl-type consolidation locks prescription diet distribution, capturing lifetime customer value through medical endorsement. |
| Insect Protein Formulation Development | EFSA novel food approvals for black soldier fly larvae unlock carbon-footprint marketing differentiation and sustainable sourcing narratives. |
| Direct-to-Consumer Platform Launch | Algorithmic portion sizing and auto-ship replenishment capture urban dog owners in London and Paris with recurring revenue models. |
| High-Pressure Processing Adoption | Non-thermal sterilization extends raw food shelf life from 7 to 45 days, enabling conventional retail placement without nutrient degradation. |
Methodological Framework
Cross-validation between trade association production data and customs import records anchors the qualitative findings, with primary interviews conducted among veterinary clinic operators, pet specialty retail category managers, extrusion plant engineers, and cold-chain logistics coordinators. Secondary sources span FEDIAF industry statistics, EFSA novel food approval registers, and REACH chemical safety compliance filings. Bottom-up capacity modeling and top-down consumption surveys triangulate volume estimates across the analysis window.
Calibration against historical price elasticities and channel shift patterns informs the projection framework, with segmentation modeling across product format, species requirement, distribution channel, and price tier. CAGRs derive from fitted growth curves applied to category penetration rates and per-household spending trajectories. Forecast inputs incorporate veterinary clinic consolidation timelines and cold-chain infrastructure deployment schedules.
Macroeconomic conditions sit as an overlay; deviation in disposable income growth, protein commodity cycles, or regulatory enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions about EFSA approval timelines and F-Gas Regulation implementation phases. Cross-checking against Nielsen retail audit data and veterinary practice management system trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Tofu Cat Litter Market
Pet Care Products
China Pet Boarding Market
Pet Care Products
Pet Rugs Market
Pet Care Products
Dog Life Jacket Market
Pet Care Products
Dog Clothes Market
Pet Care Products
Cat Backpacks Market
Pet Care Products
Pet Treats Market
Pet Care Products
Pet Toys Market
Pet Care Products
Philippines Pet Food Market
Pet Care Products
UK Pet Diet Market
Pet Care Products
Dog Box Market
Pet Care Products
Insulated Dog House Market
Pet Care Products
Plant-Based Pet Food Market
Pet Care Products
Organic Pet Food Market
Pet Care Products
PET Market
Pet Care Products
Pet Bathing Supplies Market