
 North America Pet Food Market | 2026-2036
North America Pet Food Market Size, Share, and Industry Trends Forecast 2026-2036
North America Pet Food Market Outlook
Veterinary clinic recommendations are expanding as a decisive channel for therapeutic and prescription pet food sales. Nestlé Purina PetCare leverages its science-backed Pro Plan Veterinary Diets line to anchor relationships with clinic networks. Mars Petcare Inc. competes through its Royal Canin brand, which sustains breed-specific and condition-specific formulations developed with veterinary input. The J.M. Smucker Company differentiates via Meow Mix and Milk-Bone brand strength in mass retail, controlling shelf space across supermarkets and big-box stores.
North America pet food encompasses commercially manufactured nutrition products formulated from proteins, carbohydrates, fats, vitamins, and minerals to meet AAFCO nutrient profiles for dogs, cats, and companion animals, typically processed through extrusion for dry kibble or retort sterilization for wet canned formats to ensure shelf stability and pathogen elimination. Dry food remains the volume backbone due to lower per-serving cost and storage convenience, though functional ingredient types containing probiotics, omega fatty acids, and joint-support compounds command disproportionate margin pools as owners seek condition-specific benefits. Raw food occupies a fast-growing niche despite refrigeration burdens and pathogen concerns, with grain-free formulations navigating reformulation pressures following FDA investigations into dilated cardiomyopathy links.
The FDA's Center for Veterinary Medicine enforces ingredient safety and labeling accuracy, while state feed control officials through AAFCO coordinate model bill adoption that shapes interstate commerce requirements. California's Proposition 65 chemical warning mandates and Canada's CFIA Safe Food for Canadians Regulations impose additional compliance layers affecting formulation and packaging decisions. Stakeholders must monitor evolving state-level clean label legislation and veterinary telehealth expansion, which together will reshape prescription diet dispensing and direct-to-consumer channel economics.
Market Dynamics
Veterinary telehealth expansion and the FDA's evolving dilated cardiomyopathy investigations are compressing formulation cycles and rewiring prescription diet dispensing channels across the United States and Canada.
Growth Catalysts
- AAFCO Model Bill Harmonization:State feed control officials coordinate nutrient profile standards that reduce interstate friction for manufacturers shipping across the United States and Canada.
- Condition-Specific Formulation Demand:Aging pet populations in California and Texas drive therapeutic nutrition protocols targeting renal, joint, and cognitive health endpoints.
- Cold Chain Infrastructure Maturation:Refrigerated logistics networks in the Upper Midwest and Pacific Northwest enable raw and fresh pet food distribution without spoilage penalties.
Market Restraints
- Animal Protein Input Volatility:Chicken meal and fish oil prices fluctuate with commodity feed markets, squeezing margin predictability for mid-tier manufacturers.
- Regulatory Friction from Proposition 65:California's chemical warning mandates force reformulation or label redesign for products containing trace contaminants, adding compliance overhead.
- Pathogen Surveillance Burden:CFIA Safe Food for Canadians Regulations and FDA CVM testing protocols impose batch-level documentation requirements that slow small-brand scaling.
Strategic Opportunities
- Veterinary Telehealth Dispensing:Remote consultation platforms in Texas and Florida create direct-to-home prescription diet channels that bypass traditional clinic inventory constraints.
- Insect Protein Convergence:Black soldier fly larvae meal combined with precision fermentation amino acids offers novel hypoallergenic formulations for sensitive digestive systems.
- Canadian Prairie Manufacturing:Underutilized processing capacity in Saskatchewan and Manitoba positions regional players for export into U.S. northern tier markets.
Industry Challenges
- Veterinary Nutritionist Talent Scarcity:Board-certified veterinary nutritionists remain concentrated in university research hospitals, limiting R&D bandwidth for emerging brands.
- Extrusion Equipment Lead Times:Specialized high-shear extruders required for novel protein processing face 18-month delivery backlogs from European and Asian equipment fabricators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Pet Food Market |
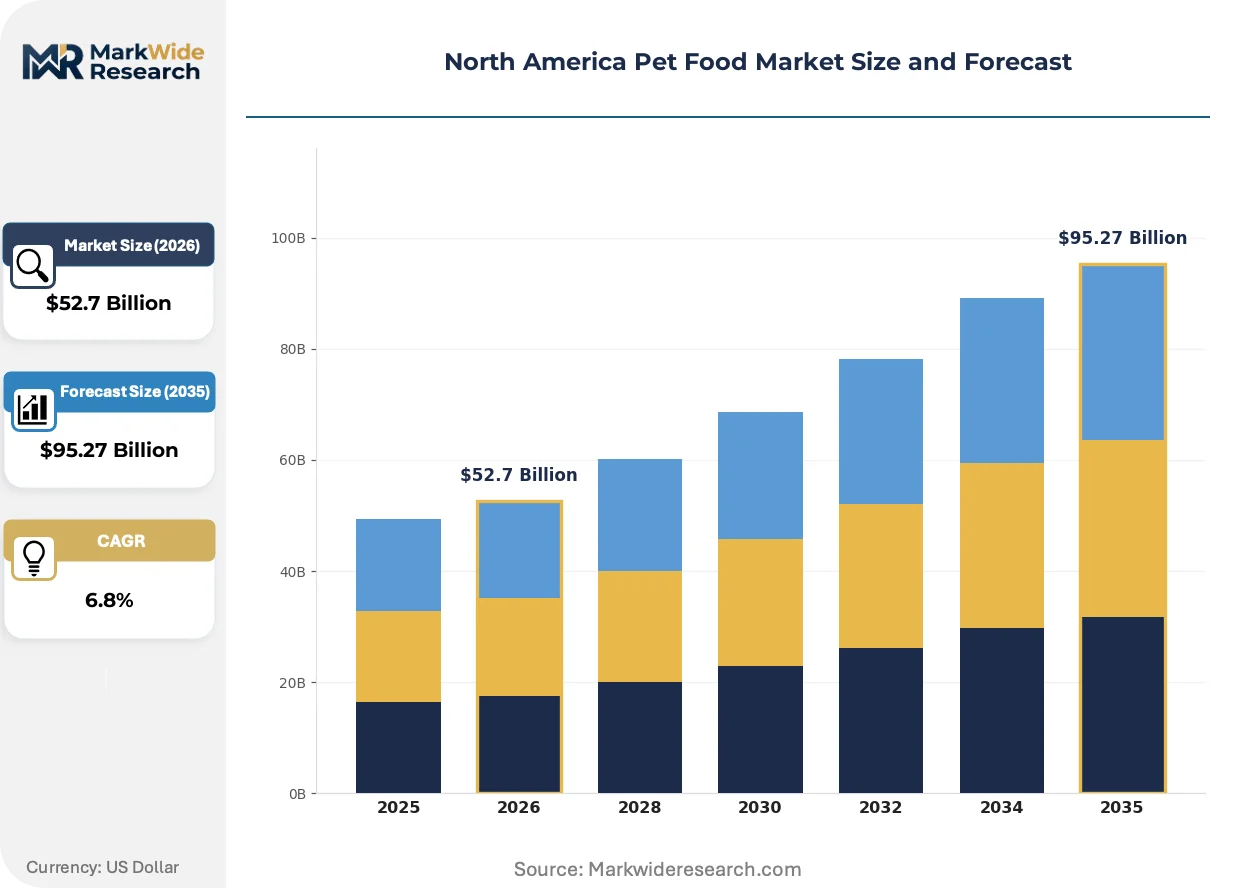
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $95.27 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Treats, Raw Food End User: Pet Owners, Veterinary Clinics, Retailers, Animal Shelters Ingredient Type: Meat-Based, Grain-Free, Organic, Functional Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Pet Food Stores |
| Companies Covered | The J.M. Smucker Company, Diamond Pet Foods, Mars Petcare Inc., Wellness Pet LLC, Spectrum Brands/United Pet Group, Nestlé Purina PetCare, General Mills, Inc., Post Holdings, Inc., Colgate-Palmolive Company (Hill's Pet Nutrition), Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Pet Food Market Strategic Shifts
Precision nutrition platforms and alternative protein sourcing are collapsing the traditional kibble-wet binary, while regulatory scrutiny of cardiac health claims forces transparency in formulation marketing.
High-moisture fresh-frozen formats produced via high-pressure processing are rewriting shelf-life assumptions for refrigerated pet food. Premium households in metropolitan California and Texas adopt these products on weekly subscription cycles. The technology is compressing the advantage legacy retort sterilization held over nutrient retention.
The FDA's ongoing dilated cardiomyopathy investigation into grain-free formulations has triggered mandatory taurine disclosure and legume-content caps. Manufacturers reformulate pulse-heavy recipes to reduce pea and lentil concentrations below investigatory thresholds. Boutique brands in the Pacific Northwest face the steepest label overhaul costs.
Subscription-based replenishment models displace supermarket impulse purchases among millennial and Gen Z pet owners. Direct-to-consumer platforms capture recurring revenue through algorithmic portion calculations based on breed, weight, and activity data. This channel rotation concentrates in urban Canadian markets and coastal U.S. cities where delivery density supports cold-chain economics.
North America Pet Food Market Segmentation
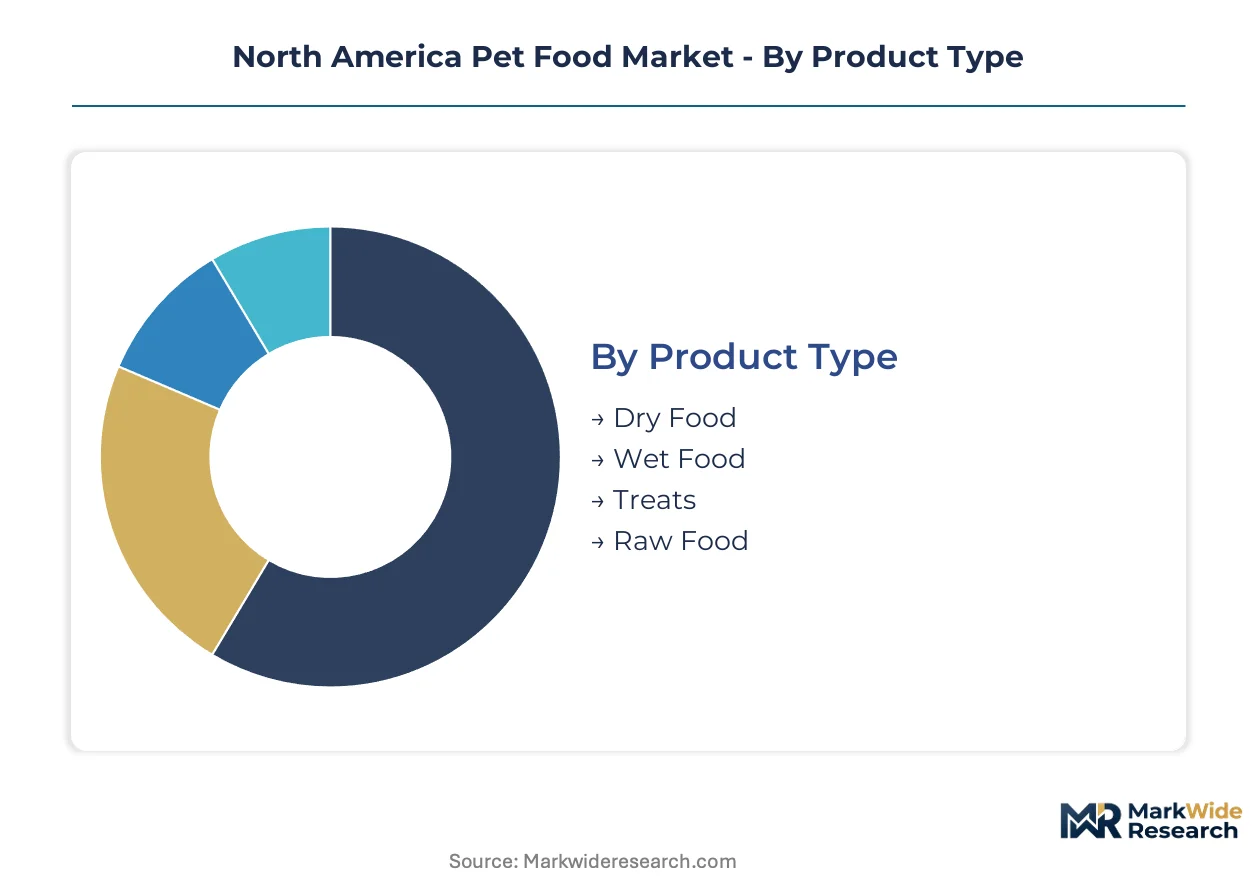
Pet food segmentation reveals how formulation technology and channel economics create distinct margin pools across the United States and Canada. Manufacturers calibrate protein sourcing, moisture content, and distribution strategy to capture specific household spending tiers and veterinary endorsement channels.
Product Type:
Upgrade cycles in pet nutrition follow humanization trends, with owners replacing basic kibble as disposable income rises and veterinary guidance intensifies.
- Dry Food:Extruded kibble formulations dominate household penetration due to shelf stability and lower per-serving cost. California and Texas households stock dry food as baseline nutrition, though premiumization pressures force mid-tier brands toward functional additive differentiation.
- Wet Food:Retort-sterilized cans and pouches deliver higher moisture content and palatability for aging pets with dental constraints. Demand concentrates in metropolitan markets where subscription services bundle wet food with veterinary telehealth consultations.
- Treats:Training rewards and dental chews occupy impulse-purchase occasions across supermarket and big-box channels.
- Raw Food:Refrigerated fresh and frozen formats gain traction among Pacific Northwest and Upper Midwest households with cold-chain access.
Dry food sits at the top of the volume ranking, with raw food climbing the fastest.
End User:
Customer type determines pricing power and formulation complexity, with veterinary channels commanding premium positioning over mass retail.
- Pet Owners:Direct purchasers drive volume through subscription platforms and retail stock-up behavior, with coastal urban households showing highest willingness-to-pay for fresh formats.
- Veterinary Clinics:Prescription diet dispensing anchors therapeutic nutrition revenue, with Texas and Florida telehealth platforms expanding remote fulfillment beyond physical clinic inventory.
- Retailers:Supermarket and big-box buyers negotiate slotting fees and promotional calendar access for mass-market brands.
- Animal Shelters:Bulk procurement contracts prioritize cost efficiency and nutritional adequacy over premium positioning.
Pet owners generate the largest absolute revenue base, while veterinary clinics deliver the steepest expansion trajectory.
Ingredient Type:
Input sourcing strategy separates margin profiles, with novel proteins and certified organic commanding shelf price premiums over conventional formulations.
- Meat-Based:Chicken, beef, and fish meals provide complete amino acid profiles through conventional rendering and extrusion processes. Price volatility in commodity feed markets squeezes mid-tier manufacturer margins.
- Grain-Free:Legume and pulse-heavy formulations face FDA dilated cardiomyopathy scrutiny, forcing taurine supplementation and pea-content reductions below investigatory thresholds.
- Organic:USDA Organic and Canada Organic certification requirements limit supplier pools and extend procurement lead times.
- Functional:Probiotic, omega fatty acid, and joint-support additives target condition-specific endpoints in aging pet populations.
Meat-based formulations retain volume leadership, with functional ingredients gaining share fastest.
Distribution Channel:
Channel selection dictates cold-chain requirements and customer acquisition economics, with digital platforms reshaping replenishment patterns.
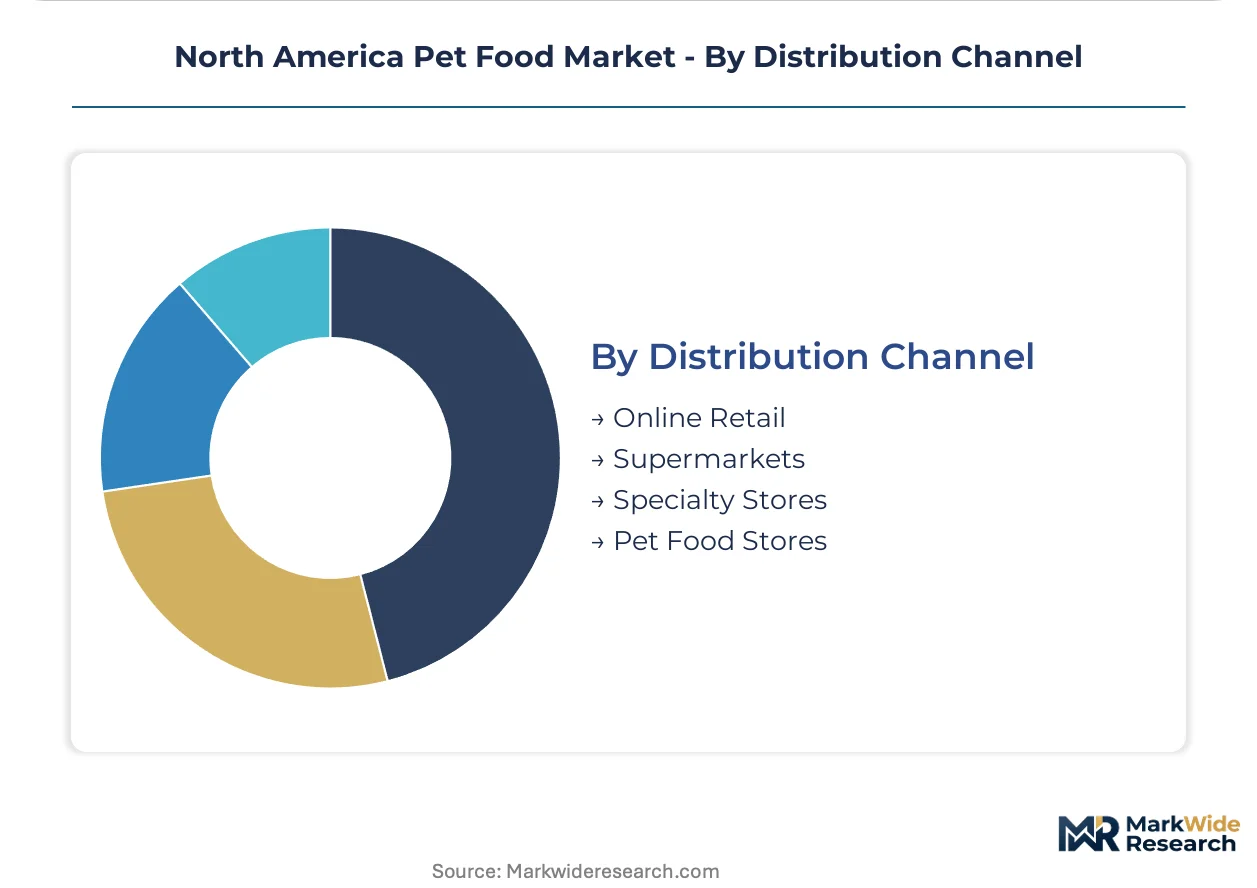
- Online Retail:Direct-to-consumer platforms capture recurring revenue through algorithmic portion calculations and subscription lock-in. Urban Canadian markets and coastal U.S. cities support delivery density for fresh-frozen formats.
- Supermarkets:Mass retail shelf space favors established brands with trade promotion budgets and packaging formats optimized for stock-up behavior.
- Specialty Stores:Independent pet retailers curate premium and boutique assortments, offering educational staff interaction for complex nutrition decisions.
- Pet Food Stores:National chains leverage private label development and veterinary partnership programs to defend against online encroachment.
Supermarkets maintain volume dominance, with online retail expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics between the United States and Canada are reshaping manufacturing footprints as compliance cost differentials influence cross-border production decisions. The FDA's Center for Veterinary Medicine maintains stricter labeling protocols than Health Canada's CFIA, yet Canada's Safe Food for Canadians Regulations impose parallel documentation burdens that narrow the arbitrage window. Mexico's emerging role as a processing hub reflects tariff advantages under USMCA provisions for regional ingredient sourcing.
United States
California and Texas households drive premium pet nutrition spending through subscription fresh-food platforms and veterinary telehealth integration. The FDA's dilated cardiomyopathy investigation into grain-free formulations has forced nationwide reformulation cycles affecting taurine disclosure standards. Kansas and Iowa host concentrated extrusion manufacturing corridors supplying dry kibble to national retail networks.
Canada
Ontario and Quebec provinces anchor therapeutic diet production serving veterinary clinic networks across both sides of the border. Health Canada's CFIA enforces Safe Food for Canadians Regulations requiring batch-level pathogen documentation that elevates compliance costs for small-scale manufacturers. Saskatchewan and Manitoba processing facilities leverage underutilized capacity for export into U.S. northern tier markets.
Mexico
Querétaro and Jalisco states are attracting contract manufacturing investment from U.S. brands seeking USMCA-compliant regional sourcing for poultry and fish meal inputs. The country's national feed control regulator coordinates with AAFCO model standards to facilitate cross-border shipment harmonization. Baja California processing clusters serve California's fresh-frozen pet food demand through shortened cold-chain logistics.
North America Pet Food Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with therapeutic nutrition channels consolidating around veterinary-endorsed portfolios while mass retail fragments across price tiers. The competitive terrain exhibits moderate concentration at the top, where multinational food conglomerates leverage R&D scale and distribution density. Three archetypes dominate: science-backed prescription diet developers, mass-market brand owners with retail shelf dominance, and emerging fresh-format disruptors with direct-to-consumer infrastructure. Capacity expansion and strategic partnerships with veterinary telehealth platforms constitute the primary competitive moves reshaping channel access.
Within the science-backed therapeutic tier, Nestlé Purina PetCare and Mars Petcare Inc. anchor veterinary clinic relationships through prescription diet formulations developed with board-certified nutritionist input. The J.M. Smucker Company occupies a distinct position in mass-market retail, leveraging brand recognition in supermarkets and big-box channels. Diamond Pet Foods exemplifies the contract manufacturing archetype, producing private-label formulations for multiple retail banners without consumer-facing brand equity.
| Leading Market Players |
|---|
| The J.M. Smucker Company |
| Diamond Pet Foods |
| Mars Petcare Inc. |
| Wellness Pet LLC |
| Spectrum Brands/United Pet Group |
| Nestlé Purina PetCare |
| General Mills, Inc. |
| Post Holdings, Inc. |
| Colgate-Palmolive Company (Hill's Pet Nutrition) |
| Others |
Value Chain & Pricing Dynamics
Veterinary clinic networks and subscription platform subscribers concentrate purchasing power across California and Texas, anchoring a three-tier pricing structure across premium, standard, and economy levels that stratifies by channel access and formulation complexity.
Pricing Analysis
Direct-to-consumer subscription margins compress traditional distributor layers, with algorithmic portion calculations enabling personalized pricing that standard retail cannot match. Price differentiation hinges on cold-chain certification grade and veterinary endorsement tier, with FDA CVM-recognized therapeutic formulations commanding shelf price premiums. Cost compression in mid-tier dry kibble is intensifying because commodity chicken meal and fish oil inputs fluctuate with feed grain markets. Mass retail shoppers exhibit highest price sensitivity, while telehealth-integrated subscribers demonstrate lowest elasticity due to convenience lock-in.
Supply Chain Analysis
Workforce availability constraints in Kansas and Iowa extrusion corridors limit expansion velocity for dry kibble manufacturing, while Saskatchewan and Manitoba processing facilities draw from underutilized protein rendering capacity. Raw material dependencies center on rendered poultry meal, fish oil concentrates, and pea protein isolates from Canadian Prairie suppliers. Single-source vulnerability runs through Upper Midwest cold-chain logistics nodes serving Pacific Northwest fresh-frozen demand. Distribution runs through veterinary clinic inventory systems, national retail DC networks, and direct-to-consumer refrigerated last-mile platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cross-border manufacturing arbitrage between FDA CVM labeling requirements and CFIA Safe Food for Canadians Regulations creates compliance cost differentials that favor Canadian Prairie production for U.S. northern tier distribution.
For Market Incumbents: To counter veterinary telehealth platforms bypassing traditional clinic inventory, Nestlé Purina PetCare and Mars Petcare Inc. should deepen exclusive prescription diet partnerships with remote consultation providers. Capacity addition in Ontario therapeutic diet production anchors cross-border veterinary channel control against emerging fresh-format competitors. For New Entrants and Emerging Players: The mid-tier price-point gap between mass-market kibble and subscription fresh formats offers white-space entry through high-pressure processed refrigerated products targeting metropolitan California households. Saskatchewan and Manitoba contract manufacturing access enables export positioning into U.S. markets without FDA facility registration burdens. Go-to-market execution should leverage veterinary telehealth dispensing partnerships in Texas and Florida. For Investors and Strategic Acquirers: Consumer packaged goods conglomerates with pet portfolio gaps are the most active acquirer in this space, seeking science-backed therapeutic brands to complement mass-market holdings. Long-term viability favors assets with board-certified veterinary nutritionist R&D bandwidth and cold-chain subscription infrastructure. Watch for FDA dilated cardiomyopathy investigation resolution as inflection indicator for grain-free reformulation cost normalization.| Strategic Initiative | Industry Significance |
|---|---|
| Veterinary Telehealth Partnership | Remote prescription diet dispensing in Texas and Florida bypasses clinic inventory constraints. |
| Canadian Prairie Manufacturing Expansion | Saskatchewan and Manitoba facilities leverage CFIA compliance for U.S. northern tier export. |
| Alternative Protein Sourcing | Black soldier fly larvae meal reduces commodity chicken meal dependency for sensitive formulations. |
| High-Pressure Processing Adoption | Refrigerated fresh-frozen formats in California and Texas rewrite nutrient retention versus retort sterilization. |
| Functional Ingredient Certification | Probiotic and omega fatty acid validation supports premium positioning in aging pet populations. |
Study Parameters
Coverage spans the United States, Canada, and Mexico, with primary inputs from each jurisdiction combining executive interviews with veterinary nutritionists, pet food manufacturing plant managers, retail category buyers, and cold-chain logistics operators. Secondary validation draws from FDA CVM enforcement reports, AAFCO model bill adoption tracking, CFIA Safe Food for Canadians Regulations documentation, and USMCA tariff schedule analysis. Bottom-up volume modeling and top-down value reconciliation triangulate market sizing across the analysis window.
Rate-of-change decomposition separates volume growth from price-mix effects across product type, ingredient sourcing tier, distribution channel, and regional regulatory cluster dimensions. CAGRs derive from segment-level trajectory modeling incorporating veterinary telehealth adoption curves, cold-chain infrastructure buildout, and FDA dilated cardiomyopathy investigation compliance costs. Industry-specific forecast inputs include AAFCO nutrient profile standard revisions and CFIA batch-level documentation burden evolution.
Caveats apply where FDA dilated cardiomyopathy investigation outcomes, California Proposition 65 chemical warning mandate expansion, or veterinary telehealth regulatory preemption could materially shift the outlook. Forecasts reflect assumptions about commodity protein input stability and cross-border manufacturing cost differentials. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Japan Pet Food Market
Pet Care Products
Dog Coats for Winter Market
Pet Care Products
Asia-Pacific Pet Food Market
Pet Care Products
Pet Care E-Commerce Market
Pet Care Products
Natural Dog Treat Market
Pet Care Products
Canned Wet Cat Food Market
Pet Care Products
Cat Bed Market
Pet Care Products
Japan Organic and Natural Pet Food Market
Pet Care Products
US Pet Boarding Market
Pet Care Products
Cat Diets Market
Pet Care Products
Dehydrated Pet Food Market
Pet Care Products
China Cat Litter Market
Pet Care Products
Europe Pet Clothing Market
Pet Care Products
Outdoor Cat House Market
Pet Care Products
Cat Harness Market
Pet Care Products
Pet Dental Health Market